
 Pygas (Pyrolysis Gasoline) Market | 2026-2036
Pygas (Pyrolysis Gasoline) Market Size, Share, and Industry Trends Forecast 2026-2036
Pygas (Pyrolysis Gasoline) Market Outlook
Hydrotreating catalyst advances is reconfiguring how refiners upgrade raw pygas into specification-grade benzene, toluene, and xylene streams. SABIC leverages its integrated Saudi petrochemical complexes to sustain captive pygas consumption at scale. ExxonMobil anchors North American supply through its Baytown refining corridor. Reliance Industries dominates the South Asian landscape with its Jamnagar complex, where pygas feeds both fuel blending and aromatics extraction.
Pygas is a C5–C12 aromatic-rich naphtha fraction produced as a byproduct of ethylene steam cracking, typically containing 60–80% aromatics by volume with significant benzene, toluene, and xylene content alongside olefinic and aliphatic components. Refiners hydrotreat raw pygas to saturate olefins and remove sulfur, nitrogen, and dienes before routing stabilized streams to reformers or aromatics extraction units. The aromatics product type leads value capture due to benzene and xylene demand in polyester and styrene chains, while fuel additives application grows fastest as octane requirements tighten under evolving engine standards. Aliphatic hydrocarbons occupy a mature, lower-margin position primarily serving solvent and blending markets.
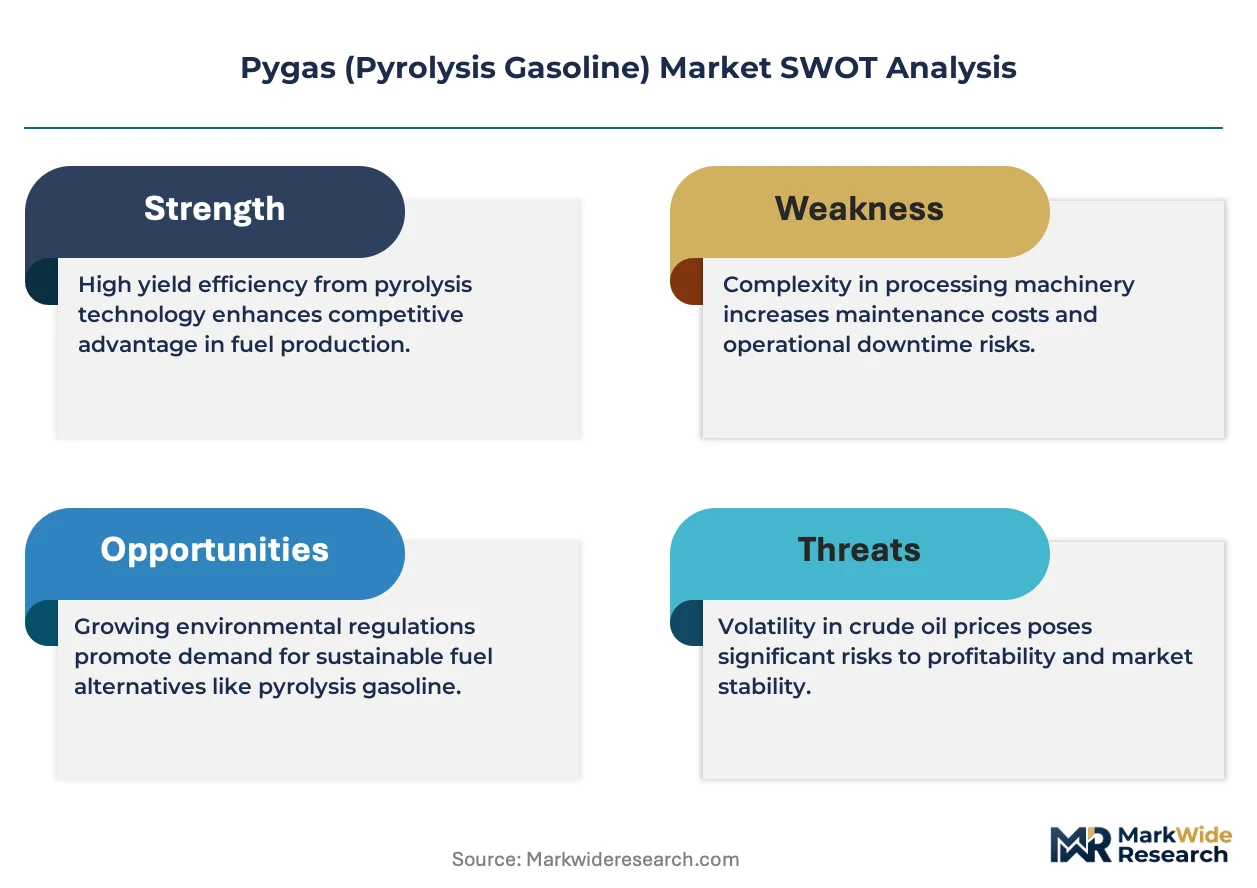
The US EPA enforces benzene content limits under the Mobile Source Air Toxics rule, compelling refiners to invest in pygas hydrotreating or alternative feedstock sourcing. REACH in Europe restricts aromatic hydrocarbon classifications in consumer-facing applications, redirecting technical-grade pygas toward industrial chemical synthesis. India's BIS fuel quality norms align with Euro-VI equivalents, tightening benzene specifications that hydrotreated pygas helps refiners meet. Stakeholders must monitor catalyst technology economics and regional fuel specification convergence to position upgrade investments ahead of regulatory phase-ins.
Market Dynamics
The US EPA's Mobile Source Air Toxics rule is compressing benzene limits in finished gasoline, forcing refiners to hydrotreat pygas streams or abandon the feedstock entirely. This regulatory compression is restructuring upgrade economics across the aromatics value chain.
Growth Catalysts
- Automotive octane demand:High-compression engines require 95+ RON gasoline, pulling hydrotreated pygas into premium fuel blending pools as a cost-effective octane booster.
- REACH aromatic classifications:Europe's chemical safety framework redirects technical-grade pygas toward industrial synthesis applications, insulating volumes from consumer-product restrictions.
- Dual carbon goals:China's MEE is tightening refinery emissions standards, accelerating catalyst replacement cycles that improve pygas upgrading efficiency.
Market Restraints
- Ethylene cracker feedstock flexibility:Refiners switching to lighter ethane feeds produce less pygas byproduct, constraining raw material availability for aromatics extractors.
- Naphtha price volatility:Pygas competes directly with reformate and imported naphtha; Asian spot price swings compress upgrading margins without warning.
- Benzene substitution in styrene:Bio-based feedstocks and recycled plastics are displacing virgin benzene in polymer chains, threatening long-term pygas offtake.
Strategic Opportunities
- India BIS Euro-VI alignment:The country's fuel quality norms now match European benzene specifications, creating fresh demand for hydrotreated pygas in domestic refineries.
- Circular feedstock integration:Pyrolysis oil from plastic waste cracking is converging with traditional pygas streams, enabling aromatics producers to claim recycled content certificates.
- Specialty solvent applications:Electronics-grade toluene and xylene from deep-hydrotreated pygas is commanding premium pricing in semiconductor cleaning processes.
Industry Challenges
- Catalyst sulfidation expertise:Hydrotreater operations require precise temperature and hydrogen sulfide management; qualified technicians are concentrated at a handful of technology licensors.
- Legacy aromatics extraction unit retrofits:Older Udex and Sulfolane plants require substantial capital to handle higher-olefin pygas feeds without solvent degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pygas (Pyrolysis Gasoline) Market |
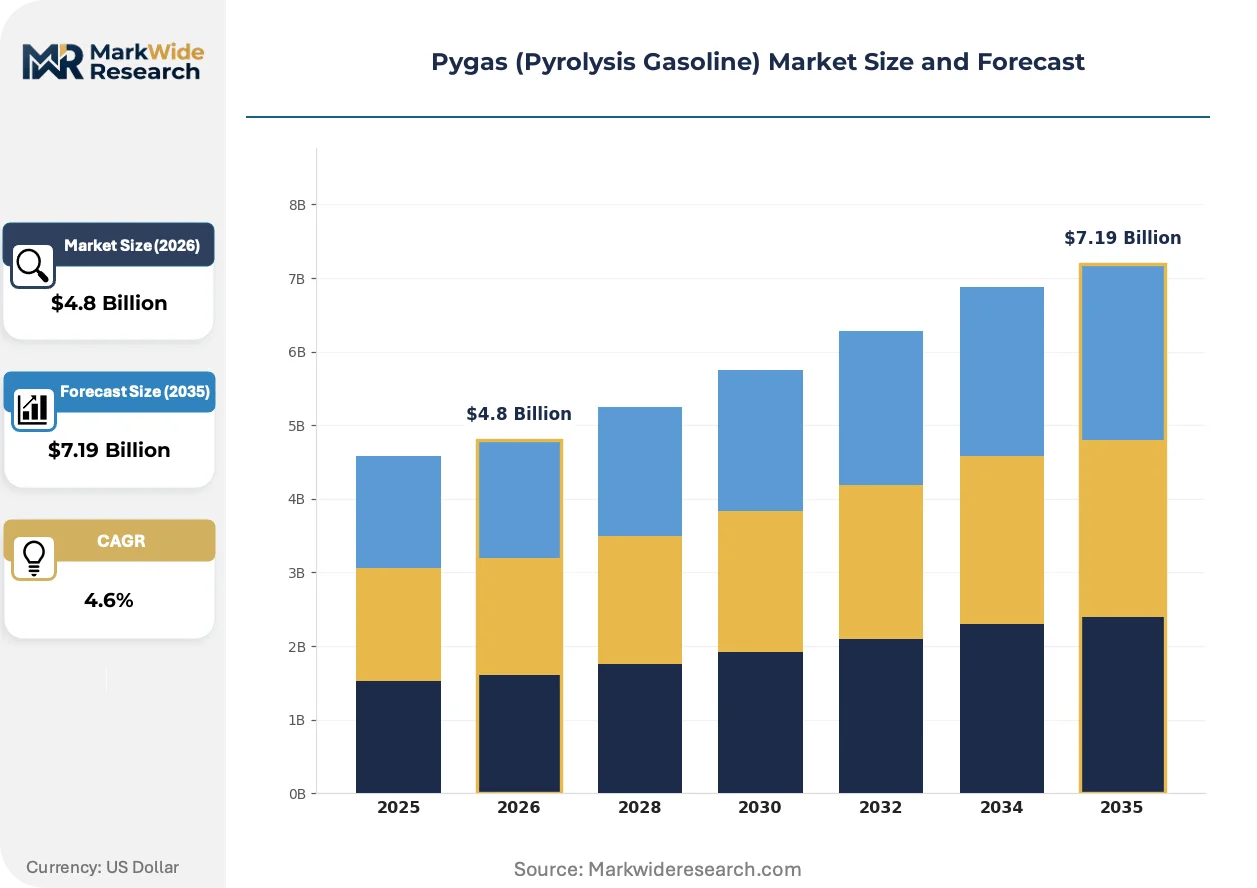
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biofuels, Aromatics, Aliphatic Hydrocarbons, Olefins Application: Petrochemical Production, Fuel Additives, Solvents, Fuel End User: Refineries, Chemical Manufacturers, Automotive Sector, Energy Providers Distribution Channel: Direct Sales, Distributors, Online Platforms, Retail |
| Companies Covered | SABIC, China National Petroleum Corporation, ExxonMobil Corporation, Dow Chemical Company, LyondellBasell Industries, Royal Dutch Shell plc, Reliance Industries Limited, ONGC Petro additions Limited, Chevron Phillips Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pygas (Pyrolysis Gasoline) Market Strategic Shifts
Digital twin technology is virtualizing pygas upgrading operations, compressing pilot-test timelines from months to weeks. Refiners now simulate catalyst performance before committing to full-scale revamps.
Advanced reactor modeling software is virtualizing hydrotreater design, allowing S-Oil and SK Energy to optimize catalyst bed configurations without physical prototyping. Korean refiners are deploying these tools for benzene saturation units ahead of domestic spec tightening. The technology is compressing engineering procurement construction cycles by eliminating redundant pilot plant runs.
REACH authorization requirements for high-volume aromatics are forcing European extractors to document full substance life cycles. ECHA's SCIP database mandates supply chain transparency down to the component level. Aromatics traders are responding by segregating pygas-derived streams through dedicated storage and certified mass balance systems.
Integrated refinery-petrochemical complexes are consolidating aromatics procurement under single sourcing desks, eliminating independent traders from high-volume benzene and xylene transactions. Reliance Industries and SABIC have internalized pygas routing decisions within centralized planning functions. This concentration is most visible in the Middle East and South Asia, where captive cracker-aromatics linkages dominate supply security calculations.
Pygas (Pyrolysis Gasoline) Market Segmentation
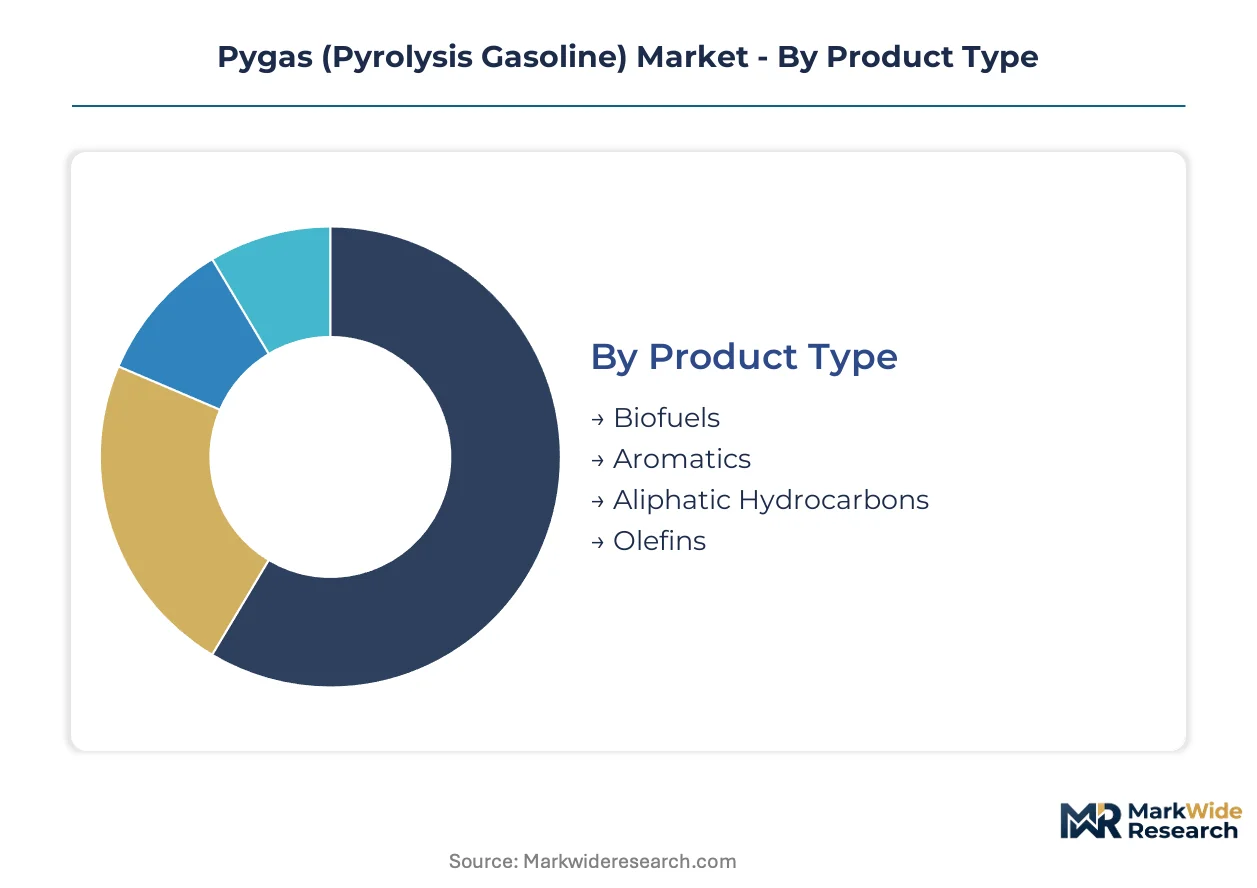
Pygas segmentation reflects divergent value capture across chemical upgrading depth and fuel specification stringency. Refiners route identical feedstock streams toward entirely different margin pools depending on hydrotreating intensity and regional benzene limits.
Product Type:
Cost tier stratification separates specification-grade chemical streams from commodity fuel blending components, with upgrading intensity determining margin realization.
- Aromatics:Benzene, toluene, and xylene fractions command premium pricing through extraction from deeply hydrotreated pygas. Demand concentrates in polyester and styrene polymer chains across China and India, where integrated petrochemical complexes maximize aromatics recovery rates.
- Aliphatic Hydrocarbons:Saturated C5–C12 paraffinic components serve solvent markets and fuel blending after moderate hydrotreating. European REACH classifications redirect technical-grade volumes toward industrial synthesis applications, insulating offtake from consumer-product restrictions.
- Olefins:Unsaturated fractions require saturation before most end-uses; diene content limits applicability without substantial upgrading investment.
- Biofuels:Emerging category converging pyrolysis oil from plastic waste cracking with traditional pygas streams for recycled content certification.
Aromatics holds installed capacity. Aliphatic Hydrocarbons is rotating up the share rankings as fuel specification convergence spreads hydrotreating requirements.
Application:
Application segmentation tracks how refiners balance chemical synthesis margins against fuel pool compliance costs under tightening regulatory phase-ins.
- Fuel Additives:Hydrotreated pygas delivers 95+ RON octane contribution for high-compression gasoline formulations. Automotive sector demand pulls volumes into premium blending pools as engine efficiency standards tighten across India BIS Euro-VI alignment and US EPA Mobile Source Air Toxics enforcement.
- Petrochemical Production:Aromatics extraction feeds benzene-toluene-xylene separation units for downstream polymer production. SABIC and Reliance Industries anchor captive consumption through integrated cracker-aromatics linkages in Saudi Arabia and India.
- Solvents:Electronics-grade toluene and xylene from deep-hydrotreated pygas commands specialty pricing in semiconductor cleaning processes.
- Fuel:Direct blending of raw or lightly treated pygas persists only where benzene specifications remain permissive.
Petrochemical Production holds installed capacity. Fuel Additives is climbing the fastest as octane requirements intensify.
End User:
Customer type concentration determines contract structure, with integrated complexes internalizing flows and independent refiners exposed to spot volatility.
- Refineries:Hydrotreater operators upgrade raw pygas to specification-grade streams for internal aromatics units or external sale. US EPA benzene limits force capital deployment toward saturation capacity.
- Chemical Manufacturers:Aromatics extractors source stabilized pygas as benzene-toluene-xylene feedstock; solvent producers purchase aliphatic cuts.
- Automotive Sector:Fuel blenders procure hydrotreated pygas as octane booster for high-RON gasoline formulations.
- Energy Providers:Limited direct offtake; primarily intermediaries in power-to-chemicals integration pilots.
Refineries holds installed capacity. Chemical Manufacturers is gaining share fastest through aromatics capacity expansion.
Distribution Channel:
Supply concentration shapes procurement patterns, with high-volume flows captured under integrated planning and residual volumes trading through intermediaries.
- Direct Sales:Captive routing within integrated refinery-petrochemical complexes eliminates intermediary margins. Reliance Industries and SABIC internalize pygas decisions within centralized supply functions.
- Distributors:Independent traders handle spot volumes from non-integrated crackers, particularly in Southeast Asian markets without captive aromatics extraction.
- Online Platforms:Emerging for standardized aliphatic solvent grades; limited penetration in specification-sensitive aromatics.
- Retail:Minimal relevance; specialty solvent drums in select industrial supply chains.
Direct Sales holds installed capacity. Distributors is rotating up the share rankings as merchant cracker capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia exports hydrotreated pygas derivatives to South Asian aromatics extractors, while the United States ships stabilized streams to European fuel blenders seeking octane compliance.
United States
US refiners deploy pygas hydrotreaters to meet EPA Mobile Source Air Toxics benzene limits for finished gasoline. The Baytown refining corridor anchors North American upgrading capacity. Houston-area complexes route stabilized streams to both domestic aromatics units and Atlantic fuel export terminals.
China
China's MEE emissions standards accelerate catalyst replacement cycles at integrated refinery-petrochemical sites. Dual carbon goals compress permitting timelines for pygas-derived aromatics expansion. The Yangtze River Delta concentrates the fastest capacity buildout for benzene-toluene-xylene extraction from deeply hydrotreated feeds.
India
India's BIS fuel quality norms now align with Euro-VI benzene specifications, forcing domestic refiners toward hydrotreated pygas blending. The Jamnagar complex dominates captive consumption through integrated cracker-aromatics linkages. Gujarat's refining clusters are adding saturation capacity ahead of specification phase-ins.
Saudi Arabia
SABIC leverages integrated petrochemical complexes to sustain captive pygas consumption at scale for regional aromatics supply. The country's national industrial regulator enforces product quality standards for export-oriented chemical streams. Jubail Industrial City houses the densest concentration of ethylene cracker-pygas upgrading integration in the Middle East.
Germany
German extractors navigate REACH authorization requirements for high-volume aromatics by documenting full substance life cycles through ECHA's SCIP database. The country's national chemical regulator mandates supply chain transparency down to the component level. Ludwigshafen's chemical cluster deploys certified mass balance systems to segregate pygas-derived benzene for automotive sector contracts.
Pygas (Pyrolysis Gasoline) Market Competitive Environment
Channel-controlling players compete with product-specialist players for pygas upgrading and aromatics extraction value. The market structures around three tiers: integrated petrochemical majors with captive cracker supply, independent refiners purchasing merchant pygas, and technology licensors providing hydrotreating catalyst systems. Consolidation concentrates at the integrated complex level while merchant trading retains fragmentation. Dominant competitive moves include catalyst technology licensing partnerships and backward integration into ethylene cracker operations to secure feedstock supply.
Among integrated petrochemical majors, SABIC, ExxonMobil Corporation, and Reliance Industries Limited exemplify the channel-controlling archetype through captive pygas routing within centralized supply functions. These entities occupy positions where cracker-aromatics linkages dominate supply security calculations, particularly in Middle Eastern and South Asian markets. The scale-driven end of the competitive spectrum sits with national oil company affiliates such as China National Petroleum Corporation, which represent state-backed vertical integration into both feedstock production and downstream aromatics extraction.
| Leading Market Players |
|---|
| SABIC |
| China National Petroleum Corporation |
| ExxonMobil Corporation |
| Dow Chemical Company |
| LyondellBasell Industries |
| Royal Dutch Shell plc |
| Reliance Industries Limited |
| ONGC Petro additions Limited |
| Chevron Phillips Chemical Company |
| Others |
Value Chain & Pricing Dynamics
The Houston-Baytown freight corridor anchors North American pygas logistics, with barge and pipeline cost dynamics compressing margins for non-integrated refiners while amplifying price differentiation between hydrotreated specification grades and raw feedstock streams. This transportation architecture concentrates pricing power among integrated operators with captive upgrading capacity, forcing merchant buyers to absorb volatility in both naphtha indexation and regional benzene specification compliance.
Pricing Analysis
Cost-plus contracts indexed to Platts Asian naphtha assessments dominate long-term offtake agreements, with aromatics extractors layering hydrotreating premiums atop base feedstock costs. Price differentiation hinges on benzene saturation depth and REACH documentation grade, with electronics-certified toluene commanding substantial premiums over technical-grade solvent streams. Pricing pressure stems from ethane feedstock switching at crackers, constraining pygas availability and pushing raw material costs upward. Integrated refiners with captive crackers exhibit lowest price sensitivity; independent aromatics extractors purchasing merchant volumes face acute margin compression during naphtha price spikes.
Supply Chain Analysis
Ethylene cracker operations in Saudi Arabia, the United States, and China concentrate upstream pygas generation, with feedstock quality varying by cracker severity and feed slate composition. Raw material flows draw from naphtha, gasoil, and increasingly ethane feeds, with lighter feeds reducing pygas yields per ton of ethylene produced. Single-source vulnerability concentrates at hydrotreating catalyst supply, where specialized sulfidation expertise rests with a handful of technology licensors. Distribution runs through integrated refinery-petrochemical complexes for high volumes, with residual merchant flows handled by regional distributors in Southeast Asian markets lacking captive aromatics extraction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified hydrotreater technicians and catalyst sulfidation specialists represent the critical capability bottleneck in this market, with their scarcity constraining capacity expansion timelines and inflating operational risk for new entrants. This talent gap amplifies competitive moats for incumbents with established technical teams while raising capital barriers for greenfield projects.
For Market Incumbents: Insulate margin positions by accelerating catalyst replacement cycles ahead of China's MEE emissions enforcement, locking in efficiency advantages before regulatory phase-ins tighten. Secure backward integration into ethylene cracker operations or long-term feedstock offtake agreements to offset raw material availability risk from ethane feedstock switching. Prioritize certification investment for electronics-grade solvent streams to capture premium pricing in semiconductor supply chains. For New Entrants and Emerging Players: Southeast Asian markets without captive aromatics extraction present the most penetrable geography, particularly Vietnam and Indonesia where merchant cracker capacity expands ahead of local hydrotreating infrastructure. Target fuel additives applications for domestic refineries facing Euro-VI benzene specification alignment, offering hydrotreating tolling services rather than competing on feedstock procurement. Deploy digital twin simulation capabilities to compress engineering timelines and differentiate against established players with legacy pilot plant dependencies. For Investors and Strategic Acquirers: Mid-scale hydrotreating technology licensors with proprietary catalyst formulations represent the most attractive acquisition archetype, offering defensive positioning against supply concentration in refining services. Monitor ethylene cracker feedstock mix disclosures as the critical inflection signal—sustained shifts toward lighter feeds would structurally constrain pygas supply and revalue captive production assets. Cross-checking against regional benzene specification phase-in schedules is advised before commitment-grade decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cracker Operations | Captive pygas supply secures feedstock availability against ethane switching trends at competitors. |
| Hydrotreating Catalyst Technology Licensing | Proprietary sulfidation protocols differentiate service offerings for refiners facing EPA benzene limits. |
| Electronics-Grade Solvent Certification | Semiconductor cleaning applications command premium pricing unreachable by technical-grade competitors. |
| Digital Twin Implementation | Virtual reactor modeling compresses engineering cycles for Korean and Chinese refiners ahead of specification tightening. |
| Long-Term Supply Agreement with Integrated Complexes | Reliance Industries and SABIC-style captive consumption models reduce spot market exposure. |
Study Parameters
A standing panel of hydrotreater operations managers, aromatics extraction unit engineers, refinery procurement leads, and catalyst technology licensors provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against customs trade data, ACC and Cefic industry reports, SEC 10-K filings from disclosed petrochemical operations, and EPA regulatory docket records. Bottom-up capacity and utilization estimates triangulated against top-down demand modeling across automotive fuel blending and polyester chain applications.
Scenario-bracketing framed analytical projections across the analysis window, with segmentation dimensions spanning product type (aromatics, aliphatic hydrocarbons, olefins), application (fuel additives, petrochemical production, solvents), and end user category (refineries, chemical manufacturers, automotive sector). CAGRs derived from fitted growth curves applied to disclosed capacity expansion timelines and regulatory phase-in schedules, with feedstock switching elasticity and catalyst replacement cycles as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by national oil company affiliates would shift outcomes beyond modeled ranges. Cross-checking against IEA petrochemical feedstock demand projections and disclosed cracker capacity additions is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Malaysia Refined Petroleum Products Market
Petroleum Products
East Africa Refined Petroleum Products Market
Petroleum Products
Oil Shale Market
Petroleum Products
Natural Gas Liquid Market
Petroleum Products
Crude Tall Oil Market
Petroleum Products
France Refined Petroleum Product Market
Petroleum Products
Petroleum Wax Market
Petroleum Products
Oil Refining Market
Petroleum Products
Africa Refined Petroleum Products Market
Petroleum Products
Balanos Oil Market
Petroleum Products
LPG [Liquefied Petroleum Gas] Market
Petroleum Products
Germany Refined Petroleum Products Market
Petroleum Products
Crude Oil Market
Petroleum Products
Asia Pacific Base Oil Market
Petroleum Products
Crude Oil Flow Improvers Market
Petroleum Products
Base Oil Market