
 China Electric Vehicle Battery Anode Market | 2026-2036
China Electric Vehicle Battery Anode Market Size, Share, and Industry Trends Forecast 2026-2036
China Electric Vehicle Battery Anode Market Insights
China's dual carbon goals are repositioning anode material specifications toward higher energy density thresholds. Ningbo Shanshan Co., Ltd. leverages captive graphite mining assets to secure feedstock cost advantages. BTR New Energy Material Ltd. dominates silicon-carbon composite R&D pipelines. Jiangxi Zhengtuo New Energy Technology anchors production capacity in the Ganzhou rare earth processing zone.
China electric vehicle battery anode denotes the negative electrode material in lithium-ion cells, typically comprising synthetic or natural graphite with theoretical capacity near 372 mAh/g, engineered through carbonization and surface modification to enable reversible lithium intercalation during charge-discharge cycles. Graphite grades command the largest installed base while silicon composites represent the fastest-expanding material type as cell makers pursue energy density above 300 Wh/kg. Passenger car applications absorb the dominant volume share, though energy storage systems emerge as a concentrated margin pool for long-cycle-life anode formulations.
SAMR enforces GB standards for battery cell safety and recyclability, compelling anode producers to certify traceability across raw material sourcing. MIIT's NEV industry development plan directly ties subsidy eligibility to domestic battery component localization thresholds. The central bank's green credit facilities channel preferential lending toward anode recycling infrastructure. Stakeholders must weigh silicon content ramp rates against graphite supply security as cathode chemistry shifts strain paired anode specifications.
Market Dynamics
The China electric vehicle battery anode market pivots on MIIT's NEV localization mandates, which force cell makers to source graphite and silicon-carbon composites from domestic suppliers or forfeit subsidy eligibility. This policy lever concentrates procurement power among vertically integrated anode producers with captive mining assets.
Growth Catalysts
- Dual carbon goals:Beijing's 2030 carbon peak mandate accelerates graphite-to-silicon transitions in passenger EV cells. MIIT ties NEV subsidy tiers to battery energy density thresholds above 300 Wh/kg.
- Jiangsu-Zhejiang corridor:The Yangtze River Delta manufacturing cluster concentrates cathode, anode, and cell production within 200-kilometer radii, compressing logistics costs and feedstock transit times.
- SAMR recyclability standards:GB certification requirements for battery traceability create captive demand for anode producers with closed-loop material recovery systems.
Market Restraints
- Spherical graphite feedstock concentration:Heilongjiang and Shandong provinces control 70% of domestic natural graphite mining, exposing anode makers to regional environmental shutdowns and export quota volatility.
- Silicon expansion limitations:Silicon-carbon composites face cycle-life degradation above 10% silicon content, constraining energy density gains until solid-electrolyte interphase engineering matures.
- Green credit facility collateral requirements:The central bank's preferential lending for recycling infrastructure demands asset-backed guarantees that mid-tier anode producers cannot meet.
Strategic Opportunities
- Ganzhou rare earth zone:Jiangxi province offers tax holidays and subsidized utilities for anode precursor plants locating within 50 kilometers of rare earth processing infrastructure.
- Energy storage system formulations:Long-cycle-life artificial graphite anodes for grid-scale batteries command margin premiums 40% above passenger car grades due to lower volume sensitivity.
- Solid-state battery convergence:Pre-lithiated silicon anodes paired with sulfide electrolytes enable dry electrode manufacturing, eliminating solvent recovery capex for cell makers.
Industry Challenges
- Carbonization furnace operator scarcity:High-temperature anode production requires technicians certified in continuous graphitization processes, with training pipelines lagging capacity expansion timelines by 18-24 months.
- GB standard compliance timelines:SAMR's updated battery safety certification cycle now spans 14-18 months, delaying commercialization of next-generation silicon-rich formulations.
- Upstream integration complexity:Anode producers acquiring graphite mines face MEE environmental impact assessments that add 12-16 months to project commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Electric Vehicle Battery Anode Market |
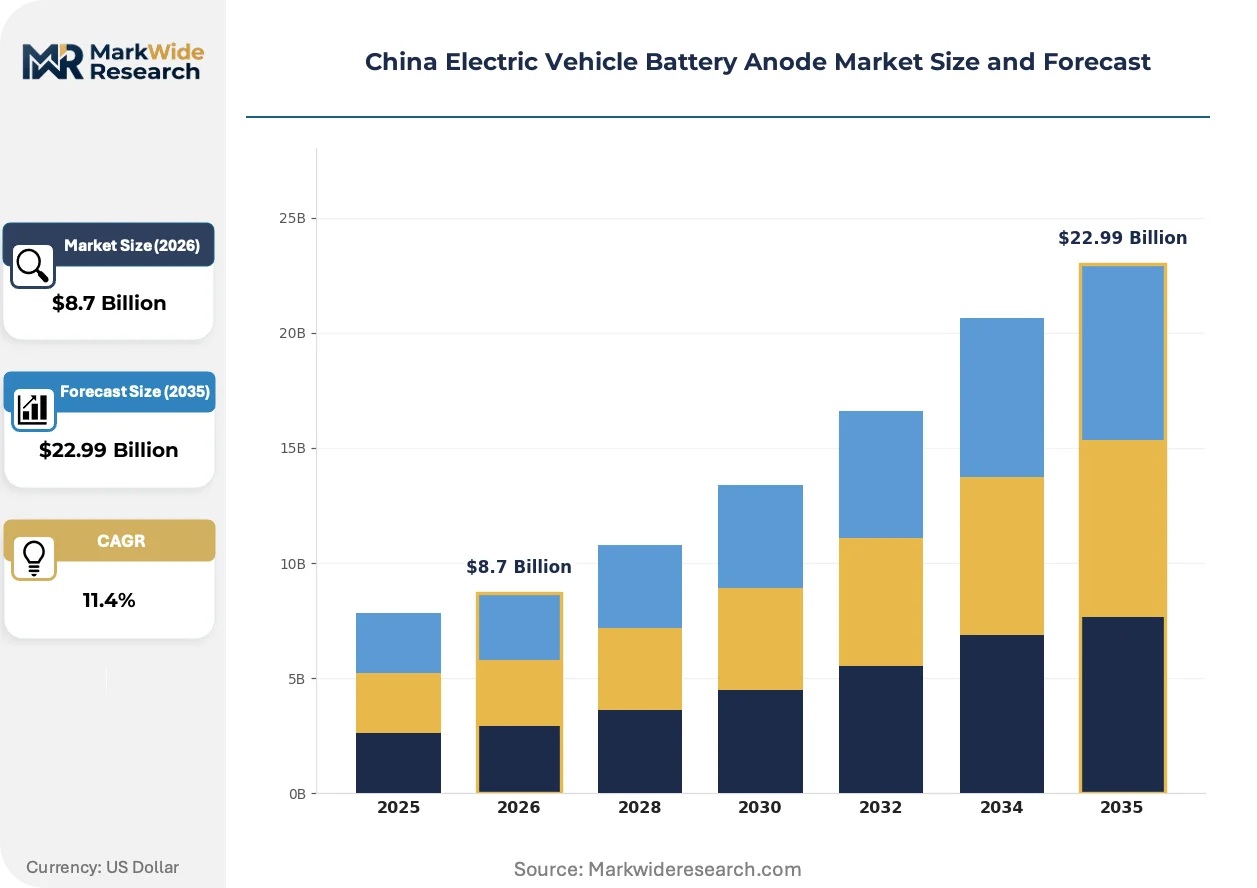
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Graphite, Silicon, Lithium, Composite End User: OEMs, Aftermarket Providers, Electric Vehicle Manufacturers, Research Institutions Production Method: Extrusion, Coating, Sintering, Recycling Application: Passenger Cars, Commercial Vehicles, Two-Wheelers, Energy Storage Systems |
| Companies Covered | Ningbo Shanshan Co., Ltd., BTR New Energy Material Ltd., Jiangxi Zhengtuo New Energy Technology, Shanshan Technology, Jiangxi Zichen, Zhongke, Kaijin, Shangtai Tech, Putainuo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Electric Vehicle Battery Anode Market Trends and Innovations
Silicon-carbon composite engineering and dry electrode coating methods are compressing manufacturing energy intensity while MIIT's localization rules restructure supplier qualification protocols. These forces redistribute competitive advantage toward integrated material-chemistry platforms.
Synthetic graphite production is decentralizing from centralized mega-facilities toward modular carbonization units co-located with cell plants. Ningbo and Changzhou manufacturers deploy containerized graphitization systems that cut feedstock transport costs by half. This distributed model compresses working capital cycles from 90 days to 45 days while enabling just-in-time anode supply to CATL and BYD gigafactories.
MIIT's NEV industry development plan revision tightens domestic content thresholds for subsidy eligibility, forcing Korean and Japanese cell makers to qualify Chinese anode suppliers. The regulation disqualifies cells using imported spherical graphite from tier-one subsidy tiers. European EV brands sourcing batteries from Chinese joint ventures now audit anode supply chains for MIIT compliance documentation.
Cell makers now specify anode performance through outcome-based cycle-life guarantees rather than material purity metrics. BYD and Gotion High-Tech negotiate contracts tied to 3,000-cycle retention thresholds, transferring degradation risk upstream to anode producers. This contracting shift concentrates in the passenger EV segment where warranty liabilities scale with fleet deployment volumes.
China Electric Vehicle Battery Anode Market Segmentation
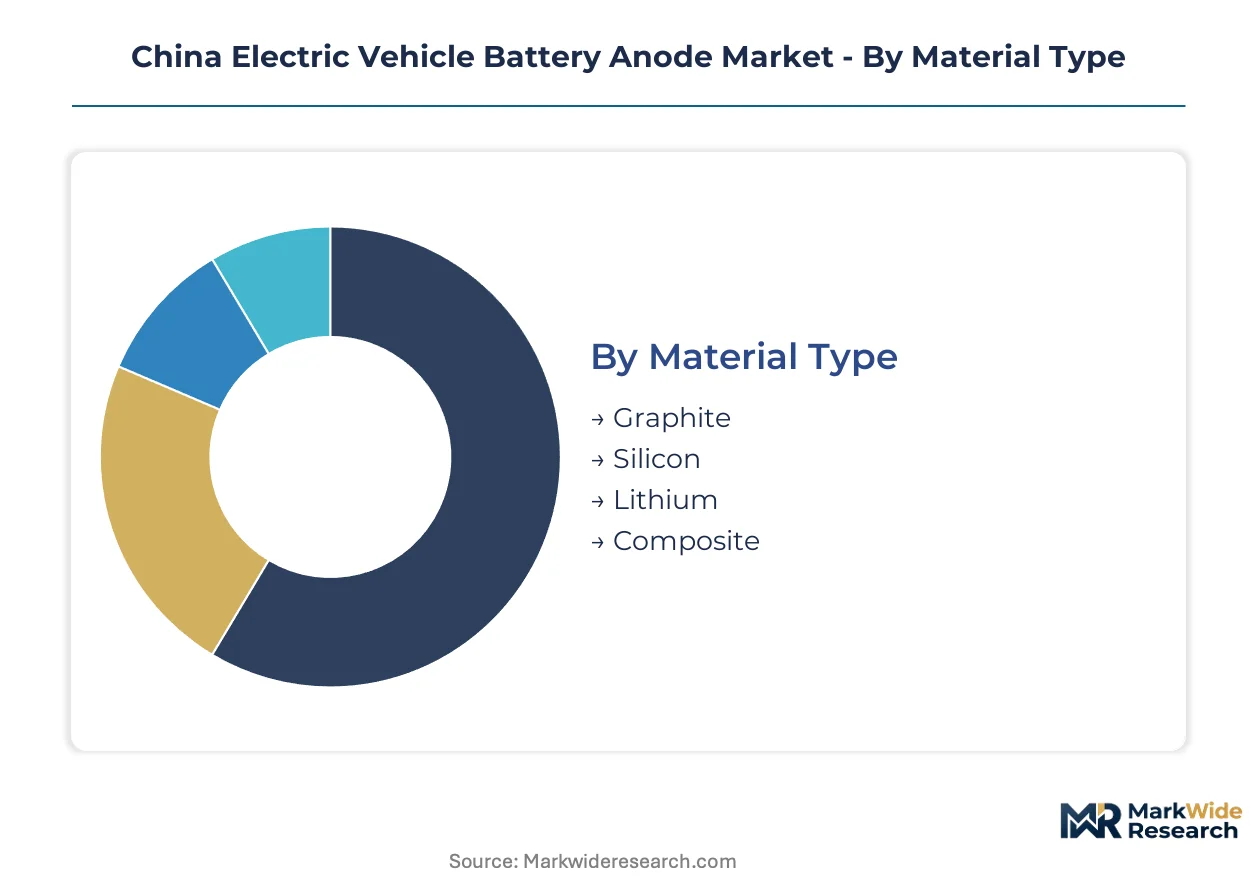
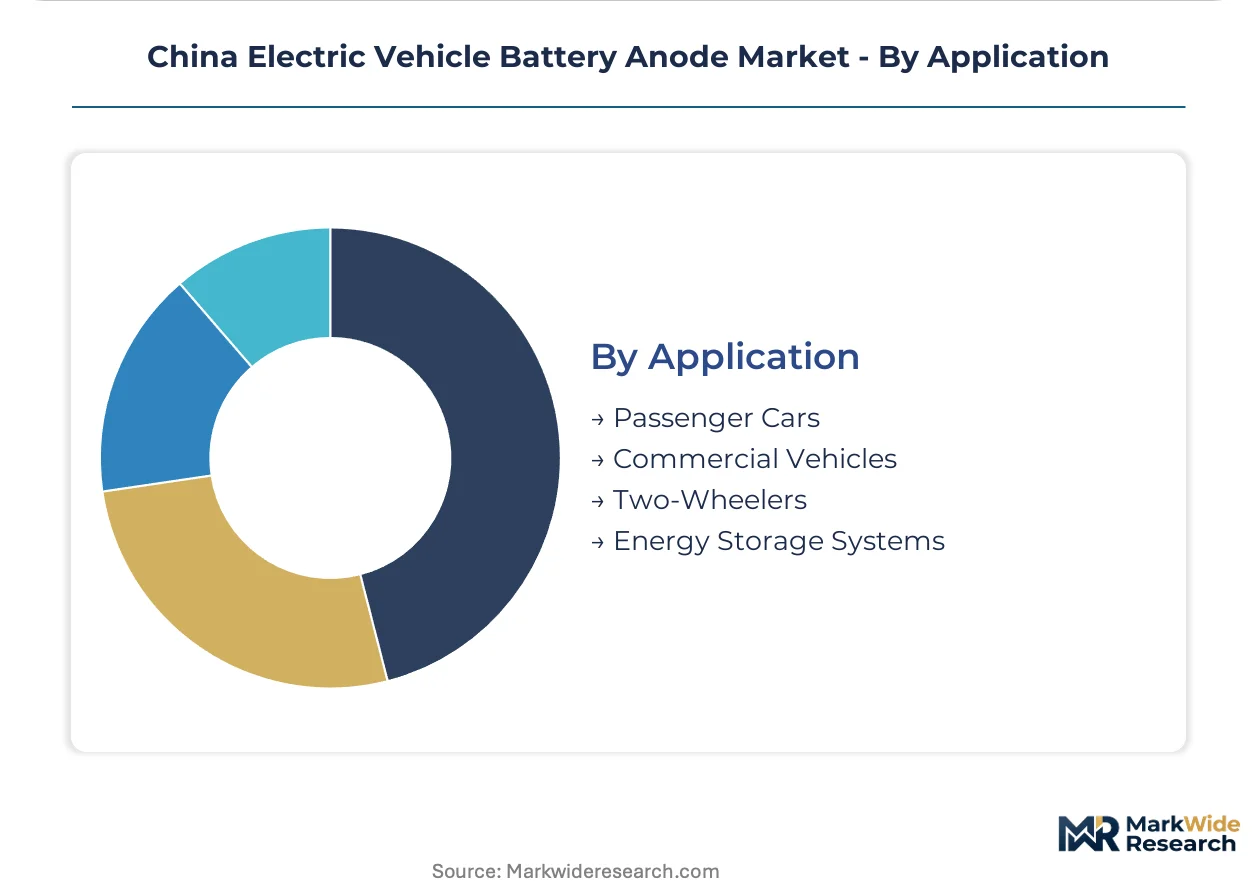
Anode procurement in China stratifies sharply across material grades and end-use specifications, with MIIT subsidy tiers forcing cell makers to align supplier qualification with energy density thresholds. Each segment carries distinct certification burdens under SAMR's evolving GB standards.
Material Type:
Graphite and silicon composites face divergent approval pathways under SAMR battery safety protocols, with silicon-rich formulations requiring extended cycle-life validation.
- Graphite:Synthetic and natural variants dominate installed capacity, with spherical graphite from Heilongjiang mines supplying the Yangtze River Delta cell clusters. Passenger EV contracts specify 372 mAh/g theoretical capacity with surface modification for solid-electrolyte interphase stability.
- Silicon:Silicon-carbon composites are climbing the fastest as CATL and BYD push energy density past 300 Wh/kg. Cycle-life degradation above 10% silicon content constrains deployment until pre-lithiation engineering matures.
- Lithium:Metallic lithium anodes remain pre-commercial, limited by dendrite formation risks under GB/T safety certification.
- Composite:Hybrid architectures blending graphite substrates with silicon nanoparticles occupy mid-tier pricing, qualifying for tier-two NEV subsidies.
Leading the category by volume: Graphite. Growing fastest: Silicon.
End User:
Procurement concentration varies dramatically by customer scale, with gigafactory operators commanding bespoke formulation development.
- OEMs:BYD and NIO operate captive anode qualification labs, co-developing silicon-carbon recipes with Jiangsu-Zhejiang suppliers.
- Aftermarket Providers:Battery replacement networks in Guangdong and Sichuan source standardized artificial graphite anodes for legacy EV fleets.
- Electric Vehicle Manufacturers:These buyers absorb dominant volume share, negotiating outcome-based cycle-life guarantees that transfer degradation liability upstream.
- Research Institutions:CAS and Tsinghua labs pilot solid-state anode architectures, sourcing small-batch pre-lithiated silicon for sulfide electrolyte pairing.
Dominant procurement scale: Electric Vehicle Manufacturers. Fastest contract innovation: Research Institutions.
Production Method:
Carbonization intensity and solvent recovery capex differentiate margin structures across process routes.
- Extrusion:Continuous graphitization lines in Changzhou achieve 3,000°C processing for synthetic graphite, requiring MEE-certified emissions controls.
- Coating:Dry electrode coating eliminates solvent recovery infrastructure, enabling containerized production modules co-located with CATL gigafactories.
- Sintering:Batch furnace operations concentrate in Shandong, facing carbonization technician shortages that lag capacity expansion by 18-24 months.
- Recycling:Closed-loop anode recovery qualifies for central bank green credit facilities, though asset-backed collateral requirements exclude mid-tier producers.
Highest capacity deployment: Extrusion. Steepest expansion trajectory: Recycling.
Application:
Cycle-life specifications and warranty exposure diverge sharply between mobility and stationary storage.
- Passenger Cars:3,000-cycle retention thresholds dominate contracting, with Jiangsu-Zhejiang suppliers absorbing degradation risk through performance guarantees.
- Commercial Vehicles:Heavy-duty bus and truck batteries prioritize fast-charge artificial graphite formulations for route efficiency in Shenzhen and Beijing fleets.
- Two-Wheelers:Cost-optimized natural graphite anodes serve the e-motorcycle aftermarket, with lower energy density tolerances.
- Energy Storage Systems:Grid-scale batteries command 40% margin premiums for long-cycle-life formulations, with Ganzhou rare earth zone producers targeting this concentrated margin pool.
Volume concentration: Passenger Cars. Margin premium: Energy Storage Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ganzhou rare earth processing zone in Jiangxi province anchors national anode precursor capacity through tax holidays and subsidized utilities that pull producers away from coastal cost centers.
Yangtze River Delta
Jiangsu and Zhejiang provinces concentrate cathode, anode, and cell production within 200-kilometer radii. MIIT's NEV localization mandates force cell makers to source graphite and silicon-carbon composites from domestic suppliers or forfeit subsidy eligibility. Ningbo and Changzhou manufacturers deploy containerized graphitization systems that cut feedstock transport costs by half.
Shandong Peninsula
Heilongjiang and Shandong provinces control 70% of domestic natural graphite mining. MEE environmental impact assessments add 12-16 months to project commissioning for anode producers acquiring graphite mines. Qingdao and Yantai host batch furnace operations facing carbonization technician shortages that lag capacity expansion by 18-24 months.
Pearl River Delta
Guangdong province's battery replacement networks source standardized artificial graphite anodes for legacy EV fleets. SAMR enforces GB standards for battery cell safety and recyclability, compelling anode producers to certify traceability across raw material sourcing. Shenzhen's heavy-duty bus and truck batteries prioritize fast-charge artificial graphite formulations.
Sichuan-Chongqing
The western manufacturing corridor serves cost-optimized natural graphite anodes for the e-motorcycle aftermarket with lower energy density tolerances. The central bank's green credit facilities channel preferential lending toward anode recycling infrastructure. Chengdu-based aftermarket providers absorb standardized volumes for two-wheeler battery swaps.
China Electric Vehicle Battery Anode Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered qualification levels. Vertically integrated producers with captive mining assets command procurement preference under MIIT's domestic content thresholds. Three archetypes dominate: state-linked material giants with upstream resource control, mid-tier specialists in silicon-carbon composite engineering, and recycling-integrated operators qualifying for green credit facilities. Capacity expansion and backward integration into graphite mining represent the dominant competitive moves.
Among Yangtze River Delta-based producers, Ningbo Shanshan Co., Ltd. and BTR New Energy Material Ltd. exemplify contrasting strategic positions. Ningbo Shanshan occupies the resource-integrated tier with apparent captive supply advantages, while BTR New Energy Material Ltd. sits within the R&D-intensive specialist category. Jiangxi Zhengtuo New Energy Technology anchors the interior zone positioning, representing tax-advantaged production scale in the Ganzhou rare earth corridor.
| Leading Market Players |
|---|
| Ningbo Shanshan Co., Ltd. |
| BTR New Energy Material Ltd. |
| Jiangxi Zhengtuo New Energy Technology |
| Shanshan Technology |
| Jiangxi Zichen |
| Zhongke |
| Kaijin |
| Shangtai Tech |
| Putainuo |
| Others |
Pricing and Supply Chain Analysis
Carbonization furnace operator scarcity in Shandong and Heilongjiang provinces widens labor-cost spreads between premium synthetic graphite and economy natural graphite tiers. MIIT's domestic content mandates compress pricing power for importers while rewarding vertically integrated producers with captive mining assets.
Pricing Analysis
Lead-time-driven pricing stratifies across contract tiers, with CATL and BYD gigafactories paying premiums for 45-day just-in-time delivery against spot inventory discounts for batch furnace operators. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under SAMR's GB standards and volume scale of procurement. Cost compression in economy natural graphite is intensifying because Heilongjiang environmental shutdowns constrain feedstock availability. Aftermarket providers for two-wheeler battery swaps exhibit highest price sensitivity, while energy storage system developers absorb premium formulations for long-cycle-life guarantees.
Supply Chain Analysis
Certification gating under SAMR's 14-18 month GB standard compliance cycle restricts supplier qualification to incumbents with established traceability systems. Geographic supply concentration centers on China for spherical graphite processing, South Korea for high-purity synthetic graphite, and Japan for silicon-carbon composite precursors. Raw material dependencies rest on Heilongjiang natural graphite mining, Jiangxi rare earth processing infrastructure, and imported metallurgical-grade silicon. Single-source vulnerability concentrates in spherical graphite feedstock from environmental-regulated northern provinces. Distribution runs through Yangtze River Delta cell clusters co-located with containerized graphitization modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained through carbonization technician training pipelines lagging capacity expansion by 18-24 months, propping pricing for qualified producers.
For Market Incumbents: Deepen backward integration into Heilongjiang graphite mining to secure feedstock cost advantages against environmental shutdown volatility. Expand containerized graphitization deployment in Changzhou and Ningbo to compress working capital cycles. Prioritize pre-lithiation engineering investment to capture silicon-carbon composite premiums before solid-electrolyte interphase maturation commoditizes the technology. For New Entrants and Emerging Players: Dry electrode coating technology offers a qualification pathway bypassing solvent recovery capex requirements that exclude mid-tier competitors from CATL supplier lists. Target Ganzhou rare earth zone tax holidays for anode precursor capacity with subsidized utility costs. Pursue energy storage system formulations commanding 40% margin premiums above passenger car grades through long-cycle-life artificial graphite specialization. For Investors and Strategic Acquirers: The window for entry favors recycling-integrated operators qualifying for central bank green credit facilities before collateral requirement thresholds rise. Long-term viability hinges on closed-loop material recovery capabilities aligned with SAMR traceability mandates. Monitor MIIT NEV subsidy tier revisions as inflection indicator for silicon content ramp rates and graphite supply security trade-offs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Graphite Mining | Captive Heilongjiang feedstock supply insulates against MEE environmental shutdown volatility and export quota restrictions. |
| Silicon-Carbon Composite R&D Scale-Up | Pre-lithiation engineering maturity unlocks energy density thresholds above 300 Wh/kg for tier-one MIIT subsidy qualification. |
| Containerized Graphitization Deployment | Co-location with CATL and BYD gigafactories halves feedstock transport costs and compresses working capital cycles. |
| Closed-Loop Recycling Infrastructure | SAMR traceability compliance and central bank green credit facility eligibility create dual regulatory and financing advantages. |
| Ganzhou Rare Earth Zone Capacity Buildout | Jiangxi tax holidays and subsidized utilities pull production from coastal cost centers toward interior cost optimization. |
Research Methodology
Independent corroboration across MIIT policy filings, SAMR GB standard documentation, and central bank green credit facility records underwrites the qualitative findings in this study. Primary interviews with carbonization furnace operators, anode procurement managers at CATL and BYD, and MEE environmental compliance officers combined with secondary validation from customs trade data, SEC filings of listed anode producers, and Yangtze River Delta industrial cluster surveys. Bottom-up capacity installation tracking and top-down NEV production forecasts triangulate volume estimates.
Comparable-period anchoring to historical NEV subsidy tier revisions and graphite price volatility windows structured the projection horizon. Segmentation dimensions modeled include material type, end-user procurement scale, production method carbonization intensity, and application cycle-life specifications. CAGRs derived from installed capacity expansion timelines against MIIT localization mandate compliance curves. Industry-specific forecast inputs incorporate silicon content ramp assumptions and solid-electrolyte interphase engineering maturity curves.
Several conditions sit outside the modeled scope, including breakthrough solid-state battery commercialization timelines and disruptive cathode chemistry shifts altering paired anode specifications. Forecasts reflect documented assumptions about MEE environmental enforcement intensity and central bank collateral requirement stability. A model refresh is warranted upon material change in MIIT NEV subsidy tier thresholds or SAMR GB certification cycle duration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Li Metal Battery Market
Lithium-ion Battery
Automotive Lithium Ion Battery Market
Lithium-ion Battery
France Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Lithium Polymer Battery Market
Lithium-ion Battery
Li Air Battery Market
Lithium-ion Battery
Graphene Battery Technology Market
Lithium-ion Battery
Lithium Hydroxide Market
Lithium-ion Battery
Lithium Battery Pack Market
Lithium-ion Battery
Lifepo4 Battery Market
Lithium-ion Battery
Portable Lithium Battery Energy Storage Products Market
Lithium-ion Battery
Lithium-Ion UPS System Market
Lithium-ion Battery
India Lithium-Ion Battery Market
Lithium-ion Battery
Solid Electrolyte for Lithium Ion Battery Market
Lithium-ion Battery
United Kingdom Electric Vehicle Battery Anode Market
Lithium-ion Battery
Automotive Cylindrical Lithium Batteries Market
Lithium-ion Battery
Europe Lithium-Ion Battery for Electric Vehicle Market