
 Spiral Submerged Arc Welded (SSAW) Steel Pipe Market | 2026-2036
Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Insights
High-strength composite liners and corrosion-resistant alloys are expanding their addressable niche in sour-gas and subsea environments, pressuring plain carbon SSAW grades on total cost of ownership. Cangzhou Steel Pipe Group leverages integrated hot-rolling capacity to control substrate costs across the Hebei corridor. Baosteel Group anchors premium line pipe supply through API 5L X80 mastery for West-East Pipeline phases. Jindal SAW dominates Indian water and hydrocarbon transmission tenders with proximity to Middle East export lanes.
Spiral Submerged Arc Welded steel pipe is produced from hot-rolled steel coil formed into a helical seam and welded by submerged arc deposition, typically achieving wall thicknesses of 6–25 mm and diameters from 219 mm to over 3,000 mm for pressure containment and structural load-bearing. Line pipe commands the largest revenue pool due to oil and gas trunk line replacements, while coating pipe—particularly FBE and three-layer PE systems—captures expanding margin pools as operators prioritize corrosion management in offshore and high-temperature deployments. Water transportation applications in municipal and irrigation networks represent a structurally growing end-use segment as climate-adaptive infrastructure budgets harden across arid regions.
API 5L standards enforced by the American Petroleum Institute and ISO 3183 under the International Organization for Standardization govern chemical composition, mechanical testing, and weld integrity acceptance criteria, effectively filtering non-compliant producers from North American and European project bids. China's GB/T 9711 national standard and SAMR quality supervision protocols shape domestic procurement for state pipeline monopolies and regional water authorities. Stakeholders must monitor evolving hydrogen pipeline compatibility standards, as repurposed natural gas infrastructure specifications will redefine permissible steel grades and coating performance thresholds.
Market Dynamics
Large-diameter line pipe specifications are tightening around hydrogen compatibility and sour-gas resistance, forcing substrate upgrades across API 5L grade ladders and compressing margins for mills without integrated metallurgical R&D.
Growth Catalysts
- Offshore pipeline replacement cycles:North Sea and Gulf of Mexico operators are accelerating trunk line renewals to extend field life, with FERC-mandated integrity management programs driving scheduled procurement.
- REACH corrosion-protection mandates:European coating specifications now require enhanced FBE and three-layer PE systems for subsea deployments, expanding addressable premium product volumes.
- Shale infrastructure densification:Permian and Bakken gathering systems require high-frequency, smaller-batch orders for intermediate-diameter pipe, sustaining domestic mill order books.
Market Restraints
- Hot-rolled coil price volatility:Scrap and iron ore input swings transmit directly to substrate costs, eroding fixed-price contract profitability for non-integrated producers.
- Hebei corridor supply concentration:China's Cangzhou cluster controls roughly half of global spiral weld capacity, creating single-point disruption exposure for international project timelines.
- Composite liner substitution:Reinforced thermoplastic pipe is capturing sour-gas gathering applications below 20-inch diameter on total installed cost advantages.
Strategic Opportunities
- Hydrogen pipeline repurposing standards:Emerging ISO 19823-1 and national hydrogen framework specifications will redefine permissible steel grades, creating first-mover certification advantages.
- India-Middle East export corridor:Proximity to Saudi Aramco and ADNOC tender pipelines positions Jindal SAW and similar regional mills for long-haul water and hydrocarbon contracts.
- Digital twin integration:Convergence of ultrasonic testing data with predictive maintenance platforms enables outcome-based coating performance guarantees.
Industry Challenges
- Welding technician scarcity:Submerged arc welding certification programs face enrollment shortfalls in North America and Europe, constraining qualified crew availability for turnarounds.
- API 5L X80 qualification timelines:Extended Charpy and DWTT testing protocols delay grade upgrades by 12-18 months, freezing capacity allocation decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spiral Submerged Arc Welded (SSAW) Steel Pipe Market |
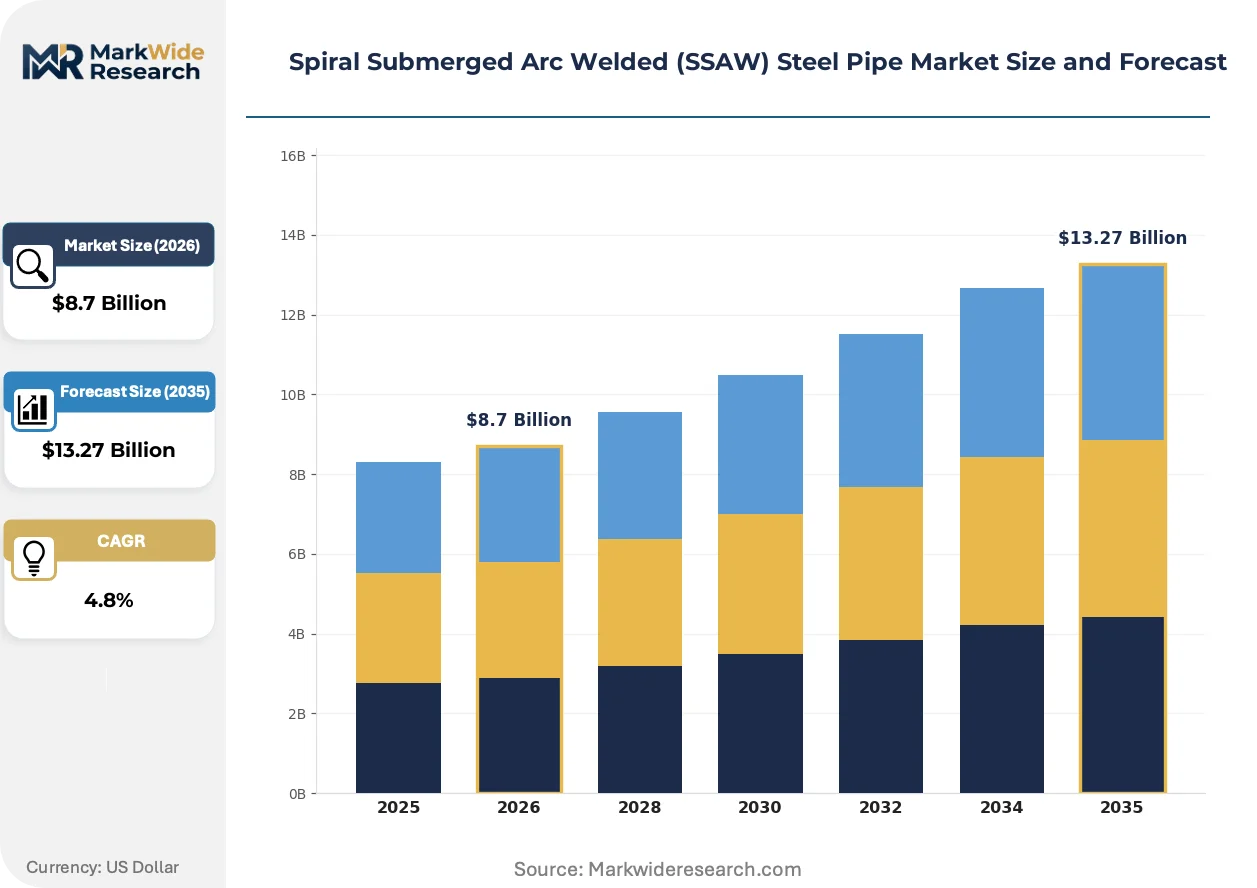
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Line Pipe, Structural Pipe, Casing Pipe, Coating Pipe End Use Industry: Oil & Gas, Water Transportation, Construction, Agriculture Pipe Diameter: Small Diameter, Medium Diameter, Large Diameter, Extra Large Diameter Coating Type: PE Coated, FBE Coated, Paint Coated, Others |
| Companies Covered | Cangzhou Steel Pipe Group, Baosteel Group, Jindal SAW, Shagang Group, Ansteel Group, EUROPIPE GmbH, Tianjin Youfa Steel Pipe Group, Tianjin Brisk Metalwork, Tenaris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Trends and Innovations
Material science advances and inspection automation are compressing the gap between commodity spiral weld and premium seamless alternatives, while procurement digitization is rewiring how operators source long-lead items.
Automated ultrasonic testing (AUT) with phased-array sensors is consolidating quality assurance protocols across offshore project specifications. Major oil and gas operators now mandate full-body scan coverage for subsea line pipe, displacing manual radiographic spot checks. This compression of inspection variance is enabling just-in-time delivery models that reduce yard inventory carrying costs.
EU F-Gas Regulation amendments are tightening volatile organic compound limits for pipe coating facilities, forcing solvent-based epoxy conversions to waterborne or powder systems. German and Dutch port authorities are enforcing these standards through berthing restrictions, redirecting coating capacity toward compliant Baltic and Mediterranean yards. The regulatory friction is accelerating capital deployment into low-emission curing ovens.
Direct mill procurement by national oil companies is bypassing traditional distributor networks for standard-diameter line pipe. Saudi Aramco and ADNOC now maintain approved manufacturer lists with annual volume commitments, compressing spot market liquidity. This channel consolidation is most pronounced in Middle Eastern water transmission and hydrocarbon trunk line segments.
Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Segmentation
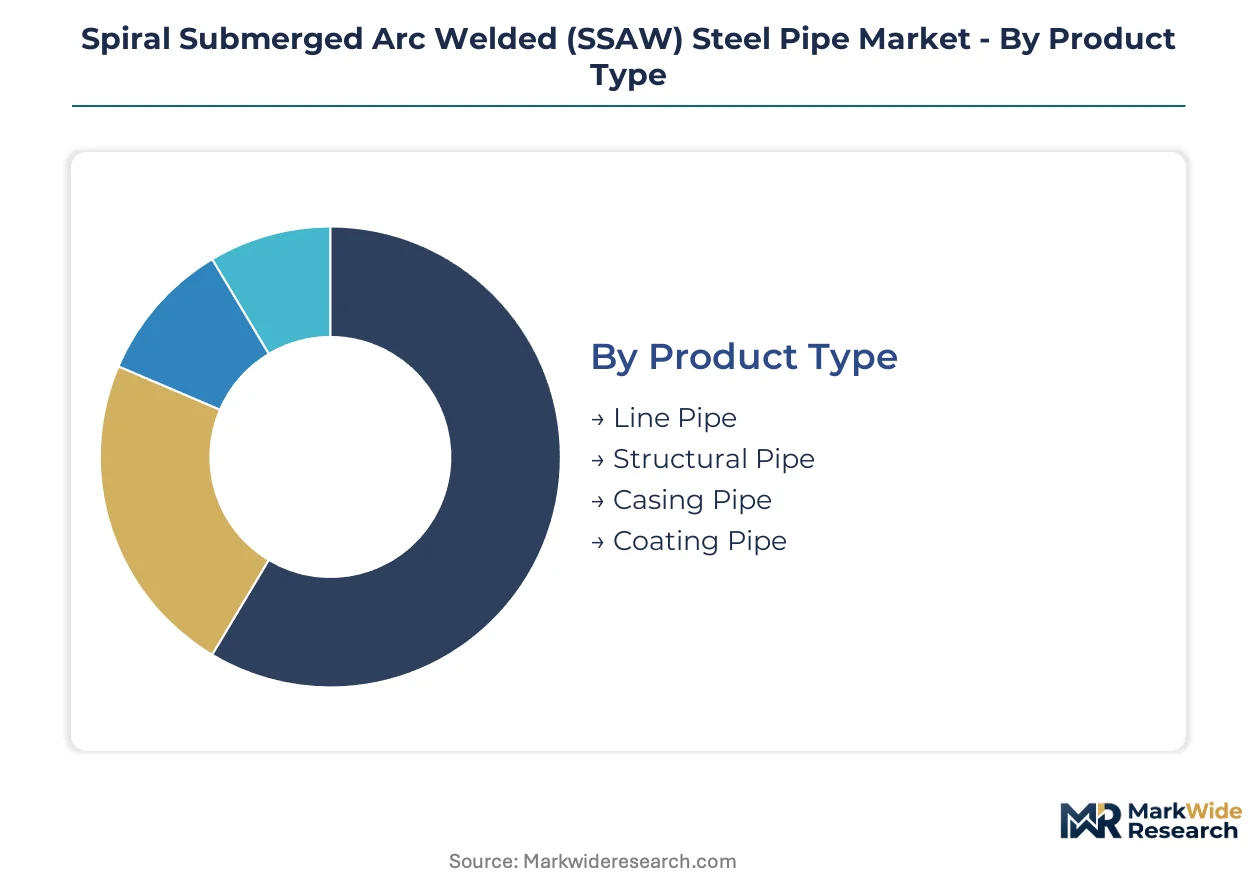
SSAW pipe procurement decisions split across pressure containment requirements, corrosion exposure severity, and installation logistics. Specification mismatches between product grade and end-use environment drive replacement costs and project delays.
Product Type:
Buyers prioritize pressure rating and weld integrity when selecting pipe category for hydrocarbon or water service.
- Line Pipe:API 5L-certified grades from X52 through X80 serve high-pressure hydrocarbon transmission. Offshore trunk line renewals in the Gulf of Mexico and North Sea concentrate procurement for large-diameter, sour-gas-resistant specifications.
- Coating Pipe:Three-layer PE and fusion-bonded epoxy systems extend field life in subsea and high-temperature deployments. REACH-mandated corrosion protection standards in European waters expand premium coating volumes.
- Structural Pipe:Non-pressure-rated grades support piling, bridge construction, and foundation loads.
- Casing Pipe:Protective sleeves for wellbore integrity in geothermal and water well applications.
Volume sits with Line Pipe; growth tilts toward Coating Pipe.
End Use Industry:
Application environment dictates material specification, with sour-gas resistance and potable water certification creating divergent procurement paths.
- Oil & Gas:Trunk line operators specify API 5L X70 and X80 grades for high-pressure, high-temperature service. FERC integrity management programs in the United States mandate scheduled replacement cycles for aging infrastructure.
- Water Transportation:Municipal transmission and irrigation networks drive demand for cement-mortar and epoxy-lined products. China's South-North Water Diversion project sustains mill utilization for large-diameter orders.
- Construction:Building frameworks and infrastructure piling consume structural grades without pressure certification.
- Agriculture:Irrigation laterals and drainage systems use thinner-wall, lower-grade specifications.
Oil & Gas commands installed base; water transportation climbs fastest on climate-adaptive infrastructure budgets.
Pipe Diameter:
Logistics constraints and welding crew availability shape diameter selection for project execution.
- Large Diameter:1,000 mm to 2,500 mm specifications dominate cross-country trunk lines and major water transmission corridors. Hebei corridor mills in China concentrate capacity for 1,500 mm-plus orders.
- Extra Large Diameter:Above 2,500 mm pipes serve specialized offshore riser and caisson applications. Limited qualified fabricators create supply bottlenecks for project-critical deliveries.
- Medium Diameter:Gathering systems and distribution networks in shale plays.
- Small Diameter:Utility service lines and process piping.
Large Diameter anchors revenue; Extra Large Diameter gains share on offshore project complexity.
Coating Type:
Regulatory compliance and service environment determine coating specification, with solvent restrictions reshaping application methods.
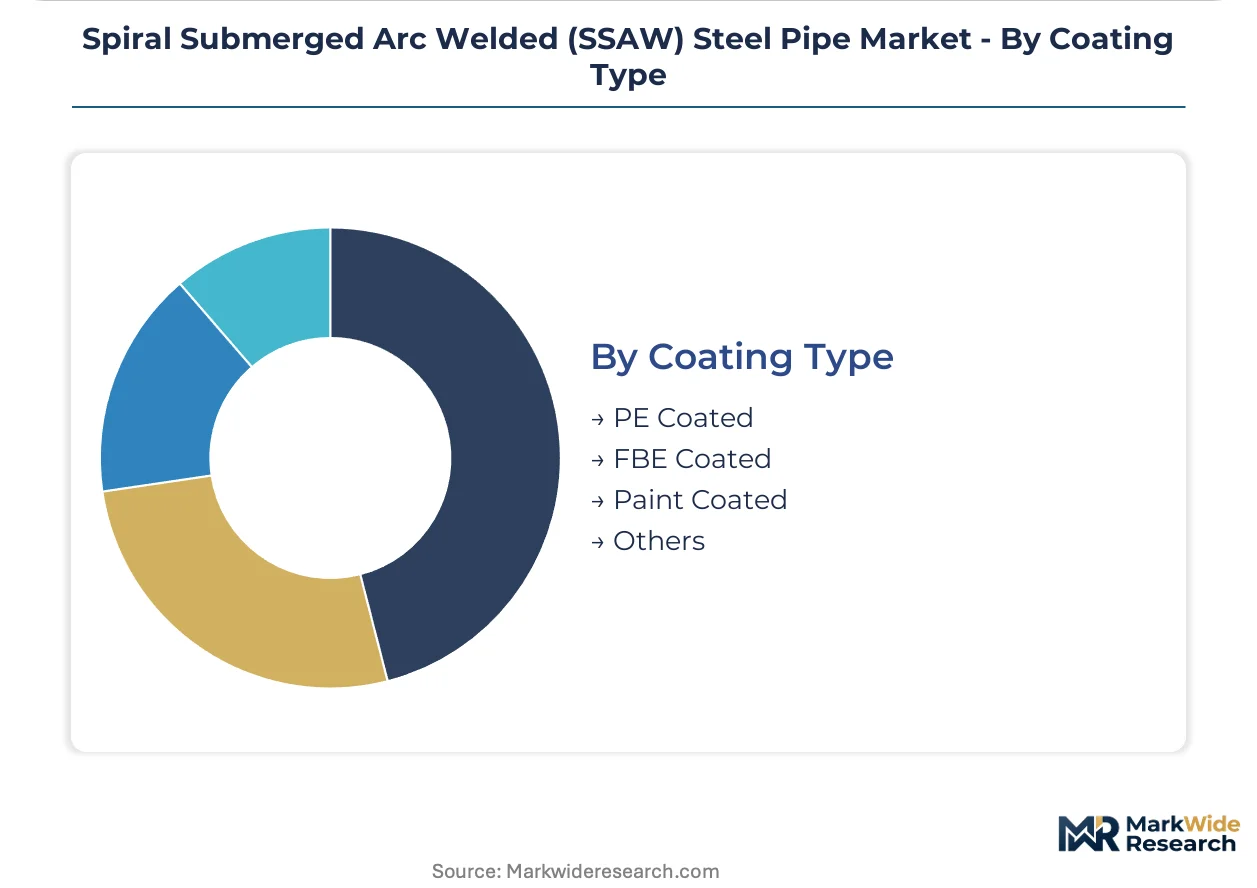
- FBE Coated:Fusion-bonded epoxy provides cathodic disbondment resistance for buried pipelines. EU F-Gas Regulation amendments force conversion from solvent-based to powder application systems.
- PE Coated:Three-layer polyethylene systems dominate subsea installations for mechanical protection and thermal insulation. German and Dutch port berthing restrictions redirect coating capacity to compliant Mediterranean yards.
- Paint Coated:Atmospheric corrosion protection for above-ground structural applications.
- Others:Cement mortar and tape systems for niche water and chemical service.
FBE Coated holds current volume; PE Coated expands most quickly on offshore deployment growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the largest share of SSAW steel pipe consumption through state-backed energy transmission corridors and inter-basin water diversion schemes. Procurement volumes split across hydrocarbon trunk lines, municipal water networks, and structural piling for coastal infrastructure.
China
West-East Pipeline phases and South-North Water Diversion sustain mill utilization for large-diameter orders. SAMR quality supervision protocols enforce GB/T 9711 compliance for state pipeline monopolies. The Hebei corridor around Cangzhou anchors half of global spiral weld capacity, serving domestic and export tenders.
United States
Permian and Bakken shale gathering systems drive intermediate-diameter orders for gathering infrastructure. FERC integrity management programs mandate scheduled replacement cycles for aging trunk lines. Gulf Coast fabricators concentrate coating capacity for offshore specifications.
Germany
North Sea pipeline replacement cycles and offshore wind jacket foundations sustain demand for sour-gas-resistant grades. EU F-Gas Regulation amendments force solvent-to-powder coating conversions at Baltic and North Sea yards. Ruhr-based distributors coordinate cross-border procurement for Central European utilities.
India
National water grid expansion and hydrocarbon transmission tenders absorb domestic mill output. BIS certification requirements filter non-compliant producers from public sector contracts. Jindal SAW anchors western India supply chains with proximity to Middle East export lanes.
Saudi Arabia
East-West crude oil pipeline extensions and seawater injection networks drive premium line pipe procurement. Saudi Aramco maintains approved manufacturer lists with annual volume commitments, compressing spot market liquidity. Jubail Industrial City hosts coating facilities serving offshore and high-temperature deployments.
Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated steel groups controlling substrate costs and independent fabricators competing on coating specialization. The vendor base clusters around three strategic archetypes: state-linked steel majors with captive hot-rolling capacity, regional specialists serving water and construction verticals, and premium-tier exporters holding API 5L X80 qualifications. Capacity expansion and certification upgrading dominate competitive moves, particularly for hydrogen compatibility and sour-gas resistance protocols.
Among Chinese state-linked producers, Cangzhou Steel Pipe Group and Baosteel Group occupy positions spanning commodity and premium grade ladders, while Jindal SAW represents the India-Middle East corridor specialist archetype. EUROPIPE GmbH anchors European premium-tier supply through integrated rolling and coating capabilities. These named entities exemplify how geographic proximity to demand corridors and metallurgical R&D depth stratify competitive positioning across procurement channels.
| Leading Market Players |
|---|
| Cangzhou Steel Pipe Group |
| Baosteel Group |
| Jindal SAW |
| Shagang Group |
| Ansteel Group |
| EUROPIPE GmbH |
| Tianjin Youfa Steel Pipe Group |
| Tianjin Brisk Metalwork |
| Tenaris |
| Others |
Pricing and Supply Chain Analysis
Submerged arc welding technician scarcity in North America and Europe widens labor-cost differentials between premium-certified and commodity-grade pipe tiers. API 5L X80 qualification timelines compress margin spreads as extended Charpy and DWTT testing protocols freeze capacity allocation decisions for mills without integrated metallurgical R&D.
Pricing Analysis
Volume concentrates in API 5L X52-X70 commodity grades where Chinese Hebei corridor mills compete on hot-rolled coil substrate costs, while margin pools shift toward X80 premium line pipe and three-layer PE coated systems for subsea deployments. Price differentiation hinges on certification tier and geographic delivery cost, with FERC-mandated integrity management programs in the United States sustaining contract premiums for domestic fabricators. Cost compression in commodity grades intensifies because scrap and iron ore input volatility transmits directly to substrate costs, eroding fixed-price contract profitability for non-integrated producers. Municipal water authorities exhibit highest price sensitivity due to budget-constrained procurement, while Saudi Aramco and ADNOC tender pipelines demonstrate lowest sensitivity through approved manufacturer lists with annual volume commitments.
Supply Chain Analysis
Dual-sourcing requirements from major oil and gas operators now mandate multi-supplier qualification for large-diameter trunk line orders, fragmenting procurement across Cangzhou Steel Pipe Group, Baosteel Group, and EUROPIPE GmbH to mitigate single-point disruption exposure. Raw material dependencies center on hot-rolled steel coil, iron ore, and scrap metal feeds, with coating chemistries drawing from epoxy resin and polyethylene suppliers. Single-source vulnerability concentrates in the Hebei corridor where roughly half of global spiral weld capacity clusters around Cangzhou. Distribution runs through direct mill procurement channels that Saudi Aramco and ADNOC have established, bypassing traditional distributor networks and compressing spot market liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API 5L X80 qualification timelines and submerged arc welding technician scarcity constrain effective capacity, propping pricing power for mills with integrated metallurgical R&D and certified crew availability.
For Market Incumbents: Anticipate reinforced thermoplastic pipe substitution in sour-gas gathering applications below 20-inch diameter by deepening backward integration into hot-rolling capacity and accelerating hydrogen compatibility certification under emerging ISO 19823-1 frameworks. Prioritize coating specialization in FBE and three-layer PE systems as EU F-Gas Regulation amendments force solvent-to-powder conversions and redirect capacity toward compliant Baltic and Mediterranean yards. For New Entrants and Emerging Players: Automated ultrasonic testing with phased-array sensors offers a technology-first wedge into offshore project specifications where major operators now mandate full-body scan coverage, displacing manual radiographic spot checks. Target the India-Middle East export corridor for water transmission tenders where Jindal SAW proximity advantages have not yet saturated procurement channels. Pursue digital twin integration partnerships with predictive maintenance platforms to enable outcome-based coating performance guarantees as a differentiated go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors regional specialists with API 5L X80 qualifications and proximity to Middle East tender pipelines, positioned for long-haul water and hydrocarbon contracts as national oil companies consolidate approved manufacturer lists. Monitor hydrogen pipeline repurposing standards development as the critical inflection signal, with first-mover certification advantages redefining permissible steel grades and coating performance thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Hebei corridor mills add large-diameter lines to capture West-East Pipeline phase orders. |
| Backward Integration | Cangzhou Steel Pipe Group controls hot-rolling substrate costs across the steel coil supply base. |
| Green Manufacturing Transition | EU F-Gas Regulation amendments force solvent-to-powder coating conversions at Baltic yards. |
| Long-term Supply Agreement | Saudi Aramco approved manufacturer lists compress spot market liquidity for standard diameters. |
| Joint Venture | Coating specialists partner with ultrasonic testing firms for digital twin integration platforms. |
Research Methodology
Independent corroboration across pipeline procurement officers at national oil companies, submerged arc welding certification program administrators, and coating facility operations managers underwrites the qualitative findings in this study. Primary interviews with EPC contractors, FERC compliance officers, and SAMR quality supervision officials combined with secondary validation from API certification databases, ISO standard revision trackers, and customs trade flow records. Bottom-up mill capacity surveys and top-down energy infrastructure investment pipelines were triangulated to anchor volume estimates.
Rate-of-change decomposition across the projection horizon isolates price elasticity effects from capacity expansion cycles and regulatory compliance cost pass-throughs. Segmentation dimensions modeled include product type, end-use industry, pipe diameter tier, coating specification, and regional procurement channel structure. CAGRs were derived from fitted trend extrapolation against announced project backlogs, with hydrogen pipeline compatibility standards and REACH corrosion-protection mandates as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced national oil company tender cancellations, abrupt Hebei corridor environmental enforcement actions, and trade policy shifts affecting hot-rolled coil import flows. Forecasts reflect documented assumptions about technician training program enrollment rates and API qualification timeline stability. Deviation in hydrogen framework specification adoption speed would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Green Petcoke Market
Petroleum Products
Global Petroleum Coke Market
Petroleum Products
Crude Oil Market
Petroleum Products
West Africa Refined Petroleum Products Market
Petroleum Products
PAG Base Oil Market
Petroleum Products
Crude Oil Pour Point Depressant Market
Petroleum Products
Petroleum Liquid Feedstock Market
Petroleum Products
Pale Oil Market
Petroleum Products
Petcoke Market
Petroleum Products
Automotive Oil Strainer Market
Petroleum Products
Pygas (Pyrolysis Gasoline) Market
Petroleum Products
Global Petroleum Pitch Market
Petroleum Products
France Refined Petroleum Product Market
Petroleum Products
Underground Storage Tanks Market
Petroleum Products
Gasoline-Naphtha-Crude-MTBE Market
Petroleum Products
Pyrolysis Gasoline Market