
 Alkylate Gasoline Market | 2026-2036
Alkylate Gasoline Market Size, Share, and Industry Trends Forecast 2026-2036
Alkylate Gasoline Market Insights
A shortage of hydrofluoric acid alkylation specialists is reorganizing how refiners staff and upgrade production units across the Gulf Coast and Rotterdam corridors. ExxonMobil Corporation leverages its proprietary sulfuric acid alkylation technology to sustain high-octane output without HF-related regulatory exposure. Valero Energy Corporation anchors its margin position through integrated refining and midstream logistics along the Texas and Louisiana coasts.
Alkylate gasoline consists of branched-chain paraffins produced through catalytic alkylation of isobutane with light olefins, yielding a product with research octane numbers typically exceeding 95 and near-zero aromatics or sulfur content. This composition makes it the preferred blending component for reformulated gasoline meeting stringent tailpipe emission limits. Premium gasoline occupies the largest value pool among product types due to consistent demand from high-compression engines and export markets, while oxygenated fuel variants are gaining share where seasonal volatility controls mandate ethanol-alkylate blends. On the application side, transportation absorbs the majority of volume, though aviation alkylate for piston-engine aircraft represents a concentrated margin segment with limited substitute availability.
The EPA enforces Tier 3 gasoline sulfur standards that effectively mandate alkylate inclusion to achieve the 10 parts-per-million cap without sacrificing octane performance. REACH and the EU Green Deal are progressively tightening aromatic and benzene limits in European gasoline pools, directing refiners toward paraffinic blendstocks. Stakeholders must monitor how California's LCFS and emerging state low-carbon fuel standards redefine carbon intensity scoring for alkylate relative to bio-based alternatives.
Market Dynamics
IMO 2020 sulfur caps and Tier 3 gasoline standards are forcing refiners to reconfigure alkylation capacity, concentrating investment along the US Gulf Coast and Rotterdam corridors where blending infrastructure already exists.
Growth Catalysts
- Tier 3 Sulfur Standards:EPA mandates for 10 ppm gasoline sulfur effectively require alkylate inclusion to maintain octane ratings, locking in demand from US refiners upgrading hydrotreaters.
- Aviation Piston Fuel:FAA specifications for 100LL replacement are driving alkylate formulations for high-performance aircraft engines with no paraffinic substitutes available.
- HF Alkylation Phaseout:Safety pressures on hydrofluoric acid units in Texas and Louisiana are accelerating sulfuric acid technology conversions, preserving capacity without regulatory shutdowns.
Market Restraints
- Isobutane Supply Volatility:Steam cracker operating rates and natural gas liquids fractionation capacity in Mont Belvieu directly constrain feedstock availability for alkylation units.
- Ethanol Blending Walls:The US Renewable Fuel Standard creates oxygenate mandates that displace alkylate volume in summer Reid Vapor Pressure-constrained markets.
- Electrification Displacement:Battery electric vehicle penetration in California and the EU is compressing long-term gasoline pool demand, stranding alkylation investments.
Strategic Opportunities
- India BS-VI Expansion:Indian refiners upgrading to Bharat Stage VI specifications present first-mover advantage for sulfuric acid alkylation technology licensors as aromatic limits tighten.
- Renewable Alkylate Pathways:Bio-isobutane from fermentation and catalytic upgrading of biomass-derived olefins opens circular carbon routes for EU Green Deal compliance.
- Merchant Alkylate Trading:Arbinet-style spot platforms for high-octane blendstocks are emerging in Singapore and Rotterdam, disintermediating traditional term contracts.
Industry Challenges
- HF Specialist Scarcity:Refiners operating legacy hydrofluoric acid units face acute shortages of certified alkylation engineers, forcing overtime regimes and deferred maintenance.
- Catalyst Supply Concentration:Sulfuric acid alkylation catalyst regeneration depends on a handful of North American service providers, creating single-source vulnerability.
- Carbon Accounting Complexity:California LCFS and emerging state low-carbon fuel standards assign divergent carbon intensity scores to alkylate versus bio-based alternatives, complicating margin optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alkylate Gasoline Market |
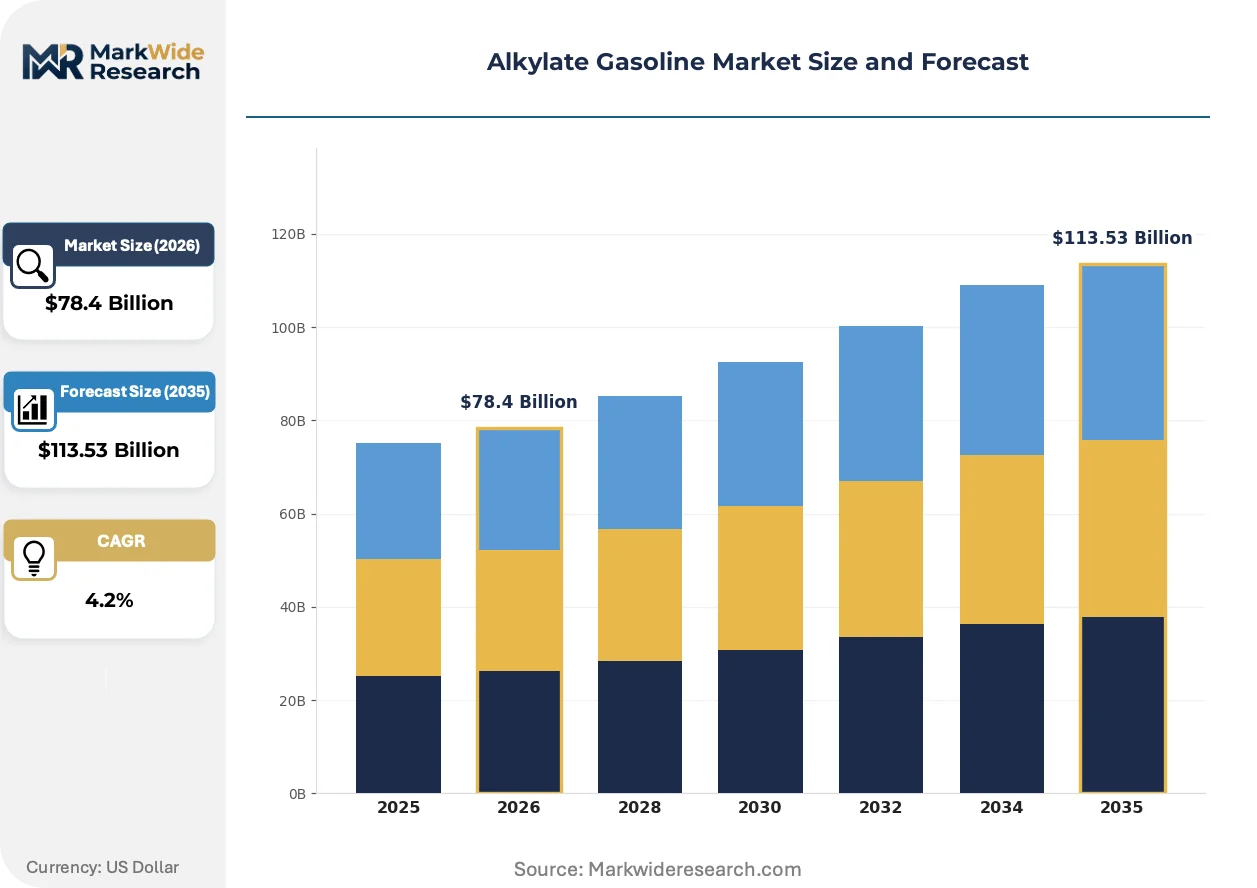
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $113.53 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reformulated Gasoline, Premium Gasoline, Racing Fuel, Oxygenated Fuel Application: Transportation, Aviation, Marine, Industrial Distribution Channel: Retail Outlets, Online Sales, Wholesale, Direct Supply End User: Consumers, Fleet Operators, Aviation Companies, Shipping Companies |
| Companies Covered | BP, Valero Energy Corporation, ExxonMobil Corporation, Phillips 66, Marathon Petroleum Corporation, Chevron Corporation, TotalEnergies, Neste Oyj, Royal Dutch Shell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alkylate Gasoline Market Trends and Innovations
Alkylation technology is splitting into two parallel development tracks as refiners weigh safety against capital efficiency, while regulatory carbon accounting redefines competitive advantage in blending markets.
Solid-acid alkylation catalysts are bifurcating the technology landscape between conventional liquid-acid units and emerging heterogeneous systems. European refiners in Rotterdam and Antwerp are piloting zeolite-based processes to eliminate acid handling entirely. This technology is bifurcating capital deployment strategies, with greenfield projects favoring solid-acid while brownfield sites retrofit sulfuric acid trains.
REACH aromatic limits and the EU Green Deal are progressively tightening benzene specifications in European gasoline pools. Refiners are redirecting reformate to petrochemical feedstock and backfilling octane with imported alkylate. Mediterranean terminals in Spain and Italy are expanding storage to handle this structural shift in blendstock sourcing.
Fleet operators are consolidating procurement around certified low-carbon gasoline pools with documented carbon intensity scores. Large trucking and delivery fleets in California are now specifying alkylate-heavy formulations to optimize LCFS credit generation. This behavioral shift is visible in contract structures that unbundle fuel supply from carbon credit ownership, forcing refiners to price CI attributes separately.
Alkylate Gasoline Market Segmentation
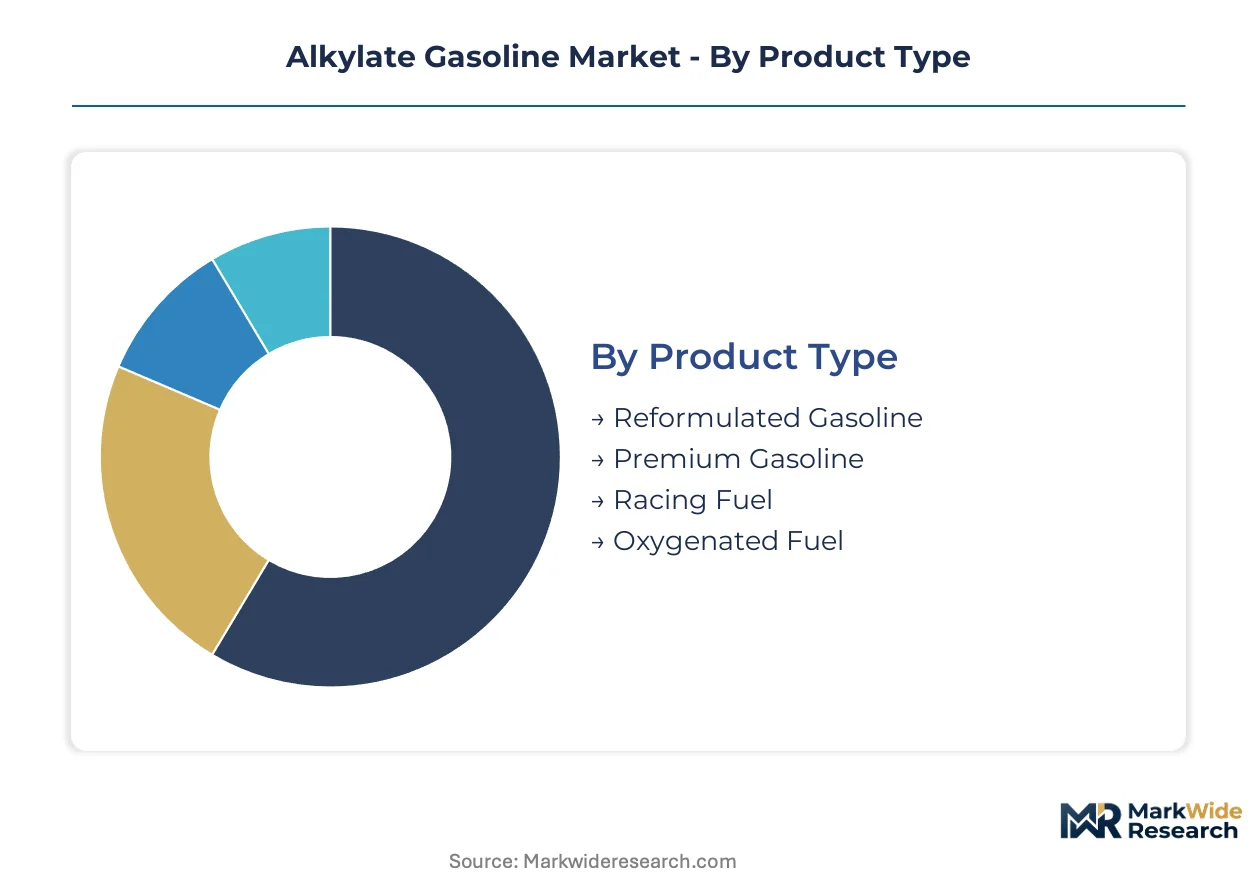
Alkylate gasoline flows through distinct channel configurations depending on specification grade and end-use certification requirements. Refinery blenders, merchant traders, and integrated oil companies each dominate different segment combinations based on sulfur handling capabilities and octane delivery guarantees.
Product Type:
Premium gasoline and reformulated gasoline move predominantly through wholesale terminals and direct supply contracts to refiners, while racing fuel and oxygenated variants split between specialized distributors and regulated retail channels.
- Premium Gasoline:High-octane alkylate blendstock with research octane numbers exceeding 95, formulated for high-compression engines and export markets. Demand concentrates among integrated refiners along the US Gulf Coast and Rotterdam corridor seeking to meet Tier 3 sulfur caps without octane degradation. Fleet operators in California specify this grade to optimize LCFS credit generation through documented carbon intensity scores.
- Reformulated Gasoline:Low-aromatic, low-sulfur formulations designed for EPA compliance in non-attainment zones. Refiners in Texas and Louisiana backfill octane shortfalls from hydrotreater upgrades by blending alkylate into these mandated summer-grade pools. The EPA's 10 ppm sulfur standard effectively locks in alkylate inclusion for this segment.
- Racing Fuel:Ultra-high-octane formulations for motorsport applications with strict aromatic prohibitions. Demand flows through specialty chemical distributors rather than mainstream fuel terminals.
- Oxygenated Fuel:Seasonal blends incorporating ethanol-alkylate combinations to manage Reid Vapor Pressure constraints. Retail outlets in RVP-controlled markets handle the majority of volume.
By volume, reformulated gasoline leads. By growth pace, premium gasoline is ahead.
Application:
Transportation and aviation applications generate margin through specification premiums, while marine and industrial offtake runs on term contracts indexed to regional benchmark differentials.
- Transportation:Road gasoline blending for passenger vehicles and commercial fleets. California trucking operators now specify alkylate-heavy formulations to capture LCFS credits, unbundling fuel supply from carbon attribute ownership in contract structures. This application absorbs the majority of alkylate volume globally.
- Aviation:Piston-engine aircraft fuel formulations replacing leaded avgas under FAA specifications. Alkylate represents the only paraffinic substitute capable of delivering 100+ motor octane without tetraethyl lead. No alternative blendstock exists for this concentrated margin segment.
- Marine:IMO 2020-compliant distillate blending for coastal vessels and harbor craft. Demand clusters in Singapore and Rotterdam bunkering hubs.
- Industrial:Solvent and process fuel applications requiring low-aromatic feedstocks. Offtake runs through direct supply agreements with chemical manufacturers.
Transportation dominates absolute volume. Aviation commands the steepest expansion trajectory as 100LL phaseout accelerates.
Distribution Channel:
Channel selection tracks batch size and certification requirements, with wholesale terminals handling standard grades and direct supply locking in specification-critical aviation and marine volumes.
- Wholesale:Terminal-to-terminal transfers of standard-grade alkylate for gasoline blending. The US Gulf Coast and Rotterdam concentrate this channel through existing storage and pipeline infrastructure.
- Direct Supply:Dedicated pipeline or vessel deliveries to refiners and aviation fueling depots. Aviation companies in California and Texas require certified handling chains for piston fuel specifications.
- Retail Outlets:Branded gasoline stations in RVP-controlled markets dispensing oxygenated seasonal blends.
- Online Sales:Emerging spot platforms for high-octane blendstocks in Singapore and Rotterdam, disintermediating traditional term contracts.
Wholesale channels move the most volume. Online sales are climbing the fastest as merchant trading platforms mature.
End User:
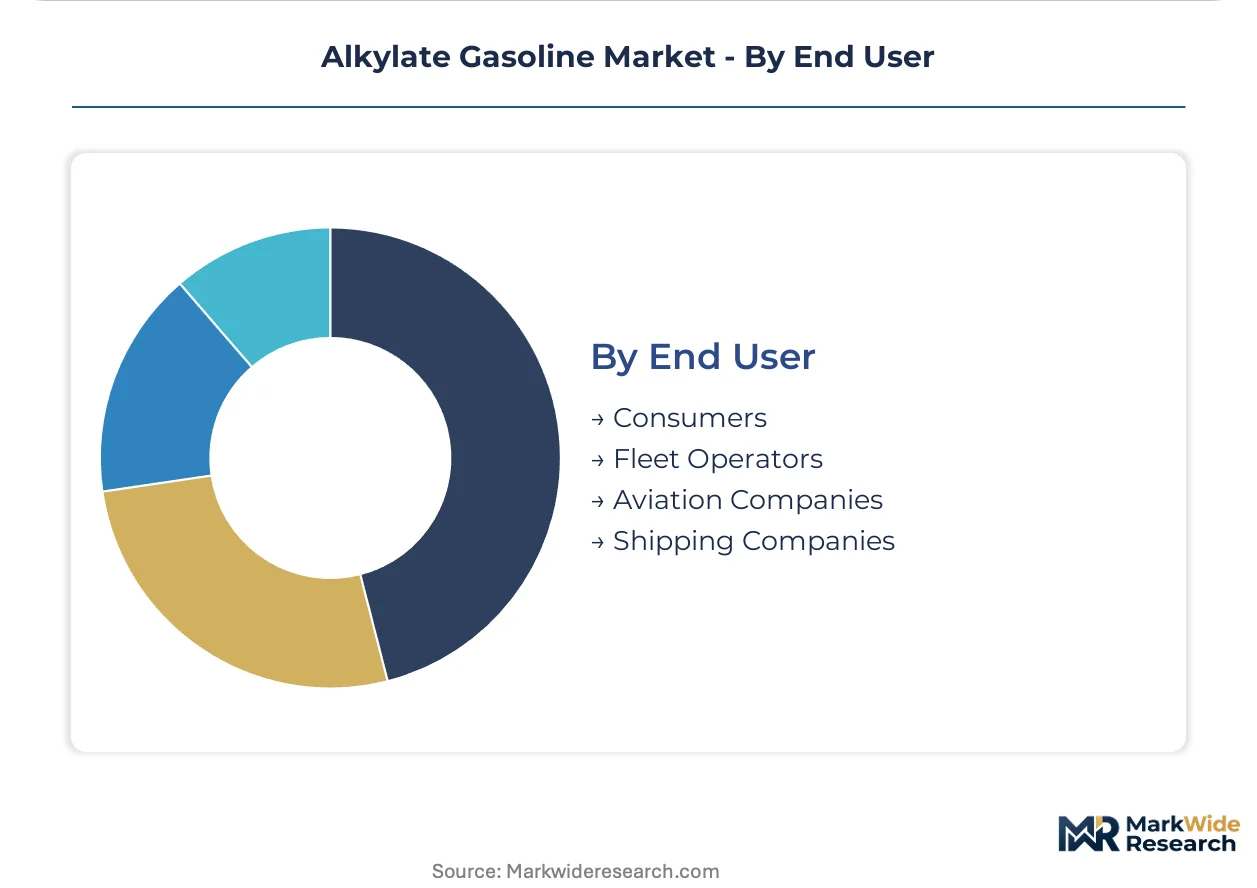
Fleet operators and aviation companies consolidate procurement around certified low-carbon pools, while consumers access alkylate only as a blended component within finished gasoline.
- Fleet Operators:Large trucking and delivery fleets specifying documented carbon intensity scores for LCFS compliance. California-based operators now unbundle fuel purchase from credit ownership, forcing separate pricing of CI attributes.
- Aviation Companies:Fixed-base operators and regional airlines sourcing 100LL replacement fuels. FAA specifications drive alkylate formulations with no available paraffinic substitute.
- Shipping Companies:Coastal and harbor vessel operators under IMO 2020 sulfur caps. Demand concentrates in Mediterranean terminals expanding storage for low-sulfur blendstocks.
- Consumers:End-users of finished gasoline containing alkylate as a blending component, with no direct purchase relationship to alkylate suppliers.
Fleet operators lead by volume commitment. Aviation companies are expanding most quickly as 100LL replacement timelines tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Tier 3 sulfur standards and IMO 2020 marine fuel regulations anchor United States demand for alkylate gasoline as refiners reconfigure blending operations to meet sub-10 ppm gasoline pools.
United States
Fleet operators in California specify alkylate-heavy formulations to optimize LCFS credit generation through documented carbon intensity scores. The EPA enforces Tier 3 gasoline sulfur standards that mandate alkylate inclusion for octane preservation without sulfur degradation. Texas and Louisiana concentrate Gulf Coast blending capacity where ExxonMobil and Valero anchor integrated refining and midstream logistics networks.
Netherlands
Rotterdam refiners pilot zeolite-based solid-acid alkylation to eliminate acid handling under REACH aromatic limits and EU Green Deal benzene restrictions. ECHA progressively tightens gasoline pool specifications, redirecting reformate to petrochemical feedstock and backfilling octane with imported alkylate. Mediterranean terminals in Spain and Italy expand storage infrastructure to handle this structural shift in European blendstock sourcing.
India
Indian refiners upgrading to Bharat Stage VI specifications present first-mover advantage for sulfuric acid alkylation technology licensors as aromatic limits tighten under national clean fuel mandates. The country's national petroleum regulator enforces sulfur caps comparable to Euro 6 standards, forcing octane-preserving blendstock investments. Reliance Industries and Indian Oil Corporation concentrate capacity around Jamnagar and Paradip refining complexes.
Singapore
Marine bunkering demand for IMO 2020-compliant distillate blending concentrates in Singapore harbor craft and coastal vessel markets. The Maritime and Port Authority enforces low-sulfur fuel regulations that redirect intermediate streams toward alkylate-inclusive formulations. Jurong Island petrochemical clusters integrate alkylation capacity with export-oriented gasoline blending for Southeast Asian distribution.
Germany
German refiners in the Antwerp-Rotterdam-Rhine-Ruhr corridor face EU Green Deal carbon intensity scoring that revalues alkylate relative to bio-based alternatives. The Federal Environment Agency implements REACH aromatic limits that progressively tighten benzene specifications in transport fuel pools. Bayernoil and Shell Rheinland facilities near Ingolstadt and Cologne adapt blending configurations to preserve octane ratings under hydrotreater upgrade constraints.
Alkylate Gasoline Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in alkylate gasoline supply, with vertical integration into refining and midstream infrastructure determining margin capture. The upper tier comprises multinational oil majors with captive alkylation capacity, while merchant traders and regional blenders occupy downstream positions. Two strategic archetypes dominate: technology licensors with proprietary sulfuric acid processes, and logistics-integrated refiners with Gulf Coast or Rotterdam terminal access. Capacity expansion and technology licensing represent the primary competitive vectors as HF alkylation phaseout accelerates.
Within the integrated major tier, ExxonMobil Corporation and Valero Energy Corporation exemplify divergent positioning strategies. ExxonMobil represents the technology-licensor archetype with proprietary sulfuric acid alkylation systems that eliminate HF-related regulatory exposure. Valero anchors the logistics-integrated archetype through midstream control along Texas and Louisiana coasts. BP and TotalEnergies occupy intermediate positions spanning European and North American refining footprints. Specialist technology providers and merchant traders sit below this tier, supplying regional blenders without captive alkylation units.
| Leading Market Players |
|---|
| BP |
| Valero Energy Corporation |
| ExxonMobil Corporation |
| Phillips 66 |
| Marathon Petroleum Corporation |
| Chevron Corporation |
| TotalEnergies |
| Neste Oyj |
| Royal Dutch Shell |
| Others |
Pricing and Supply Chain Analysis
Gulf Coast alkylation capacity utilization above 85 percent generates scale economies that compress unit costs and establish regional price floors for high-octane blendstocks. This concentration of sulfuric acid alkylation trains along the Texas and Louisiana corridor concentrates pricing power among integrated refiners while exposing buyers to transport premiums for volumes sourced outside this hub.
Pricing Analysis
Mont Belvieu spot differentials between refinery-grade alkylate and conventional gasoline blendstocks typically span 15-25 cents per gallon, reflecting quality premiums for low-sulfur, high-octane specifications. Price differentiation hinges on octane delivery guarantees and certified carbon intensity scores for California LCFS compliance, with aviation alkylate commanding the steepest premiums due to FAA specification stringency and absence of paraffinic substitutes. Cost compression in merchant alkylate supply is intensifying because Rotterdam and Singapore trading platforms are disintermediating traditional term contracts. Fleet operators in California exhibit the lowest price sensitivity as they unbundle fuel procurement from carbon credit ownership, while independent refiners without captive alkylation capacity face acute margin pressure from feedstock volatility.
Supply Chain Analysis
Houston Ship Channel transit infrastructure underwrites the majority of US alkylate movements, with pipeline connectivity to Colonial and Explorer systems determining downstream reach. Manufacturing concentrates in the United States, Netherlands, and Singapore, where integrated refining complexes anchor global supply. Feedstock procurement draws from natural gas liquids fractionation at Mont Belvieu, steam cracker byproduct recovery, and imported isobutane cargoes. Single-source vulnerability in sulfuric acid catalyst regeneration services creates operational risk for brownfield units dependent on North American service providers. Distribution runs through wholesale terminals for standard grades, with direct pipeline deliveries locking in aviation and marine volumes requiring certified handling chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified alkylation engineer scarcity is constraining operational readiness across legacy hydrofluoric acid units and forcing overtime regimes that degrade maintenance quality. This capability gap threatens production continuity for refiners without sulfuric acid conversion pathways or solid-acid pilot programs underway.
For Market Incumbents: Compound technology licensing revenues by deploying proprietary sulfuric acid alkylation systems to Indian refiners upgrading to Bharat Stage VI specifications, while accelerating solid-acid pilot programs in Rotterdam to eliminate acid handling entirely. Capture backward integration into isobutane supply through long-term offtake agreements with Mont Belvieu fractionators to defend margin position against feedstock volatility. Electrification of California and EU vehicle fleets poses stranded asset risk for alkylation capacity without renewable alkylate pathway development.
For New Entrants and Emerging Players: Merchant alkylate trading platform development represents the most penetrable service-layer gap, as incumbent integrated refiners under-serve spot market participants seeking certified high-octane blendstocks outside term contract structures. Target aviation piston fuel formulation services for fixed-base operators in California and Texas, where FAA 100LL replacement timelines concentrate demand with no paraffinic substitute availability. Establish go-to-market presence through carbon intensity certification partnerships that enable fleet operators to unbundle fuel supply from LCFS credit ownership.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among technology licensors with proprietary sulfuric acid alkylation processes and long-term service contracts for catalyst regeneration and unit optimization. Long-term viability over a five-to-ten-year horizon hinges on renewable alkylate pathway maturation and solid-acid technology commercialization, positioning integrated refiners with Gulf Coast or Rotterdam terminal access as preferred acquisition targets. Monitor California LCFS carbon intensity score revisions for alkylate relative to bio-based alternatives as the critical inflection indicator for margin trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing | Proprietary sulfuric acid alkylation systems eliminate HF regulatory exposure for refiners in Texas and Louisiana. |
| Capacity Expansion | Indian refiners upgrading to Bharat Stage VI specifications require octane-preserving blendstock investments at Jamnagar and Paradip. |
| Backward Integration | Long-term isobutane offtake agreements with Mont Belvieu fractionators anchor feedstock cost predictability. |
| Merchant Trading Platform | Arbinet-style spot markets in Singapore and Rotterdam disintermediate traditional term contract structures. |
| Renewable Pathway Development | Bio-isobutane from fermentation enables EU Green Deal compliance for European refiners in Rotterdam corridor. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with refinery operations managers, alkylation technology licensors, marine fuel procurement officers, and aviation fixed-base operators; and secondary validation through EIA refinery capacity reports, EPA Tier 3 compliance filings, IMO 2020 marine fuel quality data, and SEC 10-K disclosures from integrated refining companies. Bottom-up capacity modeling triangulated against top-down gasoline pool demand projections.
Across the projection horizon, the analytical framework segmented alkylate gasoline by product grade tier, end-use application, distribution channel configuration, and regional regulatory cluster. CAGRs were derived from capacity utilization trends, feedstock cost trajectories, and substitution elasticity estimates for ethanol and renewable blendstocks. Forecast inputs incorporated sulfuric acid technology conversion timelines, solid-acid pilot program outcomes, and LCFS carbon intensity score methodology revisions.
Material uncertainties — feedstock price volatility, electrification penetration rates, and renewable alkylate technology maturation — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as California LCFS scoring methodologies and EU Green Deal aromatic limits evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Petroleum Benzine Market
Petroleum Products
Spindle Oil Market
Petroleum Products
Global Petroleum Pitch Market
Petroleum Products
Performance Oil Sales Market
Petroleum Products
Oil Refining Market
Petroleum Products
Saudi Arabia Refined Petroleum Products Market
Petroleum Products
Marine Minerals Market
Petroleum Products
Hydrocarbon Market
Petroleum Products
North America Natural Gas Liquids Market
Petroleum Products
Pyrolysis Gasoline Market
Petroleum Products
Naphtha Market
Petroleum Products
Automotive Oil Strainer Market
Petroleum Products
Oil Refinery Market
Petroleum Products
Automotive Oil Market
Petroleum Products
Europe Refined Petroleum Products Market
Petroleum Products
Malaysia Refined Petroleum Products Market