
 Angola Oil and Gas Upstream Market | 2026-2036
Angola Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Angola Oil and Gas Upstream Market Outlook
ISO 14001 environmental management certification is redrawing the competitive landscape for offshore operators seeking Angolan acreage. TotalEnergies SE leverages its pre-salt expertise to sustain drilling programs in Block 17 and Block 32. Azule Energy anchors its position through the combination of BP Plc and Eni SpA legacy assets in the country. Chevron Corporation competes via its long-standing presence in the Cabinda enclave operations.
Angola oil and gas upstream encompasses the search for, recovery of, and initial processing of crude oil and natural gas reservoirs, with operations typically occurring at depths exceeding 1,500 meters in the Lower Congo Basin. The primary purpose centers on delivering feedstock to the Luanda refinery and export terminals for international offtake. Offshore Platforms dominate capital allocation due to the preponderance of deepwater discoveries, while Subsea Systems represent the fastest-growing technology segment as operators push into ultra-deepwater frontiers. Enhanced Oil Recovery commands attention among mature fields where natural pressure decline has reduced output from legacy wells.
Angola's petroleum regulator, the Agência Nacional de Petróleo, Gás e Biocombustíveis (ANPG), governs concession rounds and local content thresholds that reshape contractor selection. Sonangol's dominance as a national oil company creates dual regulatory pressure through production-sharing contract terms and domestic supply obligations. Stakeholders must weigh pre-salt exploration economics against the capital intensity of subsea tieback architectures before committing to new block awards.
Market Dynamics
Sonangol's local content mandates are restructuring contractor selection criteria across Angola's offshore acreage, forcing international operators to deepen partnerships with domestic service firms before bid submission deadlines.
Growth Catalysts
- Pre-salt geology:The Kwanza Basin's salt-layer formations mirror Brazil's productive analogs, attracting seismic survey investment from firms seeking analogous reservoir architecture.
- ANPG concession rounds:Regular block auctions under Angola's 2019 petroleum reform law refresh exploration portfolios for qualified bidders meeting revised technical thresholds.
- Subsea tieback engineering:Advances in subsea processing modules enable marginal field development without platform construction, unlocking stranded reserves in ultra-deepwater blocks.
Market Restraints
- Capital intensity:Deepwater drilling economics require oil prices sustained above break-even thresholds that many pre-salt projects struggle to achieve.
- Equipment supply concentration:Subsea trees and manifolds source from a narrow base of European and Asian fabricators, creating delivery bottlenecks during cycle upswings.
- Natural pressure depletion:Mature fields in the Lower Congo Basin suffer output declines that waterflooding cannot fully offset without gas injection infrastructure.
Strategic Opportunities
- Cabinda enclave redevelopment:Chevron's legacy infrastructure offers tieback potential for adjacent discoveries that bypass greenfield platform commitments.
- Associated gas commercialization:Stranded gas from oil-dominant fields feeds emerging LNG export capacity at the Soyo plant, monetizing previously flared volumes.
- ISO 14001 certification:Environmental management credentials differentiate bidders in ANPG technical scoring, creating competitive advantage for certified contractors.
Industry Challenges
- Deepwater drilling crew scarcity:Angola competes with Brazil and West Africa for limited pools of pre-salt competent engineers and dynamic positioning operators.
- Local content compliance timelines:Sonangol's workforce and supplier mandates compress project schedules, requiring earlier engagement with Angolan joint-venture partners.
- Legacy platform integration:New subsea tiebacks must interface with aging FPSO systems designed for different fluid specifications and processing capacities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Angola Oil and Gas Upstream Market |
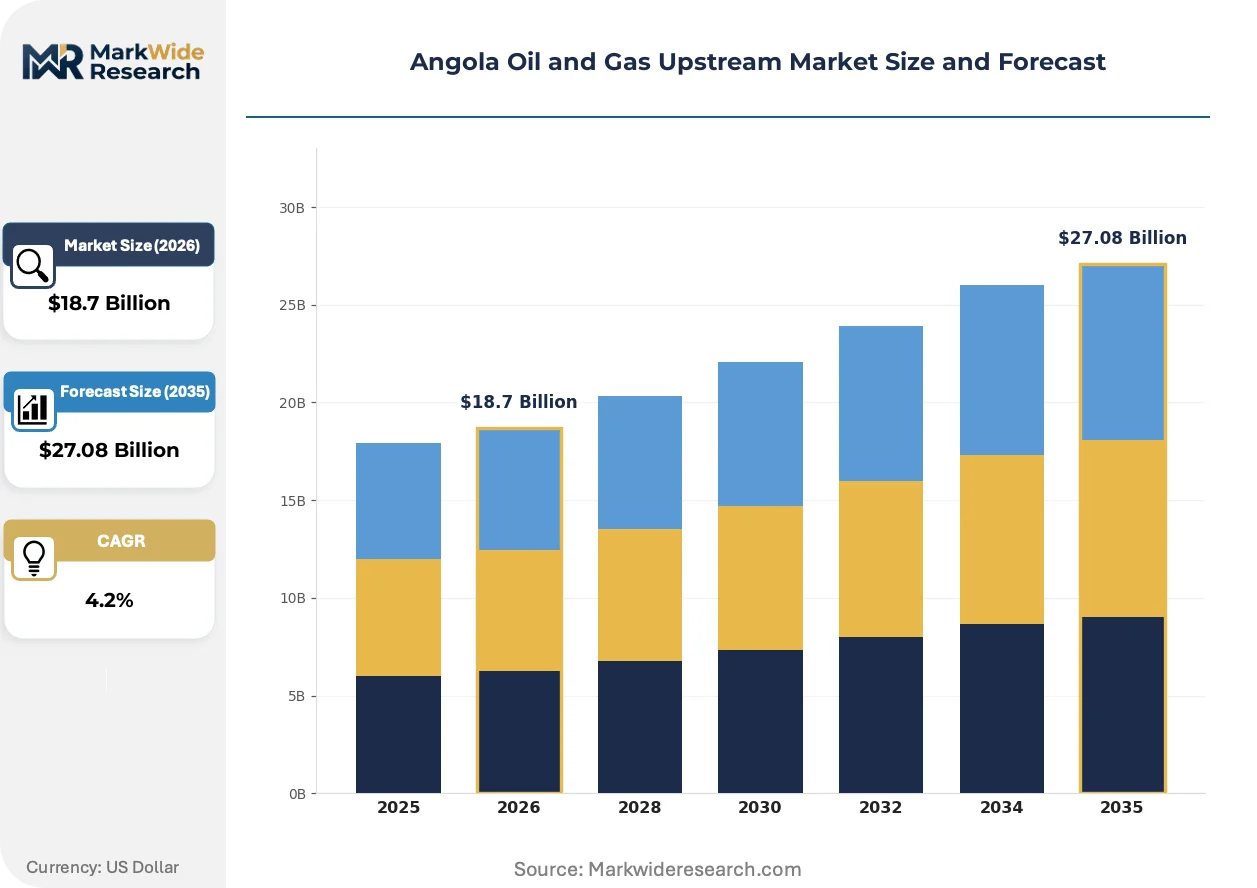
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exploration, Drilling, Production, Services Technology: Offshore Platforms, Subsea Systems, Enhanced Oil Recovery, Well Completion End User: National Oil Companies, Independent Producers, Oilfield Service Providers, Contractors Installation: Onshore Facilities, Offshore Installations, Submersible Systems, Mobile Units |
| Companies Covered | Azule Energy, BP Plc, TotalEnergies SE, Equinor ASA, Sonangol, ExxonMobil Corporation, Eni SpA, Petronas, Chevron Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Angola Oil and Gas Upstream Market Strategic Shifts
Digital reservoir characterization and modular subsea architectures are compressing development timelines for Angola's most technically demanding offshore blocks.
Electrical submersible pump systems with permanent magnet motors are fragmenting the artificial lift market in deepwater applications. Operators in Block 17 and Block 32 deploy these units for higher efficiency at extreme depths. The technology is fragmenting capital allocation between traditional beam pump retrofits and subsea boosting investments.
ANPG's revised local content regulations now mandate minimum Angolan workforce ratios and domestic supplier spending floors for all production-sharing contracts. These thresholds reshape contractor pre-qualification and joint-venture formation. Deepwater block operators respond by embedding local partners earlier in project design phases.
Integrated project delivery contracts are displacing traditional engineering-procurement-construction splits for subsea developments. Major operators bundle design, fabrication, and installation under single accountability structures. This consolidation is most visible in Kwanza Basin pre-salt projects where interface risk between multiple contractors previously delayed first oil.
Angola Oil and Gas Upstream Market Segmentation
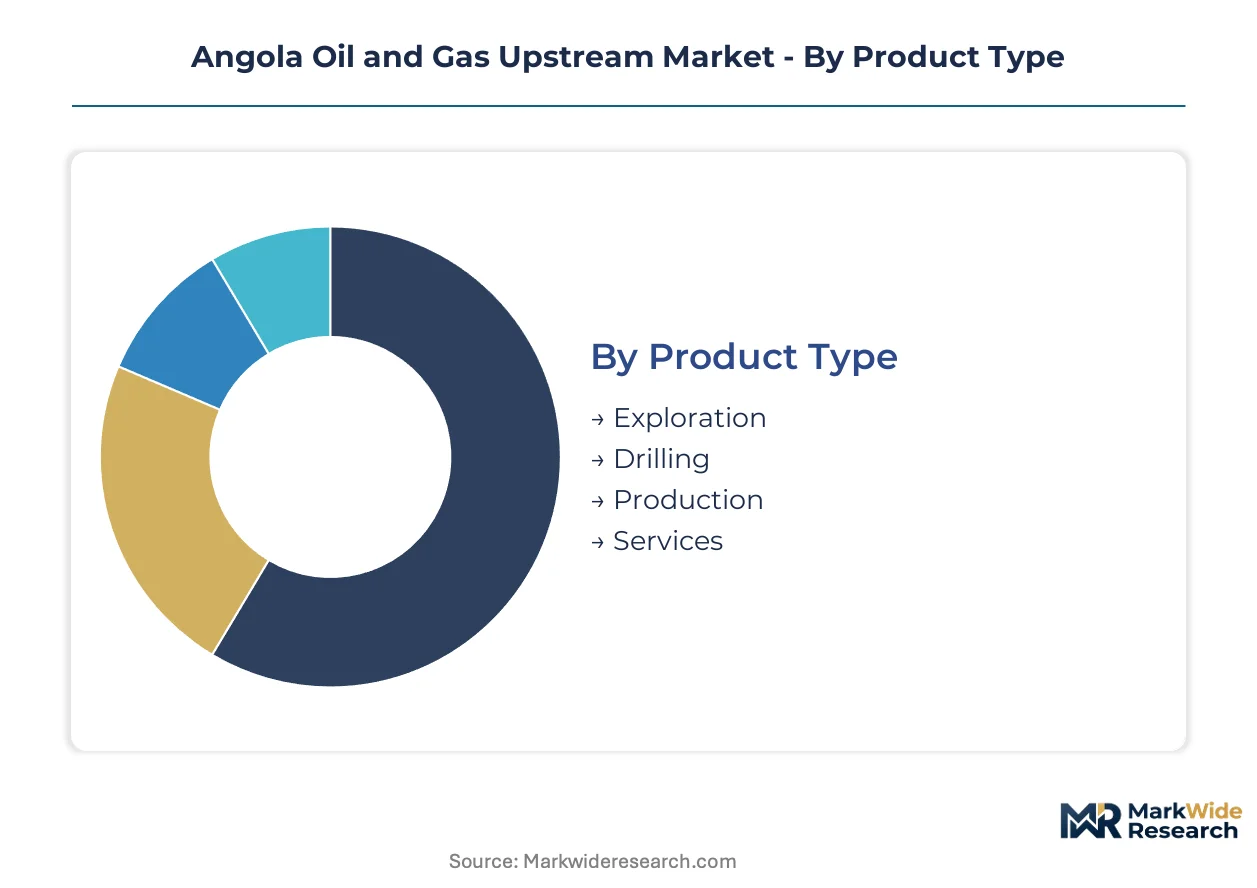
Segmentation in Angola's upstream market reveals how capital allocation shifts between mature basin redevelopment and frontier exploration. Understanding these divisions exposes where ANPG concession terms and Sonangol local content mandates exert the strongest pressure on contractor selection.
Product Type:
Substitution pressure weighs heaviest on Services segments as operators internalize capabilities previously outsourced to third parties.
- Exploration:Seismic surveying and wildcat drilling in pre-salt Kwanza Basin formations demand specialized salt-imaging technology. Block 17 and Block 32 operators concentrate exploration spending here, driven by ANPG's regular concession rounds that refresh portfolio positions.
- Drilling:Deepwater rigs capable of 1,500-meter-plus operations command premium day rates in Cabinda enclave and Lower Congo Basin activity. Scarce pre-salt competent crews and dynamic positioning operators constrain activity expansion despite strong operator demand.
- Production:Crude extraction from sanctioned fields feeds Luanda refinery and export terminals.
- Services:Well intervention and maintenance contracts face margin compression from Sonangol's domestic supplier spending floors.
Production anchors the volume base while Exploration gains share at the steepest rate.
Technology:
Cost tier stratification separates capital-intensive platform investments from modular subsea alternatives that reduce break-even thresholds.
- Offshore Platforms:Fixed and floating production systems dominate capital allocation across Angola's deepwater blocks. These structures process hydrocarbons at the surface for transfer to FPSO vessels, with demand concentrating in mature Cabinda enclave fields where infrastructure already exists.
- Subsea Systems:Seabed processing modules, manifolds, and tieback architectures enable marginal field development without greenfield platform construction. Ultra-deepwater frontier blocks in the Kwanza Basin drive adoption, though European and Asian fabricator concentration creates delivery bottlenecks.
- Enhanced Oil Recovery:Gas injection and waterflooding combat natural pressure depletion in aging Lower Congo Basin reservoirs.
- Well Completion:Subsurface hardware installation finalizes drilling programs for production commencement.
Offshore Platforms absorb the largest capital share while Subsea Systems climb the fastest as operators push into ultra-deepwater frontiers.
End User:
Customer type segmentation tracks how ANPG production-sharing contract terms distribute risk between state-backed and private capital.
- National Oil Companies:Sonangol retains carried interests and domestic supply obligations across all major blocks. The NOC's dual role as regulator and commercial participant shapes joint-venture structures and local content enforcement timelines.
- Independent Producers:Smaller operators without integrated service arms concentrate on specific Block 17 or Kwanza Basin assets. These firms rely heavily on oilfield service providers for technical execution, making them most exposed to crew scarcity and equipment delivery delays.
- Oilfield Service Providers:Schlumberger, Halliburton, and Weatherford compete for drilling and completion contracts under revised local content thresholds.
- Contractors:Construction and installation specialists execute platform fabrication and subsea installation programs.
National Oil Companies dominate equity participation while Independent Producers expand fastest through ANPG's opened concession rounds.
Installation:
Geography of deployment separates onshore infrastructure from offshore architectures that define Angola's upstream identity.
- Offshore Installations:Fixed platforms, FPSO vessels, and floating production systems constitute the core of Angolan upstream activity. These assets cluster in deepwater blocks off Cabinda and the Kwanza Basin, where pre-salt discoveries require surface processing capacity.
- Submersible Systems:Seabed production equipment and subsea tiebacks connect marginal discoveries to existing infrastructure. Block 32 operators deploy these systems to avoid standalone platform commitments, though interface risk with aging FPSO systems complicates integration.
- Onshore Facilities:Luanda refinery feedstock reception and Soyo LNG plant gas processing represent limited onshore scope.
- Mobile Units:Drillships and semisubmersible rigs relocate between exploration blocks based on ANPG drilling commitments.
Offshore Installations carry the capital weight while Submersible Systems gain deployment share through tieback economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Upstream investment concentrates in deepwater blocks off Cabinda and the Kwanza Basin, where pre-salt geology and mature field redevelopment attract distinct operator archetypes. Sonangol's local content mandates reshape contractor selection across all zones. The report examines four sub-regional concentrations where capital allocation patterns diverge.
Cabinda Enclave
Chevron's legacy infrastructure anchors production from mature shallow-water fields. ANPG production-sharing contract terms for adjacent blocks require tieback integration with aging FPSO systems. Block 0 and Block 14 operators concentrate redevelopment spending on gas injection infrastructure to combat natural pressure depletion.
Kwanza Basin
Pre-salt salt-layer formations mirror Brazil's productive analogs, attracting seismic survey investment from TotalEnergies and Azule Energy. ANPG's 2019 petroleum reform law established regular block auctions with revised technical thresholds. Deepwater drilling crews and dynamic positioning operators cluster around Luanda supply bases serving ultra-deepwater frontier blocks.
Lower Congo Basin
Block 17 and Block 32 host the most capital-intensive developments, with subsea tieback engineering enabling marginal field production without platform construction. Sonangol's domestic supplier spending floors compress project schedules for international operators. Soyo LNG plant capacity monetizes associated gas from oil-dominant fields previously flared.
Luanda Coastal Zone
Refining capacity additions at the Luanda refinery absorb more domestic crude, reducing export terminal offtake volumes. ISO 14001 environmental management certification requirements differentiate bidders in ANPG technical scoring. Local fabrication yards and service company joint ventures concentrate along the corridor to meet Sonangol workforce mandates.
Angola Oil and Gas Upstream Market Competitive Environment
Player mix skews toward integrated majors with pre-salt expertise and national oil company joint-venture structures. The market exhibits tiered concentration: a dominant national champion layer, a deepwater specialist tier, and a contracting services base. Two strategic archetypes define positioning—those leveraging legacy infrastructure for tieback economics versus those betting on frontier pre-salt exploration. Competitive moves center on portfolio consolidation through asset combinations and early local partner embedding to satisfy regulatory timelines.
Among European-integrated majors, TotalEnergies SE and BP Plc exemplify divergent strategic postures—TotalEnergies sustaining drilling programs through retained pre-salt expertise, while BP contributed legacy assets to the Azule Energy combination with Eni SpA. Chevron Corporation anchors the Americas-based tier through its Cabinda enclave longevity. These three entities represent distinct responses to ANPG concession terms: organic capability retention, portfolio restructuring through combination, and infrastructure-led redevelopment.
| Leading Market Players |
|---|
| Azule Energy |
| BP Plc |
| TotalEnergies SE |
| Equinor ASA |
| Sonangol |
| ExxonMobil Corporation |
| Eni SpA |
| Petronas |
| Chevron Corporation |
| Others |
Value Chain & Pricing Dynamics
Deepwater rig day-rate economies above 1,500-meter operations concentrate contractor pricing power among a handful of global fleet operators, compressing margins for Angolan joint-venture partners while establishing floor prices indexed to Brent crude movements. Sonangol's local content mandates add cost layers that international operators pass through production-sharing contract terms, embedding supply-chain structure directly into field development economics.
Pricing Analysis
Cost-plus contracts with Brent crude indexation dominate deepwater drilling agreements, with day rates adjusting to commodity price bands on quarterly resets. Price differentiation separates pre-salt competent crews from standard offshore personnel, while ISO 14001 certification commands premium margins in ANPG technical scoring. Pricing pressure stems from European and Asian fabricator concentration for subsea trees, squeezing project budgets. Independent producers show highest price sensitivity due to single-asset exposure, whereas integrated majors absorb volatility through portfolio diversification.
Supply Chain Analysis
Strait of Malacca transit underwrites subsea equipment delivery schedules from Singapore and South Korean fabrication yards to Luanda supply bases. Equipment concentration in Norway, Brazil, and Singapore shapes procurement timelines for manifolds and processing modules. Raw material dependencies include high-grade steel alloys, subsea umbilicals, and dynamic positioning systems. Single-source vulnerability runs through European subsea tree manufacturers. Distribution runs through Sonangol-approved domestic joint-venture partners for last-mile logistics compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Angola's upstream market enters cyclical recovery as pre-salt exploration economics improve against sustained Brent price levels, attracting capital rotation from mature basin redevelopment programs.
For Market Incumbents: Fortify tieback infrastructure positions in Cabinda enclave blocks where Chevron's legacy FPSO systems create captive demand for adjacent discoveries. Deepen partnerships with Angolan fabrication yards ahead of Sonangol's workforce mandate deadlines to compress project schedules. Defend against subsea crew scarcity by embedding training programs at Luanda supply bases before ANPG drilling commitment windows open. For New Entrants and Emerging Players: Local content compliance services represent an underserved layer where incumbent operators seek outsourced workforce and supplier management. Target independent producers lacking integrated service arms in Block 17 and Kwanza Basin assets. Pursue ANPG pre-qualification pathways that bundle domestic joint-venture formation with technical capability demonstration. For Investors and Strategic Acquirers: Subsea engineering specialists with pre-salt project execution records offer acquisition exposure to Kwanza Basin development cycles without direct equity participation in production-sharing contracts. Frame long-term viability around reserve replacement rates in ultra-deepwater blocks versus mature field decline curves. Watch ANPG concession round frequency as the inflection signal for capital allocation momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Local Content Joint Venture Formation | ANPG technical scoring now weights domestic partnership depth, reshaping contractor pre-qualification. |
| Subsea Tieback Engineering Investment | Block 32 operators deploy seabed processing modules to avoid standalone platform capital commitments. |
| Pre-salt Crew Training Programs | Luanda supply bases compete with Brazil for scarce dynamic positioning operators and salt-imaging specialists. |
| ISO 14001 Certification Pathway | Environmental management credentials differentiate bidders in Sonangol's revised production-sharing contract terms. |
| Associated Gas Commercialization | Soyo LNG plant capacity monetizes stranded gas from oil-dominant fields previously flared in Lower Congo Basin. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with upstream operators and secondary validation across regulatory and project databases. Interviews captured perspectives from ANPG concession managers, Sonangol joint-venture officers, deepwater drilling contractors, subsea equipment procurement leads, and Luanda refinery planning executives. Secondary sources included ANPG block award records, Sonangol local content compliance filings, offshore rig utilization reports, and subsea fabrication yard order books. Bottom-up project economics triangulated against top-down sector expenditure estimates.
Across the projection horizon, the analytical framework modeled value and volume trajectories through technology type, product segment, end-user category, and installation geography dimensions. CAGRs derived from weighted average of operator capital guidance, rig day-rate trends, and subsea equipment order backlogs. Pre-salt well cost curves, FPSO lease rate structures, and ANPG concession term evolution served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in ANPG petroleum reform implementation and Sonangol local content enforcement; material policy shifts would require re-modeling. Specific risks include Brent crude price sustained below deepwater break-even thresholds, subsea fabricator delivery bottlenecks during cycle upswings, and crew scarcity constraining drilling program expansion. Practitioners should keep alternative scenarios live as ANPG concession round timing and pre-salt exploration results evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Europe Well Intervention Market
Oil & Gas
Whipstocks Market
Oil & Gas
Pumpjack Market
Oil & Gas
Oil and Gas MIC Testing Market
Oil & Gas
Oil and Gas Engineering Services Market
Oil & Gas
GCC Natural Gas Market
Oil & Gas
Crude Oil Carriers Market
Oil & Gas
Middle East and Africa Drilling Market
Oil & Gas
US Sand Control Systems Market
Oil & Gas
Japan LNG Bunkering Market
Oil & Gas
Digital Oilfield Services Market
Oil & Gas
Perforating Gun Market
Oil & Gas
North America Natural Gas Market
Oil & Gas
Operational Digital Oilfield Solution Market
Oil & Gas
Africa Oil Refining Market
Oil & Gas
Oil and Gas Accumulators Market