
 Paraffin Oil Market | 2026-2036
Paraffin Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Paraffin Oil Market Analysis
Pharmaceutical-grade purification is unwinding legacy supply arrangements as buyers demand USP and EP compliance for topical and oral formulations. Exxon Mobil leverages integrated refining complexes to sustain cost-advantaged feedstock access across North American pharmaceutical corridors. Sasol anchors African supply through Fischer-Tropsch-derived wax streams that compete on consistency with petroleum-based alternatives. Royal Dutch Shell differentiates via specialized hydrocracking configurations that yield narrow-cut paraffin fractions for high-specification medical applications.
Paraffin oil denotes a saturated aliphatic hydrocarbon mixture distilled from petroleum or synthesized via Fischer-Tropsch synthesis, typically ranging from C15 to C40 carbon chains with viscosity grades spanning 2 to 30 centistokes at 40°C, functioning primarily as lubricants, moisture barriers, carrier fluids, and release agents across industrial and consumer applications. Fully refined paraffin commands premium positioning in pharmaceutical and food-grade channels where residual oil content below 0.5% determines regulatory access, while light paraffin fractions in personal care formulations face substitution pressure from plant-derived emollients. Industrial applications retain volume leadership through metalworking fluids and textile processing, though margin pools concentrate in pharmaceutical-grade distribution where batch certification and documentation requirements create supplier stickiness.
FDA 21 CFR 172.880 and 178.3620(a) govern direct and indirect food contact applications in the United States, while REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons constrain European import specifications and compel testing expenditure. India's BIS IS 1448 certification and China's GB 1886.215 food additive standard create divergent compliance burdens that fragment supplier qualification protocols. Stakeholders must monitor evolving pharmaceutical monograph harmonization between USP-NF, EP, and JP standards, as divergence in sulfur and aromatic limits threatens to bifurcate global product tiers and strand regional inventory positions.
Market Dynamics
Pharmaceutical formulation standards are tightening across multiple jurisdictions, pushing demand toward fully refined grades and unwinding legacy supply arrangements as buyers demand USP and EP compliance for topical and oral formulations.
Growth Catalysts
- REACH Annex XVII restrictions:Polycyclic aromatic hydrocarbon limits constrain European import specifications, compelling testing expenditure that redirects procurement toward verified supply chains with documented batch certification.
- Food-grade paraffin applications:Confectionery coatings and produce preservation are expanding in India and Southeast Asian processing hubs, creating new volume demand channels for refined grades meeting FSSAI and BIS IS 1448 standards.
- Fischer-Tropsch synthesis:Synthetic paraffin streams compete on consistency with petroleum-based alternatives, offering supply diversification for buyers seeking feedstock security independent of crude oil volatility.
Market Restraints
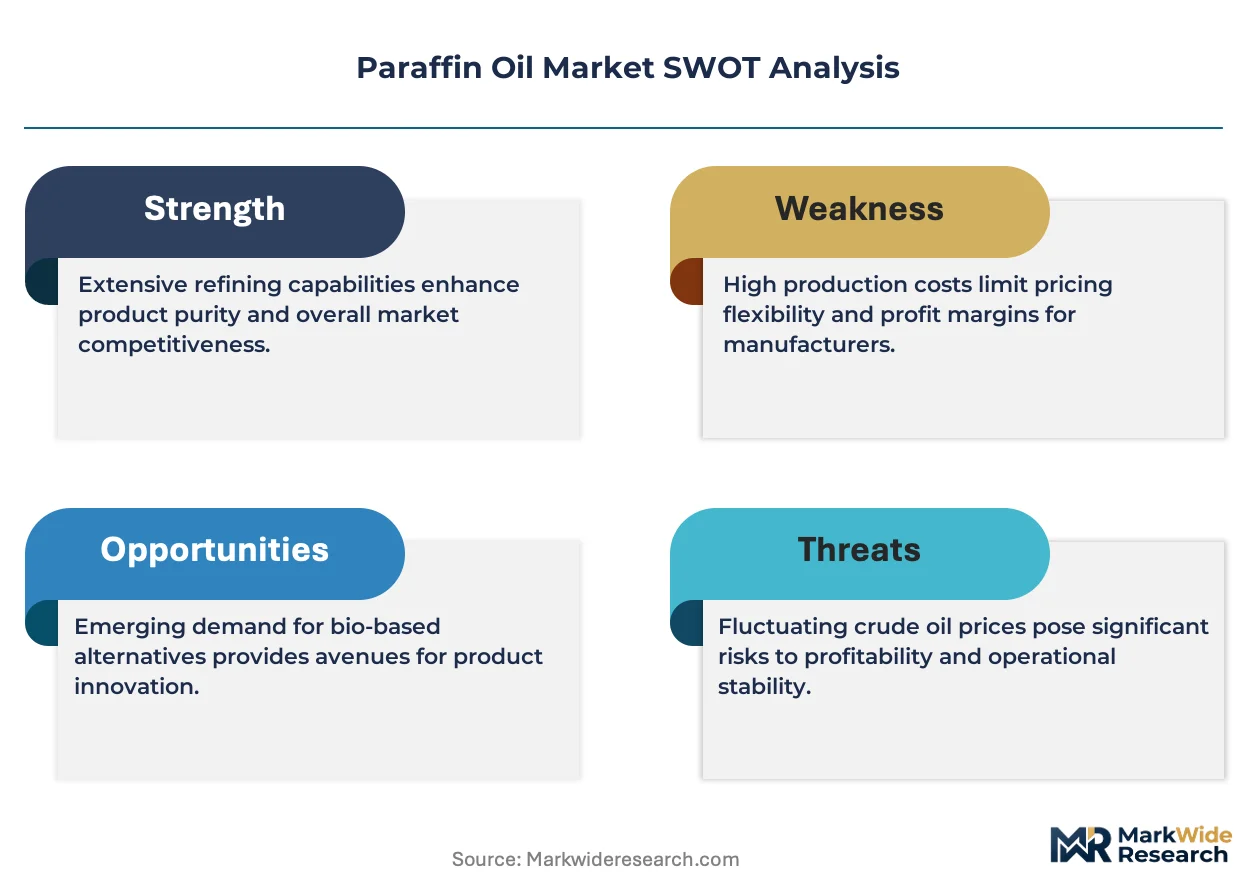
- Crude oil feedstock volatility:Petroleum-derived paraffin remains exposed to naphtha and slack wax price swings, compressing margin predictability for non-integrated refiners without captive cracking capacity.
- Plant-derived emollient substitution:Light paraffin fractions in personal care formulations face displacement pressure from squalane and jojoba oil alternatives marketed as clean-label ingredients.
- Divergent national standards:India's BIS IS 1448 certification and China's GB 1886.215 food additive standard create fragmented supplier qualification protocols that strand inventory positions across regulatory boundaries.
Strategic Opportunities
- Pharmaceutical monograph harmonization:Convergence between USP-NF, EP, and JP standards on sulfur and aromatic limits would enable global product tier consolidation, reducing stranded inventory risk for multinational formulators.
- Specialized hydrocracking configurations:Narrow-cut paraffin fractions for high-specification medical applications command premium positioning where batch certification creates supplier stickiness and defensible margins.
- Metalworking fluid reformulation:Industrial applications retain volume leadership through synthetic and semi-synthetic blends incorporating paraffin carrier bases, extending lifecycle in precision machining operations.
Industry Challenges
- Documentation and certification timelines:Pharmaceutical-grade distribution requires batch-specific testing protocols that extend order-to-delivery cycles and strain working capital for distributors managing multiple regulatory jurisdictions.
- Feedstock integration complexity:Refiners lacking in-house slack wax production face margin compression during crude price spikes, forcing reliance on spot market purchases with volatile availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paraffin Oil Market |
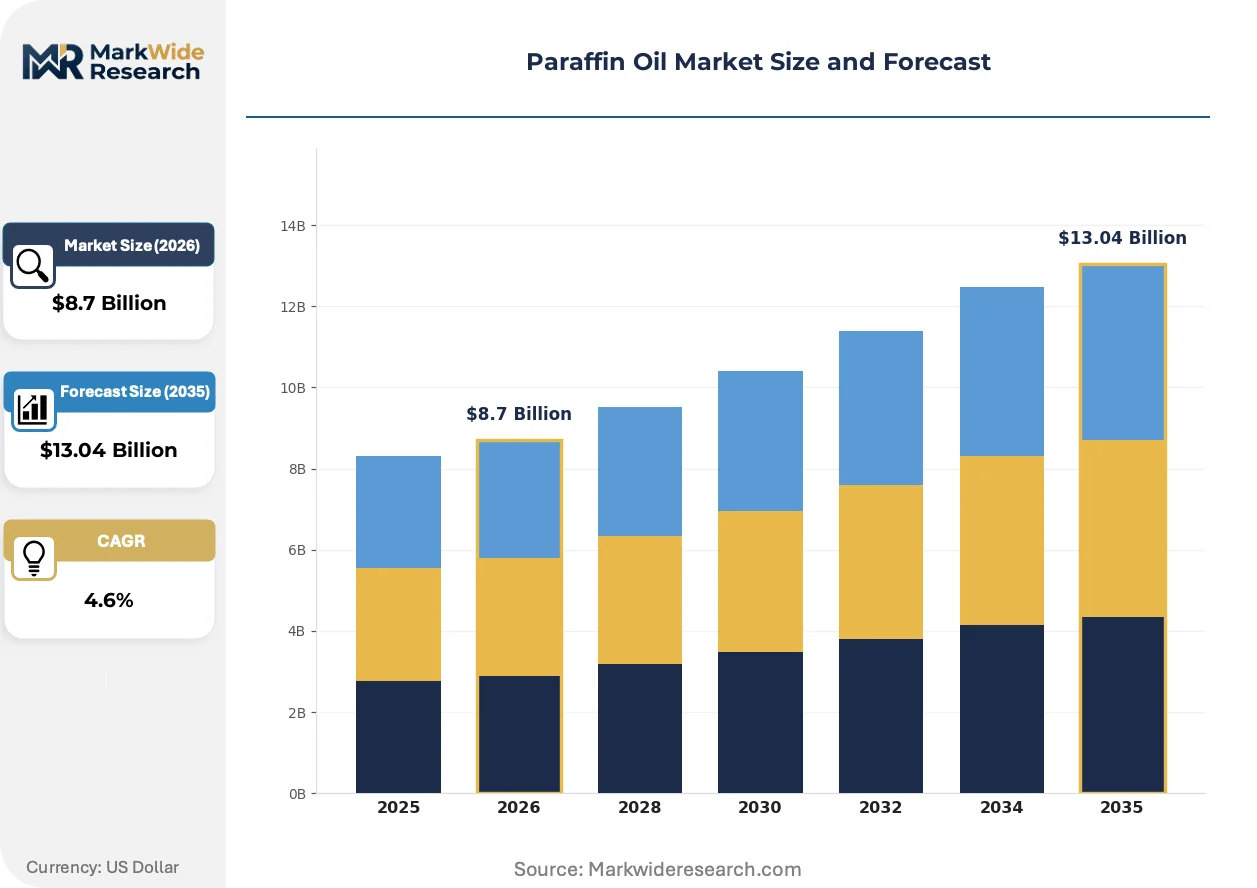
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Paraffin, Heavy Paraffin, Semi-Refined Paraffin, Fully Refined Paraffin Application: Cosmetics, Pharmaceuticals, Food Processing, Industrial Applications End User: Personal Care Manufacturers, Food Industry, Chemical Industry, Healthcare Providers Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Exxon Mobil, Royal Dutch Shell, BASF SE, China National Petroleum Corporation, Sasol, BP plc, Evonik, Linde plc, Mitsui Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paraffin Oil Market Emerging Trajectories
Refining technology advances and regulatory specification divergence are actively reshaping competitive positioning, creating tiered performance categories that separate integrated producers from merchant suppliers.
Hydrocracking catalysts with zeolite-based molecular sieves are fragmenting the traditional separation between light and heavy paraffin fractions. Pharmaceutical formulators in Germany and Switzerland are adopting these narrow-cut grades for transdermal patch matrices. The technology is fragmenting established supply relationships by enabling specification-matched sourcing from non-traditional synthetic producers.
China's GB 1886.215 food additive standard and India's BIS IS 1448 certification are diverging on polycyclic aromatic hydrocarbon testing methodologies. This regulatory friction forces dual-track qualification for suppliers serving both markets. Food-grade processors in Mumbai and Guangzhou are responding by consolidating procurement through distributors with in-house testing laboratories.
Specification-driven vendor consolidation is compressing buyer switching cycles in pharmaceutical channels. Formulators are unbundling after-sales technical support from commodity supply contracts, creating standalone advisory fee structures. This pattern is most visible among topical and oral dosage manufacturers in the United States seeking USP-compliant documentation packages.
Paraffin Oil Market Segmentation
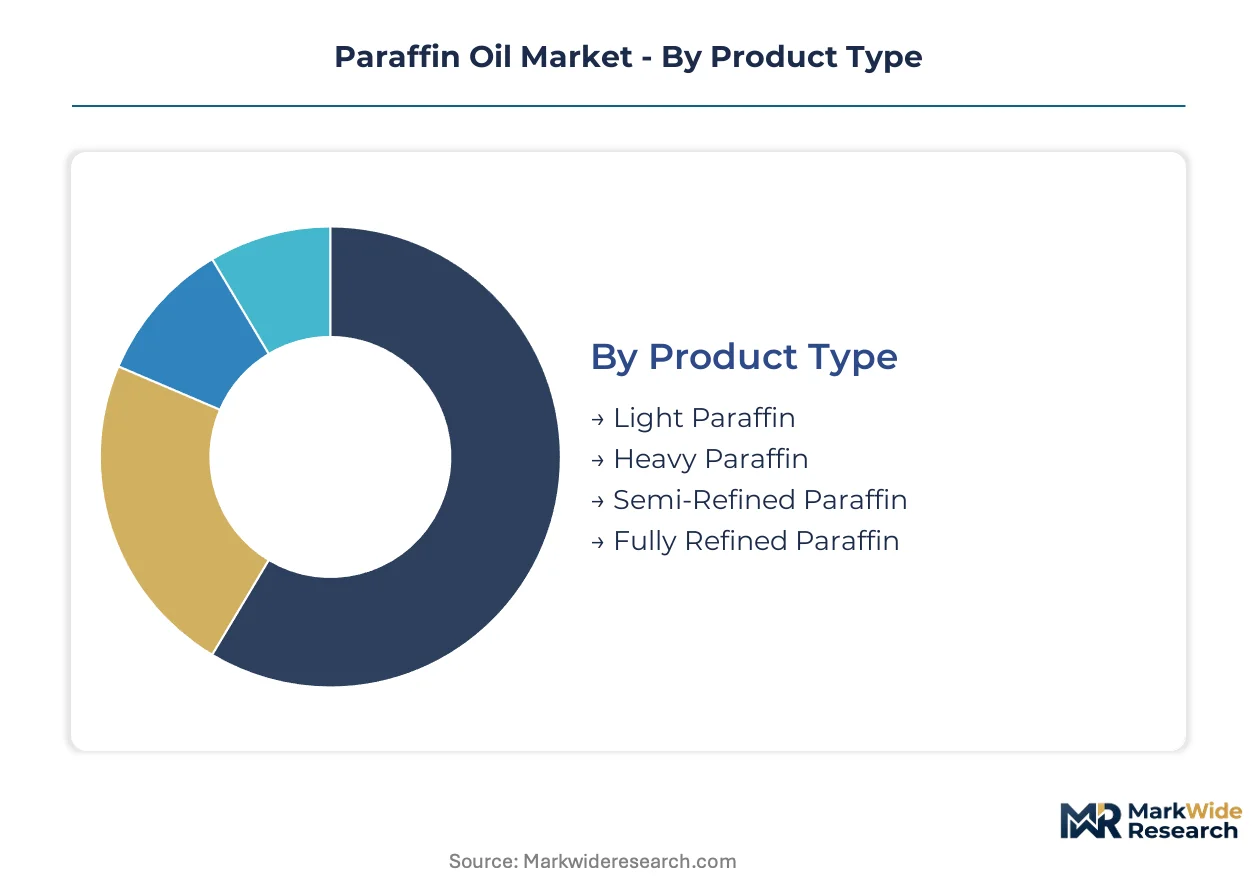
Paraffin oil segmentation reflects divergent purity requirements and channel economics. Pharmaceutical and food-grade specifications command premium positioning through specialized distribution networks, while industrial volumes flow through commodity wholesale channels with thinner documentation burdens.
Product Type:
Channel mix varies sharply by refinement level—fully refined grades concentrate in pharmaceutical-direct and certified distributor channels, while semi-refined and heavy fractions dominate industrial wholesale.
- Fully Refined Paraffin:Residual oil content below 0.5% meets USP-NF and EP monograph requirements for topical and oral pharmaceutical formulations. Demand concentrates in German and Swiss transdermal patch manufacturing, where batch certification and documentation requirements create supplier stickiness and defensible margins.
- Light Paraffin:Viscosity grades spanning 2-10 centistokes at 40°C serve personal care emollient applications. Substitution pressure from squalane and jojoba oil alternatives is compressing volume in US and European clean-label cosmetic channels, though Asian markets retain stronger penetration.
- Heavy Paraffin:Higher viscosity fractions (15-30 centistokes) function as metalworking fluid bases and textile lubricants. Industrial processors in India and China absorb volume through spot-market wholesale procurement.
- Semi-Refined Paraffin:Intermediate purification serves candle manufacturing and general industrial moisture barriers. Price-sensitive buyers in Southeast Asian processing hubs drive spot-market liquidity.
Fully refined paraffin dominates installed base value. Light paraffin is where substitution pressure concentrates most intensely.
Application:
Margin structure inverts across application tiers—pharmaceutical and food channels absorb compliance costs into premium pricing, while industrial applications compete on volume scale.
- Pharmaceuticals:Carrier fluids and topical bases require documented USP and EP compliance with tight sulfur and aromatic limits. FDA 21 CFR 172.880 governs indirect food contact pathways that intersect with oral formulation standards.
- Food Processing:Confectionery coatings and produce preservation applications expand in Indian and Southeast Asian processing hubs meeting FSSAI and BIS IS 1448 certification requirements.
- Cosmetics:Emollient and barrier functions in skincare formulations face displacement from plant-derived alternatives marketed as clean-label ingredients in European and North American channels.
- Industrial Applications:Metalworking fluids and textile processing retain volume leadership through synthetic and semi-synthetic blend formulations incorporating paraffin carrier bases.
Industrial applications anchor volume throughput. Pharmaceuticals capture margin expansion.
End User:
Procurement sophistication separates end-user tiers—healthcare and food industry buyers demand certified supply chains with testing documentation, while chemical industry purchasers prioritize feedstock security and price predictability.
- Healthcare Providers:Hospital and clinical procurement of pharmaceutical-grade paraffin for compounding pharmacies requires vendor qualification protocols extending order-to-delivery cycles.
- Food Industry:Confectionery manufacturers and fresh produce processors in India and China drive demand for food-grade certification under divergent BIS and GB standards.
- Personal Care Manufacturers:Cosmetic formulators in Germany and Switzerland source narrow-cut fractions for premium skincare lines, unbundling technical support from commodity supply contracts.
- Chemical Industry:Synthetic rubber and plasticizer producers absorb semi-refined grades through direct refinery relationships and long-term offtake agreements.
Chemical industry buyers dominate volume offtake. Healthcare providers concentrate compliance expenditure.
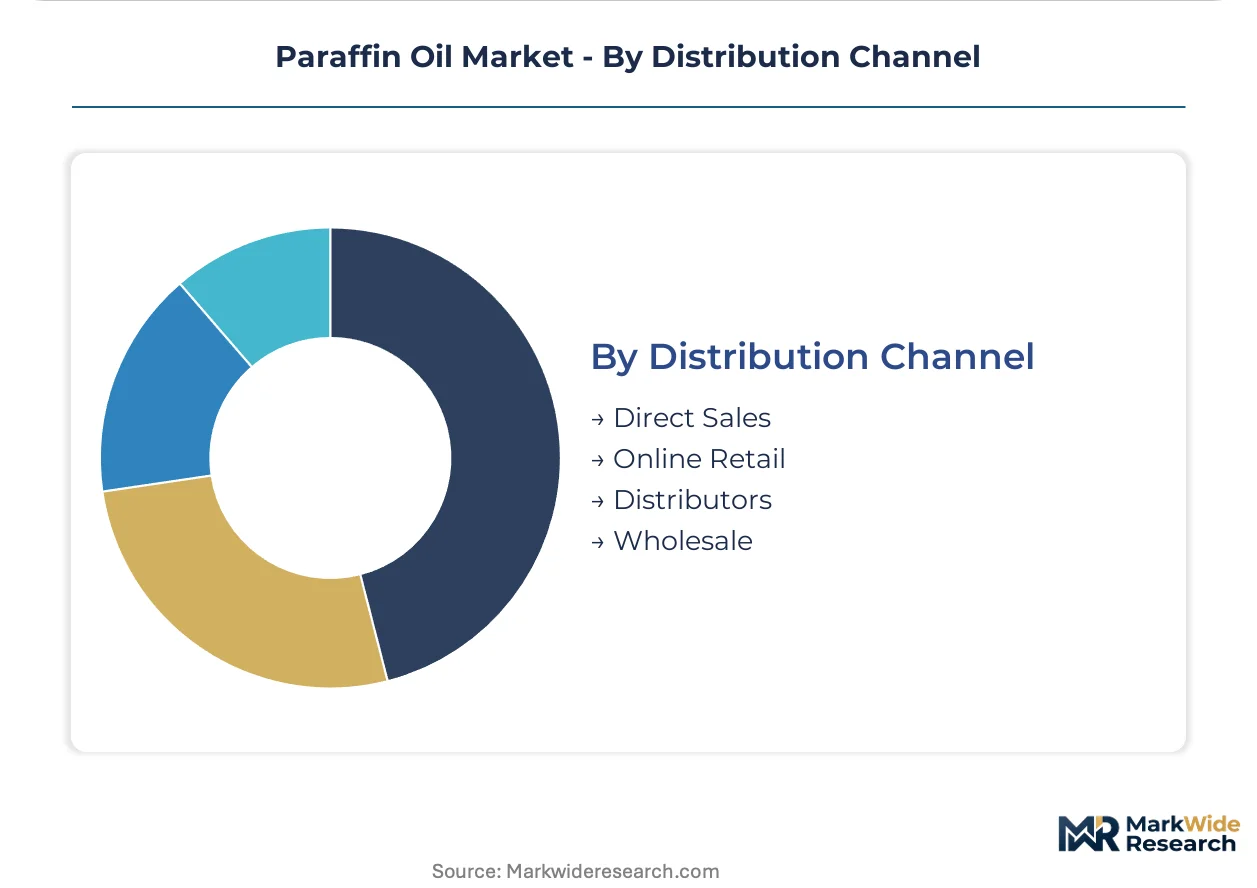
Distribution Channel:
Channel selection tracks certification burden—direct sales and certified distributors handle pharmaceutical and food-grade documentation, while wholesale and online retail serve price-sensitive industrial segments.
- Distributors:Specialized chemical distributors with in-house testing laboratories manage dual-track qualification for suppliers serving both Indian BIS and Chinese GB regulatory jurisdictions.
- Direct Sales:Integrated refiners like Exxon Mobil leverage captive production to sustain cost-advantaged pharmaceutical corridor access across North America.
- Wholesale:Bulk industrial volumes flow through commodity wholesale channels with minimal documentation requirements and compressed working capital cycles.
- Online Retail:Small-batch personal care and artisan food producers source light and food-grade fractions through specialized chemical marketplaces with variable certification reliability.
Direct sales anchor pharmaceutical value capture. Distributors are expanding most quickly as regulatory fragmentation forces consolidation through qualified intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated refiners in China and the United States control the bulk of slack wax feedstock access, while pharmaceutical-grade purification capacity clusters in Germany and Switzerland. Regulatory divergence between Indian BIS certification and Chinese GB standards is fragmenting procurement patterns across Asian processing hubs.
United States
Pharmaceutical corridor demand from New Jersey and Massachusetts formulation plants drives USP-grade paraffin consumption. FDA 21 CFR 172.880 governs indirect food contact applications that intersect with oral drug pathways. Houston-area refineries supply slack wax streams to specialty distributors serving compounding pharmacies.
China
GB 1886.215 food additive standards and tightening NMPA pharmaceutical oversight redirect procurement toward verified domestic supply chains. Yangtze River Delta confectionery processors in Shanghai and Suzhou absorb expanding volumes of fully refined grades for export-oriented candy manufacturing.
Germany
REACH Annex XVII polycyclic aromatic hydrocarbon limits constrain import specifications and compel batch testing expenditure. Cologne-Düsseldorf industrial clusters source narrow-cut paraffin fractions for transdermal patch matrices from hydrocracking specialists.
India
FSSAI and BIS IS 1448 certification requirements expand food-grade applications in Mumbai and Ahmedabad confectionery operations. Maharashtra-based processors consolidate procurement through distributors with in-house testing laboratories to manage dual-track qualification burdens.
Switzerland
Swissmedic pharmaceutical standards and proximity to German chemical corridors position Basel-region formulators as premium-grade consumers. Narrow-cut fraction demand from transdermal and topical manufacturers creates supplier stickiness through documentation requirements.
Paraffin Oil Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the paraffin oil value chain. Integrated petroleum majors with captive slack wax production dominate feedstock security, while specialized refiners compete on hydrocracking precision for narrow-cut pharmaceutical grades. The competitive terrain separates into three archetypes: integrated upstream-downstream operators, Fischer-Tropsch synthetic producers, and merchant refiners dependent on spot feedstock markets. Capacity expansion and strategic partnerships with pharmaceutical distributors constitute the dominant competitive moves as regulatory documentation requirements deepen supplier-buyer relationships.
Among petroleum-integrated majors, Exxon Mobil and Royal Dutch Shell occupy positions defined by captive refining complexes and North American corridor access. Sasol anchors the synthetic production archetype through Fischer-Tropsch-derived wax streams that compete on consistency metrics. BASF SE exemplifies the diversified chemical conglomerate model with paraffin positioning within broader specialty chemical portfolios. These three represent distinct strategic postures: feedstock-integrated scale, synthetic process differentiation, and portfolio-embedded specialization.
| Leading Market Players |
|---|
| Exxon Mobil |
| Royal Dutch Shell |
| BASF SE |
| China National Petroleum Corporation |
| Sasol |
| BP plc |
| Evonik |
| Linde plc |
| Mitsui Chemicals |
| Others |
Supply Flow & Price Mechanics
Forty-five to sixty-day order-to-delivery cycles for pharmaceutical-grade batches concentrate pricing power with integrated refiners possessing captive slack wax production and in-house hydrocracking capacity. This lead-time compression rewards suppliers who absorb batch certification burdens directly, while merchant refiners face margin erosion during crude volatility spikes.
Pricing Analysis
FDA 21 CFR 172.880 and REACH Annex XVII dictate the pricing tier structure across food and pharmaceutical channels, separating USP-certified grades from industrial semi-refined streams. Price differentiation rests on residual oil content thresholds below 0.5% and documented polycyclic aromatic hydrocarbon compliance, with German and Swiss buyers absorbing premium positioning for narrow-cut transdermal fractions. Cost compression in personal care light paraffin is intensifying because squalane substitution erodes volume in clean-label cosmetic channels. Industrial metalworking buyers exhibit highest price sensitivity through spot-market procurement, while pharmaceutical formulators prioritize supply security over unit economics.
Supply Chain Analysis
China and the United States control slack wax feedstock access through integrated refining complexes along the Yangtze River Delta and Gulf Coast corridors. Raw material dependencies center on crude-derived naphtha streams, Fischer-Tropsch synthetic wax from South African facilities, and imported heavy slack wax for semi-refined grades. Single-source vulnerability concentrates in pharmaceutical-grade hydrocracking capacity clustered in Germany and Switzerland. Distribution runs through certified chemical distributors with in-house testing laboratories serving dual-track BIS and GB qualification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across FDA, REACH, BIS, and GB standards fragments procurement patterns, creating white-space opportunities for specialized distributors and synthetic producers who navigate documentation complexity.
For Market Incumbents: Compound supplier stickiness through captive hydrocracking investments in North American pharmaceutical corridors and exclusive long-term offtake agreements with Fischer-Tropsch synthetic producers. Plant-derived emollient substitution in personal care channels threatens light paraffin volumes; defend positioning through backward integration into food-grade certification infrastructure. For New Entrants and Emerging Players: Anchor in Indian and Southeast Asian food processing hubs where FSSAI and BIS IS 1448 certification expansion outpaces qualified supplier availability. The most penetrable segment sits in confectionery coatings and produce preservation applications, with go-to-market traction through Mumbai-based distributors operating in-house testing laboratories. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because documentation and batch certification requirements deepen supplier-buyer relationships and create defendable moats. Acquisition targets should emphasize specialized hydrocracking configurations and narrow-cut fraction capabilities. The signal to watch is pharmaceutical monograph harmonization progress between USP-NF, EP, and JP standards on sulfur and aromatic limits.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Slack Wax Production | Captive feedstock access insulates margin predictability from crude price volatility for non-integrated refiners. |
| Pharmaceutical Monograph Harmonization Investment | Convergence between USP-NF and EP standards reduces stranded inventory risk across regulatory jurisdictions. |
| Specialized Hydrocracking Capacity Expansion | Narrow-cut fraction capability commands premium positioning in German and Swiss transdermal patch manufacturing. |
| Long-term Supply Agreement with Synthetic Producers | Fischer-Tropsch-derived wax streams diversify feedstock security independent of petroleum price cycles. |
| In-house Testing Laboratory Certification | Dual-track BIS and GB qualification capability consolidates procurement relationships across Asian processing hubs. |
Methodological Framework
Operator-level perspectives from refinery operations managers, pharmaceutical procurement leads at topical formulation plants, food-grade chemical distributors, and BIS certification auditors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC 10-K filings from integrated petroleum majors, BIS and GB standard documentation, and REACH Annex XVII regulatory filings. Bottom-up volume estimates from grade-specific consumption patterns triangulated against top-down refinery capacity assessments.
Sensitivity analysis across crude price scenarios, regulatory harmonization timelines, and substitution elasticity parameters shaped the analytical framework. Segmentation dimensions modeled include refinement grade tier, end-use application, viscosity specification, and regional regulatory cluster. CAGRs derived from trend extrapolation of historical consumption patterns adjusted for documented capacity additions and certification requirement intensification. Forecast inputs incorporated pharmaceutical formulation growth trajectories and food processing expansion in Indian and Southeast Asian hubs.
Material uncertainties — crude feedstock volatility, regulatory divergence persistence, and plant-derived emollient substitution rates — sit outside the modeled envelope. Forecasts reflect assumptions about certification timeline stability and hydrocracking capacity utilization. Recalibration cycles align with material shifts in pharmaceutical monograph harmonization and major refinery capacity commissioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Underground Storage Tanks Market
Petroleum Products
Longitudinal Submerged-Arc Welded (LSAW) Pipes Market
Petroleum Products
Floating Roof Tank Market
Petroleum Products
Petroleum Wax Market
Petroleum Products
South Africa Petroleum Market
Petroleum Products
Very Low Sulphur Fuel Oil (VLSFO) Market
Petroleum Products
South Africa Refined Petroleum Products Market
Petroleum Products
Marine Minerals Market
Petroleum Products
Spiral Submerged Arc Welded (SSAW) Steel Pipe Market
Petroleum Products
Spindle Oil Market
Petroleum Products
North America Natural Gas Liquids Market
Petroleum Products
Pyrolysis Gasoline Market
Petroleum Products
PAG Base Oil Market
Petroleum Products
Liquefied Petroleum Gas Market
Petroleum Products
Uganda Petroleum Products Market
Petroleum Products
LPG [Liquefied Petroleum Gas] Market