
 South Africa Lubricants Market | 2026-2036
South Africa Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Lubricants Market Outlook
The EU Green Deal's extraterritorial carbon-border pressure is repositioning South African lubricant buyers toward lower-emission formulations. Shell plc dominates the retail channel through its forecourt network, while Sasol leverages captive base-oil production to anchor its industrial supply position. BP plc (Castrol) competes on synthetic product specialization for mining and agricultural equipment.
Lubricants are formulated mixtures of base oils and functional additives designed to reduce friction, dissipate heat, and prevent wear in mechanical systems, with viscosity grades typically ranging from ISO VG 32 to ISO VG 680 for industrial applications and SAE 5W-30 to SAE 20W-50 for automotive engines. Their primary purpose is extending machinery life and optimizing energy efficiency across powertrain, hydraulic, and transmission systems. Engine oils command the largest application share due to South Africa's substantial vehicle parc and commercial fleet density, while synthetic oil formulations capture the fastest growth trajectory as mining and industrial end users prioritize extended drain intervals and thermal stability under high-stress operating conditions.
South Africa's National Regulator for Compulsory Specifications enforces lubricant quality standards aligned with SABS mark certification, while the Department of Mineral Resources and Energy oversees fuel and lubricant pricing mechanisms that influence distribution economics. The South African Revenue Service's carbon tax administration directly affects industrial lubricant procurement decisions by embedding emissions costs into operating budgets. Stakeholders must monitor evolving SABS specifications and carbon tax thresholds to align product portfolios with compliance-driven specification upgrades.
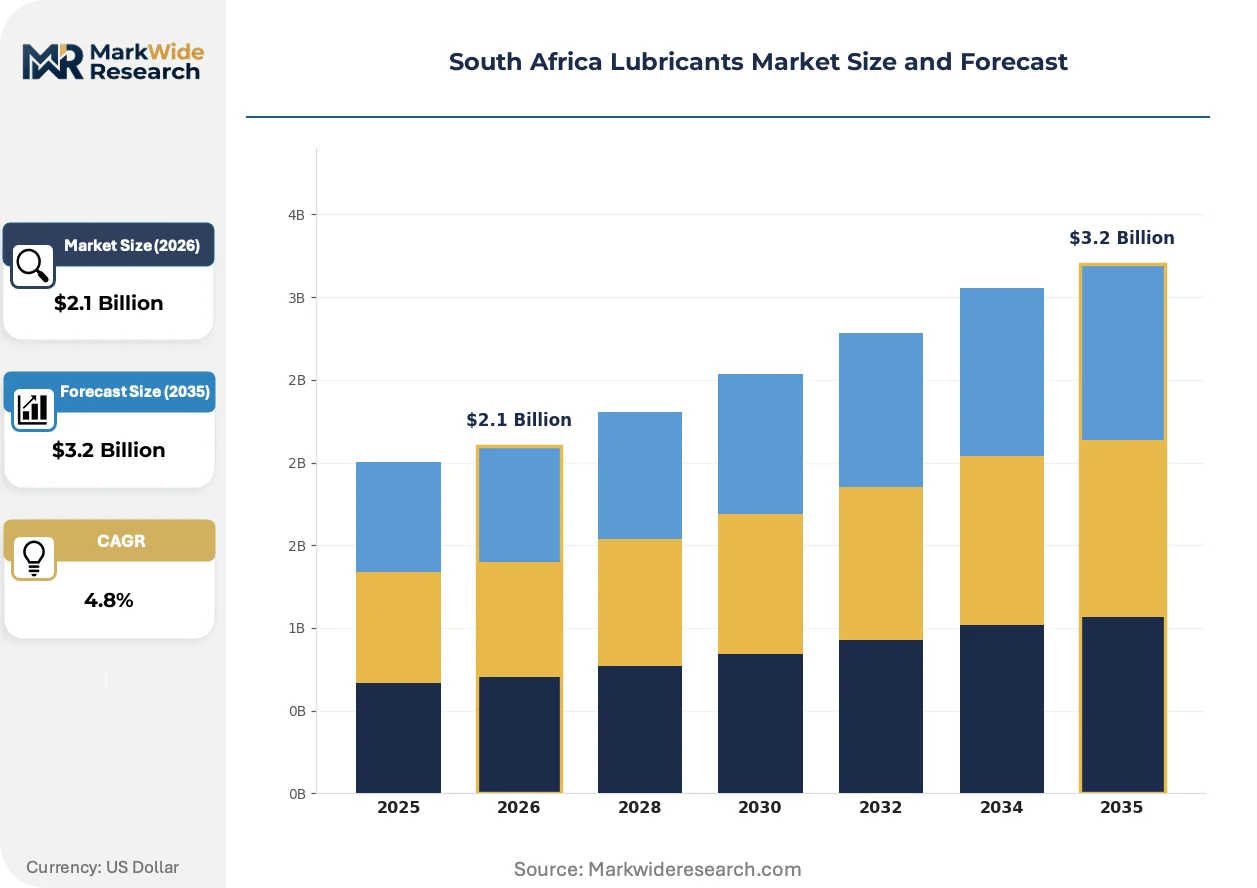
Market Dynamics
South Africa's carbon tax administration is compressing industrial lubricant procurement timelines as mining fleet operators accelerate synthetic oil adoption to offset emissions-linked operating cost penalties.
Growth Catalysts
- Carbon Tax Pressure:The South African Revenue Service's carbon tax regime forces industrial buyers toward lower-viscosity formulations that reduce fuel consumption and emissions exposure.
- Mining Equipment Intensity:Heavy-load conditions in platinum and coal extraction operations drive synthetic oil demand for extended drain intervals and thermal stability.
- Gauteng Cluster Concentration:Manufacturing and logistics hubs in Johannesburg and Pretoria generate concentrated bulk lubricant offtake from centralized procurement operations.
Market Restraints
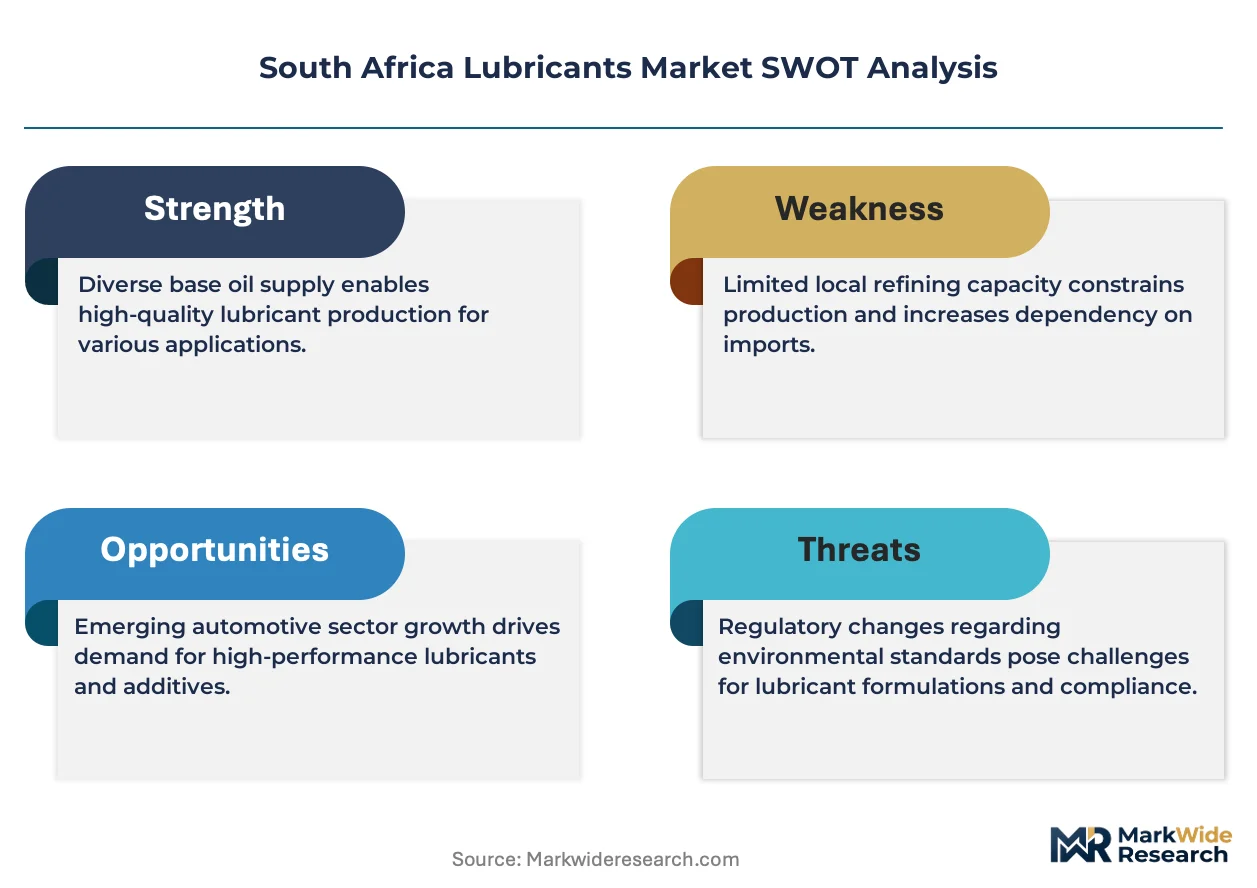
- Base Oil Import Dependence:South Africa's limited Group II/III base oil refining capacity creates exposure to dollar-denominated feedstock volatility and exchange rate risk.
- Synthetic Formulation Cost Premium:Polyalphaolefin and ester base stocks carry 40-60% higher unit costs versus mineral alternatives, constraining adoption in price-sensitive agricultural sectors.
- Counterfeit Lubricant Infiltration:Substandard products bearing falsified SABS marks erode legitimate supplier margins and equipment warranty compliance.
Strategic Opportunities
- KwaZulu-Natal Port Expansion:Durban container terminal growth and Richards Bay mining exports create untapped demand for marine and heavy-duty engine oils.
- EU Green Deal Alignment:Carbon-border adjustment mechanisms reward South African exporters adopting lower-emission lubricant specifications for EU-bound manufactured goods.
- Digital Fleet Monitoring:Oil condition sensors and predictive analytics enable servitization models linking lubricant supply to equipment uptime guarantees.
Industry Challenges
- Blending Capacity Bottlenecks:Limited automated batching infrastructure at secondary packaging facilities constrains just-in-time delivery to remote mining operations.
- SABS Certification Lag:Extended testing protocols for new additive packages delay product registration by 12-18 months against evolving engine manufacturer specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Lubricants Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Oil, Synthetic Oil, Biodegradable Oil, Additives End User: Automotive, Industrial, Marine, Agricultural Application: Engine Oils, Gear Oils, Hydraulic Fluids, Greases Distribution Channel: Retail, Wholesale, Direct Sales, Online |
| Companies Covered | BP plc (Castrol), Exxon Mobil Corporation, Shell plc, TotalEnergies, FUCHS, Astron Energy (Pty) Ltd., Sasol, Puma Energy, Engen Petroleum, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Lubricants Market Strategic Shifts
Synthetic formulation chemistry and emissions-linked procurement mandates are restructuring competitive advantage in South African lubricant supply. Technology integration, regulatory alignment, and buyer behavior transformation define the current innovation frontier.
Group III+ and polyalphaolefin base stocks are integrating into mining hydraulic and transmission systems to extend oil change intervals beyond 1,000 operating hours. Anglo American Platinum and Sibanye-Stillwater operations are standardizing these formulations across haul truck fleets. This integration compresses maintenance downtime costs while locking suppliers into long-term technical service partnerships.
The South African Revenue Service's carbon tax administration tightens lubricant viscosity specifications for industrial buyers seeking Scope 1 emissions reductions. Lower-viscosity hydraulic fluids and gear oils reduce pumping losses and fuel consumption in manufacturing plants. Mining procurement teams in the Rustenburg platinum belt now specify ISO VG 32 and VG 46 grades where VG 68 previously dominated.
Consolidated fleet operators in Gauteng and Mpumalanga are unbundling lubricant supply from original equipment manufacturer service contracts. Large logistics firms negotiate direct bulk supply agreements with blenders, bypassing traditional distributor markups. This disintermediation pressures independent distributors to add technical consulting and waste oil collection services to retain account control.
South Africa Lubricants Market Segmentation
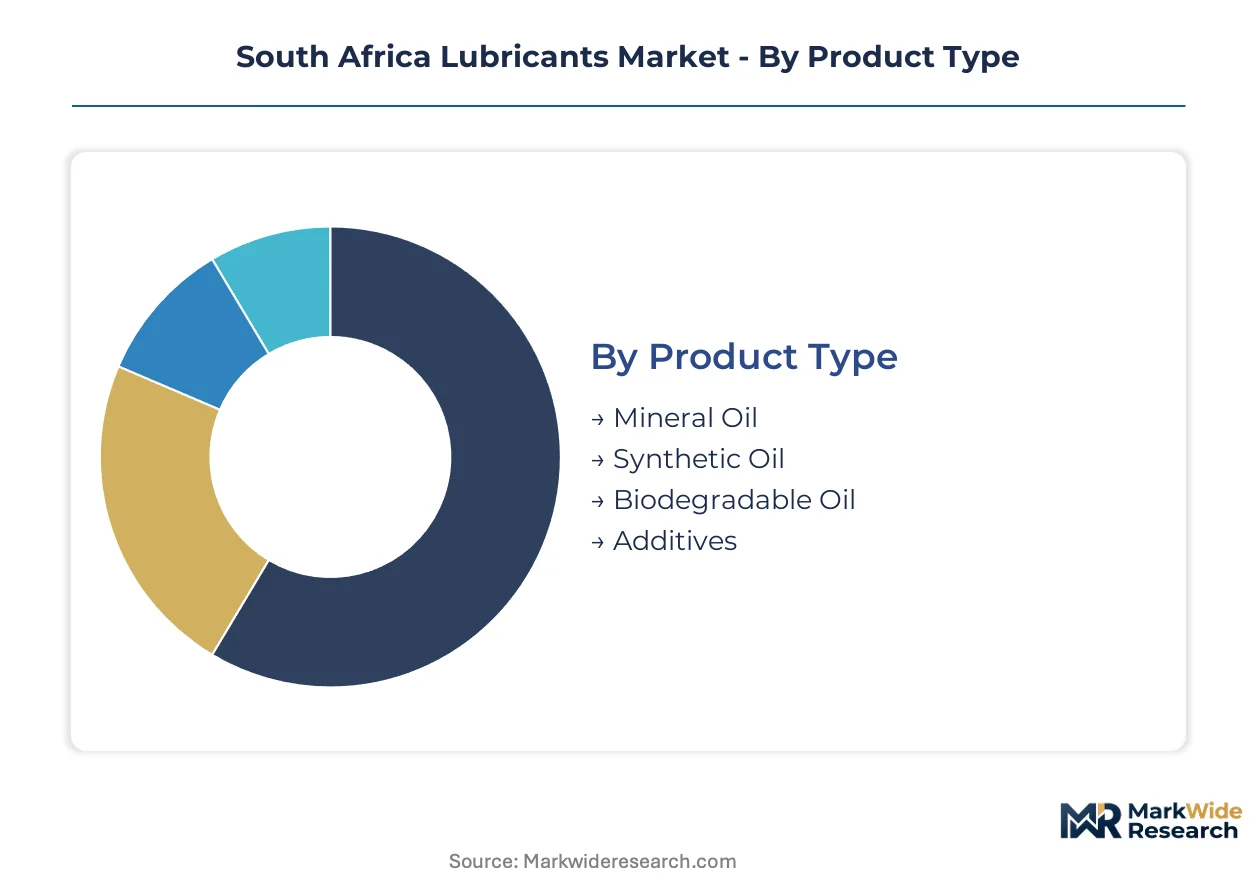
South Africa's lubricant segmentation reflects divergent certification burdens across product categories, with SABS mark requirements and OEM approvals creating tiered barriers to entry that reshape competitive positioning. Mining procurement teams and fleet operators navigate these specifications differently, driving distinct demand patterns across each segment dimension.
Product Type:
SABS certification intensity varies sharply across base oil categories, with synthetic formulations requiring extended additive package testing and biodegradable oils facing additional environmental compliance protocols.
- Mineral Oil:Refined petroleum base stocks dominate volume through established Group I supply chains. Gauteng manufacturing clusters and Mpumalanga coal operations consume bulk volumes where cost minimization outweighs extended drain interval benefits.
- Synthetic Oil:Polyalphaolefin and Group III+ formulations command premium positioning in platinum belt haul truck fleets. Anglo American Platinum specifications now mandate synthetics for hydraulic systems operating above 85°C ambient temperatures, compressing maintenance windows and locking in technical service contracts.
- Biodegradable Oil:Vegetable ester base stocks serve environmentally sensitive applications in KwaZulu-Natal port machinery and coastal marine equipment.
- Additives:Detergent, dispersant, and anti-wear chemical packages require separate SABS registration timelines.
Leading the category by volume: Mineral Oil. Growing fastest: Synthetic Oil.
End User:
Procurement sophistication diverges across end-user categories, with consolidated mining houses negotiating direct blender contracts while fragmented agricultural buyers remain distributor-dependent.
- Automotive:Passenger vehicle service shops and commercial fleet operators drive consistent demand for SAE 5W-30 and 15W-40 multigrade formulations. Johannesburg logistics corridors concentrate bulk offtake through centralized procurement operations serving thousand-vehicle fleets.
- Industrial:Manufacturing plants in Ekurhuleni and Vereeniging specify ISO VG 46 and VG 68 hydraulic fluids for press lines and conveyor systems. Carbon tax exposure now embeds viscosity optimization into procurement scorecards.
- Marine:Durban container terminal expansion and Richards Bay mineral exports create concentrated demand for trunk piston and system oils.
- Agricultural:Price-sensitive grain and livestock operations in Free State and North West provinces constrain synthetic adoption despite equipment warranty specifications.
Volume concentration: Automotive. Steepest expansion trajectory: Industrial.
Application:
Application-level segmentation tracks equipment manufacturer specification evolution, with OEM drain interval extensions forcing lubricant reformulation cycles.
- Engine Oils:Crankcase lubricants for compression-ignition and spark-ignition powertrains constitute the largest value pool. Mining fleet operators in Rustenburg and Limpopo prioritize CJ-4 and FA-4 heavy-duty specifications for exhaust aftertreatment compatibility.
- Gear Oils:Hypoid and industrial gear formulations serve transmission and final drive applications. EP additive packages face SABS retesting under revised scuffing resistance protocols.
- Hydraulic Fluids:Power transmission oils for mobile and stationary equipment. Lower-viscosity ISO VG 32 grades displace VG 46 in carbon-conscious manufacturing plants seeking pumping loss reduction.
- Greases:Thickener-stabilized lubricants for bearing and chassis applications. Lithium complex and polyurea thickeners compete in high-temperature mining environments.
Dominant by revenue: Engine Oils. Climbing the fastest: Hydraulic Fluids.
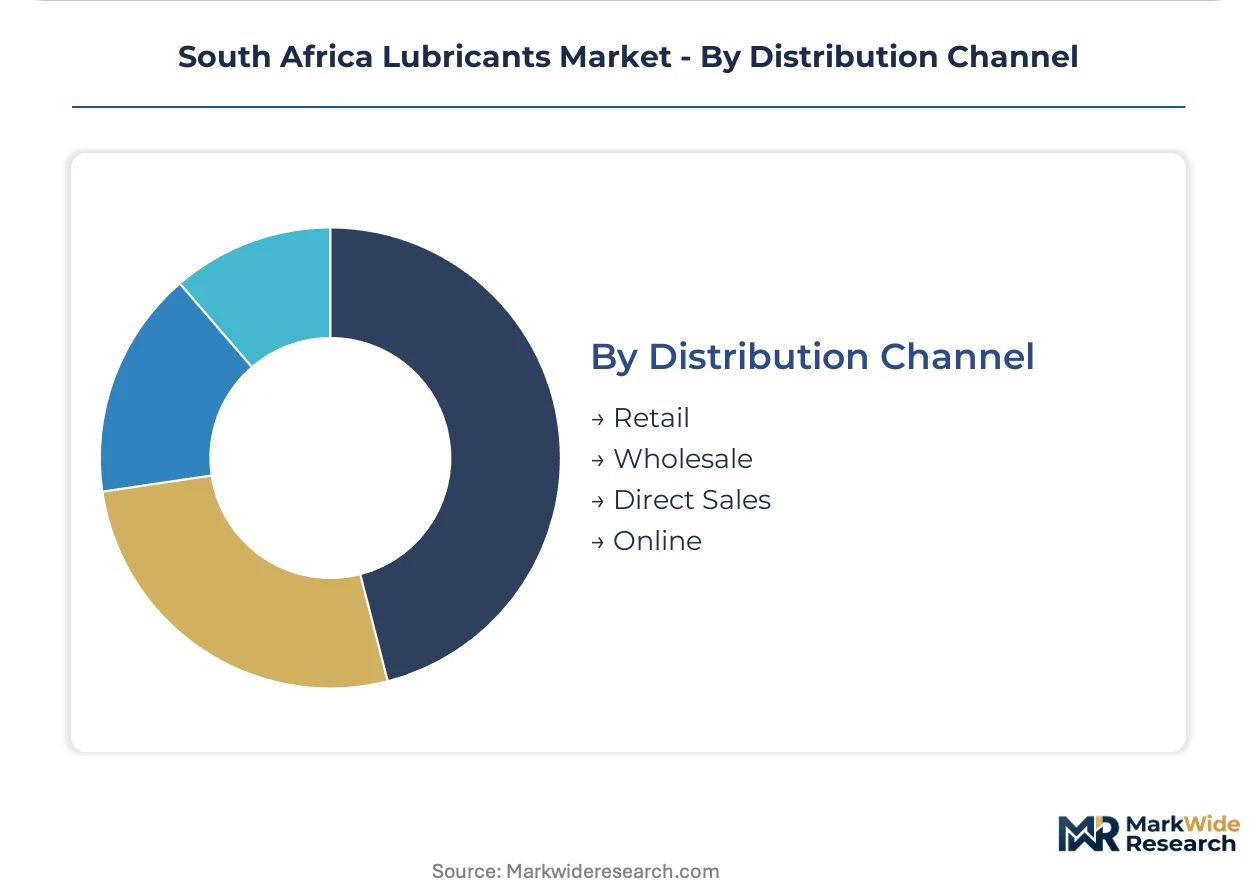
Distribution Channel:
Channel structure reflects buyer scale concentration, with large consumers disintermediating traditional supply tiers.
- Retail:Forecourt convenience stores and independent auto parts outlets serve DIY consumers and small workshops. Shell's service station network anchors this tier through brand recognition and location density.
- Wholesale:Regional distributors maintain inventory buffers for mid-size fleet operators and independent service centers. Margin compression from direct sales is forcing technical service bundling.
- Direct Sales:Bulk supply agreements between blenders and consolidated mining or logistics fleets bypass distributor markups entirely. Sasol's captive base oil production supports aggressive direct pricing.
- Online:E-commerce platforms capture emerging demand from remote agricultural buyers and small fleet operators seeking price transparency.
Channel leadership by volume: Wholesale. Gaining share fastest: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Johannesburg anchors South African lubricant demand through its manufacturing and logistics corridor, with Pretoria and Ekurhuleni forming a concentrated industrial triangle that consumes bulk hydraulic and engine oil volumes.
Gauteng Province
Mining procurement teams and fleet operators drive synthetic oil demand for extended drain intervals. The South African Revenue Service's carbon tax administration forces viscosity optimization into procurement scorecards. Rustenburg platinum belt operations now specify ISO VG 32 hydraulic fluids where VG 68 previously dominated, compressing maintenance windows.
KwaZulu-Natal
Durban container terminal expansion and Richards Bay mineral exports create concentrated demand for marine trunk piston oils and heavy-duty engine lubricants. The country's national port regulator oversees environmental compliance for coastal machinery. Vegetable ester base stocks penetrate port equipment fleets seeking biodegradable formulations for sensitive coastal zones.
Mpumalanga
Coal extraction operations and power generation clusters sustain bulk mineral oil consumption where cost minimization outweighs synthetic premiums. The Department of Mineral Resources and Energy monitors fuel and lubricant pricing mechanisms affecting distribution economics. Middelburg and Witbank mining houses negotiate direct blender contracts, bypassing traditional distributor markups entirely.
Western Cape
Winery equipment and agricultural machinery sustain seasonal lubricant demand through distributor-dependent procurement patterns. The country's agricultural product regulator enforces equipment warranty specifications that constrain synthetic adoption in price-sensitive grape and grain operations. Stellenbosch and Paarl clusters remain locked in mineral oil formulations despite OEM recommendations.
Free State and North West
Grain and livestock operations anchor price-sensitive agricultural lubricant consumption. The South African Bureau of Standards enforces quality marks that counterfeit products frequently falsify, eroding legitimate supplier margins. Bloemfontein and Klerksdorp service centers struggle with substandard infiltration while equipment dealers push warranty-compliant specifications.
South Africa Lubricants Market Competitive Environment
Premium-margin players sit above commodity-margin players across base oil technology tiers, with synthetic formulation specialists commanding technical service premiums while mineral oil distributors compete on logistics coverage. The vendor base separates into three strategic archetypes: integrated oil majors with captive refining, independent blenders with flexible formulation capabilities, and regional distributors bundling technical consulting. Consolidation pressure intensifies as large mining houses disintermediate supply tiers, while capacity expansion focuses on automated batching infrastructure for just-in-time remote delivery.
Among integrated oil majors, Shell plc and BP plc (Castrol) occupy positions that exemplify the premium-tier synthetic specialization archetype, while Sasol anchors the captive base oil production model. These three entities represent distinct competitive positioning vectors: forecourt network density, mining equipment technical partnerships, and backward integration into upstream feedstock supply.
| Leading Market Players |
|---|
| BP plc (Castrol) |
| Exxon Mobil Corporation |
| Shell plc |
| TotalEnergies |
| FUCHS |
| Astron Energy (Pty) Ltd. |
| Sasol |
| Puma Energy |
| Engen Petroleum |
| Others |
Value Chain & Pricing Dynamics
Polyalphaolefin base stock costs transmit from Singapore and Middle Eastern refineries through Group III+ synthetic formulations to mining procurement teams in Rustenburg and Limpopo, compressing margins at each tier while carbon tax exposure forces viscosity-grade trade-offs.
Pricing Analysis
Equipment uptime guarantees anchor value-based pricing for synthetic hydraulic fluids in Anglo American Platinum and Sibanye-Stillwater fleets, where extended drain intervals beyond 1,000 operating hours justify 40-60% premiums over mineral alternatives. Price differentiation rests on SABS certification grade and technical service bundling, with carbon tax compliance now embedded in procurement scorecards. Cost compression in agricultural sectors intensifies as Free State grain operations resist synthetic adoption despite OEM warranty requirements. Mining houses show lowest price sensitivity, while livestock and vineyard operators in Western Cape exhibit highest.
Supply Chain Analysis
Regional distribution centers in Johannesburg and Durban operate hub-and-spoke patterns feeding Mpumalanga coal belts and KwaZulu-Natal port machinery. Base oil supply concentrates in Singapore, South Korea, and the United States, with South Africa's limited Group II/III refining capacity drawing from dollar-denominated feedstock markets. Raw material dependencies span polyalphaolefin, Group III+ hydrocracked stocks, and vegetable ester base oils. Single-source vulnerability from Middle Eastern refinery concentration threatens formulation continuity. Distribution runs through direct blender contracts for consolidated mining fleets and wholesale distributors for fragmented agricultural buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic formulation chemistry is displacing mineral base stocks across South African mining and industrial applications, with carbon tax administration accelerating the transition timeline for procurement teams.
For Market Incumbents: Lock in long-term technical service partnerships with Rustenburg platinum belt operators by embedding oil condition monitoring into supply contracts, while defending against disintermediation through waste oil collection and predictive maintenance bundling. Backward integration into Group III+ base oil sourcing mitigates Singapore refinery concentration risk and secures formulation cost control. For New Entrants and Emerging Players: The EU Green Deal's carbon-border adjustment mechanisms in Europe opens a window for biodegradable lubricant specialists targeting KwaZulu-Natal port equipment and EU-bound manufactured goods exporters. White-space concentration sits in vegetable ester formulations for environmentally sensitive coastal machinery and digital fleet monitoring platforms for mid-size logistics operators. A technical consulting-led go-to-market approach bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor independent blenders with flexible formulation capabilities and SABS certification pipelines in Gauteng industrial corridors. Long-term viability hinges on synthetic transition readiness and automated batching infrastructure for just-in-time remote delivery. The signal to watch is carbon tax threshold escalation pressuring mineral oil-dependent distributors into consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III+ Base Oil Supply | Sasol's captive production anchors cost position against Singapore refinery volatility. |
| Digital Fleet Monitoring Platform Deployment | Oil condition sensors enable servitization linking lubricant supply to uptime guarantees. |
| SABS Certification Pipeline Expansion | Accelerated additive package registration compresses 12-18 month testing delays. |
| Biodegradable Formulation Development | Vegetable ester base stocks penetrate KwaZulu-Natal port environmental compliance requirements. |
| Automated Batching Infrastructure Investment | Just-in-time delivery capability secures remote mining operations from blending bottlenecks. |
Study Parameters
Trade statistics from the South African Revenue Service, SABS certification registries, and mining procurement databases formed the secondary backbone, supplemented by primary interviews with lubricant blending plant managers, mining fleet maintenance directors, and industrial procurement leads across Gauteng and Mpumalanga. Bottom-up volume modeling triangulated against top-down sectoral consumption estimates from the Department of Mineral Resources and Energy.
Historical trendline analysis tracked synthetic adoption rates and viscosity-grade shifts across the analysis window, with segmentation modeling across base oil category, end-user industry, application type, and distribution channel structure. CAGRs derived from equipment parc expansion, drain interval extension trajectories, and carbon tax exposure elasticity. Forecast inputs incorporated mining production forecasts and automotive fleet turnover patterns.
The model assumes a particular technology adoption path; alternative pathways for biodegradable and re-refined base oil penetration would alter the outlook if EU Green Deal alignment accelerates or SABS environmental protocols tighten. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Tar Oil Market
Petroleum Products
Balanos Oil Market
Petroleum Products
PAG Base Oil Market
Petroleum Products
North America Natural Gas Liquids Market
Petroleum Products
Liquefied Petroleum Gas Market
Petroleum Products
Germany Refined Petroleum Products Market
Petroleum Products
Green Petcoke Market
Petroleum Products
Saudi Arabia Refined Petroleum Products Market
Petroleum Products
Hydrocarbon Market
Petroleum Products
Petroleum Liquid Feedstock Market
Petroleum Products
Quenching Oil Market
Petroleum Products
Europe Refined Petroleum Products Market
Petroleum Products
Southeast Asia Refined Petroleum Products Market
Petroleum Products
Gasoline-Naphtha-Crude-MTBE Market
Petroleum Products
Crude Tall Oil Market
Petroleum Products
Crude Oil Flow Improvers Market