
 Petroleum Liquid Feedstock Market | 2026-2036
Petroleum Liquid Feedstock Market Size, Share, and Industry Trends Forecast 2026-2036
Petroleum Liquid Feedstock Market Intelligence
ISO 8217 marine fuel quality standards is unwinding competitive access for smaller traders lacking blending certification. ExxonMobil Corporation leverages integrated upstream-downstream assets to secure consistent heavy crude supply for coking operations. Saudi Aramco dominates long-term term contracts with Asian refiners, while TotalEnergies SE anchors European naphtha arbitrage flows through Rotterdam storage.
Petroleum liquid feedstock denotes crude oil-derived hydrocarbon streams—including naphtha, gasoil, vacuum gasoil, and atmospheric residue—processed through fractional distillation at temperatures between 350°C and 400°C to yield transportation fuels, olefins, and aromatics. Gasoline and naphtha segments lead value capture, with naphtha feeding ethylene crackers in integrated petrochemical sites. Diesel maintains mature volume pools in industrial applications, while kerosene faces structural pressure from aviation decarbonization targets.
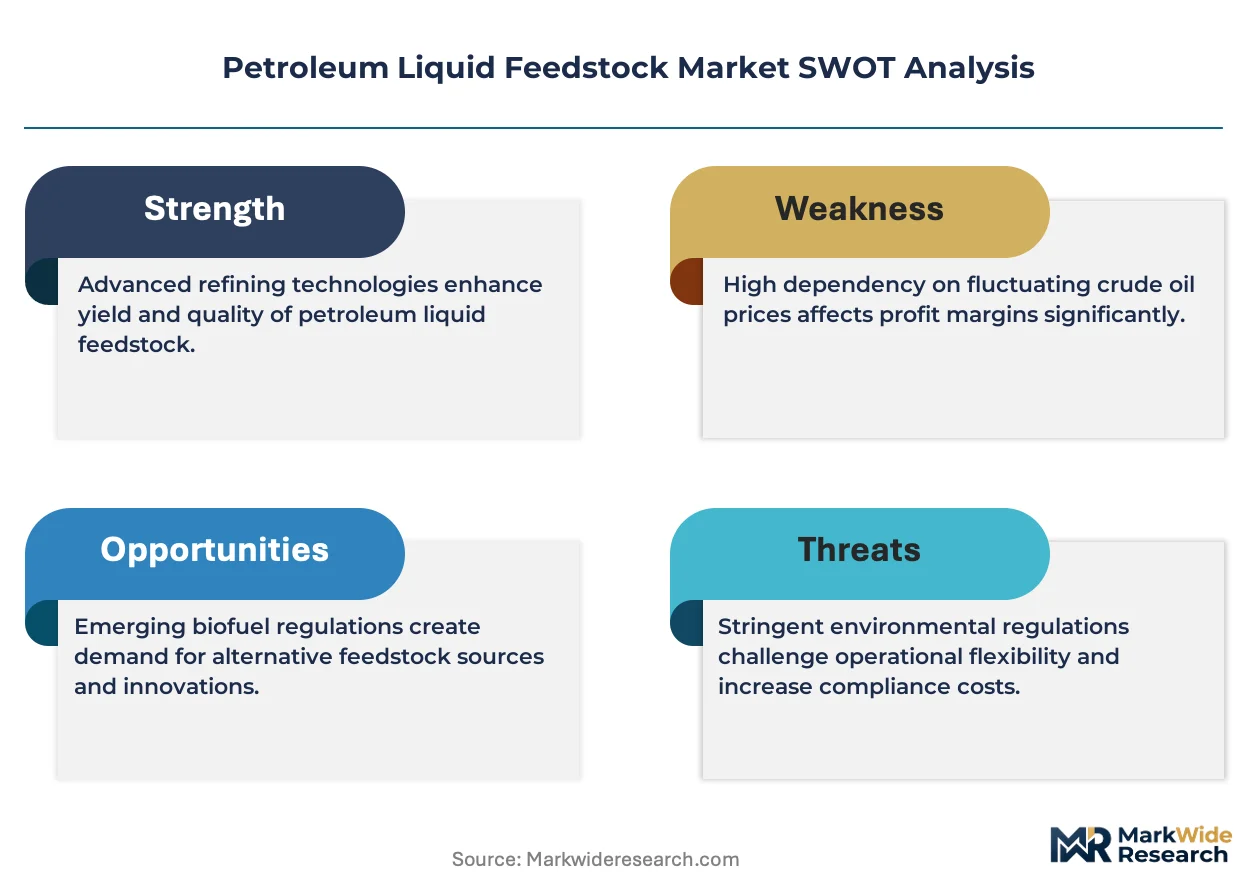
EPA fuel sulfur regulations and IMO 2020 marine fuel standards constrain high-sulfur residual trading, forcing refiners toward deeper conversion capacity. China's MEE enforces emissions caps on coastal refineries, redirecting feedstock flows to compliant facilities. Stakeholders must monitor carbon border adjustment mechanisms and hydrogen substitution timelines to calibrate long-term feedstock positioning.
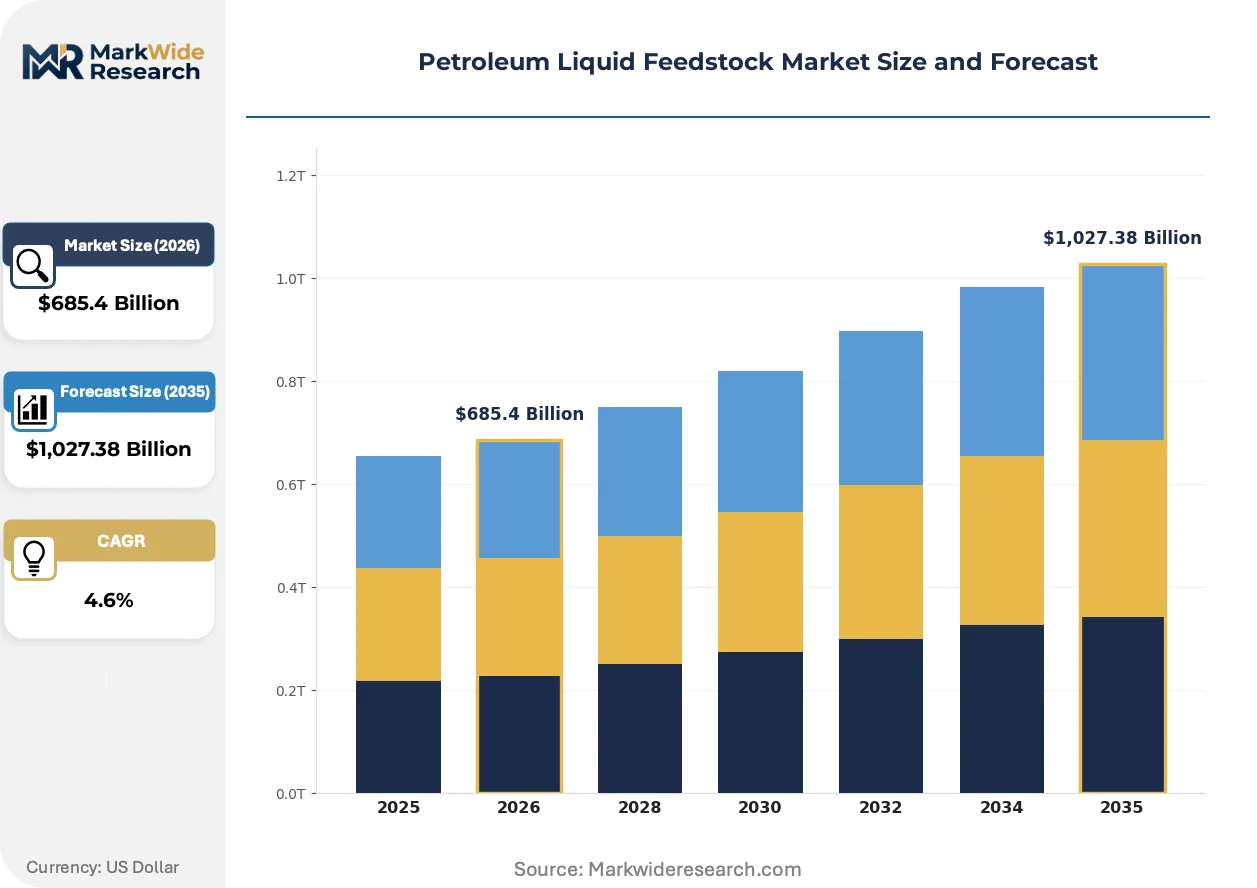
Market Dynamics
IMO 2020 low-sulfur mandates and China's MEE emissions caps are forcing refiners toward deeper conversion investments, compressing residual fuel margins while redirecting feedstock flows to compliant coastal complexes.
Growth Catalysts
- Integrated refining-petrochemical complexes:China's eastern coast facilities combine coking, cracking, and aromatics extraction in single-site configurations, capturing value across gasoline, naphtha, and olefin chains.
- Marine fuel specification evolution:ISO 8217 quality standards create certified blending demand, opening arbitrage windows for traders with storage and testing infrastructure at Rotterdam, Singapore, and Fujairah.
- Ethylene cracker feedstock diversification:Petrochemical operators in South Korea and Saudi Arabia are expanding naphtha intake capacity to offset ethane supply volatility from US shale.
Market Restraints
- Heavy crude supply concentration:Venezuelan and Iranian crude displacement has concentrated medium-heavy sour supply under Saudi Aramco and Russian export programs, amplifying term contract leverage.
- Carbon border adjustment exposure:EU CBAM pilot phase coverage of indirect emissions threatens residual fuel and unabated naphtha imports into Rotterdam and Antwerp refining hubs.
- Hydrogen substitution timelines:Aviation and maritime decarbonization roadmaps from ICAO and IMO signal long-dated kerosene and bunker demand erosion, stranding conversion capex in 15-year asset cycles.
Strategic Opportunities
- Circular feedstock integration:Chemical recycling pyrolysis oils from plastic waste are qualifying as refinery co-feeds under EU RED III sustainability criteria, opening circular naphtha premiums.
- IMO 2020-compliant blending infrastructure:Independent storage operators at Fujairah and Houston are expanding very low sulfur fuel oil (VLSFO) blending capacity to capture marine fuel certification premiums.
- Blue hydrogen production tie-ins:Refiners in the Netherlands and Canada are configuring coking and gasification units for carbon-captured hydrogen output, qualifying for IRA 45Q and EU Innovation Fund support.
Industry Challenges
- Process control engineering scarcity:Deep conversion units—residue hydrocrackers and ebullated-bed cokers—require specialized catalyst management expertise concentrated at Honeywell UOP and Axens licensing networks.
- Legacy DCS integration:Refinery distributed control systems from 1990s vintage Honeywell TDC 3000 and Yokogawa CENTUM architectures resist IIoT sensor deployment without costly middleware layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Petroleum Liquid Feedstock Market |
| Market Size in 2026 | $685.4 Billion |
| Market Size in 2035 | $1,027.38 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline, Diesel, Kerosene, Naphtha Application: Transportation, Industrial, Residential Heating, Power Generation End User: Refineries, Petrochemical Plants, Power Utilities, Transportation Industry Distribution Channel: Direct Sales, Retail Outlets, Wholesale Distributors, Online Platforms |
| Companies Covered | ExxonMobil Corporation, Chevron Corporation, Shell plc, Saudi Aramco, TotalEnergies SE, BP plc, China National Petroleum Corporation, Sinopec, Phillips 66, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Petroleum Liquid Feedstock Market Strategic Shifts & Innovations
Feedstock quality degradation and regulatory sulfur constraints are accelerating process technology substitution, with refiners prioritizing residue upgrading over atmospheric distillation expansion.
Advanced residue hydrocracking is fragmenting the traditional coking-gasification technology hierarchy. Chevron Lummus Global and Shell Catalysts are licensing ebullated-bed units to Indian and Middle Eastern refiners seeking higher liquid yields from heavy sour crudes. These installations enable direct naphtha and diesel production from vacuum residue, bypassing fuel oil intermediates that face shrinking marine demand.
EU F-Gas Regulation phase-down schedules are pressuring refinery refrigeration and flare recovery systems. Operators at Antwerp and Rotterdam clusters are retrofitting propane chiller loops with ammonia-based alternatives to maintain olefin recovery rates while eliminating hydrofluorocarbon inventory. This transition demands simultaneous compressor metallurgy upgrades and safety system recertification.
Buyers in Asian petrochemical procurement are consolidating term naphtha contracts around integrated supplier-refiner relationships, displacing spot arbitrage dependence. South Korean and Taiwanese cracker operators now prioritize 3-5 year offtake agreements with Saudi Aramco and ADNOC over Rotterdam-timed cargo optimization. This shift concentrates counterparty risk but secures feedstock qualification for downstream polymer certification schemes.
Petroleum Liquid Feedstock Market Segmentation
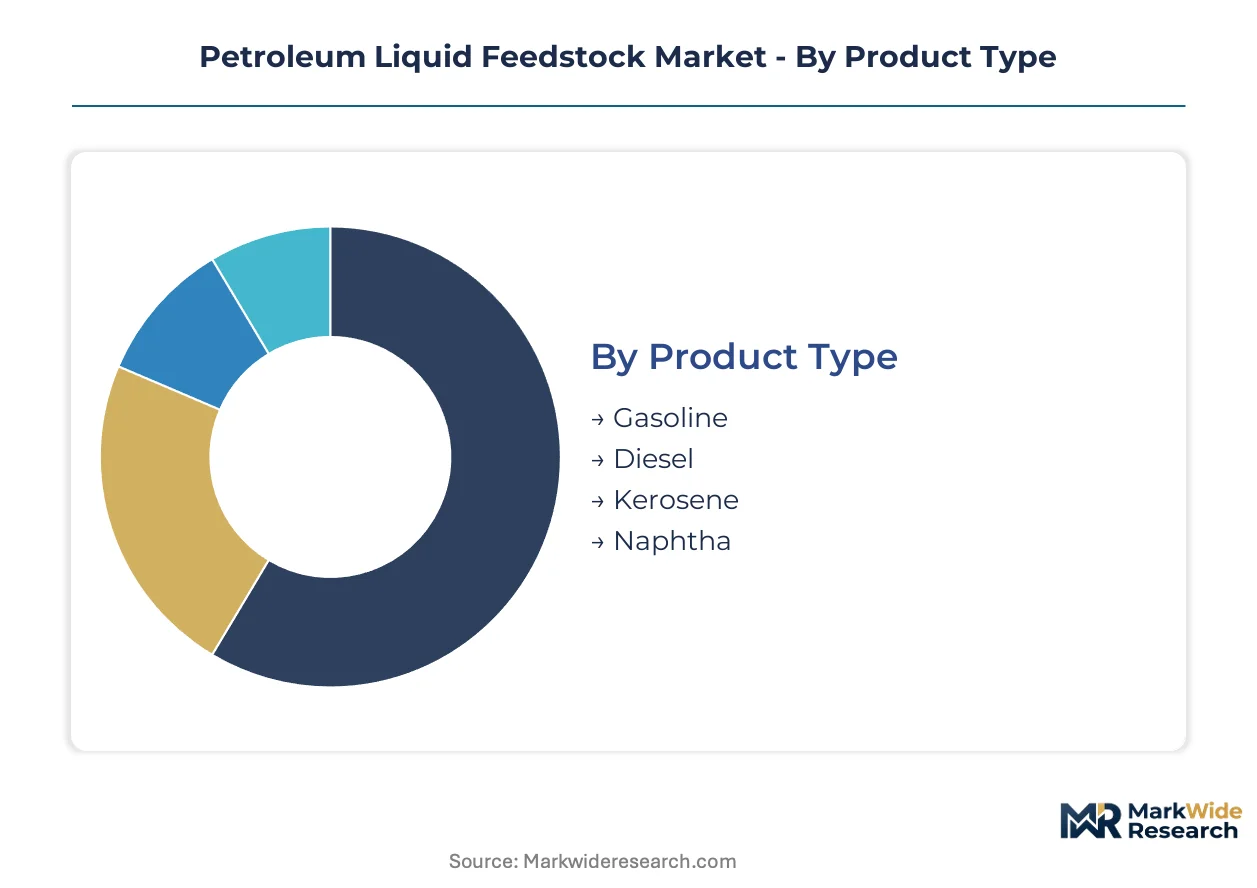
Segmentation in petroleum liquid feedstock markets tracks how refinery output splits across competing value chains. Margin capture varies sharply between transportation fuels facing electrification pressure and petrochemical feedstocks with polymer demand tailwinds.
Product Type:
Margin pools concentrate in lighter distillates feeding integrated petrochemical complexes, while residual products face marine fuel specification compression.
- Naphtha:Light straight-run and reformate fractions with 6-12 carbon paraffin and aromatic content serve as primary ethylene cracker feedstock. Demand concentrates at South Korean and Saudi Arabian petrochemical complexes diversifying away from volatile US shale ethane. Naphtha holds installed capacity. Gasoline is rotating up the share rankings.
- Gasoline:C5-C12 hydrocarbon blend of reformate, alkylate, and FCC naphtha meeting octane specifications for spark-ignition engines. China's eastern coast refineries optimize gasoline-naphtha split based on polymer margin signals from integrated aromatics units.
- Diesel:C10-C20 distillate with cetane index requirements for compression-ignition engines and industrial burner applications.
- Kerosene:C9-C16 cut refined to flash point and smoke point specifications for aviation turbine fuel and residential heating.
Kerosene carries aviation decarbonization exposure. Naphtha maintains the steepest expansion trajectory through cracker capacity additions.
Application:
Volume distribution reflects infrastructure lock-in, with transportation dominating barrel flows while industrial applications provide price floor stability.
- Transportation:Road, marine, and aviation fuel offtake from refinery blending terminals and coastal storage hubs. Diesel demand concentrates in European freight corridors facing EU ETS carbon cost pass-through, while gasoline consumption plateaus in Chinese tier-one cities with EV penetration mandates.
- Industrial:Process heating, boiler fuel, and feedstock for chemical manufacturing in cement, steel, and fertilizer plants. Naphtha offtake from South Korean and Taiwanese crackers dominates this segment with term contract consolidation displacing spot arbitrage.
- Residential Heating:Kerosene and gasoil consumption in distributed burner systems, concentrated in Northeast Asian and Northern European markets.
- Power Generation:Residual fuel oil and diesel in peaking plants and island grid systems, shrinking under renewable substitution.
Transportation anchors throughput volumes. Industrial is climbing the fastest as petrochemical integration deepens.
End User:
Customer concentration shapes contract structures, with integrated refining-petrochemical sites capturing margin across multiple processing stages.
- Petrochemical Plants:Ethylene crackers and aromatics complexes consuming naphtha, LPG, and light distillate feedstocks. South Korean operators at Yeosu and Daesan clusters source through 3-5 year term agreements with Saudi Aramco and ADNOC, prioritizing feedstock qualification for polymer certification schemes over Rotterdam-timed cargo optimization.
- Refineries:Inter-refinery transfers of intermediate streams and blending components for finished product optimization. Chinese coastal complexes combine coking, cracking, and aromatics extraction in single-site configurations capturing value across gasoline, naphtha, and olefin chains.
- Power Utilities:Residual fuel and distillate offtake for peaking generation and grid stabilization.
- Transportation Industry:Marine fuel suppliers, aviation fuel terminals, and road fuel distributors.
Refineries hold installed capacity. Petrochemical plants are rotating up the share rankings.
Distribution Channel:
Channel selection determines working capital intensity and specification compliance exposure, with certified blending infrastructure commanding premium access.
- Wholesale Distributors:Terminal operators and trading houses aggregating refinery output for resale to end users. Independent storage operators at Fujairah and Houston are expanding VLSFO blending capacity to capture marine fuel certification premiums under ISO 8217 quality standards.
- Direct Sales:Term contract offtake from refinery gate to integrated petrochemical or utility customers. Asian petrochemical procurement is consolidating around integrated supplier-refiner relationships, displacing spot arbitrage dependence.
- Retail Outlets:Branded and unbranded fuel stations for finished transportation fuels.
- Online Platforms:Digital procurement interfaces for spot cargo and scheduled delivery optimization.
Direct sales holds installed capacity. Wholesale distributors are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon border adjustment mechanisms and hydrogen substitution timelines are redirecting feedstock investment toward compliant refining hubs. National regulators enforce divergent sulfur and emissions standards that fragment trade flows.
China
Integrated refining-petrochemical complexes along the eastern coast consume rising naphtha volumes for ethylene crackers. MEE emissions caps redirect flows to compliant coastal facilities. Zhejiang and Shandong provinces host single-site configurations combining coking, cracking, and aromatics extraction.
United States
Gulf Coast refiners process medium-heavy sour crudes through coking and hydrocracking units. EPA fuel sulfur regulations constrain high-sulfur residual trading. Houston storage operators expand VLSFO blending capacity to capture ISO 8217 marine fuel certification premiums.
Saudi Arabia
State-controlled crude export programs dominate long-term term contracts with Asian refiners. SAMR standards govern product quality for domestic consumption. Jubail industrial city anchors petrochemical integration with ethylene crackers diversifying beyond ethane toward naphtha flexibility.
South Korea
Yeosu and Daesan petrochemical clusters source naphtha through 3-5 year term agreements displacing spot arbitrage. MFDS oversees industrial chemical safety compliance. Ulsan refining complex optimizes gasoline-naphtha splits based on polymer margin signals from integrated aromatics units.
Netherlands
Rotterdam and Antwerp refining hubs face EU CBAM pilot phase coverage of indirect emissions threatening unabated naphtha imports. F-Gas Regulation phase-down schedules pressure refrigeration system retrofits. Port operators configure coking and gasification units for carbon-captured hydrogen output qualifying for EU Innovation Fund support.
Petroleum Liquid Feedstock Market Key Industry Players
Player mix skews toward national oil companies with integrated upstream-downstream assets and Western majors with technology licensing networks. Market structure concentrates around term contract leverage and certified blending infrastructure access. Strategic archetypes include state-backed crude exporters, integrated refining-petrochemical operators, and independent storage-terminal specialists. Dominant competitive moves encompass capacity expansion at coastal complexes and strategic partnerships for residue upgrading technology.
Within the state-backed crude exporter tier, Saudi Aramco and China National Petroleum Corporation occupy positions securing long-term supply relationships with Asian refiners. ExxonMobil Corporation exemplifies the integrated major archetype with upstream-downstream asset coordination. These anchors represent contrasting pathways: term contract leverage versus operational integration across fractional distillation and conversion units.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Chevron Corporation |
| Shell plc |
| Saudi Aramco |
| TotalEnergies SE |
| BP plc |
| China National Petroleum Corporation |
| Sinopec |
| Phillips 66 |
| Others |
Cost & Logistics Intelligence
Ethylene cracker feedstock diversification away from volatile US shale ethane toward naphtha flexibility is simultaneously redrawing supply geography toward Middle Eastern term contract anchors and compressing spot arbitrage premiums at Rotterdam and Singapore trading hubs.
Pricing Analysis
Cost-plus contract patterns with Platts Japan Naphtha C&F indexation dominate Asian petrochemical procurement, with Saudi Aramco and ADNOC term structures incorporating freight differentials and quality adjustments. Price differentiation separates ISO 8217-certified marine fuel blends from uncertified residual streams, with VLSFO premiums at Fujairah and Houston reflecting testing and storage infrastructure costs. Pricing pressure stems from carbon border adjustment exposure at EU refining hubs, with margins tightening for unabated naphtha imports into Rotterdam and Antwerp. Integrated refining-petrochemical operators exhibit lowest price sensitivity due to captive value capture across gasoline, naphtha, and olefin chains, while independent traders face highest sensitivity to freight and certification cost pass-through.
Supply Chain Analysis
Strait of Hormuz transit underwrites approximately one-fifth of global petroleum liquid feedstock flows, with chokepoint concentration amplifying disruption risk across Asian refinery supply schedules. Geographic supply concentration centers on Saudi Arabia, Russia, and the United States, with medium-heavy sour crude programs increasingly controlled by state export entities. Raw material dependencies encompass vacuum gasoil for hydrocracker units, atmospheric residue for coker feeds, and hydrogen for desulfurization operations. Tariff exposure on refined product movements between regional hubs threatens arbitrage economics, particularly for naphtha flows into South Korean and Taiwanese cracker complexes. Distribution runs through Rotterdam, Singapore, and Fujairah storage terminals, with certified blending infrastructure commanding premium access under evolving ISO 8217 marine fuel standards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat structure where regulatory entrenchment around IMO 2020 compliance certification and MEE emissions caps creates durable barriers against unqualified competitors.
For Market Incumbents: Fortify term contract leverage with Asian petrochemical operators by extending 3-5 year naphtha offtake agreements that embed feedstock qualification for downstream polymer certification schemes. Expand VLSFO blending capacity at Fujairah and Houston storage terminals to capture ISO 8217 certification premiums as marine fuel specification evolution accelerates. Counter hydrogen substitution timelines threatening long-dated kerosene demand by configuring coking and gasification units for carbon-captured hydrogen output qualifying for IRA 45Q and EU Innovation Fund support.
For New Entrants and Emerging Players: ISO 8217 marine fuel quality certification fast-tracks market access for independent storage operators lacking legacy term contract relationships with national oil companies. White-space targets include circular feedstock integration through chemical recycling pyrolysis oils qualifying as refinery co-feeds under EU RED III sustainability criteria, and blue hydrogen production tie-ins at Netherlands and Canada coking complexes. The most penetrable segment sits with petrochemical procurement consolidation around integrated supplier-refiner relationships displacing spot arbitrage dependence. A go-to-market angle centers on digital procurement interfaces for spot cargo optimization serving mid-sized Asian cracker operators.
For Investors and Strategic Acquirers: The market sits at a conversion-capex intensity phase that favors integrated refining-petrochemical operators with stranded asset resilience and technology licensing networks. Long-term viability across the analysis window hinges on feedstock positioning ahead of carbon border adjustment mechanism expansion and hydrogen substitution roadmaps. Acquisition target archetypes include independent storage-terminal specialists with certified blending infrastructure at Rotterdam, Singapore, or Fujairah, and residue upgrading technology licensors with ebullated-bed coker deployment capabilities. The signal to watch as inflection indicator is EU CBAM pilot phase coverage expansion beyond indirect emissions to direct refinery CO2 output, which would reprice unabated naphtha import economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Residue Hydrocracker Capacity Addition | Enables direct naphtha production from vacuum residue at Indian and Middle Eastern refiners, bypassing fuel oil intermediates. |
| Backward Integration into Heavy Crude Supply | Secures consistent vacuum gasoil feedstock for coking operations through upstream asset coordination. |
| ISO 8217 Certification Investment | Opens arbitrage windows for traders with storage and testing infrastructure at Rotterdam, Singapore, and Fujairah. |
| Long-term Naphtha Supply Agreement | Concentrates counterparty risk but secures feedstock qualification for South Korean and Taiwanese polymer certification schemes. |
| Ammonia-based Refrigeration Retrofit | Maintains olefin recovery rates at Antwerp and Rotterdam clusters while eliminating hydrofluorocarbon inventory under EU F-Gas Regulation. |
Research Approach
Initial hypotheses were tested against primary input from refinery operations managers, petrochemical procurement leads, marine fuel blending terminal operators, and residue upgrading technology licensors, then refined through secondary validation against customs trade data, SEC 10-K filings, EPA fuel sulfur compliance records, and IEA refinery configuration databases. Bottom-up capacity and throughput estimates triangulated against top-down demand projections from ethylene cracker expansion announcements and integrated refining-petrochemical complex commissioning schedules.
Variance decomposition across the projection horizon isolates volume, price, and mix effects within naphtha, gasoline, diesel, and residual fuel segments, with CAGRs derived from regression against historical throughput correlations with polymer margin indices and marine fuel specification spreads. Segmentation dimensions encompass product type, application, end user, and distribution channel, with regional production hub clustering capturing MEE emissions cap enforcement and EU CBAM pilot phase coverage. Industry-specific forecast inputs include ethane-naphtha feedstock switching elasticities and coking capacity utilization rates at Chinese eastern coast complexes.
Underlying assumptions cover IMO 2020 compliance enforcement continuity, Saudi Aramco term contract pricing discipline, and ethylene cracker feedstock diversification timelines, with deviation risk concentrated in hydrogen substitution acceleration and carbon border adjustment mechanism expansion. Practitioners should keep alternative scenarios live as aviation decarbonization roadmaps and maritime fuel specification evolution reshape long-dated demand trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Petroleum Liquid Feedstock Naphtha and Gas Oil Sales Market
Petroleum Products
Oil Shale Market
Petroleum Products
Africa Refined Petroleum Products Market
Petroleum Products
Petroleum Wax Market
Petroleum Products
Australia Refined Petroleum Products Market
Petroleum Products
India White Oil Market
Petroleum Products
LPG [Liquefied Petroleum Gas] Market
Petroleum Products
Pygas (Pyrolysis Gasoline) Market
Petroleum Products
Tar Oil Market
Petroleum Products
Very Low Sulphur Fuel Oil (VLSFO) Market
Petroleum Products
Hydrocarbon Market
Petroleum Products
Europe Ethane Market
Petroleum Products
Petroleum Benzine Market
Petroleum Products
Liquefied Petroleum Gas Market
Petroleum Products
Europe Refined Petroleum Products Market
Petroleum Products
Pyrolysis Gasoline Market