
 Gasoline Octane Improvers Market | 2026-2036
Gasoline Octane Improvers Market Size, Share, and Industry Trends Forecast 2026-2036
Gasoline Octane Improvers Market Analysis
Refinery buyers is rotating toward specialty chemical suppliers as automotive OEMs tighten fuel quality specifications for next-generation engines. BASF SE leverages its integrated petrochemicals platform to supply ether-based octane boosters across European refining networks. Innospec anchors its position through deep specialization in fuel additives, competing on formulation precision rather than commodity volume. Afton Chemical extends its reach via channel control over North American fuel distributor relationships, sustaining long-term offtake agreements with major blenders.
Gasoline octane improvers are oxygenated or aromatic compounds, typically ethers such as methyl tert-butyl ether (MTBE) or ethyl tert-butyl ether (ETBE), blended at 5-15% by volume to raise fuel octane ratings above 95 RON while suppressing engine knock. These additives function by slowing flame propagation during compression ignition, enabling higher compression ratios and improved thermal efficiency in spark-ignition engines. MTBE dominates mature markets where water solubility concerns have been managed through underground storage upgrades, while ETBE gains share in regions prioritizing renewable ethanol feedstocks. Application segments reveal that emission reduction formulations command premium positioning as regulators tighten particulate and NOx limits, whereas engine protection blends occupy stable replacement demand from legacy vehicle fleets.
EPA fuel standards under the Clean Air Act mandate minimum octane levels and restrict benzene content, compelling refiners to seek compliant high-octane blending components. REACH and the EU F-Gas Regulation constrain volatile organic compound emissions during fuel handling, shaping product formulation requirements for European suppliers. China's GB standards and MEE enforcement actions on fuel quality create parallel compliance obligations for additive producers serving Asian markets. Stakeholders must monitor regulatory divergence between jurisdictions to align R&D portfolios with divergent phase-out timelines for specific oxygenate chemistries.
Market Dynamics
Refinery procurement patterns are pivoting toward bio-based ether alternatives as China's MEE enforcement and EU F-Gas Regulation tighten constraints on conventional oxygenate formulations. This regulatory compression is forcing additive suppliers to reconfigure R&D pipelines around renewable feedstock compatibility.
Growth Catalysts
- Stringent emission mandates:China's GB standards and NMPA fuel quality specifications compel refiners to adopt cleaner octane boosters. Premium gasoline demand from high-performance vehicle manufacturers accelerates formulation upgrades.
- East Asian refining corridor expansion:Complex fuel blending operations around Shanghai and Singapore require advanced additive packages. These clusters concentrate purchasing power among integrated petrochemical buyers.
- Underground storage infrastructure modernization:Water solubility management for ether-based compounds enables sustained MTBE deployment in mature markets. Storage upgrades reduce environmental liability exposure for distributors.
Market Restraints
- Ethanol feedstock price volatility:ETBE production costs fluctuate with agricultural commodity markets. Bio-based raw material sourcing exposes margins to weather-driven supply shocks.
- Regulatory friction from divergent phase-out timelines:REACH restrictions on volatile organic compounds clash with US EPA Clean Air Act oxygenate allowances. Formulation harmonization across jurisdictions inflates compliance overhead.
- Water contamination remediation liability:MTBE's environmental persistence triggers cleanup obligations at legacy storage sites. Underground leakage detection mandates raise capital requirements for terminal operators.
Strategic Opportunities
- Renewable ethanol integration:ETBE's compatibility with agricultural ethanol feedstocks aligns with EU Green Deal biofuel targets. European refiners capture carbon intensity credits through renewable blending.
- Emission reduction formulation premiums:Particulate and NOx suppression additives command price premiums from OEMs facing fleet-average emission standards. Engine protection blends serve stable replacement demand from legacy fleets.
- Channel control via distributor relationships:Long-term offtake agreements with fuel blenders lock in volume commitments. North American fuel distributor networks offer captive market access.
Industry Challenges
- Formulation precision talent scarcity:Specialized fuel additive chemists command premium compensation. Knowledge transfer gaps between retiring specialists and digital-native engineers constrain R&D velocity.
- Dual certification timeline compression:Parallel REACH and EPA registration pathways require simultaneous toxicology and performance testing. Regulatory submission backlogs delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gasoline Octane Improvers Market |
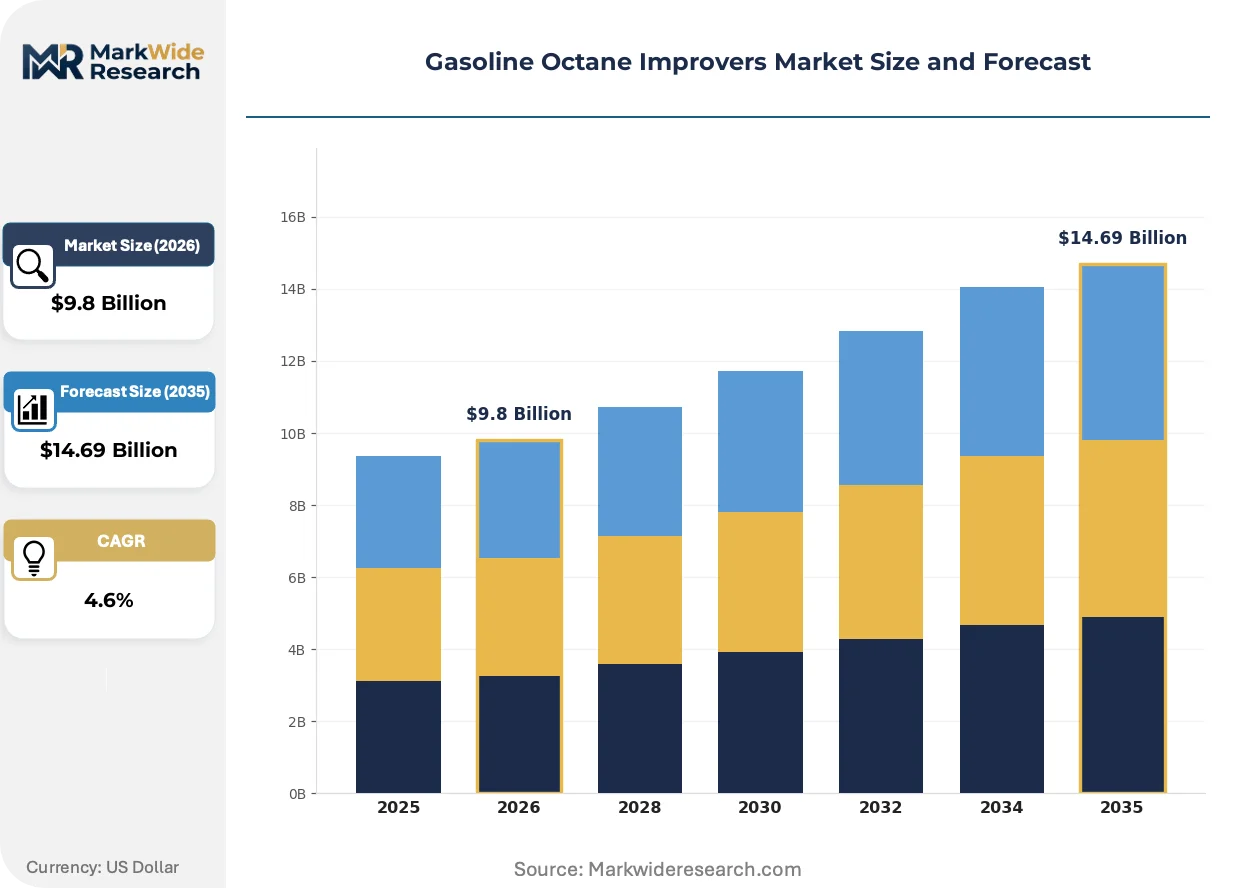
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MTBE, ETBE, TAME, Alcohols End User: Automobile Manufacturers, Aftermarket Providers, Fuel Distributors, Oil Refiners Application: Performance Improvement, Emission Reduction, Fuel Stabilization, Engine Protection Form: Liquid, Powder, Blend, Concentrate |
| Companies Covered | BASF SE, Innospec, Afton Chemical, LyondellBasell Industries Holdings B.V., The Lubrizol Corporation, Infineum International Ltd, Dorf Ketal, TotalEnergies, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gasoline Octane Improvers Market Emerging Trajectories
Bio-ether production pathways are disrupting conventional petrochemical supply structures as refiners seek carbon-neutral blending components. Three interconnected developments are compressing technology adoption cycles and reshaping competitive positioning.
ETBE manufacturing from renewable ethanol feedstocks is fragmenting the oxygenate supply base. European refiners under EU Green Deal pressure are retrofitting MTBE units for bio-ether output. This conversion trend is compressing margins for fossil-derived additive producers while opening procurement slots for agricultural processors.
China's MEE enforcement actions on fuel quality are tightening GB standard compliance windows. Refiners serving the domestic market must accelerate additive package upgrades or face distribution license suspensions. Shanghai-based blending terminals are prioritizing suppliers with dual REACH-GB certification to preempt regulatory friction.
Automotive OEMs are consolidating additive procurement through direct refinery partnerships, bypassing traditional distributor intermediaries. High-performance engine manufacturers now specify octane improver chemistries in supplier qualification documents. This disintermediation is most visible in German and Japanese premium vehicle supply chains where engine calibration precision demands additive traceability.
Gasoline Octane Improvers Market Segmentation
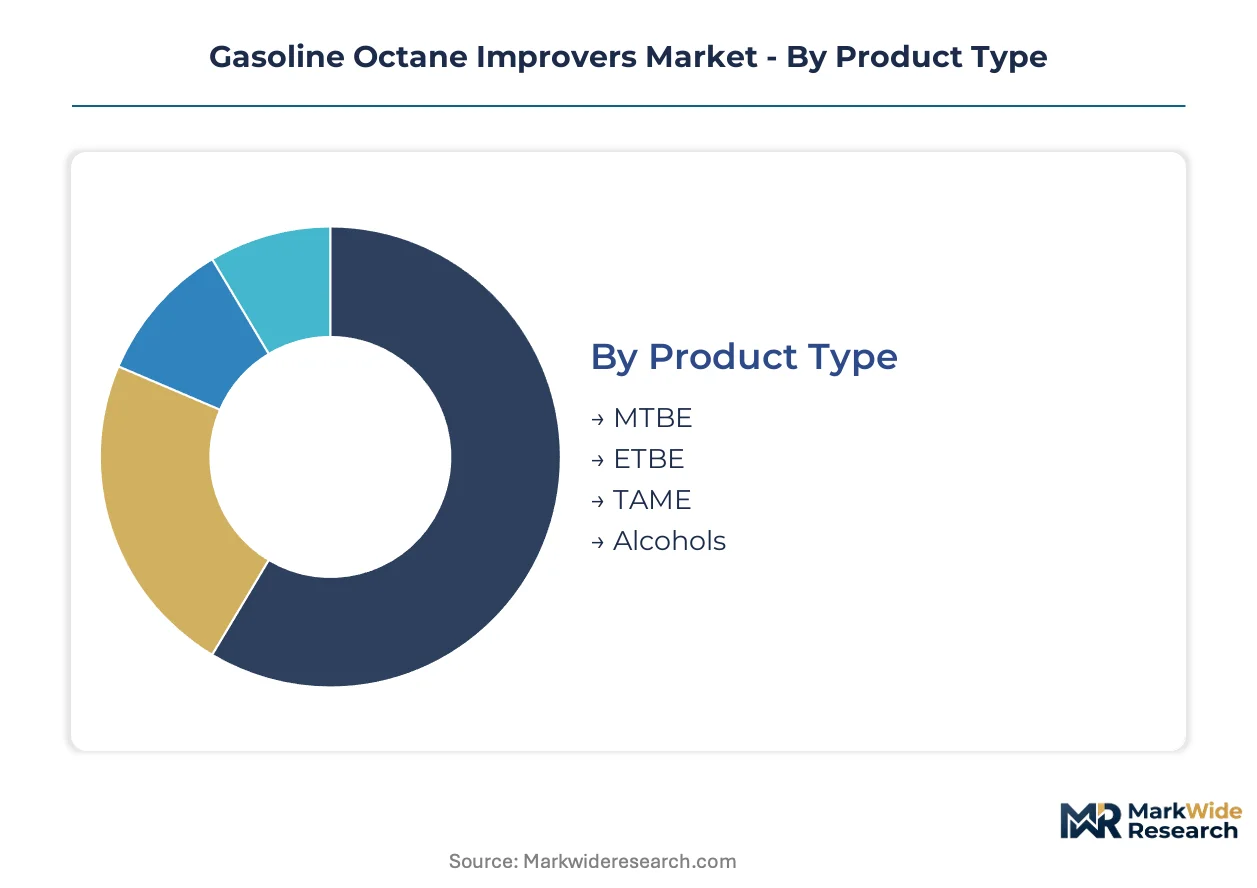
Octane improver margins concentrate in formulation precision rather than commodity volume, with regulatory compliance tiers and application-specific performance commanding price premiums. Refinery procurement patterns reveal divergent purchasing logic across product chemistries and end-user categories.
Product Type:
Margin pools sit heaviest in ether-based oxygenates where water solubility management and storage infrastructure create switching costs for buyers.
- MTBE:Methyl tert-butyl ether remains the dominant ether-based octane booster in markets with upgraded underground storage systems. Refiners in the US and China sustain offtake volumes despite environmental liability exposure, driven by established blending infrastructure and EPA oxygenate mandates.
- ETBE:Ethyl tert-butyl ether captures expanding share in EU refining corridors where renewable ethanol feedstocks align with EU Green Deal biofuel targets. European producers retrofit MTBE units for ETBE output to secure carbon intensity credits.
- TAME:Tert-amyl methyl ether serves niche gasoline blending applications requiring lower volatility profiles than MTBE.
- Alcohols:Methanol and ethanol-based improvers compete on feedstock cost in regions with agricultural surplus.
MTBE holds installed capacity across mature markets. ETBE is rotating up the share rankings in European and Asian biofuel corridors.
End User:
Procurement scale varies sharply across buyer categories, with integrated oil refiners consolidating volume and automotive OEMs extracting formulation traceability.
- Automobile Manufacturers:High-performance engine builders now specify octane improver chemistries in supplier qualification documents. German and Japanese premium vehicle supply chains demand additive traceability for engine calibration precision.
- Oil Refiners:Integrated petrochemical buyers concentrate purchasing power in East Asian refining corridors around Shanghai and Singapore. Complex fuel blending operations require advanced additive packages meeting GB standards and NMPA specifications.
- Fuel Distributors:Terminal operators face underground leakage detection mandates raising capital requirements for MTBE handling.
- Aftermarket Providers:Smaller blenders serve legacy fleet replacement demand with engine protection formulations.
Oil refiners anchor volume procurement. Automobile manufacturers are climbing fastest in influence over specification standards.
Application:
Performance tiering separates emission-compliant formulations from commodity engine protection blends.
- Emission Reduction:Particulate and NOx suppression additives command price premiums from OEMs facing fleet-average emission standards. China's MEE enforcement tightens compliance windows for domestic refiners.
- Performance Improvement:High-octane blending components enable compression ratio increases in spark-ignition engines. Premium gasoline demand from performance vehicle manufacturers accelerates formulation upgrades.
- Engine Protection:Stable replacement demand persists from legacy vehicle fleets requiring knock suppression.
- Fuel Stabilization:Storage-life extension additives serve seasonal demand fluctuations in distributor networks.
Engine protection holds steady replacement volume. Emission reduction is expanding most quickly under regulatory compression.
Form:
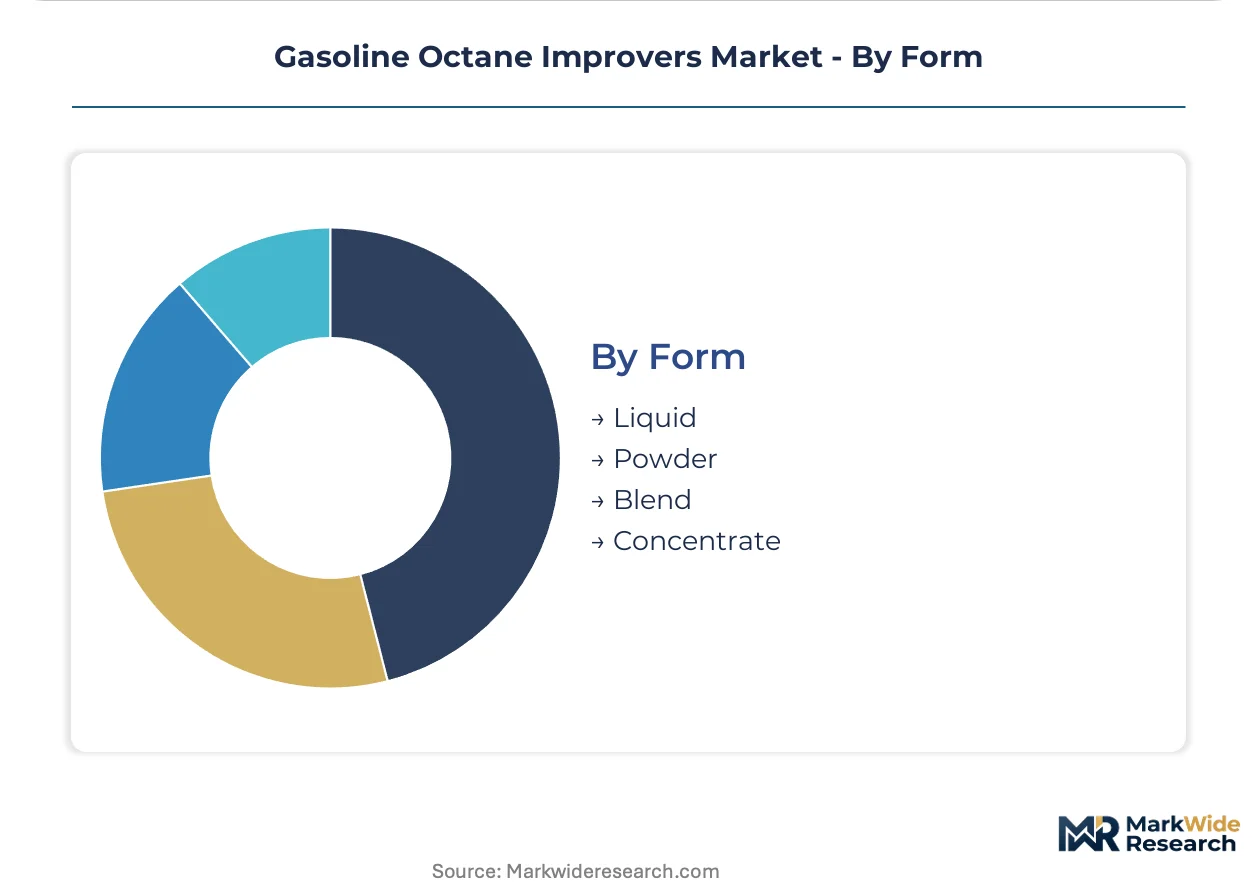
Supply chain configuration favors liquid handling infrastructure, with concentrate formats capturing logistics efficiency premiums.
- Liquid:Dominant delivery format compatible with existing refinery blending systems and pipeline transport. Terminal operators in Singapore and Rotterdam maintain bulk liquid handling capacity.
- Concentrate:Reduced volume shipping lowers freight costs for remote blending locations. Distributors in North American fuel networks leverage concentrate formats for last-mile efficiency.
- Blend:Pre-formulated additive packages simplify procurement for smaller refiners lacking in-house formulation expertise.
- Powder:Niche solid-form applications serve specialized industrial fuel requirements.
Liquid maintains infrastructure lock-in. Concentrate is gaining share fastest in logistics-optimized supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated oil refiners concentrate procurement power in coastal petrochemical corridors where complex blending operations demand advanced additive packages. Regulatory enforcement in major consuming markets is compressing compliance windows and reshaping supplier qualification requirements. East Asian refining clusters, European biofuel corridors, and North American distribution networks anchor regional demand patterns.
China
Shanghai-based blending terminals prioritize suppliers with dual REACH-GB certification to preempt regulatory friction from MEE enforcement actions. The country's GB standards and NMPA fuel quality specifications compel domestic refiners to accelerate additive package upgrades. Yangtze River Delta refiners face distribution license suspension risks without compliant octane booster formulations.
United States
EPA Clean Air Act oxygenate mandates sustain MTBE offtake volumes despite environmental liability exposure at legacy storage sites. Underground storage infrastructure modernization reduces water contamination risks for terminal operators in Gulf Coast refining corridors. Houston and Los Angeles basin blenders maintain established ether-based blending infrastructure.
Germany
EU F-Gas Regulation and REACH restrictions on volatile organic compounds shape formulation requirements for European additive suppliers. Bavaria and North Rhine-Westphalia refiners retrofit MTBE units for ETBE output to capture carbon intensity credits under EU Green Deal biofuel targets. German automotive OEMs now specify octane improver chemistries in supplier qualification documents.
Singapore
Complex fuel blending operations in the Strait of Malacca corridor require advanced additive packages meeting multiple jurisdictional standards. Terminal operators maintain bulk liquid handling capacity for ether-based oxygenates serving regional export markets. The city-state's refining hub connects Middle Eastern feedstock suppliers with East Asian gasoline demand centers.
Saudi Arabia
SABIC's integrated petrochemicals platform supplies ether-based octane boosters across Middle Eastern and Asian refining networks. Eastern Province refining complexes expand capacity to serve premium gasoline demand from high-performance vehicle manufacturers. The kingdom's fuel quality specifications align with tightening international emission mandates.
Gasoline Octane Improvers Market Vendor Landscape
Player mix skews toward integrated petrochemical conglomerates and specialized fuel additive formulators with deep regulatory certification expertise. Market structure exhibits moderate consolidation around suppliers with dual EPA-REACH registration capabilities and established refinery relationships. Three archetypes dominate: diversified chemical majors with backward integration into oxygenate feedstocks, pure-play additive specialists competing on formulation precision, and national oil company affiliates leveraging captive offtake. Competitive moves concentrate on bio-ether capacity conversions and channel control through long-term blender agreements.
Among diversified chemical majors, BASF SE and LyondellBasell Industries Holdings B.V. exemplify the integrated archetype with petrochemicals platforms spanning ether production. Specialized formulators occupy distinct positioning tiers: Innospec and Afton Chemical represent the precision-focused segment where deep additive expertise substitutes for commodity scale. These named entities anchor competitive dynamics without exhausting the supplier base, as regional specialists and national oil company affiliates maintain meaningful participation in corridor-specific procurement.
| Leading Market Players |
|---|
| BASF SE |
| Innospec |
| Afton Chemical |
| LyondellBasell Industries Holdings B.V. |
| The Lubrizol Corporation |
| Infineum International Ltd |
| Dorf Ketal |
| TotalEnergies |
| SABIC |
| Others |
Supply Flow & Price Mechanics
REACH and EPA dual certification regimes gate both supply qualification and price differentiation simultaneously, separating premium formulation suppliers from commodity oxygenate traders. Refinery procurement teams extract volume discounts from certified suppliers while paying premiums for dual-registered specialty packages. This regulatory layering compresses margins for uncertified producers and elevates pricing power for incumbents with established compliance infrastructure.
Pricing Analysis
Cost-plus contracts indexed to ethanol feedstock futures and methanol spot markets dominate long-term offtake agreements between refiners and additive suppliers. Price differentiation hinges on certification grade—dual REACH-EPA registration commands 15-20% premiums over single-jurisdiction compliance—and volume scale from integrated petrochemical buyers. Pricing pressure stems from bio-ether capacity expansions in European corridors as ETBE retrofit investments compress fossil-derived MTBE margins. Small fuel distributors exhibit highest price sensitivity due to limited storage infrastructure and fragmented procurement volumes, while automotive OEMs prioritize formulation traceability over unit cost.
Supply Chain Analysis
Germany and the United States anchor ether-based octane booster production, with China expanding specialty formulation capacity to serve domestic GB standard compliance. Feedstock dependencies draw from agricultural ethanol processors in Brazil and the EU, plus methanol streams from Middle Eastern petrochemical complexes. Single-source vulnerability concentrates in bio-ethanol supply corridors exposed to weather-driven crop failures. Distribution runs through coastal blending terminals at Rotterdam, Singapore, and Houston, where bulk liquid handling infrastructure locks in incumbent supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gasoline octane improvers occupy an early-cycle expansion phase as bio-ether adoption accelerates under EU Green Deal enforcement and China's MEE tightening. Regulatory compression on conventional oxygenates creates penetration tailwinds for renewable-compatible formulation suppliers.
For Market Incumbents: Fortify dual certification portfolios by accelerating REACH-GB registration timelines ahead of China's NMPA enforcement windows. Backward integration into renewable ethanol feedstock sourcing defends margin position against agricultural commodity volatility. Channel control through long-term offtake agreements with Singapore and Rotterdam terminal operators locks in volume commitments against emerging bio-ether specialists. For New Entrants and Emerging Players: Dual REACH-GB certification fast-tracks entry into Shanghai-based blending terminals facing MEE compliance deadlines. White-space concentrates in ETBE production for European refiners retrofitting MTBE units under EU F-Gas Regulation pressure. Agricultural processors with existing ethanol infrastructure possess the most penetrable positioning for bio-ether supply partnerships. Go-to-market leverage rests on carbon intensity credit aggregation for refinery buyers seeking EU Green Deal compliance. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across bio-ether retrofit projects as standardized conversion kits reduce engineering overhead. Long-term viability favors suppliers with integrated petrochemical platforms and established refinery relationships over pure-play formulation specialists. Acquisition targets include regional additive distributors with captive terminal access in East Asian corridors. The signal to watch is MEE enforcement action frequency as a demand inflection indicator for compliant additive packages.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Feedstocks | ETBE producers secure ethanol supply chains against agricultural price volatility from Brazilian and EU processors. |
| Dual Certification Investment | REACH-GB registration opens procurement slots at Shanghai terminals facing NMPA compliance deadlines. |
| Long-term Supply Agreement | Ofgtake contracts with Rotterdam and Singapore terminal operators lock in volume against bio-ether entrants. |
| Capacity Retrofit for Bio-ether Output | European refiners capture EU Green Deal carbon intensity credits through ETBE manufacturing conversions. |
| Channel Control via Distributor Relationships | North American fuel network partnerships provide captive market access for emission reduction formulations. |
Methodological Framework
A spread of perspectives from refinery procurement managers, fuel additive R&D directors, terminal operators, and regulatory compliance officers converged on the working assumptions. Primary fieldwork combined structured interviews with downstream blenders and upstream chemical producers. Secondary validation drew from EPA fuel standard filings, ECHA REACH registration databases, China MEE enforcement bulletins, and EU F-Gas Regulation implementation reports. Customs trade data and SEC 10-K petrochemical segment disclosures provided volume triangulation. Bottom-up additive demand estimates from individual refinery configurations were cross-checked against top-down gasoline consumption projections.
Segmentation dimensions modeled include oxygenate chemistry type, renewable feedstock integration level, application performance tier, and regional regulatory cluster. CAGRs were derived from regression analysis of historical refinery additive procurement patterns and forward projections of emission mandate stringency across the analysis window. Industry-specific forecast inputs incorporated ETBE retrofit capacity timelines and MEE enforcement action probabilities.
Underlying assumptions cover sustained EPA oxygenate mandates, EU Green Deal biofuel target adherence, and China GB standard enforcement continuity, with deviation risk concentrated in regulatory phase-out timeline acceleration for MTBE. Forecasts reflect these documented assumptions. Recalibration cycles align with material shifts in MEE enforcement intensity, EU F-Gas Regulation amendment schedules, and bio-ethanol feedstock price volatility spikes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Europe Wood Pellet Market
Fuels
Global Fuel Ethanol Market
Fuels
Europe Bunker Fuel Market
Fuels
Pyrolysis Gas Market
Fuels
Canada Bunker Fuel Market
Fuels
Global Gas Cylinder Market
Fuels
China Coal Market
Fuels
Heavy Fuel Oil Market
Fuels
Middle-East and Africa Commercial Aircraft Aviation Fuel Market
Fuels
Methane Market
Fuels
Europe Coal Market
Fuels
India LNG Market
Fuels
Defense Aircraft Aviation Fuel Market
Fuels
No.4 Fuel Oil Market
Fuels
India Coal Market
Fuels
United States Bunker Fuel Market