
 Asphaltene Inhibitors Market | 2026-2036
Asphaltene Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Asphaltene Inhibitors Market Outlook
Performance-based chemical management contracting is expanding as the dominant commercial model in the asphaltene inhibitors space. Baker Hughes leverages its integrated upstream chemicals division to bundle inhibitor supply with real-time well monitoring services. Schlumberger Limited anchors its position through proprietary asphaltene risk modeling software that predicts precipitation thresholds before field deployment. Halliburton Company competes by controlling regional blending facilities near the Permian Basin and Eagle Ford shale corridors.
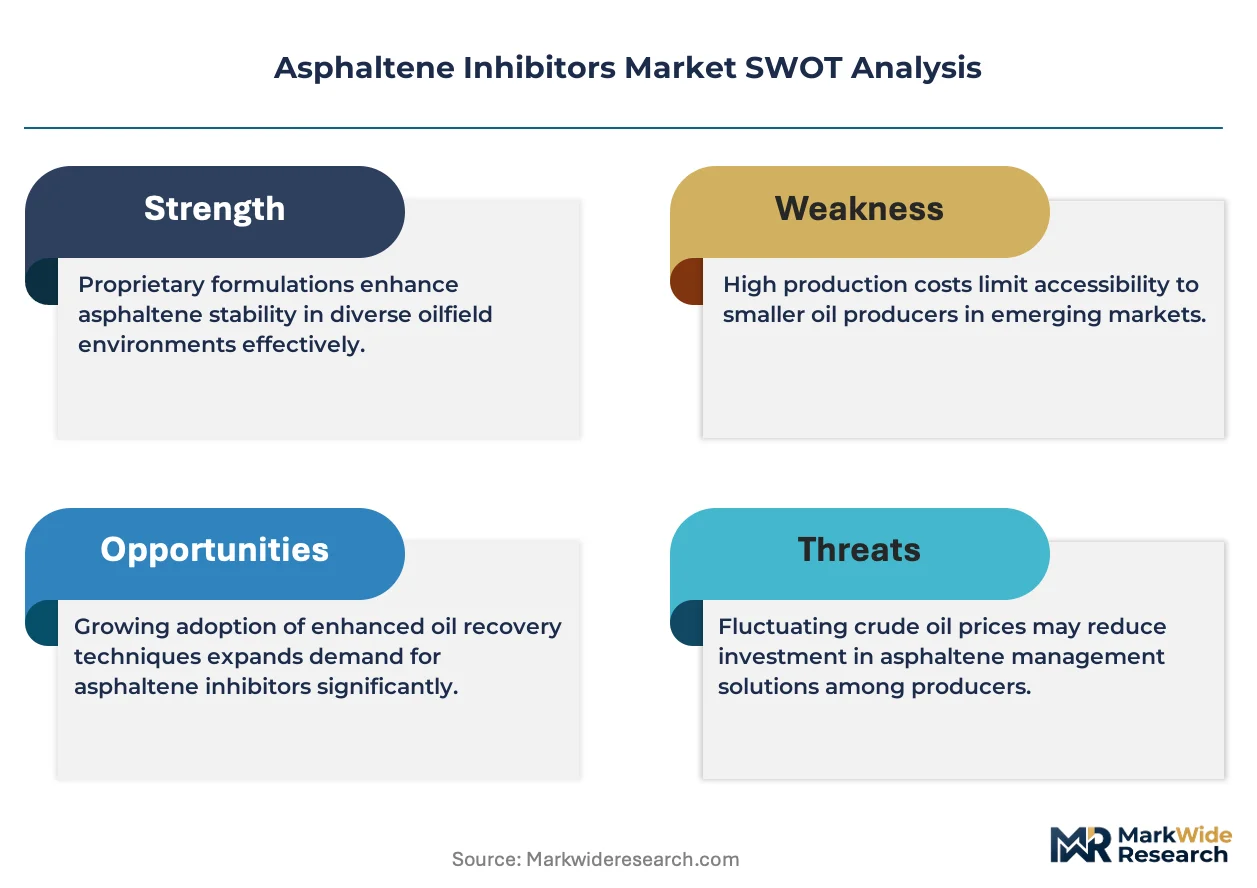
Asphaltene inhibitors are surface-active chemical formulations—typically polymeric dispersants, aromatic solvents, or amphiphilic surfactants—that adsorb onto asphaltene nanoaggregates to prevent flocculation and deposition in crude oil production systems. These chemistries function at concentrations between 50 and 500 ppm, maintaining fluid flow integrity through pipelines, wellbores, and surface processing equipment. Polymeric inhibitors dominate current procurement volumes due to their thermal stability above 150°C in deep reservoir conditions. Surfactant-based formulations represent the fastest-growing chemistry class, gaining share in offshore applications where low-dose efficiency reduces logistics costs. Heavy oil applications command the deepest margin pools, as high-asphaltene crudes require continuous inhibitor injection rather than intermittent batch treatment.
EPA regulates offshore chemical discharge under the National Pollutant Discharge Elimination System, forcing operators to document environmental fate profiles for all subsea-injected chemistries. REACH registration requirements in Europe restrict certain aromatic solvent carriers, redirecting formulation R&D toward bio-derived dispersant backbones. OSHA Process Safety Management standards govern onshore bulk chemical handling at US blending terminals, shaping facility siting and operator training protocols. Stakeholders must monitor regulatory divergence between jurisdictions while building formulation flexibility into their supply chains.
Market Dynamics
Deepwater production economics are forcing a structural recalibration of chemical deployment strategies, as operators trade bulk commodity formulations for precision-dosed, thermally stable chemistries that withstand bottom-hole temperatures exceeding 180°C. This thermal threshold pressure is compressing the supplier base toward polymer synthesis capabilities with proven subsea track records.
Growth Catalysts
- REACH chemical registration:The European Union's phased restrictions on aromatic solvent carriers are redirecting formulation R&D toward bio-derived polymeric backbones, opening procurement lanes for suppliers with renewable feedstock capabilities.
- Deepwater Gulf of Mexico:Ultra-high-pressure reservoirs at depths below 1,500 meters require continuous inhibitor injection systems, generating sustained demand for thermally stable dispersant chemistries.
- Real-time monitoring integration:Downhole sensor networks now enable predictive asphaltene risk modeling, allowing operators to optimize inhibitor dosing rates and reduce chemical over-injection by 20-40%.
Market Restraints
- Ethylene oxide supply concentration:Polymeric inhibitor synthesis depends on ethylene oxide feedstocks concentrated among Gulf Coast petrochemical complexes, exposing formulators to price volatility and force majeure risks.
- EPA NPDES discharge documentation:Offshore operators must submit environmental fate profiles for every subsea-injected chemistry, extending qualification timelines by 12-18 months and raising compliance costs.
- Demulsifier substitution:Some heavy oil operators are redirecting capital toward combined demulsifier-inhibitor packages that sacrifice asphaltene control performance for operational simplicity.
Strategic Opportunities
- Brazil pre-salt basins:Petrobras-operated fields in the Santos Basin present untapped demand for high-pressure, high-temperature inhibitor formulations as production ramps toward 2 million barrels daily.
- Carbon intensity scoring:The EU Green Deal's embodied carbon regulations are creating first-mover advantage for suppliers with verified low-carbon supply chains and renewable feedstock certifications.
- Modular offshore platforms:Standardized subsea production systems are enabling pre-qualified chemical skids, reducing field-specific engineering and accelerating deployment cycles.
Industry Challenges
- Computational chemistry expertise:The shift toward molecular simulation for inhibitor design has created acute shortages of reservoir chemists with combined petroleum engineering and computational modeling skills.
- Subsea umbilical integration:Inhibitor delivery systems must interface with existing hydraulic control lines, requiring extensive compatibility testing that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asphaltene Inhibitors Market |
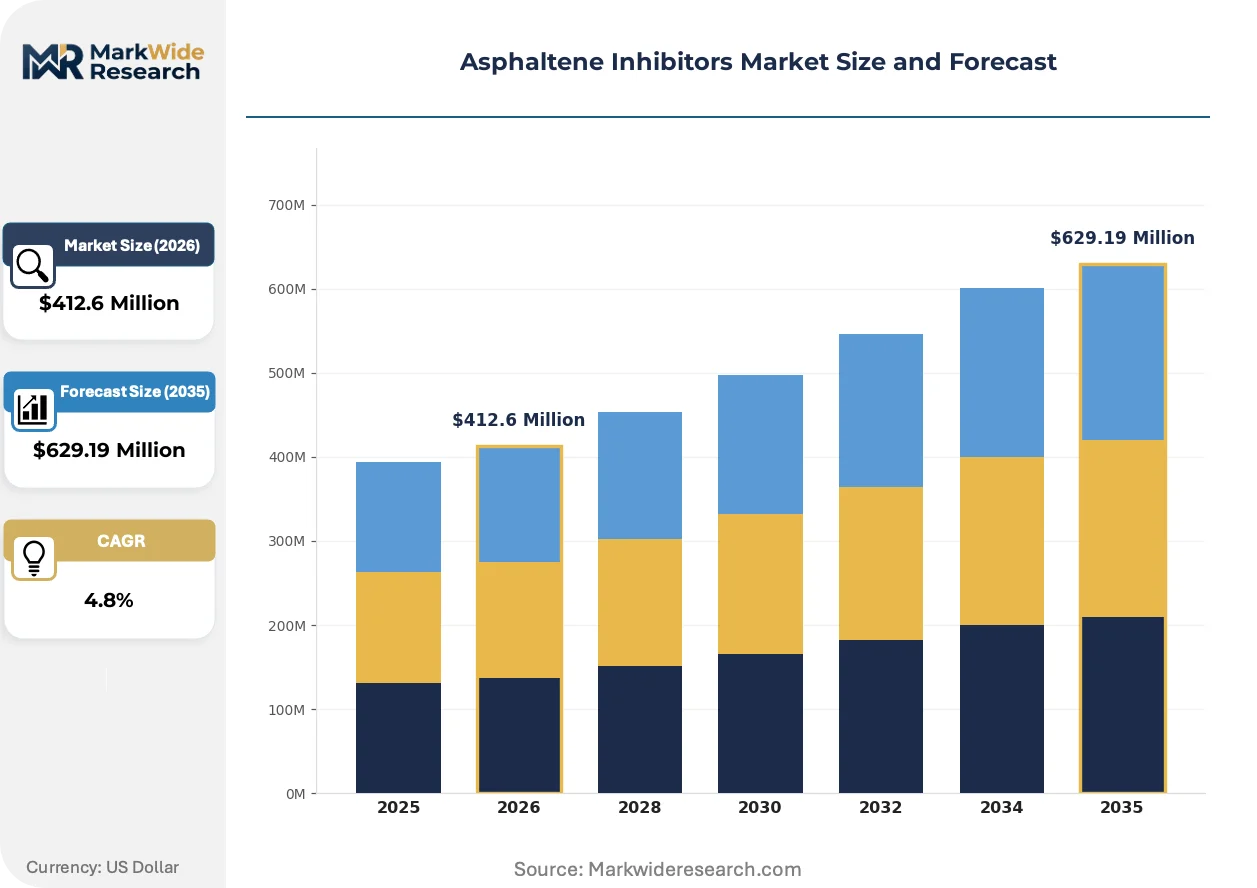
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $629.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymeric Inhibitors, Organic Solvents, Surfactants, Water-soluble Inhibitors Application: Oil Sands, Crude Oil, Heavy Oil, Refinery Processes End User: Oil & Gas Companies, Refineries, Research Institutions, Independent Operators Delivery Mode: Batch Processing, Continuous Processing, Onsite Treatment, Remote Monitoring |
| Companies Covered | Baker Hughes, Schlumberger Limited, Halliburton Company, Clariant AG, BASF SE, Akzo Nobel N.V., Croda International Plc, Innospec Inc., Dorf Ketal Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asphaltene Inhibitors Market Strategic Shifts
Formulation science is pivoting from empirical field testing toward predictive molecular design, compressing development cycles while raising performance benchmarks for thermal stability and environmental persistence. This methodological shift is redrawing competitive boundaries between integrated service companies and specialized chemical suppliers.
Amphiphilic surfactant architectures are converging with machine learning-driven molecular screening platforms to identify novel dispersant structures with superior adsorption kinetics on asphaltene nanoaggregates. Major integrated operators in the US Gulf Coast are piloting these next-generation formulations at 50-100 ppm dose rates, half the concentration required by conventional polymeric inhibitors. The convergence is compressing the addressable market for legacy aromatic solvent carriers while elevating technical barriers to entry.
EPA's revised National Pollutant Discharge Elimination System permit requirements now mandate bioaccumulation testing for all subsea chemicals, forcing reformulation away from certain alkyl phenol ethoxylate surfactants. The industrial consequence is a supplier scramble to qualify alternative hydrophilic-lipophilic balance modifiers before permit renewal deadlines. Deepwater projects in federal waters are most affected, with operators pre-qualifying multiple chemical suppliers to mitigate approval timeline risks.
Performance-based contracting is displacing traditional volume-of-product procurement across North American heavy oil operations. Operators in the Permian and Eagle Ford corridors now pay per barrel of asphaltene-free throughput rather than per gallon of inhibitor delivered, transferring precipitation risk to chemical suppliers. This shift is most visible among private equity-backed producers seeking to cap operating expenditure volatility while maintaining production targets.
Asphaltene Inhibitors Market Segmentation
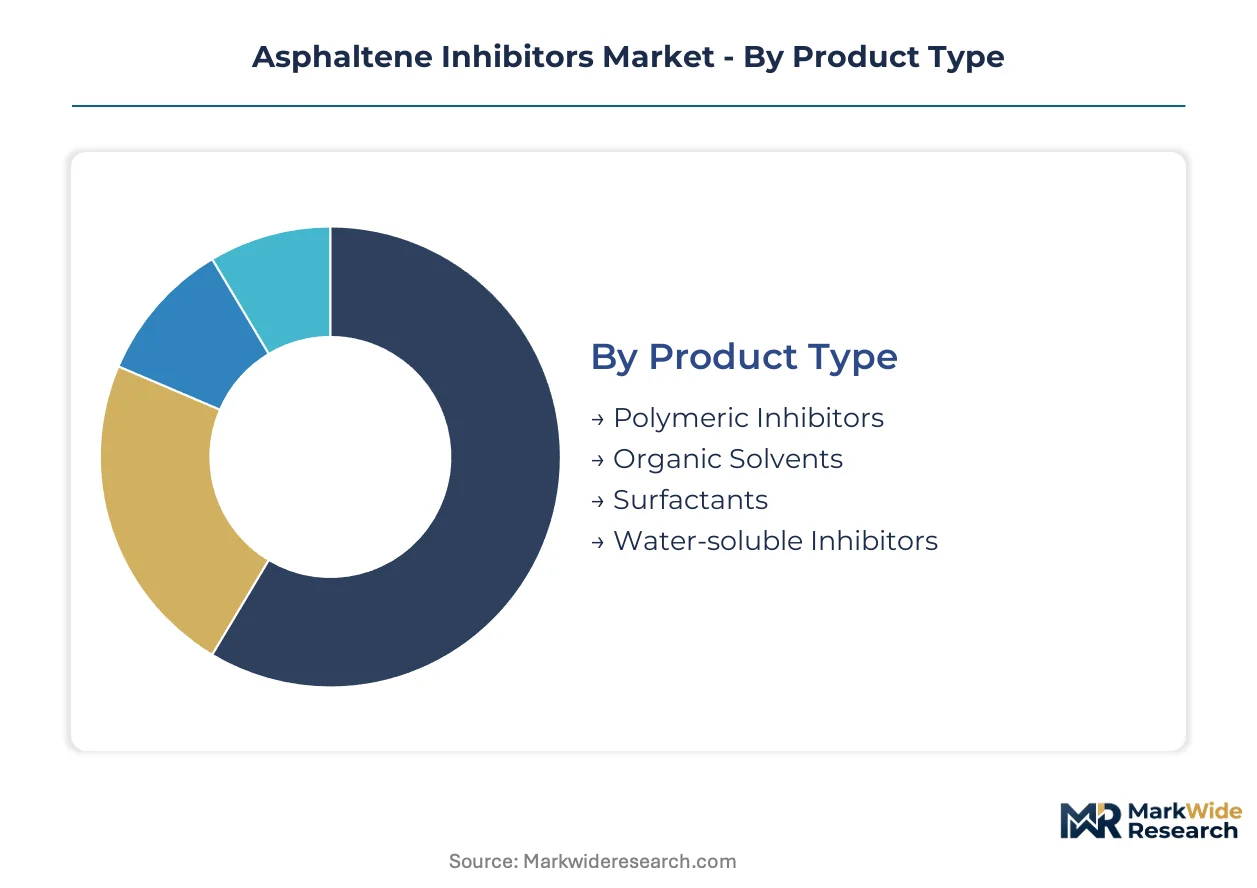
Segmentation in the asphaltene inhibitors market reflects divergent technical requirements across reservoir conditions and operational models. Chemical suppliers must align formulation portfolios with distinct deployment environments rather than pursuing universal product strategies.
Product Type:
Product selection hinges on thermal stability thresholds and environmental compliance profiles, with some chemistries functioning as standalone treatments while others require carrier fluid systems.
- Polymeric Inhibitors:Long-chain dispersant molecules engineered with alkyl-aromatic backbones deliver thermal stability above 150°C in deep reservoir conditions. US Gulf Coast operators prioritize these formulations for continuous injection programs in high-pressure sandstone reservoirs where thermal degradation risks exclude conventional alternatives.
- Surfactants:Amphiphilic molecular architectures adsorb onto asphaltene nanoaggregates through hydrophobic-hydrophilic balance optimization. Offshore Brazil pre-salt developments favor these chemistries at 50-100 ppm dose rates, cutting logistics costs versus polymeric alternatives while meeting ANVISA environmental discharge protocols.
- Organic Solvents:Aromatic hydrocarbon carriers dissolve precipitated asphaltene deposits through physical solvation mechanisms.
- Water-soluble Inhibitors:Polymeric dispersants modified with sulfonate or carboxylate functional groups enable aqueous-phase delivery in waterflooding operations.
Polymeric inhibitors lead volumes today; surfactants are gaining share fastest.
Application:
Application segmentation tracks crude oil density gradients and processing complexity, with heavier feedstocks demanding more intensive chemical intervention.
- Heavy Oil:Viscous crudes with API gravity below 22 degrees contain elevated asphaltene fractions that precipitate during pressure-drawdown operations. Canadian oil sands producers and Venezuelan Orinoco belt operators deploy continuous inhibitor injection rather than intermittent batch treatments, generating the deepest margin pools for chemical suppliers.
- Crude Oil:Conventional production systems face asphaltene deposition risks during primary recovery and secondary waterflooding phases.
- Oil Sands:Bitumen extraction through steam-assisted gravity drainage creates unique asphaltene stabilization challenges in high-temperature processing streams.
- Refinery Processes:Vacuum residue upgrading and coker feed pre-treatment operations require asphaltene control to prevent heat exchanger fouling.
Heavy oil applications command premium pricing; crude oil treatment represents the broadest volume base.
End User:
End user categories reflect divergent procurement capabilities, with integrated operators pursuing performance-based contracts while smaller entities favor transactional supply arrangements.
- Oil & Gas Companies:Integrated majors and national oil companies operate dedicated flow assurance teams that specify inhibitor chemistries based on reservoir simulation outputs. These entities dominate Gulf of Mexico and North Sea procurement volumes through multi-year chemical management contracts bundling supply with real-time monitoring services.
- Refineries:Downstream processing facilities prioritize asphaltene control in resid upgrading units to maintain thermal efficiency and reduce unplanned shutdowns.
- Independent Operators:Private equity-backed producers in Permian Basin unconventional plays favor spot purchasing with rapid logistics response.
- Research Institutions:University and national laboratory partnerships drive pre-competitive formulation development for next-generation chemistries.
Oil and gas companies anchor procurement volumes; independent operators are expanding their share through unconventional production growth.
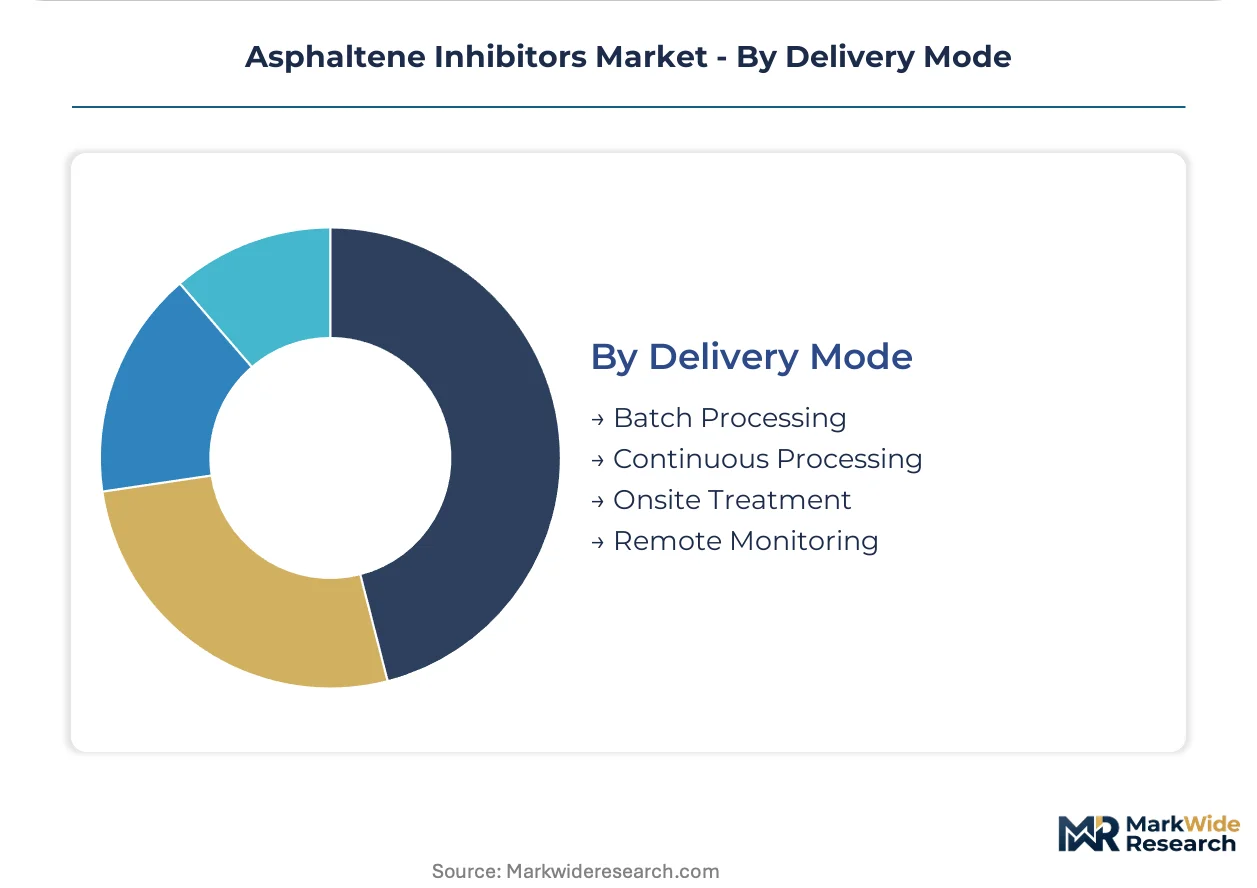
Delivery Mode:
Delivery segmentation separates capital-intensive infrastructure investments from flexible operational approaches, with offshore developments locking in continuous systems while onshore operations retain batch optionality.
- Continuous Processing:Dedicated injection skids meter inhibitor into wellhead flowlines at rates calibrated to real-time asphaltene risk models. Subsea tieback developments in US federal waters mandate these systems, with chemical umbilicals integrated into hydraulic control infrastructure during platform commissioning.
- Batch Processing:Periodic inhibitor slug treatments address deposition events in mature onshore fields with intermittent production upsets.
- Onsite Treatment:Mobile blending and injection units service remote well pads without permanent chemical infrastructure.
- Remote Monitoring:Satellite-linked sensor networks enable centralized dosing optimization across dispersed well portfolios.
Continuous processing dominates offshore investment; remote monitoring is climbing the fastest as digital infrastructure penetrates onshore operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deepwater production economics diverge sharply between mature basins and frontier developments, with the United States sustaining chemical consumption through aging infrastructure while Brazil scales inhibitor demand through pre-salt expansion.
United States
Federal waters in the Gulf of Mexico host over 1,900 producing platforms requiring continuous flow assurance. EPA NPDES permit renewals now mandate bioaccumulation testing for all subsea chemistries, extending qualification timelines. Houston and New Orleans anchor the chemical supply corridor, with blending terminals concentrated along the Ship Channel and Mississippi River.
Brazil
Petrobras-operated pre-salt fields in the Santos Basin drive demand for thermally stable formulations exceeding 180°C tolerance. ANVISA environmental discharge protocols restrict certain aromatic carriers, redirecting procurement toward bio-derived alternatives. Rio de Janeiro clusters service company headquarters, while Macaé serves as the operational hub for offshore logistics.
Norway
North Sea mature field redevelopment prioritizes precision-dosed inhibitor systems to maximize recovery from aging reservoirs. REACH registration requirements govern all chemical imports, with ECHA restrictions on solvent carriers shaping formulation portfolios. Stavanger and Bergen concentrate operator procurement teams and subsea engineering capabilities.
Saudi Arabia
Offshore fields in the Arabian Gulf require high-volume inhibitor programs for heavy crude production systems. The national petroleum regulator mandates environmental fate documentation for all injected chemistries under offshore discharge protocols. Dhahran and Jubail host integrated chemical manufacturing and blending infrastructure serving domestic and regional demand.
United Kingdom
Decommissioning delays and late-life field extensions sustain chemical consumption in the UK North Sea. HSE offshore chemical regulations align with REACH frameworks, creating compliance continuity with European suppliers. Aberdeen maintains its position as the primary logistics and technical services hub for subsea chemical deployment.
Asphaltene Inhibitors Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated oilfield service companies commanding premium positions in performance-based contracting while independent chemical formulators compete on spot supply flexibility. Market structure tilts toward consolidation among the top tier, where bundled service offerings create switching costs for operators. Three archetypes dominate: integrated energy service conglomerates with proprietary modeling software, specialized chemical manufacturers with regional blending networks, and technology licensors supplying molecular designs to third-party formulators. Competitive dynamics center on vertical integration into ethylene oxide feedstocks and strategic partnerships with subsea equipment OEMs for umbilical integration.
Within the integrated service tier, Baker Hughes and Schlumberger Limited exemplify the convergence of chemical supply with digital monitoring capabilities. Halliburton Company anchors the regional infrastructure archetype through Permian Basin proximity. Clariant AG and BASF SE represent the specialized chemical manufacturing segment with formulation flexibility across regulatory jurisdictions. Akzo Nobel N.V. and Croda International Plc occupy positions emphasizing bio-derived and surfactant-based chemistries aligned with tightening environmental standards. Innospec Inc. and Dorf Ketal Chemicals illustrate mid-tier competitors competing on dose efficiency and rapid logistics response.
| Leading Market Players |
|---|
| Baker Hughes |
| Schlumberger Limited |
| Halliburton Company |
| Clariant AG |
| BASF SE |
| Akzo Nobel N.V. |
| Croda International Plc |
| Innospec Inc. |
| Dorf Ketal Chemicals |
| Others |
Value Chain & Pricing Dynamics
Machine learning-driven molecular screening platforms are compressing development cycles for surfactant-based formulations while simultaneously concentrating production among suppliers with captive ethylene oxide synthesis capabilities. This technological shift rewards integrated operators with backward control over petrochemical feedstocks while squeezing margins for formulators dependent on spot market aromatics.
Pricing Analysis
Capacity additions in the US Gulf Coast are reshaping price floors for polymeric inhibitor grades as ethylene oxide supply expands from Corpus Christi and Baytown complexes. Three-tier pricing structure across premium thermally-stable, standard polymeric, and economy solvent-carrier levels separates field-proven subsea formulations from untested alternatives. Price differentiation rests on REACH registration status and EPA NPDES discharge approval documentation. Cost compression in standard polymeric tiers is intensifying because Brazilian and Norwegian operators are consolidating procurement volumes under performance-based contracts. Independent Permian Basin operators exhibit highest price sensitivity; integrated Gulf of Mexico majors prioritize technical qualification over unit cost.
Supply Chain Analysis
Specialized reservoir chemists with computational modeling skills remain scarce in Houston, Stavanger, and Rio de Janeiro, constraining formulation R&D throughput and extending project timelines for molecular design services. Geographic supply concentration centers on the United States, Germany, and Brazil, with ethylene oxide feedstocks anchored in Gulf Coast petrochemical corridors and specialized surfactant production clustered in European chemical manufacturing belts. Raw material dependencies draw from aromatic hydrocarbon carriers, bio-derived dispersant backbones, and alkyl phenol ethoxylate surfactants facing regulatory phase-out. Single-source vulnerability runs through ethylene oxide supply concentrated among integrated petrochemical complexes. Distribution runs through regional blending terminals co-located with offshore logistics hubs in New Orleans, Macaé, and Aberdeen.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The asphaltene inhibitors market functions as a regulatory compounder where EPA NPDES bioaccumulation testing mandates and REACH aromatic solvent restrictions are accelerating procurement consolidation among pre-qualified suppliers with environmental fate documentation.
For Market Incumbents: Anticipate margin compression from combined demulsifier-inhibitor packages by deepening proprietary asphaltene risk modeling software capabilities and securing captive ethylene oxide supply through Gulf Coast petrochemical partnerships. Defend position by pre-qualifying alternative hydrophilic-lipophilic balance modifiers ahead of permit renewal deadlines. Certification investment in ANVISA-compliant bio-derived backbones represents the critical lever for Brazilian pre-salt expansion. For New Entrants and Emerging Players: Regional blending facilities near the Permian Basin offer the most penetrable entry point, as private equity-backed producers prioritize rapid logistics response over bundled service contracts. Target spot purchasing relationships with independent operators seeking dose efficiency improvements over integrated service offerings. A go-to-market angle anchored in machine learning-driven molecular screening for 50-100 ppm surfactant formulations bypasses incumbent polymeric patent thickets. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier chemical formulators with regional blending networks but lacking proprietary modeling software or subsea umbilical integration partnerships. Long-term viability favors suppliers with verified low-carbon supply chains as EU Green Deal embodied carbon regulations mature. The signal to watch is Petrobras pre-salt production ramp announcements above 2 million barrels daily, which would trigger step-change demand for thermally stable formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Captive feedstock supply insulates formulators from Gulf Coast price volatility and force majeure risks. |
| REACH-Compliant Bio-Derived Formulation | European aromatic solvent restrictions redirect R&D toward renewable dispersant backbones with procurement preference. |
| Subsea Umbilical Integration Partnership | Chemical delivery compatibility with existing hydraulic control lines accelerates deepwater project deployment cycles. |
| Performance-Based Contracting Platform | Real-time monitoring integration transfers precipitation risk from operators to suppliers while locking in multi-year revenue. |
| Machine Learning Molecular Screening | Predictive design platforms compress development timelines for next-generation amphiphilic surfactant architectures. |
Study Parameters
Multiple input streams — structured interviews with flow assurance engineers and procurement leads at integrated operators, technical discussions with reservoir chemists at service company R&D centers, and validation sessions with subsea equipment OEMs — were reconciled against customs data tracking ethylene oxide derivative trade flows, EPA NPDES permit filings, and SEC 10-K disclosures from listed chemical suppliers. Bottom-up field deployment estimates and top-down petrochemical feedstock consumption patterns were triangulated to anchor volume assumptions.
Data-stream reconciliation applied across the projection horizon modeled segmentation dimensions spanning product chemistry class, application severity tier, end-user procurement capability, and delivery mode infrastructure intensity. CAGRs were derived from elasticity-adjusted deployment curves calibrated to deepwater project sanctioning announcements and regulatory compliance timeline shifts. Industry-specific forecast inputs incorporated thermal stability threshold requirements for pre-salt reservoir conditions and environmental discharge protocol adoption trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ethylene oxide supply disruptions, REACH substance restriction expansions, and demulsifier-inhibitor package substitution rates. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Southeast Asia Oil and Gas Midstream Market
Oil & Gas
Vacuum Gas Oil Market
Oil & Gas
Netherlands LNG Bunkering Market
Oil & Gas
Well Stimulation Vessels Market
Oil & Gas
Global Deep-Well Disposal Services Market
Oil & Gas
Europe Oilfield Equipment Rental Services Market
Oil & Gas
Blowout Preventers (BOP) Market
Oil & Gas
Oman Oil and Gas Upstream Market
Oil & Gas
Global Drilling Jars Market
Oil & Gas
Desalter Market
Oil & Gas
Gabon Oil and Gas Market
Oil & Gas
Asia-Pacific Small-Scale LNG Market
Oil & Gas
Middle East and Africa Coiled Tubing Market
Oil & Gas
Russian Federation Oil and Gas Upstream Market
Oil & Gas
Indonesia Coal Market
Oil & Gas
Aqueous Flare Meter Market