
 Critical Power and Cooling Market | 2026-2036
Critical Power and Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Critical Power and Cooling Market Intelligence
Buyer concentration in the data center sector is broadening as hyperscale cloud providers fragment procurement across multiple vendors while colocation operators consolidate into fewer national platforms. Schneider Electric leverages its integrated EcoStruxure architecture to anchor large-scale deployments across three continents. Eaton Corporation competes through advanced power distribution units and modular UPS architectures designed for edge computing environments. ABB sustains technology leadership in medium-voltage UPS systems and DC power infrastructure for industrial automation.
Critical power and cooling encompasses electrical infrastructure and thermal management systems engineered to maintain continuous operation for mission-critical loads, typically achieving availability ratings from 99.9% to 99.999% through N+1 or 2N redundancy configurations. Uninterruptible power supply systems form the largest product category by installed base, though liquid cooling and heat exchangers represent the fastest-expanding segment as rack densities exceed 50 kW in AI training clusters. Data center applications command the dominant share of capital allocation, while healthcare facilities and telecommunication networks present specialized requirements for runtime duration and acoustic performance that sustain premium pricing tiers.
The U.S. EPA Energy Star program and EU Ecodesign Directive are mandating minimum efficiency standards for UPS systems above 10 kVA, while India's Bureau of Energy Efficiency is developing parallel labeling requirements for diesel generators and cooling equipment. These frameworks compel manufacturers to redesign power conversion topologies and adopt variable-speed compressor technologies to maintain market access. Stakeholders must evaluate whether thermal design power trajectories in AI infrastructure will force a wholesale shift from air-cooled to direct liquid cooling architectures before current facility investments reach end of life.
Market Dynamics
Rack power densities exceeding 50 kW in AI training clusters are forcing infrastructure operators to abandon traditional air-cooled architectures before planned refresh cycles complete. This thermal inflection point is compressing replacement timelines and redistributing capital allocation across the supply chain.
Growth Catalysts
- India's Digital India initiative:Cloud infrastructure buildouts in Mumbai, Bangalore, and Hyderabad are accelerating investments in captive diesel generation and liquid cooling systems.
- EU Ecodesign Directive:Tightening efficiency thresholds for power conversion equipment above 10 kVA are compelling manufacturers to redesign topologies and expand premium product lines.
- Hyperscale procurement fragmentation:Redundant UPS and precision cooling demand is dispersing across multiple vendors as cloud providers diversify supplier relationships.
Market Restraints
- Copper and rare earth magnet volatility:Input cost swings for transformer windings and permanent magnet motors compress margin predictability for UPS and cooling equipment manufacturers.
- Semiconductor supply concentration:IGBT and SiC module fabrication concentrates in East Asian foundries, exposing lead time risks for power conversion equipment.
- Diesel generator substitution pressure:Battery energy storage systems and fuel cells are displacing traditional backup generation in jurisdictions with carbon intensity mandates.
Strategic Opportunities
- Edge computing infrastructure:Distributed AI inference nodes in secondary cities require compact modular UPS and precision cooling with minimal acoustic signatures.
- US EPA Energy Star certification:Premium positioning for certified equipment creates pricing separation in federal and state procurement channels.
- Liquid-to-chip cooling convergence:Direct dielectric fluid contact with processors is integrating with existing facility water loops, enabling retrofit pathways for air-cooled legacy halls.
Industry Challenges
- Thermal engineer scarcity:Expertise in two-phase cooling physics and computational fluid dynamics for high-density racks remains concentrated among semiconductor and aerospace specialists.
- Legacy electrical integration:Retrofitting liquid cooling manifolds into raised-floor environments designed for perimeter CRAC units demands structural reinforcement and containment redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Critical Power and Cooling Market |
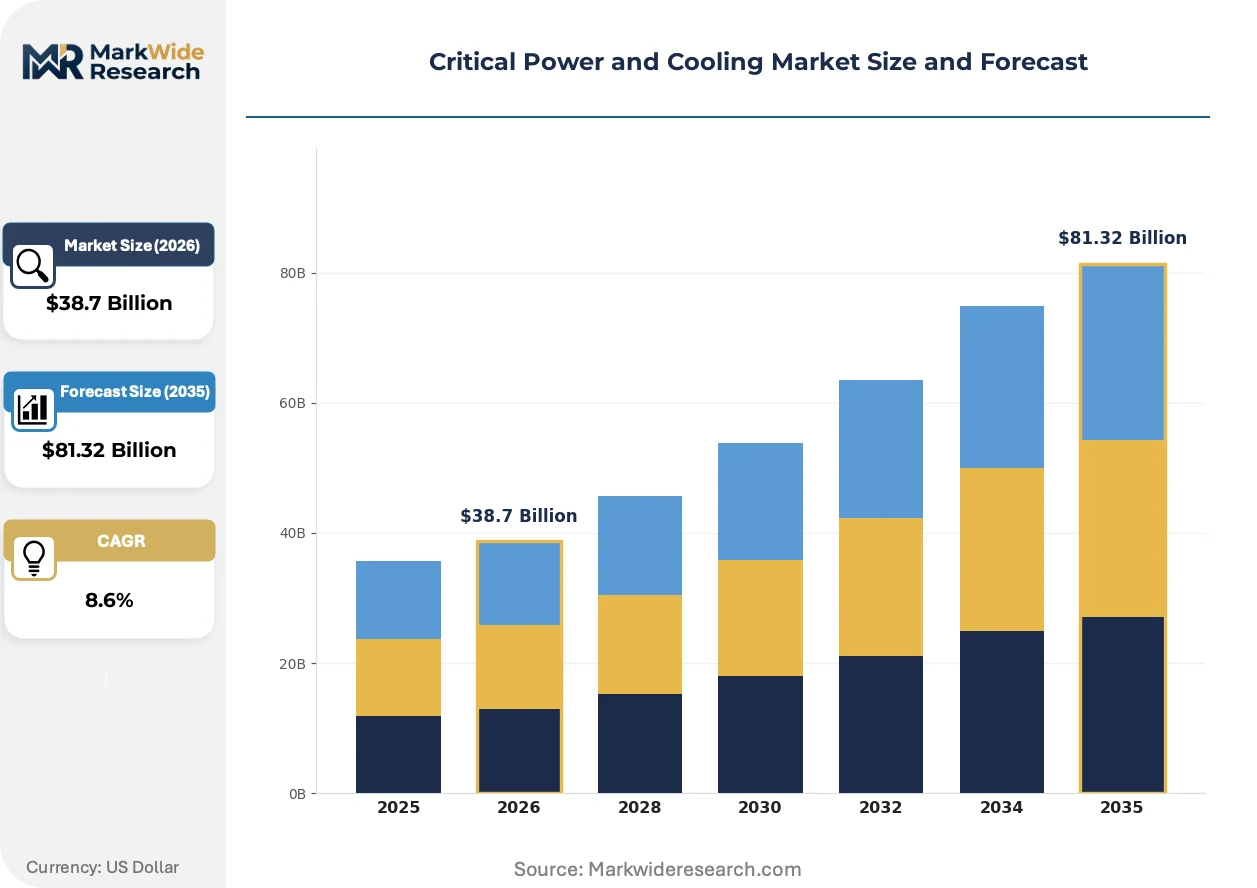
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $81.32 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Uninterruptible Power Supply, Cooling Towers, Diesel Generators, Heat Exchangers Application: Data Centers, Industrial Facilities, Telecommunication, Healthcare Facilities End User: IT Companies, Retail, Manufacturing, Government Installation: On-Site, Off-Site, Modular, Temporary |
| Companies Covered | Schneider Electric, Eaton Corporation, ABB, Vertiv Co., Delta Electronics, Inc., Siemens, General Electric, Johnson Controls, Inc., Socomec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Critical Power and Cooling Market Strategic Shifts & Innovations
Power and thermal infrastructure is bifurcating between evolutionary efficiency gains in traditional equipment and architectural discontinuity driven by AI compute densities. Three distinct vectors are reshaping supplier positioning and buyer procurement criteria.
Immersion cooling systems using engineered dielectric fluids are integrating with high-voltage DC distribution architectures to eliminate intermediate conversion losses. Hyperscale operators in Singapore and the Netherlands are piloting tank-based deployments for GPU clusters exceeding 100 kW per rack. This convergence is compressing the addressable market for conventional air-handling units while expanding demand for fluid chemistry management and corrosion monitoring services.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in precision air conditioning, forcing manufacturers to adopt natural refrigerants or low-GWP synthetic alternatives. Industrial consequence includes redesigned compressor architectures and expanded safety containment for ammonia and CO2 systems. Data center operators in Germany and France are most affected, with facility managers accelerating replacement timelines to avoid stranded asset risk from refrigerant supply constraints.
Colocation buyers are unbundling long-term service contracts from initial equipment procurement, favoring multi-vendor maintenance agreements and performance-based thermal guarantees. This disintermediation compresses OEM service attach rates while expanding third-party facility management contracts. The pattern is most visible in Northern Virginia and London, where hyperscale tenants negotiate direct relationships with cooling infrastructure specialists separate from landlord electrical provisions.
Critical Power and Cooling Market Segmentation
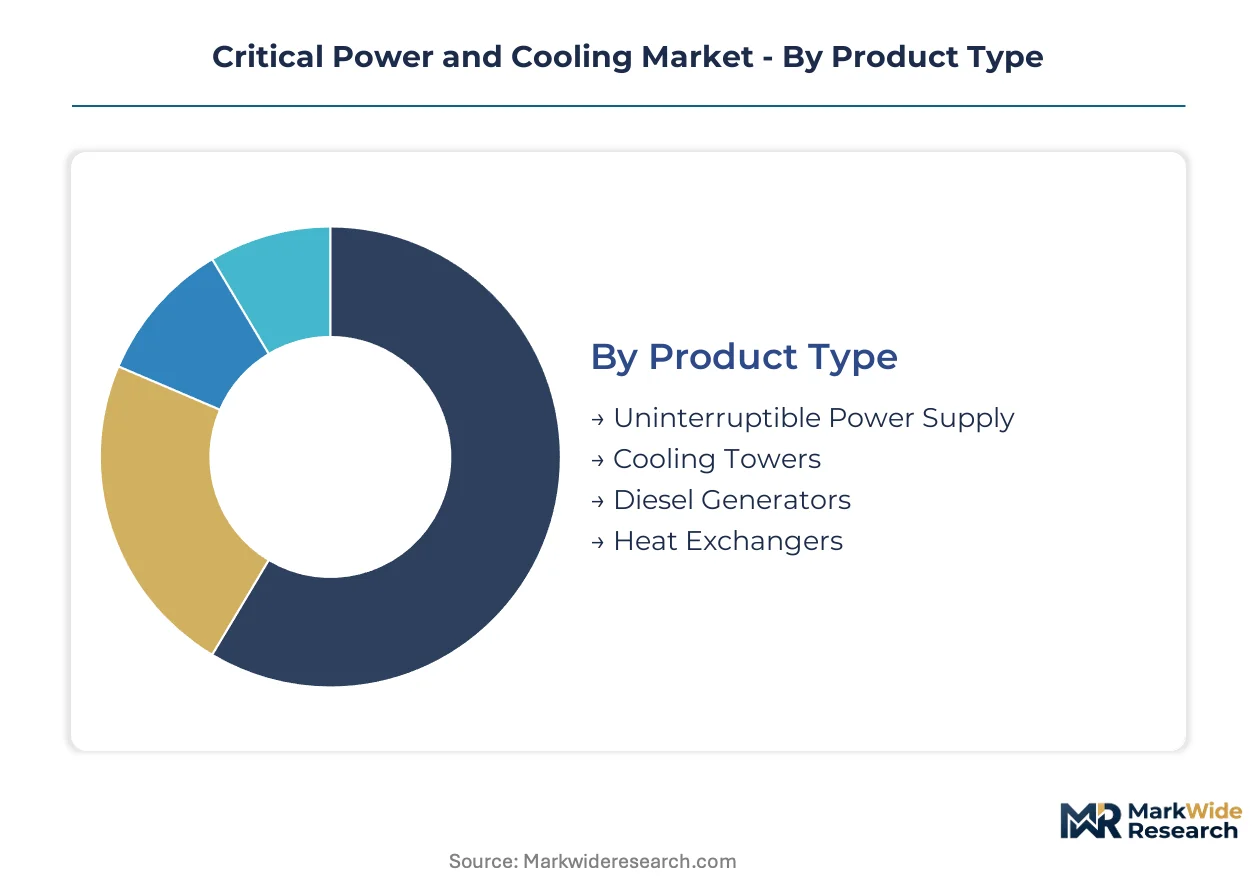
Segmentation in critical power and cooling reveals how certification requirements, thermal density thresholds, and procurement authority fragment demand across equipment categories and buyer types. Understanding these divisions exposes where capital concentrates and where margin compression threatens.
Product Type:
EPA Energy Star certification applies to UPS systems above 10 kVA, while EU Ecodesign Directive efficiency mandates cover power conversion equipment across all four product categories, with refrigerant-phase regulations from the EU F-Gas Regulation specifically targeting cooling towers and heat exchangers.
- Uninterruptible Power Supply:Double-conversion online topology dominates mission-critical installations, achieving 96% efficiency in silicon carbide architectures. Hyperscale data centers in Northern Virginia and Frankfurt are standardizing on modular UPS frames with N+1 redundancy to accommodate 50 kW rack densities. This segment commands the largest installed base and anchors vendor R&D allocation.
- Heat Exchangers:Liquid-to-liquid plate and frame configurations are displacing air-cooled coils in AI training clusters exceeding 100 kW per rack. Singapore and Netherlands facilities are piloting dielectric fluid integration with facility water loops, compressing replacement timelines for legacy perimeter CRAC infrastructure.
- Cooling Towers:Open-loop evaporative designs face water scarcity constraints in Arizona and Saudi Arabia, pushing adoption toward hybrid dry-fluid coolers with adiabatic assist.
- Diesel Generators:Tier 4 Final EPA emissions compliance and India's CEA grid code requirements are extending lead times for captive backup systems, while battery energy storage and fuel cells displace procurement in carbon-mandated jurisdictions.
Uninterruptible Power Supply sits at the top of the volume ranking, with Heat Exchangers climbing the fastest.
Application:
Cost tiering separates application segments, with data centers absorbing premium liquid cooling and medium-voltage UPS while healthcare and telecommunications prioritize runtime duration and acoustic performance over efficiency metrics.
- Data Centers:Hyperscale operators fragment procurement across redundant UPS and precision cooling vendors, while colocation platforms consolidate into national footprints. India's Digital India initiative is accelerating captive diesel and liquid cooling investments across Mumbai, Bangalore, and Hyderabad.
- Industrial Facilities:ABB's medium-voltage UPS and DC power architectures serve automation loads with 99.999% availability requirements, sustaining premium pricing through specialized channel relationships.
- Telecommunication:Edge computing nodes in secondary cities demand compact modular UPS with minimal acoustic signatures, favoring Eaton's power distribution units designed for distributed AI inference.
- Healthcare Facilities:Runtime duration requirements for surgical suites and imaging suites sustain premium tiers for extended-battery UPS configurations, with Joint Commission accreditation mandating specific testing protocols.
Data Centers capture the dominant capital allocation share, with Telecommunication infrastructure expanding most quickly at the network edge.
End User:
Procurement authority concentrates differently across end user types, with IT companies wielding direct vendor relationships and technical specifications while government buyers navigate federal and state certification channels.
- IT Companies:Hyperscale cloud providers diversify supplier relationships across Schneider Electric's EcoStruxure deployments, unbundling long-term service contracts from initial equipment procurement in Northern Virginia and London.
- Government:US EPA Energy Star certification creates pricing separation in federal procurement channels, with GSA schedules and state energy office rebates steering specification toward certified equipment.
- Manufacturing:Industrial automation loads require DC power infrastructure and medium-voltage UPS systems, with ABB sustaining technology leadership through specialized integration capabilities.
- Retail:Distributed store footprints favor compact modular UPS with rapid deployment timelines, prioritizing standardization over customization to reduce maintenance complexity.
IT Companies anchor demand volume, with Government procurement climbing fastest as efficiency mandates tighten across federal and state channels.
Installation:
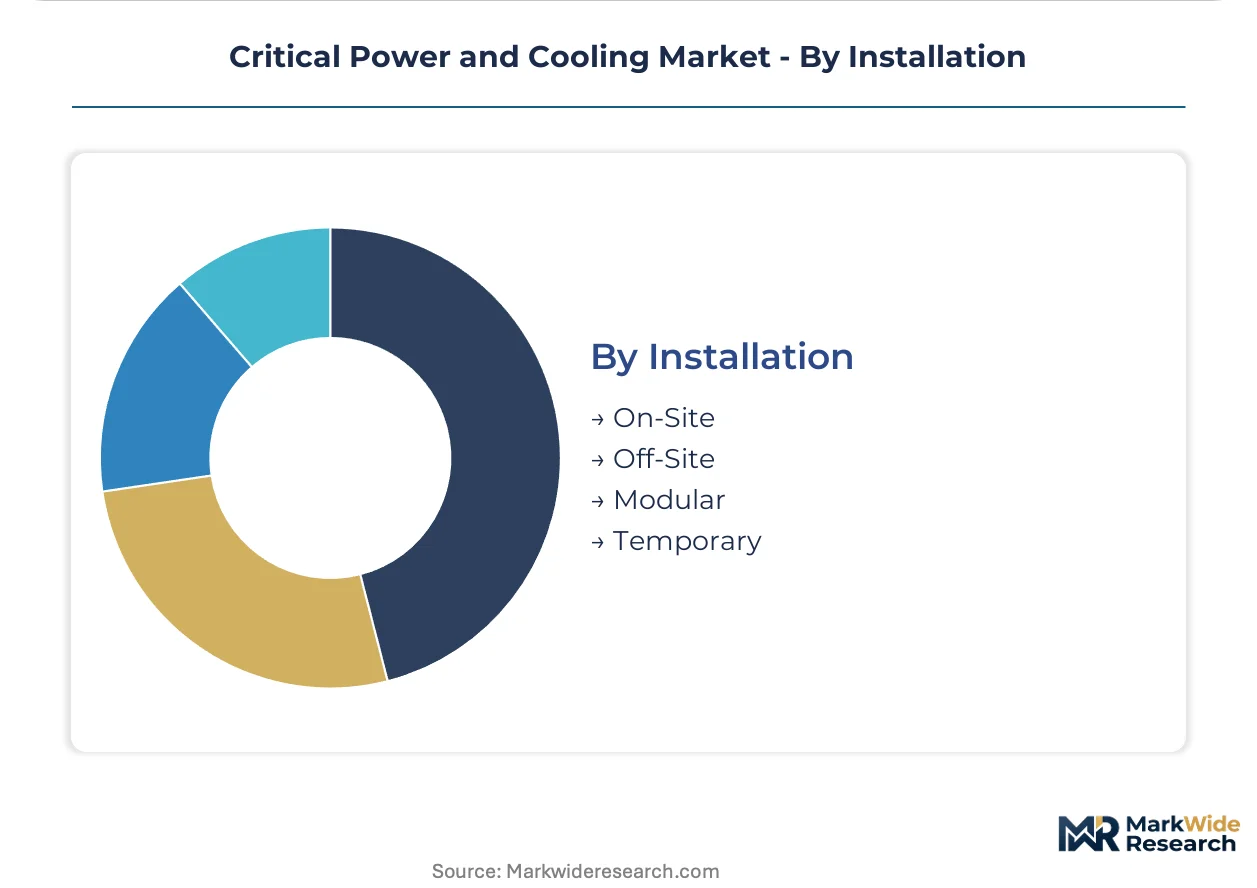
Maturity gradients separate installation approaches, with on-site construction dominating legacy facility expansion while modular and temporary configurations address compressed deployment timelines for AI infrastructure.
- Modular:Prefabricated power and cooling skids enable rapid scaling for GPU clusters exceeding thermal design power thresholds, with Schneider Electric and Eaton competing on factory integration and site commissioning speed.
- On-Site:Traditional raised-floor environments designed for perimeter CRAC units face structural reinforcement demands when retrofitting liquid cooling manifolds, extending project timelines and capital requirements.
- Off-Site:Build-to-suit colocation in secondary markets concentrates electrical and mechanical infrastructure construction, with landlords pre-provisioning redundant UPS and precision cooling to attract hyperscale tenants.
- Temporary:Event-driven and disaster-recovery deployments utilize rental diesel generators and portable cooling for short-duration resilience requirements, with procurement favoring operational expenditure over capital commitment.
On-Site installation retains the largest cumulative installed base, with Modular deployment gaining share fastest as rack densities compress infrastructure refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thermal engineering talent clusters in Singapore and the Netherlands anchor liquid cooling pilot programs for GPU-intensive workloads. India's data center construction surge draws electrical infrastructure specialists to Mumbai and Hyderabad. German mechanical engineers dominate precision cooling redesigns under EU F-Gas compliance timelines.
United States
Hyperscale cloud procurement fragments across redundant UPS vendors in Northern Virginia and Dallas-Fort Worth. The EPA Energy Star program mandates minimum efficiency standards for systems above 10 kVA, compressing margins for non-certified equipment. Phoenix and Mesa facilities face water scarcity constraints that accelerate hybrid dry-fluid cooler adoption.
Germany
Industrial automation loads sustain premium demand for medium-voltage UPS and DC power architectures in Bavaria and Baden-Württemberg. The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants, forcing compressor redesigns for ammonia and CO2 systems. Frankfurt's financial district colocation operators unbundle long-term service contracts from initial equipment procurement.
India
Digital India initiative investments concentrate captive diesel generation and liquid cooling procurement in Mumbai, Bangalore, and Hyderabad. The Bureau of Energy Efficiency develops labeling requirements for diesel generators and cooling equipment under CEA grid code alignment. Telangana's data center policy attracts hyperscale operators with power infrastructure subsidies.
Singapore
Tropical climate constraints and land scarcity force direct liquid cooling adoption for AI training clusters exceeding 100 kW per rack. The national water agency mandates strict evaporative cooling efficiency standards to preserve reservoir capacity. Tuas industrial zone hosts tank-based dielectric fluid deployments integrating with facility water loops.
Netherlands
Amsterdam's data center moratorium redirects construction to secondary markets like Eindhoven and Groningen with pre-provisioned electrical infrastructure. The EU Ecodesign Directive tightens efficiency thresholds for power conversion equipment above 10 kVA. Dutch mechanical engineering firms lead heat exchanger integration for liquid-to-chip cooling retrofits.
Critical Power and Cooling Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across electrical infrastructure and thermal management segments. The vendor base separates into three strategic archetypes: integrated platform providers spanning power and cooling, electrical specialists with UPS and distribution depth, and thermal engineering firms with fluid dynamics expertise. Consolidation pressure intensifies as hyperscale procurement fragmentation favors multi-vendor relationships over single-source dependencies. Geographic expansion and technology licensing dominate competitive moves as players seek to anchor regional data center construction waves.
Within the integrated platform tier, Schneider Electric and Eaton Corporation represent archetypal positions bridging power conversion and thermal management. ABB occupies a distinct position among electrical specialists with medium-voltage UPS and industrial DC infrastructure heritage. These three firms exemplify how vendor positioning fragments across procurement authority splits between IT companies unbundling service contracts and government buyers navigating certification channels.
| Leading Market Players |
|---|
| Schneider Electric |
| Eaton Corporation |
| ABB |
| Vertiv Co. |
| Delta Electronics, Inc. |
| Siemens |
| General Electric |
| Johnson Controls, Inc. |
| Socomec |
| Others |
Cost & Logistics Intelligence
Hyperscale cloud providers fragmenting procurement across redundant UPS and precision cooling vendors anchor the dominant pricing model around unbundled equipment procurement with separately negotiated service contracts. This buyer concentration compresses OEM service attach rates while expanding third-party facility management contracts in Northern Virginia and London.
Pricing Analysis
Unbundled equipment procurement with separately negotiated multi-year service agreements dominates pricing structures across data center applications. Price differentiation hinges on EPA Energy Star certification status and volume scale commitments, with certified equipment commanding premium positioning in federal procurement channels. Cost compression in standard-efficiency UPS tiers is intensifying because silicon carbide module adoption raises baseline performance expectations. Colocation operators exhibit highest price sensitivity due to margin pressure from hyperscale tenant negotiations, while healthcare facilities sustain premium tolerance for extended-battery runtime configurations.
Supply Chain Analysis
Thermal engineer scarcity concentrated among semiconductor and aerospace specialists constrains manufacturing scale-up in Singapore and the Netherlands. IGBT and SiC module fabrication draws from East Asian foundries, while copper winding and rare earth magnet supply rests on concentrated mining jurisdictions. Single-source vulnerability in power semiconductor fabrication exposes lead time risks for modular UPS frames. Distribution runs through direct OEM relationships with hyperscale operators and national colocation platforms, bypassing traditional electrical distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between India's Digital India infrastructure subsidies and the EU's tightening Ecodesign efficiency mandates creates cost and regulatory differentials for capital allocation. Telangana's data center policy offers power infrastructure subsidies unavailable under German F-Gas compliance timelines.
For Market Incumbents: Deploy backward integration into silicon carbide module supply to secure power semiconductor access against East Asian foundry concentration. Anchor large-scale EcoStruxure deployments across three continents while defending against battery energy storage substitution pressure in carbon-mandated jurisdictions through liquid cooling convergence offerings. For New Entrants and Emerging Players: Direct-to-hyperscale digital procurement channels bypass incumbent service bundling advantages in Northern Virginia and London. Target edge computing nodes in secondary cities requiring compact modular UPS with minimal acoustic signatures, leveraging Eaton's modular architecture precedent for distributed AI inference deployments. For Investors and Strategic Acquirers: Hyperscale cloud providers are the most active acquirer in this space, seeking captive cooling infrastructure capabilities. Long-term viability centers on liquid-to-chip cooling retrofit pathways for air-cooled legacy halls. Watch thermal design power trajectories in AI training clusters as the inflection signal forcing wholesale architectural shifts before facility investment end of life.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Convergence | Direct dielectric fluid integration with facility water loops enables retrofit pathways for legacy halls in Singapore and Netherlands. |
| Silicon Carbide Module Adoption | Advanced power conversion topologies achieve 96% efficiency in double-conversion online UPS architectures for hyperscale deployments. |
| Service Contract Unbundling | Multi-vendor maintenance agreements separate from initial equipment procurement compress OEM attach rates in colocation markets. |
| Natural Refrigerant Transition | Ammonia and CO2 compressor redesigns under EU F-Gas Regulation avoid stranded asset risk in German and French facilities. |
| Modular Prefabrication Scale-Up | Factory-integrated power and cooling skids address compressed deployment timelines for GPU clusters exceeding thermal thresholds. |
Research Approach
Multiple input streams — hyperscale procurement officer interviews, thermal engineering specialist consultations, regulatory affairs director exchanges, and facility manager panels — were reconciled against secondary validation. Primary engagement with data center operators, electrical infrastructure OEMs, and cooling system integrators combined with EPA Energy Star certification databases, EU Ecodesign Directive compliance filings, and Bureau of Energy Efficiency labeling records. Bottom-up equipment shipment aggregation and top-down capex allocation triangulation anchored market sizing.
Historical hyperscale facility deployment patterns cross-referenced against panel input from cloud provider infrastructure planners shaped the analytical framework. Segmentation dimensions modeled include product type, application vertical, end user procurement authority, and installation approach across the projection horizon. CAGRs derived from equipment replacement cycle compression and rack density inflection points. Forecast inputs incorporated AI training cluster thermal trajectories and diesel generator substitution rates in carbon-mandated jurisdictions.
The model assumes a particular technology adoption path; alternative pathways for direct liquid cooling would alter the outlook if air-cooled architectures extend viable deployment beyond current thermal thresholds. Forecasts reflect assumptions about hyperscale procurement fragmentation persistence and F-Gas refrigerant phase-down adherence. Material deviation in silicon carbide supply concentration or Digital India subsidy continuity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Industrial Radiators Market
Cooling Systems
Water Source Heat Pump Market
Cooling Systems
Battery Cooling Plate Market
Cooling Systems
Adiabatic Cooler Market
Cooling Systems
Cryogenic Systems Market
Cooling Systems
Heat Pipe Market
Cooling Systems
Radiant Cooling Systems Market
Cooling Systems
Low Temperature Radiators Market
Cooling Systems
Horizontal Air Flow Condensers Market
Cooling Systems
District Heating and Cooling Market
Cooling Systems
Cold Climate Air Source Heat Pump Market
Cooling Systems
Middle East and Africa Cooling Systems Market
Cooling Systems
Global Evaporative Cooling Market
Cooling Systems
Global Transcritical Co2 Systems Market
Cooling Systems
Solar-Assisted Heat Pump Market
Cooling Systems
Saudi Arabia Desert Air Coolers Market