
 Solar-Assisted Heat Pump Market | 2026-2036
Solar-Assisted Heat Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Solar-Assisted Heat Pump Market Analytics
The solar-assisted heat pump supply base is restructuring around a widening capability gap between premium integrated systems and commodity heat pump-only units. Daikin Industries leverages its inverter compressor expertise to dominate high-end residential installations across Japan and Europe. Bosch Thermotechnology competes through captive control over hydronic distribution components, while NIBE Industrier AB anchors its position in Nordic markets with cold-climate thermal storage specialization.
A solar-assisted heat pump combines photovoltaic or thermal solar collection with vapor-compression or absorption heat pump cycles, typically achieving coefficient of performance values above three by using solar-derived electricity or low-grade heat as the primary energy input rather than direct electrical resistance. The technology serves commercial and residential buildings seeking to displace fossil fuel boilers while maintaining heating capacity during suboptimal solar conditions. Air source products currently occupy the largest installed base due to lower upfront costs and minimal site preparation, though photovoltaic integration is the fastest-expanding technology segment as module prices decline and building-integrated designs mature. Ground source applications sustain premium pricing in new construction where drilling costs amortize across larger thermal loads, while district heating represents a concentrated but emerging demand channel for utility-scale solar-thermal hybrid plants.
The EU Green Deal and F-Gas Regulation are compressing refrigerant choices and mandating minimum renewable energy shares in building heat, directly elevating solar-assisted configurations in European product portfolios. EPA efficiency standards and state-level electrification mandates in the US are similarly redirecting contractor procurement toward heat pumps with solar pre-conditioning. Stakeholders must monitor how refrigerant phase-down schedules interact with solar collector certification protocols to avoid stranded product development cycles.
Market Dynamics
The solar-assisted heat pump supply base is restructuring around a widening capability gap between premium integrated systems and commodity heat pump-only units, as photovoltaic-thermal hybrid architectures capture concentrated interest across European housing cooperatives seeking unified renewable heat and power solutions.
Growth Catalysts
- EU F-Gas Regulation:The refrigerant phase-down compresses conventional heat pump viability, directly elevating solar-assisted configurations in European product portfolios as manufacturers pivot toward lower-GWP alternatives paired with solar pre-conditioning.
- Building energy codes:Germany's tightening standards under the EU Green Deal accelerate residential retrofit installations, creating pull-through demand for systems that satisfy renewable energy share mandates without fossil fuel boiler displacement risk.
- Photovoltaic cost decline:Module price erosion enables building-integrated designs that amortize collector costs across combined heat and power output, expanding addressable markets beyond premium new-construction segments.
Market Restraints
- Drilling cost volatility:Ground source applications face capital intensity barriers where geological complexity and labor shortages in Nordic markets inflate borehole installation expenses beyond residential payback thresholds.
- Refrigerant certification friction:The EU's F-Gas Regulation interacts unpredictably with solar collector certification protocols, creating stranded product development cycles for manufacturers pursuing parallel compliance tracks.
- Air source substitution ceiling:Cold-climate performance degradation limits air source penetration in subarctic zones, preserving fossil fuel boiler relevance where ground source drilling remains economically prohibitive.
Strategic Opportunities
- District heating channel:Utility-scale solar-thermal hybrid plants represent a concentrated but emerging demand channel for municipal energy providers seeking decarbonized baseload heat supply.
- Photovoltaic-thermal convergence:Hybrid PVT collectors that simultaneously generate electricity and low-grade thermal input are integrating with absorption heat pump cycles, unlocking coefficient-of-performance advantages unavailable to pure electric or pure thermal approaches.
- US electrification mandates:State-level policies redirect contractor procurement toward heat pumps with solar pre-conditioning, creating regulatory tailwinds for configurations that satisfy EPA efficiency standards while qualifying for IRA-aligned incentives.
Industry Challenges
- Controls engineering scarcity:The specialized skill set required for inverter-driven compressor synchronization with variable solar input remains concentrated among Japanese and German engineering teams, constraining deployment velocity.
- Legacy hydronic retrofit complexity:Integration with existing radiator-based distribution systems demands customized sizing calculations that extend sales cycles and elevate contractor training burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar-Assisted Heat Pump Market |
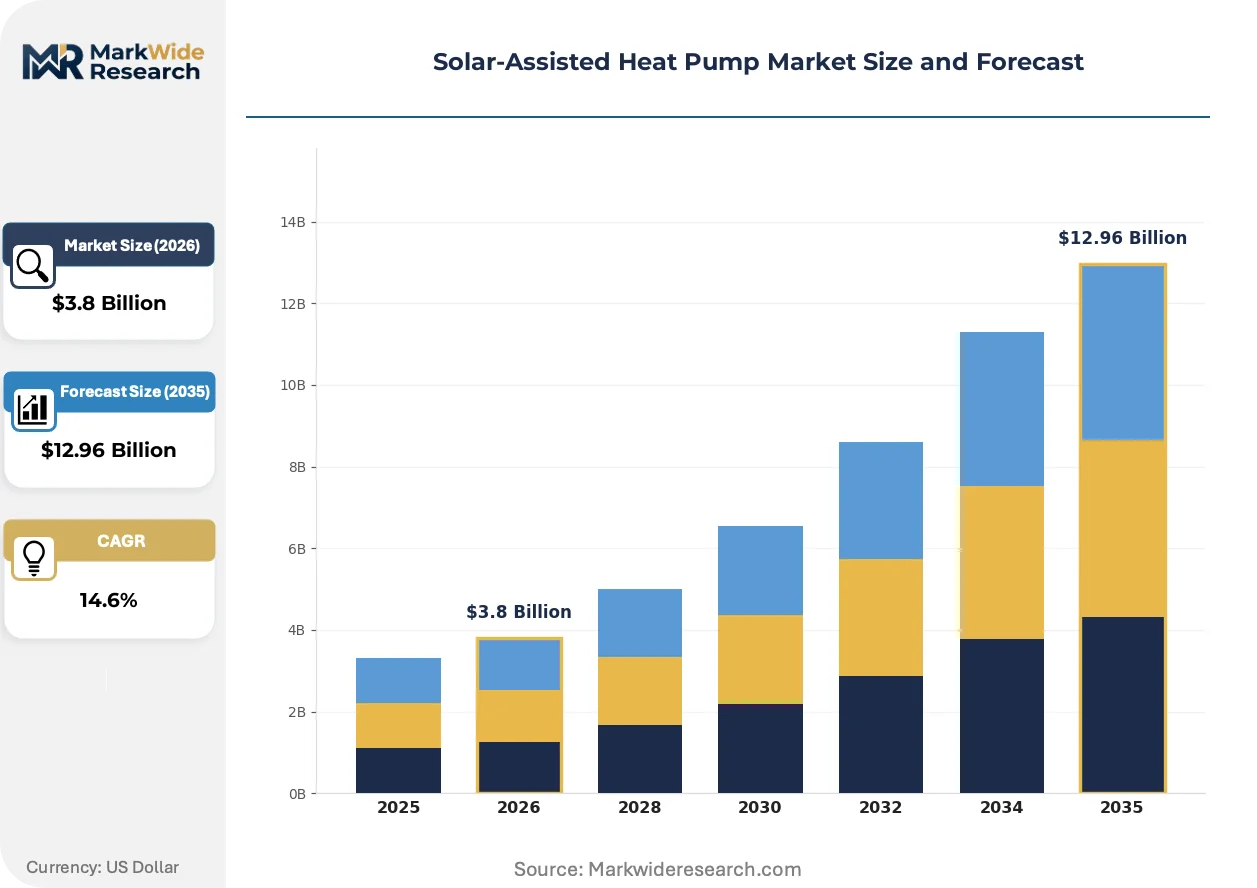
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Source, Water Source, Ground Source, Hybrid System Technology: Thermal Storage, Active Systems, Passive Systems, Photovoltaic Integration Application: Residential, Commercial, Industrial, District Heating End User: Homeowners, Contractors, Facility Managers, Property Developers |
| Companies Covered | Daikin Industries, Mitsubishi Electric, Bosch Thermotechnology, Viessmann Group, Vaillant Group, NIBE Industrier AB, Stiebel Eltron, Trane Technologies, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar-Assisted Heat Pump Market Evolving Landscape
Active innovation across the solar-assisted heat pump market centers on architectural unification of collection and conversion stages, as manufacturers compete to collapse system footprint while maintaining thermal output across suboptimal solar conditions.
Photovoltaic-thermal hybrid collectors are integrating dual-output functionality that simultaneously feeds electricity to vapor-compression compressors and low-grade heat to absorption cycle priming. German housing cooperatives are piloting these configurations at scale, compressing payback periods by stacking renewable energy certificates against thermal output metering. The technology is integrating building envelope functions that displace separate roofing and cladding procurement, restructuring contractor value capture toward turnkey envelope-energy packages.
The EU Green Deal's building renovation wave is mandating minimum renewable energy shares in heat supply, forcing refrigerant selections toward lower-GWP alternatives that pair favorably with solar-assisted architectures. Industrial consequence includes accelerated R-32 and R-290 adoption curves that compress equipment replacement cycles ahead of baseline economic obsolescence. Nordic markets exhibit the most pronounced response, with cold-climate thermal storage specialization emerging as a competitive differentiator against southern European cost-optimized alternatives.
Buyer preference is rotating toward performance-guaranteed contracting models that unbundle equipment procurement from operational outcome accountability. Housing associations in the Netherlands and Denmark are displacing traditional capital purchase with energy-service agreements that transfer seasonal performance risk to installer-operators. This channel shift is most visible in multi-unit residential retrofits where collective decision-making friction previously stalled individual owner investment.
Solar-Assisted Heat Pump Market Segmentation
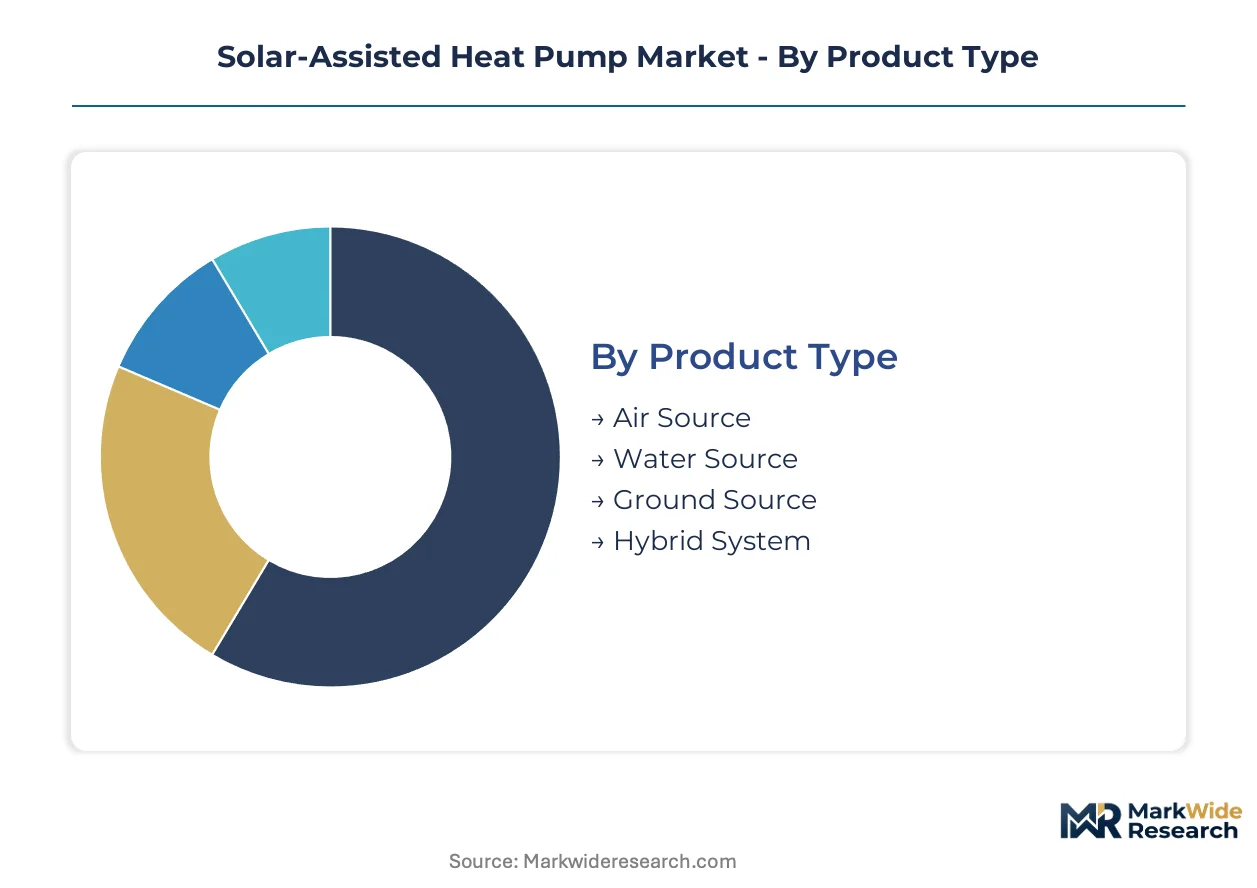
The solar-assisted heat pump market fragments across four critical dimensions that determine system configuration, sales channel strategy, and margin capture. Product type and technology choices define capital intensity and performance boundaries, while application and end-user segmentation dictate contract structure and installation complexity.
Product Type:
Capital outlay and site preparation requirements separate buyers into distinct procurement tiers with radically different payback calculations.
- Air Source:Ambient air serves as the thermal exchange medium, eliminating groundworks and enabling rapid retrofit deployment. German housing cooperatives favor these units for multi-family renovations where drilling access is constrained, though cold-climate performance degradation limits Nordic penetration.
- Ground Source:Vertical borehole arrays or horizontal ground loops extract stable subterranean temperatures, delivering coefficient-of-performance advantages that justify premium pricing in new construction. Swedish and Finnish markets absorb disproportionate volumes where geological conditions and district heating integration amortize drilling costs across larger thermal loads.
- Water Source:Lakes, rivers, or aquifers provide thermal exchange with superior efficiency versus air source alternatives. These configurations concentrate near water bodies in the Netherlands and Denmark where aquifer thermal energy storage regulations permit open-loop operation.
- Hybrid System:Dual-source architectures switch between air and ground thermal exchange based on seasonal optimization algorithms. Japanese residential developments pilot these configurations where space constraints prevent full ground loop deployment.
Air source leads volumes today; hybrid systems are gaining share fastest.
Technology:
Control sophistication and solar coupling architecture determine which buyers capture operational savings versus upfront capital relief.
- Photovoltaic Integration:Direct DC coupling between rooftop modules and variable-speed compressors eliminates inverter losses and grid interconnection delays. Dutch housing associations deploy these configurations under energy-service agreements that transfer performance risk to installer-operators.
- Thermal Storage:Phase-change materials or stratified water tanks buffer solar thermal input against demand timing mismatches. Nordic cold-climate specialization anchors competitive positioning here, with NIBE Industrier AB dominating seasonal storage configurations.
- Active Systems:Pumped circulation and forced convection maximize heat transfer rates in commercial-scale installations. Facility managers in German industrial parks specify these units where process heat demands exceed residential duty cycles.
- Passive Systems:Thermosiphon circulation and natural convection eliminate parasitic pumping energy in off-grid or resilience-focused deployments. Remote Alpine installations in Austria and Switzerland favor these configurations where grid reliability concerns override efficiency optimization.
Thermal storage anchors premium pricing; photovoltaic integration is climbing the fastest.
Application:
Decision-making friction and capital aggregation capacity vary dramatically across building scale and ownership structure.
- Residential:Single-family and multi-family dwellings where individual or collective ownership determines procurement modality. Germany's building energy code tightening accelerates retrofit installations as owners seek compliance without fossil fuel boiler displacement risk.
- Commercial:Office buildings, retail, and hospitality where facility managers balance tenant comfort against operating expenditure targets. The EU Green Deal's renovation wave mandates minimum renewable energy shares that elevate solar-assisted configurations in refurbishment specifications.
- Industrial:Process heat and manufacturing applications where thermal load magnitude justifies custom engineering. These deployments concentrate in energy-intensive clusters where F-Gas Regulation refrigerant constraints accelerate equipment replacement ahead of baseline obsolescence.
- District Heating:Municipal-scale thermal networks where utility providers aggregate distributed solar-thermal hybrid plants. Danish and Swedish energy companies pilot these configurations for decarbonized baseload heat supply.
Residential dominates installation counts; district heating shows the steepest expansion trajectory.
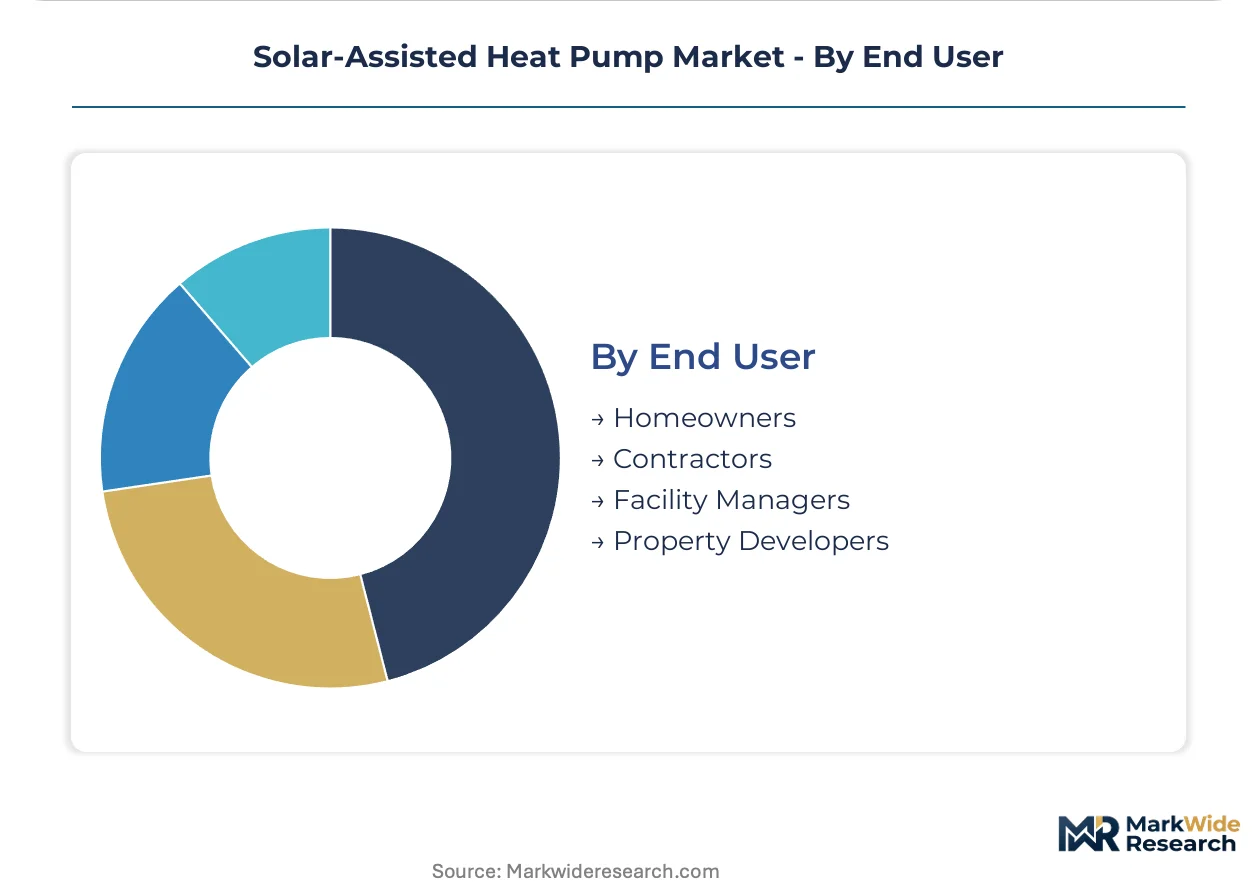
End User:
Technical literacy and risk tolerance shape whether buyers prefer capital purchase, performance contracting, or turnkey development models.
- Contractors:Installation and maintenance professionals who specify equipment based on training familiarity and supplier support infrastructure. These stakeholders redirect procurement toward heat pumps with solar pre-conditioning as EPA efficiency standards and state-level US electrification mandates tighten.
- Property Developers:New construction actors who optimize total project cost and marketing differentiation over operational efficiency. Building-integrated photovoltaic designs that amortize collector costs across combined heat and power output attract concentrated interest here.
- Homeowners:Individual purchasers navigating complex sizing calculations and incentive qualification. Legacy hydronic retrofit complexity extends sales cycles for this segment as radiator-based distribution demands customized engineering.
- Facility Managers:Operational professionals accountable for energy expenditure and regulatory compliance in commercial and institutional portfolios. Performance-guaranteed contracting models transfer seasonal performance risk to installer-operators, displacing traditional capital purchase in Dutch and Danish multi-unit residential retrofits.
Contractors move the highest equipment volumes; facility managers are adopting performance-based procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Japan and Germany anchor solar-assisted heat pump development, while Nordic cold-climate specialization and Dutch energy-service contracting models reshape deployment patterns across distinct regulatory environments.
Germany
Residential retrofit demand accelerates as housing cooperatives pursue unified renewable heat and power solutions. The EU Green Deal's building renovation wave tightens energy codes, mandating minimum renewable shares that elevate solar-assisted configurations. The Rhine-Ruhr industrial corridor concentrates installer networks specializing in legacy hydronic integration for multi-family renovations.
Japan
Inverter-driven compressor synchronization expertise concentrates among Osaka and Nagoya engineering teams. METI efficiency standards redirect residential development toward photovoltaic-thermal hybrid architectures. Tokyo metropolitan area pilots dual-source hybrid systems where space constraints prevent full ground loop deployment.
Sweden
Cold-climate thermal storage specialization dominates competitive positioning as subarctic conditions degrade air source performance. The F-Gas Regulation accelerates R-32 and R-290 adoption curves ahead of baseline obsolescence. Stockholm district heating networks pilot utility-scale solar-thermal hybrid plants for decarbonized baseload supply.
Netherlands
Housing associations displace capital purchase with performance-guaranteed energy-service agreements. Aquifer thermal energy storage regulations permit open-loop water source configurations near lakes and rivers. Randstad urban clusters concentrate facility managers adopting outcome-based procurement fastest.
United States
State-level electrification mandates redirect contractor procurement toward solar-pre-conditioned heat pumps. EPA efficiency standards tighten while IRA-aligned incentives reshape equipment qualification pathways. Pacific Northwest and Northeast corridor states lead retrofit deployment where drilling costs amortize across larger thermal loads.
Solar-Assisted Heat Pump Market Competitive Landscape
Top-tier vendors anchor premium integrated system tiers, while commodity heat pump-only suppliers compete on installation velocity and distributor relationships. The supply base restructures around a widening capability gap between sophisticated controls engineering and standardized vapor-compression units. Three archetypes dominate: inverter compressor specialists, hydronic distribution integrators, and cold-climate thermal storage experts. Competitive moves concentrate on backward integration into collector manufacturing and strategic partnerships with housing cooperative procurement platforms.
Among Japanese engineering-intensive specialists, Daikin Industries and Mitsubishi Electric exemplify inverter-driven compressor synchronization capabilities that constrain deployment velocity elsewhere. Bosch Thermotechnology GmbH occupies a position bridging European hydronic distribution control with solar-assisted system integration. These three entities represent distinct competitive vectors—compressor electronics, captive component supply, and system-level thermal management—that define tier boundaries in residential and commercial procurement decisions.
| Leading Market Players |
|---|
| Daikin Industries |
| Mitsubishi Electric |
| Bosch Thermotechnology |
| Viessmann Group |
| Vaillant Group |
| NIBE Industrier AB |
| Stiebel Eltron |
| Trane Technologies |
| Panasonic Corporation |
| Others |
Value Network & Pricing Analysis
Controls engineering talent concentrated in Osaka and Nagoya engineering clusters widens labor-cost differentials between Japanese inverter-compressor specialists and European hydronic integrators, compressing margin spreads at the premium tier while elevating standard-tier pricing volatility.
Pricing Analysis
Bundled energy-service agreements diverge sharply from unbundled equipment-only transactions across procurement channels. Three-tier pricing structure across premium integrated systems, standard hybrid configurations, and economy heat-pump-only units separates buyers by after-sales service bundling and certification grade. Price differentiation stems from cold-climate performance guarantees and F-Gas Regulation refrigerant compliance tiers. Pricing pressure intensifies in the standard tier as photovoltaic module cost declines compress collector margins. Housing cooperatives exhibit lowest price sensitivity; individual homeowners in retrofit scenarios show highest elasticity.
Supply Chain Analysis
Workforce availability constraints in Japanese compressor electronics and German hydronic component manufacturing lengthen lead times for premium integrated systems. Manufacturing concentrates in Japan, Germany, and Sweden, with Nordic thermal storage specialization anchoring cold-climate supply. Component sourcing draws from Chinese photovoltaic module producers, South Korean inverter suppliers, and European refrigerant specialists. Single-source vulnerability in R-32 and R-290 refrigerant supply creates exposure to EU regulatory restriction timelines. Distribution runs through certified installer networks and housing cooperative procurement platforms rather than traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar-assisted heat pump market functions as a regulatory compounder where EU F-Gas Regulation phase-down schedules and building energy code tightening create demand acceleration independent of pure cost economics.
For Market Incumbents: Hedge refrigerant transition risk by accelerating R-290 and R-32 certification investments ahead of baseline equipment replacement cycles. Secure captive control over collector manufacturing to defend margin position against photovoltaic cost compression. Cold-climate thermal storage specialization offers defensive moat against southern European cost-optimized entrants. For New Entrants and Emerging Players: US state-level electrification mandates in the Pacific Northwest and Northeast corridor open a window for solar-pre-conditioned heat pump configurations that satisfy EPA efficiency standards. Target facility manager procurement in Dutch and Danish multi-unit residential retrofits where performance-guaranteed contracting displaces capital purchase. Pursue energy-service agreement go-to-market models that transfer seasonal performance risk to installer-operators. For Investors and Strategic Acquirers: HVAC incumbent strategics are the most active acquirer in this space, seeking controls engineering capabilities and collector manufacturing assets. Five-to-ten-year viability hinges on regulatory enforcement durability rather than technology cost curves. Acquisition target archetype: mid-cap specialists with cold-climate thermal storage IP and housing cooperative channel relationships. Watch F-Gas Regulation refrigerant quota auction prices as inflection indicator for equipment replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collector Manufacturing | Captures margin compression from photovoltaic module cost declines while securing supply certainty. |
| Cold-Climate Thermal Storage R&D Investment | NIBE Industrier AB anchors Nordic positioning as subarctic conditions degrade air source alternatives. |
| Energy-Service Agreement Channel Development | Dutch housing associations displace capital purchase with outcome-based procurement models. |
| R-290 Refrigerant Certification Acceleration | EU F-Gas Regulation phase-down compresses conventional heat pump viability ahead of schedule. |
| Housing Cooperative Procurement Platform Partnerships | German cooperatives pilot photovoltaic-thermal hybrid configurations at scale for unified renewable supply. |
Research Methodology
Direct dialogue with inverter compressor engineering directors, hydronic system procurement managers, housing cooperative facility directors, and EU regulatory affairs specialists grounded qualitative assessment. Secondary validation drew from ECHA refrigerant registration databases, EU Green Deal implementation progress reports, national building energy code filings, and trade customs data for photovoltaic module and heat pump unit flows. Bottom-up installation volume estimates triangulated against top-down energy system transition targets.
Installed base projections and revenue estimates across the analysis window reflect segmentation by product type, technology architecture, application scale, and end-user procurement modality. CAGRs derived from regression against historical equipment replacement cycles, regulatory milestone enforcement timelines, and photovoltaic cost elasticity parameters. Forecast inputs incorporated F-Gas Regulation refrigerant quota trajectories and EU building renovation wave mandate penetration curves.
Revisions become necessary when refrigerant phase-down schedules accelerate, building energy code enforcement weakens, or photovoltaic module supply disruptions materialize. Forecasts reflect documented assumptions regarding regulatory durability and technology cost convergence. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Solar Ventilation Systems Market
Cooling Systems
Global Magnetic Refrigeration Market
Cooling Systems
Low Temperature Radiators Market
Cooling Systems
Solar Cold Room Market
Cooling Systems
Adiabatic Cooler Market
Cooling Systems
Global Secondary Refrigerants Market
Cooling Systems
Evaporative Cooling Tower Market
Cooling Systems
Horizontal Air Flow Condensers Market
Cooling Systems
Middle East and Africa Cooling Systems Market
Cooling Systems
Annular Cooler Market
Cooling Systems
Marine Cooling Systems Market
Cooling Systems
Solar Refrigerators Market
Cooling Systems
Plate and Frame Heat Exchangers Market
Cooling Systems
Heat Pump Dryer Market
Cooling Systems
Temperature Controlled Container Market
Cooling Systems
Water Cooling Corona Discharge Ozone Generator Market