
 Global Transcritical Co2 Systems Market | 2026-2036
Global Transcritical Co2 Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Transcritical Co2 Systems Market Foresight
Supermarket retrofit activity is realigning procurement patterns across the commercial refrigeration value chain. Danfoss leverages its component integration depth to anchor European retrofit demand for high-pressure CO2 rack systems. BITZER Kühlmaschinenbau GmbH sustains technology leadership through specialized semi-hermetic compressor platforms engineered for transcritical pressure envelopes. Advansor competes on turnkey booster system delivery, controlling project timelines for retail chains navigating phased F-Gas compliance deadlines.
Transcritical CO2 systems circulate carbon dioxide above its critical point, typically operating at discharge pressures exceeding 100 bar and employing gas coolers rather than traditional condensers to reject heat. The technology serves commercial and industrial refrigeration applications where environmental regulations prohibit high-global-warming-potential synthetic refrigerants. Booster system configurations dominate installed capacity across European supermarket networks, while heat recovery technology captures fastest-growing interest as operators seek to offset thermal energy costs through integrated hot water generation. Electronic expansion valves command concentrated margin pools due to precision superheat control requirements under transcritical pressure transients.
The EU F-Gas Regulation and ECHA REACH framework enforce phased hydrofluorocarbon quota reductions, compelling end users toward natural refrigerant alternatives. The EPA Significant New Alternatives Policy program in the United States parallels this trajectory, restricting high-GWP options in commercial refrigeration sectors. Stakeholders must monitor evolving national implementation timelines and pressure equipment safety codes as transcritical CO2 adoption scales beyond its Nordic and Central European strongholds into North American and Asia-Pacific regulatory jurisdictions.
Market Dynamics
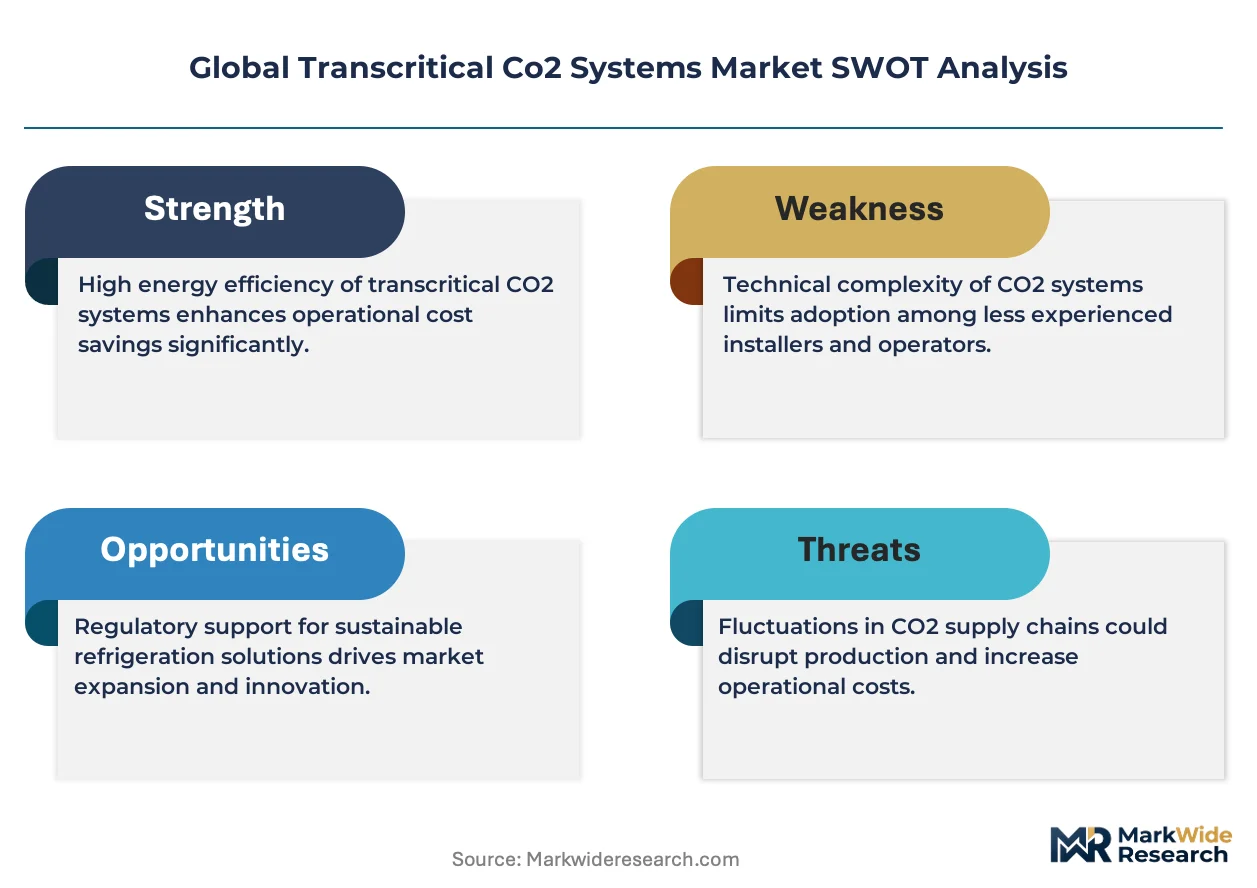
The EU F-Gas Regulation's phasedown schedule is compressing adoption timelines for natural refrigerant infrastructure across commercial refrigeration networks. Retail operators face binding quota reductions that eliminate hydrofluorocarbon alternatives, forcing capital deployment toward high-pressure CO2 architectures regardless of replacement cycle maturity.
Growth Catalysts
- Regulatory Mandate Compression:The EU F-Gas Regulation enforces annual hydrofluorocarbon quota cuts, eliminating lower-GWP synthetic options and mandating CO2 transition for supermarket chains across Germany, France, and Italy.
- Heat Recovery Integration:Captured thermal energy from gas coolers now offsets domestic hot water costs in Nordic retail locations, improving project economics for transcritical booster installations.
- Electronic Valve Precision:Advanced superheat control under transcritical pressure transients enables stable operation across wider ambient temperature ranges, expanding addressable climate zones.
Market Restraints
- Specialized Compressor Supply Concentration:Semi-hermetic CO2 compressor manufacturing concentrates among German and Danish component suppliers, creating single-source vulnerability for rack system integrators.
- High-Grade Steel Input Volatility:Pressure vessel and piping specifications require specialized alloys whose pricing fluctuates with energy-intensive metallurgical production cycles.
- Technical Skill Scarcity:Certified technicians capable of servicing 100+ bar systems remain concentrated in Northern Europe, limiting deployment velocity in Southern European and North American markets.
Strategic Opportunities
- North American Regulatory Alignment:The EPA Significant New Alternatives Policy program restricts high-GWP refrigerants in commercial sectors, creating compliance-driven demand analogous to European patterns.
- Industrial Cold Storage Expansion:Food processing and logistics facilities represent underpenetrated verticals where scale economics favor centralized CO2 refrigeration over distributed HFC systems.
- IoT-Enabled Predictive Maintenance:Sensor integration with cloud-based diagnostics reduces unplanned downtime for high-pressure installations, creating recurring revenue streams for system providers.
Industry Challenges
- Pressure Equipment Certification Bottlenecks:National implementation of harmonized safety codes varies across EU member states, delaying project approvals for cross-border retail chains.
- Legacy Control System Integration:Existing building management protocols require custom middleware development to interface with transcritical CO2 rack controllers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Transcritical Co2 Systems Market |
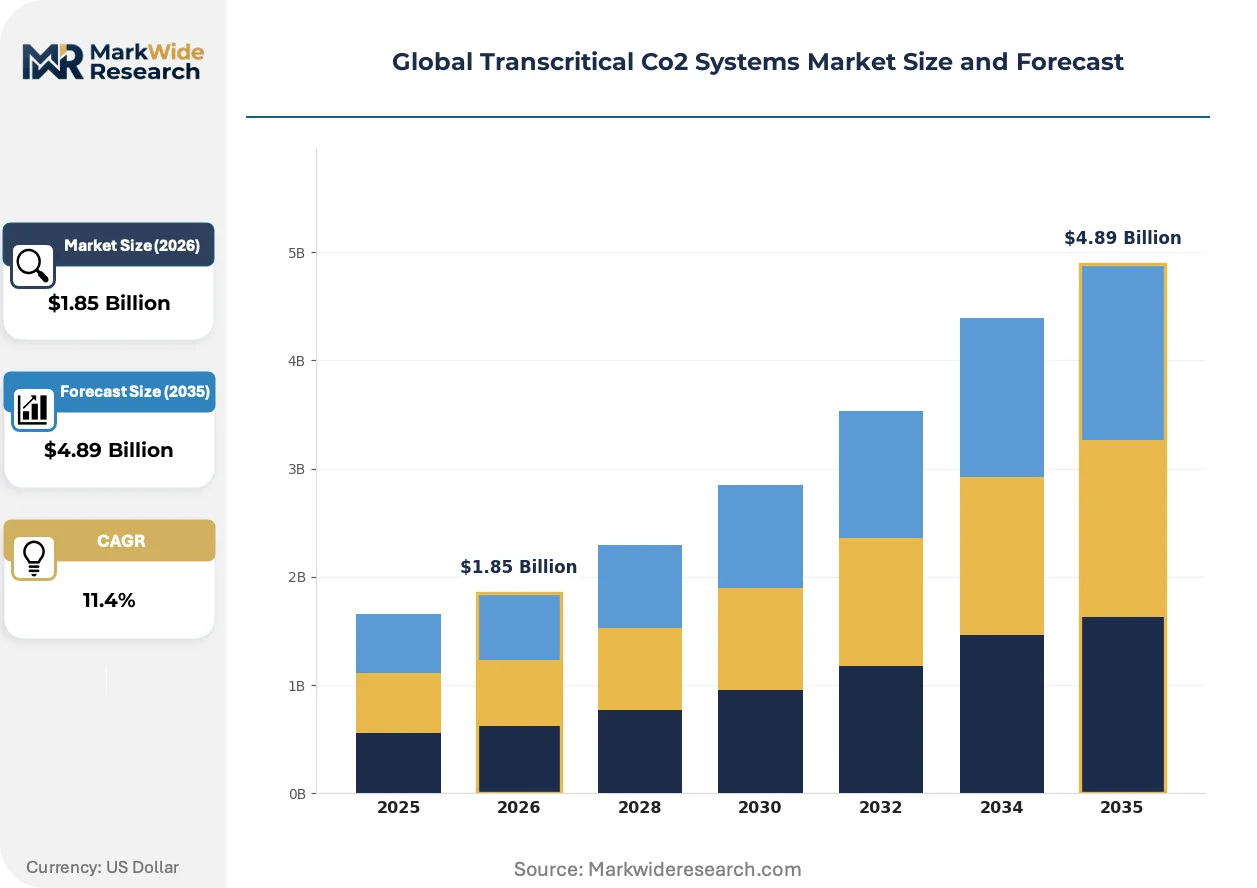
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Parallel, Booster, Secondary Loop, Cascade, Integral, Others Application: Supermarkets, Cold Storage, Food Processing, Ice Rinks, Pharmacies, Data Centers End User: Retail Chains, Warehousing Operators, Food Manufacturers, Sports Facilities, Healthcare Providers, IT Infrastructure Technology: Electronic Expansion Valves, Pressure Control, Heat Recovery, Remote Monitoring, Variable Speed Drives, Leak Detection |
| Companies Covered | Danfoss, Advansor, BITZER Kühlmaschinenbau GmbH, Emerson Climate Technologies, Carrier Commercial Refrigeration, Hillphoenix, Inc., Carnot Refrigeration, Mayekawa MFG. Co., Ltd., Baltimore Aircoil Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Transcritical Co2 Systems Market Shifts & Advancements
Technology convergence between refrigeration hardware and digital control systems is redefining competitive differentiation in commercial cooling infrastructure. System providers now compete on integrated energy optimization rather than standalone thermal performance.
Parallel compressor architecture is modularizing transcritical CO2 rack configurations, allowing incremental capacity expansion without full system replacement. German supermarket operators deploy staged compressor additions to match cooling load growth across store network expansions. This modular approach compresses initial capital outlay while preserving upgrade pathways.
The EPA Significant New Alternatives Policy program restricts high-GWP refrigerant eligibility in commercial refrigeration categories, paralleling European regulatory trajectories. US food retail chains now evaluate transcritical CO2 architectures for new construction and major renovation projects. California and New York state-level mandates accelerate this evaluation timeline beyond federal minimums.
Energy-as-a-service contracting is displacing traditional equipment purchase models among capital-constrained retail operators. Third-party ownership structures transfer performance risk to system providers while guaranteeing thermal output specifications. Nordic retail cooperatives pioneered this arrangement; Southern European chains now adopt similar structures to bypass upfront infrastructure investment.
Global Transcritical Co2 Systems Market Segmentation
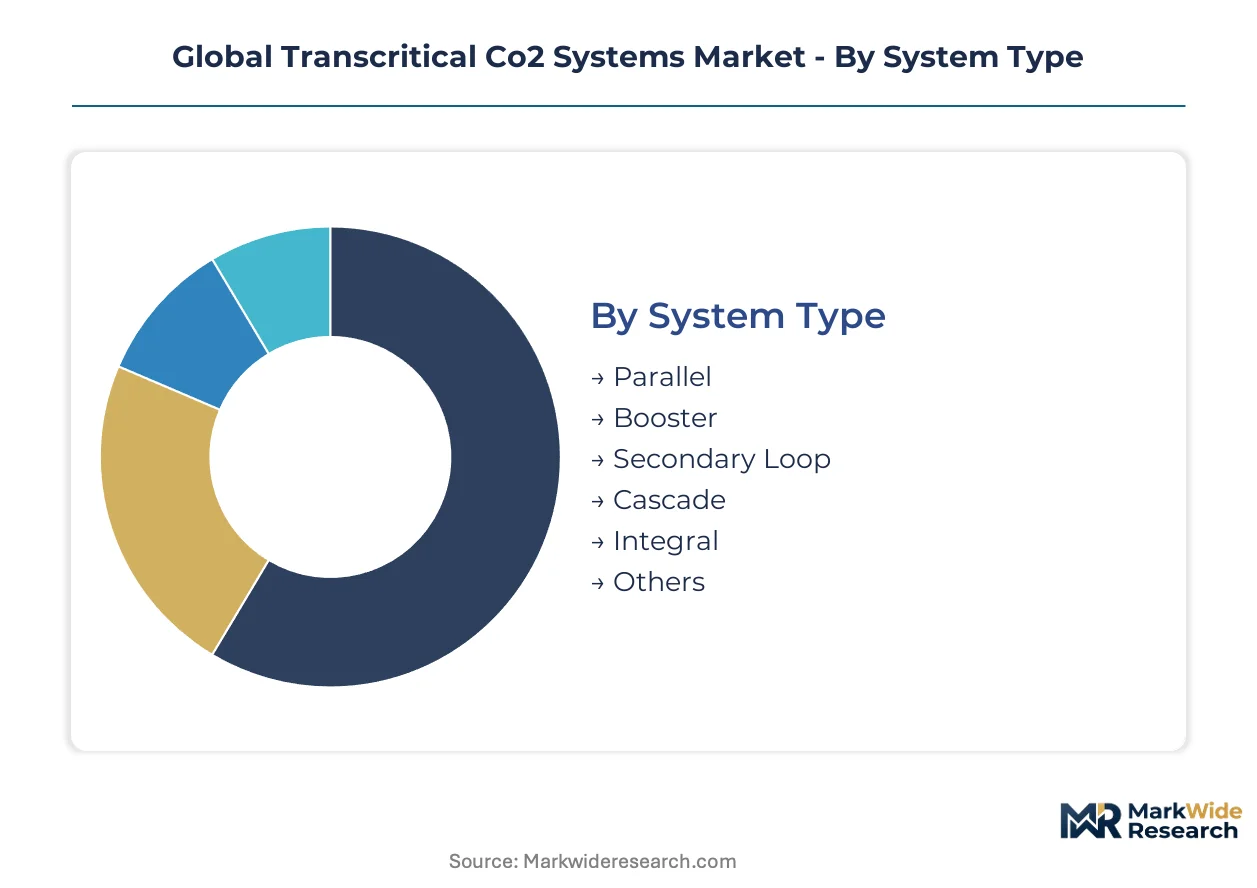
Transcritical CO2 system configurations vary dramatically in capital intensity, operating pressure envelopes, and integration complexity. Procurement decisions across supermarkets, industrial cold storage, and emerging verticals hinge on matching thermal load profiles to compressor architecture and control technology combinations.
System Type:
End users select architectures based on ambient temperature range, retrofit constraints, and heat recovery requirements rather than upfront cost alone.
- Booster:Two-stage compression separates low-temperature and medium-temperature circuits through dedicated compressors. German and Scandinavian supermarket chains specify booster systems for ambient temperatures below 31°C where transcritical efficiency peaks. Heat recovery integration from gas coolers improves project economics in Nordic retail locations.
- Parallel:Single-stage compressors operate in tandem across unified suction groups. Southern European operators favor parallel architectures for warmer climates where transcritical operation dominates year-round. Simplified piping reduces installation labor for retrofit projects facing compressed F-Gas compliance deadlines.
- Secondary Loop:Chilled glycol circulates to display cases while CO2 remains confined to machine room. Food processing facilities in France deploy secondary loops to isolate personnel from high-pressure refrigerant circuits.
- Cascade:CO2 serves low-temperature stage with separate refrigerant handling medium-temperature loads. Industrial cold storage operators in Italy retain cascade systems during phased HFC phaseout.
- Integral:Self-contained plug-and-play units eliminate centralized machinery. Small-format urban supermarkets in Spain specify integral systems where mechanical space constraints prohibit rack installations.
- Others:Hybrid configurations and emerging architectures including adiabatic gas cooler integration. Pilot deployments in the Netherlands test combined evaporative cooling for extreme ambient conditions.
Booster systems lead volumes today; parallel configurations are gaining share fastest in Southern European retrofit activity.
Application:
Thermal load stability, temperature band requirements, and regulatory scrutiny intensity create distinct procurement patterns across end-use environments.
- Supermarkets:Combined medium and low-temperature refrigeration for display cases and walk-in freezers. German retail chains account for concentrated demand as EU F-Gas Regulation quotas eliminate HFC alternatives. Electronic expansion valve precision proves critical for superheat control across variable ambient conditions.
- Cold Storage:Large-capacity centralized refrigeration for frozen and chilled goods warehousing. Danish logistics operators deploy transcritical CO2 for new facilities exceeding 10,000 pallet positions where scale economics offset higher capital costs.
- Food Processing:Blast freezing, chilling tunnels, and process cooling for meat, dairy, and prepared foods. French poultry processors specify heat recovery integration to offset sanitation hot water costs.
- Ice Rinks:Sub-zero brine circulation for arena floor freezing. Swedish municipal facilities convert aging ammonia systems to CO2 for improved safety profiles and regulatory compliance.
- Pharmacies:Ultra-stable temperature control for vaccine and pharmaceutical storage. Italian hospital pharmacies deploy transcritical CO2 for EU Good Distribution Practice compliance.
- Data Centers:High-density server cooling through direct expansion or chilled water loops. Pilot installations in Finland leverage free cooling integration for hyperscale facility efficiency targets.
Supermarket applications dominate current deployment; cold storage represents the steepest expansion trajectory as logistics capacity scales.
End User:
Capital availability, technical staffing depth, and regulatory exposure differentiate procurement sophistication across customer categories.
- Retail Chains:Multi-site operators with standardized equipment specifications and centralized maintenance contracts. German cooperatives negotiate fleet-wide service agreements covering predictive maintenance and refrigerant management.
- Warehousing Operators:Third-party logistics providers serving multiple food industry clients. Danish cold storage specialists prioritize modularity for capacity expansion matching seasonal demand fluctuations.
- Food Manufacturers:Integrated producers with captive refrigeration requirements from raw material intake through finished goods dispatch. French dairy cooperatives specify heat recovery for process hot water and CIP systems.
- Sports Facilities:Municipal and private arena operators with seasonal load variation and public safety oversight. Swedish ice hockey venues lead conversion from legacy ammonia systems.
- Healthcare Providers:Hospital pharmacies and blood banks requiring validated temperature documentation. Italian regional health authorities mandate natural refrigerant compliance for public procurement.
- IT Infrastructure:Colocation and hyperscale data center operators with power usage effectiveness targets. Finnish cloud computing facilities pilot CO2 for mechanical cooling redundancy.
Retail chains anchor current procurement volumes; warehousing operators are expanding most quickly as cold chain infrastructure scales.
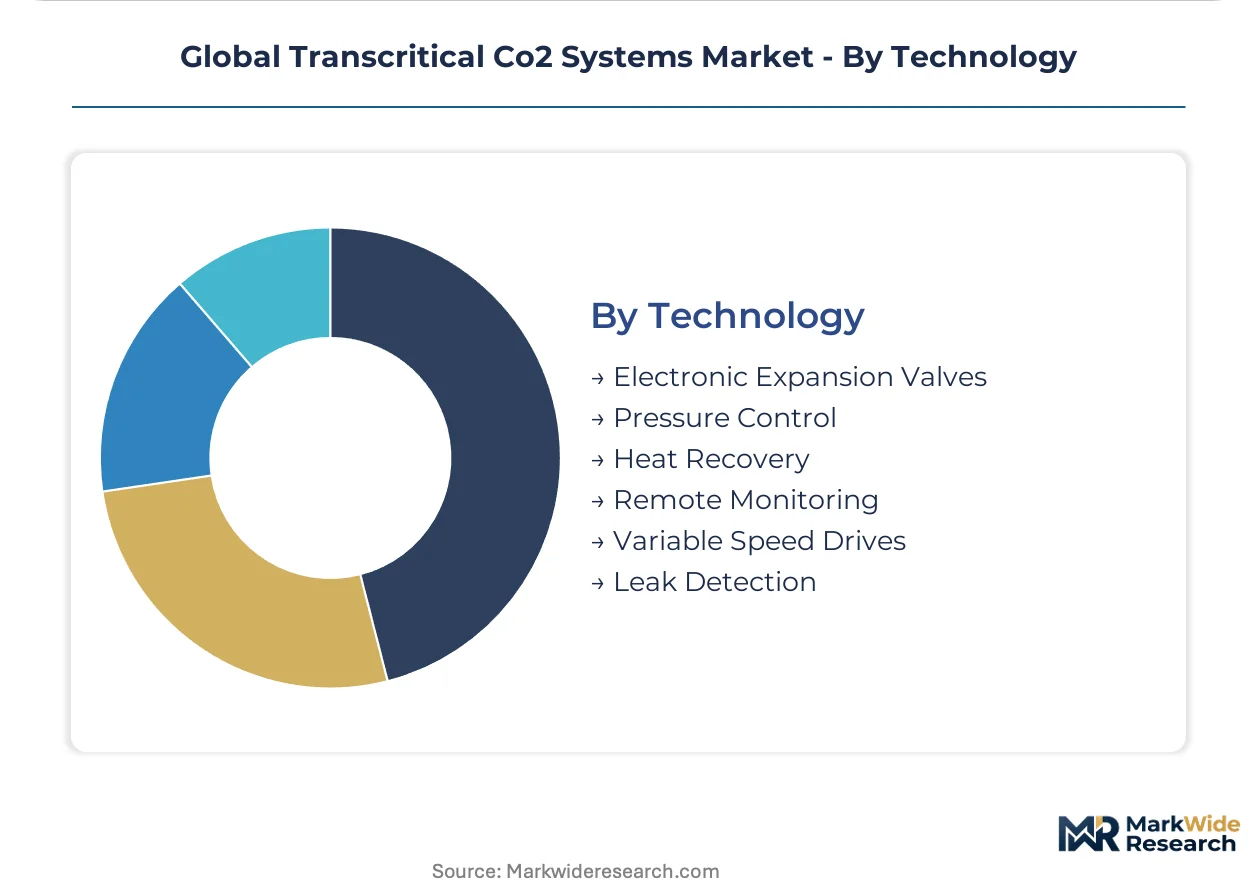
Technology:
Control precision, energy recovery, and operational visibility determine system performance differentiation and lifecycle cost profiles.
- Electronic Expansion Valves:Stepper-motor driven metering devices enabling superheat control within 0.5K accuracy. Precision under transcritical pressure transients commands concentrated margin pools for component suppliers.
- Pressure Control:Adaptive discharge pressure optimization for gas cooler performance across ambient temperature variation. German rack manufacturers integrate proprietary algorithms for seasonal efficiency gains.
- Heat Recovery:Gas cooler output capture for domestic hot water or process heating. Nordic retail locations achieve 40-60% thermal energy offset through integrated recovery systems.
- Remote Monitoring:Cloud-connected sensors enabling predictive maintenance and refrigerant leak detection. Danish service providers offer performance guarantees through continuous diagnostics.
- Variable Speed Drives:Compressor motor control matching capacity to real-time cooling load. French supermarket operators report 15-25% energy reduction through staged speed modulation.
- Leak Detection:Infrared and ultrasonic sensors for early warning of high-pressure circuit integrity compromise. Italian safety codes mandate continuous monitoring for systems exceeding 100 bar design pressure.
Electronic expansion valves dominate technology attachment rates today; heat recovery integration is climbing the fastest as energy costs escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as producers relocate to jurisdictions with streamlined pressure equipment certification. The EU F-Gas Regulation's binding quota reductions compress adoption timelines unevenly across member states, creating compliance-cost differentials that favor early-mover countries with established technician training infrastructure.
Germany
Industrial cold storage operators in Lower Saxony and Bavaria anchor European deployment volumes for transcritical CO2 booster systems. The Bundesamt für Wirtschaft und Ausfuhrkontrolle enforces strict F-Gas quota tracking that eliminates hydrofluorocarbon alternatives for supermarket retrofit projects. The Ruhr industrial corridor concentrates compressor manufacturing capacity serving cross-border retail chains.
United States
California and New York state-level mandates accelerate evaluation timelines beyond EPA Significant New Alternatives Policy minimums for commercial refrigeration. The EPA restricts high-GWP refrigerant eligibility in food retail categories, paralleling European regulatory trajectories. Cold chain logistics clusters in the Midwest pilot transcritical architectures for new distribution center construction.
Denmark
Retail cooperatives in Copenhagen and Aarhus pioneered energy-as-a-service contracting structures now diffusing across Southern Europe. The Danish Energy Agency subsidizes heat recovery integration for domestic hot water offset in supermarket applications. Nordic technician certification programs supply qualified service personnel for high-pressure system maintenance.
France
Poultry processors in Brittany specify transcritical CO2 with integrated heat recovery to offset sanitation hot water costs. The French Environment and Energy Management Agency enforces EU F-Gas Regulation implementation through regional prefecture oversight. The Lyon-Auvergne-Rhône-Alpes corridor concentrates food manufacturing demand for process cooling applications.
Sweden
Municipal ice rink operators in Stockholm and Gothenburg convert aging ammonia systems to CO2 for improved safety profiles. The Swedish Environmental Protection Agency mandates natural refrigerant compliance for public procurement of refrigeration infrastructure. Northern retail locations achieve thermal energy offsets exceeding 40% through gas cooler heat capture.
Global Transcritical Co2 Systems Market Competitive Landscape
Technology licensing dominates the current landscape as specialized component suppliers monetize proprietary control algorithms and compressor platforms. The market structures around three tiers: integrated system providers delivering turnkey rack installations, component specialists supplying compressors and electronic expansion valves, and regional fabricators assembling standardized configurations for local retrofit markets. Two strategic archetypes define competitive positioning: full-stack integrators controlling project timelines and certification risk, and modular component suppliers capturing recurring demand from maintenance and capacity expansion cycles. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with fabricators securing exclusive distribution arrangements to lock in retrofit procurement channels.
Among European-integrated system providers, Danfoss and BITZER Kühlmaschinenbau GmbH exemplify divergent archetypes. Danfoss occupies a position anchoring component integration depth across electronic expansion valve and control system portfolios. BITZER represents specialized semi-hermetic compressor engineering for transcritical pressure envelopes. Advansor sits within the turnkey delivery tier, competing on project timeline compression for retail chains navigating phased compliance deadlines. These three entities collectively illustrate how competitive positioning fragments across the value chain rather than consolidating around unified platform dominance.
| Leading Market Players |
|---|
| Danfoss |
| Advansor |
| BITZER Kühlmaschinenbau GmbH |
| Emerson Climate Technologies |
| Carrier Commercial Refrigeration |
| Hillphoenix, Inc. |
| Carnot Refrigeration |
| Mayekawa MFG. Co., Ltd. |
| Baltimore Aircoil Company |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between EU F-Gas compliant rack systems and non-compliant legacy architectures manifests in both component pricing premiums and supply chain sourcing strategies. Tier-one German compressor manufacturers command pricing power through specialized semi-hermetic platforms, while retrofit integrators absorb margin compression from certified technician scarcity across Southern European deployment zones.
Pricing Analysis
Distributor margins on electronic expansion valves and gas cooler assemblies typically range 15-25% above commodity refrigeration components due to precision engineering requirements. Three-tier pricing structure across premium certified systems, standard compliant configurations, and economy retrofit kits reflects differentiation by pressure rating certification and heat recovery integration depth. Cost compression in parallel compressor architectures intensifies as Southern European fabricators enter with simplified control packages. Retail chains with fleet-wide service agreements demonstrate lowest price sensitivity; independent single-store operators face acute capital constraint pressure.
Supply Chain Analysis
Certified welding technician availability in Germany, Denmark, and Sweden constrains fabrication throughput for high-pressure vessel assemblies. Semi-hermetic CO2 compressor production draws from specialized alloy steel feedstock sourced through Ruhr corridor metallurgical suppliers, with electronic controller chips anchored in Taiwanese semiconductor foundries. Single-source vulnerability concentrates around German OEM compressor platforms serving cross-border retail chains. Distribution runs through authorized refrigeration system integrators with direct OEM technical support relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation functions as a regulatory compounder, with its phasedown schedule mandating CO2 transition regardless of equipment replacement cycles. This binding quota compression eliminates synthetic refrigerant alternatives and locks in demand visibility for compliant system providers.
For Market Incumbents: Extend control system integration depth to capture recurring software and predictive maintenance revenue streams. Compressor OEMs face margin pressure from modular parallel architecture entrants; defensive moves require captive valve-controller bundling and exclusive service network lock-in across Nordic retail cooperatives. For New Entrants and Emerging Players: The EPA Significant New Alternatives Policy program in the United States opens a window for turnkey system delivery in Midwest cold chain logistics clusters. Underpenetrated industrial cold storage verticals in France and Italy offer white-space expansion with heat recovery integration as the primary go-to-market wedge. For Investors and Strategic Acquirers: Consolidation pressure builds where component specialists lack full-stack integration capability to guarantee project timelines. Long-term viability favors platform providers with captive compressor supply and certified technician training infrastructure. The signal to watch is cross-border retail chain procurement standardization toward single-source integrators.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Recovery Integration Partnership | Nordic retail cooperatives offset domestic hot water costs through gas cooler thermal capture. |
| Electronic Valve Controller Acquisition | Precision superheat capability under transcritical pressure transients commands concentrated margin pools. |
| Certified Technician Training Program | Danish Energy Agency subsidies address service personnel scarcity limiting Southern European deployment velocity. |
| Parallel Compressor Platform Launch | Modular capacity expansion compresses initial capital outlay for capital-constrained retail operators. |
| Energy-as-a-Service Contracting Structure | Third-party ownership transfers performance risk while guaranteeing thermal output specifications. |
Research Methodology
Multiple input streams — regulatory filing analysis, component supplier production data, and end-user procurement pattern assessment — were reconciled to construct demand estimates. Primary interviews with supermarket engineering directors, refrigeration system integrators, compressor OEM technical leads, and EU member state environmental enforcement officers informed adoption timeline assumptions. Secondary validation drew from EPA Significant New Alternatives Policy dockets, EU F-Gas Regulation quota tracking reports, and national pressure equipment safety code implementations. Bottom-up project pipeline enumeration and top-down regulatory mandate sizing were triangulated to cross-check volume estimates.
Historical installation data from Nordic retrofit waves were cross-referenced against panel input from German and Danish system providers to anchor growth trajectory assumptions across the analysis window. Segmentation modeling incorporated system type architecture, application vertical, end-user capital structure, and control technology attachment rates. CAGRs were derived from regulatory deadline pacing and equipment replacement cycle overlap analysis. Forecast inputs included EU F-Gas quota phase-down coefficients and North American state-level mandate adoption curves.
Revisions become necessary when EU member state implementation timelines diverge from harmonized schedules or when pressure equipment certification bottlenecks extend beyond current regulatory allowance periods. Forecasts reflect documented assumptions regarding technician training pipeline scaling and alloy steel input cost stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Global Magnetic Refrigeration Market
Cooling Systems
Temperature Controlled Container Market
Cooling Systems
Three Phase Cooling Fans Market
Cooling Systems
Aftercoolers Market
Cooling Systems
Evaporative Cooling Tower Market
Cooling Systems
Flue Gas Coolers Market
Cooling Systems
Radiant Cooling Systems Market
Cooling Systems
Water Source Heat Pump Market
Cooling Systems
Solar Powered Cold Storage Market
Cooling Systems
Seawater Cooling System Market
Cooling Systems
Global Chiller Market
Cooling Systems
Europe Cooling Systems Market
Cooling Systems
Heat Pump (>100°C) Market
Cooling Systems
Air Cooling Corona Discharge Ozone Generator Market
Cooling Systems
Air Source Heat Pump Market
Cooling Systems
Water Cooling Corona Discharge Ozone Generator Market