
 Planned LNG Market | 2026-2036
Planned LNG Market Size, Share, and Industry Trends Forecast 2026-2036
Planned LNG Market Outlook
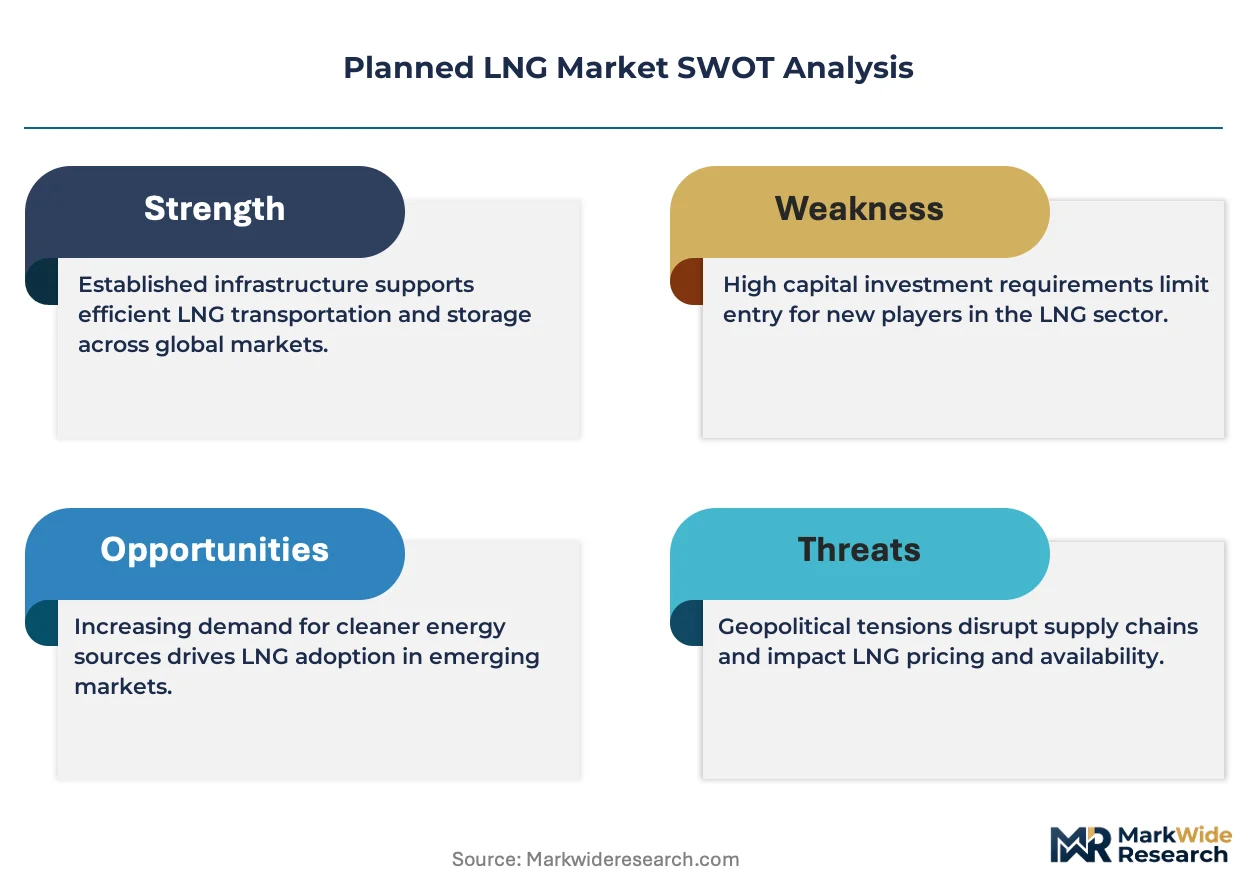
Project finance with long-term offtake-backed structures is reconfiguring competitive entry in planned LNG development. Chevron Corporation leverages integrated upstream-to-export capabilities across multiple basins. Venture Global LNG anchors its position through modular liquefaction technology at brownfield sites. Royal Dutch Shell plc sustains portfolio breadth across floating and onshore terminal formats.
Planned LNG encompasses liquefied natural gas infrastructure in pre-construction or committed development phases, typically involving cryogenic processing at minus 162 degrees Celsius for volume reduction and marine transport. Export terminals dominate committed capacity volumes, while floating LNG represents the fastest-growing category as operators target stranded gas fields with lower capital intensity. Mega projects by capacity class command the largest capital pools, though modular LNG plants are attracting new entrants seeking phased deployment.
Environmental assessments under EPA guidelines in the United States and EU Green Deal methane-emission standards in Europe are lengthening permitting timelines for planned LNG facilities. FERC certification requirements for U.S. export terminals and CE marking obligations for European regasification equipment are reshaping engineering specifications and procurement criteria. Stakeholders must monitor evolving carbon-accounting rules that could restructure offtake contract terms and project financing conditions.
Market Dynamics
Modular liquefaction technology is collapsing minimum efficient scale thresholds for planned LNG entry, enabling mid-scale developers to challenge mega-project incumbents through phased capital deployment and brownfield site repurposing.
Growth Catalysts
- Asia-Pacific power generation offtake:Utilities in Japan, South Korea, and Taiwan are signing long-term purchase agreements that underwrite greenfield terminal financing.
- FERC export certification:Streamlined U.S. federal permitting for liquefaction capacity is accelerating committed project timelines.
- Stranded gas monetization:Floating LNG vessels are unlocking reserves in Mozambique and Tanzania that lack pipeline connectivity to established demand centers.
Market Restraints
- Nickel-alloy cryogenic material costs:Specialized 9% nickel steel for storage tanks faces supply concentration from Japanese and Korean mills.
- EU Green Deal methane standards:Stringent emission monitoring requirements are extending European project development cycles.
- Electrification substitution:Grid-scale battery storage and renewable hydrogen are capturing peak power demand that LNG previously served.
Strategic Opportunities
- Vietnam and Bangladesh demand:First-time LNG importers are building maiden regasification terminals without legacy infrastructure lock-in.
- Carbon capture integration:Post-combustion CCS retrofits at liquefaction plants qualify for U.S. IRA production tax credits.
- Small-scale bunkering:ISO tank container logistics are creating distributed marine fuel supply networks at secondary ports.
Industry Challenges
- Cryogenic welding specialist scarcity:Qualified technicians for minus 162 degree Celsius pipeline construction command premium labor rates.
- CE marking compliance timelines:European regasification equipment certification is delaying procurement schedules.
- Legacy SCADA integration:Brownfield automation upgrades require harmonization between Siemens, Honeywell, and Yokogawa control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Planned LNG Market |
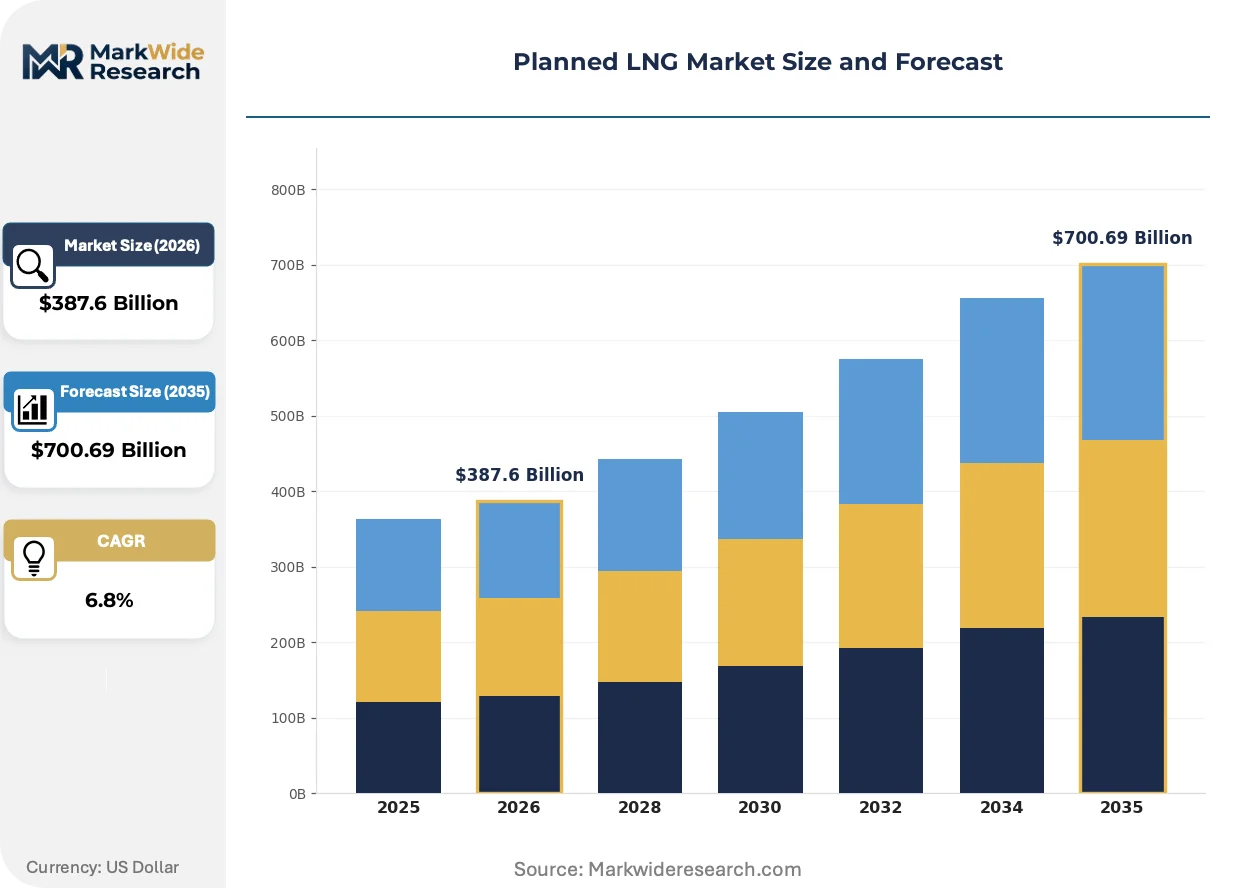
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Import Terminals, Export Terminals, Floating LNG, Liquefaction Facilities Capacity: Small Scale, Medium Scale, Large Scale, Mega Projects End User: Power Generation, Industrial Usage, Residential Heating, Marine Fuel Technology: Cryogenic Process, Modular LNG Plants, Regasification Systems, Storage Solutions |
| Companies Covered | Chevron Corporation, Royal Dutch Shell plc, ExxonMobil Corporation, Cheniere Energy, Inc., Freeport LNG, Energy Transfer LP, ConocoPhillips Company, Equinor ASA, Venture Global LNG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Planned LNG Market Strategic Shifts
Technology convergence and regulatory stringency are compressing development cycles while fragmenting the optimal project scale. Developers now optimize across carbon intensity, modular flexibility, and offtake duration rather than maximizing nameplate capacity alone.
Modular liquefaction trains using standardized 1-2 MTPA blocks are hybridizing project finance structures. Mid-scale developers in Texas and Louisiana are stacking these units at existing industrial sites. This approach is compressing front-end engineering timelines from five years to thirty-six months.
The EPA's supplemental environmental impact requirements for greenhouse gas emissions are mandating continuous monitoring systems at U.S. Gulf Coast terminals. Engineering contractors are redesigning flare minimization protocols. Greenfield projects in Texas and Louisiana are responding with closed-loop refrigeration and electric motor drives.
Asian utility procurement is pivoting toward fifteen-year indexed contracts with destination flexibility clauses. Japanese trading houses are displacing traditional oil-linked pricing with Henry Hub-based structures. This shift is most visible in South Korean and Taiwanese power sector tenders.
Planned LNG Market Segmentation
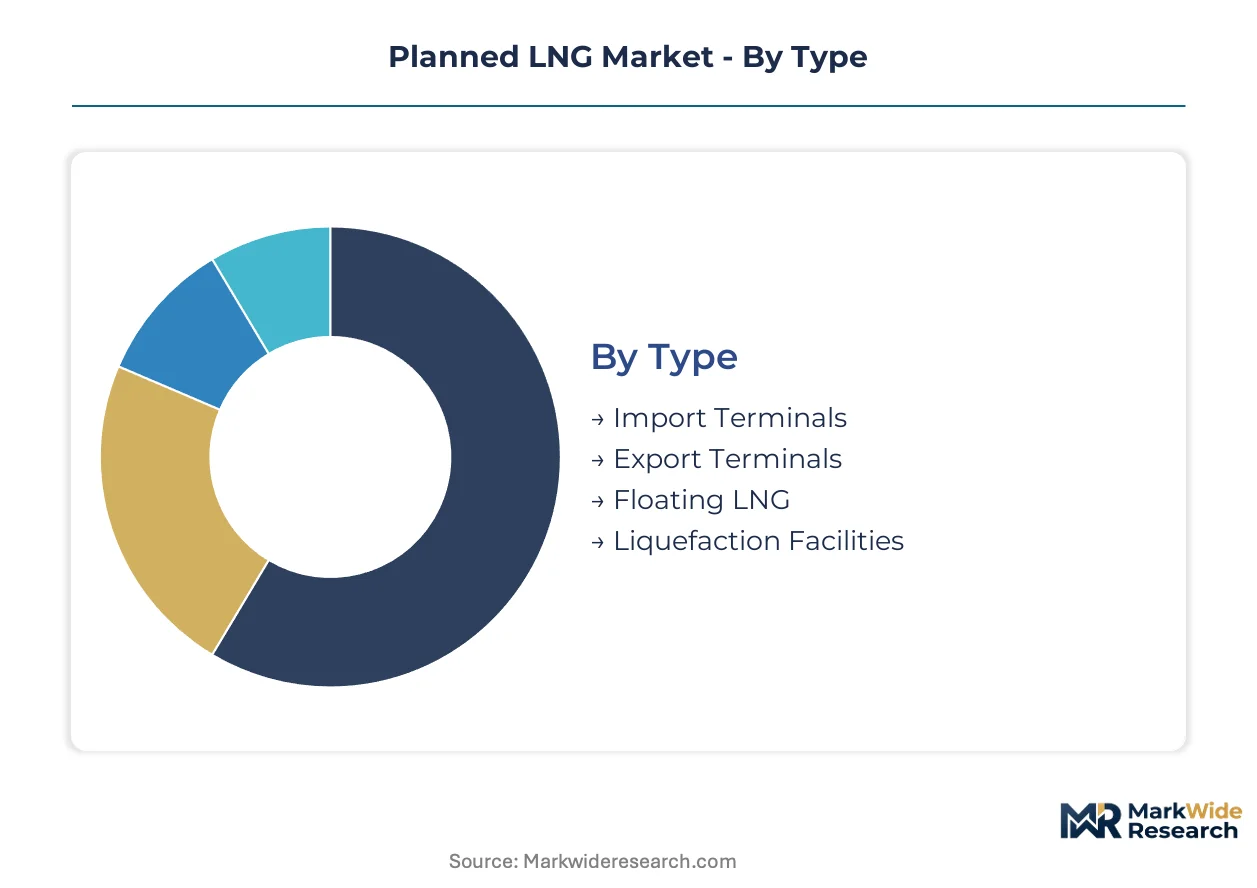
Planned LNG infrastructure exhibits divergent capital intensity and risk profiles across facility types, capacity classes, and technology platforms. Segmentation reveals how modular systems are collapsing entry barriers while mega projects concentrate financing capacity among integrated operators.
Type:
Use-case spectrum spans baseload energy security, export revenue generation, and stranded reserve monetization through differentiated physical configurations.
- Export Terminals:Onshore liquefaction complexes with dedicated marine loading infrastructure and long-term offtake contracting structures. Qatar and the United States dominate committed capacity volumes as national oil companies anchor project financing with sovereign-backed guarantees.
- Floating LNG:Vessel-mounted liquefaction systems enabling offshore production without pipeline connection to shorebase. Mozambique and Tanzania deployments target stranded gas fields with lower capital intensity than equivalent onshore developments.
- Import Terminals:Regasification facilities converting shipped LNG back to gaseous state for grid injection or local distribution. Vietnam and Bangladesh are constructing maiden terminals without legacy infrastructure constraints.
- Liquefaction Facilities:Cryogenic processing plants reducing natural gas volume for marine transport. Brownfield expansions at existing industrial sites are compressing front-end engineering timelines through modular train replication.
Established volume favors export terminals; emerging adoption favors floating LNG.
Capacity:
Capital deployment scale determines financing structure complexity and stakeholder composition across the project pipeline.
- Mega Projects:Multi-train facilities exceeding 10 MTPA with integrated upstream development and dedicated fleet arrangements. QatarEnergy and U.S. Gulf Coast developers command the largest capital pools through joint venture structures with international oil companies.
- Large Scale:Single-train or dual-train installations in the 5-10 MTPA range with standardized equipment procurement. Gulf Coast brownfield sites are attracting private equity through phased expansion options.
- Medium Scale:1-5 MTPA configurations using modular liquefaction technology at repurposed industrial locations. Venture Global LNG anchors this category through standardized block deployment.
- Small Scale:Sub-1 MTPA installations serving isolated demand centers or piloting novel technology configurations. Remote mine sites and island grids are driving niche procurement.
Financing concentration centers on mega projects; technology innovation concentrates on medium scale.
End User:
Demand composition reflects energy transition pacing and industrial base characteristics across target markets.
- Power Generation:Combined-cycle gas turbine fuel procurement by electric utilities under long-term indexed contracts. Japanese, South Korean, and Taiwanese utilities are expanding offtake agreements with destination flexibility clauses.
- Industrial Usage:Process heat and feedstock supply for petrochemical, fertilizer, and metals production. Grid-scale battery storage and renewable hydrogen are displacing peak power demand previously served by LNG.
- Residential Heating:Seasonal demand concentration in markets lacking pipeline natural gas infrastructure. European regasification terminals are prioritizing winter supply security.
- Marine Fuel:LNG bunkering for container shipping and cruise vessels meeting IMO sulfur regulations. ISO tank container logistics are creating distributed supply networks at secondary ports.
Contract duration favors power generation; volume growth favors marine fuel.
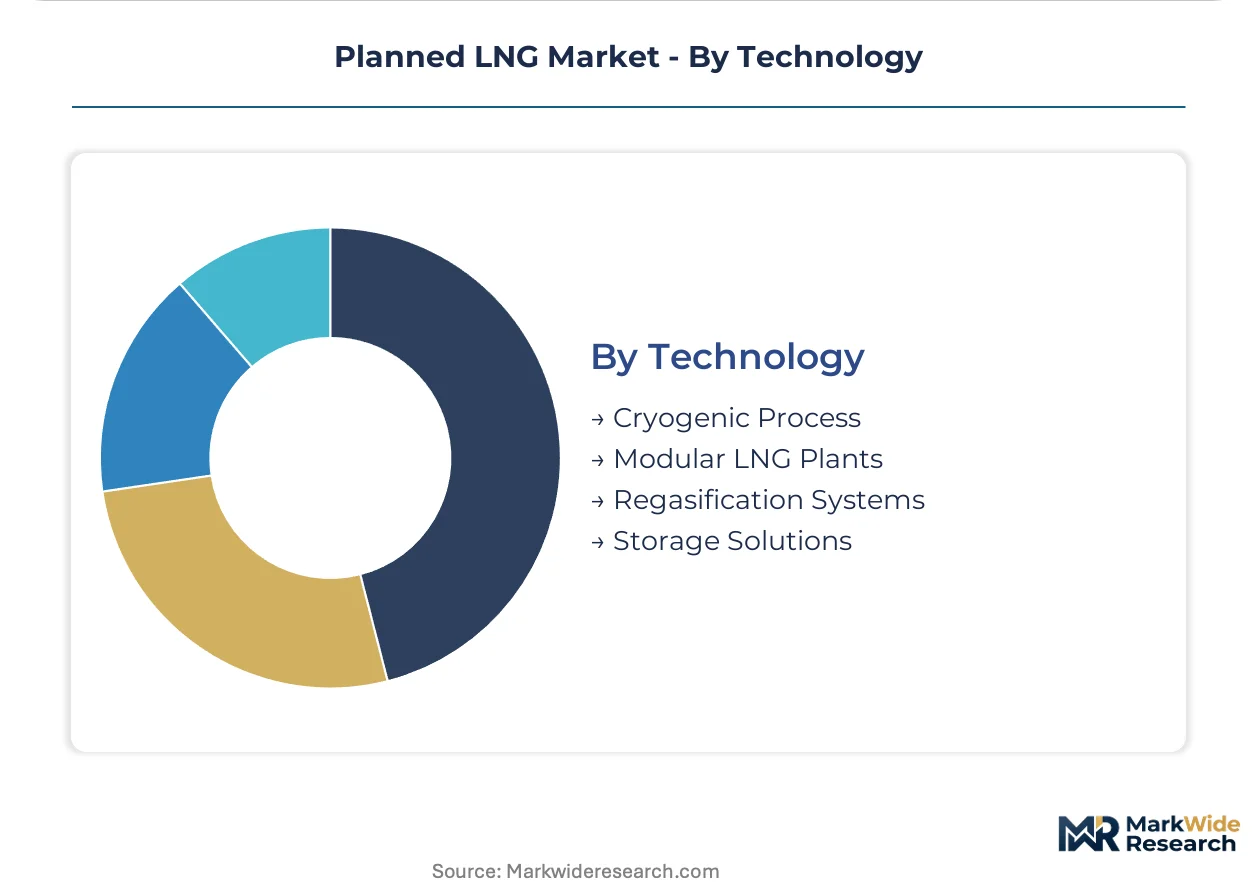
Technology:
Process architecture selection determines carbon intensity, operational flexibility, and maintenance requirements.
- Cryogenic Process:Conventional refrigeration cycles using mixed refrigerant or cascade systems at minus 162 degrees Celsius. EPA supplemental environmental impact requirements are mandating continuous emissions monitoring at U.S. Gulf Coast installations.
- Modular LNG Plants:Standardized 1-2 MTPA train blocks enabling phased deployment and brownfield site repurposing. Texas and Louisiana developers are compressing front-end engineering from five years to thirty-six months.
- Regasification Systems:Open-rack vaporizers, submerged combustion units, and ambient air systems for LNG-to-gas conversion. CE marking obligations are reshaping European equipment procurement criteria.
- Storage Solutions:Full-containment tanks using 9% nickel steel and membrane systems for cargo containment. Japanese and Korean mills concentrate specialized cryogenic material supply.
Process efficiency favors cryogenic systems; deployment velocity favors modular plants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar commands premium pricing leverage through sovereign-backed project finance, while U.S. Gulf Coast developers absorb Henry Hub volatility to secure Asian offtake volumes. This asymmetry concentrates committed liquefaction capacity in Doha and Houston, with emerging supply corridors forming in East Africa and Southeast Asia.
United States
Texas and Louisiana brownfield sites attract private equity through phased modular deployment. FERC certification timelines compress project development cycles. Corpus Christi and Lake Charles anchor the Gulf Coast liquefaction corridor with stacked liquefaction trains.
Qatar
QatarEnergy anchors mega-project financing through joint venture structures with international oil companies. Sovereign guarantee mechanisms de-risk capital pools for North Field expansion. Ras Laffan Industrial City concentrates cryogenic processing infrastructure and dedicated fleet arrangements.
Mozambique
Offshore stranded gas fields drive floating LNG adoption without pipeline shorebase requirements. National petroleum regulator oversight shapes environmental compliance timelines. Coral South development anchors the Rovuma Basin liquefaction corridor.
Japan
Trading houses displace oil-linked pricing with Henry Hub-indexed procurement structures. METI policy frameworks accelerate power sector fuel-switching agreements. Tokyo Bay and Osaka Bay regasification terminals prioritize winter supply security.
Vietnam
First-time LNG import demand builds maiden regasification terminals without legacy infrastructure constraints. Ministry of Industry and Trade licensing shapes terminal development schedules. Thi Vai and Son My anchor the southern Vietnam import corridor.
Planned LNG Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in cryogenic materials and modular train fabrication. The vendor base concentrates around integrated operators with sovereign-backed balance sheets and private developers leveraging brownfield site repurposing. Three archetypes dominate: national oil companies with captive upstream reserves, independent liquefaction developers using modular technology, and trading houses aggregating offtake portfolios. Competitive moves center on long-term contract structuring for project finance and phased capacity expansion to manage construction risk.
Within the integrated operator tier, Chevron Corporation and ExxonMobil Corporation exemplify upstream-to-export capability across multiple basins. Venture Global LNG anchors the independent developer archetype through standardized modular deployment at Gulf Coast brownfield sites. Royal Dutch Shell plc occupies a position spanning floating and onshore terminal formats with portfolio breadth across liquefaction and regasification infrastructure.
| Leading Market Players |
|---|
| Chevron Corporation |
| Royal Dutch Shell plc |
| ExxonMobil Corporation |
| Cheniere Energy, Inc. |
| Freeport LNG |
| Energy Transfer LP |
| ConocoPhillips Company |
| Equinor ASA |
| Venture Global LNG |
| Others |
Value Chain & Pricing Dynamics
Commodity volatility in Henry Hub natural gas pricing determines both contract tier spreads and supply chain configuration across liquefaction project development. Japanese and South Korean utility buyers negotiate destination-flexible clauses that compress margin buffers for integrated operators, while modular developers in Texas and Louisiana exploit brownfield site repurposing to circumvent upstream feedstock concentration risks.
Pricing Analysis
Industrial OEM buyers anchor long-term offtake contract structures with oil-linked and Henry Hub-indexed pricing models. Price differentiation separates baseload power utilities with fifteen-year commitments from spot-market industrial offtakers seeking six-month tenors. Pricing pressure stems from grid-scale battery storage and renewable hydrogen displacing peak power demand previously served by LNG. Industrial process heat buyers exhibit highest price sensitivity; sovereign-backed national oil companies show lowest sensitivity due to captive upstream reserves.
Supply Chain Analysis
Upstream natural gas feedstock draws from Qatar, the United States, and Mozambique as primary liquefaction supply basins. Raw material dependencies center on specialized 9% nickel steel from Japanese and Korean mills, mixed refrigerant chemicals, and cryogenic compression equipment. Supply chain risk concentrates in single-source vulnerability for cryogenic storage tank fabrication. Distribution runs through dedicated LNG carrier fleets under long-term charter arrangements to Asian regasification terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Asian utility procurement consortia, with Japanese trading houses and South Korean power generators consolidating offtake negotiation leverage through multi-terminal portfolio approaches.
For Market Incumbents: Harden project finance structures against Henry Hub volatility exposure through integrated upstream-to-export capability expansion. Chevron Corporation and ExxonMobil Corporation exemplify basin diversification across Qatar, Mozambique, and U.S. Gulf Coast developments. Defend against modular liquefaction challengers by accelerating brownfield capacity additions at Corpus Christi and Lake Charles corridors. For New Entrants and Emerging Players: Build out medium-scale modular deployment at repurposed industrial sites in Texas and Louisiana to exploit FERC certification timeline advantages. Vietnam and Bangladesh present penetrable white-space demand as first-time LNG importers constructing maiden regasification terminals without legacy infrastructure constraints. Target power generation offtake through fifteen-year indexed contracts with destination flexibility clauses. For Investors and Strategic Acquirers: Independent liquefaction developers with standardized modular technology and brownfield site control represent acquisition targets with asymmetric upside exposure. Long-term viability hinges on carbon capture integration qualifying for U.S. IRA production tax credits. Watch EPA supplemental environmental impact requirement enforcement intensity as inflection indicator for permitting timeline risk.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Liquefaction Capacity Buildout | Venture Global LNG compresses front-end engineering timelines from five years to thirty-six months at Gulf Coast brownfield sites. |
| Long-term Offtake Agreement Structuring | Japanese trading houses displace oil-linked pricing with Henry Hub-indexed contracts anchoring project finance. |
| Carbon Capture Integration Program | Post-combustion CCS retrofits at Texas and Louisiana plants qualify for U.S. IRA production tax credits. |
| Floating LNG Technology Licensing | Mozambique and Tanzania deployments unlock stranded gas reserves without pipeline shorebase requirements. |
| Destination Flexibility Clause Negotiation | South Korean and Taiwanese power sector tenders pivot toward fifteen-year indexed contracts with cargo redirection rights. |
Study Parameters
Cross-validation between primary interviews with LNG project developers, EPC contractors, utility procurement officers, and shipping operators anchors the qualitative findings. Secondary validation draws from FERC certification filings, EIA natural gas data, IEA market reports, and project finance database disclosures. Bottom-up capacity aggregation and top-down demand modeling triangulate volume estimates across the analysis window.
Calibration against historical project completion timelines and offtake contract execution rates refines the analytical framework. Segmentation dimensions span facility type, capacity class, end-use sector, and technology platform. CAGRs derive from capacity commitment trajectories and demand elasticity modeling. Forecast inputs incorporate EPA regulatory timeline assumptions and Asian utility procurement pattern shifts.
The forecast holds incumbent behavior within observed patterns; aggressive moves by modular liquefaction specialists or sovereign-backed national oil companies would shift outcomes. Regulatory acceleration under EU Green Deal methane standards or FERC certification streamlining represents specific revision risks. Cross-checking against IEA World Energy Outlook demand benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Drilling Mud Desander and Desilter Market
Oil & Gas
Gulf of Mexico Oil and Gas Upstream Market
Oil & Gas
Mining and Oil & Gas Fasteners Market
Oil & Gas
Subsea Multiphase Flowmeter Market
Oil & Gas
Oil & Gas Defoaming Separator Market
Oil & Gas
Africa Drilling and Completion Fluids Market
Oil & Gas
Oil and Gas Hose Assemblies Market
Oil & Gas
Drilling Fluids Market
Oil & Gas
Mud Logging Unit Market
Oil & Gas
Zonal Isolation Market
Oil & Gas
South Korea Oil and Gas Market
Oil & Gas
Multi-Point Ground Flares (MPGF) Market
Oil & Gas
Frac Tree Market
Oil & Gas
China Oil and Gas Market
Oil & Gas
India Oil and Gas Midstream Market
Oil & Gas
Oil and Gas Swell Packers Market