
 Critical Care Antiarrhythmic Drugs Market | 2026-2036
Critical Care Antiarrhythmic Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Critical Care Antiarrhythmic Drugs Market Analysis
Generic lidocaine is broadening cost-accessible options in acute ventricular arrhythmia protocols, displacing premium branded alternatives in price-sensitive hospital formularies. Pfizer leverages its manufacturing scale to sustain supply chain reliability across North American intensive care units. Sanofi anchors its position through deep specialization in intravenous amiodarone formulations for emergency settings.
Critical care antiarrhythmic drugs comprise pharmaceutical agents administered in acute settings to restore normal cardiac rhythm through modulation of ion channel activity, with intravenous formulations requiring precise titration parameters for hemodynamic stability. These agents serve primarily to prevent sudden cardiac death and stabilize patients during ventricular fibrillation, pulseless ventricular tachycardia, or hemodynamically unstable tachyarrhythmias. The product type dimension shows amiodarone occupying the dominant share due to its broad efficacy spectrum, while sotalol competes in niche atrial arrhythmia protocols with stricter monitoring requirements. Among delivery modes, intravenous administration leads in critical care revenue contribution because oral bioavailability constraints exclude per-os routes from emergency stabilization scenarios.
The FDA's Risk Evaluation and Mitigation Strategy for QT-prolonging agents shapes clinical trial design and post-market surveillance obligations for manufacturers seeking acute-care indications. EMA's cardiovascular safety guidelines under the MDR framework impose additional electrophysiological monitoring standards on European market entrants. Health Canada's PMRA aligns with ICH E14 guidance, creating transatlantic convergence on cardiac safety pharmacology requirements. Stakeholders must monitor evolving regulatory divergence between stringent QT liability thresholds and emerging precision-dosing technologies that could reshape risk stratification paradigms.
Market Dynamics
The FDA's tightening QT-prolonging drug guidance is compressing development timelines and forcing manufacturers to front-load cardiac safety pharmacology investment before Phase II trials.
Growth Catalysts
- Aging demographics in the United States:Hospital emergency departments are expanding intravenous antiarrhythmic protocols for acute cardiac stabilization as cardiovascular disease burden intensifies among patients over 65.
- EMA's MDR cardiovascular safety framework:Electrophysiological monitoring standards are creating regulatory convergence that streamlines multi-jurisdiction trial design for acute-care indications.
- Precision-dosing technologies:Algorithm-guided titration systems are reducing adverse event rates in intensive care settings and expanding the treatable patient pool.
Market Restraints
- Active pharmaceutical ingredient concentration:Lidocaine and amiodarone precursor supply clusters in India and China, creating geographic vulnerability to export restrictions or quality enforcement actions.
- FDA Risk Evaluation and Mitigation Strategy compliance costs:Post-market surveillance obligations for QT-prolonging agents require dedicated pharmacovigilance infrastructure that elevates fixed costs for new entrants.
- Substitution pressure from catheter ablation:Electrophysiology labs are expanding non-pharmacological rhythm control procedures for stable atrial arrhythmias, narrowing the addressable population for chronic oral antiarrhythmics.
Strategic Opportunities
- Underpenetrated emergency medicine networks in Brazil:ANVISA's streamlined approval pathway for essential medicines creates first-mover potential for intravenous formulation sponsors willing to establish local manufacturing partnerships.
- Health Canada's alignment with ICH E14:Transatlantic cardiac safety pharmacology convergence reduces redundant testing burden for sponsors pursuing simultaneous US-Canada filings.
- Closed-loop infusion systems:Integration of real-time ECG monitoring with automated dose adjustment is opening protocol standardization contracts with integrated delivery networks.
Industry Challenges
- Electrophysiology specialist scarcity:Intensive care units lack sufficient trained personnel to manage complex antiarrhythmic titration protocols, forcing reliance on telemedicine consultation models with variable response latency.
- Legacy formulary contract lock-in:Hospital purchasing cooperatives negotiate multi-year agreements with incumbent suppliers, creating switching friction even when clinical evidence favors alternative agents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Critical Care Antiarrhythmic Drugs Market |
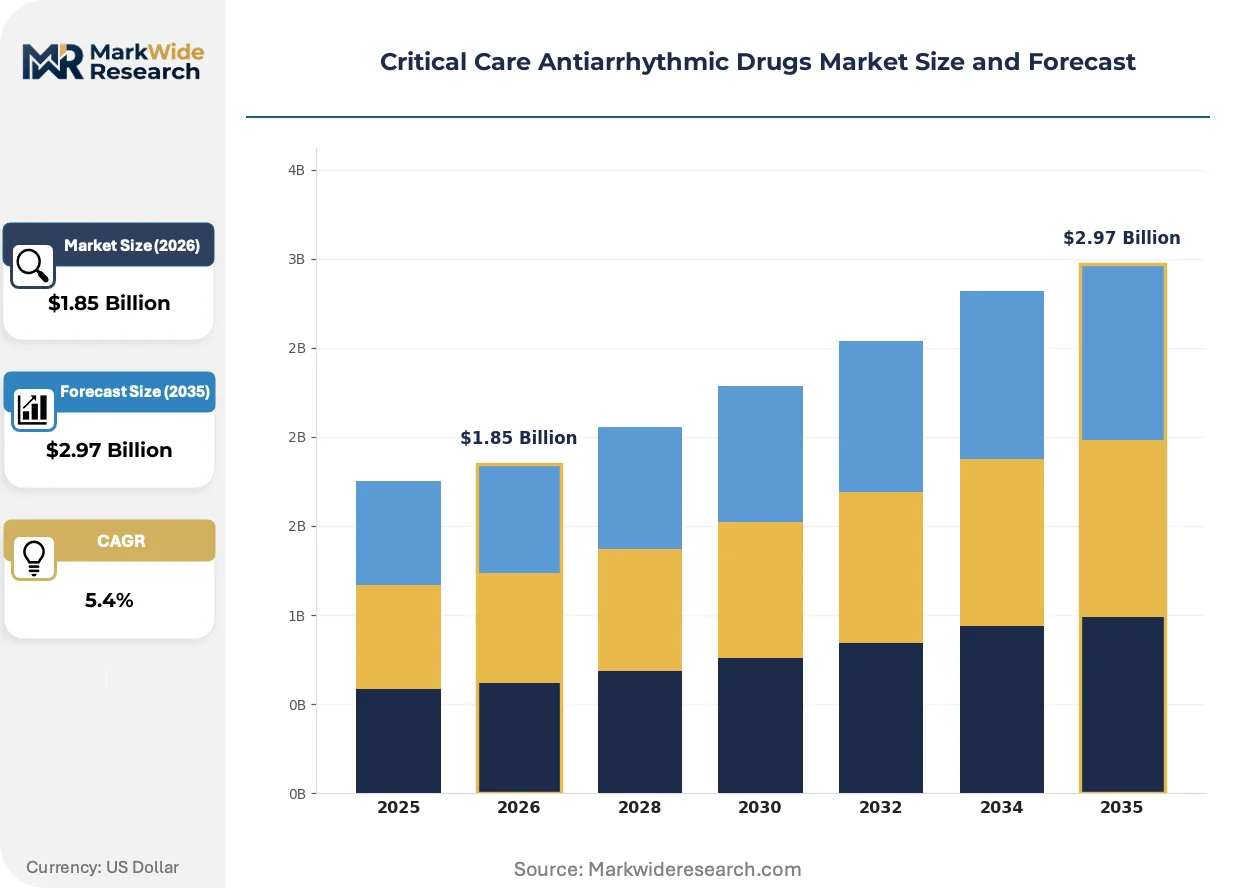
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sotalol, Amiodarone, Dronedarone, Flecainide End User: Hospitals, Cardiology Clinics, Emergency Rooms, Surgical Centers Delivery Mode: Intravenous, Oral, Intramuscular, Inhalation Application: Atrial Fibrillation, Ventricular Tachycardia, Supraventricular Tachycardia, Cardiac Arrest |
| Companies Covered | Sanofi, Pfizer, Viatris, Baxter International, Mayne Pharma, GlaxoSmithKline, Novartis, Upsher-Smith Laboratories, Amomed Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Critical Care Antiarrhythmic Drugs Market Emerging Trajectories
Acute cardiac care is experiencing a technology-driven compression of therapeutic decision windows, with automation and real-time biomonitoring displacing traditional weight-based dosing protocols.
Closed-loop smart infusion pumps with integrated arrhythmia detection algorithms are overtaking conventional volumetric pumps in tertiary hospital intensive care units. Cardiac surgery departments and electrophysiology labs in the United States and Germany are piloting these systems for post-operative atrial fibrillation management. The technology is compressing time-to-therapeutic effect and reducing nursing workload during high-acuity events.
EMA's Medical Device Regulation is imposing electrophysiological monitoring standards on combination products that incorporate drug-device delivery systems. Manufacturers must now submit integrated clinical evidence packages addressing both pharmaceutical and hardware safety endpoints. Intravenous antiarrhythmic sponsors with pre-filled syringe or infusion bag formats are restructuring regulatory teams to address MDR technical documentation requirements.
Hospital purchasing cooperatives are consolidating formulary decisions through centralized value-analysis committees that unbundle drug acquisition from device provision. Integrated delivery networks in the United States are replacing individual hospital pharmacy autonomy with regional therapeutic class standardization. This concentration is visible most acutely in the southeastern states, where multi-hospital systems are negotiating sole-source contracts for entire antiarrhythmic portfolios.
Critical Care Antiarrhythmic Drugs Market Segmentation
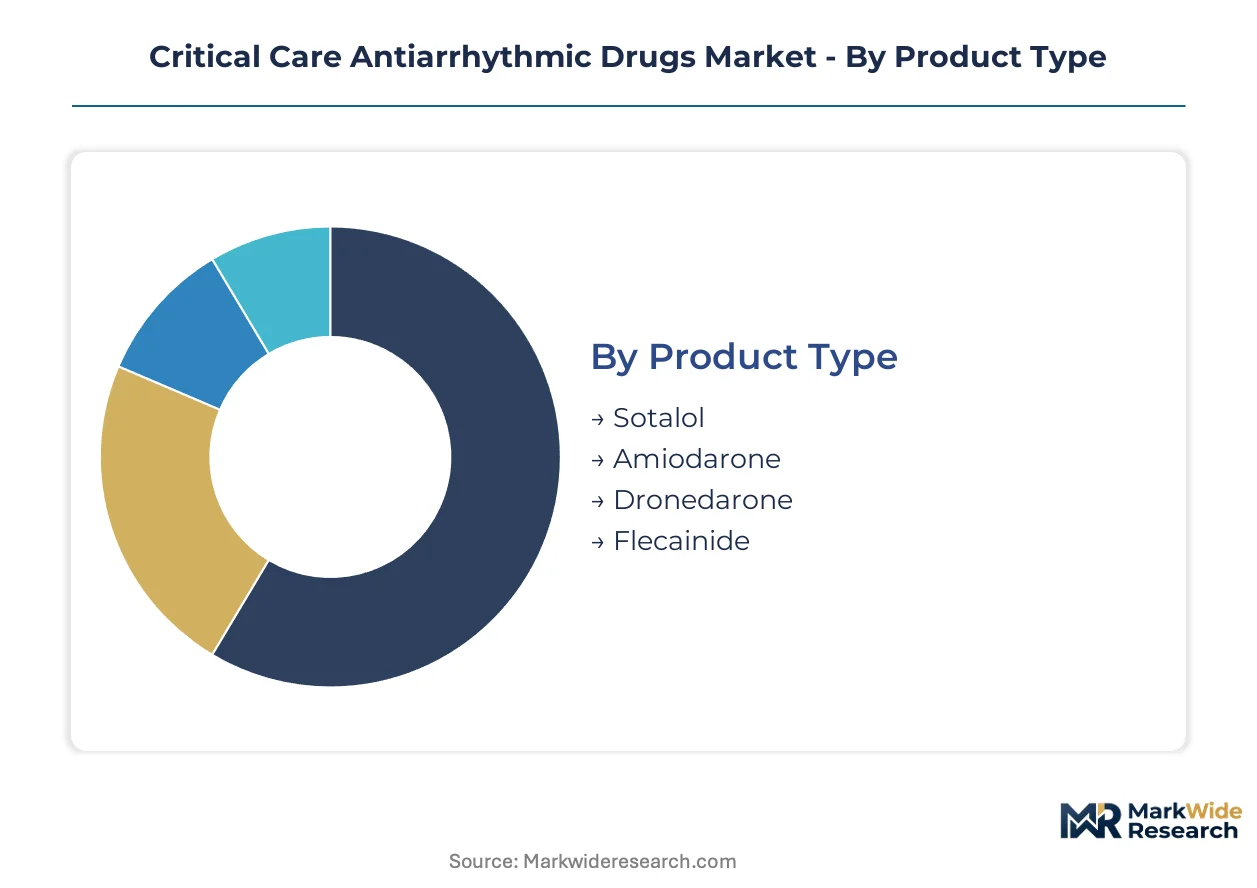
Segmentation in critical care antiarrhythmics reveals how formulation choices, care settings, and administration routes determine clinical utility and procurement economics. Hospital formularies balance broad-spectrum efficacy against monitoring infrastructure requirements when selecting agents across these dimensions.
Product Type:
Customization versus standardization tension runs deepest here, with single-mechanism agents offering titration precision against multi-channel blockers delivering protocol simplicity.
- Amiodarone:Multi-channel electrophysiological blocker with sodium, potassium, and calcium channel activity plus non-competitive beta-adrenergic antagonism. Demand concentrates in United States emergency departments managing polymorphic ventricular tachycardia where its broad efficacy reduces need for rapid reclassification. FDA REMS requirements for QT monitoring constrain new entrant competition.
- Sotalol:Pure potassium channel blocker with additional non-selective beta-adrenergic antagonism requiring mandatory inpatient initiation with continuous telemetry. Cardiology clinics in Germany favor its use for atrial fibrillation rhythm control where electrophysiology lab backup enables safe loading protocols.
- Dronedarone:Amiodarone analogue with reduced iodine content and modified lipophilicity profile designed for outpatient oral maintenance.
- Flecainide:Class IC sodium channel blocker restricted to structurally normal hearts due to proarrhythmic risk in ischemic tissue.
Most installed capacity flows through amiodarone formulations. Expansion is steepest in sotalol as electrophysiology monitoring infrastructure proliferates.
End User:
Cost tier stratification separates capital-intensive hospital systems from ambulatory settings operating on procedure-based reimbursement.
- Hospitals:Comprehensive acute care infrastructure with 24-hour pharmacy, telemetry, and rapid response capabilities enabling high-risk antiarrhythmic protocols. United States tertiary centers command premium pricing for intravenous formulations through GPO-negotiated sole-source contracts.
- Emergency Rooms:High-acuity, time-compressed environments where automated defibrillation protocols and crash cart standardization drive formulary concentration around amiodarone and lidocaine.
- Cardiology Clinics:Outpatient rhythm management facilities with Holter monitoring and event recorder capabilities supporting oral antiarrhythmic initiation.
- Surgical Centers:Ambulatory facilities with limited overnight capacity restricting antiarrhythmic use to perioperative prophylaxis and immediate post-operative stabilization.
Revenue concentration sits with hospital inpatient admissions. Surgical centers are gaining share fastest as same-day cardiac procedures expand.
Delivery Mode:
Volume economics favor intravenous manufacturing scale, while oral and alternative routes serve niche compliance and compliance-sensitive populations.
- Intravenous:Direct vascular administration with immediate bioavailability and precise titration control for hemodynamic instability. German intensive care units are piloting closed-loop infusion systems integrating real-time QT monitoring with automated dose adjustment.
- Oral:Maintenance therapy route with delayed onset unsuitable for acute termination but essential for chronic rhythm control and outpatient cost containment.
- Intramuscular:Alternative parenteral route for prehospital settings where intravenous access is delayed or contraindicated.
- Inhalation:Experimental pulmonary delivery modality under investigation for rapid systemic absorption without first-pass metabolism.
Manufacturing throughput clusters on intravenous formulations. Inhalation delivery is climbing the fastest as device-drug combination products advance through clinical validation.
Application:
Margin structure separates life-threatening arrhythmia indications commanding premium pricing from chronic management protocols facing generic substitution.
- Ventricular Tachycardia:Wide-complex tachyarrhythmia with pulseless or hemodynamically unstable presentations requiring immediate electrical or pharmacological cardioversion. United States emergency medicine protocols mandate amiodarone as first-line pharmacological intervention when defibrillation is deferred or unsuccessful.
- Atrial Fibrillation:Supraventricular arrhythmia with heterogeneous presentation from asymptomatic to rapid ventricular response with hemodynamic compromise. Rate versus rhythm control decisions drive product selection toward beta-blockers, calcium channel antagonists, or antiarrhythmics based on comorbidity profile.
- Supraventricular Tachycardia:Narrow-complex re-entrant tachycardias often responsive to vagal maneuvers or adenosine with antiarrhythmics reserved for refractory cases.
- Cardiac Arrest:Pulseless electrical activity or asystole presentations where antiarrhythmics play adjunctive role to advanced cardiac life support algorithms.
Clinical trial investment concentrates on ventricular tachycardia indications. Atrial fibrillation represents the fastest-expanding addressable population as aging demographics escalate disease prevalence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital networks command the largest share of critical care antiarrhythmic utilization, with tertiary cardiac centers in Boston, Cleveland, and Houston setting protocol standards that diffuse through integrated delivery networks.
United States
FDA Risk Evaluation and Mitigation Strategy requirements for QT-prolonging agents shape clinical trial investment and post-market surveillance obligations for manufacturers pursuing acute-care indications. Hospital emergency departments in the Southeast are consolidating formulary decisions through regional purchasing cooperatives that negotiate sole-source contracts for intravenous amiodarone and lidocaine portfolios.
Germany
EMA Medical Device Regulation electrophysiological monitoring standards impose integrated safety documentation on drug-device combination products entering European critical care markets. Intensive care units in Bavaria and North Rhine-Westphalia are piloting closed-loop infusion systems that automate dose adjustment based on real-time QT interval telemetry.
Japan
PMDA cardiovascular safety guidelines align with ICH E14 standards, creating streamlined pathways for sponsors seeking simultaneous US-Japan filings for intravenous antiarrhythmic indications. Tokyo and Osaka metropolitan hospital systems maintain high per-capita utilization of precision-dosing technologies for post-operative atrial fibrillation management.
Brazil
ANVISA streamlined approval pathways for essential medicines create first-mover opportunities for intravenous formulation sponsors establishing local manufacturing partnerships. São Paulo state emergency medicine networks are expanding access to acute cardiac stabilization protocols as hospital infrastructure investments accelerate.
Canada
Health Canada PMRA alignment with ICH E14 guidance reduces redundant cardiac safety pharmacology testing for sponsors pursuing simultaneous US-Canada regulatory submissions. Ontario and Quebec hospital systems are standardizing critical care antiarrhythmic protocols through provincial formularies that emphasize cost-accessible generic options.
Critical Care Antiarrhythmic Drugs Market Vendor Landscape
Global majors compete with regional champions across manufacturing scale and regulatory navigation capabilities. Market structure concentrates around diversified pharmaceutical conglomerates with established hospital supply chain relationships and specialized critical care-focused operators with deep formulation expertise. Three archetypes dominate: large-cap diversified manufacturers with intensive care unit distribution infrastructure, mid-size parenteral drug specialists with flexible manufacturing networks, and generic injectable producers competing on price-accessibility. Capacity expansion and strategic portfolio diversification through in-house production of active pharmaceutical ingredients represent the dominant competitive moves.
Within the diversified pharmaceutical tier, Sanofi and Pfizer occupy positions anchored by manufacturing scale and supply chain reliability across North American intensive care units. Viatris exemplifies the generic-specialist archetype, representing cost-accessible alternatives that displace premium branded agents in price-sensitive hospital formularies.
| Leading Market Players |
|---|
| Sanofi |
| Pfizer |
| Viatris |
| Baxter International |
| Mayne Pharma |
| GlaxoSmithKline |
| Novartis |
| Upsher-Smith Laboratories |
| Amomed Pharma |
| Others |
Supply Flow & Price Mechanics
Hospital purchasing cooperative consolidation across the southeastern United States is compressing formulary slots and forcing manufacturers to absorb logistics premiums or cede shelf space to generic injectable producers. This procurement concentration reshapes supply chain economics as sponsors weigh direct distribution investments against GPO rebate structures.
Pricing Analysis
Active pharmaceutical ingredient cost pass-through from Indian and Chinese precursor suppliers governs contract pricing for intravenous amiodarone and lidocaine formulations. Three-tier pricing structure across premium branded, standard authorized generic, and economy multi-source injectables separates FDA REMS-compliant portfolios from price-accessible alternatives. Cost compression in the economy tier is intensifying because Viatris and regional generic houses are expanding capacity for pre-filled syringe formats. Emergency departments demonstrate lowest price sensitivity due to crash cart standardization protocols, while surgical centers negotiate aggressively on per-unit acquisition costs.
Supply Chain Analysis
Cold-chain freight premiums for temperature-sensitive parenteral formulations are elevating landed costs for European and Asian manufacturers serving North American intensive care units. API manufacturing concentrates in India, China, and Italy, with final formulation and sterile fill-finish clustering in the United States, Germany, and Ireland. Supply chains rest on amiodarone hydrochloride and lidocaine base inputs vulnerable to Indian export restriction policies. Single-source vulnerability permeates the pre-filled syringe segment where specialized elastomer component suppliers operate limited qualified facilities. Distribution runs through GPO-negotiated warehouse networks with regional redistribution centers serving integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in automated dosing system integration and captive API production, as precision-dosing premiums offset generic substitution pressure in emergency medicine protocols.
For Market Incumbents: Acquire closed-loop infusion technology platforms to preempt device-drug combination product competition from electrophysiology equipment manufacturers. Baxter International and Pfizer should expand sterile injectable capacity in Ireland to mitigate transatlantic logistics exposure. Defensive patent extension strategies around amiodarone formulation improvements can delay authorized generic entry. For New Entrants and Emerging Players: ANVISA's streamlined essential medicines pathway in Brazil opens a window for intravenous formulation sponsors establishing local manufacturing partnerships with São Paulo state hospital networks. Target underpenetrated emergency medicine cooperatives in Brazil's interior states where crash cart standardization lags metropolitan centers. Pursue pre-filled syringe format differentiation to bypass incumbent GPO contract lock-in. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap parenteral drug specialists possessing FDA-inspected sterile capacity and underutilized API fermentation infrastructure. Long-term viability hinges on electrophysiology monitoring convergence with drug delivery systems over the next decade. Monitor FDA guidance evolution on QT-prolonging agent REMS requirements as inflection signal for regulatory compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Production | Captive amiodarone precursor supply insulates against Indian export policy volatility. |
| Closed-Loop Infusion System Development | FDA MDR compliance for drug-device combinations opens protocol standardization contracts with IDNs. |
| Pre-Filled Syringe Format Expansion | EMA sterility assurance requirements favor sponsors with validated aseptic processing lines. |
| ANVISA Local Manufacturing Partnership | Brazilian hospital infrastructure investments create first-mover formulary positioning. |
| Precision-Dosing Algorithm Licensing | Telemedicine consultation latency in rural ICUs drives demand for automated titration support. |
Methodological Framework
Multiple input streams — regulatory filing databases, hospital procurement contract records, and API trade flow customs data — were reconciled against primary intelligence from formulary directors, critical care pharmacists, and GPO contracts managers. Secondary validation drew from FDA REMS documentation, EMA MDR technical files, ClinicalTrials.gov cardiovascular trial records, and ANVISA essential medicines registration pathways. Bottom-up demand modeling across end-user segments was cross-checked against top-down pharmaceutical market sizing from national health expenditure accounts.
Data-stream reconciliation enabled segmentation modeling across product type, delivery mode, application indication, and regional regulatory cluster throughout the projection horizon. CAGRs were derived from trend extrapolation of intensive care admission patterns, antiarrhythmic utilization rates per cardiac event, and generic substitution elasticities observed in hospital formulary transitions. Forecast inputs incorporated electrophysiology lab expansion trajectories, closed-loop infusion system adoption curves, and catheter ablation procedure growth as demand-side cross-elasticities.
Revisions become necessary when FDA REMS requirements for QT-prolonging agents materially expand post-market surveillance obligations, or when API supply disruptions from Indian enforcement actions exceed historical volatility bands. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Hydrocortisone Market
Pharmaceuticals
Asia-Pacific Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Urticaria Drugs Market
Pharmaceuticals
Isotretinoin Drugs Market
Pharmaceuticals
Structured Product Label Management Market
Pharmaceuticals
Spain Opioids Market
Pharmaceuticals
Homocystinuria Therapeutics Market
Pharmaceuticals
Clindamycin Palmitate Hcl Market
Pharmaceuticals
Valganciclovir Market
Pharmaceuticals
Anti-Parasitic Drugs Market
Pharmaceuticals
Europe G-CSF/PEG-G-CSF Market
Pharmaceuticals
Wilson Disease Drugs Market
Pharmaceuticals
Global Shingles Vaccine Market
Pharmaceuticals
North America Glucagon-Like Peptide-1 Agonists Market
Pharmaceuticals
Nuclear Medicines Radioisotopes Market
Pharmaceuticals
Oral Thin Film Drugs Market