
 Asia-Pacific Glucagon-Like Peptide-1 (GLP-1) Agonists Market | 2026-2036
Asia-Pacific Glucagon-Like Peptide-1 (GLP-1) Agonists Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Glucagon-Like Peptide-1 (GLP-1) Agonists Market Outlook
Project finance for biologics manufacturing is narrowing the competitive field to sponsors with balance-sheet depth. Novo Nordisk leverages its captive fermentation network across Denmark and China to sustain cost leadership in semaglutide supply. Eli Lilly anchors high-volume peptide production through contract manufacturing partnerships that compete on scale rather than asset ownership. Biocon Ltd. differentiates via vertically integrated insulin and peptide manufacturing in Bangalore, occupying a cost-efficient position for regional tender markets.
Glucagon-like peptide-1 agonists are synthetic analogues of the endogenous incretin hormone GLP-1, typically formulated as acylated peptides with fatty-acid side chains to extend plasma half-life beyond native hormone degradation. These agents stimulate glucose-dependent insulin secretion from pancreatic beta cells, forming a cornerstone of pharmacotherapy for type 2 diabetes and obesity. Semaglutide now leads product-type revenue pools across the Asia-Pacific, while oral formulations within the delivery-mode dimension represent the fastest-expanding access channel for treatment-naive patients. Hospitals retain the dominant end-user share for initiation protocols, though homecare settings capture margin expansion as once-weekly injectable regimens reduce clinical supervision requirements.
Japan's PMDA maintains stringent stability-testing requirements for peptide therapeutics, shaping formulation investments toward cold-chain resilience. China's NMPA and India's CDSCO enforce divergent bioequivalence standards for biosimilar GLP-1 entrants, fragmenting regulatory submission strategies across the region. The EU AI Act and GDPR extraterritorially influence clinical data platforms that Asia-Pacific sponsors use for multinational trials. Stakeholders must monitor how reimbursement negotiations in Australia's PBS and South Korea's HIRA reweight obesity versus diabetes indications, as these decisions will redirect promotional investment and prescriber education priorities without explicit timeline commitments.
Market Dynamics
China's NMPA biosimilar pathway reforms are compressing peptide therapeutic review timelines and concentrating manufacturing investment among sponsors with captive fermentation capacity across the region.
Growth Catalysts
- Obesity indication expansion:Endocrinology clinics in Japan and South Korea are scaling GLP-1 prescribing capacity for weight management protocols, redirecting promotional investment from diabetes monotherapy.
- Accelerated regulatory pathways:China's NMPA has streamlined biosimilar submissions for peptide therapeutics, reducing time-to-market for regional entrants competing on cost efficiency.
- Once-weekly formulation adoption:Extended-release injectable regimens are reducing clinical supervision requirements and shifting patient volumes toward homecare settings across metropolitan hospital networks.
Market Restraints
- Cold-chain infrastructure dependency:Peptide stability requirements mandate continuous refrigerated distribution, limiting access expansion into India's tier-two and tier-three cities lacking temperature-controlled logistics.
- Concentrated active pharmaceutical ingredient supply:Fermentation-based peptide production clusters in Denmark and select Chinese facilities, creating single-source vulnerability for regional formulation sponsors.
- Divergent bioequivalence standards:India's CDSCO and China's NMPA enforce non-harmonized biosimilar testing protocols, fragmenting clinical trial design and regulatory submission costs across the Asia-Pacific.
Strategic Opportunities
- Oral formulation penetration:Non-injectable GLP-1 delivery modes represent underdeveloped access channels for treatment-naive patient populations in Southeast Asian markets lacking injection infrastructure.
- Vertically integrated manufacturing:Sponsors with in-house production of both insulin and peptide analogues occupy cost-efficient positions for government tender markets across South Asia.
- Homecare channel expansion:Reduced dosing frequency is enabling direct-to-patient distribution partnerships that bypass traditional hospital pharmacy procurement in Australia's private insurance networks.
Industry Challenges
- Peptide synthesis workforce scarcity:Fermentation process engineering and acylation chemistry expertise concentrates in Bangalore and Shanghai hubs, constraining scale-up capacity for new market entrants.
- Stability-testing timeline compression:Japan's PMDA mandates extended real-time stability data for peptide therapeutics, extending development cycles and locking working capital in inventory.
- Reimbursement indication reweighting:Australia's PBS and South Korea's HIRA are recalibrating obesity versus diabetes coverage criteria without published timelines, forcing promotional strategy ambiguity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Glucagon-Like Peptide-1 (GLP-1) Agonists Market |
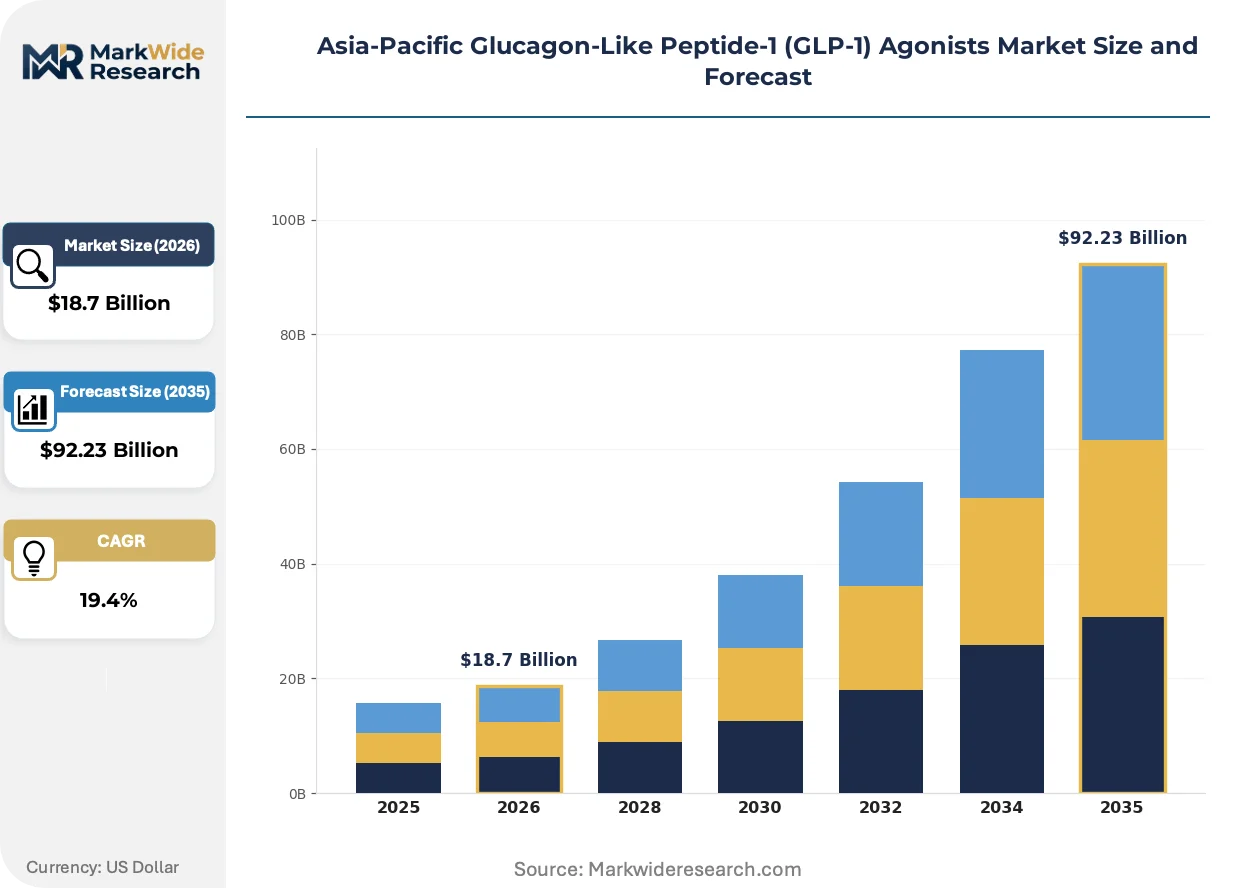
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $92.23 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liraglutide, Semaglutide, Dulaglutide, Exenatide Delivery Mode: Subcutaneous Injection, Oral, Intravenous, Inhalation End User: Hospitals, Clinics, Homecare, Pharmacies Application: Type 2 Diabetes, Obesity, Cardiovascular Health, Metabolic Syndrome |
| Companies Covered | Novo Nordisk, Eli Lilly and Company, AstraZeneca, Sanofi, Biocon Ltd., Innovent Biologics, Takeda Pharmaceutical Company, Daiichi Sankyo, Boehringer Ingelheim, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Glucagon-Like Peptide-1 (GLP-1) Agonists Market Strategic Shifts
Digital integration across clinical trial platforms and supply chain monitoring is compressing development timelines while regulatory divergence between national agencies fragments standardization efforts.
Continuous manufacturing technologies for peptide synthesis are digitizing batch record management and real-time quality monitoring. Contract development and manufacturing organizations in Singapore and South Korea are adopting these platforms to reduce deviation rates and accelerate technology transfer. This digitization is compressing the gap between clinical-scale and commercial-scale production economics for regional biosimilar sponsors.
Japan's PMDA has tightened stability-testing requirements for thermally sensitive biologics, mandating real-time data over accelerated studies for peptide therapeutics. This regulatory friction is extending formulation development timelines and redirecting investment toward cold-chain resilience infrastructure. Domestic sponsors are responding by partnering with specialized logistics providers rather than building captive distribution networks.
Hospital procurement committees across China's tier-one cities are consolidating GLP-1 purchasing through centralized tender platforms, displacing fragmented physician-directed prescribing. Volume-based procurement is compressing margin structures for originator molecules while creating entry points for biosimilar competitors. This concentration is most visible in Beijing and Shanghai hospital networks, where formulary placement now determines regional market access.
Asia-Pacific Glucagon-Like Peptide-1 (GLP-1) Agonists Market Segmentation
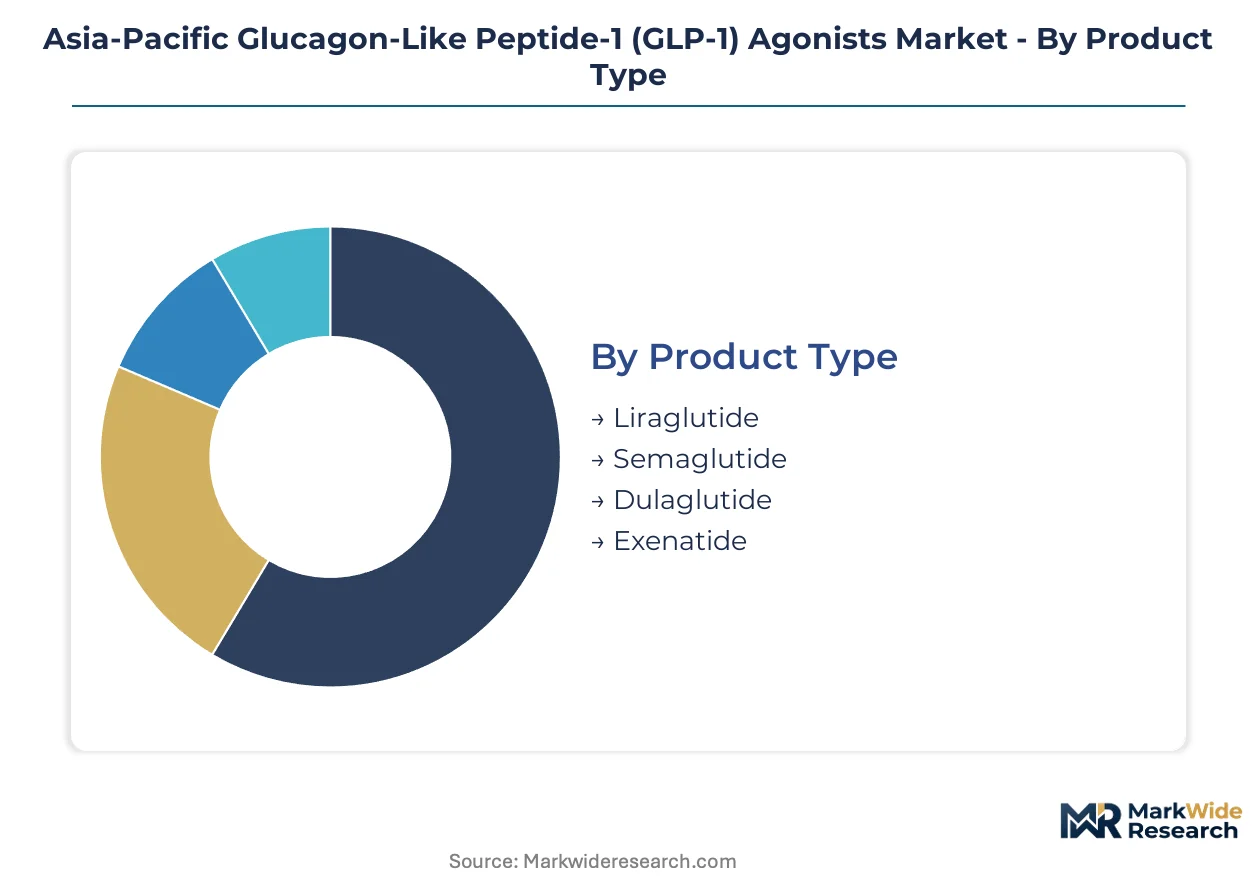
GLP-1 agonist segmentation reflects divergent clinical protocols and reimbursement architectures across Asia-Pacific healthcare systems. Product-type concentration determines manufacturing scale economics, while delivery-mode differentiation shapes patient adherence and channel economics in markets with uneven injection infrastructure.
Product Type:
Mature molecules anchor volume commitments while emerging analogues capture indication expansion.
- Semaglutide:Acylated peptide with C18 fatty diacid side chain enabling albumin binding and extended half-life. Endocrinology clinics in Japan and South Korea prioritize this agent for obesity protocols, displacing earlier-generation prescribing patterns.
- Liraglutide:First-generation acylated GLP-1 analogue requiring daily administration. China's tier-one hospital networks retain substantial volume for diabetes monotherapy where reimbursement pathways remain established.
- Dulaglutide:Fusion protein construct with reduced immunogenicity profile.
- Exenatide:Synthetic exendin-4 analogue with twice-daily and extended-release formulations.
Semaglutide handles the majority of throughput; dulaglutide is gaining share fastest in government tender markets.
Delivery Mode:
Patient convenience hierarchies reshape channel economics and cold-chain requirements.
- Subcutaneous Injection:Pen-device and prefilled syringe formats dominate clinical initiation. Once-weekly depot formulations reduce dosing burden and shift patient volumes toward homecare settings across Australia's private insurance networks.
- Oral:Semaglutide tablet formulation using absorption enhancer technology for gastric permeation. Southeast Asian markets lacking injection infrastructure represent primary expansion terrain for treatment-naive populations.
- Intravenous:Hospital-confined administration for acute metabolic decompensation.
- Inhalation:Investigational delivery pathway with pulmonary deposition challenges.
Subcutaneous injection handles the majority of throughput; oral delivery is expanding most quickly in access-limited markets.
End User:
Site-of-care migration restructures procurement relationships and margin capture.
- Hospitals:Tertiary centers in Beijing, Shanghai, and Tokyo control initiation protocols and formulary placement. Centralized tender platforms in China's tier-one cities consolidate purchasing volume and compress originator margins.
- Homecare:Direct-to-patient distribution partnerships bypass traditional pharmacy procurement. Reduced dosing frequency enables this channel expansion in South Korea's metropolitan corridors.
- Clinics:Endocrinology specialty practices in India and Indonesia.
- Pharmacies:Retail dispensing for maintenance therapy in Australia's PBS framework.
Hospitals handle the majority of throughput; homecare is climbing the fastest on share.
Application:
Indication breadth determines prescriber target lists and promotional investment allocation.
- Type 2 Diabetes:Established therapeutic cornerstone with decades of outcomes data. India's metropolitan specialty chains and China's hospital networks anchor volume concentration for glycemic control protocols.
- Obesity:Weight management indication driving capacity expansion in Japan's endocrinology clinics. Australia's PBS and South Korea's HIRA are recalibrating coverage criteria without published timelines, creating strategic ambiguity.
- Cardiovascular Health:Risk reduction endpoint with evolving evidentiary requirements.
- Metabolic Syndrome:Cluster indication with heterogeneous diagnostic thresholds.
Type 2 diabetes handles the majority of throughput; obesity is the fastest mover on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NMPA biosimilar pathway reforms are compressing peptide therapeutic review timelines and redirecting manufacturing investment toward sponsors with captive fermentation capacity across the region.
China
Beijing and Shanghai hospital networks anchor volume concentration through centralized tender platforms that displace fragmented physician-directed prescribing. NMPA's accelerated biosimilar pathway compresses time-to-market for regional entrants competing on cost efficiency. Yangtze River Delta manufacturing clusters host captive fermentation facilities supplying semaglutide active pharmaceutical ingredient to domestic formulation sponsors.
Japan
Tokyo endocrinology clinics scale GLP-1 prescribing capacity for obesity management protocols, redirecting promotional investment from diabetes monotherapy. PMDA mandates extended real-time stability data for peptide therapeutics, extending formulation development cycles. Kanto region sponsors partner with specialized logistics providers rather than building captive cold-chain distribution networks.
India
Metropolitan specialty chains in Mumbai and Delhi concentrate demand for glycemic control protocols among treatment-naive patient populations. CDSCO enforces bioequivalence standards that fragment from China's NMPA protocols, complicating regional clinical trial design. Bangalore's vertically integrated insulin and peptide manufacturing hub occupies cost-efficient positions for government tender markets across South Asia.
South Korea
Seoul Capital Area endocrinology practices expand obesity indication prescribing as HIRA recalibrates coverage criteria without published timelines. MFDS maintains alignment with international peptide stability standards while accelerating review for locally manufactured biosimilars. Busan-Ulsan corridor contract manufacturing organizations adopt continuous manufacturing technologies to reduce deviation rates.
Australia
Private insurance networks enable direct-to-patient distribution partnerships that bypass traditional hospital pharmacy procurement for once-weekly injectable regimens. PBS reimbursement negotiations reweight obesity versus diabetes indications, forcing promotional strategy ambiguity. Sydney and Melbourne tertiary centers control initiation protocols while homecare channels capture margin expansion from reduced dosing frequency.
Asia-Pacific Glucagon-Like Peptide-1 (GLP-1) Agonists Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure that concentrates around fermentation-capable manufacturers and formulation-scale sponsors. The competitive field narrows to sponsors with balance-sheet depth for biologics manufacturing project finance. Three archetypes dominate: originator multinationals with captive supply networks, regional biosimilar specialists with vertical integration, and contract manufacturing organizations competing on scale. Capacity expansion and regulatory submission acceleration constitute the dominant competitive moves.
Among originator multinationals with Danish and American roots, Novo Nordisk and Eli Lilly exemplify the fermentation-capable archetype that anchors high-volume peptide production through distinct asset strategies. Biocon Ltd. occupies a position within the vertically integrated specialist tier, representing cost-efficient manufacturing for regional tender markets. These three anchors illustrate how supply-side configuration determines competitive positioning across NMPA, PMDA, and CDSCO regulatory jurisdictions.
| Leading Market Players |
|---|
| Novo Nordisk |
| Eli Lilly and Company |
| AstraZeneca |
| Sanofi |
| Biocon Ltd. |
| Innovent Biologics |
| Takeda Pharmaceutical Company |
| Daiichi Sankyo |
| Boehringer Ingelheim |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Busan maritime corridor's refrigerated container rates directly compress margin structures for peptide API shippers while amplifying price spreads between cold-chain-compliant and ambient-distribution formulations across Asia-Pacific hospital networks.
Pricing Analysis
Certification level (NMPA/PMDA/MFDS-grade) creates the primary spread between originator and biosimilar GLP-1 agonists, with daily-administration liraglutide commanding premium positioning against weekly semaglutide alternatives. Volume-based procurement through China's centralized tender platforms is intensifying cost compression for diabetes indications while obesity protocols retain pricing power. Government tender markets across South Asia exhibit highest price sensitivity; private insurance networks in Australia's metropolitan corridors show lowest sensitivity due to direct-to-patient reimbursement pathways.
Supply Chain Analysis
Upstream fermentation feedstock for peptide synthesis concentrates in Denmark, China's Yangtze River Delta, and Bangalore's biologics corridor. Acylated peptide production draws from recombinant yeast cultures, C18 fatty diacid side chains, and specialized chromatography resins. Single-source vulnerability clusters around Danish-origin semaglutide API, exposing regional formulators to trans-shipment disruption. Distribution runs through hospital-centric procurement committees in tier-one Chinese cities and specialty pharmacy networks in Australia's PBS framework.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation process engineering expertise anchors competitive viability, with fewer than six regional hubs producing GLP-1 peptide chemists at commercial scale. This capability scarcity rewards sponsors who lock in talent pipelines and captive manufacturing assets before biosimilar pathway maturation accelerates.
For Market Incumbents: Build regulatory data moats through extended real-time stability studies that exceed PMDA minimums and extend biosimilar time-to-market. Novo Nordisk's captive fermentation network across Denmark and China exemplifies asset control that limits competitor API access. Anchor capacity expansion in Yangtze River Delta clusters to exploit NMPA accelerated review timelines for locally manufactured peptides.
For New Entrants and Emerging Players: Establish a beachhead in oral semaglutide distribution across Southeast Asian markets lacking injection infrastructure, where cold-chain dependency excludes incumbent depot formulations. India's metropolitan specialty chains offer penetrable entry points through CDSCO bioequivalence pathways that diverge from NMPA standards, creating regulatory arbitrage for regionally focused sponsors. Partner with Singapore-based contract manufacturers adopting continuous peptide synthesis platforms to reduce deviation-driven batch losses.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational pharmaceutical parents spinning off peptide manufacturing assets that lack obesity-indication positioning. Long-term viability hinges on sponsors capturing both diabetes and weight management reimbursement across Australia's PBS and South Korea's HIRA frameworks. Watch for HIRA's obesity coverage recalibration as the inflection signal that redirects promotional investment and unlocks valuation step-ups for indication-diversified assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | NMPA biosimilar acceleration compresses review timelines for peptide therapeutics against PMDA's extended stability mandates. |
| Manufacturing Scale-Up | Continuous fermentation technology adoption in Busan-Ulsan corridors reduces batch deviation rates for regional biosimilar sponsors. |
| Pipeline Diversification | Oral formulation development targets Southeast Asian access gaps where injection infrastructure remains underdeveloped. |
| Long-term Supply Agreement | Captive API offtake contracts with Yangtze River Delta fermentation facilities secure semaglutide precursor availability. |
| Reimbursement Strategy | PBS obesity indication lobbying redirects formulary placement decisions toward weight management protocols in Australian hospital networks. |
Study Parameters
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists and refined through secondary validation against NMPA filings, PMDA submissions, ClinicalTrials.gov records, and hospital formulary databases. Bottom-up prescription volume modeling and top-down biologics market sizing were triangulated to constrain estimate variance across the Asia-Pacific region.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, delivery mode, end-user site of care, and application indication. CAGRs were derived from patient population growth, reimbursement expansion scenarios, and biosimilar entry timing assumptions. Fermentation capacity buildout schedules and regulatory pathway velocity served as industry-specific forecast inputs.
Stress conditions across reimbursement reweighting, cold-chain disruption, and biosimilar approval acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about indication expansion timelines and manufacturing scale economics. Cross-checking against CDSCO and MFDS regulatory disclosure patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Anti-Fungal Drugs Market
Pharmaceuticals
Trenbolone Acetate Market
Pharmaceuticals
Global Corticosteroids Market
Pharmaceuticals
Stomach Cancer Drugs Market
Pharmaceuticals
OTC Analgesic Market
Pharmaceuticals
Minocycline Hydrochloride Market
Pharmaceuticals
Glioblastoma Treatment Drugs Market
Pharmaceuticals
Global Janus Kinase Inhibitor (JAK) Market
Pharmaceuticals
Hypertensive Emergency Medications Market
Pharmaceuticals
Iodine Deficiency Drug Market
Pharmaceuticals
Ginkgo Leaf Extract and Dipyridamole Injection Market
Pharmaceuticals
Global Immune Checkpoint Inhibitors Market
Pharmaceuticals
Global Desmopressin Market
Pharmaceuticals
North America Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Global Primary Biliary Cirrhosis Drug Market
Pharmaceuticals
Vutrisiran Market