
 Valganciclovir Market | 2026-2036
Valganciclovir Market Size, Share, and Industry Trends Forecast 2026-2036
Valganciclovir Market Analytics
Indian generic API production is shifting toward valganciclovir hydrochloride intermediates as patent cliffs mature. F. Hoffmann-La Roche Ltd anchors originator-grade quality standards through its legacy valganciclovir portfolio. Cipla Inc. leverages extensive hospital pharmacy networks across emerging markets. Teva Pharmaceutical Industries Ltd. competes on cost-optimized tablet formulations for post-transplant prophylaxis.
Valganciclovir is an L-valyl ester prodrug of ganciclovir with a molecular weight of 390.4 g/mol, designed for enhanced oral bioavailability to treat cytomegalovirus infections in immunocompromised patients. Tablet formulations dominate hospital procurement due to standardized dosing regimens, while organ transplant rejection prophylaxis represents the fastest-expanding indication segment as transplant volumes rise. Hospital pharmacies control the primary distribution channel for inpatient CMV protocols.
The US FDA and EMA enforce bioequivalence standards that filter subgeneric entrants from the valganciclovir supply base. India's CDSCO mandates local stability testing for imported antiviral finished doses, extending approval timelines for foreign manufacturers. Stakeholders must monitor evolving CMV prophylaxis guidelines from transplant societies and prepare for indication expansion into newer immunosuppressed populations.
Market Dynamics
Orphan drug exclusivity frameworks and transplant center consolidation are compressing competitive entry timelines while concentrating procurement authority in tertiary hospital networks. This structural concentration favors established manufacturers with validated bioequivalence dossiers and deep hospital pharmacy relationships.
Growth Catalysts
- Solid organ transplant volume expansion:Rising kidney, liver, and heart transplant procedures in the United States, Germany, and Japan are expanding the addressable patient pool for CMV prophylaxis protocols.
- EMA bioequivalence pathway harmonization:Streamlined generic approval standards across EU member states are accelerating market entry for validated valganciclovir formulations.
- Post-transplant immunosuppression intensification:Tacrolimus-mycophenolate combination therapies in modern transplant medicine elevate CMV reactivation risk and prophylactic antiviral demand.
Market Restraints
- API supply geographic concentration:Active pharmaceutical ingredient production clusters heavily in Indian chemical manufacturing zones, creating single-point vulnerability for global finished dose supply.
- FDA orphan exclusivity enforcement:Extended market protection periods for originator formulations delay full generic substitution in the United States transplant center segment.
- Letermovir therapeutic substitution:Novartis's newer CMV prophylaxis agent competes for high-risk transplant patient segments with improved bone marrow toxicity profiles.
Strategic Opportunities
- Pediatric indication expansion:Underdeveloped neonatal and pediatric CMV treatment protocols present white-space potential for age-appropriate formulation development.
- India CDSCO local manufacturing incentives:Production-linked incentive schemes for critical drug intermediates reward domestic valganciclovir hydrochloride synthesis capacity.
- Direct-to-hospital distribution models:Bypassing wholesale intermediaries through integrated supply contracts with transplant center networks captures margin and ensures cold-chain integrity.
Industry Challenges
- Bioequivalence study execution complexity:FDA-mandated pharmacokinetic bridging trials for generic valganciclovir require specialized CRO capabilities and extended timeline management.
- CMV resistance surveillance infrastructure:UL97 and UL54 mutation monitoring demands laboratory investment that smaller market entrants struggle to operationalize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Valganciclovir Market |
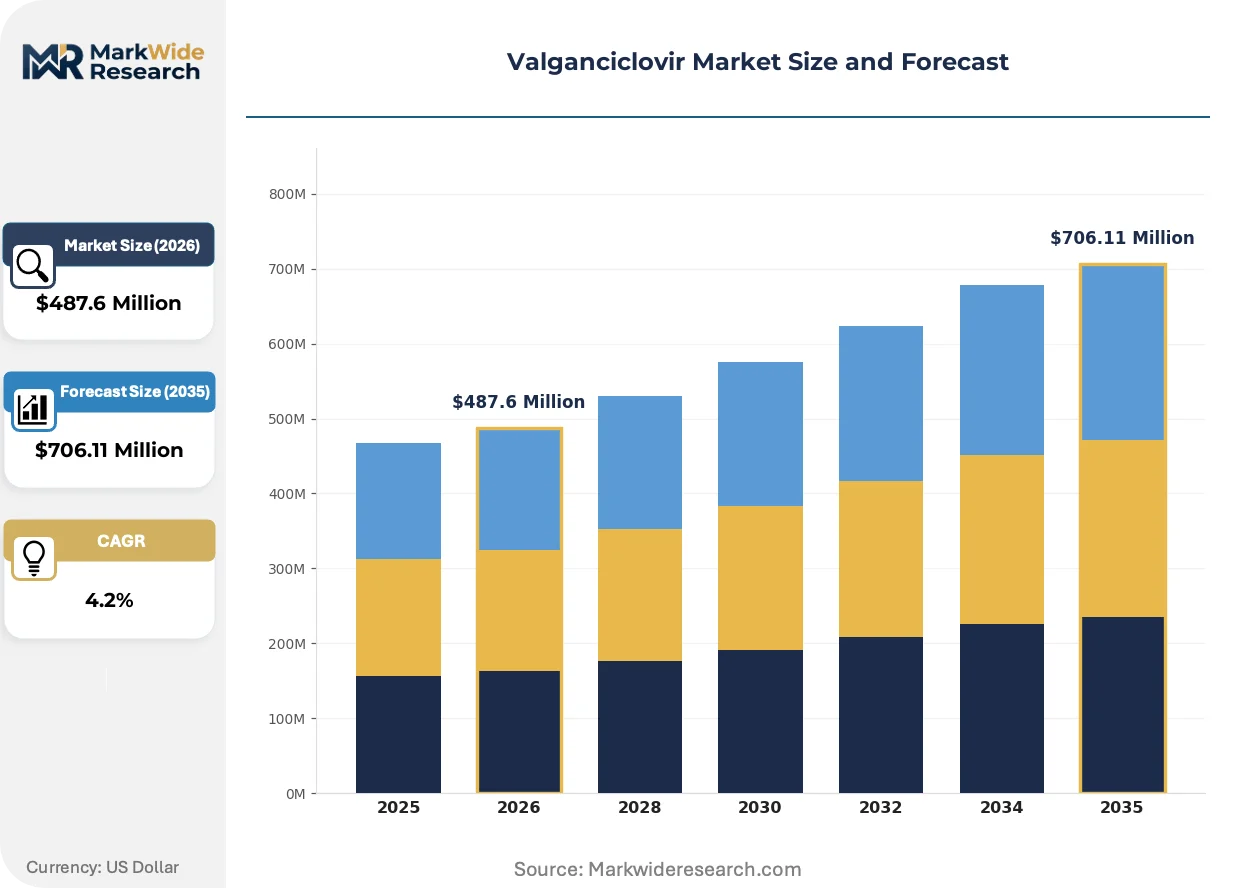
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $706.11 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Injections, Infusions, Oral Solution Indication: CMV Retinitis, Prevention of CMV Infection, Organ Transplant Rejection, Herpes Simplex End User: Hospitals, Specialty Clinics, Home Healthcare, Long-term Care Facilities Distribution Channel: Retail Pharmacies, Online Pharmacies, Hospital Pharmacies, Wholesalers |
| Companies Covered | F. Hoffmann-La Roche Ltd, Cipla Inc., Teva Pharmaceutical Industries Ltd., Dr. Reddy's Laboratories Ltd., Mylan N.V., Endo International plc, Aurobindo Pharma Ltd., Alniche Life Sciences Pvt. Ltd., Panacea Biotec Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Valganciclovir Market Evolving Landscape
Pharmaceutical manufacturing and clinical practice around valganciclovir are converging on precision dosing, regulatory data harmonization, and procurement centralization. These shifts are compressing traditional competitive advantages while elevating technical and compliance barriers.
Continuous manufacturing technology for oral solid dosage forms is integrating into antiviral production lines at contract development and manufacturing organizations serving the transplant therapeutic area. European and North American CDMOs are adopting this platform to reduce batch-to-batch variability and accelerate regulatory filing timelines. The structural consequence is a compression of quality differentiation between originator and high-tier generic suppliers.
EMA's updated bioequivalence guideline for narrow therapeutic index drugs is tightening pharmacokinetic equivalence standards for valganciclovir generics across the European Union. This regulatory refinement elevates clinical trial costs and filters marginal entrants from the supply base. German and French national health technology assessment bodies are responding by prioritizing suppliers with demonstrated intrasubject variability control.
Transplant center procurement consolidation is aggregating purchasing authority within integrated health networks in the United States and Western Europe. Hospital pharmacy directors now negotiate multi-year supply agreements directly with manufacturers, displacing traditional wholesale distribution for high-volume antivirals. This behavioral shift is most pronounced in U.S. academic medical centers with established solid organ transplant programs.
Valganciclovir Market Segmentation
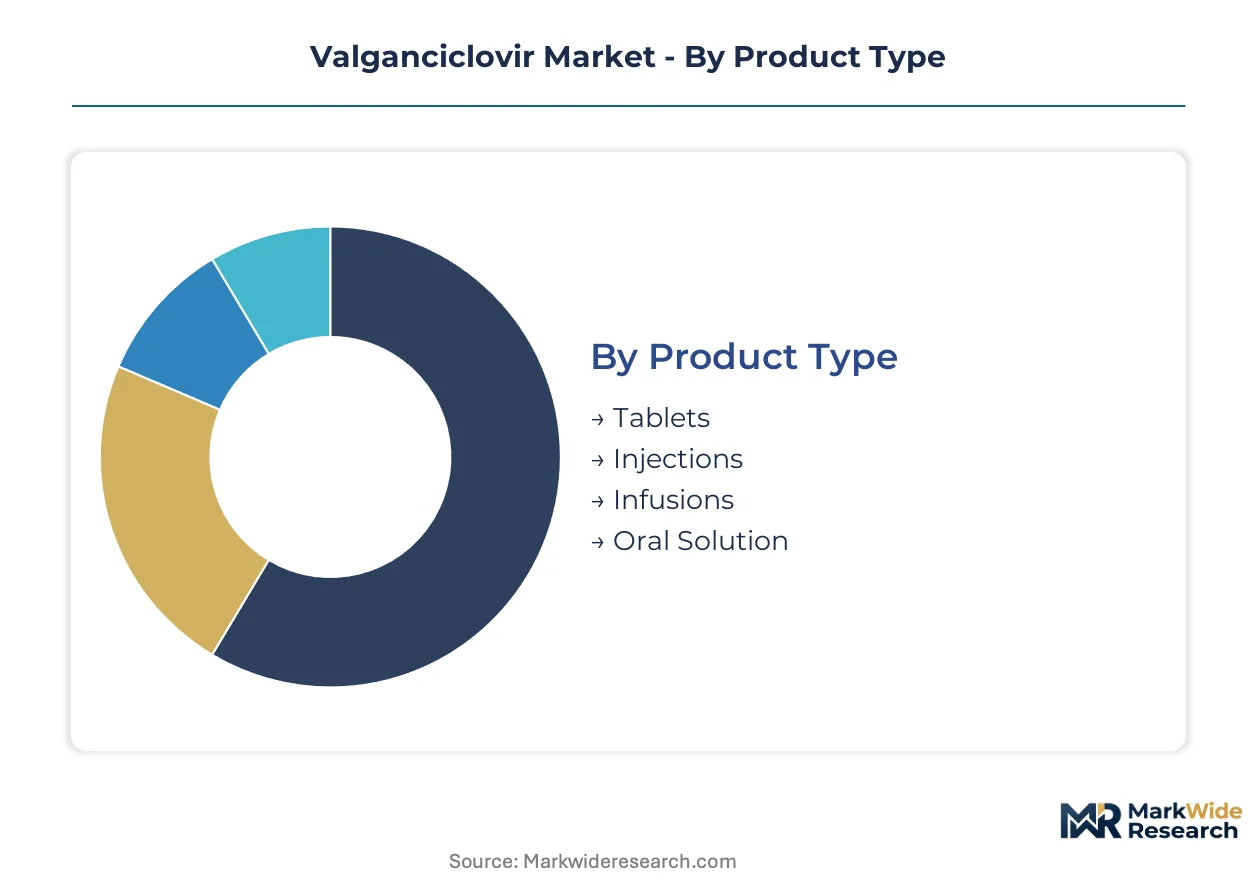
Valganciclovir's market segmentation reflects divergent regulatory pathways across dosage forms and the concentration of procurement authority within tertiary hospital networks. Each category carries distinct certification burdens and supply chain configurations that shape competitive positioning.
Product Type:
FDA bioequivalence requirements and EMA narrow therapeutic index standards apply differentially across solid and liquid dosage forms, filtering manufacturer participation by technical capability.
- Tablets:Compressed oral solid dosage forms containing valganciclovir hydrochloride equivalent to ganciclovir, manufactured under ICH Q7 API guidelines and USP dissolution specifications. Hospital pharmacy procurement in the United States, Germany, and Japan concentrates here due to standardized 450mg dosing regimens and cold-chain elimination. FDA abbreviated new drug application pathways for generics require pharmacokinetic bridging studies against Roche's originator.
- Injections:Sterile lyophilized powder for intravenous reconstitution, demanding aseptic manufacturing suites and endotoxin control under EU GMP Annex 1. Tertiary transplant centers in France and the United Kingdom maintain injection stockpiles for CMV disease treatment in patients unable to tolerate oral therapy, though volume share is compressing as tablet bioavailability improves.
- Infusions:Premixed intravenous bags requiring validated container-closure integrity and photostability testing per ICH Q1B.
- Oral Solution:Reconstitutable powder for pediatric and dysphagia populations, subject to FDA guidance on excipient safety in immunocompromised patients.
Leading the category by volume: Tablets. Growing fastest: Oral Solution.
Indication:
Clinical trial endpoints and label expansion strategies diverge sharply between prophylaxis and treatment indications, with transplant societies driving protocol standardization.
- Organ Transplant Rejection:Prophylactic administration to prevent CMV reactivation following kidney, liver, heart, and lung transplantation, guided by AST and ASTS consensus guidelines. The United States dominates addressable volume as high-risk donor-positive/recipient-negative protocols achieve near-universal penetration in academic medical centers. Tacrolimus-mycophenolate immunosuppression intensification continues elevating prophylactic antiviral demand.
- Prevention of CMV Infection:Primary prophylaxis in HIV/AIDS patients with CD4 counts below threshold levels, or secondary prophylaxis following resolution of acute retinitis. European markets in Germany and Spain retain significant volume as salvage therapy for letermovir non-responders.
- CMV Retinitis:Induction and maintenance therapy for AIDS-related sight-threatening retinal infection, now declining as ART penetration reduces HIV-associated CMV disease incidence.
- Herpes Simplex:Off-label utilization in immunocompromised hosts with acyclovir-resistant HSV, supported by case series rather than randomized trial evidence.
Volume concentrates in: Organ Transplant Rejection. Steepest expansion trajectory: Prevention of CMV Infection.
End User:
Patient acuity and reimbursement mechanics determine site-of-care distribution, with inpatient settings capturing high-margin induction dosing.
- Hospitals:Tertiary academic medical centers with solid organ transplant programs control the majority of valganciclovir consumption through integrated pharmacy and therapeutics committees. The United States, Germany, and Japan account for the preponderance of inpatient CMV prophylaxis protocols, with 340B pricing mechanisms distorting procurement economics in eligible facilities.
- Specialty Clinics:Transplant outpatient clinics managing stable post-operative patients on maintenance prophylaxis.
- Home Healthcare:Infusion nursing services for patients requiring prolonged intravenous therapy.
- Long-term Care Facilities:Skilled nursing facilities with limited transplant patient census and restricted antiviral formularies.
Revenue dominance: Hospitals. Patient volume growth: Specialty Clinics.
Distribution Channel:
Channel selection reflects inventory carrying costs, cold-chain requirements, and direct contracting prevalence in consolidated health systems.
- Hospital Pharmacies:Internal distribution networks within integrated delivery networks, capturing margin through 340B and group purchasing organization mechanisms. Direct manufacturer contracts are displacing wholesale intermediaries in the United States as transplant center procurement consolidates.
- Retail Pharmacies:Community and specialty pharmacy dispensing for outpatient maintenance therapy, with limited volume due to transplant patient care centralization.
- Online Pharmacies:Mail-order fulfillment for stable chronic prophylaxis patients with established therapeutic regimens.
- Wholesalers:Three-tier distribution intermediaries serving non-consolidated hospital systems and international markets lacking direct manufacturer infrastructure.
Margin capture concentrates in: Hospital Pharmacies. Channel expansion: Online Pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian API manufacturing clusters in Hyderabad and Ahmedabad supply the majority of valganciclovir hydrochloride intermediates consumed by formulation facilities worldwide.
United States
Solid organ transplant volumes at academic medical centers in Pittsburgh, Houston, and Cleveland drive CMV prophylaxis protocol penetration. FDA orphan drug exclusivity enforcement maintains originator formulation market protection periods. The Mayo Clinic and Johns Hopkins transplant networks negotiate direct manufacturer contracts for high-volume antiviral procurement.
Germany
Tacrolimus-mycophenolate immunosuppression intensification elevates CMV reactivation risk in kidney and liver transplant recipients. EMA bioequivalence guideline harmonization for narrow therapeutic index drugs tightens generic approval standards. Heidelberg and Berlin tertiary hospital pharmacy directors prioritize suppliers with demonstrated intrasubject variability control.
India
CDSCO local manufacturing incentives under production-linked schemes reward domestic valganciclovir hydrochloride synthesis capacity. Import stability testing mandates extend approval timelines for foreign finished dose manufacturers. Hyderabad's bulk drug cluster and Ahmedabad's formulation corridor concentrate API and finished dose production respectively.
Japan
PMDA pharmacokinetic bridging study requirements filter subgeneric entrants from the transplant therapeutic supply base. Aging demographics expand the addressable pool for kidney transplant procedures requiring prophylactic antiviral coverage. Tokyo and Osaka academic medical centers anchor national CMV protocol standardization efforts.
Valganciclovir Market Competitive Landscape
Global majors compete with regional champions across bioequivalence dossier quality and hospital pharmacy network depth. The vendor base stratifies into three tiers: originator-grade suppliers with legacy transplant portfolios, validated generic manufacturers with EMA/FDA filings, and emerging API-to-formulation integrators in Indian chemical manufacturing zones. Dominant competitive moves include backward integration into hydrochloride intermediate production and direct-to-hospital distribution contract capture.
Within the originator-grade tier, F. Hoffmann-La Roche Ltd exemplifies legacy quality standard anchoring through validated manufacturing dossiers. Among Indian API-to-formulation integrators, Cipla Inc. and Dr. Reddy's Laboratories Ltd occupy positions bridging bulk drug intermediate synthesis with finished dose hospital supply contracts. These three entities represent the competitive spectrum from originator maintenance to generic cost optimization in transplant center procurement.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Cipla Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Dr. Reddy's Laboratories Ltd. |
| Mylan N.V. |
| Endo International plc |
| Aurobindo Pharma Ltd. |
| Alniche Life Sciences Pvt. Ltd. |
| Panacea Biotec Ltd. |
| Others |
Value Network & Pricing Analysis
Valganciclovir hydrochloride intermediate spot pricing in Hyderabad's bulk drug clusters cascades through three distinct procurement tiers. FDA-validated originator-grade formulations command premium positioning against CDSCO-registered Indian generics and unbundled API supply to regional formulation facilities.
Pricing Analysis
Service bundling separates originator-grade suppliers offering integrated bioequivalence dossier support and resistance surveillance infrastructure from unbundled commodity tablet suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects certification tier and geographic delivery cost differentials. Cost compression in the economy tier is intensifying because Indian API manufacturers are expanding captive formulation capacity. Hospital pharmacy directors at tertiary transplant centers exhibit lowest price sensitivity due to protocol standardization requirements, while regional distributors in emerging markets face acute margin pressure.
Supply Chain Analysis
Dual-sourcing mandates from German and French hospital pharmacy directors require qualified backup suppliers for valganciclovir hydrochloride intermediates. API production concentrates in India, China, and Italy, with formulation finishing clustered in the United States, Germany, and Japan. The supply chain draws from acyclovir-derived starting materials, L-valine esterification reagents, and specialized aseptic packaging components. Single-source vulnerability persists in Indian intermediate manufacturing zones subject to environmental compliance shutdowns. Distribution runs through direct manufacturer contracts with integrated transplant center networks, displacing wholesale intermediaries in consolidated health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
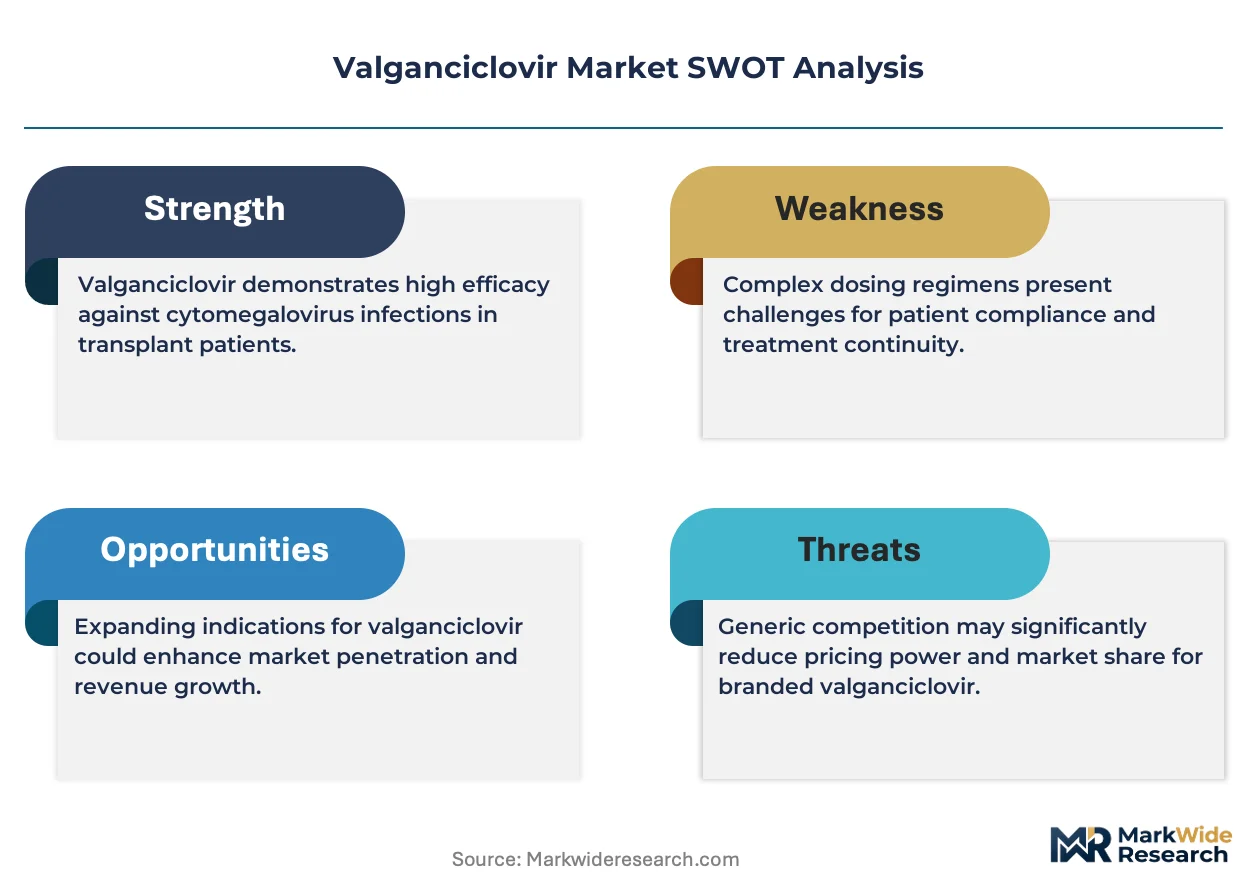
The valganciclovir market is transitioning from small-molecule prodrug dominance to precision antiviral alternatives, as letermovir displaces legacy ganciclovir analogs in high-risk transplant protocols.
For Market Incumbents: Acquire CMV resistance surveillance laboratory assets to differentiate beyond commodity tablet supply. Incumbents should secure backward integration into hydrochloride intermediate production in Indian chemical manufacturing zones to defend against API supply disruption threats. Hospital pharmacy direct contracting capabilities represent the priority lever for margin defense against letermovir substitution pressure. For New Entrants and Emerging Players: Launch via direct-to-hospital distribution models bypassing wholesale intermediaries in United States academic medical centers. Pediatric oral solution formulations present the most penetrable white-space target, given underdeveloped neonatal CMV protocols and limited age-appropriate competition. CDSCO production-linked incentive qualification offers a regulatory-fast-tracked entry angle for Indian API-to-formulation integrators. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Indian API manufacturers with pending EMA bioequivalence filings in Hyderabad and Ahmedabad. Long-term viability hinges on indication expansion into newer immunosuppressed populations beyond transplant medicine. The signal to watch is letermovir formulary restriction reversals indicating sustained ganciclovir-prodrug demand durability.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Pediatric pharmacokinetic bridging studies unlock neonatal CMV indication expansion at Johns Hopkins and Mayo Clinic networks. |
| Regulatory Approval Pathway | EMA narrow therapeutic index bioequivalence filings filter subgeneric entrants from European transplant center supply. |
| Backward Integration | Captive valganciclovir hydrochloride synthesis in Hyderabad reduces API supply disruption exposure for Indian formulators. |
| Long-term Supply Agreement | Multi-year direct contracts with Pittsburgh and Houston transplant centers lock in volume against letermovir substitution. |
| Pipeline Diversification | Resistance surveillance service bundling differentiates originator-grade suppliers from commodity generic tablet providers. |
Research Methodology
FDA filings, EMA regulatory submissions, and ClinicalTrials.gov protocol databases formed the secondary backbone of this analysis. Primary interviews with transplant pharmacy directors, CDSCO regulatory affairs leads, hospital procurement managers, and antiviral drug development executives combined with secondary validation through formulary databases and SEC pharmaceutical filings. Bottom-up patient volume modeling across solid organ transplant procedures and top-down market size triangulation anchored the quantitative framework.
Bottom-up demand modeling segmented by dosage form, indication type, and end-user site-of-care generated volume and value outputs across the projection horizon. Treatment line differentiation, regional regulatory cluster classification, and administration route preferences structured the analytical segmentation. CAGRs were derived from transplant volume growth assumptions, immunosuppression protocol evolution, and therapeutic substitution elasticity parameters calibrated against historical CMV prophylaxis penetration patterns.
The model assumes a particular technology adoption path; alternative pathways for letermovir first-line prophylaxis would alter the outlook for valganciclovir demand materially. Forecasts reflect documented assumptions regarding transplant center consolidation rates and FDA orphan exclusivity enforcement patterns. Deviation in letermovir bone marrow toxicity profile superiority claims would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
US Hormone Replacement Therapy Market
Pharmaceuticals
Bladder Cancer Treatment Drugs Market
Pharmaceuticals
Tissue Plasminogen Activator Market
Pharmaceuticals
Global Chickenpox Vaccine Market
Pharmaceuticals
Epigenetics Drugs and Diagnostic Technologies Market
Pharmaceuticals
Europe FMD Vaccine Market
Pharmaceuticals
Stye Drug Market
Pharmaceuticals
Enteric Empty Capsules Sales Market
Pharmaceuticals
Opioids Market
Pharmaceuticals
Seropositive Rheumatoid Arthritis Drug Market
Pharmaceuticals
Ramipril Market
Pharmaceuticals
Dermatitis Drugs Market
Pharmaceuticals
Macrolides Market
Pharmaceuticals
Global Pharmaceuticals Market
Pharmaceuticals
North America Sodium-Dependent Glucose Co-Transporter 2 (Sglt2) Market
Pharmaceuticals
Xerostomia Therapeutics Market