
 Stromal Vascular Fraction Market | 2026-2036
Stromal Vascular Fraction Market Size, Share, and Industry Trends Forecast 2026-2036
Stromal Vascular Fraction Market Outlook
Japan is rewriting competitive dynamics in stromal vascular fraction processing through advanced cell isolation infrastructure. IntelliCell BioSciences anchors North American capacity with proprietary enzymatic digestion platforms. Cytori Therapeutics leverages Celution system technology to dominate point-of-care adipose-derived cell preparation. Genesis Biosystems competes through lipoaspirate concentration devices optimized for clinic-scale workflows.
Stromal vascular fraction constitutes a heterogeneous population of adipose-derived stem cells, pericytes, preadipocytes, endothelial cells, and immune cells isolated from enzymatically digested adipose tissue, typically yielding 500,000 to 2 million nucleated cells per gram of processed lipoaspirate for therapeutic deployment in tissue repair and regeneration. The primary commercial purpose centers on delivering autologous regenerative cell populations without ex vivo expansion, shortening the therapeutic pipeline from harvest to administration. Cell Enrichment products command the dominant revenue share given their role as the indispensable first step in all downstream SVF workflows, while 3D Bioprinting represents the fastest-growing technology segment as biofabrication platforms integrate living SVF populations into structured tissue constructs. Regenerative Medicine applications concentrate the deepest margin pools, though Orthopedics sustains the highest procedure volume through joint and soft-tissue interventions.
The US FDA regulates SVF under 21 CFR 1271 human cells, tissues, and cellular and tissue-based products frameworks, with minimal manipulation criteria determining whether products qualify for homologous-use exemptions or require full biologics licensing. Japan's PMDA and the EU EMA maintain divergent classification thresholds for enzymatic digestion processes, fragmenting market access requirements across major jurisdictions. ISO 14644 cleanroom standards and WHO Good Manufacturing Practice guidelines further constrain production economics for commercial-scale SVF manufacturing. Stakeholders must monitor regulatory precedent from adipose-derived stem cell litigation to anticipate whether enforcement shifts will reclassify common SVF preparation methods as drug manufacturing.
Market Dynamics
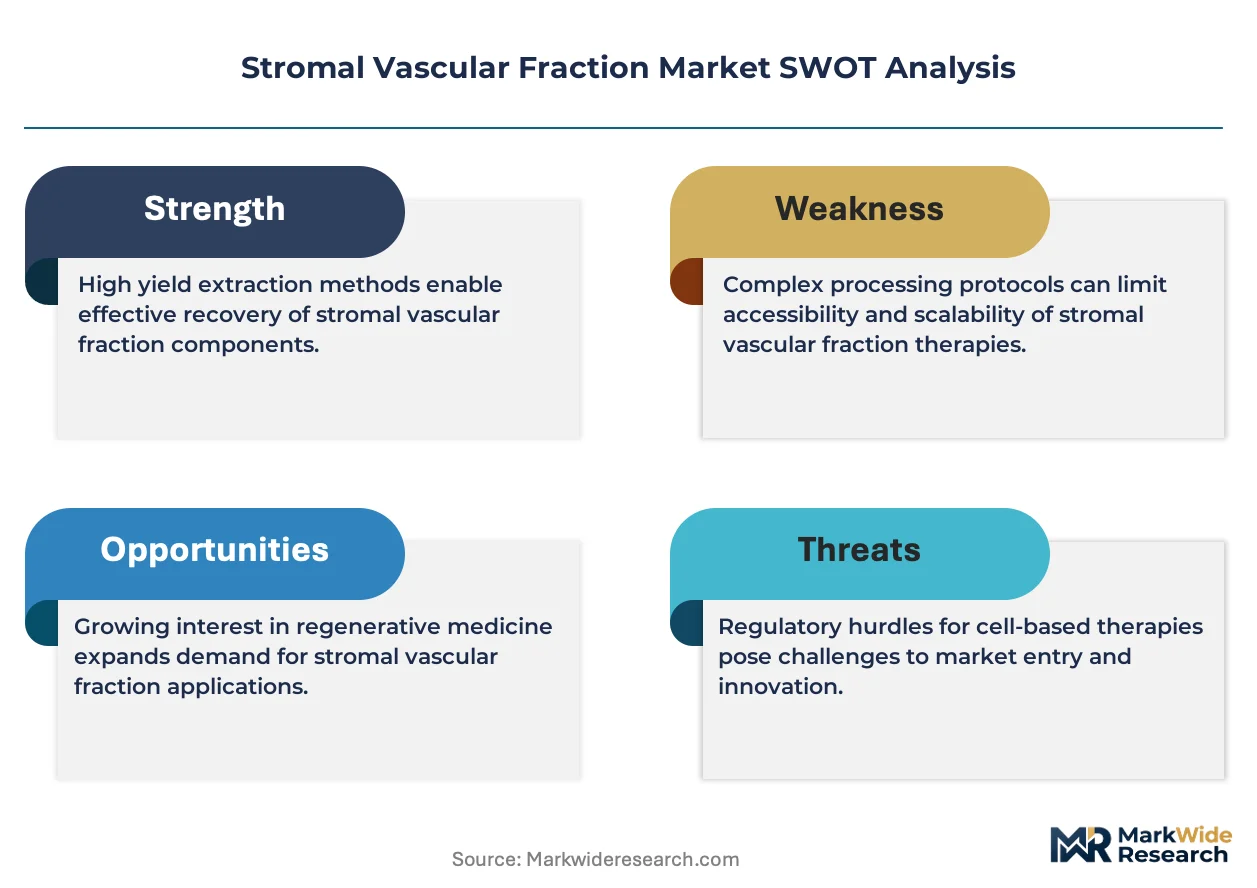
Enzymatic isolation protocols are fragmenting product classification pathways across major jurisdictions, forcing manufacturers to rebuild compliance architectures around divergent minimal-manipulation thresholds rather than unified standards.
Growth Catalysts
- Cosmetic surgery clinic expansion:South Korean facial rejuvenation centers are scaling autologous cell therapies into premium service tiers, creating procedural volume anchors for SVF device manufacturers.
- EMA adaptive pathway frameworks:The EU's regenerative medicine advanced therapy classification is accelerating market authorization timelines for adipose-derived cell products in Germany's Heidelberg and Berlin clusters.
- 3D bioprinting convergence:Biofabrication platforms are integrating living SVF populations into structured tissue constructs, opening orthopedic and wound-care applications previously unreachable with suspension injections alone.
Market Restraints
- Collagenase cost volatility:Pharmaceutical-grade enzyme supply concentrates among three European manufacturers, exposing processors to input price shocks that compress per-procedure margins.
- FDA enforcement ambiguity:The US regulator's evolving 21 CFR 1271 guidance on what constitutes "more than minimal manipulation" creates classification uncertainty that delays product launches and raises legal compliance spend.
- Allogeneic stem cell substitution:Ex vivo expanded mesenchymal stem cell products from cord and bone marrow sources are capturing orthopedic indications where SVF previously held autologous advantage.
Strategic Opportunities
- Japan's PMDA regenerative medicine framework:Conditional approval pathways for processed autologous cells are opening faster commercialization routes than US or EU equivalents.
- Point-of-care workflow automation:Closed-system devices that complete enzymatic digestion and concentration in under two hours are enabling office-based procedures outside hospital OR economics.
- Veterinary medicine extension:Equine orthopedic and small-animal soft-tissue applications face no human-cell regulatory barriers, allowing faster indication expansion and pricing experimentation.
Industry Challenges
- Cleanroom technician scarcity:ISO 14644-compliant facility operations require specialized cell-therapy manufacturing skills that outpace training program output in most markets.
- Batch-to-batch variability control:Lipoaspirate donor heterogeneity and enzyme lot variation create nucleated cell yield swings that complicate dosing standardization and clinical protocol design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stromal Vascular Fraction Market |
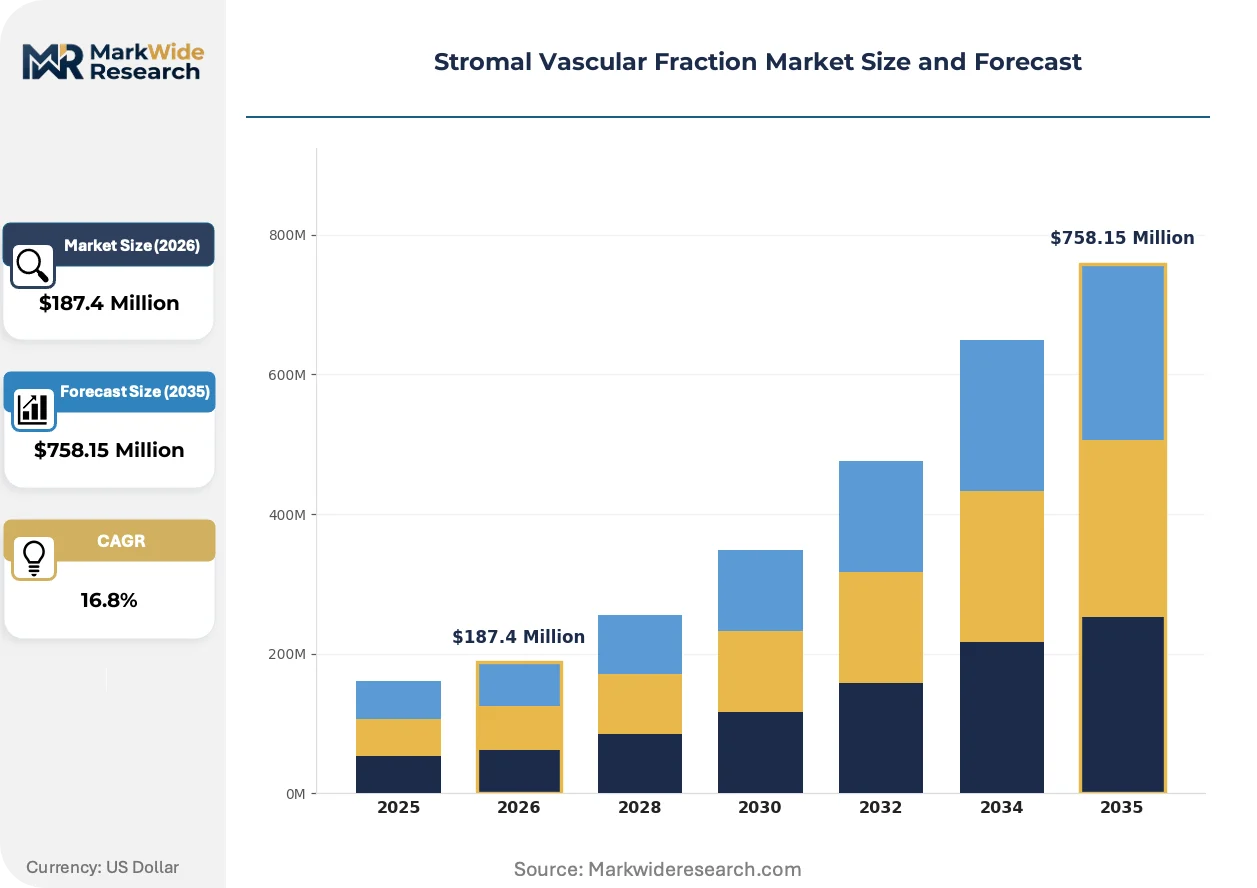
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $758.15 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell Enrichment, Tissue Regeneration, Biologics, Stem Cell Therapy End User: Hospitals, Research Institutions, Clinics, Biotechnology Firms Application: Orthopedics, Cosmetic Surgery, Wound Healing, Regenerative Medicine Technology: Cell Isolation, Flow Cytometry, Tissue Engineering, 3D Bioprinting |
| Companies Covered | Medikan International, IntelliCell BioSciences, Cytori Therapeutics, Genesis Biosystems, Human Med, GE Healthcare, Tissue Genesis, LifeCell, InGeneron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stromal Vascular Fraction Market Strategic Shifts
Mechanical dissociation technologies are challenging enzymatic dominance in SVF isolation, while regulatory arbitrage between Japan, the US, and the EU is reshaping where manufacturers choose to validate and launch first.
Mechanical SVF isolation systems are collapsing the historical dependence on collagenase digestion for cell recovery. These devices use calibrated adipose tissue processing to liberate the stromal vascular fraction without exogenous enzymes. South Korean cosmetic surgery chains are adopting mechanical platforms fastest, driven by regulatory preference for "non-enzymatic" product classifications. This collapse of enzymatic workflow dominance is compressing the addressable market for traditional isolation reagents while expanding the installed base for capital equipment.
Japan's PMDA has established a distinct regulatory category for processed autologous adipose tissue that diverges from both FDA and EMA minimal-manipulation criteria. This framework permits commercial distribution of SVF products without full biologics licensing if processed in certified facilities. European manufacturers are responding by prioritizing Japanese regulatory submissions ahead of US filings. The segment most affected—orthopedic point-of-care preparation—is redirecting R&D investment toward PMDA-aligned quality systems.
Buyers in Germany's regenerative medicine clusters are consolidating procurement around single-source device-and-consumable contracts that bundle capital equipment with per-procedure disposables. This bundling displaces the previous model of separate device purchase and open reagent sourcing. The shift is most visible in Heidelberg's university hospital network, where procurement committees now require five-year total-cost-of-ownership guarantees from SVF system vendors.
Stromal Vascular Fraction Market Segmentation
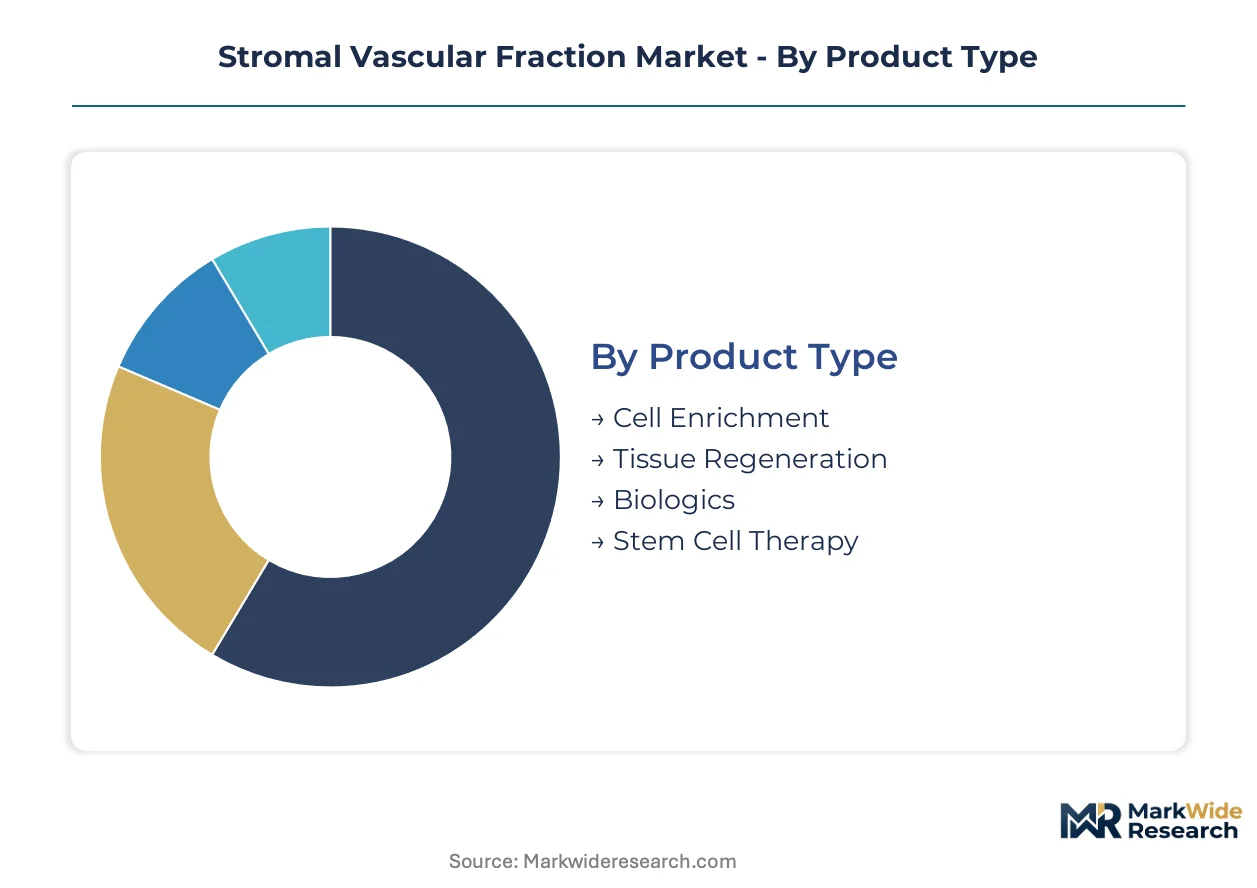
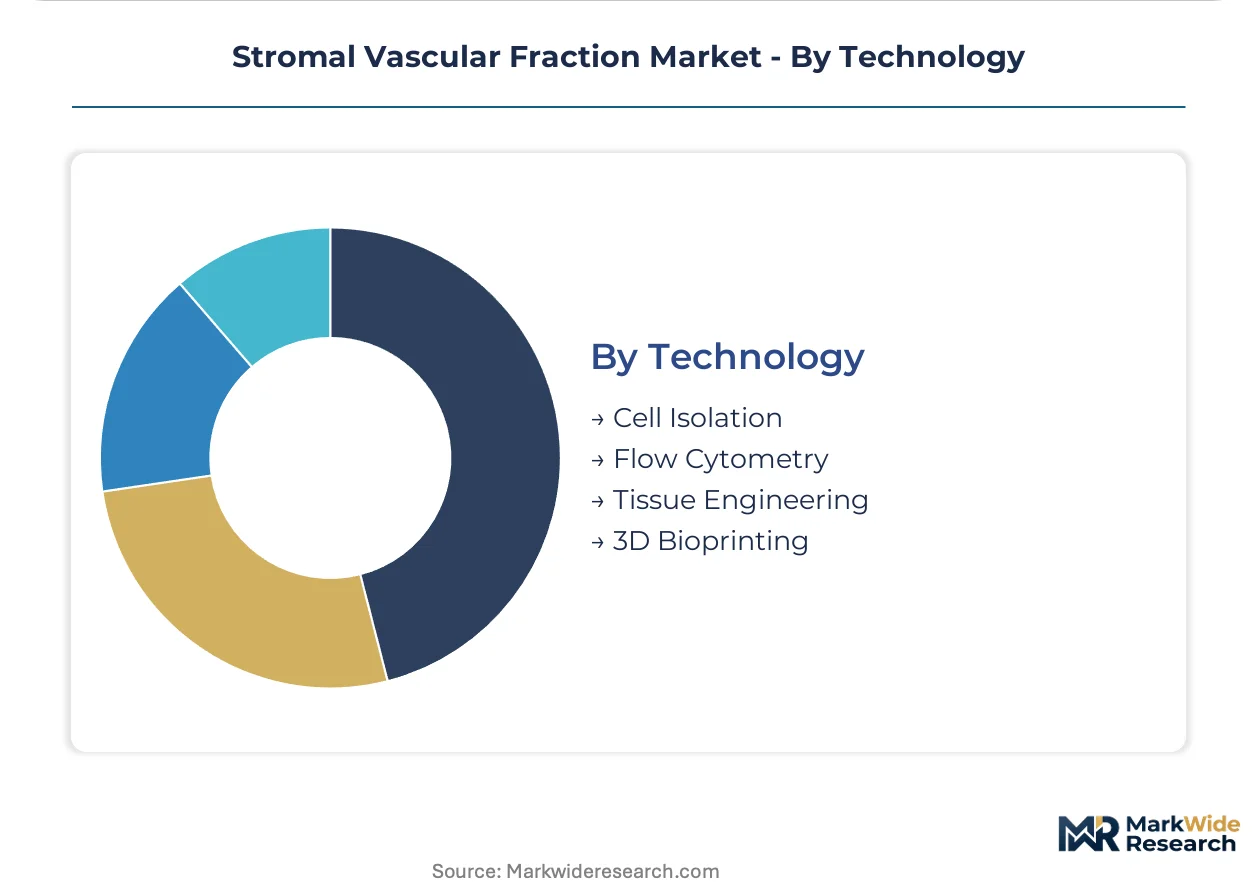
SVF market segmentation reflects divergent regulatory pathways and clinical workflows. Product type determines manufacturing compliance burden, while technology choice dictates whether providers operate within hospital OR economics or office-based settings.
Product Type:
Use cases span from simple cell concentration to complex biologic manufacturing, with regulatory intensity escalating across the spectrum.
- Cell Enrichment:Enzymatic digestion and mechanical filtration systems yield concentrated nucleated cell populations without ex vivo expansion. Demand concentrates in South Korean cosmetic surgery chains and German orthopedic clinics where rapid turnaround drives procurement decisions. This segment anchors installed base expansion for device manufacturers.
- Tissue Regeneration:Scaffold-integrated SVF products combine living cells with structural matrices for defect repair. Heidelberg university hospitals and Berlin regenerative medicine clusters prioritize these higher-complexity offerings for cartilage and bone applications. Regulatory classification as combination products extends approval timelines.
- Biologics:Processed adipose tissue products meeting pharmaceutical manufacturing standards.
- Stem Cell Therapy:SVF-derived therapeutic interventions targeting specific disease pathways.
Established volume favors Cell Enrichment; emerging adoption favors Tissue Regeneration.
End User:
Customer type determines pricing power, procurement complexity, and service bundling requirements across the value chain.
- Hospitals:Academic medical centers and tertiary care facilities with integrated surgical and laboratory infrastructure. Heidelberg and Berlin hospital networks command volume discounts through multi-year device-and-consumable contracts. OR scheduling constraints limit SVF procedure throughput.
- Clinics:Ambulatory surgical centers and specialty cosmetic practices. South Korean facial rejuvenation clinics scale autologous therapies into premium service tiers with sub-two-hour processing workflows. Point-of-care automation enables margin capture outside hospital economics.
- Research Institutions:Academic laboratories and translational medicine centers.
- Biotechnology Firms:Commercial developers of SVF-derived therapeutic products.
Procurement concentration favors Hospitals; margin expansion favors Clinics.
Application:
Clinical indication drives reimbursement coding, outcome evidence requirements, and competitive substitution risk from alternative regenerative modalities.
- Orthopedics:Joint preservation, soft-tissue repair, and bone defect interventions sustain highest procedure volumes. German orthopedic networks and US sports medicine practices standardize SVF for osteoarthritis and tendon pathology. Allogeneic stem cell substitution threatens autologous positioning in large-joint applications.
- Regenerative Medicine:Broad therapeutic deployment across organ system repair and anti-aging protocols. Japan's PMDA conditional approval framework accelerates commercialization for processed autologous cells. Deepest margin pools concentrate here despite smaller current volumes.
- Cosmetic Surgery:Facial rejuvenation and adipose transfer enhancement procedures.
- Wound Healing:Chronic ulcer management and post-surgical tissue repair applications.
Procedure volume favors Orthopedics; value per intervention favors Regenerative Medicine.
Technology:
Platform selection determines capital intensity, regulatory classification, and integration potential with adjacent biofabrication workflows.
- 3D Bioprinting:Biofabrication platforms deposit living SVF populations within structured tissue constructs. South Korean research consortia and German engineering clusters drive fastest platform adoption for orthopedic and wound-care applications previously unreachable with suspension injections alone. Technology convergence expands addressable indications.
- Cell Isolation:Mechanical and enzymatic systems for SVF liberation from adipose tissue. Dominates current installed base with established reimbursement pathways. Collagenase cost volatility and FDA minimal-manipulation uncertainty constrain per-procedure margins.
- Flow Cytometry:Analytical characterization and cell population sorting technologies.
- Tissue Engineering:Scaffold-based approaches for structured tissue construct development.
Current deployment favors Cell Isolation; steepest expansion trajectory favors 3D Bioprinting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SVF processing infrastructure concentrates in jurisdictions with explicit regenerative medicine frameworks. Device manufacturing clusters in Germany and South Korea supply global demand, while regulatory arbitrage between Japan, the US, and the EU reshapes commercialization sequencing.
United States
Cosmetic surgery practices and orthopedic clinics drive procedural volume across Florida, California, and Texas. The FDA's evolving 21 CFR 1271 guidance on minimal manipulation creates classification uncertainty that delays product launches. Boston and San Francisco biotech clusters concentrate venture-backed SVF technology development.
Germany
Heidelberg and Berlin regenerative medicine clusters prioritize scaffold-integrated SVF products for cartilage and bone applications. The EMA adaptive pathway framework accelerates market authorization timelines for adipose-derived cell therapies. University hospital networks now require five-year total-cost-of-ownership guarantees from SVF system vendors.
Japan
The PMDA conditional approval framework permits commercial distribution of processed autologous adipose tissue without full biologics licensing. Tokyo and Osaka medical centers scale point-of-care SVF preparation for orthopedic and anti-aging protocols. European manufacturers increasingly prioritize Japanese regulatory submissions ahead of US filings.
South Korea
Seoul facial rejuvenation clinics integrate autologous cell therapies into premium service tiers with sub-two-hour processing workflows. The MFDS regulatory preference for non-enzymatic product classifications accelerates mechanical platform adoption. Busan device manufacturers supply enzymatic digestion systems across Asia-Pacific markets.
Stromal Vascular Fraction Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in reagent and consumable supply. The vendor base separates into three functional layers: capital equipment manufacturers, enzymatic reagent suppliers, and point-of-care workflow automation developers. Strategic moves concentrate on regulatory submission sequencing across Japan, the US, and the EU, plus bundling contracts that lock in per-procedure consumable revenue.
Among North American platform developers, IntelliCell BioSciences and Cytori Therapeutics occupy positions within the integrated system tier, while Genesis Biosystems represents the clinic-scale workflow optimization archetype. These entities exemplify divergent approaches to FDA minimal-manipulation compliance and point-of-care automation.
| Leading Market Players |
|---|
| Medikan International |
| IntelliCell BioSciences |
| Cytori Therapeutics |
| Genesis Biosystems |
| Human Med |
| GE Healthcare |
| Tissue Genesis |
| LifeCell |
| InGeneron |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Frankfurt freight corridors transmit collagenase cost volatility directly into German clinic pricing tiers, while South Korean device manufacturers exploit shorter logistics loops to compress per-procedure margins for enzymatic isolation systems.
Pricing Analysis
21 CFR 1271 dictates the pricing tier structure across the SVF market, separating FDA-compliant minimal-manipulation devices from higher-complexity biologics manufacturing platforms. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in economy-tier mechanical isolation devices is intensifying because South Korean manufacturers are flooding Asia-Pacific markets with non-enzymatic platforms. Hospital procurement committees in Heidelberg demonstrate lowest price sensitivity due to five-year total-cost-of-ownership guarantees, while independent cosmetic surgery clinics in Seoul face acute margin pressure.
Supply Chain Analysis
Extended payment terms from European enzyme manufacturers now stretch 90-120 days, straining working capital for mid-tier device assemblers in South Korea and the United States. Pharmaceutical-grade collagenase supply concentrates in Germany, Switzerland, and Belgium, while mechanical isolation device fabrication rests on precision machining clusters in South Korea, Japan, and Germany. Single-source vulnerability around collagenase APIs threatens batch-to-batch yield consistency. Distribution runs through hospital procurement committees in academic medical centers and direct-to-clinic sales forces for ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Per-procedure consumable contracts and maintenance service agreements are expanding at double the rate of capital equipment sales, making aftermarket attach rates the decisive profitability lever across SVF system vendors.
For Market Incumbents: Pre-empt mechanical isolation substitution by acquiring complementary scaffold-integrated tissue regeneration capabilities or exclusive distribution rights for Japan's PMDA-certified processing platforms. Collagenase cost volatility threatens margin stability in enzymatic-dominant installed bases. Vertical integration into pharmaceutical-grade enzyme sourcing insulates against European supply concentration. For New Entrants and Emerging Players: Veterinary orthopedic applications in North American equine practices and European small-animal specialty clinics represent the most penetrable entry point, bypassing human-cell regulatory barriers entirely. Point-of-care workflow automation for sub-two-hour processing protocols offers the clearest go-to-market angle against entrenched hospital OR economics. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medtech conglomerates with underperforming adipose-tissue processing divisions lacking dedicated SVF commercial infrastructure. Long-term viability hinges on regulatory submission sequencing across Japan's PMDA conditional approval pathway versus FDA's evolving minimal-manipulation guidance. Watch for FDA enforcement actions reclassifying common enzymatic digestion methods as drug manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Conditional Approval Pathway | Accelerates Japanese commercialization without full biologics licensing requirements. |
| Point-of-Care Workflow Automation | Enables office-based SVF procedures outside hospital OR economics. |
| Mechanical Isolation Platform Launch | Captures South Korean regulatory preference for non-enzymatic classifications. |
| Five-Year Total-Cost-of-Ownership Contracts | Locks in German university hospital procurement committees against competitors. |
| Veterinary Medicine Extension | Opens faster indication expansion without human-cell regulatory barriers. |
Study Parameters
A standing panel of SVF device manufacturing executives, hospital procurement managers, regulatory affairs specialists, and cosmetic surgery clinic operators provided ongoing calibration across primary fieldwork. Secondary validation drew from FDA 510(k) filings, PMDA approval databases, EMA adaptive pathway decisions, and ISO 14644 cleanroom certification records. Bottom-up procedure volume estimates triangulated against top-down device shipment data.
Scenario bracketing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type, end-user facility tier, clinical application, and technology platform. CAGRs were derived from procedure volume trajectories and per-procedure pricing trends. Forecast inputs incorporated collagenase supply elasticity, regulatory submission timelines, and mechanical platform substitution curves.
Stress conditions across enzyme cost volatility, FDA enforcement intensity, and Japanese regulatory backlog were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding reimbursement pathway stability and clinician adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Global Vaginal Rejuvenation Market
Regenerative Medicine
Next Generation Immunotherapies Market
Regenerative Medicine
Mesotherapy Guns Market
Regenerative Medicine
Tumour-Induced Osteomalacia Market
Regenerative Medicine
Asia Pacific Platelet Rich Plasma Market
Regenerative Medicine
Th17 Driven Disease Treatment Market
Regenerative Medicine
Bone Regeneration Market
Regenerative Medicine
Degenerative Disc Disease Treatment Market
Regenerative Medicine
Tooth Regeneration Market
Regenerative Medicine
Cartilage Degeneration Market
Regenerative Medicine
Europe Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Hyper Personalized Medicine Market
Regenerative Medicine
Cytokine Storm Therapy Market
Regenerative Medicine
US Platelet Rich Plasma Market
Regenerative Medicine
Hypertrophic and Keloid Scar Treatment Market
Regenerative Medicine
North America Scar Treatment Market