
 Anti-Parasitic Drugs Market | 2026-2036
Anti-Parasitic Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Parasitic Drugs Market Outlook
Indian pharmaceutical clusters is repositioning active pharmaceutical ingredient capacity toward antiparasitic intermediates, tightening global supply lines for avermectin derivatives. GlaxoSmithKline plc leverages its established neglected-disease portfolio to sustain access contracts across endemic regions. Merck KGaA anchors its position through veterinary antiparasitic manufacturing scale, while Cipla Inc. competes on cost-optimized oral therapy production for malaria and helminth indications.
Anti-parasitic drugs comprise chemically synthesized or fermentation-derived agents that disrupt parasite metabolism, neuromuscular function, or cellular respiration, typically formulated as tablets, injectables, or topical preparations with defined pharmacokinetic profiles for target species. These compounds serve therapeutic and prophylactic purposes in human tropical medicine, livestock production, and companion animal health. Avermectins occupy the dominant share of product-type revenue due to broad-spectrum nematocidal efficacy and cross-species applicability. The malaria therapy area commands substantial funding flows from donor institutions, while injectable administration routes capture premium pricing in veterinary settings where compliance and bioavailability determine treatment outcomes.
WHO prequalification, FDA tropical disease priority review vouchers, and EMA orphan drug incentives collectively shape clinical trial investment and market access pathways for antiparasitic developers. India's CDSCO and China's NMPA impose distinct bioequivalence and stability-testing requirements that filter which manufacturers qualify for public procurement tenders. Stakeholders must monitor evolving resistance patterns in Plasmodium and helminth populations alongside regulatory shifts in vector-control policy integration.
Market Dynamics
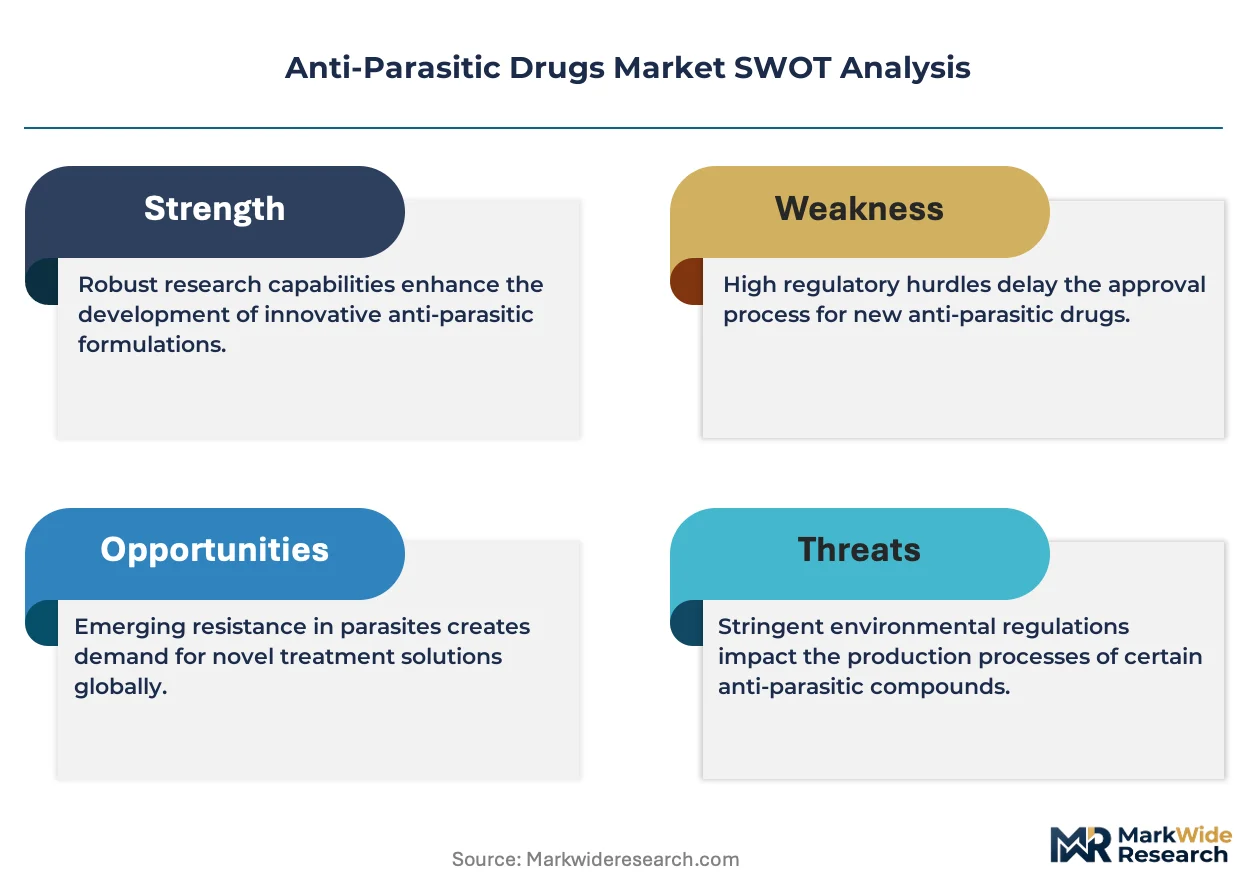
Resistance amplification in Plasmodium falciparum and soil-transmitted helminths is compressing product lifecycles and forcing R&D pipelines toward combination therapies with novel mechanisms of action.
Growth Catalysts
- Vector-control integration mandates:WHO policy frameworks now require co-deployment of chemoprophylaxis with insecticide-treated materials, expanding addressable patient pools in endemic zones.
- Veterinary anthelmintic procurement:Sub-Saharan livestock health programs are scaling bulk purchases of macrocyclic lactones for regional eradication campaigns.
- FDA tropical disease priority review vouchers:Transferable regulatory incentives are redirecting private capital toward antiparasitic clinical trials previously deemed commercially marginal.
Market Restraints
- Fermentation capacity concentration:Avermectin API synthesis depends on captive bioreactor networks clustered in eastern China, creating single-source vulnerability.
- Artemisinin raw material volatility:Sweet wormwood cultivation cycles in Vietnam and Madagascar generate 18-24 month supply lags that destabilize ACT formulation costs.
- Prequalification timeline friction:WHO PQ pathways for fixed-dose combinations impose 4-7 year validation windows that deter generic manufacturer entry.
Strategic Opportunities
- Companion animal parasiticide premiumization:Monthly chewable formulations for heartworm prevention command 8-12x human-equivalent margins in US and EU veterinary channels.
- CDSCO fast-track orphan pathways:India's regulator offers accelerated review for tropical disease indications, enabling first-mover positioning in domestic and export tenders.
- CRISPR-based resistance diagnostics:Point-of-care molecular surveillance tools are converging with drone-enabled sample logistics to enable precision mass drug administration.
Industry Challenges
- Parasitology clinical trial infrastructure:Recruitment networks for hookworm and schistosomiasis studies remain concentrated at five tropical medicine institutes, creating site access bottlenecks.
- Multispecies formulation complexity:Cross-species pharmacokinetic bridging studies for veterinary-human product extensions consume 30-40% of development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Parasitic Drugs Market |
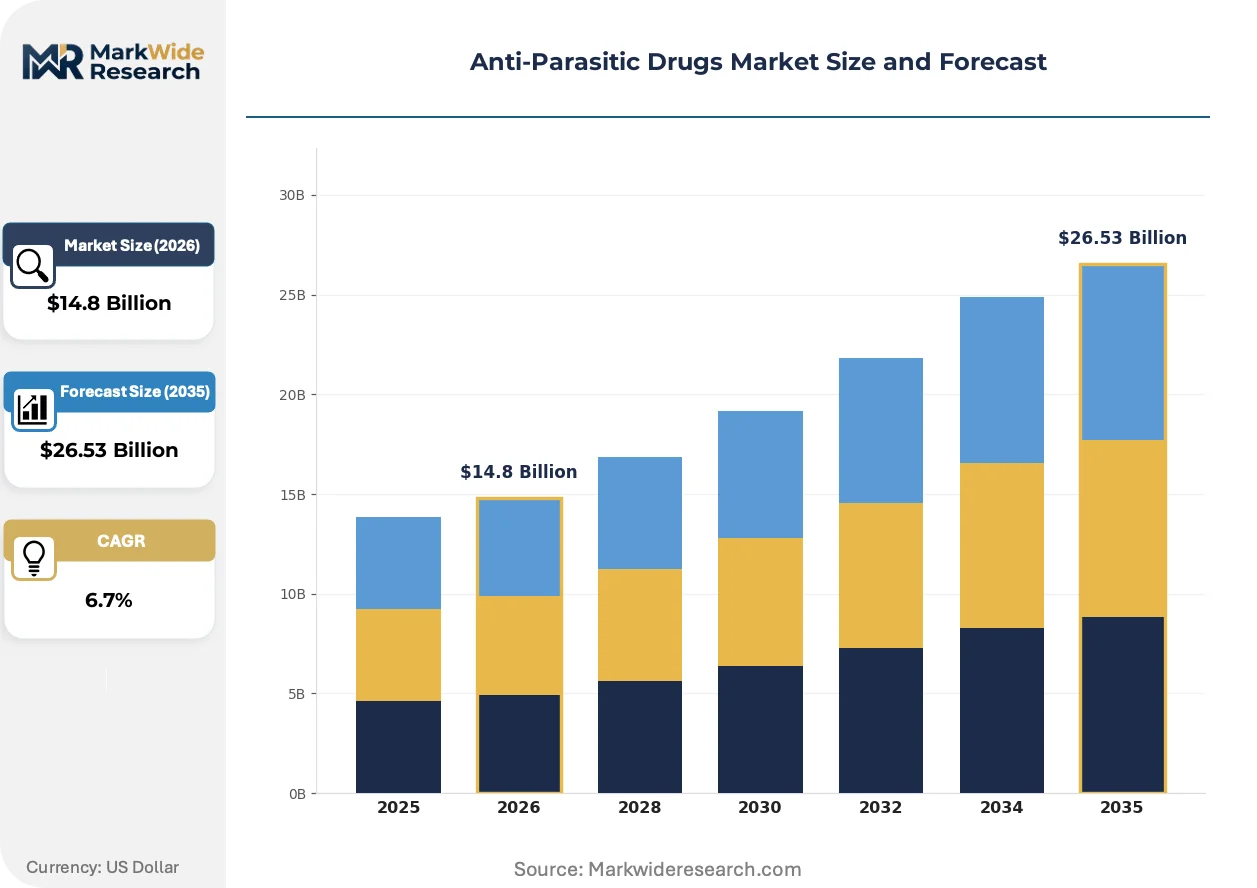
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
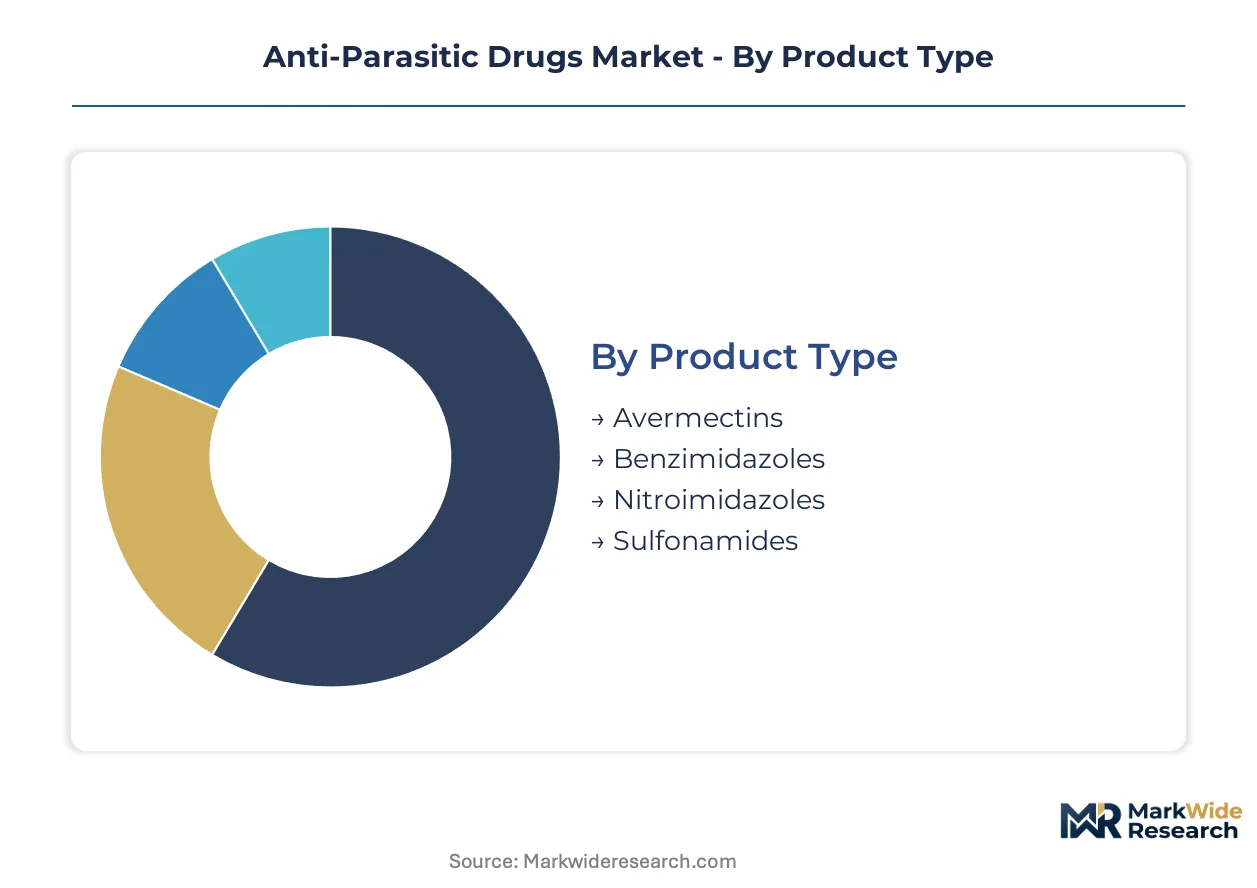
| Segmentation | Product Type: Avermectins, Benzimidazoles, Nitroimidazoles, Sulfonamides Therapy Area: Malaria, Schistosomiasis, Giardiasis, Leishmaniasis End User: Hospitals, Clinics, Pharmacies, Research Institutions Administration Route: Oral, Injectable, Topical, Intravenous |
| Companies Covered | GlaxoSmithKline plc, Novartis AG, Merck KGaA, Bayer AG, Sanofi, Cipla Inc., Ipca Laboratories Ltd., Dr. Reddy’s Laboratories Ltd, Zydus Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Parasitic Drugs Market Strategic Shifts
Antiparasitic development is pivoting from single-agent chemotherapy toward precision delivery systems and resistance-aware combination platforms that extend therapeutic utility against evolving pathogen populations.
Long-acting injectable formulations are unifying veterinary and human application platforms through shared depot-release polymer matrices. Cattle producers in Brazil and smallholder farmers in Kenya are adopting 90-day persistent anthelmintic implants at accelerating rates. This convergence is compressing the traditional species-siloed manufacturing model and forcing API suppliers toward flexible multi-indication production lines.
EMA's orphan drug incentives for neglected tropical diseases are redirecting European biotech pipelines toward leishmaniasis and Chagas disease targets previously abandoned after Phase II failures. The regulation's 10-year market exclusivity provision is altering portfolio prioritization at mid-cap developers. Sub-Saharan procurement agencies are responding by pre-negotiating access commitments before regulatory submission to secure post-approval supply guarantees.
Bulk purchasing consortia are consolidating demand-side leverage across Ministries of Health in endemic countries, displacing fragmented tender processes that previously favored spot-market suppliers. The Global Fund and UNITAID are channeling 70% of malaria therapy procurement through three-year framework agreements with volume guarantees. East African Community member states are piloting this consolidated model most aggressively, with pooled antimalarial orders now exceeding individual national volumes.
Anti-Parasitic Drugs Market Segmentation
Anti-parasitic drug procurement patterns diverge sharply across therapeutic settings, with veterinary bulk purchasing, hospital formulary controls, and retail pharmacy accessibility each demanding distinct formulation strategies and distribution architectures.
Product Type:
Formulation chemistry determines manufacturing scale, fermentation infrastructure requirements, and resistance management protocols that separate commodity suppliers from specialized API producers.
- Avermectins:Macrocyclic lactones derived from Streptomyces fermentation exhibit broad-spectrum nematocidal activity across human and veterinary indications. Demand concentrates in Brazilian cattle operations and Kenyan smallholder dairy cooperatives where 90-day persistent implants reduce labor costs. Resistance monitoring networks in these regions now mandate rotation with non-avermectin classes.
- Benzimidazoles:Synthetic heterocyclic compounds disrupt parasite microtubule assembly with established safety profiles in mass drug administration campaigns. India's national deworming program and Nigeria's schistosomiasis control initiative anchor procurement volumes, though efficacy erosion against hookworm strains in Southeast Asia is accelerating combination therapy adoption.
- Nitroimidazoles:Nitro-group activated prodrugs target anaerobic protozoan metabolism in giardiasis and amoebiasis indications.
- Sulfonamides:Folate pathway inhibitors retain niche utility in toxoplasmosis prophylaxis and veterinary coccidiosis control.
Avermectins lead volumes today; benzimidazoles are gaining share fastest through expanded access programs.
Therapy Area:
Disease burden distribution and donor funding concentration create divergent commercial models between vertically-integrated malaria programs and fragmented neglected tropical disease markets.
- Malaria:Artemisinin-based combination therapies command structured procurement through Global Fund and UNITAID framework agreements with three-year volume guarantees. ACT formulation demand clusters in East African Community pooled purchasing arrangements exceeding individual national order volumes, while resistance surveillance in Greater Mekong subregion drives pipeline investment toward triple-combination candidates.
- Schistosomiasis:Praziquantel mass administration relies on Merck KGaA donation commitments and WHO prequalification pathways with 4-7 year validation windows. Egyptian irrigation schemes and Nigerian river basin control programs generate seasonal procurement spikes synchronized with transmission dynamics.
- Giardiasis:Metronidazole and tinidazole oral therapies serve traveler and immunocompromised patient segments in North American and European retail channels.
- Leishmaniasis:Liposomal amphotericin B and miltefosine address visceral and cutaneous forms with EMA orphan drug incentives redirecting European biotech pipelines toward previously abandoned Phase II candidates.
Malaria dominates procurement value; leishmaniasis exhibits the steepest expansion trajectory as regulatory incentives activate development.
End User:
Channel structure determines pricing architecture, with institutional tender processes, retail margin stacking, and research subsidy mechanisms operating in parallel.
- Hospitals:Tertiary care centers in endemic regions manage severe malaria complications and leishmaniasis cases requiring intravenous amphotericin B or intensive supportive care. Teaching hospitals in India, Brazil, and Kenya anchor clinical trial recruitment networks for hookworm and schistosomiasis studies.
- Clinics:Primary health posts in sub-Saharan Africa and Southeast Asia deliver integrated community case management with rapid diagnostic test-guided ACT dispensing.
- Pharmacies:Retail networks in India and Nigeria distribute albendazole and mebendazole for soil-transmitted helminth self-treatment.
- Research Institutions:Tropical medicine institutes at five major sites maintain parasitology clinical trial infrastructure with site access bottlenecks for Phase II recruitment.
Hospitals capture premium intravenous volumes; clinics are expanding fastest through community health worker deployment.
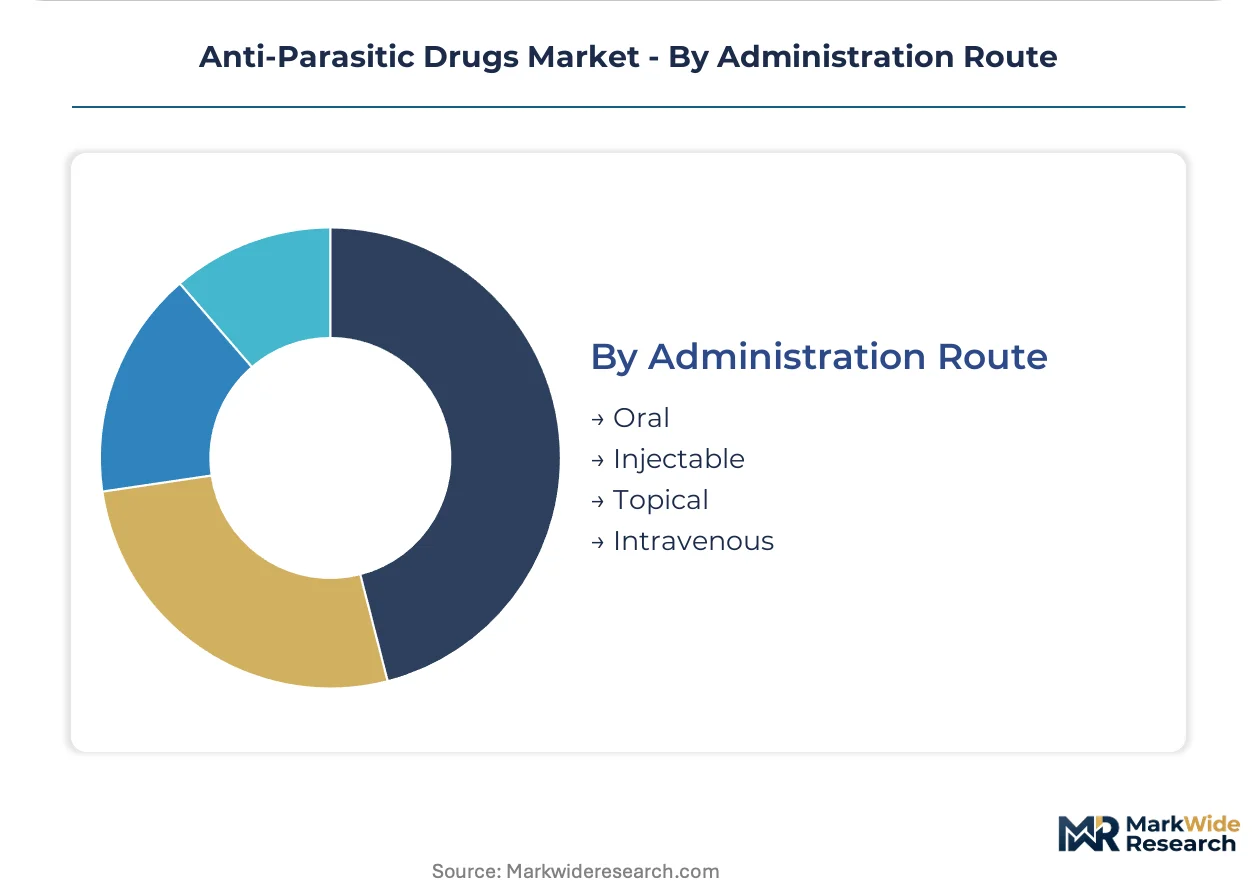
Administration Route:
Delivery mechanism selection reflects patient compliance constraints, bioavailability requirements, and veterinary labor cost minimization priorities.
- Oral:Fixed-dose combinations dominate human mass drug administration with CDSCO fast-track pathways accelerating Indian generic entry. Co-formulated artemether-lumefantrine and dihydroartemisinin-piperaquine tablets serve WHO prequalified procurement with stability-testing requirements filtering manufacturer qualification.
- Injectable:Long-acting depot formulations command 8-12x human-equivalent margins in US and EU veterinary channels where monthly heartworm prevention chewables drive compliance. Cattle producers in Brazil adopt 90-day persistent anthelmintic implants at accelerating rates.
- Topical:Pour-on and spot-on formulations address ectoparasite control in companion animal and livestock segments.
- Intravenous:Hospital-administered amphotericin B and pentamidine serve severe visceral leishmaniasis and trypanosomiasis with cold chain requirements limiting distribution reach.
Oral formulations anchor volume; injectables are climbing the fastest through veterinary premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting active pharmaceutical ingredient production toward jurisdictions with streamlined bioequivalence pathways and lower validation costs, compressing margins for manufacturers anchored in high-compliance markets.
India
Domestic API production for avermectin intermediates is tightening global supply lines as Hyderabad and Ahmedabad clusters expand fermentation capacity. CDSCO fast-track orphan pathways accelerate generic entry for tropical disease indications, enabling first-mover positioning in export tenders to sub-Saharan Africa.
China
Captive bioreactor networks in eastern provinces generate single-source vulnerability for macrocyclic lactone synthesis despite NMPA stability-testing requirements filtering tender qualification. Zhejiang and Jiangsu manufacturing hubs are repositioning toward antiparasitic intermediates as antibiotic margins compress.
Brazil
Cattle producers in Mato Grosso and São Paulo states are adopting 90-day persistent anthelmintic implants at accelerating rates, driving veterinary procurement volumes. ANVISA bioequivalence standards for generic formulations create entry barriers that favor established suppliers with local manufacturing partnerships.
Kenya
Smallholder dairy cooperatives in the Rift Valley anchor demand for mass drug administration campaigns against soil-transmitted helminths. WHO prequalification pathways for fixed-dose combinations impose validation windows that deter regional generic manufacturers from entering public procurement tenders.
Germany
EMA orphan drug incentives for neglected tropical diseases are redirecting European biotech pipelines toward leishmaniasis targets previously abandoned after Phase II failures. Bavaria-based veterinary antiparasitic manufacturing anchors Merck KGaA's position through scale advantages in macrocyclic lactone production.
Anti-Parasitic Drugs Market Competitive Environment
Indian producers anchor the cost-optimized generic tier; European and North American specialists hold premium positions through regulatory exclusivity and veterinary premiumization. The vendor base splits between fermentation-scale API suppliers and formulation-focused finished-dose manufacturers. Three archetypes dominate: multinational conglomerates with neglected-disease portfolios, mid-cap generic houses with CDSCO fast-track capabilities, and veterinary-focused manufacturers with implant formulation expertise. Competitive moves concentrate on backward integration into captive API supply and strategic partnerships with sub-Saharan procurement consortia.
Among European-based multinationals, GlaxoSmithKline plc and Novartis AG occupy positions exemplifying the neglected-disease portfolio archetype, leveraging established access contracts across endemic regions. Merck KGaA represents the veterinary-scale anchor, with manufacturing concentration supporting bulk supply commitments to regional eradication campaigns. These three entities illustrate how regulatory incentives and procurement consolidation are reshaping competitive positioning without requiring identical strategic postures.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Novartis AG |
| Merck KGaA |
| Bayer AG |
| Sanofi |
| Cipla Inc. |
| Ipca Laboratories Ltd. |
| Dr. Reddy's Laboratories Ltd |
| Zydus Group |
| Others |
Value Chain & Pricing Dynamics
WHO prequalification mandates for fixed-dose combinations gate qualified supply and premium-tier pricing access, compressing margins for manufacturers unable to navigate validation timelines while rewarding CDSCO-fast-tracked Indian producers with first-mover tender positioning in sub-Saharan procurement.
Pricing Analysis
Distributor margin layers in veterinary channels absorb 15-25 percentage points before retail markup, creating substantial pricing power concentration at the wholesale tier. Three-tier pricing structure across premium, standard, and economy levels separates WHO-prequalified ACT formulations from non-qualified generics and commodity spot purchases. Pricing pressure stems from bulk purchasing consortia consolidating demand-side leverage across East African Community member states. Veterinary clinics in US and EU markets exhibit lowest price sensitivity due to compliance-driven monthly heartworm prevention protocols.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Global Fund and UNITAID framework agreements with three-year volume guarantees. Fermentation capacity draws from captive bioreactor networks clustered in eastern China and expanding Hyderabad and Ahmedabad clusters in India. Single-source vulnerability concentrates in avermectin API synthesis where Streptomyces fermentation infrastructure remains geographically concentrated. Distribution runs through consolidated procurement consortia displacing fragmented spot-market tender processes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as resistance amplification in Plasmodium falciparum forces procurement agencies toward triple-combination ACT specifications with novel mechanisms of action.
For Market Incumbents: Anticipate resistance surveillance mandates compressing product lifecycles by investing in combination therapy pipelines with differentiated mechanisms. Merck KGaA's veterinary scale and GlaxoSmithKline's neglected-disease access contracts demonstrate how backward integration into captive API supply anchors position against emerging Indian generic houses with CDSCO fast-track capabilities.
For New Entrants and Emerging Players: CRISPR-based resistance diagnostics offer technology-first wedge into precision mass drug administration partnerships with drone-enabled sample logistics networks. White-space concentrates in leishmaniasis and Chagas disease targets where EMA orphan drug incentives redirect European biotech pipelines. Target East African Community pooled procurement arrangements exceeding individual national order volumes through pre-negotiated access commitments before regulatory submission.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap generic houses with CDSCO fast-track capabilities because regulatory arbitrage dynamics redirect API production toward jurisdictions with streamlined bioequivalence pathways. Five-to-ten year viability hinges on positioning ahead of resistance-driven therapy switches. Signal to monitor: WHO prequalification timeline compression for fixed-dose combinations as validation windows deter regional generic manufacturer entry.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase II recruitment networks at five tropical medicine institutes address site access bottlenecks for hookworm studies. |
| Regulatory Approval Pathway | FDA tropical disease priority review vouchers redirect private capital toward commercially marginal antiparasitic indications. |
| Manufacturing Scale-Up | Fermentation capacity expansion in Zhejiang and Jiangsu hubs repositions Chinese suppliers toward antiparasitic intermediates. |
| Pipeline Diversification | Long-acting injectable formulations unify veterinary and human platforms through shared depot-release polymer matrices. |
| Strategic Partnership | Pre-negotiated access commitments with sub-Saharan procurement consortia secure post-approval supply guarantees. |
Study Parameters
Bottom-up mass drug administration modeling reconciled against top-down fermentation capacity tracking forms the analytical core, combining primary interviews with regulatory affairs leads, formulary directors at tertiary care centers, veterinary procurement managers, and WHO prequalification specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and Global Fund procurement databases.
Historical trendline analysis of artemisinin raw material volatility and avermectin fermentation yield improvements anchors projection methodology across the analysis window. Segmentation dimensions span product type, therapy area, end user, and administration route with regional regulatory cluster overlays. CAGRs derive from elasticity-adjusted demand curves incorporating resistance surveillance data and vector-control policy integration mandates.
The model holds under stable WHO prequalification timelines and sustained donor funding concentration; deviation in artemisinin supply lag duration or CDSCO regulatory acceleration would shift volume trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Opium Tincture Market
Pharmaceuticals
Asia-Pacific Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Global Pharmacy Benefit Management (PBM) Market
Pharmaceuticals
Global Basal Insulin Market
Pharmaceuticals
Compound Glycyrrhizin Injection Market
Pharmaceuticals
Rheumatology Therapeutics Market
Pharmaceuticals
Asia-Pacific Meglitinide Market
Pharmaceuticals
Pharmaceutical Pellets Market
Pharmaceuticals
Normal Saline for Parenteral Use Market
Pharmaceuticals
Alkaptonuria Drugs Market
Pharmaceuticals
Europe Meglitinide Market
Pharmaceuticals
US Sex Reassignment Hormone Therapy Market
Pharmaceuticals
Iceland Pharmaceutical Market
Pharmaceuticals
Famotidine Market
Pharmaceuticals
Cryptococcosis Therapeutics Market
Pharmaceuticals
Global Pediatric Drugs Market