
 Structured Product Label Management Market | 2026-2036
Structured Product Label Management Market Size, Share, and Industry Trends Forecast 2026-2036
Structured Product Label Management Market Analytics
Enterprise-grade SPL compliance is rotating toward cloud-native architectures with embedded AI validation engines. Veeva Systems leverages its vault platform to anchor multi-tenant deployments across top-20 pharmaceutical manufacturers. IQVIA competes through integrated real-world evidence pipelines that extend label management into post-market surveillance workflows. Oracle Health Sciences dominates regulated environments with deep database connectivity to existing clinical trial management ecosystems.
Structured Product Label Management encompasses the creation, validation, submission, and maintenance of machine-readable XML-based label documents conforming to FDA SPL specifications, with embedded controlled vocabulary from the National Library of Medicine's RxNorm and MED-RT dictionaries. The primary commercial purpose is ensuring regulatory submission acceptance while enabling downstream drug information exchange across pharmacies, payers, and electronic health record systems. Regulatory Compliance applications within the Application Area segment lead current revenue pools as FDA rejection rates for improperly formatted SPL submissions drive replacement demand. Digital Printing within Labeling Technology is capturing fastest growth as pharmaceutical manufacturers adopt variable-data serialization for track-and-trace mandates. The End User base concentrates among Manufacturers, where batch-record integration requirements create stickier platform relationships than standalone labeling tools permit.
FDA's SPL guidance documents and the NLM's DailyMed distribution requirements shape product roadmap priorities for every vendor selling into US pharmaceutical markets. EMA's ISO IDMP implementation timeline and Health Canada's evolving label format standards are forcing platform architects to design multi-jurisdiction submission engines rather than single-regulator point solutions. Stakeholders must monitor whether FDA advances machine-readable label requirements into biologics and combination product categories, as this expansion would trigger replacement cycles across installed bases currently serving small-molecule portfolios only.
Market Dynamics
Cloud-native architecture migration is fragmenting the installed base of legacy on-premise SPL systems, forcing pharmaceutical manufacturers into multi-year replacement cycles as FDA validation requirements tighten for machine-readable submissions.
Growth Catalysts
- FDA SPL Mandates:The agency's escalating rejection rates for improperly formatted XML submissions are compelling manufacturers to upgrade from manual validation workflows to automated compliance engines.
- RxNorm Integration:The National Library of Medicine's controlled vocabulary expansion into combination products is requiring platform refreshes that embed real-time dictionary synchronization capabilities.
- Digital Printing:Variable-data serialization for track-and-trace mandates is pulling label management systems into direct integration with packaging line execution software.
Market Restraints
- Validation Timeline Compression:FDA's 21 CFR Part 11 compliance requirements extend cloud migration projects by 18-24 months due to computer system validation protocols.
- Specialized Talent Scarcity:The intersection of pharmaceutical regulatory science and XML schema engineering creates acute hiring bottlenecks in Boston and San Francisco metro clusters.
- Legacy System Entrenchment:Batch-record integration dependencies with existing manufacturing execution systems create switching costs that anchor incumbents.
Strategic Opportunities
- Biologics Expansion:FDA's anticipated extension of machine-readable label requirements into biologics and cell therapy categories would unlock replacement demand across portfolios currently limited to small molecules.
- ISO IDMP Convergence:EMA's implementation timeline is forcing platform architects to design multi-jurisdiction engines rather than single-regulator solutions, opening European contract opportunities.
- AI Validation Engines:Embedded machine learning for automated SPL error detection represents whitespace for vendors able to train models on FDA rejection datasets.
Industry Challenges
- Cross-Functional Coordination:Label changes require simultaneous updates across regulatory affairs, quality assurance, manufacturing, and pharmacovigilance departments with conflicting priority matrices.
- Dictionary Version Synchronization:RxNorm and MED-RT monthly releases create version-control complexity that automated pipelines must resolve without manual intervention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Structured Product Label Management Market |
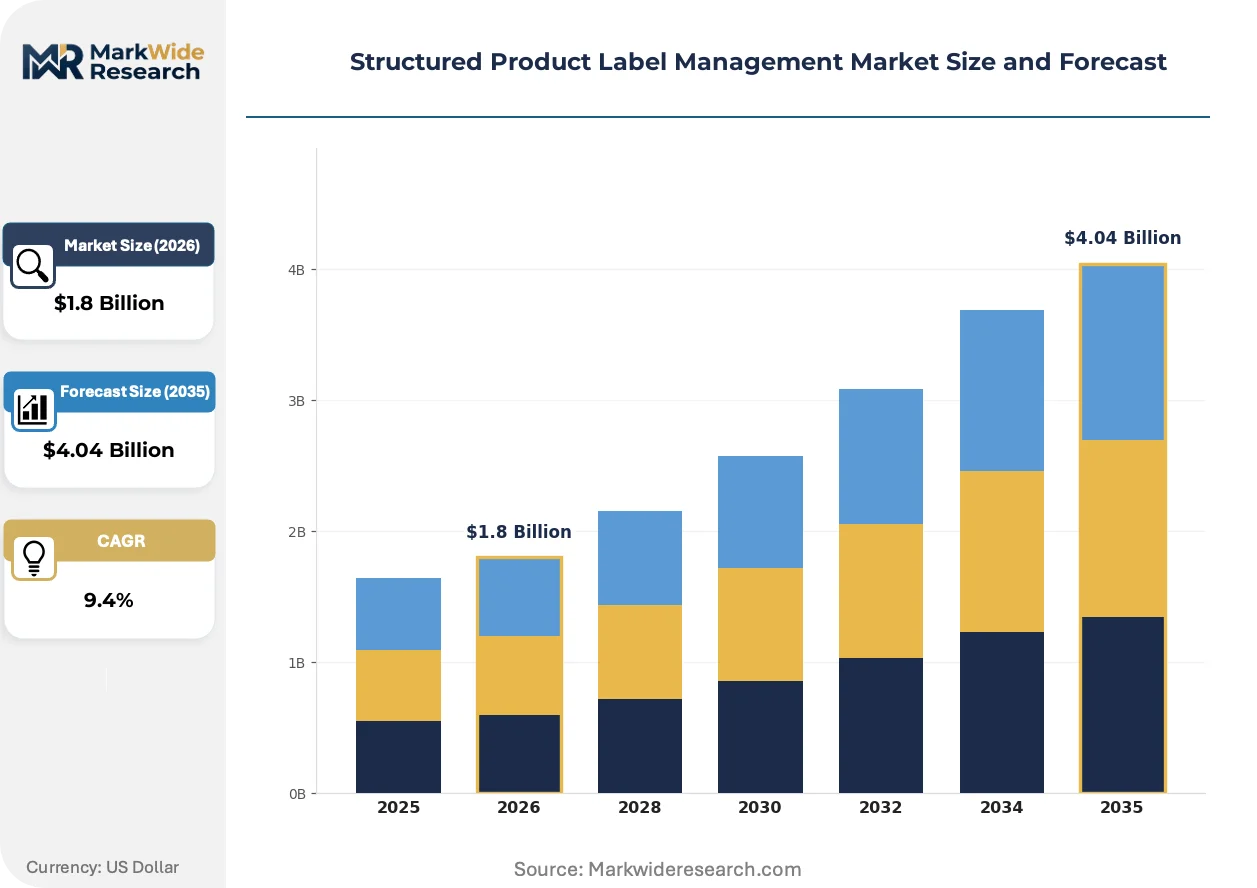
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Food & Beverages, Cosmetics, Household Goods Labeling Technology: Digital Printing, Flexographic, Lithographic, Screen Printing Application Area: Regulatory Compliance, Branding, Inventory Management, Serialization End User: Manufacturers, Retailers, Distribution Centers, Logistics Providers |
| Companies Covered | Veeva Systems, ArisGlobal, IQVIA, PharmaLex, Extedo, Oracle Health Sciences, DXC Technology, MasterControl, Ennov, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Structured Product Label Management Market Evolving Landscape
Artificial intelligence is embedding into validation workflows, regulatory data standards are converging across jurisdictions, and deployment models are shifting from perpetual licenses to consumption-based architectures.
Natural language processing engines are fragmenting traditional manual review processes by automatically flagging SPL schema violations before FDA submission. Mid-tier pharmaceutical manufacturers are adopting these tools fastest, driven by smaller regulatory affairs headcounts. The technology is compressing error detection cycles from days to minutes while reducing consultant dependency for routine validation tasks.
EMA's ISO IDMP implementation timeline is forcing platform vendors to rebuild submission engines for five-dimensional product master data structures. This regulatory pressure is accelerating R&D spending on multi-jurisdiction compliance architectures. European manufacturers with US export obligations are piloting these converged systems first, seeking to eliminate redundant label maintenance workflows.
Subscription pricing models are displacing perpetual license structures across the buyer base, with annual recurring revenue contracts now dominating new vendor relationships. Large pharmaceutical procurement departments are consolidating vendor relationships around platform ecosystems rather than point solutions. This shift is most visible among top-20 manufacturers seeking to unify SPL management with clinical trial disclosure and promotional material review workflows.
Structured Product Label Management Market Segmentation
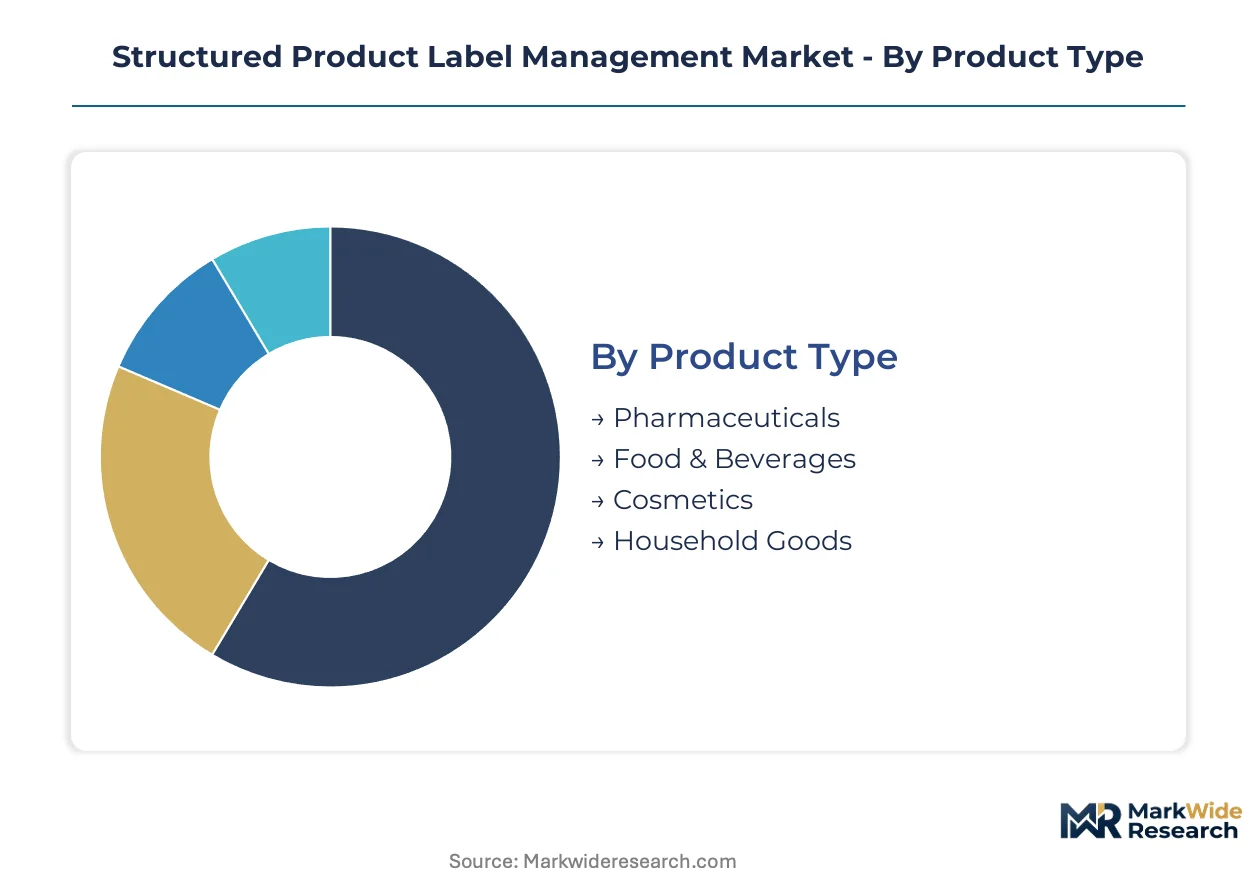
Segmentation in Structured Product Label Management reveals how regulatory pressure and technology substitution reshape commercial positioning. Pharmaceutical manufacturers drive premium platform investment while adjacent verticals face commoditization from generic labeling tools.
Product Type:
Substitution pressure from adjacent compliance software segments reshapes competitive boundaries across product categories, with regulatory complexity determining defensibility.
- Pharmaceuticals:XML-based SPL submissions to FDA demand specialized validation engines with embedded RxNorm dictionary synchronization. Large manufacturers in the United States anchor demand here, as rejection rates for improperly formatted machine-readable labels force platform upgrades from manual workflows.
- Food & Beverages:FDA nutritional labeling mandates and GS1 barcode standards create compliance requirements, though generic enterprise labeling software poses stronger substitution threats than in regulated pharma environments.
- Cosmetics:INCI ingredient disclosure rules and EU Regulation 1223/2009 compliance requirements vary by export destination, fragmenting demand across regional labeling platforms rather than unified SPL systems.
- Household Goods:Consumer product safety labeling and multilingual packaging requirements concentrate demand in private-label manufacturers serving mass retail channels.
Pharmaceuticals anchors the volume base while Food & Beverages gains share at the steepest rate as CPG manufacturers adopt serialization for supply chain traceability.
Labeling Technology:
Cost tier stratification separates capital-intensive digital infrastructure from legacy mechanical systems, with migration timelines varying by end-use scale and regulatory urgency.
- Digital Printing:Variable-data inkjet and toner systems enable lot-level serialization for DSCSA track-and-trace mandates. Pharmaceutical packaging lines in New Jersey and North Carolina metro clusters drive replacement demand as compliance deadlines tighten.
- Flexographic:Rotary letterpress analog systems dominate high-volume commodity labeling where changeover frequency remains low and substrate flexibility matters.
- Lithographic:Offset printing maintains cost advantages for long-run pharmaceutical inserts and folding cartons despite slower makeready times.
- Screen Printing:Heavy-deposit applications for tamper-evident seals and braille overlays serve niche compliance requirements in European export packaging.
Flexographic equipment retains the largest installed base while Digital Printing climbs the fastest as FDA serialization mandates accelerate capital deployment.
Application Area:
Application maturity curves diverge sharply, with foundational compliance functions approaching saturation while emerging use cases reshape platform roadmaps.
- Regulatory Compliance:FDA SPL validation, EMA ISO IDMP conformance, and Health Canada label format requirements constitute the core commercial purpose. Pharmaceutical regulatory affairs departments in Boston and San Francisco metro clusters concentrate procurement authority here.
- Branding:Consistent visual identity across multi-channel distribution competes for budget priority against mandatory compliance investments.
- Inventory Management:Warehouse barcode and RFID integration extends label management into ERP connectivity projects.
- Serialization:Unique identifier generation and aggregation for supply chain authentication represents the fastest-expanding functional requirement.
Regulatory Compliance absorbs the majority of current spending while Serialization expands most quickly as track-and-trace mandates proliferate beyond pharmaceuticals into medical devices.
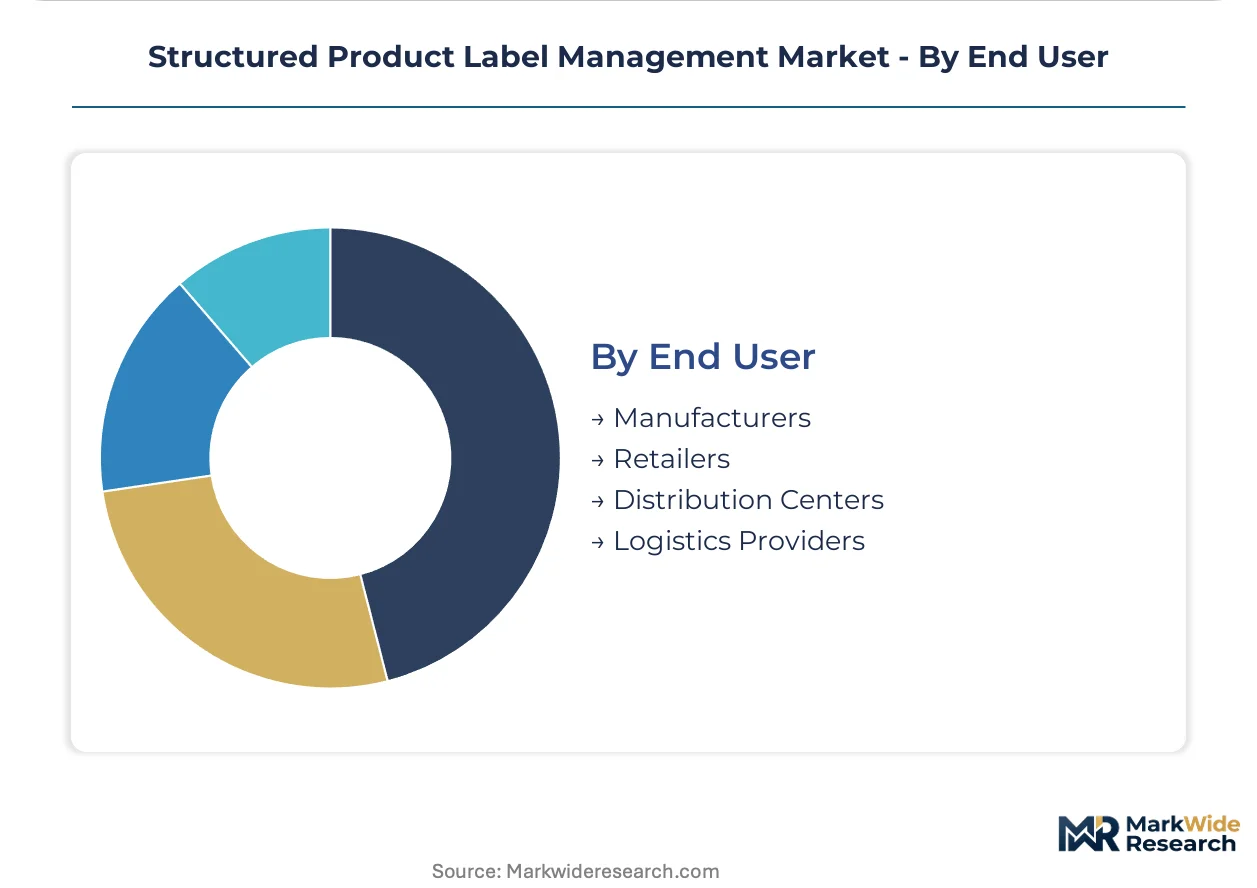
End User:
Customer type concentration determines platform stickiness, with manufacturing integration requirements creating higher switching costs than downstream distribution relationships.
- Manufacturers:Batch-record integration with manufacturing execution systems and quality management platforms creates the stickiest vendor relationships. Top-20 pharmaceutical companies anchor enterprise contract values here.
- Retailers:Private-label sourcing departments require supplier label standardization without direct SPL submission obligations.
- Distribution Centers:Cross-dock relabeling for export compliance and damaged goods replacement generates transactional demand.
- Logistics Providers:Third-party warehousing and freight forwarding operations need temporary label generation for customs documentation and hazmat classification.
Manufacturers dominate current revenue pools while Logistics Providers show the steepest adoption trajectory as pharmaceutical cold chain requirements extend labeling accountability downstream.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based pharmaceutical manufacturers export SPL-compliant labeling systems to European and Asia-Pacific markets, creating a technology trade corridor that shapes regional adoption timelines. FDA validation requirements drive platform specifications that foreign regulators increasingly reference.
United States
FDA rejection rates for improperly formatted XML submissions compel pharmaceutical manufacturers to upgrade from manual workflows to automated compliance engines. The agency's SPL guidance documents and DailyMed distribution requirements dictate product roadmap priorities for every vendor selling into US markets. Boston and San Francisco metro clusters concentrate procurement authority among top-20 pharmaceutical companies.
Germany
EMA's ISO IDMP implementation timeline forces platform architects to design multi-jurisdiction submission engines rather than single-regulator point solutions. REACH compliance obligations and MDR requirements for medical devices extend labeling accountability into combination product categories. Frankfurt and Munich anchor demand among exporters with US pharmaceutical obligations.
Switzerland
Swissmedic's alignment with FDA technical standards creates favorable conditions for vendors with existing US validation engines. Basel's pharmaceutical concentration drives premium platform investment from Roche and Novartis supply chain operations. Geneva-based contract manufacturers pilot converged systems for multi-market label maintenance.
United Kingdom
MHRA's post-Brexit labeling divergence from EU templates forces platform refreshes for exporters serving both European and British markets. London's regulatory affairs consultancies drive demand for validation tools that manage parallel submission workflows. Cambridge biotech clusters adopt cloud-native architectures faster than legacy pharmaceutical strongholds.
India
CDSCO's tightening label format standards for export-oriented pharmaceutical manufacturers accelerate adoption of FDA-validated platforms. Hyderabad and Mumbai manufacturing hubs invest in serialization-ready systems for DSCSA compliance. Bangalore's IT services sector supplies implementation talent for global SPL migration projects.
Structured Product Label Management Market Competitive Landscape
Listed leaders compete with private specialists across cloud deployment models, creating a tiered structure where scale-driven platforms face nimble regulatory specialists. The vendor base concentrates among three archetypes: vault-platform ecosystems, integrated real-world evidence pipelines, and regulated-environment database specialists. Consolidation pressure intensifies as pharmaceutical procurement departments unify vendor relationships around platform ecosystems rather than point solutions.
Within the vault-platform tier, Veeva Systems anchors multi-tenant deployments across top-20 pharmaceutical manufacturers. IQVIA occupies a position exemplifying integrated evidence pipelines that extend label management into post-market surveillance workflows. Oracle Health Sciences represents regulated-environment specialists with deep database connectivity to clinical trial management ecosystems. These three entities collectively illustrate how competitive positioning rotates toward embedded AI validation engines and consumption-based pricing architectures.
| Leading Market Players |
|---|
| Veeva Systems |
| ArisGlobal |
| IQVIA |
| PharmaLex |
| Extedo |
| Oracle Health Sciences |
| DXC Technology |
| MasterControl |
| Ennov |
| Others |
Value Network & Pricing Analysis
Ninety-day implementation timelines for cloud-native SPL migrations concentrate pricing power among vendors with pre-validated FDA submission engines, while compressed validation schedules amplify buyer switching costs across pharmaceutical procurement departments. This temporal pressure shapes contract structures more than raw feature differentiation, locking manufacturers into multi-year subscription commitments before competitor platforms complete equivalent compliance certifications.
Pricing Analysis
Industrial OEM buyers anchor subscription-tiered pricing structures across the SPL management landscape, with annual recurring revenue contracts displacing perpetual licenses at the fastest clip. Pricing stratifies across enterprise-grade validation engines with embedded AI error detection, mid-tier cloud deployments with manual review workflows, and entry-level point solutions lacking RxNorm synchronization capabilities. Cost compression in mid-tier segments is intensifying because private-label pharmaceutical manufacturers prioritize budget certainty over advanced functionality. Contract manufacturers and export-oriented generic producers exhibit the highest price sensitivity, while top-20 pharmaceutical companies absorb premium tiers for batch-record integration and multi-jurisdiction compliance architectures.
Supply Chain Analysis
FDA validation documentation bottlenecks in Boston and San Francisco metro clusters tether platform deployment capacity to specialized regulatory affairs talent pools, constraining vendor expansion velocity. Software development feeds from India and Ireland engineering centers, while cloud infrastructure rests on hyperscaler regions in the United States, Germany, and Singapore. Single-source vulnerability concentrates in XML schema engineering expertise, where pharmaceutical regulatory science intersects with technical implementation. Distribution runs through direct enterprise sales teams for large manufacturers and channel partners serving mid-tier pharmaceutical companies without dedicated regulatory technology procurement functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among top-20 pharmaceutical procurement departments, which are consolidating vendor relationships around unified platform ecosystems rather than fragmented point solutions. This consolidation compresses margins for standalone labeling specialists while rewarding integrated suite providers.
For Market Incumbents: Shield installed base relationships by embedding AI validation engines deeper into manufacturing execution system workflows, creating technical switching costs that rival contractual lock-in periods. Prioritize backward integration into RxNorm dictionary synchronization infrastructure to neutralize emerging entrants promising real-time vocabulary updates. Regulatory affairs talent scarcity in Boston and San Francisco represents the critical defensive lever for platform differentiation. For New Entrants and Emerging Players: Lead with AI-native validation architectures targeting mid-tier pharmaceutical manufacturers with smaller regulatory affairs headcounts, where manual review bottlenecks create acute pain points. Biologics and cell therapy categories offer the most penetrable white space, as FDA machine-readable label requirements remain unenforced in these portfolios. A compliance-as-a-service go-to-market angle, bundling validation consulting with software subscriptions, bypasses entrenched procurement relationships at larger manufacturers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because jurisdictional divergence between FDA SPL mandates and EMA ISO IDMP timelines perpetuates demand for multi-engine platforms. Acquisition targets should display pre-built validation pipelines for at least two major regulatory regimes, with existing customer relationships spanning both small-molecule and emerging biologics portfolios. The signal to watch is FDA guidance document releases extending machine-readable requirements into combination products and gene therapies, which would trigger replacement cycles across installed bases currently limited to traditional pharmaceutical categories.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies SPL management with clinical trial disclosure and pharmacovigilance workflows for top-20 manufacturers. |
| AI Validation Engine Development | Compresses FDA submission error detection from days to minutes using natural language processing trained on rejection datasets. |
| Multi-Jurisdiction Compliance Architecture | Accommodates simultaneous FDA SPL and EMA ISO IDMP submissions without redundant label maintenance workflows. |
| Regulatory Talent Acquisition | Secures scarce XML schema engineering expertise in Boston and San Francisco metro clusters. |
| Biologics Portfolio Expansion | Positions platforms for anticipated FDA machine-readable label requirements in cell therapy and gene therapy categories. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with regulatory affairs directors, pharmaceutical IT procurement officers, SPL platform engineers, and manufacturing quality managers. Secondary validation drew from FDA SPL guidance documents, EMA ISO IDMP implementation timelines, NLM RxNorm release schedules, and pharmaceutical company SEC filings disclosing regulatory technology investments. Bottom-up segmentation modeling triangulated against top-down market sizing derived from vendor revenue disclosures and pharmaceutical R&D expenditure patterns.
Across the analysis window, volume and value outputs reflect analytical frameworks segmented by deployment model, organization size, therapeutic area portfolio complexity, and regional regulatory cluster. CAGRs were derived from growth driver elasticity modeling against FDA mandate enforcement timelines and cloud migration adoption curves. Forecast inputs incorporated pharmaceutical manufacturer capital expenditure intentions for serialization infrastructure and validated platform replacement cycles.
Forecasts assume regulatory continuity in FDA SPL enforcement and EMA ISO IDMP implementation; material policy shifts would require re-modeling submission engine demand trajectories. Practitioners should keep alternative scenarios live as biologics labeling requirements and combination product category expansions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Roflumilast API Market
Pharmaceuticals
Opioid Analgesics Market
Pharmaceuticals
Global Finasteride Market
Pharmaceuticals
Asia-Pacific Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Respiratory Disease Vaccine Market
Pharmaceuticals
Peptide Therapeutics Market
Pharmaceuticals
PDE Inhibitors Market
Pharmaceuticals
Wujibaifeng Pills Market
Pharmaceuticals
Global Pharmaceutical Gelatin Market
Pharmaceuticals
Africa Generic Pharmaceutical Market
Pharmaceuticals
Acne Therapeutics Market
Pharmaceuticals
Long-Acting Monoclonal Antibodies Market
Pharmaceuticals
Hyperphosphatemia Market
Pharmaceuticals
Global Hemostasis and Tissue Sealing Agents Market
Pharmaceuticals
Pharmaceuticals Serialization Market
Pharmaceuticals
North America Pharmaceutical Warehousing Market