
 Isotretinoin Drugs Market | 2026-2036
Isotretinoin Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Isotretinoin Drugs Market Foresight
The gap between patented originator formulations and commoditized generic capsules is repositioning how manufacturers compete on bioequivalence documentation and supply security. Teva Pharmaceutical Industries Ltd. leverages its vertically integrated API-to-dosage-form capability to sustain cost leadership across multiple markets. F. Hoffmann-La Roche Ltd., the originator of isotretinoin, anchors premium positioning through decades of clinical data and physician familiarity. Dr. Reddy's Laboratories Ltd. competes aggressively in emerging markets with dedicated dermatology portfolios and localized manufacturing.
Isotretinoin drugs are synthetic retinoids derived from vitamin A, formulated as oral capsules typically containing 10 mg to 40 mg of active pharmaceutical ingredient, that function by reducing sebaceous gland activity and normalizing keratinization to treat severe recalcitrant nodular acne. Capsules dominate value capture due to established oral bioavailability and decades of clinical validation, while topical gel represents a faster-growing structural segment as prescribers seek localized delivery with reduced systemic teratogenic exposure. Dermatology clinics command the largest share of end-user demand, though homecare channels are expanding where telemedicine oversight and centralized pharmacy dispensing align with REMS compliance requirements.
The FDA enforces iPLEDGE REMS protocols that mandate monthly prescriber, pharmacist, and patient verification before any isotretinoin dispensing, directly constraining market access velocity and shaping distribution architecture. EMA and national European regulators including ANSM in France apply parallel pregnancy-prevention programs under varying implementation strictness, fragmenting go-to-market requirements across the continent. Manufacturers and distributors must monitor how regulatory divergence between FDA REMS and European teratogenic drug frameworks affects cross-border clinical trial design and label harmonization strategies.
Market Dynamics
The FDA's iPLEDGE REMS program creates a structural bottleneck that constrains prescription velocity while simultaneously erecting competitive moats around compliant distribution networks. This regulatory architecture forces manufacturers to build specialized pharmacy partnerships and patient-monitoring infrastructure that smaller competitors cannot replicate.
Growth Catalysts
- Severe Acne Prevalence:Rising diagnosis rates among adolescent and young adult populations in the United States are expanding the addressable patient pool for oral retinoid therapy.
- EMA Parallel Programs:The European Medicines Agency's teratogenic drug frameworks are harmonizing across member states, reducing regulatory fragmentation for cross-border commercialization.
- Telemedicine Integration:Remote dermatology platforms are absorbing REMS-compliant workflows, enabling centralized pharmacy dispensing and expanding prescriber reach.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient production clusters in India and China, creating geographic vulnerability to export restrictions or quality enforcement actions.
- Teratogenic Liability:Mandatory pregnancy prevention programs impose fixed compliance costs regardless of prescription volume, compressing margins on low-dose generic formulations.
- Topical Substitutes:Adapalene and tretinoin creams for moderate acne divert patients who might otherwise progress to oral isotretinoin protocols.
Strategic Opportunities
- Brazil Expansion:ANVISA's evolving dermatology guidelines and underpenetrated specialist networks present white-space opportunity for structured patient-access programs.
- Pediatric Labeling:Expanded FDA indications for younger severe acne patients could unlock prescriber comfort in previously restricted age segments.
- Localized Manufacturing:India's PLI scheme incentives for active pharmaceutical ingredients are attracting backward-integrated investments that reduce import dependency.
Industry Challenges
- REMS Infrastructure Costs:Building and maintaining iPLEDGE-compliant patient verification systems demands specialized IT and pharmacy coordination capabilities.
- Prescriber Certification Bottlenecks:Monthly registration requirements and training modules limit the pace at which new dermatologists can initiate isotretinoin therapy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isotretinoin Drugs Market |
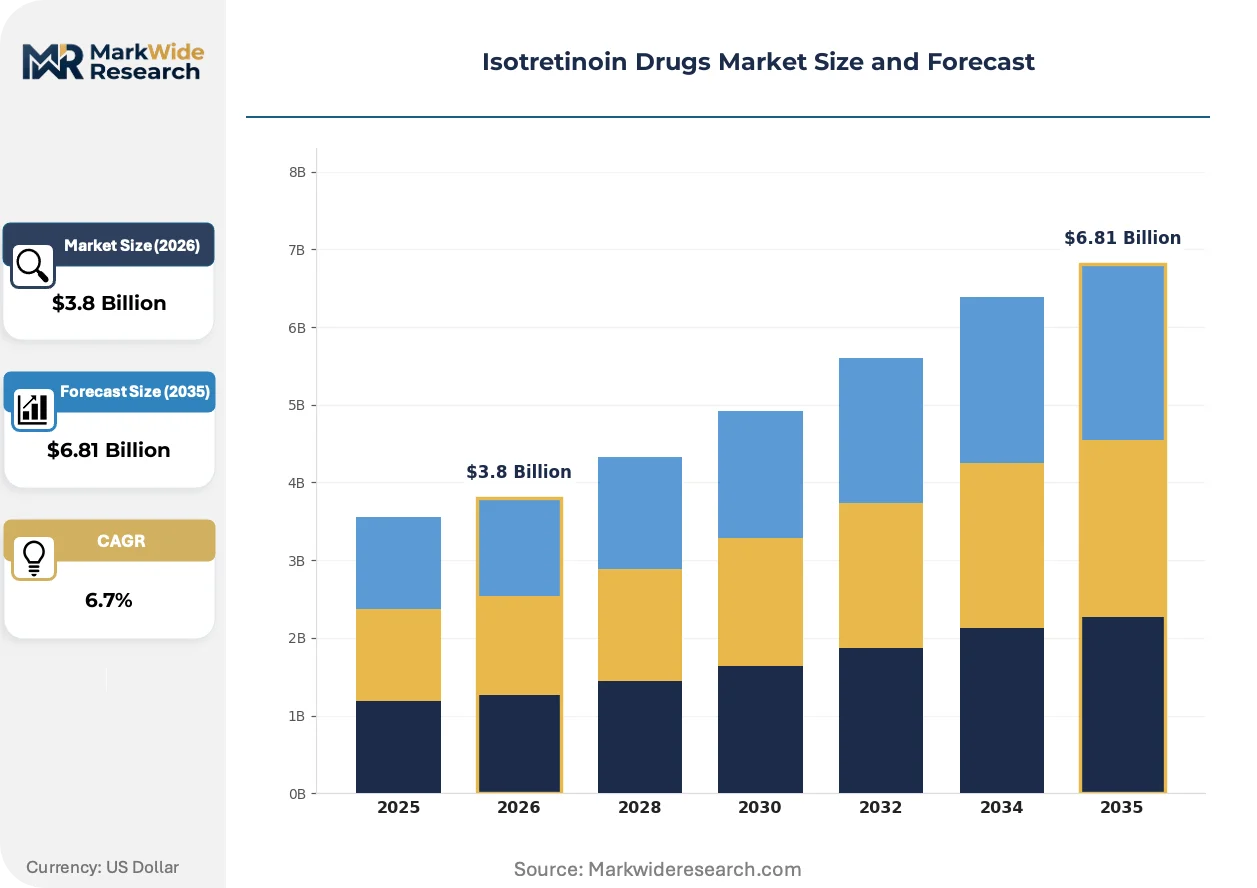
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Tablets, Topical Gel, Injectable End User: Dermatology Clinics, Hospitals, Homecare, Pharmacies Therapy Area: Acne, Psoriasis, Off-Label Uses, Skin Disorders Delivery Mode: Oral, Topical, Intravenous, Subcutaneous |
| Companies Covered | F. Hoffmann-La Roche Ltd., Teva Pharmaceutical Industries Ltd., Dr. Reddy's Laboratories Ltd., Sun Pharmaceutical Industries Ltd., Abbott Laboratories, Mylan NV, GlaxoSmithKline plc, Cipher Pharmaceuticals Inc., Douglas Pharmaceuticals Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isotretinoin Drugs Market Shifts & Advancements
Formulation science and distribution architecture are converging to address the central tension between systemic efficacy and teratogenic risk management. Manufacturers are pursuing localized delivery mechanisms and digital compliance tools that reshape how prescribers and patients interact with the drug.
Microsphere-encapsulated isotretinoin formulations are absorbing sustained-release engineering advances that smooth plasma concentration curves and reduce peak-dose side effects. Pediatric dermatology practices in the United States are adopting these modified-release capsules to improve tolerability in weight-variable adolescent patients. The technology is absorbing market share from conventional immediate-release generics by commanding reimbursement premiums for reduced monitoring burden.
REACH registration requirements for retinoid compounds are tightening documentation standards for European manufacturers and importers. The European Chemicals Agency's expanded substance evaluation protocols are extending lead times for new supplier qualification. German and French dermatology networks are responding by consolidating purchases around established API sources with complete dossier portfolios.
Centralized specialty pharmacy dispensing is replacing traditional retail distribution for isotretinoin prescriptions in the United States. REMS-mandated patient verification and pregnancy testing align naturally with mail-order pharmacy infrastructure that can coordinate monthly shipments. This channel rotation is most visible in California and Texas, where large dermatology groups have integrated with closed-network pharmacy partners to streamline compliance workflows.
Isotretinoin Drugs Market Segmentation
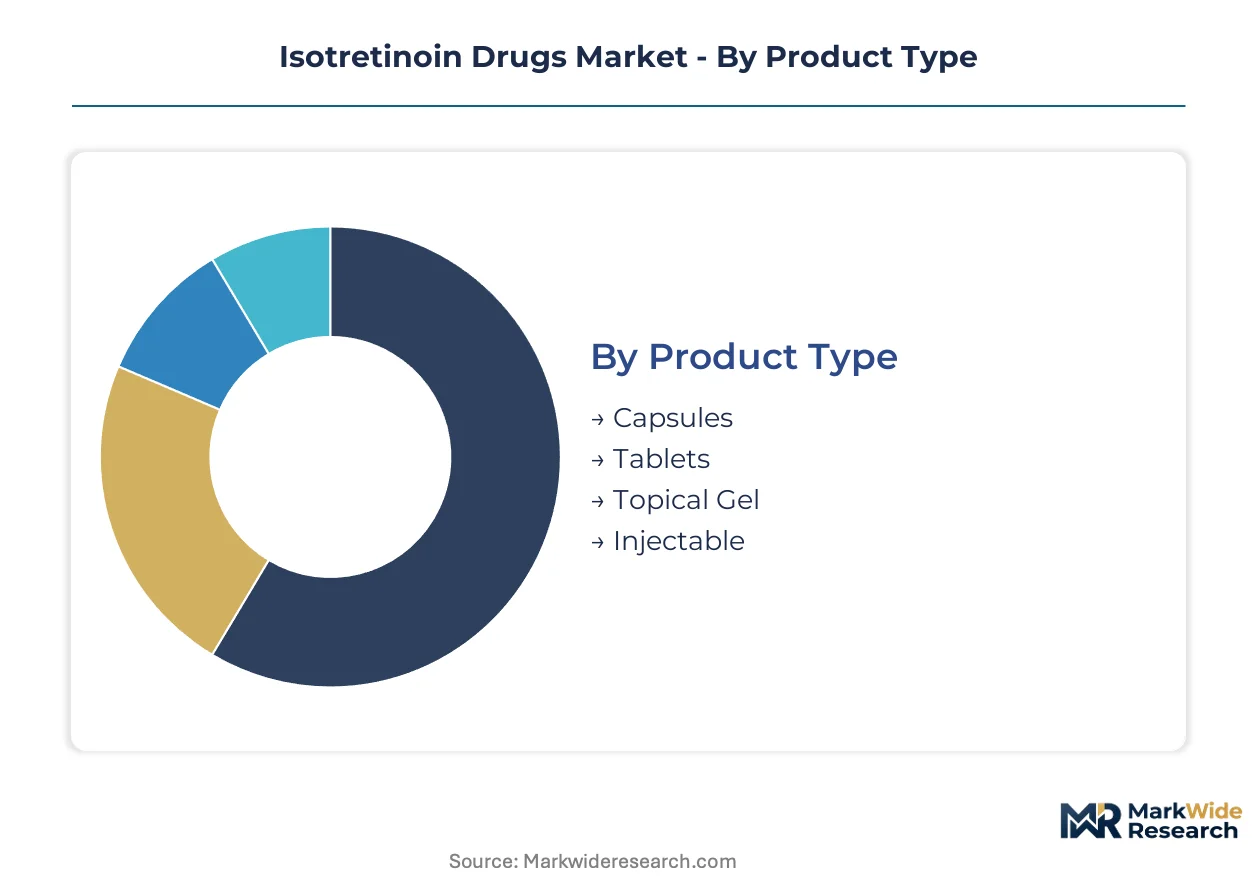
Isotretinoin market dynamics fragment across formulation formats, care settings, and delivery technologies. Each segmentation layer reveals distinct margin structures and compliance burdens that reshape competitive positioning.
Product Type:
Capsules absorb the majority of volume while topical gel commands expanding premium pricing for teratogenic risk mitigation.
- Capsules:Hard gelatin shells containing 10 mg to 40 mg isotretinoin deliver established oral bioavailability with decades of FDA-validated safety data. Dermatology clinics in the United States concentrate demand here for severe nodular acne protocols, though REMS compliance costs compress margins on commoditized generics.
- Topical Gel:Microsphere-encapsulated formulations enable localized retinoid delivery with reduced systemic absorption. Prescribers in Germany and France are shifting moderate cases toward this channel to bypass monthly pregnancy verification burdens.
- Tablets:Compressed dosage forms offer manufacturing flexibility but lack the lipid-dissolution advantages of gelatin encapsulation.
- Injectable:Parenteral isotretinoin remains experimental, confined to investigator-initiated trials for psoriasis refractory to oral therapy.
Today's leader: Capsules. Tomorrow's challenger: Topical Gel.
End User:
Institutional channels dominate prescription velocity while homecare absorbs telemedicine-enabled expansion.
- Dermatology Clinics:Specialist practices generate the highest per-prescription revenue through bundled consultation and monitoring fees. California and Texas clinic networks have integrated closed-loop pharmacy partnerships to streamline iPLEDGE workflows.
- Homecare:Centralized mail-order dispensing aligns with REMS pregnancy verification requirements. ANVISA-regulated programs in Brazil are piloting similar remote-monitoring structures for underserved interior states.
- Hospitals:Inpatient dermatology wards handle acute acne fulminans cases requiring supervised isotretinoin initiation.
- Pharmacies:Retail dispensing persists in European markets with less restrictive teratogenic frameworks than the FDA's REMS architecture.
Dermatology Clinics anchor current value capture. Homecare channels are climbing the fastest as telemedicine infrastructure matures.
Therapy Area:
Acne indications concentrate regulatory investment while off-label expansion faces evidence thresholds.
- Acne:Severe recalcitrant nodular acne represents the sole FDA-approved indication with full reimbursement support. EMA-aligned markets including France and Italy maintain parallel pregnancy-prevention programs for this segment.
- Off-Label Uses:Rosacea and sebaceous hyperplasia applications absorb clinician experimentation where formal trials are uneconomical.
- Psoriasis:Oral retinoid therapy for pustular variants remains second-line to biologics in most prescribing guidelines.
- Skin Disorders:Keratinization disorders like Darier disease capture minimal volume due to ultra-orphan prevalence.
Acne commands present economics. Off-Label Uses present the steepest expansion trajectory if pediatric labeling expands.
Delivery Mode:
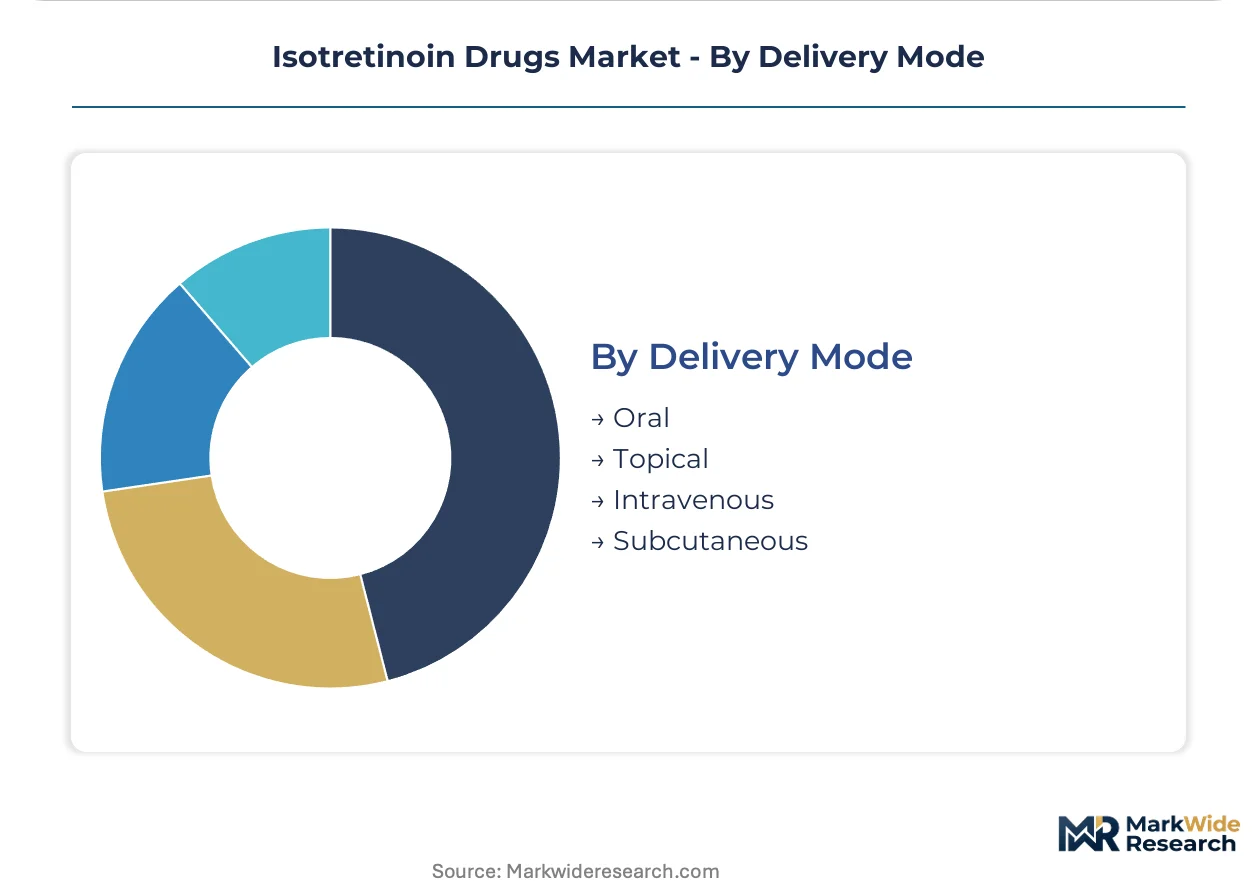
Oral administration dominates bioavailability while topical routes address safety liability.
- Oral:Gastrointestinal absorption of isotretinoin requires co-administration with high-fat meals for therapeutic plasma levels. CDSCO-registered Indian manufacturers optimize capsule formulations for this pharmacokinetic requirement.
- Topical:Percutaneous delivery systems reduce systemic exposure but struggle with stratum corneum penetration of this lipophilic molecule.
- Intravenous:No approved isotretinoin IV formulation exists; investigational liposomal carriers remain preclinical.
- Subcutaneous:Depot injection concepts for isotretinoin have attracted patent filings but no commercial development.
Oral delivery sustains incumbent position. Topical approaches are gaining share fastest through microsphere engineering advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dermatologist density and specialist clinic networks determine prescription velocity across major markets. Regulatory stringency around teratogenic risk management creates divergent compliance architectures that reshape competitive access.
United States
California and Texas host the densest concentrations of iPLEDGE-certified dermatology practices, with Los Angeles and Houston clinic networks driving prescription volume. FDA REMS protocols mandate monthly prescriber-pharmacist-patient verification through centralized databases. Mail-order specialty pharmacies in Arizona and Florida coordinate pregnancy testing and drug dispensing under closed-network partnerships with dermatology groups.
Germany
Baden-Württemberg and Bavaria anchor dermatological research and private clinic expansion for severe acne protocols. The country's national pharmaceutical regulator enforces pregnancy-prevention documentation parallel to EMA frameworks, though with decentralized state-level implementation. Frankfurt and Munich hospital networks concentrate investigator-initiated trials for modified-release isotretinoin formulations.
India
Maharashtra and Telangana manufacture the majority of isotretinoin active pharmaceutical ingredient through CDSCO-registered facilities. The PLI scheme for APIs attracts backward-integrated investments from formulation producers seeking captive supply security. Hyderabad and Mumbai pharmaceutical clusters export to regulated markets while supplying domestic dermatology chains expanding into tier-2 cities.
Brazil
São Paulo state dermatology networks absorb the highest prescription volumes for severe nodular acne in Latin America. ANVISA's evolving teratogenic drug guidelines create compliance windows for structured patient-access programs. Rio de Janeiro and Minas Gerais interior states pilot remote-monitoring structures adapted from US telemedicine models.
France
Île-de-France and Provence-Alpes-Côte d'Azur concentrate private dermatology demand and hospital-based acne fulminans treatment. ANSM applies stricter pregnancy-prevention program enforcement than neighboring jurisdictions, fragmenting prescriber workflows. Lyon and Marseille clinic networks consolidate purchases around established API sources with complete REACH dossier portfolios.
Isotretinoin Drugs Market Competitive Landscape
Top-tier vendors anchor originator and large-generic portfolios, while mid-tier specialists compete on regional manufacturing and dermatology-focused distribution. The market structures around three concentration nodes: vertically integrated API-to-formulation producers, originator firms with decades of clinical data assets, and emerging-market generic houses with localized cost positions. Strategic moves center on backward integration into active pharmaceutical ingredient production and specialty pharmacy partnership networks that satisfy REMS compliance requirements.
Among Swiss and Israeli pharmaceutical anchors, F. Hoffmann-La Roche Ltd. occupies the originator position exemplifying premium-tier clinical data strategies, while Teva Pharmaceutical Industries Ltd. represents scale-driven generic manufacturing with vertically integrated supply chains. Dr. Reddy's Laboratories Ltd. sits within the emerging-market specialist archetype, anchoring cost-competitive positioning through Indian manufacturing bases and dedicated dermatology portfolios. These three patterns illustrate how geographic origin and corporate structure shape competitive access to regulated markets.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Dr. Reddy's Laboratories Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Abbott Laboratories |
| Mylan NV |
| GlaxoSmithKline plc |
| Cipher Pharmaceuticals Inc. |
| Douglas Pharmaceuticals Limited |
| Others |
Supply & Pricing Matrix
Dermatology clinic networks in California and Texas concentrate purchasing volume for isotretinoin capsules, driving a pricing model that bundles REMS-compliant monitoring services with drug procurement. This buyer concentration creates tiered contracting structures where large clinic systems extract volume discounts while independent practices absorb premium markups for unbundled pharmacy dispensing.
Pricing Analysis
Bundled service contracts dominate the United States market, combining drug cost with pregnancy verification and monthly prescriber certification into single per-patient fees. Unbundled transactional pricing persists in European markets where ANSM and EMA frameworks impose lighter compliance infrastructure. Price differentiation rests on REMS certification tier and prescriber network scale, with mail-order specialty pharmacies commanding premiums for compliance automation. Cost compression in generic capsule formulations is intensifying because Indian API producers are expanding CDSCO-registered capacity. Independent dermatology practices show highest price sensitivity, while integrated clinic-pharmacy networks absorb bundled premiums for workflow efficiency.
Supply Chain Analysis
Closed-network specialty pharmacy channels handle REMS-mandated dispensing for United States dermatology groups, replacing traditional retail distribution. API production draws from Maharashtra and Telangana in India, with secondary concentration in Zhejiang and Jiangsu provinces of China. Isotretinoin synthesis depends on retinoic acid precursors, gelatin capsule shells, and microsphere encapsulation polymers. Single-source vulnerability clusters around Indian API export permits, where CDSCO enforcement actions can disrupt formulation supply. Distribution runs through temperature-controlled logistics networks serving Arizona and Florida mail-order hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Isotretinoin drug economics favor margin expansion through REMS infrastructure monetization, as telemedicine integration and specialty pharmacy partnerships transform compliance costs into service revenue streams.
For Market Incumbents: Extend backward integration into API production through India's PLI scheme incentives, securing captive supply of retinoic acid precursors against CDSCO regulatory volatility. Deepen closed-loop pharmacy partnerships in California and Texas clinic networks to entrench iPLEDGE workflow control. Invest in microsphere formulation R&D to capture reimbursement premiums from modified-release capsules displacing immediate-release generics.
For New Entrants and Emerging Players: Rural dermatology patients in Brazil's Minas Gerais interior present an underserved buyer archetype with expanding ANVISA-regulated telemedicine access. ANVISA's evolving teratogenic guidelines create compliance windows for structured patient-access programs adapted from United States REMS models. Target white-space expansion through Portuguese-language REMS platform licensing to Brazilian clinic networks.
For Investors and Strategic Acquirers: Specialty pharmacy operators with REMS IT infrastructure are the most active acquirer in this space, consolidating dispensing networks around iPLEDGE compliance automation. Long-term viability hinges on regulatory moat sustainability rather than manufacturing scale. Watch for FDA pediatric labeling expansion as the signal indicating addressable patient pool inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| REMS Platform Licensing | Enables geographic expansion into Brazil's ANVISA-regulated telemedicine markets. |
| Microsphere Formulation Development | Captures reimbursement premiums through reduced monitoring burden claims. |
| API Backward Integration | Reduces exposure to CDSCO enforcement volatility in Indian supply clusters. |
| Specialty Pharmacy Acquisition | Consolidates iPLEDGE-compliant dispensing infrastructure under single ownership. |
| Pediatric Labeling Investment | Unlocks prescriber comfort in previously restricted adolescent age segments. |
Research Methodology
Bottom-up dermatology clinic prescription modeling reconciled against top-down API production tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads at FDA-certified manufacturers, formulary directors at United States payers, and hospital procurement managers in Germany and France were combined with secondary validation. FDA REMS enrollment databases, EMA teratogenic drug registries, ClinicalTrials.gov investigator-initiated trial filings, and Indian CDSCO manufacturing facility registrations provided external triangulation points.
Historical trendline analysis of capsule and topical gel prescription velocity informed the projection framework across the modeling period. Segmentation dimensions include formulation type, end-user channel, therapy area indication, and regional regulatory cluster. CAGRs were derived from spline-fitted growth curves applied to patient diagnosis rates and prescriber certification expansion. Forecast inputs incorporated iPLEDGE workflow automation adoption curves and ANVISA guideline evolution timelines.
Underlying measurement precision varies by segment; United States dermatology clinic data carries tighter precision than emerging market estimates. Forecasts reflect base-case assumptions around REMS program continuity and API export permit stability. Periodic stress-testing of base assumptions is recommended against FDA pediatric labeling decisions and CDSCO manufacturing inspection intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Pharmaceutical Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceuticals
Global Lifestyle Drugs Market
Pharmaceuticals
Global Pediatric Electrolyte Solutions Market
Pharmaceuticals
Antiplatelet Market
Pharmaceuticals
Guaifenesin Market
Pharmaceuticals
Japan Diabetes Drugs Market
Pharmaceuticals
North America Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
Global Autism Spectrum Disorder Therapeutics Market
Pharmaceuticals
Fucosidosis Therapeutics Market
Pharmaceuticals
Germany Opioids Market
Pharmaceuticals
Global Diphtheria Vaccine Market
Pharmaceuticals
Metoprolol Tartrate Market
Pharmaceuticals
Monkeypox Vaccine and Treatment Market
Pharmaceuticals
Inhalable Drug Market
Pharmaceuticals
Endocarditis Drugs Market
Pharmaceuticals
Italy Healthcare Market