
 Spain Opioids Market | 2026-2036
Spain Opioids Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Opioids Market Insights
Hospital procurement in Spain is pivoting toward centralized autonomous-community tendering, consolidating purchasing power across regional health services. Mallinckrodt Pharmaceuticals leverages its European manufacturing footprint to supply extended-release morphine formulations to Spanish hospital networks. Hikma Pharmaceuticals anchors its position through generic injectable opioids aligned with public-sector cost-containment protocols. Pfizer competes in the transdermal segment with fentanyl patch technologies tailored to outpatient palliative protocols.
Opioids constitute semi-synthetic and synthetic alkaloid derivatives that bind to mu, kappa, and delta receptors in the central nervous system, with morphine sulfate serving as the reference standard measured in milligram morphine equivalents for dosing equivalence across formulations. These compounds primarily manage moderate-to-severe pain in oncological, postoperative, and chronic non-malignant indications where non-opioid analgesics prove insufficient. The fentanyl transdermal patch segment leads value generation due to extended-release pharmacokinetics and reduced nursing burden in home-care settings, while intravenous morphine dominates hospital volume through perioperative and emergency-department protocols. Oral oxycodone formulations represent the fastest-expanding category as ambulatory pain management shifts toward take-home regimens following Spanish Ministry of Health discharge optimization guidelines.
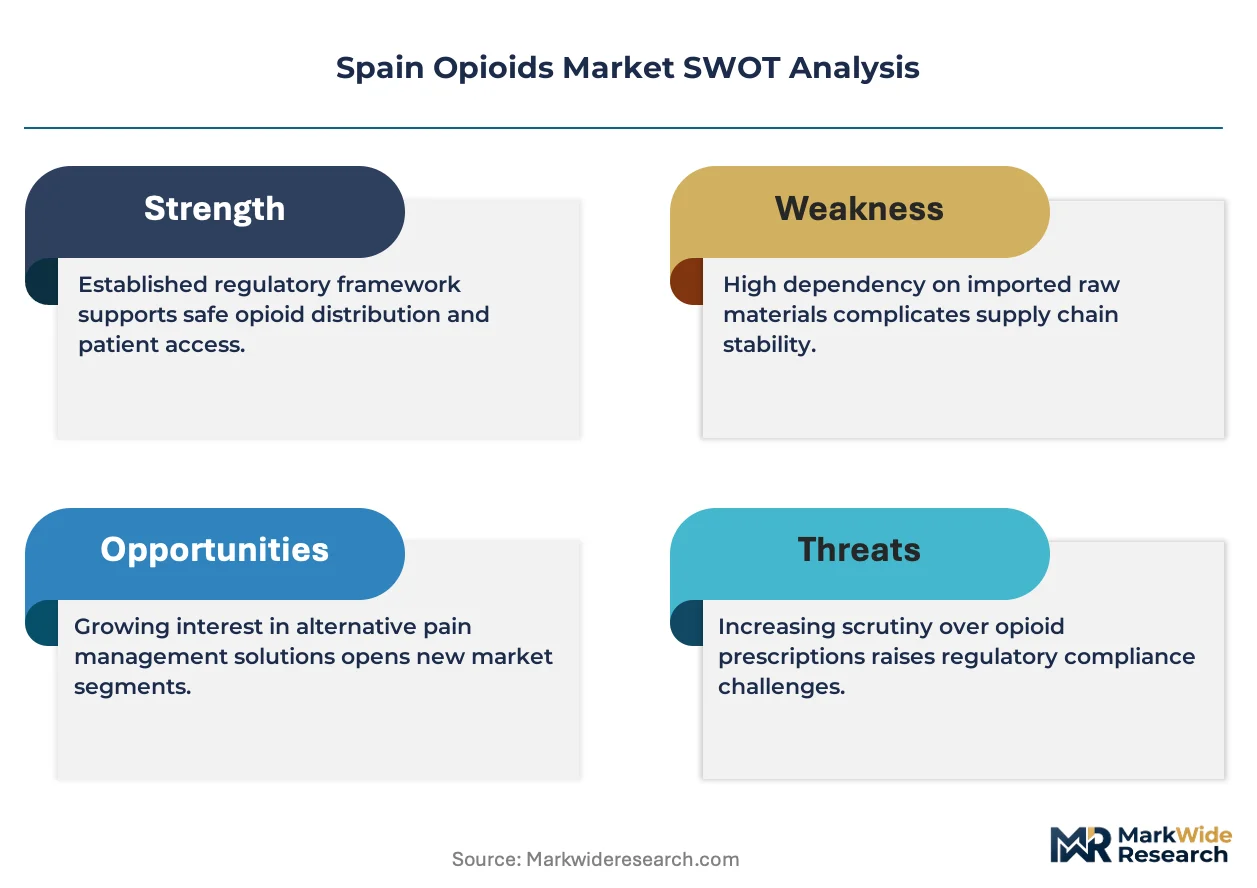
Spain's Agencia Española de Medicamentos y Productos Sanitarios (AEMPS) enforces Real Decreto 2829/1977 scheduling requirements that restrict opioid dispensing to specialized prescriptions with triplicate documentation, directly constraining retail pharmacy access and channeling volume through hospital pharmacies. The European Medicines Agency (EMA) pharmacovigilance framework mandates risk-minimization materials for transdermal fentanyl, shaping prescriber education and patient-selection criteria across Spanish pain units. Stakeholders must monitor AEMPS deliberations on abuse-deterrent formulation incentives, as regulatory preference for tamper-resistant technologies would reshape R&D allocation and generic substitution dynamics in this market.
Market Dynamics
AEMPS triplicate prescription requirements for controlled substances are compressing retail pharmacy access and concentrating opioid dispensing through hospital channels, fundamentally restructuring patient flow and procurement patterns across autonomous communities.
Growth Catalysts
- Palliative care expansion:Terminal cancer units across Andalusia and Catalonia are extending opioid protocols to home-care settings, driving demand for extended-release formulations.
- Sistema de Información de Medicamentos de Especial Control:AEMPS digital tracking infrastructure is streamlining controlled-substance distribution, reducing diversion risk and enabling volume growth.
- Aging demographics:Spain's 65-plus population concentration in Mediterranean coastal provinces is elevating chronic pain prevalence and specialized pain management referrals.
Market Restraints
- Active pharmaceutical ingredient concentration:European manufacturing of morphine sulfate API clusters in a limited number of specialized chemical facilities, exposing supply continuity to single-source vulnerabilities.
- Real Decreto 2829/1977 scheduling friction:Triplicate documentation requirements create administrative burden that constrains prescriber willingness and retail pharmacy stocking.
- Non-opioid analgesic substitution:Gabapentinoids and regional nerve block protocols are displacing opioids in select chronic non-malignant pain indications.
Strategic Opportunities
- Abuse-deterrent formulation incentives:AEMPS deliberations on tamper-resistant technology preferences could reshape R&D allocation and generic substitution dynamics.
- Autonomous community tender consolidation:Centralized purchasing across regional health services creates volume aggregation opportunities for suppliers aligned with public-sector cost protocols.
- Home-care channel expansion:Transdermal fentanyl patch protocols are extending into outpatient palliative settings, reducing nursing burden and enabling geographic penetration beyond hospital catchments.
Industry Challenges
- Specialized pain management workforce scarcity:Certified palliative care physicians and advanced-practice nurses concentrate in Barcelona, Madrid, and Seville, leaving provincial gaps.
- EMA pharmacovigilance compliance complexity:Risk-minimization materials for transdermal fentanyl mandate prescriber education investments and patient-selection criteria documentation.
- Legacy Sistema integration:Autonomous community health services operate divergent electronic health record platforms, complicating cross-regional prescription tracking and patient monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Opioids Market |
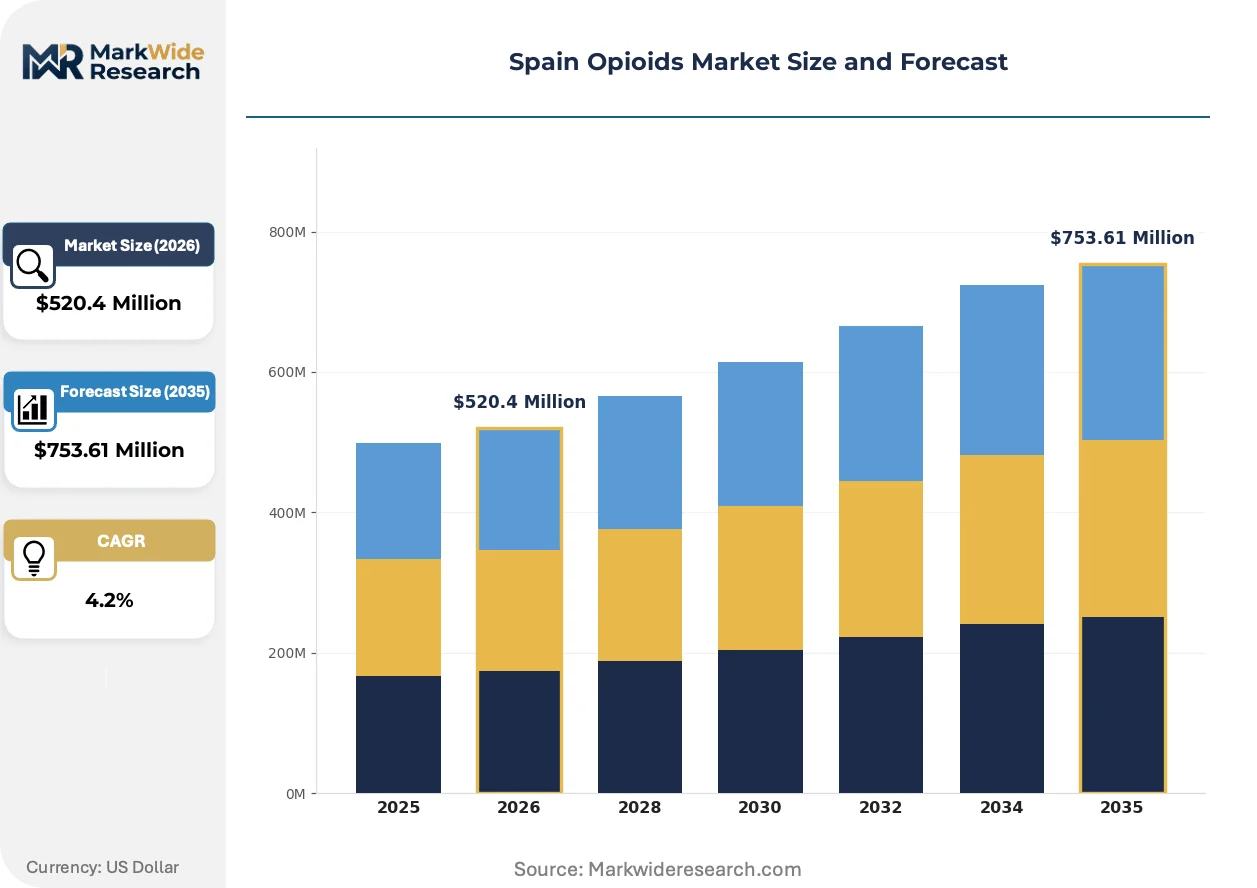
| Market Size in 2026 | $520.4 Million |
| Market Size in 2035 | $753.61 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Morphine, Fentanyl, Oxycodone, Hydrocodone Delivery Mode: Oral, Transdermal, Intravenous, Rectal Healthcare Setting: Hospitals, Clinics, Home Care, Palliative Care Patient Type: Cancer, Chronic Pain, Postoperative, Neuropathic Pain |
| Companies Covered | Mallinckrodt Pharmaceuticals, Hikma Pharmaceuticals, Pfizer, Teva Pharmaceutical Industries, AbbVie, Sanofi, AstraZeneca, Novartis, Johnson & Johnson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Opioids Market Trends and Innovations
Formulation science and regulatory preference are converging to reshape competitive positioning in Spain's opioid landscape, with extended-release technologies and abuse-deterrent architectures displacing conventional immediate-release protocols.
Abuse-deterrent polymer matrix technologies are modularizing tablet and capsule architectures to resist crushing, chewing, and solvent extraction. Hospital pharmacies in Catalonia and Andalusia are prioritizing these formulations in tender specifications. AEMPS signaling on tamper-resistant preferences is compressing R&D timelines for legacy immediate-release morphine portfolios.
EMA pharmacovigilance frameworks are mandating expanded risk-minimization materials for transdermal fentanyl, requiring prescriber certification and patient registry participation. Spanish pain units are restructuring intake protocols to accommodate documentation burdens. The fentanyl patch segment is responding with enhanced patient-selection algorithms and nurse-led education programs.
Centralized autonomous-community tendering is consolidating procurement authority across regional health services, displacing hospital-level purchasing discretion. Generic injectable suppliers aligned with public-sector cost-containment protocols are capturing volume in consolidated awards. Andalusia and Valencia are most advanced in this transition, with Madrid and Catalonia following.
Spain Opioids Market Segmentation
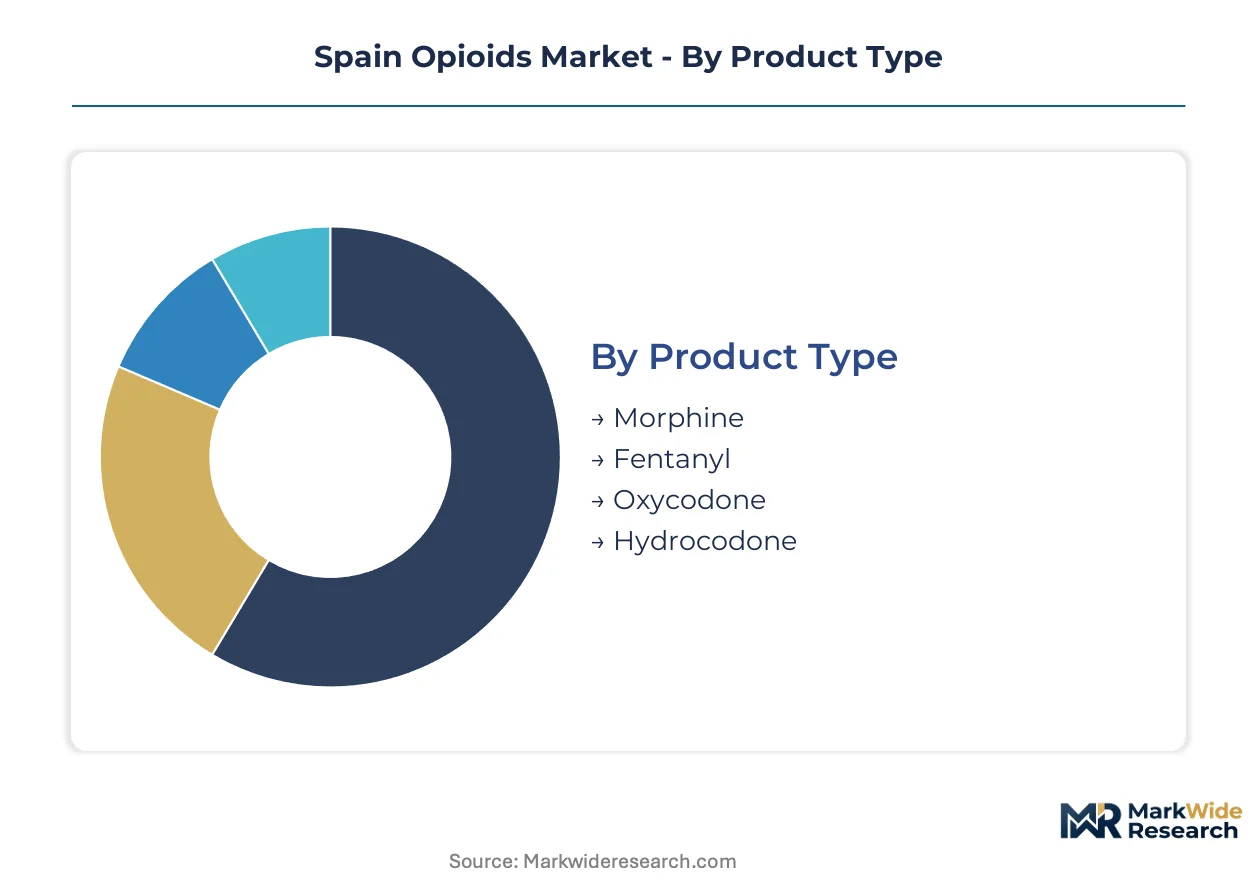
Opioid segmentation in Spain reflects the tension between hospital-controlled distribution and expanding ambulatory channels. AEMPS scheduling requirements channel high-potency formulations through institutional procurement, while patient-type diversification is reshaping prescriber specialization.
Product Type:
Fentanyl and oxycodone capture premium value through extended-release patents, while morphine dominates volume through generic perioperative use.
- Morphine:The reference standard measured in milligram morphine equivalents, available as immediate-release tablets and extended-release formulations. Hospital pharmacies in Andalusia and Catalonia concentrate procurement of injectable morphine sulfate for surgical and emergency protocols, constrained by API sourcing from limited European chemical facilities.
- Fentanyl:Synthetic mu-opioid agonist with rapid onset and short duration, formulated as transdermal patches and lozenges. Transdermal delivery is gaining share fastest in home-care palliative settings across Mediterranean coastal provinces, reducing nursing burden for terminal cancer patients.
- Oxycodone:Semi-synthetic derivative with higher oral bioavailability than morphine, enabling reduced pill burden in ambulatory regimens.
- Hydrocodone:Schedule III compound with lower abuse liability profile, utilized in select combination therapies for moderate pain.
Mature deployment sits with morphine. Newer deployment is concentrated in fentanyl transdermal systems.
Delivery Mode:
Route selection tracks the shift from inpatient control to outpatient autonomy, with absorption kinetics determining reimbursement tiering.
- Oral:Tablets, capsules, and liquid formulations enabling self-administration. Oral oxycodone protocols are climbing the fastest in postoperative discharge optimization across Madrid and Barcelona health services, aligned with Ministry of Health length-of-stay reduction targets.
- Transdermal:Fentanyl patches with 72-hour dosing intervals providing steady-state plasma concentrations. Patch utilization concentrates in Catalonia's home-care networks, where nurse-led palliative teams manage terminal cancer patients beyond hospital catchments.
- Intravenous:Bolus and patient-controlled analgesia systems for perioperative and critical-care settings.
- Rectal:Suppository formulations for patients with compromised oral absorption or vomiting.
Hospital procurement prioritizes intravenous control. Home-care expansion favors transdermal absorption.
Healthcare Setting:
Channel concentration reflects AEMPS triplicate prescription requirements that compress retail pharmacy access.
- Hospitals:Centralized autonomous-community tendering consolidates purchasing across regional health services. Hospital pharmacies in Valencia and Andalusia lead consolidated awards for generic injectable opioids, displacing facility-level procurement discretion.
- Clinics:Specialized pain management centers in Barcelona, Madrid, and Seville concentrate certified prescribers for chronic non-malignant indications.
- Home Care:Nurse-led palliative protocols extending opioid administration to residential settings.
- Palliative Care:Dedicated terminal cancer units operating across autonomous community health services.
Volume concentration remains with hospital channels. Steepest expansion trajectory is occurring in home-care nursing networks.
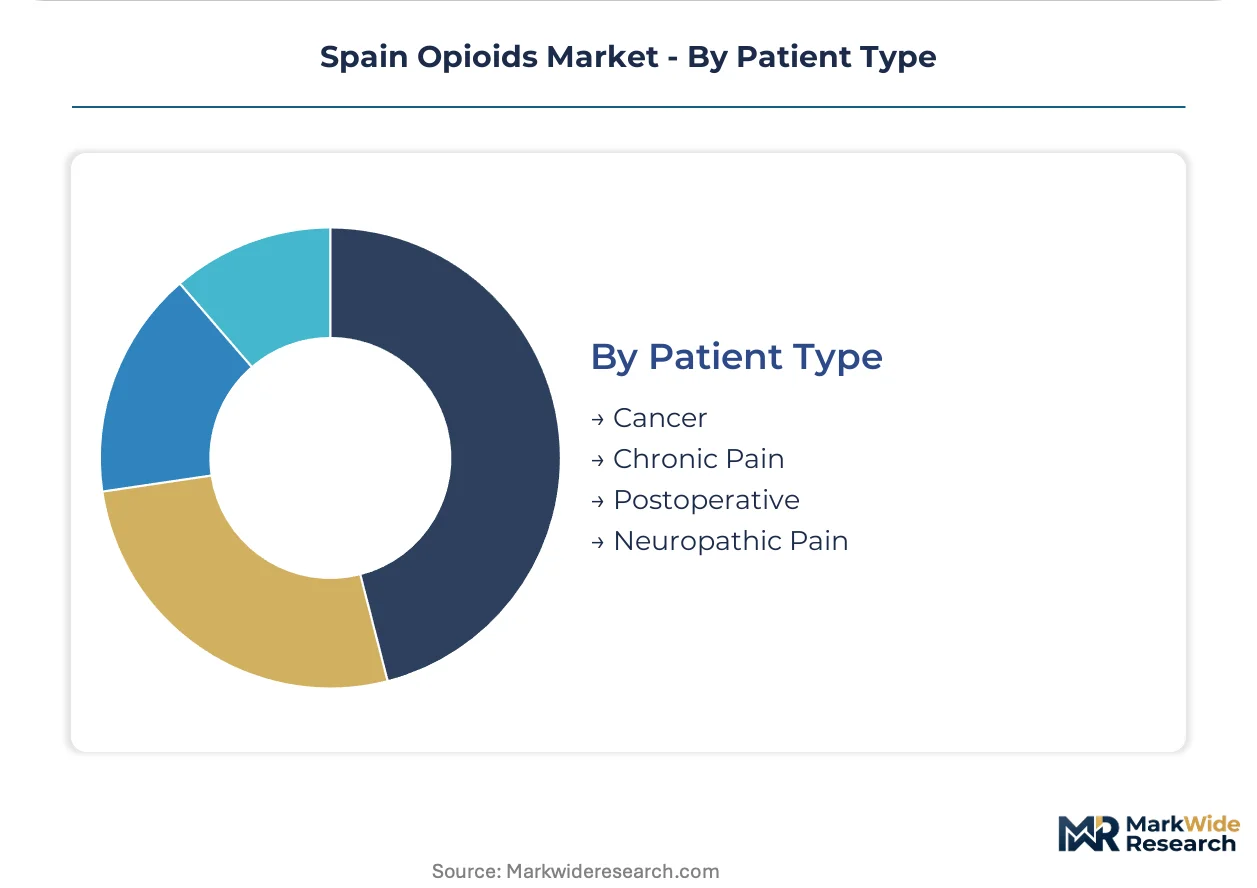
Patient Type:
Indication-specific protocols are segmenting prescriber specialization and formulary positioning.
- Cancer:Oncological pain management with WHO analgesic ladder escalation. Terminal cancer units in Andalusia extend opioid protocols to residential settings, driving demand for extended-release fentanyl and morphine formulations with reduced dosing frequency.
- Chronic Pain:Non-malignant persistent pain syndromes including osteoarthritis and lower back pathology. Chronic pain referrals concentrate in specialized Barcelona and Madrid pain units, where gabapentinoid co-prescription is displacing opioid monotherapy in select indications.
- Postoperative:Acute surgical pain with defined tapering protocols.
- Neuropathic Pain:Nerve injury and dysfunction indications with mixed opioid adjuvant approaches.
Cancer indications anchor institutional opioid utilization. Chronic pain segmentation is diversifying toward multimodal protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Andalusia and Catalonia concentrate over half of Spain's opioid demand through specialized palliative care networks and aging coastal demographics. AEMPS scheduling requirements channel procurement through autonomous-community tendering, restructuring distribution across seventeen regional health services.
Andalusia
Terminal cancer units in Seville and Málaga extend opioid protocols to home-care settings, driving demand for extended-release fentanyl formulations. The Junta de Andalucía health service operates Spain's most advanced consolidated tendering system for generic injectable opioids. Hospital pharmacies in Granada and Córdoba cluster procurement authority under regional centralized purchasing.
Catalonia
Barcelona anchors specialized pain management capacity with certified palliative care physicians concentrated in metropolitan hospital networks. The CatSalut regional health service mandates prescriber certification for transdermal fentanyl through EMA-aligned risk-minimization protocols. Nurse-led palliative teams in Girona and Tarragona deploy patch-based regimens beyond hospital catchments.
Madrid
The Servicio Madrileño de Salud optimizes postoperative discharge protocols, accelerating oral oxycodone utilization in ambulatory pain management. Ministry of Health length-of-stay reduction targets reshape prescribing patterns across twelve public hospital networks. Specialized pain units in Alcorcón and Fuenlabrada concentrate chronic non-malignant referrals.
Valencia
The Conselleria de Sanitat leads autonomous-community tender consolidation for hospital pharmacies, displacing facility-level procurement discretion. Aging demographics in Alicante and Castellón elevate chronic pain prevalence among retired coastal populations. Generic injectable suppliers capture volume through cost-containment aligned regional awards.
Spain Opioids Market Competitive Landscape
European manufacturers anchor one tier; North American and Israeli specialists hold differentiated positions through formulation patents and generic portfolios. Hospital procurement consolidation across seventeen autonomous communities compresses vendor counts, concentrating awards on suppliers aligned with public-sector cost protocols. Three archetypes dominate: patent-protected extended-release developers, high-volume generic injectable manufacturers, and transdermal delivery technology specialists. Competitive moves center on abuse-deterrent formulation R&D acceleration and autonomous-community tender pre-qualification.
Within the extended-release and transdermal tier, Mallinckrodt Pharmaceuticals and Pfizer occupy positions shaped by European manufacturing footprint and patch technology portfolios. Hikma Pharmaceuticals exemplifies the generic injectable archetype, anchoring cost-containment alignment through public-sector supply relationships. These three entities represent the competitive structure compressing around centralized regional tendering and AEMPS scheduling compliance.
| Leading Market Players |
|---|
| Mallinckrodt Pharmaceuticals |
| Hikma Pharmaceuticals |
| Pfizer |
| Teva Pharmaceutical Industries |
| AbbVie |
| Sanofi |
| AstraZeneca |
| Novartis |
| Johnson & Johnson |
| Others |
Pricing and Supply Chain Analysis
Morphine sulfate API spot pricing in European chemical markets cascades through Spain's opioid supply chain, compressing margins on generic injectable formulations while preserving premium tiers for patent-protected extended-release and transdermal delivery systems. AEMPS triplicate prescription requirements and autonomous-community tender consolidation amplify this tiering by channeling volume through hospital procurement networks that prioritize cost-containment alignment over brand premiums.
Pricing Analysis
Volume concentrates in generic injectable morphine where autonomous-community tendering drives cost compression, while margins accrue to extended-release oxycodone and transdermal fentanyl protected by formulation patents and EMA risk-minimization protocols. Price differentiation hinges on abuse-deterrent certification status and prescriber education bundling. Pricing pressure intensifies in the generic injectable tier as Valencia and Andalusia consolidate hospital pharmacy awards. Public-sector buyers exhibit highest price sensitivity; private pain management clinics demonstrate lowest sensitivity due to reimbursement pass-through structures.
Supply Chain Analysis
Direct-to-hospital channels handle consolidated autonomous-community tender demand, while specialized distributors serve outpatient palliative networks with cold-chain and controlled-substance compliance capabilities. API manufacturing concentrates in France, the United Kingdom, and Spain itself, with morphine sulfate feedstock drawing from Turkish and Australian poppy cultivation. Finished dose production rests on European chemical facility capacity and AEMPS GMP certification timelines. Single-source API vulnerability poses the dominant structural risk, particularly for injectable morphine formulations. Distribution runs through hospital pharmacy networks and authorized narcotics distributors with Sistema de Información de Medicamentos de Especial Control integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's opioid market functions as a cost-of-compliance arena where AEMPS scheduling requirements and EMA pharmacovigilance mandates erect regulatory moats favoring incumbents with established controlled-substance infrastructure and prescriber education platforms.
For Market Incumbents: To counter generic injectable price erosion from autonomous-community tender consolidation, prioritize backward integration into European API sourcing and accelerate abuse-deterrent formulation R&D to capture AEMPS preference signaling. Defensive capacity positioning in Catalonia and Andalusia hospital networks anchors volume retention against cost-containment pressure. For New Entrants and Emerging Players: Abuse-deterrent polymer matrix technologies offer the most penetrable wedge for specialty formulation entrants lacking legacy controlled-substance distribution licenses. Target Madrid's postoperative discharge optimization protocols with oral oxycodone alternatives aligned to Ministry of Health length-of-stay targets. A nurse-education-centric go-to-market model bypasses prescriber concentration barriers in Barcelona and Seville. For Investors and Strategic Acquirers: Distressed-cycle entries favor generic injectable manufacturers with AEMPS pre-qualification and autonomous-community tender track records in Valencia and Andalusia. Five-to-ten year viability hinges on consolidation capture in centralized procurement environments. Monitor AEMPS deliberations on tamper-resistant formulation incentives as the critical inflection signal for R&D allocation shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Abuse-Deterrent Formulation Development | AEMPS preference signaling would reshape competitive positioning for Mallinckrodt and Pfizer portfolios. |
| Autonomous-Community Tender Pre-Qualification | Hospital pharmacy consolidation in Valencia and Andalusia compresses vendor counts to cost-aligned suppliers. |
| API Backward Integration | European morphine sulfate sourcing control mitigates single-source vulnerability exposed by Turkish supply concentration. |
| Nurse-Led Palliative Education Programs | CatSalut risk-minimization protocols mandate prescriber certification investments that entrench incumbent relationships. |
| Home-Care Channel Expansion | Transdermal fentanyl patch protocols in Girona and Tarragona extend geographic penetration beyond hospital catchments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving hospital pharmacy directors, palliative care physicians, AEMPS regulatory affairs specialists, and generic injectable procurement managers at autonomous-community health services. AEMPS controlled-substance tracking databases, EMA pharmacovigilance reports, and Spanish Ministry of Health tender documentation supplemented bottom-up volume estimates. Top-down reconciliation applied national health expenditure patterns and aging demographic projections.
Data-stream reconciliation across patient-flow modeling, prescriber concentration mapping, and regional procurement aggregation generated volume and value outputs across the projection horizon. Segmentation dimensions incorporated product type, delivery mode, healthcare setting, patient indication, and autonomous-community regulatory cluster. CAGRs derived from trend extrapolation of palliative care expansion rates and tender award patterns, stress-tested against API supply continuity scenarios and non-opioid substitution elasticities.
Several conditions sit outside the modeled scope, including speculative AEMPS scheduling reclassification, abrupt EMA pharmacovigilance framework revisions, and poppy cultivation disruption in source countries. Forecasts embed assumptions on autonomous-community tender consolidation trajectories and abuse-deterrent technology adoption curves. Periodic stress-testing of base assumptions against AEMPS regulatory deliberations and European API manufacturing capacity utilization is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Colorectal Cancer Therapeutics Market
Pharmaceuticals
Global Bronchodilators Market
Pharmaceuticals
Gamma-Hydroxybutyric Acid Market
Pharmaceuticals
Metastatic Cancer Treatment Drug Market
Pharmaceuticals
Russia Diabetes Drugs Market
Pharmaceuticals
Contraceptive Drugs Market
Pharmaceuticals
Nasal Antihistamines Market
Pharmaceuticals
Asia-Pacific Vaccines Market
Pharmaceuticals
4-Valent HPV Vaccine (4vHPV) Market
Pharmaceuticals
Migraine Nasal Spray Market
Pharmaceuticals
Canagliflozin Market
Pharmaceuticals
Antidotes Market
Pharmaceuticals
Intravenous Pegloticase Market
Pharmaceuticals
Injectable Potassium Phosphate Market
Pharmaceuticals
Alopecia Drugs Market
Pharmaceuticals
US Oral Solid Dosage Contract Manufacturing Market