
 Homocystinuria Therapeutics Market | 2026-2036
Homocystinuria Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Homocystinuria Therapeutics Market Foresight
A shrinking pool of metabolic geneticists is unwinding clinical trial enrollment timelines across the homocystinuria landscape. Travere Therapeutics leverages its rare disease infrastructure to sustain investigator-led site networks. Pfizer Inc. anchors commercialization readiness through distribution partnerships with specialized pharmacy channels. BASF SE competes as a bulk active pharmaceutical ingredient supplier for betaine anhydrous formulations.
Homocystinuria therapeutics encompass pharmacological and nutritional interventions targeting cystathionine beta-synthase deficiency or cobalamin metabolism defects, with pyridoxine (vitamin B6) functioning as a cofactor to restore residual enzymatic activity in responsive genotypes. Betaine anhydrous serves as a methyl group donor to remethylate homocysteine into methionine via alternative hepatic pathways, reducing plasma homocysteine concentrations and mitigating thromboembolic and skeletal complications. Oral delivery mode dominates current prescribing patterns due to chronic administration requirements and pediatric tolerability, though injectable cobalamin formulations capture refractory patient segments with inherited B12 processing disorders. Hospital-based end users retain the largest patient volume share through metabolic clinics, while homecare settings represent the fastest-growing channel as oral therapies shift monitoring to telemedicine models.
The US FDA Orphan Drug designation and European EMA rare disease frameworks shape development economics through extended exclusivity and protocol assistance, while the US IRA price negotiation provisions introduce uncertainty for small-molecule rare disease assets. The EU MDR imposes clinical evidence thresholds on in vitro diagnostic companion devices used to genotype pyridoxine responsiveness. Stakeholders must monitor reimbursement granularity for dietary supplements versus prescription pharmaceuticals across national formularies.
Market Dynamics
The homocystinuria therapeutics landscape is restructuring around newborn screening infrastructure expansion and the migration of chronic disease management from hospital metabolic clinics to home-based telemedicine platforms, compressing traditional care delivery models.
Growth Catalysts
- US FDA newborn screening mandates:State health departments are expanding panel requirements to capture homocystinuria cases earlier, accelerating diagnostic capture rates among pediatric populations and expanding the addressable patient pool.
- EMA rare disease protocol assistance:European developers leverage scientific advice and accelerated assessment pathways to compress clinical development timelines for pyridoxine-responsive and betaine-dependent formulations.
- Homecare channel expansion:Oral betaine anhydrous and pyridoxine therapies enable patient monitoring through remote metabolic clinics, reducing hospital dependency and extending geographic reach into underserved rural catchments.
Market Restraints
- Bulk API supply concentration:Betaine anhydrous active pharmaceutical ingredient production clusters with specialized chemical manufacturers, creating single-source vulnerability for finished dose formulators.
- EU MDR clinical evidence thresholds:In vitro diagnostic companion devices for pyridoxine responsiveness genotyping face elevated documentation requirements, extending regulatory clearance timelines.
- Metabolic geneticist workforce scarcity:The shrinking specialist pool unwinds clinical trial enrollment velocity and stretches site activation timelines across investigator networks.
Strategic Opportunities
- Injectable cobalamin refractory segments:Inherited B12 processing disorders represent an underserved subset where parenteral formulations command premium positioning and limited competition.
- US IRA price negotiation carve-outs:Orphan drug exemptions for small-molecule rare disease assets preserve pricing autonomy for designated therapies outside Medicare negotiation scope.
- Telemedicine metabolic monitoring:Remote homocysteine tracking platforms enable pharmaceutical manufacturers to embed digital therapeutics alongside drug delivery, creating stickier patient relationships.
Industry Challenges
- Site investigator recruitment:The metabolic geneticist talent gap forces sponsors to sustain investigator-led networks through higher per-patient grants and extended site training commitments.
- Dietary supplement reimbursement ambiguity:National formularies apply inconsistent coding for nutritional interventions versus prescription pharmaceuticals, complicating patient access programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Homocystinuria Therapeutics Market |
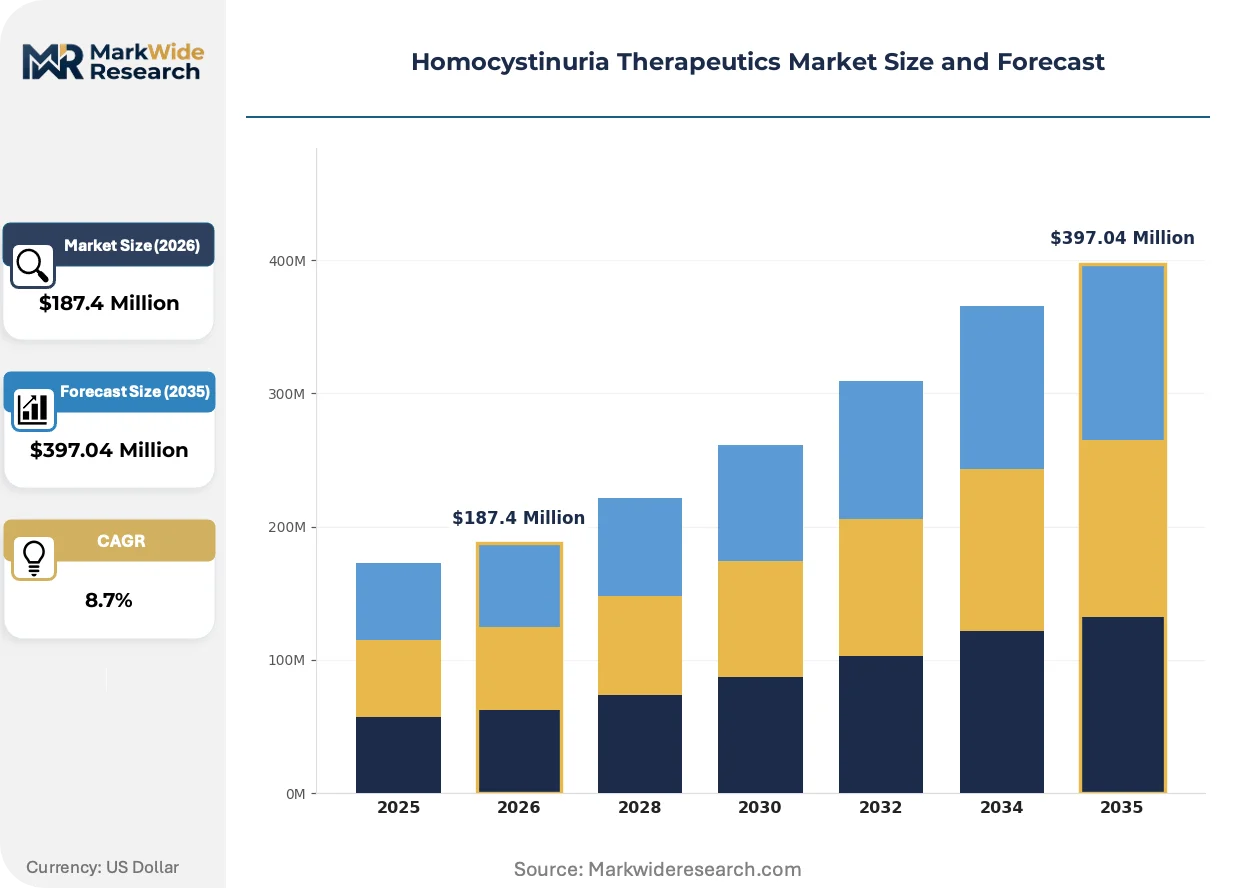
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pyridoxine, Betaine, Folic Acid, Cobalamin Delivery Mode: Oral, Injectable, Sublingual, Topical End User: Hospitals, Clinics, Homecare, Pharmacies Treatment Strategy: Dietary Management, Medications, Supplements, Genetic Counseling |
| Companies Covered | Travere Therapeutics, BASF SE, Pfizer Inc., Mylan Pharmaceuticals, Aeglea BioTherapeutics, DSM N.V., Kao Corporation, Fresenius Kabi AG, Recordati, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Homocystinuria Therapeutics Market Shifts & Advancements
Gene therapy platforms and precision enzymology are decomposing the traditional cofactor replacement paradigm, while regulatory frameworks and care delivery models co-evolve to accommodate these mechanistic shifts.
Enzyme replacement biologics targeting residual cystathionine beta-synthase activity are decomposing the historical dominance of pyridoxine and betaine monotherapy. Pediatric metabolic centers in the United States are piloting these candidates in pyridoxine-nonresponsive genotypes, compressing the addressable market for conventional small-molecule interventions.
EMA's rare disease framework and US FDA Orphan Drug designation are extending market exclusivity periods and compressing development risk for novel mechanisms. Developers are responding by prioritizing protocol assistance engagements over traditional regulatory pathways, with the European market experiencing accelerated assessment uptake for first-in-class enzymatic approaches.
Homecare infusion services are displacing hospital-based cobalamin administration for refractory homocystinuria subtypes. Specialty pharmacy distributors in the United States are capturing this volume through nursing-supported subcutaneous delivery models, shifting reimbursement complexity toward medical benefit billing and away from retail pharmacy channels.
Homocystinuria Therapeutics Market Segmentation
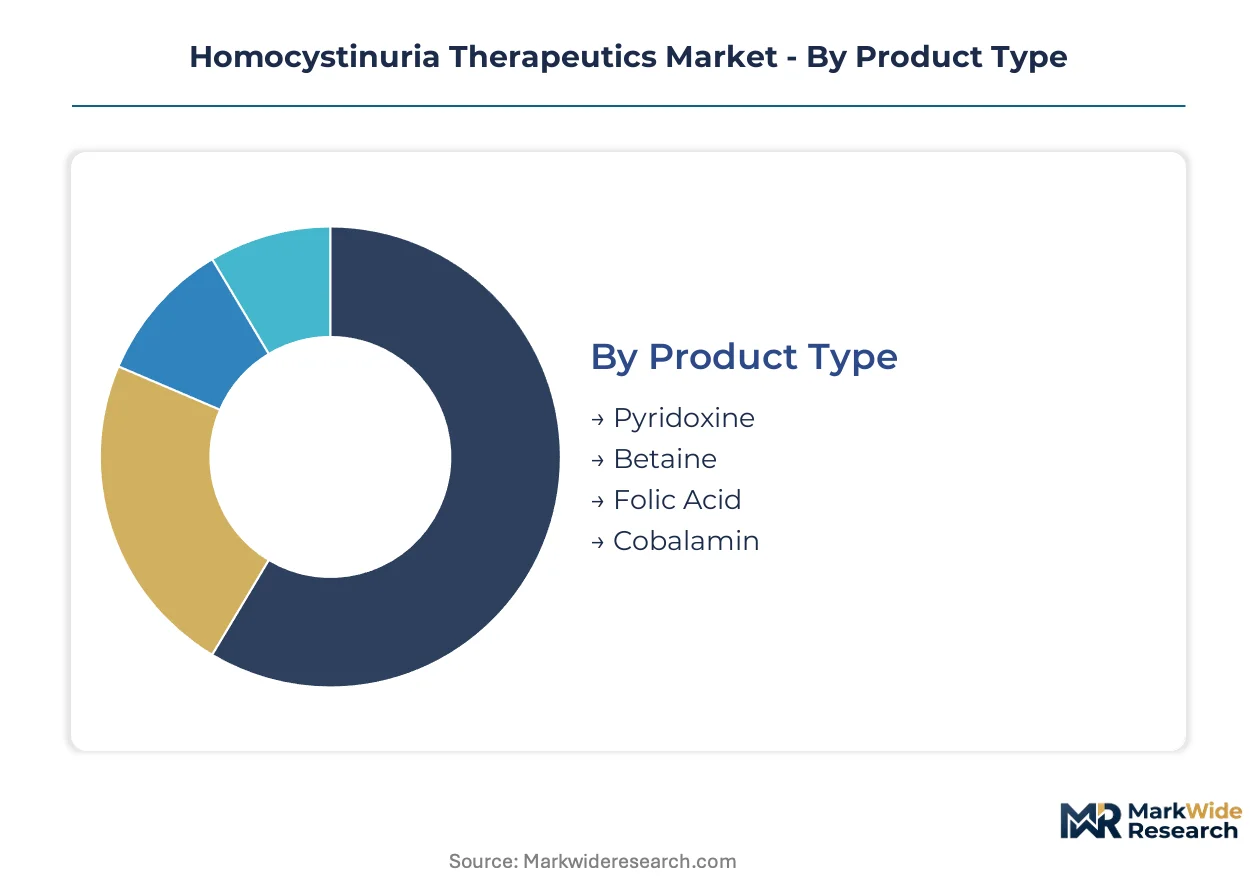
Homocystinuria therapeutics segment along four intersecting dimensions that determine reimbursement pathways, regulatory classification, and patient access economics. Product type and delivery mode classifications shape FDA and EMA approval strategies, while end-user and treatment strategy segments dictate commercial infrastructure requirements and pricing autonomy.
Product Type:
Pyridoxine and betaine formulations anchor domestic prescription markets in the United States and Europe, while folic acid and cobalamin variants face steeper import dependency from Asian API manufacturers.
- Betaine:Anhydrous methyl donor compounds remethylate homocysteine via alternative hepatic pathways, reducing thromboembolic risk. Demand concentrates in US pediatric metabolic clinics where newborn screening mandates expand the addressable pyridoxine-nonresponsive population, though bulk API supply vulnerability from single-source chemical manufacturers constrains finished dose security.
- Pyridoxine:Vitamin B6 cofactor therapy restores residual cystathionine beta-synthase activity in responsive genotypes identified through companion diagnostic genotyping. European EMA protocol assistance accelerates development timelines for enhanced bioavailability formulations, while US Orphan Drug designation preserves pricing autonomy outside IRA negotiation scope.
- Folic Acid:Adjunctive methylenetetrahydrofolate reductase support addresses ancillary methylation pathway defects in compound heterozygous patients.
- Cobalamin:Injectable hydroxocobalamin and cyanocobalamin formulations target inherited B12 processing disorders refractory to oral cofactor replacement.
Betaine commands the established base. The steepest expansion runs through cobalamin refractory segments where parenteral formulations face limited competition.
Delivery Mode:
Cost tier stratification separates chronic oral maintenance therapies from premium-priced injectable interventions, with reimbursement complexity escalating across the hierarchy.
- Oral:Tablets and powder formulations dominate chronic administration due to pediatric tolerability and homecare compatibility. US specialty pharmacy distributors capture this volume through mail-order channels, shifting monitoring toward telemedicine metabolic clinics and compressing hospital dependency.
- Injectable:Parenteral cobalamin and intensive betaine delivery serve acute homocysteine crises and malabsorption disorders. European homecare infusion services displace hospital administration for refractory subtypes, with nursing-supported subcutaneous models migrating reimbursement toward medical benefit billing.
- Sublingual:Buccal absorption alternatives address gastrointestinal intolerance in select pediatric populations.
- Topical:Transdermal delivery remains investigational for cofactor replacement with limited commercial penetration.
Oral formulations anchor volume economics. Injectable modalities claim the fastest margin expansion through premium positioning in refractory segments.
End User:
Customer type segmentation tracks the migration from institutional metabolic centers toward distributed homecare platforms, with site activation timelines stretching across the specialist workforce shortage.
- Hospitals:Academic metabolic clinics retain the largest patient volume share through diagnostic confirmation, genotyping, and acute crisis management. US children's hospitals anchor investigator-led trial networks for enzyme replacement biologics, though shrinking metabolic geneticist pools unwind enrollment velocity.
- Homecare:Remote monitoring platforms enable chronic disease management outside traditional hospital catchments. European telemedicine metabolic tracking extends geographic reach into underserved rural areas, creating stickier pharmaceutical-patient relationships through digital therapeutics embedding.
- Clinics:Community-based metabolic specialists bridge diagnostic transition to chronic maintenance.
- Pharmacies:Retail and specialty pharmacy channels handle oral maintenance prescription fulfillment.
Hospitals retain the diagnostic and acute intervention base. Homecare platforms are gaining share fastest as oral therapies shift monitoring to remote models.
Treatment Strategy:
Maturity differentiation separates established pharmacological interventions from emerging precision approaches, with regulatory frameworks co-evolving to accommodate mechanistic shifts.
- Medications:Prescription pharmaceuticals including betaine anhydrous and pyridoxine formulations command reimbursement clarity through FDA and EMA orphan drug pathways. US expanded access programs channel investment toward responsive genotype subsets, while EU MDR imposes clinical evidence thresholds on companion diagnostic devices.
- Genetic Counseling:Preconception and family planning services address autosomal recessive inheritance patterns. US state health department newborn screening expansion accelerates diagnostic capture, embedding counseling into pediatric metabolic clinic workflows.
- Dietary Management:Methionine-restricted protocols require specialized metabolic dietitian oversight.
- Supplements:Nutritional interventions face inconsistent national formulary coding versus prescription classification.
Medications anchor the revenue base. Genetic counseling services are climbing the fastest as screening infrastructure expands diagnostic capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA newborn screening mandates anchor United States demand, while EMA protocol assistance accelerates European development timelines. State health departments and national regulators collectively expand diagnostic infrastructure across pediatric populations.
United States
Expanded access programs and rare disease designations channel investment toward pyridoxine-responsive patient subsets. The FDA Orphan Drug designation preserves pricing autonomy for small-molecule assets outside IRA negotiation scope. Boston and San Francisco metabolic clinic clusters anchor investigator-led trial networks for enzyme replacement biologics.
Germany
EMA scientific advice and accelerated assessment pathways compress clinical development timelines for betaine-dependent formulations. The EU MDR imposes clinical evidence thresholds on companion diagnostic devices for pyridoxine responsiveness genotyping. Munich and Heidelberg pediatric metabolic centers pilot homecare infusion services for refractory subtypes.
United Kingdom
NHS newborn screening expansion captures homocystinuria cases earlier, embedding genetic counseling into pediatric metabolic workflows. MHRA post-Brexit regulatory autonomy enables tailored orphan drug assessment pathways. London and Cambridge metabolic research clusters advance precision enzymology platforms.
Japan
PMDA orphan drug designation and priority review vouchers attract developers targeting cobalamin-refractory segments with inherited B12 processing disorders. METI rare disease innovation grants subsidize domestic clinical trial infrastructure. Tokyo and Osaka academic medical centers retain the largest patient volume share through diagnostic confirmation protocols.
Switzerland
Swissmedic rare disease frameworks and early access schemes enable pre-approval patient access for pyridoxine-nonresponsive genotypes. Cantonal health system fragmentation creates reimbursement complexity for dietary supplement versus prescription classification. Basel and Zurich pharmaceutical clusters concentrate bulk API supply relationships for betaine anhydrous formulations.
Homocystinuria Therapeutics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the homocystinuria therapeutics landscape. Large-cap pharmaceutical incumbents anchor commercialization readiness through specialized pharmacy distribution partnerships, while mid-cap rare disease specialists sustain investigator-led site networks. The competitive terrain fragments across three strategic archetypes: orphan drug developers, bulk API chemical manufacturers, and metabolic genetic service providers. Dominant competitive moves include strategic partnerships with specialty pharmacy channels and portfolio diversification into enzyme replacement biologics.
Within the orphan drug development tier, Travere Therapeutics and Recordati occupy positions exemplifying rare disease infrastructure leverage. Among bulk active pharmaceutical ingredient suppliers, BASF SE anchors chemical manufacturing scale for betaine anhydrous formulations. Pfizer Inc. sits within the large-cap commercialization archetype, representing distribution partnership strategies with specialized pharmacy channels.
| Leading Market Players |
|---|
| Travere Therapeutics |
| BASF SE |
| Pfizer Inc. |
| Mylan Pharmaceuticals |
| Aeglea BioTherapeutics |
| DSM N.V. |
| Kao Corporation |
| Fresenius Kabi AG |
| Recordati |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between finished dose formulators and bulk API manufacturers lock in betaine anhydrous supply access while stabilizing unit cost visibility across multi-year procurement horizons. These contractual structures insulate pyridoxine-responsive therapy developers from spot market volatility in chemical feedstock markets.
Pricing Analysis
US-European price spreads for oral betaine formulations exceed those for pyridoxine by substantial margins due to FDA orphan drug exclusivity preserving pricing autonomy outside IRA negotiation scope. Three-tier pricing structure across premium injectable cobalamin, standard oral betaine, and economy generic pyridoxine separates reimbursement tiers by delivery complexity. Pricing pressure stems from bulk API supply concentration among German and Swiss chemical manufacturers. Pediatric metabolic clinics demonstrate highest price sensitivity, while homecare infusion services for refractory B12 disorders show lowest elasticity.
Supply Chain Analysis
Germany and Switzerland anchor bulk betaine anhydrous API production through specialized chemical manufacturers serving global finished dose formulators. China and India supply folic acid and pyridoxine intermediates, while Japanese manufacturers concentrate on high-purity cobalamin derivatives. Single-source vulnerability runs through betaine anhydrous crystallization capacity at Basel-area chemical parks. Distribution runs through US specialty pharmacy channels and European homecare infusion networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telemedicine metabolic monitoring services attach faster than underlying pharmaceutical hardware, creating recurring revenue layers that extend patient lifetime value beyond drug dispensing margins.
For Market Incumbents: Fortify investigator-led site networks through extended metabolic geneticist training commitments and higher per-patient grants to offset workforce scarcity. Deepen backward integration into betaine anhydrous API supply through captive manufacturing relationships or strategic offtake structures to neutralize single-source vulnerability from Basel chemical clusters. For New Entrants and Emerging Players: Lead with cobalamin-refractory segments where parenteral formulations face limited competition and premium positioning remains intact. Target inherited B12 processing disorder subsets in Japanese and US pediatric metabolic centers. Deploy nursing-supported subcutaneous delivery models to capture homecare infusion volume migrating from hospital settings. For Investors and Strategic Acquirers: Rare disease infrastructure specialists with established FDA orphan drug designations and EMA protocol assistance track records represent priority acquisition archetypes. Long-term viability hinges on newborn screening mandate expansion sustaining diagnostic capture rates. Watch for EU MDR clearance timelines on pyridoxine responsiveness genotyping companion devices as inflection indicators for precision therapy addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pathway | FDA and EMA frameworks extend exclusivity periods for homocystinuria therapies. |
| Specialty Pharmacy Distribution Partnership | Pfizer anchors commercialization readiness through US mail-order channel control. |
| Telemedicine Platform Integration | Remote homocysteine tracking embeds digital therapeutics alongside drug delivery. |
| Enzyme Replacement Pipeline Advancement | Pediatric metabolic centers pilot biologics for pyridoxine-nonresponsive genotypes. |
| Bulk API Supply Agreement | BASF SE secures chemical manufacturing scale for betaine anhydrous formulations. |
Research Methodology
Desk research of FDA orphan drug filings, EMA scientific advice records, and newborn screening panel databases preceded structured interviews with pediatric metabolic specialists, specialty pharmacy procurement directors, and rare disease regulatory affairs leads. Primary fieldwork with hospital metabolic clinic administrators and homecare infusion service operators was cross-validated against ClinicalTrials.gov enrollment data and CMS Medicare reimbursement schedules. Bottom-up patient population estimates and top-down pharmaceutical revenue triangulation anchored market sizing.
Variance decomposition across product type, delivery mode, end-user channel, and regional regulatory cluster segments shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth trajectory blending. Modeled inputs included newborn screening expansion rates, metabolic geneticist workforce supply curves, and IRA price negotiation exemption eligibility patterns.
The analysis sits within stated boundaries; outcomes outside sustained FDA and EMA orphan drug framework stability or accelerated EU MDR diagnostic clearance timelines would require recalibration. Forecasts reflect documented assumptions regarding screening infrastructure investment continuity and specialist workforce replenishment. Recalibration cycles align with material shifts in reimbursement granularity for dietary supplements versus prescription pharmaceuticals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Direct Oral Anticoagulants Market
Pharmaceuticals
Artificial Intelligence in Drug Screening Market
Pharmaceuticals
Conjunctivitis Drugs Market
Pharmaceuticals
Respiratory Virus Infection Drug Market
Pharmaceuticals
Pantoprazole Market
Pharmaceuticals
Chloramphenicol Eye Drops Market
Pharmaceuticals
Global Bone Morphogenetic Protein Market
Pharmaceuticals
Seropositive Rheumatoid Arthritis Drug Market
Pharmaceuticals
Posaconazole Market
Pharmaceuticals
Minocycline Hydrochloride Market
Pharmaceuticals
Next-Generation Immunology Drugs Market
Pharmaceuticals
Asia-Pacific Pharmaceutical Contract Manufacturing Organization Market
Pharmaceuticals
Viscosupplementation Market
Pharmaceuticals
Global Immune Checkpoint Inhibitors Market
Pharmaceuticals
Global Intravenous Immunoglobulin Market
Pharmaceuticals
Alectinib Drugs Market