
 Europe G-CSF/PEG-G-CSF Market | 2026-2036
Europe G-CSF/PEG-G-CSF Market Size, Share, and Industry Trends Forecast 2026-2036
Europe G-CSF/PEG-G-CSF Market Foresight
Pricing and clinical positioning is decoupling between originator PEG-G-CSF and biosimilar G-CSF tiers across European markets. Amgen leverages its long-acting Neulasta heritage to sustain premium positioning in hospital formularies. Sandoz anchors the biosimilar segment through aggressive tender participation and broad European distribution networks.
G-CSF (granulocyte colony-stimulating factor) and its polyethylene glycol-conjugated variant PEG-G-CSF are recombinant glycoproteins produced via mammalian cell culture, typically dosed at 5-6 mg per chemotherapy cycle to stimulate neutrophil proliferation and prevent febrile neutropenia. These agents serve as essential supportive care in myelosuppressive cancer treatment protocols. Biosimilar G-CSF now captures the fastest volume expansion as national health systems in Italy and Spain mandate substitution policies, while PEG-G-CSF retains margin concentration in private oncology clinics seeking reduced injection frequency. The subcutaneous administration route dominates outpatient delivery, though intravenous formulations persist in certain hematology protocols.
EMA's biosimilar framework and the EU's MDR (Medical Device Regulation) for companion delivery devices shape product approval timelines and post-market surveillance obligations across member states. Germany's KBA-equivalent pharmaceutical pricing regulator, the G-BA, enforces reference pricing that compresses biosimilar reimbursement bands. France's ANSM maintains strict pharmacovigilance reporting that extends market access negotiations. Stakeholders must monitor evolving HTA divergence between France's HAS and England's NICE as each body weighs cost-effectiveness thresholds for long-acting versus short-acting formulations.
Market Dynamics
The biosimilar substitution mandates across Western European hospital systems are compressing originator PEG-G-CSF volumes while expanding access corridors for short-acting G-CSF alternatives. This regulatory-driven volume rotation is restructuring procurement hierarchies and tender participation thresholds.
Growth Catalysts
- EMA biosimilar pathway acceleration:The streamlined approval framework reduces time-to-market for follow-on biologics, enabling faster formulary inclusion across EU member state hospital systems.
- Prophylactic chemotherapy support expansion:Oncology clinics in Germany and France are embedding G-CSF prophylaxis deeper into myelosuppressive regimens, expanding addressable patient populations per treatment cycle.
- Subcutaneous delivery preference:Outpatient administration protocols favor subcutaneous formulations, reducing infusion center burden and aligning with ambulatory care cost containment objectives.
Market Restraints
- Reference pricing compression:Germany's G-BA enforces strict reimbursement bands that cap biosimilar price premiums and compress margin structures across short-acting G-CSF tiers.
- Long-acting formulation concentration:PEG-G-CSF supply remains concentrated among originator manufacturers with established hospital formulary contracts, creating entry barriers for biosimilar long-acting alternatives.
- Pharmacovigilance reporting burden:France's ANSM maintains extended adverse event tracking requirements that lengthen market access negotiations and elevate post-launch compliance costs.
Strategic Opportunities
- Italian regional tender consolidation:Lombardy and Veneto health authorities are centralizing oncology drug procurement, creating volume aggregation points for biosimilar suppliers with manufacturing scale.
- Companion device integration:The EU's MDR framework for on-body injector systems is automating reimbursement pathways for delivery-device combinations that reduce clinic visit frequency.
- Spain's substitution policy expansion:Regional health services in Catalonia and Andalusia are mandating pharmacist-led biosimilar substitution, opening automatic switching corridors previously controlled by prescriber preference.
Industry Challenges
- Cold chain integrity maintenance:Temperature-controlled distribution across fragmented European logistics networks requires specialized infrastructure investments that strain regional distributor margins.
- HTA divergence navigation:France's HAS and England's NICE apply divergent cost-effectiveness thresholds for long-acting versus short-acting formulations, forcing manufacturers to maintain parallel evidence-generation strategies.
- Biosimilar immunogenicity surveillance:Extended patient follow-up protocols for neutropenia recurrence detection demand registry infrastructure that smaller market entrants struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe G-CSF/PEG-G-CSF Market |
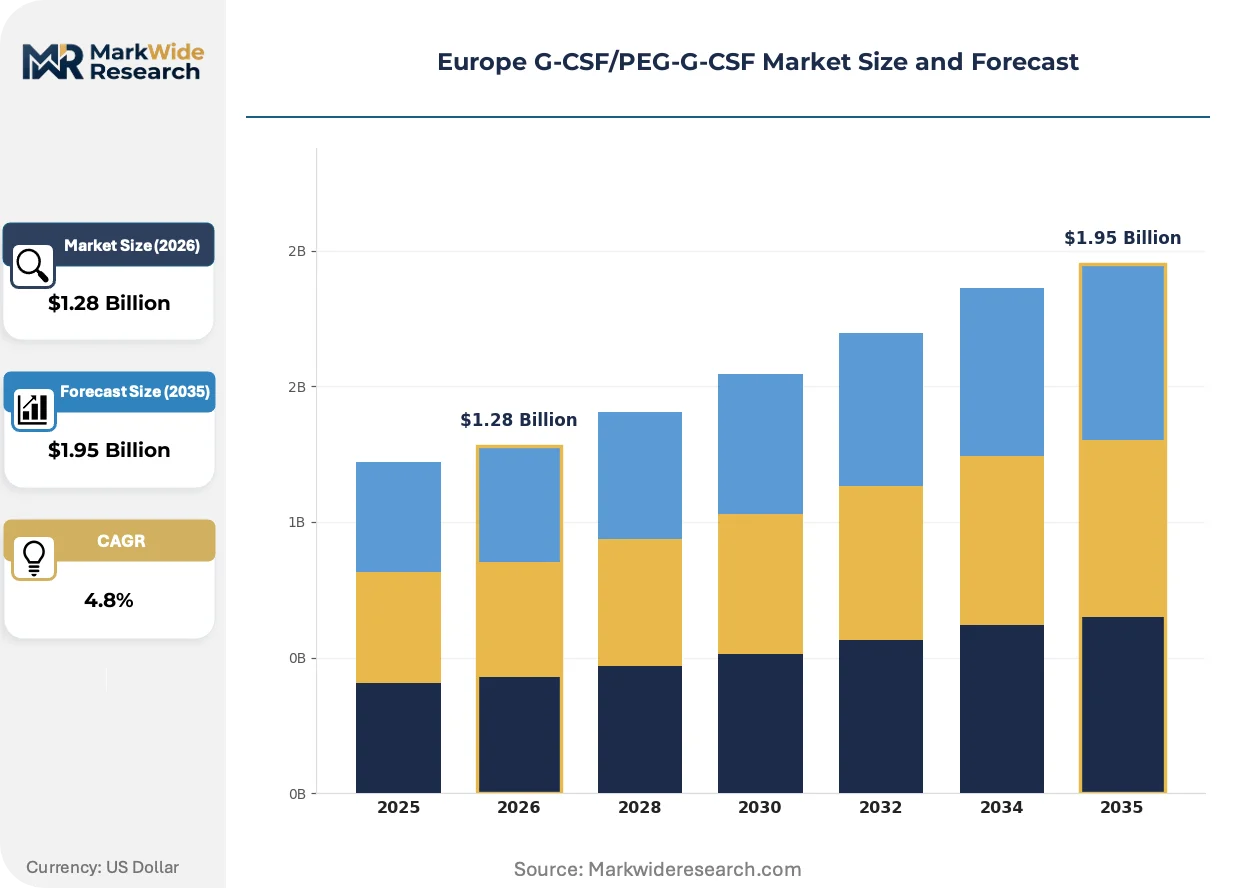
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $1.95 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: G-CSF, PEG-G-CSF, Biosimilar G-CSF, Combination Therapy Administration Route: Subcutaneous, Intravenous, Oral, Intramuscular End User: Hospitals, Clinics, Homecare Settings, Research Institutions Therapeutic Area: Oncology, Hematology, Autoimmune Diseases, Infectious Diseases |
| Companies Covered | Fresenius Kabi, Chugai Pharmaceutical, Amgen, Evive Biotech, Italfarmaco, Pfizer, Coherus BioSciences, Stada Arzneimittel, Sandoz, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe G-CSF/PEG-G-CSF Market Shifts & Advancements
Delivery device convergence with digital adherence tracking is reshaping how G-CSF therapies are administered and monitored across European outpatient settings. These innovations are compressing the gap between clinical efficacy and real-world treatment persistence.
On-body injector systems with integrated dose confirmation sensors are automating the capture of administration timing and completion data. Oncology clinics in the Netherlands and Belgium are piloting these devices for PEG-G-CSF delivery to reduce missed-dose episodes. The technology is automating the linkage between drug delivery and electronic health record documentation, reducing nursing documentation burden while improving reimbursement audit trails.
The EU's MDR implementation for companion delivery devices is extending approval timelines and elevating post-market surveillance obligations for injector system manufacturers. Device makers must now demonstrate biocompatibility and electromagnetic compatibility under consolidated technical documentation requirements. German hospital procurement consortia are responding by bundling device qualification into tender specifications, favoring suppliers with established MDR compliance dossiers.
Centralized tendering by multi-hospital purchasing alliances is displacing single-institution procurement negotiations across France and Italy. These aggregators are unbundling drug and device pricing, forcing manufacturers to compete on transparent unit economics rather than bundled service packages. The shift is most visible in Spain, where regional health authorities are consolidating oncology supportive care purchasing into framework agreements with quarterly price revision clauses.
Europe G-CSF/PEG-G-CSF Market Segmentation
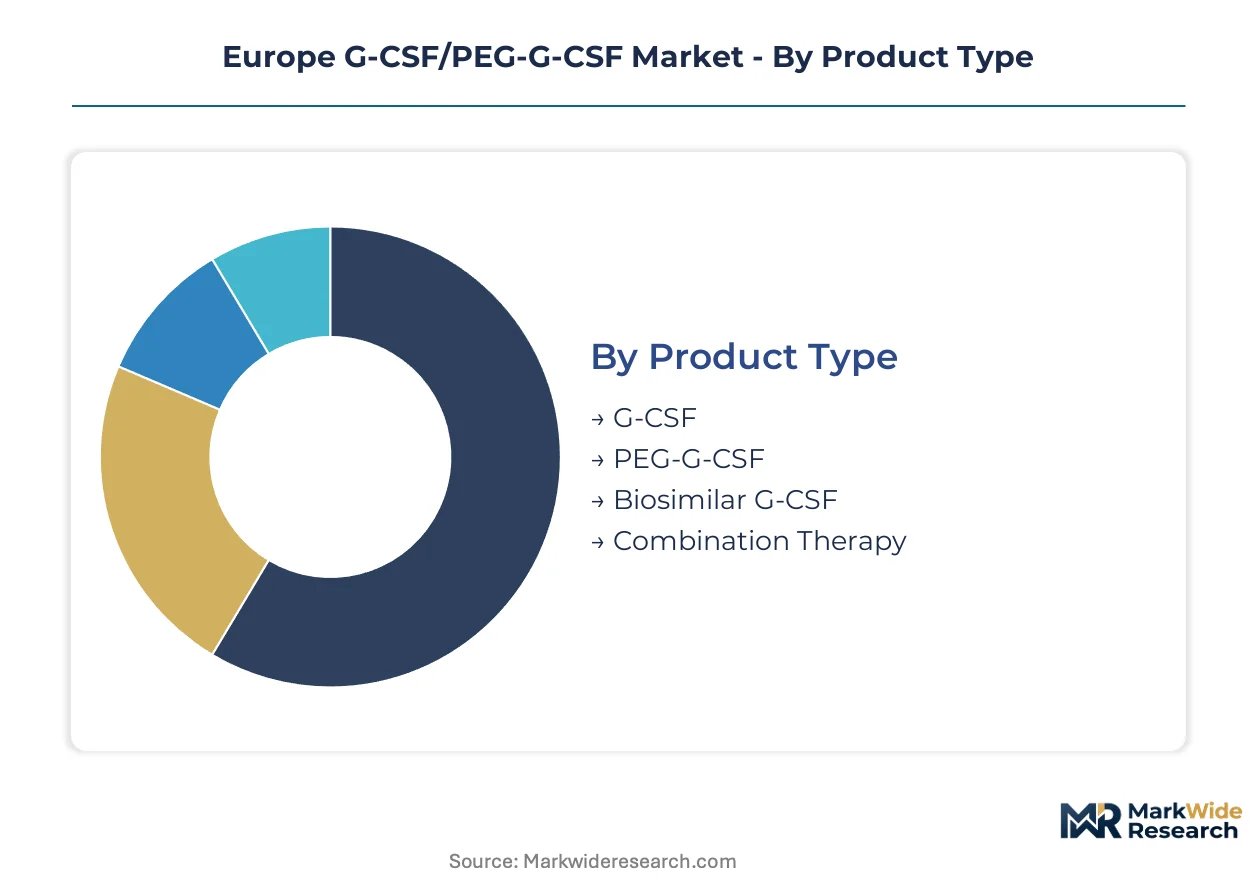
Segmentation reveals how capital deployment and reimbursement pathways diverge across the Europe G-CSF/PEG-G-CSF Market. Manufacturers must align production scale with the specific regulatory and procurement channels governing each segment.
Product Type:
Capital intensity concentrates in long-acting formulation manufacturing, where pegylation chemistry and mammalian cell culture infrastructure demand specialized bioprocessing investments.
- G-CSF:Short-acting recombinant glycoprotein produced via E. coli or mammalian expression systems, requiring fermentation capacity and downstream purification suites. Hospital procurement in Germany and France favors this segment for cost-containment protocols in high-volume chemotherapy centers, though reimbursement bands compress margins under G-BA reference pricing.
- PEG-G-CSF:Pegylated variant extending half-life through polyethylene glycol conjugation, demanding specialized chemical modification capabilities and extended stability testing. Private oncology clinics in Belgium and the Netherlands absorb premium positioning to reduce injection frequency and nursing burden.
- Biosimilar G-CSF:Follow-on biologics approved through EMA comparability pathways, leveraging abbreviated clinical development against reference products. Italian regional tenders and Spanish substitution mandates accelerate volume penetration.
- Combination Therapy:Co-formulated or sequential regimens pairing G-CSF with chemotherapy agents or anti-infectives, requiring partnership structures with oncology drug manufacturers.
Most installed capacity flows through G-CSF. Expansion is steepest in Biosimilar G-CSF.
Administration Route:
Route selection determines delivery device requirements and reimbursement coding complexity across European hospital systems.
- Subcutaneous:Dominant outpatient protocol using prefilled syringes or autoinjectors, aligning with ambulatory care cost containment in France and Germany. EMA MDR compliance for companion devices elevates qualification barriers.
- Intravenous:Reserved for hematology inpatient protocols and patients with compromised subcutaneous tissue, requiring infusion center capacity and longer administration windows.
- Oral:Investigational and limited commercial availability, constrained by peptide degradation in gastrointestinal environments.
- Intramuscular:Rarely employed in oncology supportive care, retained primarily for specific hematologic emergency protocols.
Subcutaneous delivery captures the majority of administered doses. Device-integrated subcutaneous systems are gaining share fastest.
End User:
End-user structure shapes cold chain logistics, patient education investments, and pharmacovigilance reporting obligations.
- Hospitals:Centralized procurement through multi-hospital alliances in France and Italy, with tender specifications bundling drug and device qualification requirements.
- Clinics:Private oncology facilities in Germany and Belgium prioritizing reduced visit frequency through long-acting formulations and on-body injector adoption.
- Homecare Settings:Expanding corridor in the Netherlands and Scandinavia, requiring patient self-administration training and remote monitoring infrastructure.
- Research Institutions:Academic medical centers conducting investigator-initiated trials with EMA-registered reference products for biosimilar development.
Hospitals absorb the largest prescription volumes. Homecare settings are expanding most quickly.
Therapeutic Area:
Therapeutic focus determines clinical evidence requirements and health technology assessment pathways across EU member states.
- Oncology:Myelosuppressive chemotherapy prophylaxis representing the core indication, with febrile neutropenia prevention driving prophylactic embedding in German and French treatment protocols.
- Hematology:Stem cell mobilization and neutropenia management in bone marrow transplant settings, requiring coordination with specialized transplant centers.
- Autoimmune Diseases:Off-label and emerging applications in neutropenia associated with systemic lupus or rheumatoid arthritis immunosuppression.
- Infectious Diseases:Adjunctive therapy in severe neutropenia secondary to HIV or antiviral treatment, limited by competing granulocyte transfusion protocols.
Oncology commands the dominant share of administered therapy. Hematology applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and France diverge in procurement intensity despite comparable chemotherapy volumes, with Italian regional consolidation now outpacing both in tender velocity. Spain's substitution mandates are compressing prescriber discretion faster than anywhere else in Western Europe.
Germany
Oncology clinics in Bavaria and North Rhine-Westphalia are embedding G-CSF prophylaxis deeper into myelosuppressive regimens, expanding addressable patient populations per treatment cycle. The G-BA enforces reference pricing that compresses biosimilar reimbursement bands and caps price premiums. Hospital procurement consortia in Berlin-Brandenburg are bundling device qualification into tender specifications, favoring suppliers with established MDR compliance dossiers.
France
Private oncology facilities in Île-de-France prioritize reduced visit frequency through long-acting formulations and on-body injector adoption. ANSM maintains strict pharmacovigilance reporting that extends market access negotiations and elevates post-launch compliance costs. The HAS applies cost-effectiveness thresholds for long-acting versus short-acting formulations that diverge from England's NICE methodology, forcing parallel evidence-generation strategies.
Italy
Lombardy and Veneto health authorities are centralizing oncology drug procurement, creating volume aggregation points for biosimilar suppliers with manufacturing scale. Regional tender consolidation is displacing single-institution procurement negotiations across the north. Hospital systems in Emilia-Romagna are mandating substitution policies that accelerate automatic switching corridors previously controlled by prescriber preference.
Spain
Catalonia and Andalusia regional health services are mandating pharmacist-led biosimilar substitution, opening automatic switching corridors. Framework agreements with quarterly price revision clauses are consolidating oncology supportive care purchasing. Madrid-based hospital alliances are unbundling drug and device pricing, forcing manufacturers to compete on transparent unit economics rather than bundled service packages.
Netherlands
Outpatient administration protocols favor subcutaneous formulations, reducing infusion center burden and aligning with ambulatory care cost containment objectives. Homecare settings are expanding through patient self-administration training and remote monitoring infrastructure. Oncology clinics in Randstad are piloting on-body injector systems with integrated dose confirmation sensors to reduce missed-dose episodes.
Europe G-CSF/PEG-G-CSF Market Competitive Landscape
Top-tier vendors anchor hospital formulary contracts, while mid-tier biosimilar specialists compete through aggressive tender participation and regional distribution scale. The vendor base stratifies across originator heritage players, biosimilar pure-plays, and diversified pharmaceutical conglomerates with oncology portfolios. Three archetypes dominate: long-acting formulation originators defending premium positioning, short-acting biosimilar suppliers capturing volume through price compression, and device-integrated delivery system partners. Competitive moves concentrate on M&A for manufacturing scale and strategic partnerships for companion device co-development.
Within the diversified pharmaceutical tier, Amgen and Pfizer occupy positions anchored by heritage oncology portfolios and established European hospital relationships. Sandoz exemplifies the biosimilar pure-play archetype through broad distribution networks and tender-focused commercial models. Among specialized biologics manufacturers, Coherus BioSciences and Evive Biotech represent entrants leveraging EMA pathway acceleration for market entry.
| Leading Market Players |
|---|
| Fresenius Kabi |
| Chugai Pharmaceutical |
| Amgen |
| Evive Biotech |
| Italfarmaco |
| Pfizer |
| Coherus BioSciences |
| Stada Arzneimittel |
| Sandoz |
| Others |
Supply & Pricing Matrix
Mammalian cell culture media costs flow downstream through pegylation chemistry steps to compress margin structures at the biosimilar tier while sustaining premium positioning for originator PEG-G-CSF in Belgian and Dutch private clinics. This input-cost pathway shapes how German hospital procurement consortia negotiate reference-priced short-acting G-CSF tenders against long-acting formulation premiums.
Pricing Analysis
Capacity additions in South Korean and Indian biologics manufacturing are reshaping price floors for short-acting G-CSF across European tender markets. Three-tier pricing structure across premium, standard, and economy levels separates originator PEG-G-CSF with on-body injector bundling from unbranded biosimilar G-CSF and private-label hospital contract tiers. Cost compression in the biosimilar segment is intensifying because Italy's regional tender consolidation and Spain's pharmacist-led substitution mandates eliminate prescriber discretion buffers. Hospital procurement managers in Germany exhibit the highest price sensitivity, while private oncology clinics in the Netherlands absorb premiums for reduced injection frequency.
Supply Chain Analysis
Specialized bioprocessing workforce availability in Germany, Switzerland, and Ireland constrains mammalian cell culture capacity expansion for pegylated formulation manufacturing. Upstream inputs draw from Chinese-sourced polyethylene glycol derivatives, European-sourced cell culture media, and US-sourced filtration membranes. Single-source vulnerability concentrates in the on-body injector device tier, where EU MDR compliance dossiers require 18-24 month qualification cycles that lock in incumbent suppliers. Distribution runs through temperature-controlled logistics networks anchored by regional hubs in the Netherlands and Belgium, with last-mile cold chain integrity monitored via GxP-validated tracking systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe G-CSF/PEG-G-CSF Market represents a late-cycle quality story where demand is shifting toward premium long-acting formulations with integrated delivery devices that reduce clinic visit burden and improve real-world adherence.
For Market Incumbents: Extend formulary contract duration through device-integrated bundling that raises switching costs for hospital procurement committees facing Italian regional tender consolidation. Deepen pegylation chemistry capabilities through captive supply of specialized polyethylene glycol derivatives to defend against South Korean and Indian biosimilar manufacturing scale. Prioritize MDR compliance dossier maintenance as a barrier against mid-tier device competitors seeking entry into German hospital consortia specifications. For New Entrants and Emerging Players: On-body injector platform differentiation offers a technology-first wedge into the Netherlands and Scandinavian homecare settings where patient self-administration training infrastructure remains underdeveloped. Target Spain's Andalusian and Catalan regional health services where pharmacist-led substitution mandates create automatic switching corridors without prescriber relationship requirements. Pursue strategic partnerships with established cold chain logistics providers to bypass the infrastructure investments that strain regional distributor margins. For Investors and Strategic Acquirers: Consolidation pressure builds where EMA biosimilar pathway acceleration enables faster time-to-market but post-launch pharmacovigilance reporting burdens demand registry infrastructure that smaller entrants cannot fund. Over the projection horizon, vertically integrated players with mammalian cell culture capacity and device co-development capabilities present the most durable acquisition profiles. Watch for divergence between France's HAS and England's NICE cost-effectiveness thresholds as an inflection indicator that would force parallel evidence-generation strategies and elevate compliance costs for non-integrated competitors.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Biosimilar Pathway Acceleration | Streamlined comparability studies reduce development timelines for follow-on biologics targeting Italian and Spanish tenders. |
| Companion Device Co-Development | On-body injector integration with dose confirmation sensors automates reimbursement audit trails for Dutch outpatient clinics. |
| Regional Tender Consolidation Participation | Lombardy and Veneto volume aggregation points reward manufacturing scale with preferential biosimilar procurement terms. |
| Cold Chain Infrastructure Investment | Temperature-controlled distribution networks with GxP validation secure last-mile integrity for Belgian hospital alliances. |
| Pharmacovigilance Registry Development | Extended neutropenia recurrence tracking satisfies France's ANSM requirements and accelerates market access negotiations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with regulatory affairs leads at EMA, formulary directors in German hospital procurement consortia, payer access specialists in French national health insurance, and hospital procurement managers in Italian regional health authorities with secondary validation against EMA submission databases, ClinicalTrials.gov records, hospital formulary listings, and G-BA reference pricing decisions. Bottom-up patient-volume modeling and top-down market sizing triangulated segment-level estimates across the analysis window.
Segment-weighting approaches applied differential growth assumptions by product type, administration route, and end-user channel, with oncology prophylaxis volumes, hematology stem cell mobilization protocols, and homecare setting expansion rates serving as key forecast inputs. CAGRs were derived from fitted trend analysis of historical biosimilar penetration curves and reference pricing compression trajectories, cross-referenced against tender participation thresholds and substitution policy implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to HTA divergence between France's HAS and England's NICE, EMA MDR implementation delays for companion devices, and biosimilar immunogenicity surveillance findings that could trigger registry protocol revisions. Forecasts reflect documented assumptions about pegylation chemistry capacity expansion, regional tender consolidation velocity, and cold chain infrastructure investment levels. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Benzodiazepine Drugs Market
Pharmaceuticals
Global Alteplase Market
Pharmaceuticals
Hypertriglyceridemia Therapeutics Market
Pharmaceuticals
Long-Acting Monoclonal Antibodies Market
Pharmaceuticals
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market
Pharmaceuticals
Global Antacids Market
Pharmaceuticals
South Korea Human Papillomavirus Vaccine Market
Pharmaceuticals
Pain Management Drugs Market
Pharmaceuticals
Pharmaceutical Wholesale & Distribution Market
Pharmaceuticals
Asia-Pacific Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Europe Pharmaceutical Market
Pharmaceuticals
Cancer Immunotherapy Drug Discovery Outsourcing Market
Pharmaceuticals
Indonesia Oral Anti-Diabetic Drug Market
Pharmaceuticals
Africa Generic Pharmaceutical Market
Pharmaceuticals
Global Cholera Vaccines Market
Pharmaceuticals
Nefopam Hydrochloride Injection Market