
 Clindamycin Palmitate Hcl Market | 2026-2036
Clindamycin Palmitate Hcl Market Size, Share, and Industry Trends Forecast 2026-2036
Clindamycin Palmitate Hcl Market Insights
Qualified synthetic organic chemists with esterification expertise is bifurcating the competitive landscape into firms that can execute palmitoyl chloride coupling at scale versus those reliant on contract manufacturers. Pfizer Inc leverages its legacy fermentation infrastructure to sustain cost advantages in clindamycin base supply. Aurobindo Pharma Limited anchors its position through vertical integration into active pharmaceutical ingredient production. Zhejiang Tiantai Pharmaceutical competes on geographic proximity to raw material suppliers in eastern China.
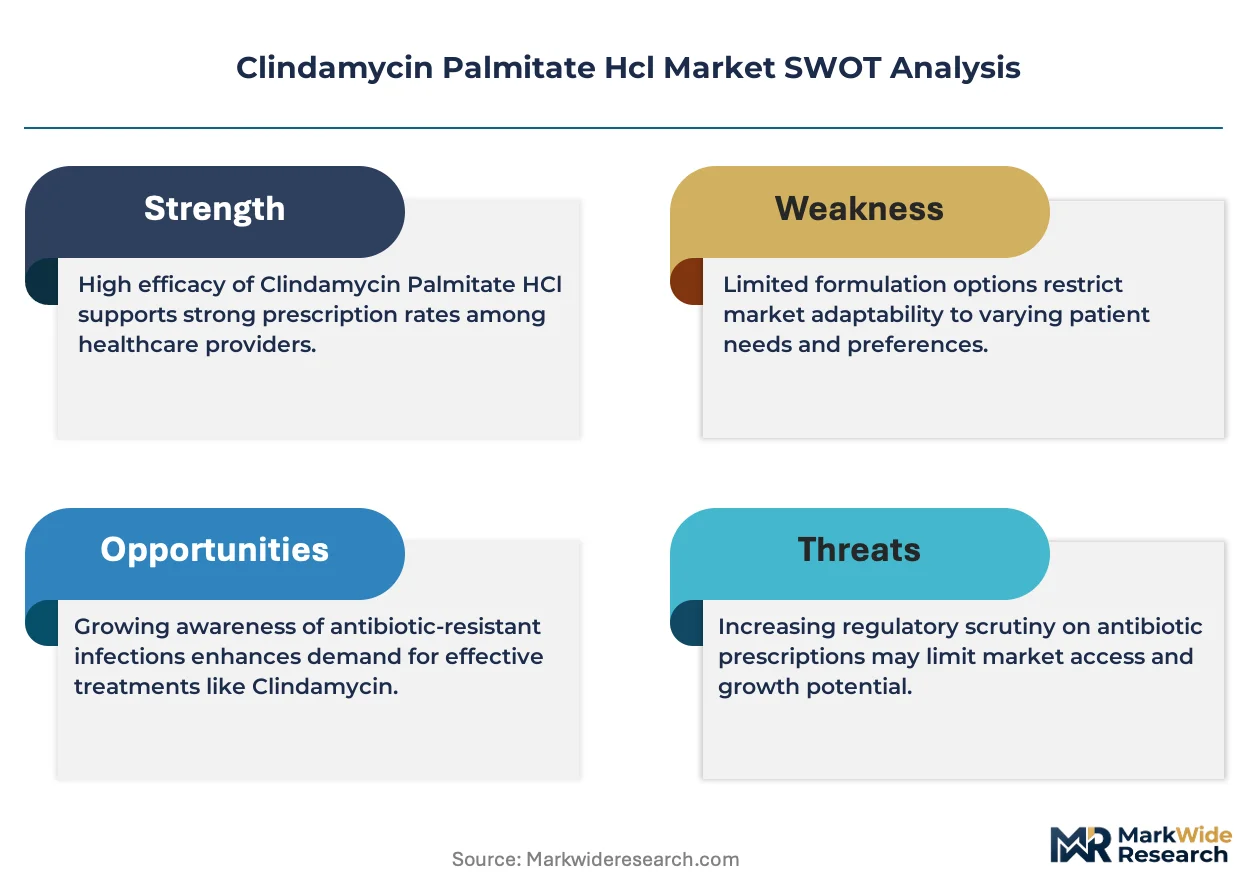
Clindamycin palmitate hydrochloride is a water-soluble prodrug of clindamycin formed by esterification of the C-7 hydroxyl group with palmitic acid, yielding a compound with enhanced stability in aqueous oral suspensions and improved pediatric palatability through reduced bitterness. The molecule serves primarily as a front-line lincosamide antibiotic for Gram-positive and anaerobic infections in patients unable to tolerate clindamycin phosphate injections. Oral solution formulations command expanding share in pediatric and geriatric populations where swallowing capsules presents compliance barriers, while injectable segments retain margin concentration in perioperative surgical prophylaxis. Topical gel applications within skin infections therapy occupy a mature niche with slower volume expansion but durable dermatology channel relationships.
FDA Current Good Manufacturing Practice inspections and USP monograph compliance for clindamycin palmitate HCl assay and impurity profiles shape manufacturer qualification timelines for domestic suppliers. EMA's revised antibiotic stewardship guidelines and REACH chemical registration requirements for palmitoyl chloride intermediates influence European market access conditions and environmental release testing obligations. Stakeholders must monitor evolving FDA guidance on post-market antimicrobial susceptibility reporting as resistance surveillance data increasingly determines formulary placement and reimbursement thresholds for lincosamide therapies.
Market Dynamics
Hospital procurement of pediatric oral antibiotic formulations is expanding as streptococcal and staphylococcal resistance patterns shift, tightening FDA stability testing requirements for palmitate ester prodrugs and bifurcating manufacturers by synthetic organic chemistry capability.
Growth Catalysts
- Outpatient parenteral-to-oral conversion protocols:United States hospital systems are standardizing step-down therapy pathways that favor palmitate prodrug suspensions over extended IV clindamycin phosphate, reducing length-of-stay costs and catheter-associated infection risks.
- REACH chemical registration alignment:European manufacturers achieving full palmitoyl chloride intermediate dossier compliance under ECHA requirements are securing preferential formulary placement in EU5 hospital tenders.
- Esterification process intensification:Continuous-flow reactor technology for C-7 hydroxyl palmitoylation is cutting batch cycle times and impurity formation versus traditional stirred-tank synthesis.
Market Restraints
- Clindamycin base supply concentration:Fermentation-derived base production clusters in China and India, exposing finished dose manufacturers to API import inspection delays and currency volatility.
- Palmitic acid feedstock cost structure:Oleochemical price swings tied to palm oil commodity markets directly compress prodrug synthesis margins for non-integrated formulators.
- Lincosamide cross-resistance surveillance:CDC and ECDC tracking of erm gene-mediated resistance in Streptococcus pneumoniae threatens long-term therapeutic utility and reimbursement tiering.
Strategic Opportunities
- Geriatric swallowing difficulty segments:Japan's aging demographic and PMDA geriatric formulation incentives create demand for palatable oral solutions beyond traditional pediatric positioning.
- Dual-release fixed-dose combinations:Convergence of immediate-release palmitate with extended-release metronidazole core technology addresses polymicrobial abdominal infection protocols.
- Direct-to-pharmacy distribution:Bypassing wholesale consolidation through 340B contract pharmacy networks in the United States captures margin from safety-net hospital dispensing.
Industry Challenges
- Qualified synthetic organic chemist scarcity:Palmitoyl chloride coupling expertise at production scale is concentrated among legacy fermentation-chemistry workforces nearing retirement.
- USP monograph compliance timelines:Assay method validation and impurity profile qualification for clindamycin palmitate HCl extends FDA pre-approval inspection windows by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clindamycin Palmitate Hcl Market |
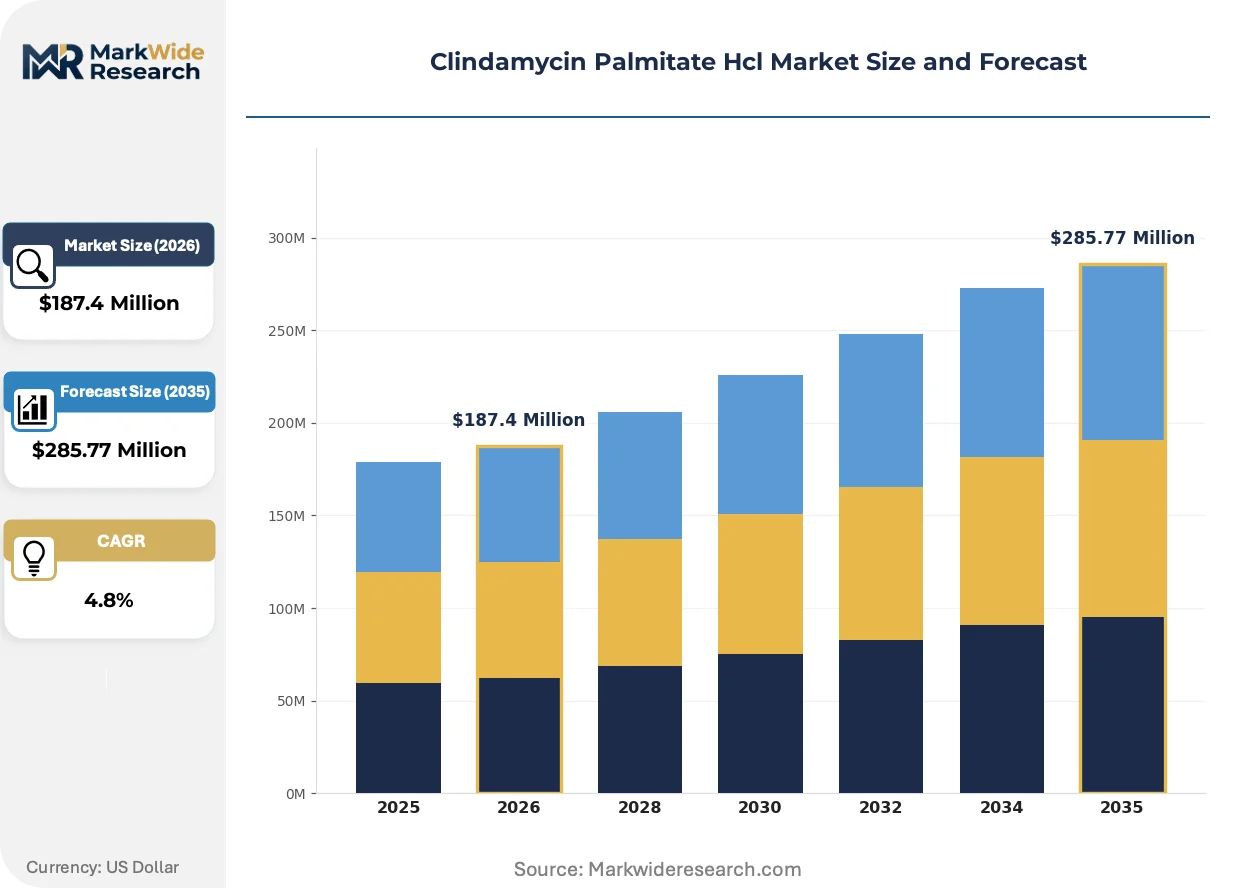
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Oral Solution, Injectable, Topical Gel Therapy Area: Antibiotic Treatment, Skin Infections, Respiratory Infections, Gynecological Disorders End User: Hospitals, Clinics, Home Care Services, Retail Pharmacies Delivery Mode: Oral Administration, Injection, Topical Application, Intravenous Infusion |
| Companies Covered | SCI Pharmtech, YaoPharma, Midas Pharma, Hubei Yitai Pharmaceutical, Zhejiang Tiantai Pharmaceutical, Zhejiang Weili Chemical, Aurobindo Pharma Limited, Lupin Ltd, Pfizer Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clindamycin Palmitate Hcl Market Trends and Innovations
Formulation science and regulatory chemistry are converging to reshape lincosamide prodrug manufacturing, with stability optimization and pediatric palatability engineering driving competitive differentiation.
Continuous manufacturing platforms for palmitate ester synthesis are displacing batch-reactor operations at mid-scale API producers. European CMOs serving hospital generic markets are retrofitting plug-flow reactors to reduce solvent volumes and thermal degradation of the C-7 ester linkage. This displacement is compressing capital intensity thresholds and enabling geographic redistribution of finished dose production.
EMA's revised antibiotic stewardship guidelines now mandate post-market susceptibility reporting for all systemic lincosamide formulations, creating compliance infrastructure requirements that favor larger manufacturers with dedicated pharmacovigilance teams. Hospital antibiotic committees in Germany and France are incorporating these surveillance data into quarterly formulary reviews, shifting procurement toward suppliers with transparent resistance tracking systems.
Pediatric taste-masking through bitterness reduction is redirecting R&D investment toward excipient innovation rather than API modification. Flavor house partnerships with generic suspension manufacturers are replacing in-house formulation development, with strawberry-grape masking systems now standard in United States retail pharmacy compounding. This outsourcing pattern is most visible in independent pharmacy chains serving Medicaid populations where palatability drives adherence metrics.
Clindamycin Palmitate Hcl Market Segmentation
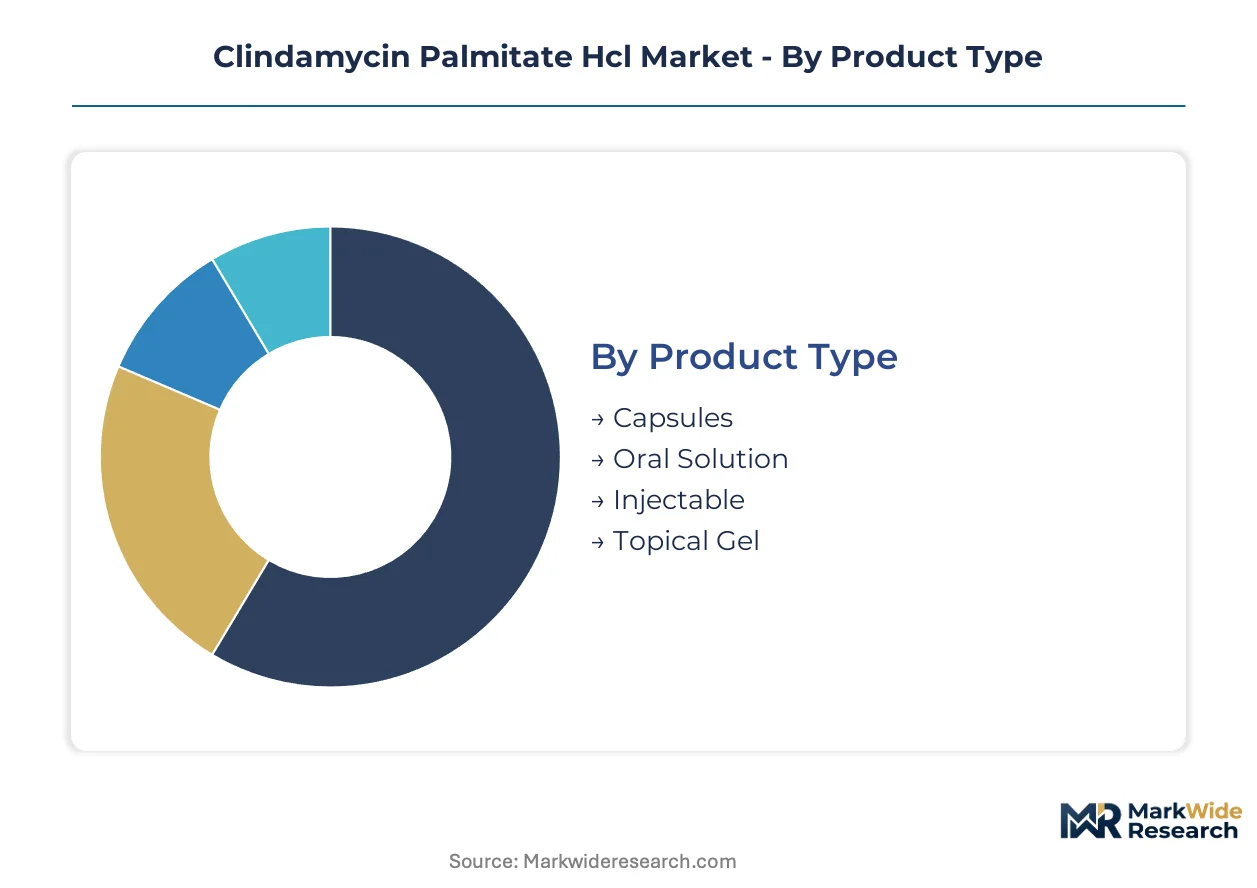
Segmentation in clindamycin palmitate HCl markets reveals how formulation chemistry, clinical setting, and patient physiology intersect to determine procurement patterns. Hospital antibiotic committees weight pediatric palatability against IV-to-oral conversion economics when allocating formulary slots across product categories.
Product Type:
Substitution pressure from generic clindamycin phosphate and newer lincosamides varies sharply across formulation platforms, with liquid suspensions facing distinct competitive dynamics from solid oral doses.
- Oral Solution:Aqueous palmitate suspensions with enhanced stability profiles and bitterness-masking excipients serve pediatric populations unable to swallow solids. United States hospital discharge protocols for community-acquired pneumonia are standardizing step-down therapy to this format, reducing catheter-associated bloodstream infection risks.
- Injectable:Sterile clindamycin palmitate HCl for IV or IM administration retains perioperative surgical prophylaxis applications where rapid therapeutic levels outweigh oral bioavailability considerations. Japanese acute care facilities maintain preference for parenteral initiation in severe anaerobic infections before conversion.
- Capsules:Solid oral dosage forms containing palmitate salt for adult populations with intact swallowing function.
- Topical Gel:Dermatological formulations for localized acne vulgaris and superficial skin infections with limited systemic absorption.
Oral solution anchors the volume base while injectable formats gain share at the steepest rate through parenteral-to-oral protocol expansion.
Therapy Area:
Cost tier stratification separates acute infection management from chronic dermatological maintenance, with reimbursement intensity tracking severity of illness and hospitalization requirements.
- Antibiotic Treatment:Systemic lincosamide therapy for Gram-positive and anaerobic infections spanning pneumonia, intra-abdominal sepsis, and bone and joint infections. United States Medicaid programs track adherence metrics for palmitate suspensions in pediatric populations, influencing pharmacy benefit manager tier placement.
- Skin Infections:Topical and oral formulations targeting methicillin-resistant Staphylococcus aureus and Streptococcus pyogenes in cellulitis and wound infections. German outpatient clinics are expanding prescription volumes for community-treated dermatological cases as hospital admission thresholds tighten.
- Respiratory Infections:Anaerobic lung abscess and aspiration pneumonia indications where clindamycin penetrates well into pulmonary tissue.
- Gynecological Disorders:Bacterial vaginosis and pelvic inflammatory disease applications with preference for oral over intravaginal metronidazole in certain patient populations.
Antibiotic treatment commands the largest revenue pool while skin infection applications expand most quickly through outpatient protocol shifts.
End User:
Customer type determines packaging specifications, cold chain requirements, and compliance support infrastructure, with institutional procurement favoring bulk suspensions and retail channels requiring unit-dose convenience.
- Hospitals:Integrated delivery networks purchasing palmitate suspensions through 340B contract pharmacy arrangements and group purchasing organization contracts. FDA stability testing requirements for palmitate ester prodrugs extend supplier qualification timelines, concentrating procurement among manufacturers with established inspection histories.
- Retail Pharmacies:Independent and chain pharmacies compounding flavored suspensions for Medicaid pediatric populations. Flavor house partnerships with generic manufacturers are replacing in-house formulation development, with strawberry-grape masking systems now standard in United States retail settings.
- Clinics:Outpatient facilities with limited on-site pharmacy services.
- Home Care Services:Infusion and visiting nurse organizations managing IV-to-oral transitions in residential settings.
Hospitals anchor the volume base while retail pharmacies gain share at the steepest rate through direct-to-consumer compounding expansion.
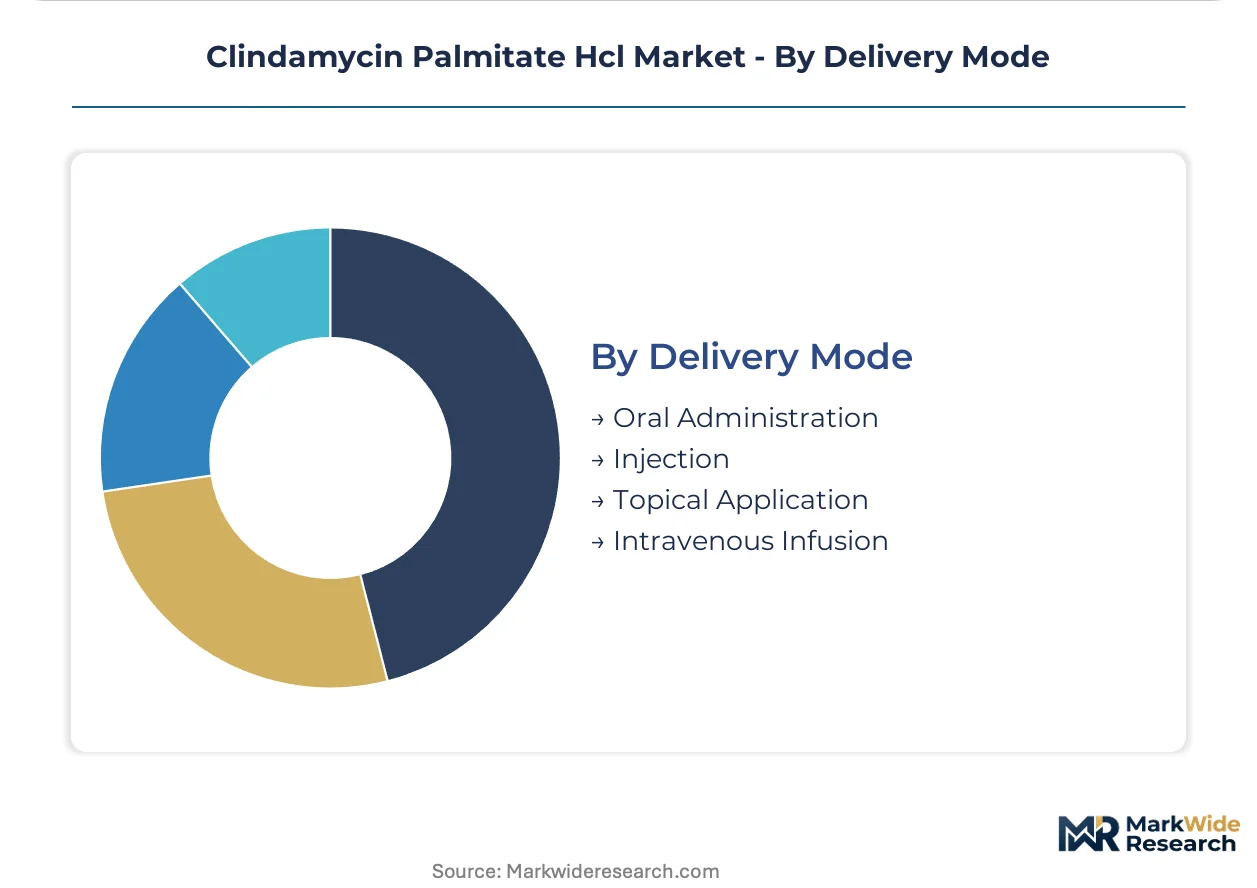
Delivery Mode:
Supply concentration in fermentation-derived API production shapes finished dose availability across administration routes, with oral formats less exposed to import inspection delays than sterile injectables.
- Oral Administration:Palmitate suspension and capsule formats leveraging enhanced aqueous stability and reduced gastric irritation versus clindamycin base. Continuous-flow reactor technology for C-7 hydroxyl palmitoylation is cutting batch cycle times at mid-scale API producers serving this segment.
- Injection:Parenteral clindamycin palmitate HCl for perioperative prophylaxis and severe infection initiation. Clindamycin base supply concentration in China and India exposes finished dose manufacturers to API import inspection delays and currency volatility.
- Topical Application:Dermatological gel and lotion vehicles for localized drug delivery.
- Intravenous Infusion:Diluted palmitate solutions for extended infusion protocols in intensive care settings.
Oral administration anchors the volume base while injection formats gain share at the steepest rate through surgical prophylaxis protocol standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA outpatient parenteral-to-oral conversion protocols anchor United States demand, while EMA antibiotic stewardship guidelines and REACH chemical registration requirements reshape European access conditions. Hospital procurement patterns and fermentation-base supply geography determine finished dose availability across major markets.
United States
Hospital discharge protocols for community-acquired pneumonia standardize step-down therapy to palmitate suspensions, reducing catheter-associated bloodstream infection risks. FDA Current Good Manufacturing Practice inspections and USP monograph compliance extend supplier qualification timelines. The 340B contract pharmacy network captures margin from safety-net hospital dispensing in urban clusters.
Germany
Hospital antibiotic committees incorporate ECDC resistance surveillance data into quarterly formulary reviews. EMA revised antibiotic stewardship guidelines mandate post-market susceptibility reporting for systemic lincosamide formulations. Continuous-flow reactor retrofits at mid-scale API producers in the Rhineland compress capital intensity thresholds.
China
Fermentation-derived clindamycin base production concentrates in eastern coastal provinces, exposing finished dose manufacturers to NMPA import inspection delays. Dual carbon goals and MEE environmental release testing obligations tighten palmitoyl chloride intermediate production standards. Zhejiang province API producers compete on geographic proximity to oleochemical feedstock suppliers.
India
CDSCO stability testing requirements for palmitate ester prodrugs align with tightening quality benchmarks for pediatric oral antibiotic exports. PLI scheme incentives for active pharmaceutical ingredient production attract backward integration investments. Maharashtra and Gujarat fermentation-chemistry workforces concentrate palmitoyl chloride coupling expertise.
Japan
PMDA geriatric formulation incentives create demand for palatable oral solutions beyond traditional pediatric positioning. METI standards guide continuous manufacturing platform adoption for palmitate ester synthesis. Kanto region acute care facilities maintain preference for parenteral initiation in severe anaerobic infections before conversion.
Clindamycin Palmitate Hcl Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with fermentation infrastructure ownership and esterification chemistry capability determining competitive position. The upper tier commands cost advantages in base supply and FDA inspection histories. Three archetypes dominate: legacy pharmaceutical conglomerates with captive fermentation assets, vertically integrated Indian generic houses, and China-based API-to-formulation specialists. Competitive moves concentrate on continuous manufacturing technology licensing and 340B contract pharmacy network access.
Among fermentation-anchored conglomerates, Pfizer Inc exemplifies the integrated leader archetype through legacy infrastructure control. Aurobindo Pharma Limited and Lupin Ltd represent the Indian vertical-integration model, with backward integration into active pharmaceutical ingredient production securing supply chain position. Zhejiang Tiantai Pharmaceutical occupies a position within the China-based specialist tier, leveraging geographic proximity to raw material suppliers in eastern coastal provinces.
| Leading Market Players |
|---|
| SCI Pharmtech |
| YaoPharma |
| Midas Pharma |
| Hubei Yitai Pharmaceutical |
| Zhejiang Tiantai Pharmaceutical |
| Zhejiang Weili Chemical |
| Aurobindo Pharma Limited |
| Lupin Ltd |
| Pfizer Inc |
| Others |
Pricing and Supply Chain Analysis
Continuous-flow reactor retrofits displacing stirred-tank palmitoylation simultaneously redistribute API production geography and compress capital-recovery timelines for finished dose pricing. This substitution dynamic tightens margins at legacy batch-reactor facilities while enabling mid-scale European producers to capture hospital generic tenders through lower unit economics.
Pricing Analysis
Long-term offtake contracts between integrated fermentation houses and finished dose manufacturers dominate procurement, with spot market activity concentrated in oleochemical feedstock purchasing. Price differentiation hinges on FDA inspection history and USP monograph compliance status, with qualified suppliers commanding premiums over contract-manufacturing alternatives. Pricing pressure stems from palmitic acid commodity volatility tied to palm oil markets. Retail pharmacy compounding chains exhibit highest price sensitivity due to Medicaid reimbursement ceilings, while hospital 340B networks tolerate premium positioning for supply security.
Supply Chain Analysis
Inbound logistics costs through Shanghai and Ningbo port corridors expose non-integrated formulators to container availability swings and NMPA export documentation delays. Fermentation-derived clindamycin base production anchors in Zhejiang and Jiangsu provinces, with palmitoyl chloride intermediates sourced from Shandong oleochemical clusters. Single-source vulnerability concentrates in the C-7 hydroxyl palmitoylation step, where qualified synthetic organic chemist scarcity limits qualified CMO alternatives. Distribution runs through 340B contract pharmacy networks and group purchasing organization contracts to hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as parenteral-to-oral conversion protocols create formulation-specific demand niches beyond commodity antibiotic positioning. Pediatric palatability engineering and geriatric swallowing difficulty segments reward specialized capability investments over broad portfolio plays.
For Market Incumbents: Fortify FDA inspection histories through preemptive USP monograph assay validation investments, extending supplier qualification moats against emerging contract manufacturers. Captive fermentation infrastructure anchors cost position against API import volatility from Zhejiang and Jiangsu production clusters. Continuous-flow reactor licensing to mid-scale European CMOs defends volume share in EU5 hospital tenders. For New Entrants and Emerging Players: Differentiate on geriatric formulation science for Japan's aging demographic, where PMDA incentives reduce regulatory barriers for palatable oral solutions. Japan's acute care facilities present the most penetrable conversion opportunity from parenteral initiation protocols. Target flavor house partnerships rather than in-house excipient development to compress R&D timelines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Indian API-to-formulation specialists possessing CDSCO export qualifications and PLI scheme incentives. Five-to-ten year viability hinges on erm gene resistance surveillance trajectories and lincosamide stewardship guideline evolution. Watch CDC and ECDC quarterly resistance reports as formulary tiering inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Platform Adoption | Plug-flow reactor retrofits cut batch cycle times and impurity formation at mid-scale API producers. |
| Flavor House Partnership Expansion | Strawberry-grape masking systems replace in-house formulation development for Medicaid pediatric adherence. |
| 340B Contract Pharmacy Network Access | Bypassing wholesale consolidation captures margin from safety-net hospital dispensing in urban clusters. |
| Backward Integration into Fermentation Base | Captive clindamycin base production insulates against NMPA import inspection delays and currency volatility. |
| EMA Antibiotic Stewardship Compliance Infrastructure | Post-market susceptibility reporting capabilities secure preferential formulary placement in German and French hospital tenders. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital formulary directors, regulatory affairs leads at API manufacturers, pediatric infectious disease specialists, and procurement managers at group purchasing organizations. Secondary validation drew from FDA inspection databases, EMA submission records, USP monograph documentation, and CDSCO export registration filings. Bottom-up volume modeling triangulated against top-down pharmaceutical market sizing from customs trade data and hospital procurement databases.
Across the analysis window, forecasts segment by formulation platform, therapy area severity tier, end-user channel, and regional regulatory cluster. CAGRs derive from patient volume epidemiology, resistance surveillance trajectories, and protocol adoption curves for parenteral-to-oral conversion. Model inputs incorporate ECDC resistance tracking, Medicaid pharmacy benefit manager tier placement dynamics, and continuous manufacturing technology diffusion rates.
Material uncertainties — erm gene-mediated resistance expansion, palmitic acid commodity volatility, and FDA inspection prioritization shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding stewardship guideline stability and REACH chemical registration alignment. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Compound Acetaminophen Market
Pharmaceuticals
Digital Pharmaceutical Supply Chain Management Market
Pharmaceuticals
Global Contraceptive Drugs and Devices Market
Pharmaceuticals
Global Lidocaine Transdermal Patch Market
Pharmaceuticals
Global PD-1 and PD-L1 Inhibitors Market
Pharmaceuticals
Global Epilepsy Drug Market
Pharmaceuticals
Capecitabine Market
Pharmaceuticals
Anti-Vascular Endothelial Growth Factor Therapeutics Market
Pharmaceuticals
Vaginal Antifungals Market
Pharmaceuticals
Global Anticoccidial Drugs Market
Pharmaceuticals
Africa Generic Pharmaceutical Market
Pharmaceuticals
Extended Release Drugs Market
Pharmaceuticals
Global Monoclonal Antibody Therapeutics Market
Pharmaceuticals
Global Human Growth Hormone (HGH) Market
Pharmaceuticals
Oral Vaccines Market
Pharmaceuticals
Second Generation Cephalosporins Market