
 Articaine Hydrochloride Market | 2026-2036
Articaine Hydrochloride Market Size, Share, and Industry Trends Forecast 2026-2036
Articaine Hydrochloride Market Analysis
Maintenance and calibration service contracts bundled with articaine delivery systems is recalibrating how dental supply contracts are negotiated and renewed. Pierrel S.p.A. leverages its European manufacturing base to sustain long-term supply agreements with major dental distributors. Septodont anchors its competitive stance through deep specialization in dental anesthetics and adjacent infection control products. Dentsply Sirona extends its reach by integrating articaine formulations into its broader digital dentistry workflow platforms.
Articaine hydrochloride is an amide-type local anesthetic containing a thiophene ring and an additional ester group, enabling rapid plasma hydrolysis by plasma cholinesterases and reducing systemic toxicity risk compared to conventional amides. It serves primarily as an infiltrative and block anesthetic in dental and oral surgical procedures where rapid onset and short half-life improve patient throughput. Injectable formulations dominate volume due to their established efficacy in mandibular and maxillary blocks, while dental solutions represent the fastest-growing category as pre-mixed cartridges simplify chairside preparation and reduce dosing errors. Ambulatory surgical centers are emerging as a concentrated margin pool as same-day oral surgery migration accelerates and anesthetic procurement consolidates under group purchasing organizations.
FDA oversight of local anesthetic cardiovascular safety warnings shapes product labeling and liability exposure for manufacturers distributing in the United States. EMA pharmacovigilance requirements and the EU Medical Device Regulation collectively tighten post-market surveillance obligations for articaine-device combination products entering European channels. Stakeholders must monitor evolving biodegradability standards for single-use dental cartridges and assess how plasma cholinesterase deficiency screening protocols could reshape patient selection criteria across clinical settings.
Market Dynamics
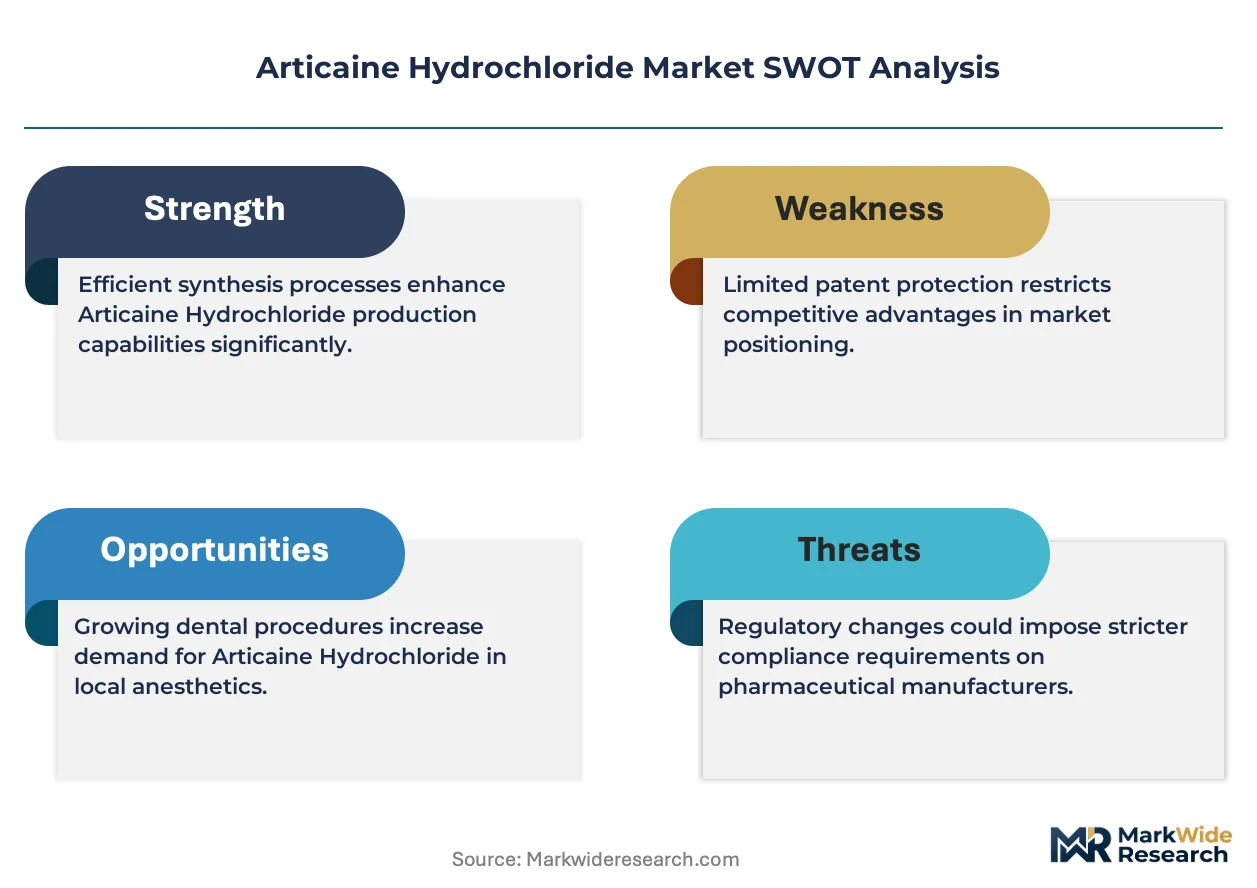
Regulatory tightening around local anesthetic cardiovascular safety profiles by the FDA and EMA is accelerating manufacturer investment in articaine's favorable plasma cholinesterase metabolism pathway. This structural force is compressing development timelines for competing amide formulations while elevating articaine's clinical positioning across outpatient surgical settings.
Growth Catalysts
- EMA Pharmacovigilance Requirements:Post-market surveillance obligations for articaine-device combinations create compliance barriers that favor established manufacturers with robust pharmacovigilance infrastructure.
- Dental Clinic Consolidation:Outpatient oral surgery volumes are climbing as same-day procedures migrate from hospitals, concentrating procurement power among large dental service organizations.
- Plasma Cholinesterase Metabolism:Articaine's rapid hydrolysis pathway reduces systemic toxicity risk compared to lidocaine and prilocaine, driving formulary preference in pediatric and geriatric patient populations.
Market Restraints
- Raw Material Concentration:Thiophene ring precursors for articaine synthesis concentrate among specialty chemical suppliers in Germany and Switzerland, creating single-source vulnerability.
- Plasma Cholinesterase Deficiency Screening:Patient selection protocols requiring genetic or enzymatic testing add procedural friction and limit addressable population in emergency settings.
- Prilocaine Substitution:Competing amide anesthetics with established reimbursement codes and lower unit costs retain share in price-sensitive public health systems.
Strategic Opportunities
- Ambulatory Surgical Center Migration:Same-day oral surgery consolidation under group purchasing organizations creates concentrated margin pools for articaine cartridge suppliers with GPO contracting capability.
- Pre-Mixed Cartridge Formats:Dental solutions simplify chairside preparation and reduce dosing errors, opening premium positioning against conventional vial-and-syringe compounding.
- Biodegradability Standards:Evolving EU requirements for single-use dental cartridge materials create first-mover advantage for suppliers with compostable or recyclable injection systems.
Industry Challenges
- Combination Product Certification:Articaine-device submissions under EU MDR face extended timeline compression as notified body capacity constraints delay CE marking.
- Legacy Anesthetic Inventory:Dental practices maintain parallel stocks of lidocaine and articaine, complicating inventory management and diluting articaine penetration metrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Articaine Hydrochloride Market |
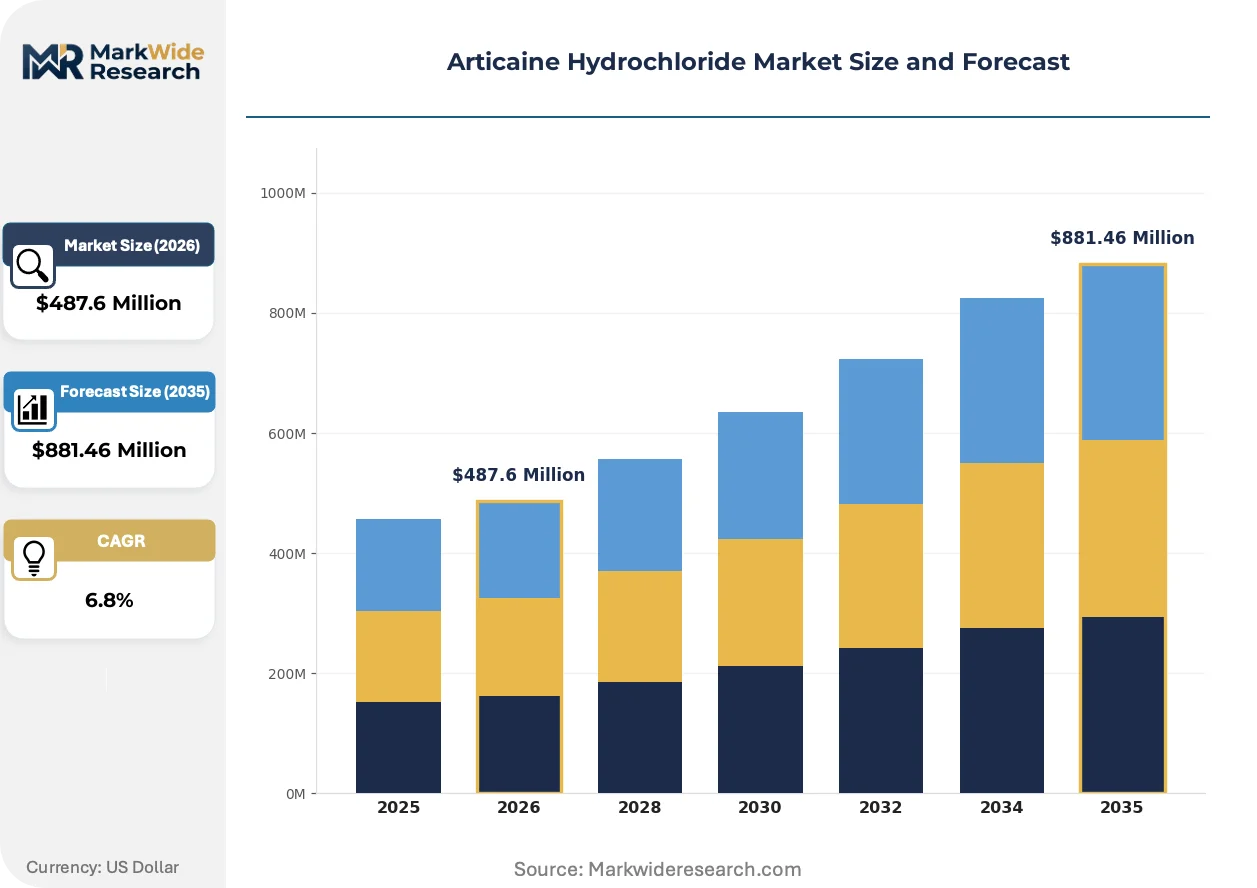
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Dental Solutions, Topical, Other Forms Application: Dental Anesthesia, Surgical Procedures, Pain Management, Orthopedic Procedures End User: Dental Clinics, Hospitals, Ambulatory Surgical Centers, Home Care Delivery Mode: Intravenous, Intraosseous, Subcutaneous, Others |
| Companies Covered | Pierrel S.p.A., Anhui BBCA Pharmaceutical Co., Ltd., Septodont, Patterson Companies, Manus Aktteva Biopharma LLP, Dentsply Sirona, Sanofi, Heraeus Kulzer, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Articaine Hydrochloride Market Emerging Trajectories
Digital dentistry workflow integration is reshaping how anesthetic procurement aligns with chairside technology investments. Pre-mixed cartridge systems and connected delivery devices are compressing traditional supply relationships while elevating service-contract centrality.
Pre-mixed articaine cartridges with integrated aspiration detection are decentralizing anesthetic preparation from central pharmacy compounding to point-of-care activation. Large dental service organizations in Germany and the United States are adopting these systems at accelerated pace to reduce chairside setup time. This technology is decentralizing procurement authority from hospital pharmacy committees to individual clinic administrators.
FDA cardiovascular safety warnings for local anesthetics are mandating enhanced product labeling and risk mitigation strategies for manufacturers distributing in the United States. The industrial consequence is elevated liability exposure and accelerated withdrawal of older amide formulations with less favorable safety profiles. Injectable articaine products with established post-market surveillance data are capturing share from reformulating competitors.
Group purchasing organization consolidation is compressing supplier negotiation cycles and unbundling traditional equipment-anesthetic bundled contracts. Dental distributors in North America and Western Europe are responding with subscription-based inventory management programs. This shift is most visible in Germany, where dental procedure density and reimbursement support for advanced anesthetics exceed regional peers.
Articaine Hydrochloride Market Segmentation
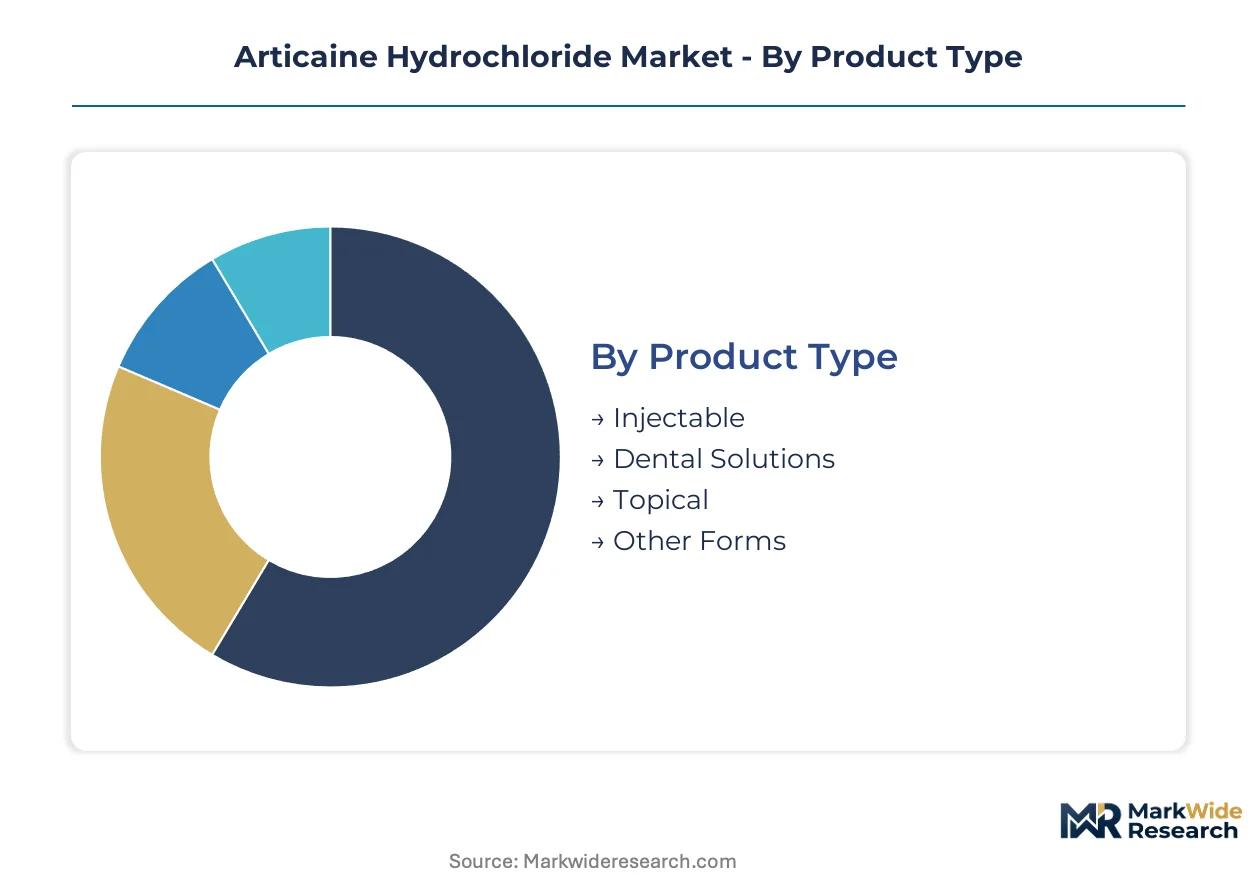
Articaine hydrochloride's structural differentiation across delivery formats and clinical settings creates distinct regulatory pathways and margin profiles. Each segment carries specific FDA, EMA, or national pharmaceutical regulator certification burdens that shape competitive entry costs and supplier concentration.
Product Type:
Injectable formulations demand FDA New Drug Application or EMA Marketing Authorization pathways, while dental solutions fall under combination product rules requiring device-anesthetic dual clearance. Topical preparations face lighter cosmetic or over-the-counter designation thresholds in most jurisdictions.
- Injectable:Cartridge-based parenteral formulations containing articaine hydrochloride with epinephrine or plain variants dominate mandibular and maxillary block procedures. Demand concentrates in German dental clinics where reimbursement for advanced anesthetics exceeds regional peers, driven by outpatient oral surgery volume expansion.
- Dental Solutions:Pre-mixed cartridges with integrated aspiration detection simplify chairside preparation and reduce dosing errors. Ambulatory surgical centers in the United States are adopting these systems fastest as same-day oral surgery migration accelerates under group purchasing organization procurement consolidation.
- Topical:Surface anesthesia for mucosal pre-injection numbing carries lighter regulatory designation in most markets.
- Other Forms:Compounding pharmacy preparations and specialty delivery formats serve niche pediatric or allergy-sensitive patient populations.
Injectable sits at the top of the volume ranking, with dental solutions climbing the fastest.
Application:
Cost tier differentiation separates premium-positioned surgical applications from commoditized pain management, with dental anesthesia commanding the highest unit economics due to procedure-specific reimbursement codes.
- Dental Anesthesia:Infiltrative and block anesthesia for routine extractions, endodontic procedures, and implant placements represents the core revenue pool. German dental procedure density and favorable reimbursement for articaine over lidocaine or prilocaine sustains premium positioning.
- Surgical Procedures:Outpatient oral surgery applications leverage articaine's rapid plasma cholinesterase metabolism to reduce systemic toxicity risk in same-day discharge settings. FDA cardiovascular safety warnings for competing amide anesthetics accelerate formulary preference in United States ambulatory surgical centers.
- Pain Management:Post-operative and chronic pain applications compete against established lidocaine and bupivacaine formulations with deeper reimbursement history.
- Orthopedic Procedures:Joint infiltration and regional block applications remain experimental with limited approved indications.
Dental anesthesia captures the dominant share of value, while surgical procedures gain share fastest on outpatient migration trends.
End User:
Customer type determines procurement authority concentration, with dental service organizations consolidating purchasing power while home care remains fragmented and price-sensitive.
- Dental Clinics:Solo and group practices drive volume through high procedure frequency and preference for rapid-onset, short-half-life anesthetics that improve patient throughput. Large dental service organizations in Germany and the United States are centralizing procurement under subscription-based inventory management programs.
- Hospitals:Inpatient oral surgery and emergency departments maintain parallel stocks of multiple amide anesthetics, complicating articaine penetration metrics.
- Ambulatory Surgical Centers:Same-day oral surgery consolidation creates concentrated margin pools for suppliers with group purchasing organization contracting capability.
- Home Care:Limited to post-operative pain management with restricted reimbursement for self-administered local anesthetics.
Dental clinics anchor volume, with ambulatory surgical centers expanding most quickly on procedure migration.
Delivery Mode:
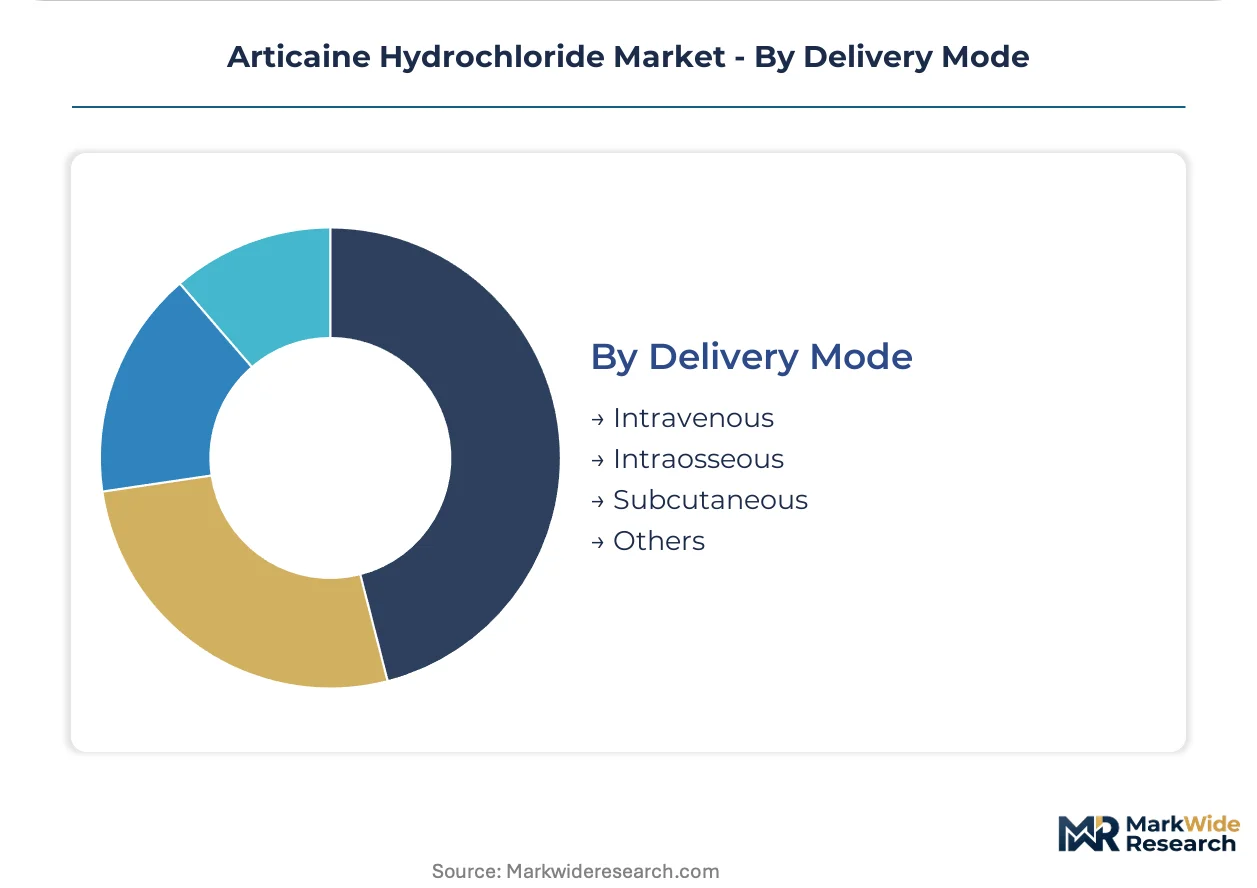
Volume concentration favors traditional intravenous and intraosseous pathways, with emerging techniques requiring specialized training and capital equipment investment.
- Intravenous:Standard parenteral delivery through conventional dental syringes and aspirating cartridges dominates clinical practice.
- Intraosseous:Direct bone infiltration techniques for mandibular anesthesia reduce injection volume and systemic exposure.
- Subcutaneous:Soft tissue infiltration for minor surgical procedures and supplemental anesthesia.
- Others:Computer-controlled delivery systems and pressure-sensing technologies emerging in premium dental equipment integrations.
Intravenous maintains volume leadership, with intraosseous techniques gaining adoption fastest on reduced systemic toxicity positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands higher articaine procedure density than the United States, though American ambulatory surgical centers are consolidating procurement faster under group purchasing organizations. Regulatory divergence between FDA cardiovascular warnings and EMA pharmacovigilance requirements is fragmenting go-to-market strategies across jurisdictions.
Germany
Dental procedure density and favorable reimbursement for advanced anesthetics over lidocaine sustain premium articaine positioning. The national pharmaceutical regulator enforces strict post-market surveillance under EU Medical Device Regulation for combination products. Manufacturing clusters in North Rhine-Westphalia and Hesse concentrate thiophene precursor supply for regional API production.
United States
FDA cardiovascular safety warnings for competing amide anesthetics accelerate formulary preference in outpatient oral surgery settings. The agency mandates enhanced risk mitigation strategies and labeling disclosures for local anesthetic distribution. Dental service organizations in Texas and Florida lead subscription-based inventory management adoption.
Switzerland
Swissmedic oversight of plasma cholinesterase metabolism claims supports articaine's clinical differentiation in pediatric applications. The regulator's pharmacovigilance requirements align with EMA frameworks while maintaining independent device-anesthetic combination assessments. Basel and Zurich anchor specialty chemical production for thiophene ring precursors.
France
ANSM monitoring of local anesthetic adverse events reinforces articaine's safety profile in dental practice guidelines. The national regulator coordinates with EMA on post-market surveillance for cartridge-based delivery systems. Industrial concentration around Paris and Lyon supports dental distributor consolidation under regional purchasing alliances.
China
NMPA marketing authorization pathways for imported dental anesthetics create compliance barriers favoring established manufacturers with local pharmacovigilance infrastructure. The regulator's emphasis on cardiovascular safety data shapes product registration timelines. Shanghai and Beijing dental clinics drive demand for pre-mixed cartridge formats.
Articaine Hydrochloride Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation innovators capturing premium positioning in dental solutions while API suppliers compete on thiophene precursor purity and volume scale. Market structure tilts toward consolidation among European incumbents with established EMA compliance infrastructure, though Asian manufacturers are penetrating contract manufacturing tiers. Three archetypes dominate: integrated dental equipment-anesthetic bundlers, pure-play pharmaceutical formulators, and specialty chemical API suppliers. Dominant competitive moves include strategic partnerships with group purchasing organizations and backward integration into thiophene ring precursor production.
Among European pharmaceutical specialists, Pierrel S.p.A. and Septodont occupy positions anchored by regional manufacturing bases and dental anesthetic specialization. Dentsply Sirona exemplifies the equipment-anesthetic bundler archetype, leveraging digital dentistry workflow integration to secure long-term supply agreements. These three companies represent distinct strategic postures within a market where regulatory compliance infrastructure and distributor relationship depth determine sustainable positioning.
| Leading Market Players |
|---|
| Pierrel S.p.A. |
| Anhui BBCA Pharmaceutical Co., Ltd. |
| Septodont |
| Patterson Companies |
| Manus Aktteva Biopharma LLP |
| Dentsply Sirona |
| Sanofi |
| Heraeus Kulzer |
| 3M Company |
| Others |
Supply Flow & Price Mechanics
Group purchasing organization consolidation among United States dental service organizations is compressing supplier negotiation cycles and forcing cartridge manufacturers toward subscription-based inventory models that embed service contracts into per-unit pricing. This procurement shift concentrates volume commitments among fewer buyers, elevating price transparency while squeezing margin on transactional sales.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for thiophene-derived articaine API as regional manufacturers expand output. Pricing stratifies across premium, standard, and economy tiers based on FDA cardiovascular safety data depth and EMA pharmacovigilance infrastructure investment. Cost compression in the standard tier is intensifying because prilocaine retains reimbursement advantage in price-sensitive public health systems. Ambulatory surgical centers exhibit lowest price sensitivity due to bundled procedure economics, while solo dental practices in Southern Europe face acute budget constraints.
Supply Chain Analysis
Dual-sourcing mandates from major German dental distributors are forcing thiophene precursor suppliers to qualify secondary manufacturing sites in Switzerland and Belgium. Raw material dependencies center on thiophene ring precursors, epinephrine stabilizers, and glass cartridge substrates. Single-source vulnerability concentrates in North Rhine-Westphalia specialty chemical clusters, where one supplier dominates high-purity thiophene production. Distribution runs through regional dental distributors with exclusive territory agreements, though direct-to-clinic subscription models are eroding this structure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Articaine hydrochloride offers margin expansion potential as pre-mixed cartridge formats command premium positioning and plasma cholinesterase metabolism claims justify reimbursement tier elevation above legacy amides.
For Market Incumbents: Cement formulary lock-in through backward integration into thiophene precursor production and exclusive GPO contracting with United States ambulatory surgical center networks. Prilocaine substitution pressure in European public health systems demands defensive certification investment under EU MDR combination product rules. Capacity expansion in Hesse manufacturing clusters secures supply continuity against Swiss competitor inroads. For New Entrants and Emerging Players: Pediatric dental clinics represent an underserved buyer archetype with unmet demand for plasma cholinesterase deficiency screening protocols and weight-based dosing formats. White-space opportunity concentrates in Chinese pre-mixed cartridge imports where NMPA pharmacovigilance infrastructure gaps delay incumbent registration timelines. Go-to-market angle should leverage contract manufacturing partnerships with established European API suppliers to bypass thiophene synthesis barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty chemical API suppliers possessing captive thiophene precursor capacity and EMA compliance infrastructure. Long-term viability hinges on biodegradability standard evolution for single-use dental cartridges. Acquisition target archetype: mid-scale European formulators with undervalued combination product regulatory dossiers. Signal to watch is FDA cardiovascular safety warning expansion to additional amide anesthetics, which would accelerate articaine formulary substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thiophene Precursors | Captive supply of German-sourced API precursors insulates margin from specialty chemical price volatility. |
| EMA Combination Product Certification | Dual device-anesthetic clearance under EU MDR creates compliance moats against Asian contract manufacturers. |
| GPO Contracting with ASC Networks | Long-term supply agreements with United States ambulatory surgical centers concentrate volume and reduce churn. |
| Pre-Mixed Cartridge Format Launch | Integrated aspiration detection systems capture premium positioning against conventional vial-and-syringe compounding. |
| Biodegradable Cartridge Development | Compostable injection systems align with evolving EU single-use plastic regulations and open sustainability premiums. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dental supply procurement managers, GPO contract administrators, EMA regulatory affairs specialists, and pharmaceutical formulation scientists with secondary validation against FDA 510(k) filings, EMA marketing authorization databases, German dental reimbursement schedules, and customs trade records for thiophene derivative imports. Bottom-up demand modeling from clinic procedure volumes and top-down supply assessment from API manufacturing capacity were triangulated against distributor shipment data.
Segment-weighting applied differential growth assumptions across product type, application, end user, and delivery mode dimensions over the projection horizon. Injectable formulations carried higher base-period weighting reflecting established mandibular block penetration, while dental solutions received accelerated growth coefficients based on ambulatory surgical center adoption curves. CAGRs were derived from regression analysis of historical pricing and volume trajectories, incorporating FDA cardiovascular safety warning impacts and EMA pharmacovigilance cost pass-through effects as industry-specific modifiers.
Underlying measurement precision varies by segment; dental clinic procurement data carries tighter precision than hospital pharmacy inventory estimates. Forecasts reflect assumptions about outpatient oral surgery migration rates, reimbursement code stability for articaine versus prilocaine, and notified body capacity constraints under EU MDR. Deviation in FDA cardiovascular safety warning scope or thiophene precursor supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Hepatitis B Treatment Market
Pharmaceuticals
Bisphosphonates Market
Pharmaceuticals
Global Thyroid Cancer Drugs Market
Pharmaceuticals
Systemic Antibiotics Market
Pharmaceuticals
Pharmaceutical Water Market
Pharmaceuticals
Specialty Active Pharmaceutical Ingredients Market
Pharmaceuticals
HPV Vaccines Market
Pharmaceuticals
Oncology Adjuvants Market
Pharmaceuticals
Drug-Induced Dyskinesia Market
Pharmaceuticals
Global Cytotoxic Drugs Market
Pharmaceuticals
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market
Pharmaceuticals
Middle-East and Africa Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Pentoxyverine Market
Pharmaceuticals
Middle East and Africa Adenomyosis Drugs Market
Pharmaceuticals
Asia-Pacific Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Hard Empty HPMC Capsule Market