
 Crawler Crane Market | 2026-2036
Crawler Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Crawler Crane Market Intelligence
Market Context
China's crawler crane manufacturing base is fragmenting as domestic overcapacity meets export push into Southeast Asia and the Middle East. Liebherr sustains its premium positioning through in-house component production and European assembly footprint. Zoomlion competes aggressively on cost-engineered lattice boom models while building African and Latin American dealer networks. Sany anchors its volume leadership in the domestic Chinese infrastructure segment with telescopic boom variants for urban rail projects.
Technical Definition and Segment Structure
A crawler crane is a self-propelled lifting machine mounted on tracked undercarriage, utilizing diesel, electric, or hybrid power to deliver rated capacities from 50 to over 3,000 metric tons through lattice or telescopic boom configurations. The tracked chassis distributes ground pressure below 2 kg per square centimeter, enabling operation on unprepared terrain where rubber-tired cranes cannot deploy. Lattice boom crawler cranes dominate heavy-lift applications in wind energy and shipbuilding where maximum reach-to-weight ratios command premium pricing. Hydraulic crawler cranes with telescopic booms capture the fastest growth in urban infrastructure and demolition where rapid setup cycles reduce site downtime. Electric motor and hybrid power technologies are gaining structural share as European construction contractors face tightening carbon accounting under CSRD scope requirements.
Regulatory Environment and Outlook
The EU F-Gas Regulation and Stage V emission standards from the European Commission constrain diesel-powered crawler crane deployment in member states, while China's MEE enforces national emission zones in Beijing-Tianjin-Hebei and Yangtze River Delta clusters. OSHA crane operator certification mandates in the United States extend equipment inspection cycles and elevate training costs for construction contractors. Stakeholders must monitor how battery energy density advances and carbon border adjustment mechanisms reshape total cost of ownership calculations across competing powertrain technologies.
Market Dynamics
Powertrain electrification is fragmenting crawler crane manufacturing economics as battery density improvements and emission zone enforcement split fleet procurement strategies between diesel, hybrid, and full-electric configurations.
Growth Catalysts
- EU F-Gas Regulation:Stage V emission mandates in Germany and France are forcing construction contractors to retire legacy diesel fleets ahead of schedule, opening replacement demand for electric and hybrid crawler cranes.
- Offshore wind installation:Turbine nacelle weights exceeding 15 metric tons require lattice boom crawler cranes with 1,000+ ton capacity, concentrating orders among specialized heavy-lift contractors in Denmark and the United Kingdom.
- China's MIIT emission standards:National emission zones in Beijing-Tianjin-Hebei and Yangtze River Delta clusters are accelerating domestic manufacturer transitions to electric powertrains for urban rail projects.
Market Restraints
- High-voltage battery cost volatility:Lithium-ion cell prices and nickel supply concentration in Indonesia create margin pressure for electric crawler crane producers targeting price-sensitive municipal buyers.
- Lattice boom supply concentration:Specialized high-strength steel for 100+ meter booms sources from a limited German and Japanese supplier base, creating lead time risk for heavy-lift crane assembly.
- OSHA certification friction:Extended operator training cycles and inspection mandates elevate total cost of ownership for US construction contractors managing mixed diesel-electric fleets.
Strategic Opportunities
- Southeast Asia port modernization:Vietnam and Indonesia lack domestic crawler crane manufacturing, creating import demand for cost-engineered telescopic boom models from Chinese producers building regional dealer networks.
- CSRD carbon accounting:European corporate sustainability reporting requirements are elevating electric crawler crane preference among contractors bidding for public infrastructure tenders in France and the Netherlands.
- Battery-swapping infrastructure:Convergence of modular battery packs and automated swap stations is digitizing fleet uptime management for urban demolition contractors in Tokyo and Singapore.
Industry Challenges
- Certified technician scarcity:High-voltage powertrain maintenance requires electricians with combined mechanical-hydraulic expertise, a skill set concentrated among German and Japanese service networks.
- Telescopic boom integration complexity:Multi-section hydraulic extension systems for electric crawler cranes demand synchronized control software validation, extending product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crawler Crane Market |
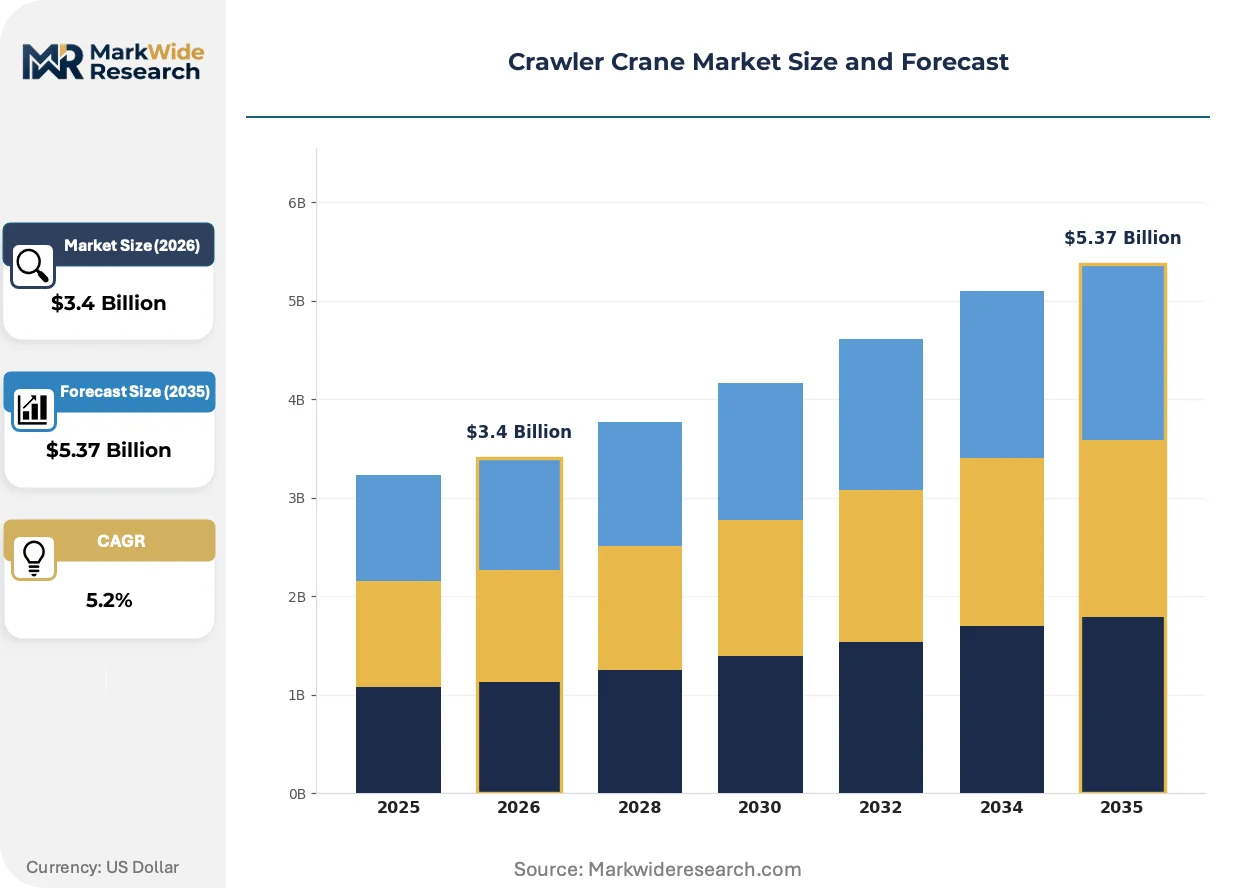
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.37 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Crawler Crane, Lattice Boom Crawler Crane, Telescopic Boom Crawler Crane, Rough Terrain Crawler Crane Technology: Diesel Engine, Electric Motor, Hybrid Power, Remote Control Systems, GPS-Enabled Guidance Application: Infrastructure Projects, Heavy Construction, Shipbuilding, Wind Energy, Mining Operations, Demolition End User: Construction Contractors, Mining Companies, Energy Suppliers, Port Operators, Steel Manufacturers |
| Companies Covered | Liebherr, Zoomlion, Sany, Mammoet, Kobelco, XCMG, Manitowoc Cranes, Sarens, Demag, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crawler Crane Market Strategic Shifts & Innovations
Telematics and predictive maintenance systems are compressing crawler crane ownership economics by shifting fleet management from scheduled downtime to condition-based intervention models.
Load moment indicator systems integrated with real-time boom stress sensors and GPS positioning are digitizing site safety protocols for wind energy contractors in Germany and Denmark. These systems reduce insurance premiums and accelerate project certification timelines. Manufacturers embedding this technology capture preference among risk-averse European infrastructure funds.
China's MEE national emission zones and the EU Green Deal machinery directives are converging to accelerate hybrid powertrain adoption across overlapping export markets. Dual-engine configurations allowing electric-only operation in urban cores while retaining diesel range extension satisfy both regulatory frameworks. German and Chinese manufacturers are prioritizing this architecture for port and rail applications.
Rental fleet operators are unbundling maintenance contracts from equipment leases, creating standalone service revenue streams. This model displaces traditional bundled financing in the United States where contractor balance sheet constraints favor operating expense treatment. Independent service providers in Texas and California are capturing this margin by specializing in high-tonnage crawler crane refurbishment.
Crawler Crane Market Segmentation

Crawler crane procurement decisions split sharply between boom configuration requirements and powertrain compliance obligations. Fleet managers weight ground pressure specifications against emission zone access, while project scale dictates capacity tier selection across overlapping regulatory jurisdictions.
Product Type:
Mature lattice boom designs anchor heavy-lift applications; telescopic variants are gaining share in urban infrastructure cycles.
- Hydraulic Crawler Crane:Multi-section telescopic booms deploy hydraulic cylinder extension for rapid setup without auxiliary assembly equipment. Municipal contractors in Tokyo and Singapore specify these for rail station construction where site footprints constrain boom transport logistics.
- Lattice Boom Crawler Crane:Modular pinned-section booms assembled on-site deliver maximum reach-to-weight ratios exceeding 100 meters at 1,000+ metric ton capacity. Offshore wind installation fleets in Denmark and the United Kingdom concentrate orders here for nacelle lifts exceeding 15 metric tons.
- Telescopic Boom Crawler Crane:Single-unit transportability reduces mobilization costs for demolition contractors facing compressed urban project timelines. German rental fleets are expanding this category fastest under CSRD carbon accounting pressure.
- Rough Terrain Crawler Crane:Reinforced undercarriage and wider track gauges distribute ground pressure below 1.5 kg per square centimeter for unprepared mining and quarry access roads in Australia and Chile.
Lattice boom crawler cranes retain volume leadership in heavy-lift contracting; telescopic boom configurations hold the steepest expansion curve in urban demolition and rail applications.
Technology:
Powertrain cost tiers are fragmenting procurement strategies between diesel legacy fleets and electrified replacements.
- Diesel Engine:Tier 4 Final and Stage V compliant powertrains dominate export markets lacking charging infrastructure. Indonesian port operators continue specifying these for archipelago logistics where grid reliability varies by island.
- Electric Motor:Battery-electric configurations eliminate local emissions for indoor shipyard work and urban emission zones. Norwegian shipbuilders in Bergen and Stavanger are retrofitting quay cranes with shore-power compatible electric crawler systems.
- Hybrid Power:Dual-engine architectures switch between electric-only urban operation and diesel range extension. Chinese manufacturers prioritize this configuration for Beijing-Tianjin-Hebei rail projects under MEE national emission zone enforcement.
- Remote Control Systems:Radio-frequency and tethered operator stations enable precision placement in hazardous demolition environments. French nuclear decommissioning contractors mandate these for radiation-exposed structural dismantling.
- GPS-Enabled Guidance:Real-time kinematic positioning integrates with load moment indicators for automated boom positioning. German wind energy contractors use these systems to reduce insurance premiums and accelerate project certification timelines.
Diesel powertrains retain installed base dominance; hybrid configurations are climbing the fastest as dual-market compliance architecture.
Application:
Customer type concentration varies by project duration and equipment utilization intensity.
- Infrastructure Projects:Urban rail, bridge, and highway construction demands rapid-setup telescopic booms with 50-300 ton capacity. Chinese state contractors deploy these in Yangtze River Delta clusters under MIIT emission compliance deadlines.
- Heavy Construction:Commercial and industrial building frameworks require versatile mid-capacity crawlers with interchangeable boom configurations. Brazilian petrochemical expansion projects in Rio de Janeiro state are driving import demand.
- Shipbuilding:Drydock hull assembly and block erection specify high-precision lattice booms with load moment indicator integration. South Korean yards in Ulsan and Geoje maintain dedicated crawler fleets for ultra-large container vessel construction.
- Wind Energy:Onshore turbine installation requires 600-1,500 ton capacity lattice booms for hub heights exceeding 150 meters. Polish and Romanian project developers are expanding fleets to meet EU renewable capacity targets.
- Mining Operations:Continuous-duty extraction and processing equipment maintenance demands ruggedized undercarriages with 24-hour operational ratings. Chilean copper operations in the Atacama specify these for altitude performance above 3,000 meters.
- Demolition:High-reach boom configurations with specialized attachments dismantle urban structures floor-by-floor. Japanese contractors in Osaka and Yokohama are piloting battery-swapping infrastructure for zero-emission demolition cycles.
Infrastructure projects retain volume leadership in unit shipments; wind energy applications are gaining share fastest on capacity expansion mandates.
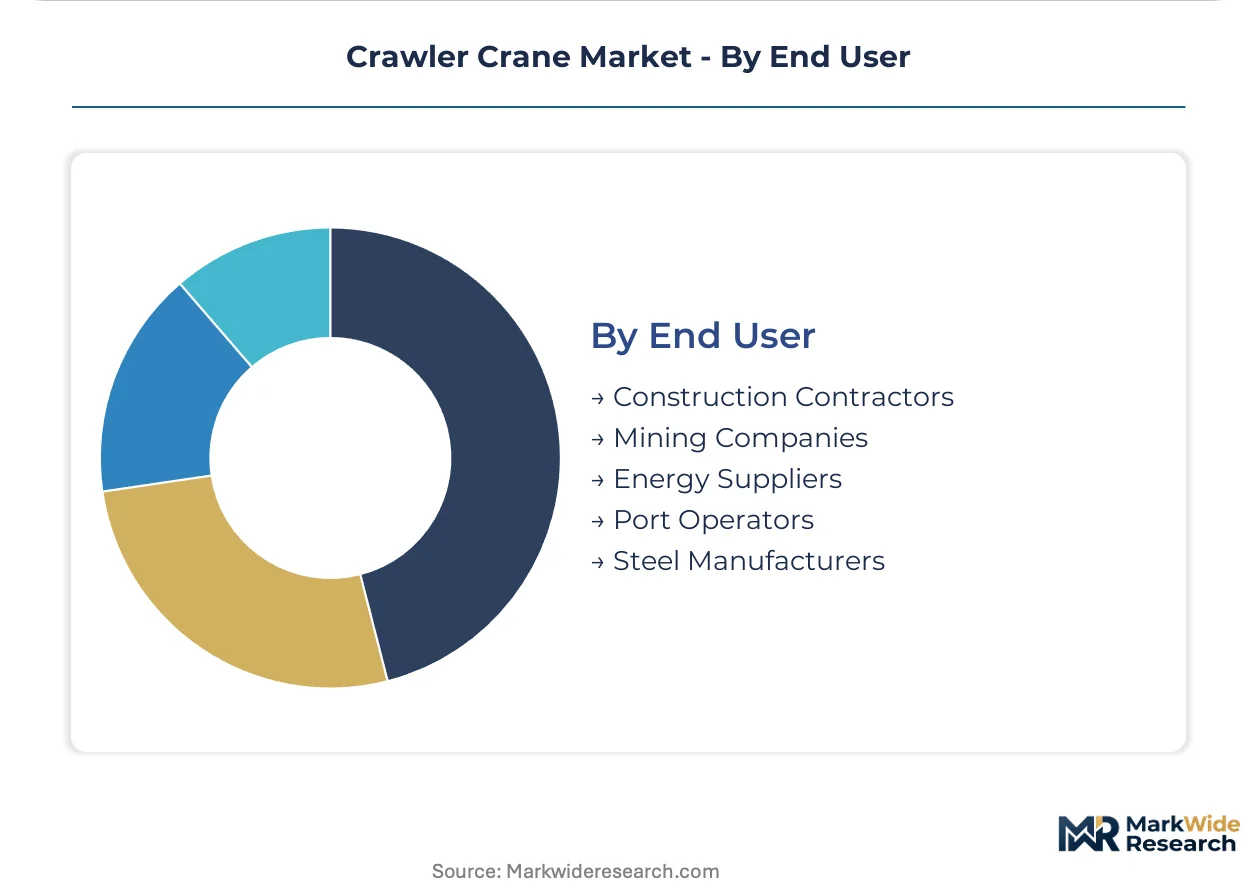
End User:
Procurement patterns diverge between rental fleet operators and captive equipment owners.
- Construction Contractors:General and specialized builders balance owned equipment against rental flexibility based on project pipeline visibility. German mid-cap contractors are consolidating toward hybrid fleet standards under EU Green Deal machinery directives.
- Mining Companies:Captive maintenance fleets prioritize uptime availability and parts commonality across remote sites. Australian iron ore operators in Western Australia specify standardized crawler configurations for Pilbara maintenance bases.
- Energy Suppliers:Utility-scale wind and solar developers contract heavy-lift services or maintain specialized installation subsidiaries. Danish offshore wind developers in Esbjerg anchor the European lattice boom order book.
- Port Operators:Container and bulk terminal maintenance requires versatile crawlers for crane refurbishment and infrastructure repair. Vietnamese port authorities in Hai Phong and Da Nang are importing Chinese telescopic models for terminal expansion.
- Steel Manufacturers:Blast furnace and rolling mill maintenance demands high-heat-resistant boom specifications and specialized rigging. Indian integrated steel producers in Odisha and Jharkhand are expanding crawler fleets under PLI scheme capacity additions.
Construction contractors retain broadest segment participation; energy suppliers are expanding procurement fastest on renewable installation targets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese manufacturers control the high-strength steel supply chain for lattice boom production, while Chinese fabricators dominate telescopic boom volume exports into Southeast Asian infrastructure markets.
United States
Port modernization along the Gulf Coast and Atlantic seaboard drives heavy-lift crawler demand for container crane refurbishment. OSHA certification mandates extend operator training cycles and elevate compliance costs for construction contractors. Houston and New Orleans anchor the domestic rental fleet concentration, with Texas-based independent service providers capturing maintenance contract unbundling opportunities.
Germany
Offshore wind installation fleets in the North Sea require 1,000+ ton capacity lattice booms for nacelle lifts exceeding 15 metric tons. EU F-Gas Regulation and Stage V emission standards force premature retirement of legacy diesel fleets. The Port of Hamburg and Bremerhaven industrial cluster concentrates specialized heavy-lift contractor activity under CSRD carbon accounting pressure.
China
Urban rail construction in Beijing-Tianjin-Hebei and Yangtze River Delta clusters consumes telescopic boom variants for compressed site timelines. MIIT emission standards and MEE national emission zones accelerate domestic manufacturer transitions to electric powertrains. Shanghai and Shenzhen infrastructure contractors deploy hybrid configurations for dual-mode urban and intercity operation.
Japan
Demolition contractors in Osaka and Yokohama pilot battery-swapping infrastructure for zero-emission high-reach dismantling cycles. METI industrial efficiency guidelines promote telematics integration for predictive maintenance. The Kanto region around Tokyo anchors domestic fleet modernization, with municipal rail projects specifying rapid-setup hydraulic crawlers.
Denmark
Offshore wind developers in Esbjerg anchor the European lattice boom order book for turbine hub heights exceeding 150 meters. EU Green Deal machinery directives elevate electric and hybrid powertrain preference among installation contractors. The Danish west coast industrial zone concentrates specialized heavy-lift capacity serving North Sea renewable energy expansion.
Crawler Crane Market Key Industry Players
Vertically integrated conglomerates and specialized heavy-lift contractors split the market between volume manufacturing and project-specific service provision. The vendor base concentrates among three strategic archetypes: European premium manufacturers with in-house component production, Chinese cost-engineered volume producers, and global heavy-lift service contractors operating captive fleets. Competitive positioning hinges on backward integration into high-strength steel sourcing and geographic footprint in emission-regulated markets. M&A activity targets regional dealer networks, while technology licensing agreements accelerate electric powertrain development.
Within the European premium tier, Liebherr exemplifies in-house production architecture and maintains assembly footprint advantages in regulated markets. Among Chinese volume producers, Zoomlion and Sany occupy positions on opposite ends of the domestic application spectrum, with the former building export dealer networks and the latter anchoring urban infrastructure segments. Mammoet represents the specialized heavy-lift contractor archetype, operating project-specific fleet configurations rather than manufacturing assets.
| Leading Market Players |
|---|
| Liebherr |
| Zoomlion |
| Sany |
| Mammoet |
| Kobelco |
| XCMG |
| Manitowoc Cranes |
| Sarens |
| Demag |
| Others |
Cost & Logistics Intelligence
German and Japanese high-strength steel suppliers for lattice boom fabrication concentrate upstream margin capture, forcing crane assemblers to absorb volatility through long-term offtake contracts or captive forging investments.
Pricing Analysis
EU Stage V emission standards dictate the pricing tier structure across diesel, hybrid, and full-electric configurations. Pricing stratifies across premium European in-house production, mid-tier Chinese export engineering, and economy-grade regional assembly based on certification grade and after-sales service bundling. Cost compression in electric powertrains is intensifying because lithium-ion cell supply concentrates in Indonesian nickel processing. Municipal contractors in emission-regulated zones exhibit lowest price sensitivity; Southeast Asian port operators show highest elasticity.
Supply Chain Analysis
Dual-use technology controls on high-tensile steel alloys and precision hydraulic components limit flows from German and Japanese suppliers to Chinese fabricators. Manufacturing draws from Germany for lattice boom forgings, China for telescopic boom stampings, and South Korea for precision hydraulic cylinders. Raw material dependencies center on nickel for battery cathodes, high-strength steel for boom sections, and rare-earth elements for electric motor magnets. Single-source vulnerability concentrates in 100+ meter boom steel from ThyssenKrupp and Nippon Steel. Distribution runs through manufacturer-direct sales for heavy-lift units and regional dealer networks for mid-capacity telescopic models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-swapping infrastructure and telematics platform interoperability are shifting crawler crane economics toward fleet-as-a-service models, rewarding operators who control uptime data and modular powertrain ecosystems.
For Market Incumbents: Build captive service network moats by acquiring independent refurbishment specialists in Texas and California maintenance corridors. Consolidate backward integration into high-strength steel sourcing through joint ventures with German forging houses. Battery cell cost volatility and Chinese manufacturer export expansion threaten margin stability. Certification investment in EU Stage V and China MIIT compliance creates switching costs for fleet operators.
For New Entrants and Emerging Players: Vietnamese and Indonesian port authorities lack domestic manufacturing, creating import demand for cost-engineered telescopic boom configurations. Target African mining maintenance bases where parts commonality scarcity elevates third-party service margins. Partner with Chinese battery-swapping infrastructure providers to bypass charging network capital intensity.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized heavy-lift service contractors with captive lattice boom fleets and long-term offshore wind installation contracts. The five-to-ten year viability window favors asset-light platform operators over capital-intensive manufacturing. Monitor battery energy density advances above 300 Wh per kilogram as the inflection signal for full-electric fleet economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Swapping Infrastructure Partnership | Tokyo and Singapore demolition contractors pilot automated swap stations for zero-emission uptime. |
| Backward Integration into High-Strength Steel | Liebherr's captive forging capacity insulates margin from ThyssenKrupp supply constraints. |
| Telematics Platform Integration | German wind energy contractors reduce insurance premiums through real-time boom stress monitoring. |
| Regional Dealer Network Expansion | Zoomlion builds African and Latin American distribution to capture Southeast Asian port demand. |
| Hybrid Powertrain Certification Investment | Dual-engine architectures satisfy both EU Green Deal and China MIIT emission frameworks. |
Research Approach
Two parallel data streams informed the analysis: primary engagement with equipment procurement directors, fleet maintenance managers, and port authority engineering leads; and secondary validation through customs trade records, SEC equipment manufacturer filings, and EU ETS carbon disclosure databases. Bottom-up unit shipment modeling triangulated against top-down infrastructure investment forecasts across wind energy, port modernization, and urban rail segments.
Forecast inputs incorporated powertrain transition curves, emission zone enforcement timelines, and battery cost trajectories across the projection horizon. Segmentation dimensions spanned boom configuration type, powertrain technology tier, application intensity, and end-user ownership structure. CAGRs derived from fitted adoption curves for electric and hybrid configurations against diesel baseline retirement patterns.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese manufacturers or breakthrough solid-state battery commercialization would shift outcomes. Material shifts in EU carbon border adjustment mechanisms or Indonesian nickel export restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Mechanical Seals Market
Material Handling Equipment
Dynamic Compactor Market
Material Handling Equipment
Hoist Chains Market
Material Handling Equipment
High-Pressure Die Casting Market
Material Handling Equipment
Bulk Material Handling System Market
Material Handling Equipment
Heavy Duty Ramp Market
Material Handling Equipment
Push-Back Racking System Market
Material Handling Equipment
Mobile Crane Market
Material Handling Equipment
Global Industrial Lifting Equipment Market
Material Handling Equipment
Cable Conduit Systems Market
Material Handling Equipment
Industrial Bag Dust Filter Market
Material Handling Equipment
Asia Pacific Automated Material Handling and Storage Systems Market
Material Handling Equipment
Vibratory Feeder Machine Market
Material Handling Equipment
Fluid Conveyance Systems Market
Material Handling Equipment
Hydraulic Hose and Fittings Market
Material Handling Equipment
Slow Speed Shredding Machines Market