
 Hydraulic Hose and Fittings Market | 2026-2036
Hydraulic Hose and Fittings Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Hose and Fittings Market Outlook
SAE 100R15 and ISO 18752 super-pressure specifications are bifurcating the competitive landscape into premium certified suppliers and commodity assemblers. Parker Hannifin Corp. leverages its captive elastomer compounding to control specification-grade availability across North American distribution. Alfagomma SpA anchors Mediterranean supply through vertically integrated rubber processing near its Bologna headquarters. Eaton Corp. Plc differentiates via integrated hydraulic system design, bundling hose assemblies with pump and valve portfolios for mining OEMs.
Hydraulic hose and fittings constitute reinforced elastomeric or thermoplastic conduits with crimped or threaded metallic terminations, engineered to transmit pressurized fluid at working pressures typically spanning 3,000 to 6,000 psi in mobile equipment applications. Rubber hoses dominate replacement volume due to established compatibility with petroleum-based hydraulic fluids across construction and agricultural machinery. Metal hoses capture premium positioning in oil and gas end uses where extreme temperature cycling and fire resistance command specification premiums. Crimped connection types are displacing threaded alternatives in OEM assembly lines, though field repair channels still favor reusable threaded fittings for downtime reduction.
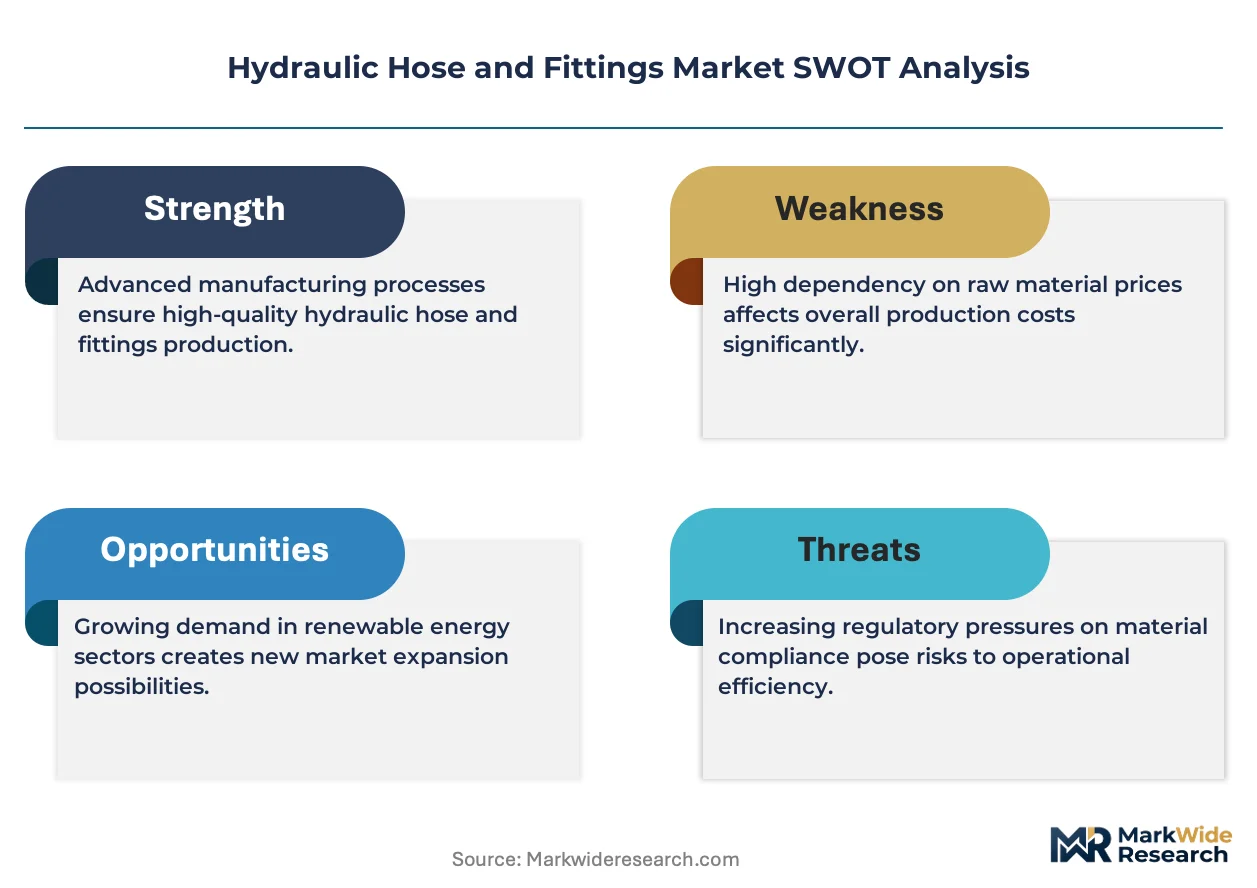
SAE J517 and ISO 1436 standards govern pressure rating classifications and impulse test protocols, compelling manufacturers to maintain accredited testing laboratories for OEM qualification. The EPA's spill prevention regulations for hydraulic fluid containment are tightening seal and coupling specifications in US marine and oilfield applications. Stakeholders must monitor evolving REACH restrictions on zinc-based corrosion inhibitors in European rubber compounds, as formulation shifts will ripple through supply chains and recertification timelines.
Market Dynamics
Tier IV emissions standards in North America and Europe are compressing engine compartment geometries, forcing hydraulic routing through tighter spaces and accelerating specification upgrades toward spiral-wire high-pressure constructions.
Growth Catalysts
- Infrastructure Stimulus Programs:Government capital allocation toward bridge rehabilitation and utility modernization in the United States and Germany is expanding construction equipment utilization rates and accelerating hose replacement cycles.
- REACH Phase-Down Schedules:ECHA restrictions on zinc-based corrosion inhibitors in rubber compounds are compelling formulation upgrades that favor certified suppliers with accredited testing laboratories.
- Spiral-Wire Technology Migration:OEMs are specifying SAE 100R15 constructions for compact excavators and wheel loaders operating above 5,000 psi working pressures.
Market Restraints
- Synthetic Rubber Feedstock Volatility:EPDM and nitrile compound costs fluctuate with petrochemical pricing, compressing margin predictability for assemblers without captive elastomer processing.
- Geographic Supply Concentration:Germany's industrial corridor and the US Midwest account for disproportionate certified hose assembly capacity, creating vulnerability to regional logistics disruptions.
- Thermoplastic Substitution Threat:Non-conductive thermoplastic hoses are capturing specification share in aerial lift and utility applications where weight reduction commands design priority.
Strategic Opportunities
- Indian Capital Goods Expansion:The country's PLI scheme for construction equipment manufacturing is attracting OEM assembly operations that require localized hose certification and inventory positioning.
- Marine Spill Prevention Mandates:EPA regulations for hydraulic fluid containment in US offshore and inland waterway applications are tightening seal specifications and favoring integrated coupling solutions.
- Digital Inventory Integration:Mining fleet operators in Western Australia are adopting vendor-managed inventory systems that shift procurement from spot replacement to contracted availability guarantees.
Industry Challenges
- Impulse Test Certification Bottlenecks:SAE J517 and ISO 1436 qualification timelines extend 18-24 months for new compound formulations, delaying product launches and locking out speculative R&D investments.
- Crimp Equipment Capital Intensity:Field service channels require portable crimping systems compatible with both spiral-wire and braided constructions, demanding tooling investments that smaller distributors struggle to justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Hose and Fittings Market |
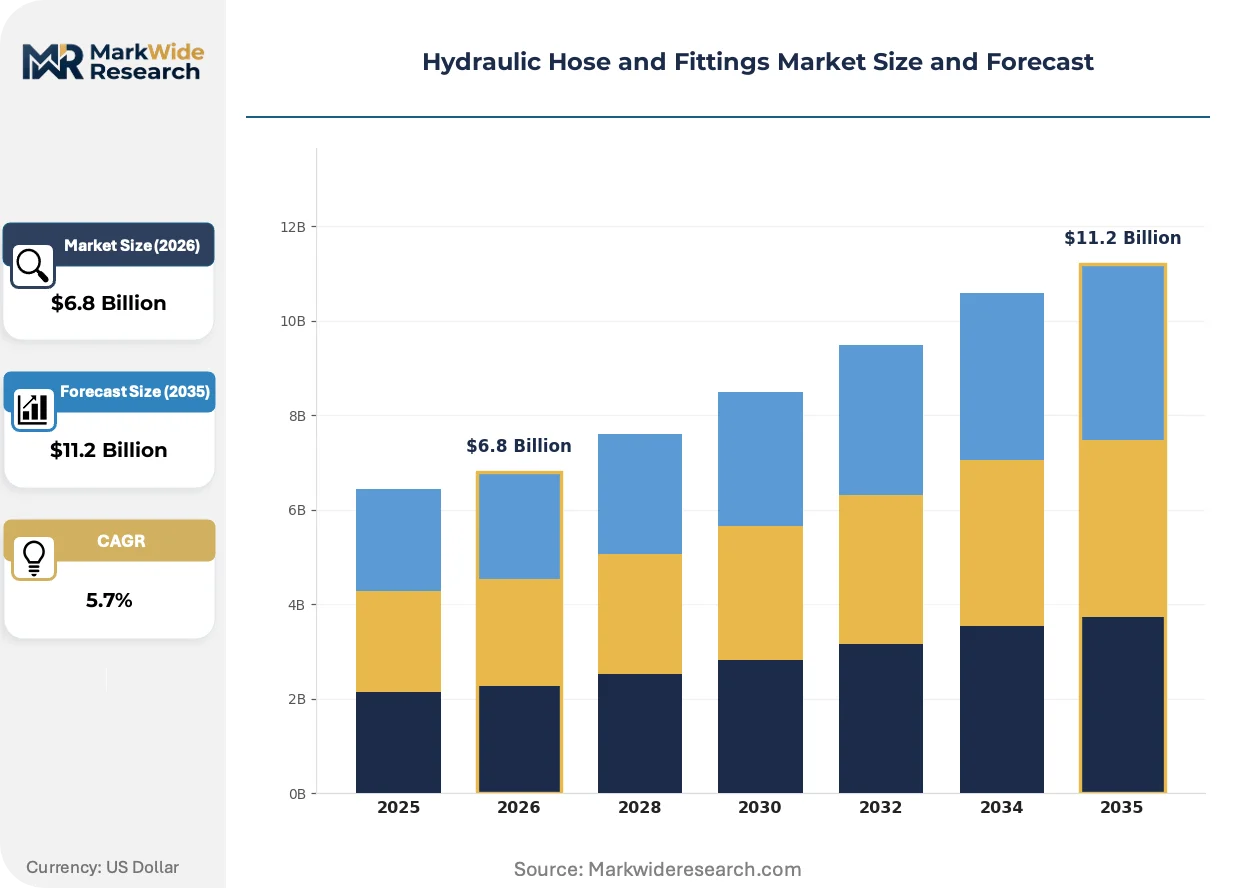
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Hoses, PVC Hoses, Fiber Hoses, Metal Hoses Application: Agricultural Machinery, Construction Equipment, Industrial Machinery, Marine Equipment End User: Manufacturing, Oil & Gas, Agriculture, Mining Connection Type: Threaded, Quick Disconnect, Flanged, Crimped |
| Companies Covered | Manuli Hydraulics Group, Brennan Industries Inc., Parker Hannifin Corp., Bridgestone Industrial, Kurt Manufacturing Co., Eaton Corp. Plc, Alfagomma SpA, Laike Hydraulics Co. Ltd., Gates Industrial Corp. plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Hose and Fittings Market Strategic Shifts
Material science advances and regulatory compression are converging to reshape product architectures, with specification-grade suppliers separating from commodity assemblers through accredited testing capabilities and compound control.
Wire-braid reinforcement configurations are miniaturizing as manufacturers deploy higher-tensile steel grades that maintain pressure ratings with reduced outer diameters. Compact excavator OEMs in Japan and Germany are adopting these constructions to resolve routing conflicts with aftertreatment hardware. The technology is miniaturizing hose envelope dimensions by 15-20% without degrading impulse life, enabling cleaner engine bay packaging.
EPA spill prevention regulations for hydraulic fluid containment are tightening coupling and seal specifications in US marine and oilfield applications. The rules mandate secondary containment provisions and quick-disconnect integrity testing that exceed historical SAE requirements. Offshore service contractors are responding by consolidating supplier bases toward vertically integrated manufacturers with in-house metallurgy and elastomer compounding.
Certification-driven procurement preferences are consolidating buyer-seller relationships around accredited testing documentation. Mining OEMs in Western Australia and construction fleet managers in Texas now require ISO 1436 test reports with each assembly lot, displacing spot-market sourcing. The shift favors suppliers with captive laboratory capacity and compresses price competition among uncertified assemblers.
Hydraulic Hose and Fittings Market Segmentation
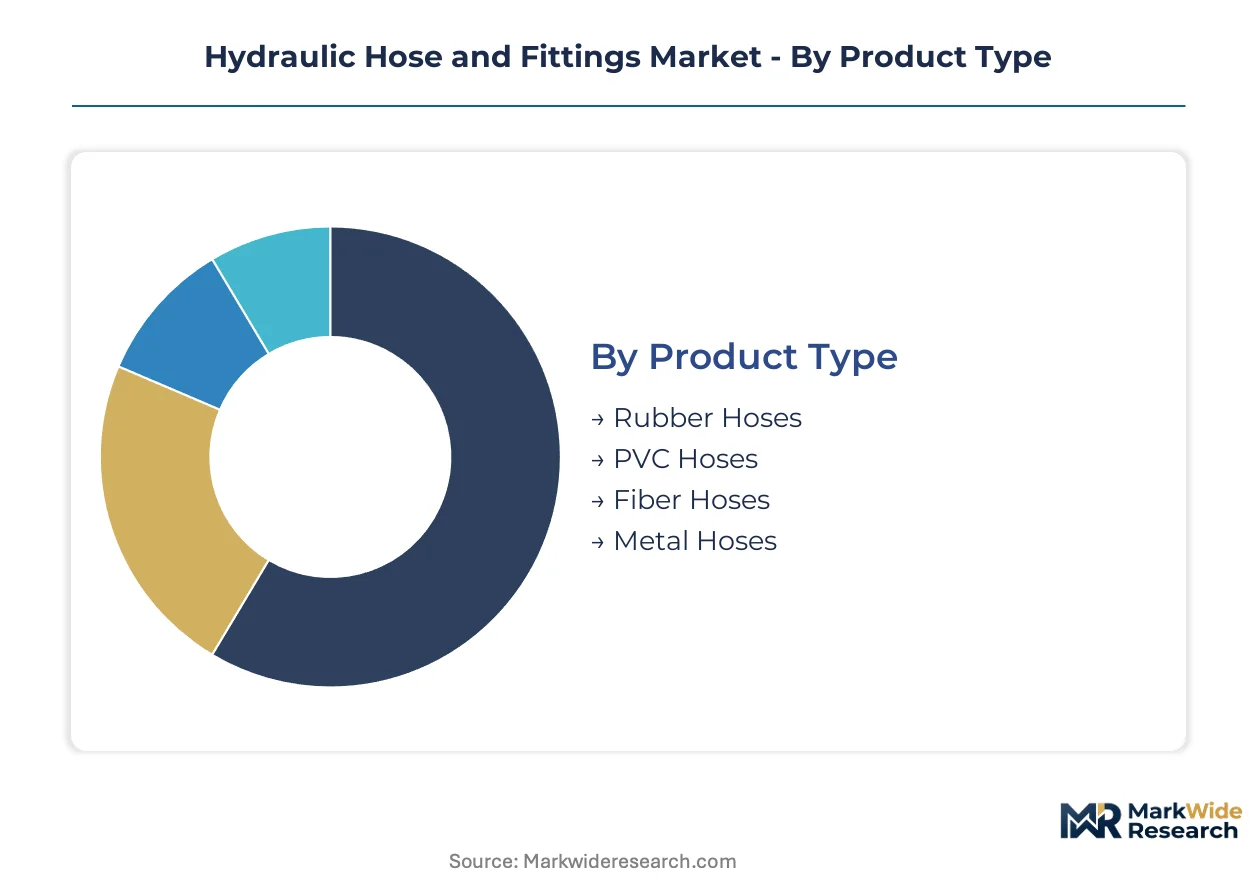
Segmentation in hydraulic hose and fittings reveals how specification complexity, fluid compatibility demands, and assembly methods fragment procurement across mobile equipment and stationary industrial systems. Understanding these divisions exposes where certified suppliers command premium positioning versus where commodity assemblers compete on availability and price.
Product Type:
Rubber hoses dominate domestic replacement channels across North American and European construction fleets, while metal hose exports concentrate in oil and gas applications serving Middle Eastern and Southeast Asian project sites.
- Rubber Hoses:Reinforced elastomeric constructions with steel-wire braid or spiral reinforcement, engineered for petroleum-based hydraulic fluid compatibility. Demand concentrates in German machine tool exports and US Midwest construction equipment rebuilds, where SAE J517 certification mandates lock in supplier relationships. Tier IV engine compartment compression is accelerating specification upgrades toward higher-pressure spiral-wire variants.
- Metal Hoses:Corrugated stainless steel or bronze constructions with welded or brazed end fittings, delivering fire resistance and extreme temperature cycling performance. Export-led demand centers on US Gulf Coast offshore platforms and Saudi Aramco processing facilities, where EPA spill prevention rules and API specifications enforce secondary containment requirements.
- PVC Hoses:Thermoplastic constructions for lower-pressure utility and agricultural applications where cost sensitivity outweighs impulse life requirements.
- Fiber Hoses:Synthetic textile-reinforced conduits for pneumatic and light hydraulic service in material handling and packaging machinery.
Rubber hoses command the established base. The steepest expansion runs through metal hoses.
Application:
Cost tier stratification separates specification-grade OEM assembly from aftermarket replacement, with construction equipment commanding the highest certification burden and agricultural machinery tolerating broader supplier qualification.
- Construction Equipment:Excavators, wheel loaders, and cranes operating above 5,000 psi working pressures with impulse cycling exceeding one million test cycles. OEM specification concentrates in Japan's compact excavator sector and Germany's mobile crane manufacturing, where SAE 100R15 constructions resolve routing conflicts with aftertreatment hardware. Infrastructure stimulus programs in the United States and Germany are accelerating replacement cycle frequency.
- Industrial Machinery:Machine tools, presses, and automated manufacturing systems requiring ISO 18752 super-pressure ratings and leak-free coupling integrity. Demand clusters in Germany's industrial corridor around Stuttgart and Dortmund, where export-oriented capital goods manufacturers require lot-traceable hose assemblies with accredited test documentation.
- Agricultural Machinery:Tractors and harvesters with moderate pressure requirements and seasonal utilization patterns favoring price-competitive braided constructions and field-repairable threaded fittings.
- Marine Equipment:Offshore support vessels and inland waterway barges subject to EPA spill prevention mandates tightening seal specifications and quick-disconnect integrity testing beyond historical SAE requirements.
Construction equipment absorbs the premium tier. Agricultural machinery captures volume scale.
End User:
Customer type differentiation separates integrated system buyers seeking bundled hydraulic portfolios from component purchasers optimizing spot replacement costs and inventory turns.
- Mining:Surface and underground operations with continuous equipment utilization demanding vendor-managed inventory systems and contracted availability guarantees. Western Australian iron ore operators and Chilean copper mines are consolidating supplier bases toward vertically integrated manufacturers with captive elastomer compounding and in-house metallurgy.
- Oil & Gas:Upstream drilling and downstream refining applications with fire resistance and sour gas compatibility requirements. US Permian Basin operators and Saudi processing facilities specify metal hose assemblies with API certification and secondary containment provisions.
- Manufacturing:Automotive stamping, plastic injection molding, and general industrial automation requiring consistent lead times and ISO 1436 documentation for each assembly lot.
- Agriculture:Seasonal equipment operators with dispersed geographic footprints favoring distributor networks carrying braided rubber hoses and portable crimping systems for field repair.
Mining leads system integration. Manufacturing drives standardization.
Connection Type:
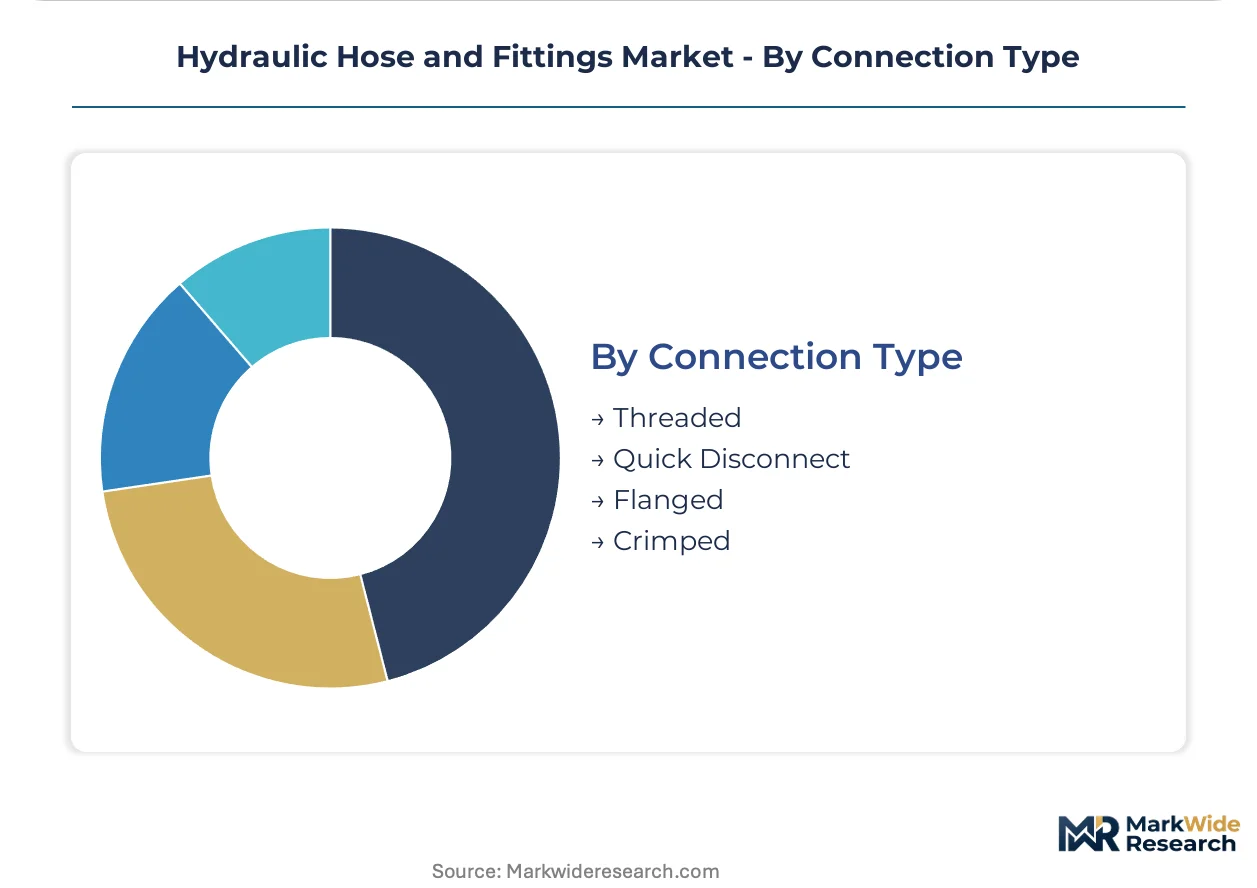
Assembly method maturity reflects the tension between OEM line-speed efficiency and field service flexibility, with crimped connections displacing threaded alternatives in factory assembly while reusable fittings persist in remote maintenance channels.
- Crimped:Permanent metallic terminations formed via hydraulic compression equipment, delivering consistent assembly quality and leak resistance for high-pressure spiral-wire constructions. OEM adoption concentrates in Japanese compact excavator plants and German wheel loader assembly lines, where production throughput demands automated crimping stations with statistical process control.
- Threaded:Reusable metallic fittings with tapered or parallel threads permitting field disassembly and reassembly without specialized tooling. Construction fleet operators in Texas and mining contractors in Western Australia maintain threaded fitting inventories for downtime reduction in remote locations where portable crimp equipment capital intensity strains smaller distributors.
- Quick Disconnect:Push-to-connect couplings with self-sealing valve mechanisms for hydraulic attachment swapping in multi-implement agricultural and utility applications.
- Flanged:Bolted connections for large-bore high-flow industrial and marine systems where assembly torque monitoring ensures joint integrity.
Threaded connections retain the installed base. Crimped terminations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German machine tool builders export certified hose assemblies to capital goods markets across Asia and the Americas, while US Gulf Coast metal hose fabricators supply fire-resistant constructions to Saudi Aramco and Permian Basin operators.
United States
Infrastructure stimulus programs are accelerating construction equipment utilization rates and hose replacement cycles across Texas and the Midwest. EPA spill prevention regulations for hydraulic fluid containment tighten coupling specifications in marine and oilfield applications. Houston anchors metal hose fabrication for offshore platforms, while Chicago-area distributors serve agricultural machinery rebuilds with braided rubber constructions.
Germany
Export-oriented capital goods manufacturers in Stuttgart and Dortmund require lot-traceable hose assemblies with ISO 1436 accredited test documentation. ECHA restrictions on zinc-based corrosion inhibitors compel formulation upgrades favoring certified suppliers with captive laboratory capacity. The industrial corridor around Bologna supplies Mediterranean markets through vertically integrated rubber processing operations.
Japan
Compact excavator OEMs specify SAE 100R15 spiral-wire constructions to resolve routing conflicts with Tier IV aftertreatment hardware. METI industrial standards govern pressure rating classifications for domestic mobile equipment. Nagoya-area assembly plants deploy automated crimping stations with statistical process control for high-throughput production lines.
India
The PLI scheme for construction equipment manufacturing attracts OEM assembly operations requiring localized hose certification and inventory positioning. BIS standards increasingly reference ISO 1436 test protocols for imported assemblies. Maharashtra-based fabricators are building accredited testing laboratories to serve mining fleet operators in Western Australia through vendor-managed inventory contracts.
Saudi Arabia
Aramco processing facilities specify metal hose assemblies with API certification and secondary containment provisions for sour gas compatibility. SFDA-equivalent industrial regulators enforce fire resistance standards exceeding historical SAE requirements. Eastern Province project sites consolidate supplier bases toward vertically integrated manufacturers with in-house metallurgy capabilities.
Hydraulic Hose and Fittings Market Competitive Environment
Listed leaders compete with private specialists across certification-grade availability and captive compound control. The vendor base separates into three tiers: multinational diversified industrials with accredited testing laboratories, regional specialists with backward integration into elastomer processing, and commodity assemblers competing on spot-market pricing and distributor availability. Strategic moves concentrate on M&A to secure compound formulation expertise and geographic expansion to position inventory near OEM assembly operations.
Among diversified industrial conglomerates, Parker Hannifin Corp. and Eaton Corp. Plc occupy positions defined by integrated hydraulic system bundling and captive elastomer compounding. Alfagomma SpA anchors Mediterranean supply through its Bologna headquarters proximity to rubber processing infrastructure. These three exemplify how specification-grade suppliers separate from commodity competitors through accredited laboratory capacity and control over critical raw material formulations.
| Leading Market Players |
|---|
| Manuli Hydraulics Group |
| Brennan Industries Inc. |
| Parker Hannifin Corp. |
| Bridgestone Industrial |
| Kurt Manufacturing Co. |
| Eaton Corp. Plc |
| Alfagomma SpA |
| Laike Hydraulics Co. Ltd. |
| Gates Industrial Corp. plc |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at accredited testing laboratories in Germany and the US Midwest shapes both supply concentration and price floors for specification-grade assemblies. Compound formulation control and captive elastomer processing create tiered cost structures that commodity assemblers cannot match.
Pricing Analysis
SAE 100R15 spiral-wire constructions command 40-60% premiums over wire-braid alternatives due to impulse test certification requirements and tighter engine compartment routing demands. Pricing stratifies across premium specification-grade, standard certified, and economy non-certified tiers. Cost compression in commodity braided constructions is intensifying because EPDM and nitrile feedstock volatility squeezes margin predictability for assemblers without captive rubber processing. Construction fleet operators exhibit highest price sensitivity, while mining OEMs prioritize lot-traceable documentation over unit cost.
Supply Chain Analysis
Strategic stockpiling of zinc-free rubber compounds dominates procurement behavior as ECHA phase-down schedules compress formulation transition timelines. Supply concentrates in Germany's industrial corridor, the US Midwest, and Japan's Nagoya manufacturing belt. Production draws from EPDM and nitrile elastomer feedstocks, high-tensile steel wire reinforcement, and specialized crimping metallurgy. Single-source vulnerability runs through accredited laboratory capacity for ISO 1436 and SAE J517 certification. Distribution runs through OEM direct contracts for specification-grade assemblies and distributor networks for aftermarket replacement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vendor-managed inventory contracts and field service bundling represent faster-expanding recurring revenue layers than hardware unit sales alone. Aftermarket service attach rates now determine supplier profitability more than initial assembly placement.
For Market Incumbents: Shield specification-grade positioning by accelerating captive laboratory capacity additions in India and Western Australia before PLI scheme localization matures. Consolidate supplier relationships with mining fleet operators through contracted availability guarantees that thermoplastic substitution threats cannot match. Prioritize zinc-free compound formulation R&D to stay ahead of REACH restriction enforcement timelines. For New Entrants and Emerging Players: Anchor in Maharashtra-based accredited testing infrastructure to serve Indian OEM assembly operations requiring BIS-compliant ISO 1436 documentation. Target agricultural machinery aftermarket channels where price-competitive braided constructions and portable crimping system distribution face lower certification barriers. Pursue quick-disconnect coupling specialization for utility aerial lift applications where weight reduction commands design priority. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated manufacturers with backward integration into elastomer compounding and in-house metallurgy capabilities. Long-term viability rests on compound control and certification capacity rather than distributor footprint scale. Acquisition candidates should demonstrate captive laboratory infrastructure and established OEM qualification relationships. Watch for thermoplastic hose specification share crossing critical thresholds in aerial lift and utility segments as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Accredited Laboratory Expansion | ISO 1436 certification capacity in India and Australia secures mining OEM vendor-managed inventory contracts. |
| Zinc-Free Compound Transition | ECHA REACH compliance eliminates regulatory recertification risk for European rubber hose exports. |
| Crimp Equipment Channel Partnership | Portable crimping system distribution captures construction fleet field repair aftermarket share. |
| Spiral-Wire Capacity Addition | SAE 100R15 production lines serve Japanese compact excavator OEM Tier IV routing requirements. |
| Digital Inventory Integration | Real-time availability guarantees displace spot-market sourcing for Western Australian iron ore operators. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SAE J517 standard documentation, EPA spill prevention rulemaking records, and ECHA REACH restriction schedules. Primary interviews engaged maintenance directors at construction equipment fleets, OEM procurement teams at Japanese compact excavator manufacturers, aftermarket service heads at mining operations, and technical R&D directors at rubber compound suppliers. Secondary validation drew from customs trade data, SEC 10-K filings of listed industrial conglomerates, and ISO 1436 test protocol documentation. Bottom-up assembly volume estimates triangulate against top-down equipment fleet utilization models.
Segmentation dimensions modeled include hose construction type, pressure rating classification, connection method, end-use equipment category, and geographic regulatory cluster. CAGRs derive from equipment fleet replacement cycle analysis, infrastructure stimulus program allocation tracking, and OEM specification migration patterns across the analysis window. Forecast inputs incorporate Tier IV emissions standard implementation timelines, PLI scheme localization incentives, and thermoplastic substitution elasticity estimates.
Decision-makers should treat outputs as directional under assumptions of sustained infrastructure stimulus allocation and stable petrochemical feedstock pricing; material deviation would warrant model refresh. Revision becomes warranted when thermoplastic hose specification share crosses critical thresholds or when REACH restriction enforcement accelerates compound reformulation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Portable Loading Ramps Market
Material Handling Equipment
Global Mechanical Seals Market
Material Handling Equipment
Global Lifting Columns Market
Material Handling Equipment
Global Precision Gearboxes Market
Material Handling Equipment
Rotating Fork Clamp Market
Material Handling Equipment
Europe Port Equipment Market
Material Handling Equipment
Pipelayer Market
Material Handling Equipment
Bale Clamp Intensive Market
Material Handling Equipment
Drive-In Pallet Racking Market
Material Handling Equipment
India Automated Material Handling (AMH) Market
Material Handling Equipment
Autonomous Warehouse Equipment Market
Material Handling Equipment
Material Handling Integration Market
Material Handling Equipment
Australia Forklift Rental Market
Material Handling Equipment
North America Industrial Duct for Dust Collection Market
Material Handling Equipment
Rubber Tired Gantry (RTG) Crane Market
Material Handling Equipment
Compaction Machines Market