
 High-Pressure Die Casting Market | 2026-2036
High-Pressure Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
High-Pressure Die Casting Market Outlook
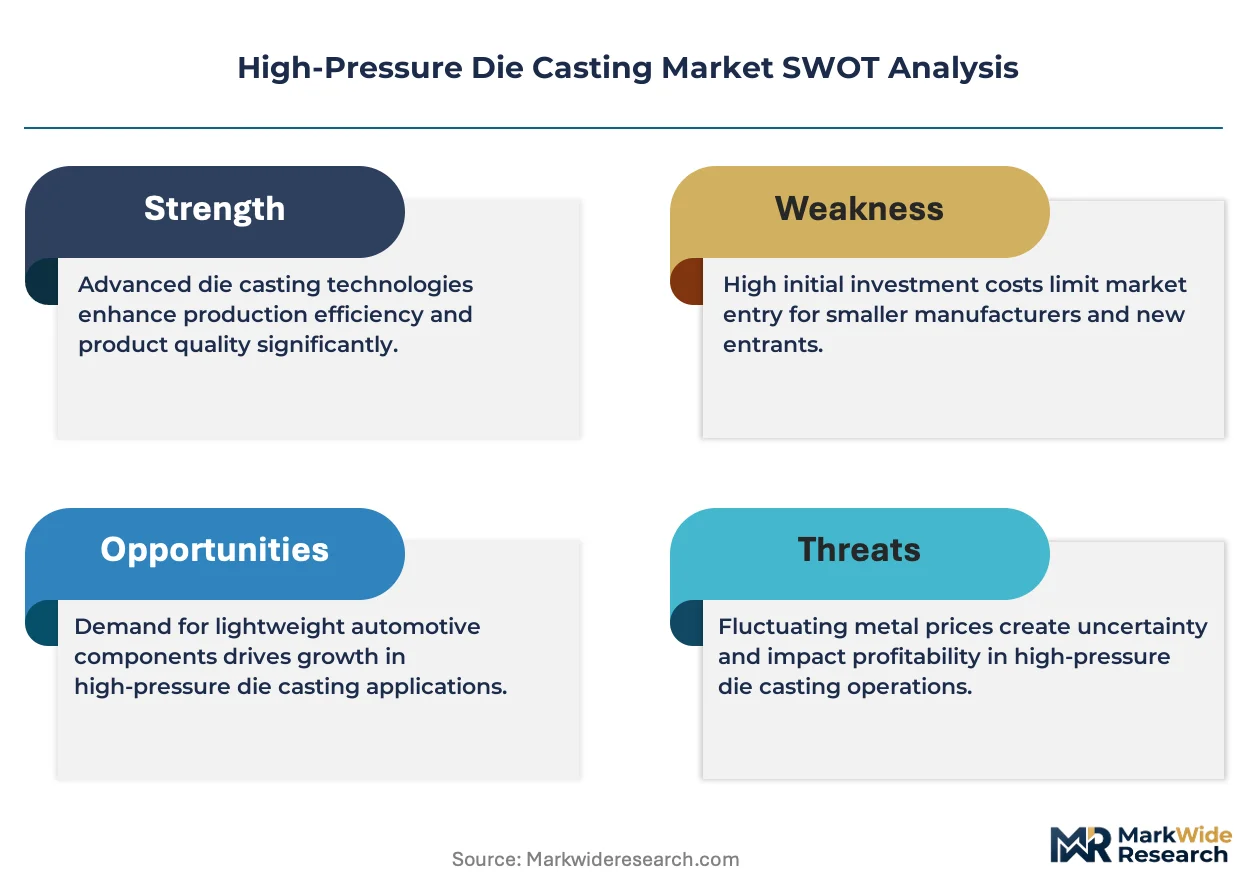
Structural-grade aluminum casting specifications is bifurcating the competitive landscape between premium automotive suppliers and volume producers. GF Casting Solutions AG leverages its European foundry network to anchor structural battery housing contracts for electric vehicle platforms. Rheinmetall AG dominates defense and commercial powertrain casting through captive metallurgy R&D in Germany. Endurance Technologies specializes in thin-walled transmission cases from its India-based manufacturing footprint.
High-pressure die casting injects molten metal into hardened steel dies at pressures exceeding 1,000 bar, producing near-net-shape components with wall thickness below two millimeters for weight-critical applications. Aluminum castings lead product type demand due to strength-to-weight ratios mandated by automotive electrification programs. Vacuum die casting technology captures margin pools in aerospace and premium automotive segments by eliminating porosity in safety-critical brake and steering components. Cold chamber equipment anchors volume production for large automotive structural parts, while hot chamber systems sustain zinc and magnesium output for electronics enclosures and precision hardware.
EPA fuel economy standards and NHTSA safety regulations in the United States compel automakers to adopt lighter die-cast subframes, while REACH compliance in Europe restricts certain alloy additives and shapes material sourcing. China's SAMR enforces GB standards for automotive component integrity that affect export qualification requirements. Stakeholders must monitor evolving EU Green Deal carbon border adjustments and their interaction with domestic scrap aluminum recycling infrastructure to secure qualified metal supply.
Market Dynamics
Automotive electrification programs are compressing design cycles for structural aluminum components while tightening porosity tolerances for battery housing integrity. Tier-1 suppliers must retool cold chamber lines for larger part envelopes or cede platform contracts to integrated foundry operators.
Growth Catalysts
- EU automotive CO2 fleet standards:German OEMs mandate aluminum subframes to meet 2025 fleet averages, pulling structural casting capacity toward Stuttgart and Munich supplier corridors.
- China MIIT dual carbon goals:Domestic EV platforms specify recycled-content aluminum housings, qualifying local foundries for national new energy vehicle subsidies.
- Vacuum die casting technology:Aerospace brake manufacturers specify porosity-free microstructures for safety-critical landing gear, capturing margin premiums unavailable to conventional gravity casting.
Market Restraints
- Scrap aluminum supply concentration:Qualified secondary alloy streams cluster in German and Chinese recycling infrastructure, exposing non-integrated foundries to feedstock disruption.
- REACH additive restrictions:ECHA scrutiny of certain copper and magnesium alloying elements forces reformulation of legacy transmission housing specifications.
- Tooling lead times:Hardened steel die production spans 16-24 weeks at specialized European and Japanese machine shops, gating capacity expansion.
Strategic Opportunities
- India commercial vehicle electrification:Thin-walled motor housings for electric buses remain underpenetrated by organized foundries, creating white space for cold chamber specialists.
- GB standards alignment:China's SAMR automotive component integrity rules open export qualification pathways for compliant suppliers serving EU battery platform demand.
- Digital twin convergence:Real-time porosity prediction from in-mold sensor arrays enables first-shot qualification, compressing prototyping cycles for structural part programs.
Industry Challenges
- Process technician scarcity:Vacuum die casting and real-time quality control systems require metallurgists trained in both foundry physics and data analytics, a skill intersection concentrated at German technical universities.
- Platform requalification timelines:OEM structural part certification spans 18-24 months, locking supplier capacity before volume ramps and straining working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Pressure Die Casting Market |
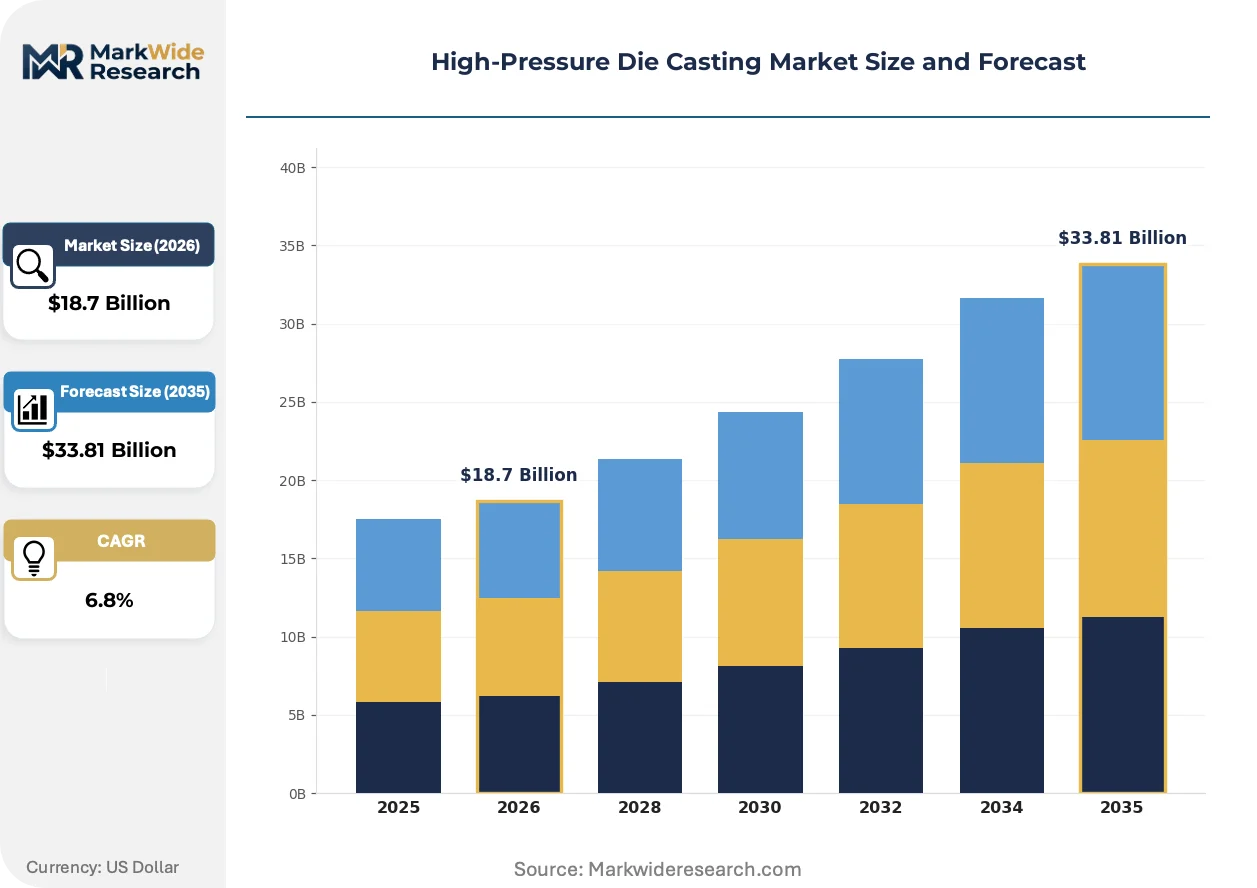
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Zinc, Magnesium, Copper End User: Aerospace, Automotive, Electronics, Industrial Form: Complex Shapes, Thin-Walled Parts, Large Components, Precision Parts Technology: Cold Chamber, Hot Chamber, Semi-Solid, Vacuum Die Casting |
| Companies Covered | Nemak SAB De CV, GF Casting Solutions AG, Ryobi Die Casting, Rheinmetall AG, Shiloh Industries, Dynacast, Bühler AG, Idra Group, Endurance Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Pressure Die Casting Market Strategic Shifts
Process digitization and material traceability requirements are restructuring competitive advantage around data-capture capabilities rather than tonnage throughput alone. Foundries must now integrate sensor infrastructure and alloy provenance documentation to retain tier-1 supplier status.
Real-time X-ray computed tomography is supplanting destructive sectioning for porosity validation in safety-critical brake caliper production. German premium automotive suppliers deploy inline CT scanning at 100% inspection rates, eliminating batch release delays. This technology compression collapses the traditional separation between foundry floor and quality laboratory, forcing capital retooling decisions.
REACH compliance deadlines for restricted substance thresholds are accelerating substitution of certain alloying additives in European-sourced aluminum grades. Foundry operators reformulate melt chemistries to maintain mechanical properties while satisfying ECHA registration requirements. Battery housing contracts specify full material pedigree documentation, making compliance a gatekeeper for platform qualification.
Consolidated procurement of structural aluminum castings by EV platform architects is displacing fragmented sourcing from individual component engineers. German and Chinese OEMs now mandate single-supplier responsibility for entire battery tray assemblies, compressing vendor lists. Tier-1 foundries respond by acquiring machining and assembly capabilities to capture value previously distributed across multiple tiers.
High-Pressure Die Casting Market Segmentation
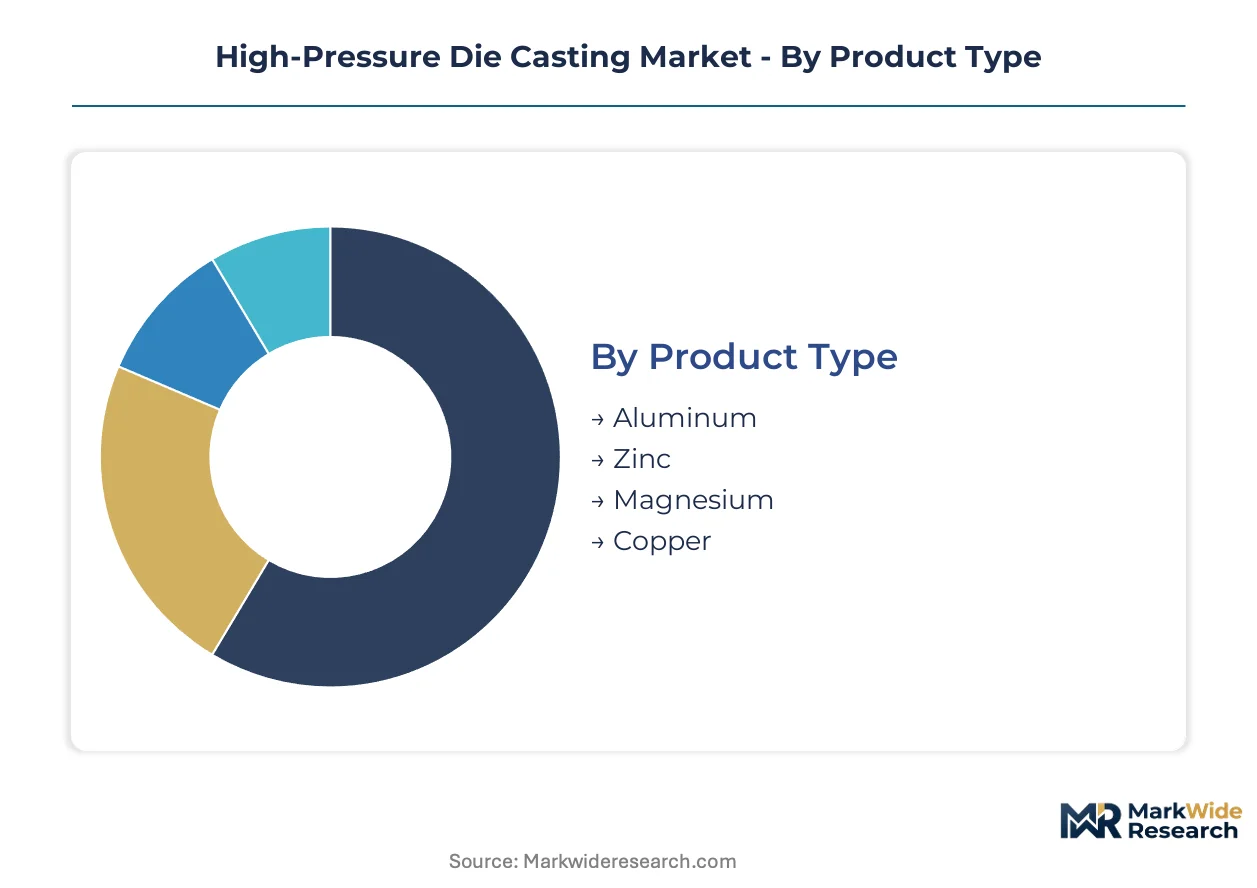
High-pressure die casting segments diverge sharply on regulatory compliance burdens and material certification requirements. Each category demands distinct capital deployment strategies and technical capabilities from foundry operators.
Product Type:
REACH and GB standards enforce divergent alloying limits across European and Chinese supply chains, fragmenting material sourcing strategies.
- Aluminum:Structural-grade specifications dominate automotive electrification programs with strength-to-weight ratios mandated by EU CO2 fleet standards. German OEMs anchor procurement around Stuttgart and Munich supplier corridors for subframe and battery housing contracts.
- Zinc:Electronics enclosure manufacturers specify Zamak alloys for thin-walled precision hardware with dimensional stability under thermal cycling. China's MIIT dual carbon goals accelerate recycled-content mandates for domestic EV platform suppliers.
- Magnesium:Lightweight transmission cases for commercial vehicles face REACH scrutiny on rare earth additive content.
- Copper:Electrical busbar and thermal management components serve industrial motor and power electronics applications.
Aluminum handles the majority of throughput; magnesium is gaining share fastest on commercial vehicle electrification demand.
End User:
Customer procurement patterns split between long-cycle platform qualification and spot-market component sourcing.
- Automotive:Tier-1 suppliers consolidate battery tray assembly contracts under single-source responsibility, compressing vendor lists. Cold chamber capacity retooling for larger part envelopes determines competitive survival as electrification accelerates design cycles.
- Aerospace:Landing gear and brake caliper manufacturers specify vacuum die casting for porosity-free microstructures under FAA and EASA safety mandates. Inline CT scanning at 100% inspection rates eliminates batch release delays.
- Electronics:Hot chamber zinc output sustains precision hardware for consumer device enclosures with tight dimensional tolerances.
- Industrial:Pump housings and valve bodies serve fluid power and process equipment OEMs with moderate volume requirements.
Automotive commands the dominant revenue share; aerospace represents the steepest expansion trajectory on margin premiums for safety-critical certification.
Form:
Geometric complexity drives equipment selection and cycle time economics across foundry floors.
- Thin-Walled Parts:Transmission cases and motor housings below two millimeter wall thickness demand precise thermal management and injection parameter control. Endurance Technologies anchors this segment from India-based manufacturing for commercial vehicle electrification.
- Complex Shapes:Structural nodes and bracket assemblies integrate multiple functional surfaces in single castings, reducing downstream machining.
- Large Components:Battery tray assemblies and subframes exceed conventional cold chamber envelope limits, requiring integrated foundry operators with captive machining.
- Precision Parts:Aerospace brake calipers and steering knuckles hold tight tolerances on critical dimensions.
Thin-walled parts absorb the greatest capital investment intensity; large components are climbing fastest on EV platform consolidation.
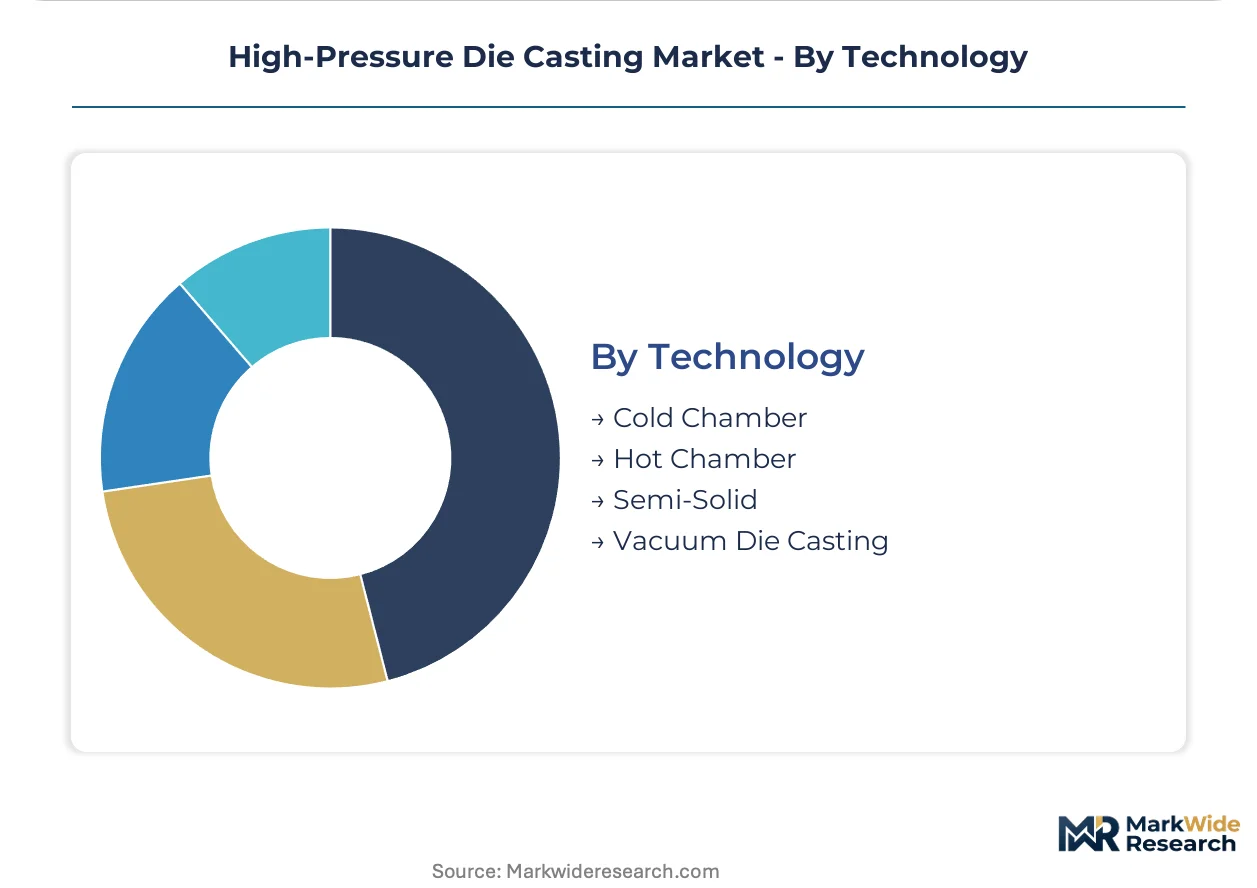
Technology:
Process selection locks foundries into distinct customer tiers and margin structures.
- Vacuum Die Casting:Porosity elimination through controlled atmosphere injection captures premium pricing from aerospace brake and steering component manufacturers. GF Casting Solutions deploys this technology for structural battery housing contracts requiring weldable microstructures.
- Cold Chamber:Aluminum and magnesium volume production for automotive structural parts anchors capacity at major tier-1 suppliers. Rheinmetall AG leverages captive metallurgy R&D to dominate defense and commercial powertrain casting.
- Hot Chamber:Zinc and magnesium alloys sustain high-volume output for electronics enclosures and precision hardware with minimal oxidation.
- Semi-Solid:Thixotropic metal forming reduces porosity in thick-section components for industrial applications.
Cold chamber equipment underpins the broadest installed base; vacuum die casting is expanding most quickly on aerospace and premium automotive qualification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Die casting capacity clusters around automotive manufacturing corridors where OEM electrification programs concentrate procurement. Foundry investment follows tier-1 supplier corridors in Germany, China, India, Japan, and the United States.
Germany
Stuttgart and Munich anchor structural aluminum casting demand from BMW, Mercedes-Benz, and Porsche electrification platforms. EU Green Deal carbon border adjustments and REACH compliance deadlines force reformulation of legacy alloy specifications. The supplier belt around Neckarsulm and Ingolstadt concentrates vacuum die casting capacity for battery housing contracts.
China
Domestic EV platforms from BYD, NIO, and Xpeng specify recycled-content aluminum housings under MIIT dual carbon goals. SAMR enforces GB standards for automotive component integrity that affect export qualification to European battery programs. Yangtze River Delta foundries around Shanghai and Ningbo dominate cold chamber capacity for large structural parts.
United States
Detroit Three electrification programs pull aluminum subframe sourcing toward Michigan and Ohio supplier corridors. EPA fuel economy standards and NHTSA safety regulations compel lighter die-cast chassis components. Tooling lead times from specialized Japanese and European machine shops strain capacity expansion timelines for domestic foundries.
India
Commercial vehicle electrification for electric buses creates white space for thin-walled motor housing specialists. BIS standards alignment with global automotive quality frameworks opens export pathways for compliant suppliers. Pune and Chennai manufacturing corridors concentrate organized foundry capacity serving domestic and export transmission case demand.
Japan
Precision hardware and electronics enclosure manufacturers sustain hot chamber zinc output for consumer device supply chains. METI industrial policy supports advanced die casting technology development for aerospace brake component qualification. Nagoya and Osaka industrial zones maintain specialized vacuum die casting capacity for safety-critical landing gear applications.
High-Pressure Die Casting Market Competitive Environment
Concentration sits with integrated automotive tier-1 suppliers and specialized foundry equipment manufacturers. The competitive structure bifurcates between premium structural casting specialists and volume producers serving standard component specifications. Three archetypes dominate: European automotive-integrated foundries, Asian commercial vehicle specialists, and Swiss-Japanese equipment technology providers. Competitive moves center on cold chamber capacity retooling for larger EV battery envelopes and strategic partnerships for scrap aluminum supply security.
Among European automotive-integrated suppliers, GF Casting Solutions AG and Rheinmetall AG occupy positions spanning structural battery housing and defense powertrain applications. Endurance Technologies represents the India-based commercial vehicle specialist archetype. These three exemplify how geographic manufacturing footprint and metallurgy R&D access determine competitive positioning in platform qualification cycles.
| Leading Market Players |
|---|
| Nemak SAB De CV |
| GF Casting Solutions AG |
| Ryobi Die Casting |
| Rheinmetall AG |
| Shiloh Industries |
| Dynacast |
| Bühler AG |
| Idra Group |
| Endurance Technologies |
| Others |
Value Chain & Pricing Dynamics
Sixteen-to-twenty-four week hardened steel die production cycles at specialized European and Japanese machine shops concentrate pricing power among integrated foundry operators with captive tooling partnerships, while tier-1 suppliers without such relationships face margin compression from expedited procurement premiums.
Pricing Analysis
REACH compliance deadlines dictate the pricing tier structure across European aluminum die casting procurement. Three-tier pricing structure across premium, standard, and economy levels separates vacuum die casting for aerospace brake components from cold chamber automotive structural parts and hot chamber zinc electronics enclosures. Price differentiation hinges on certification grade and volume scale, with OEM battery platform contracts commanding stability while spot-market industrial components face softness from scrap aluminum volatility. Tier-1 automotive suppliers exhibit least price sensitivity due to platform requalification lock-in; electronics enclosure manufacturers show highest sensitivity to zinc alloy spot movements.
Supply Chain Analysis
Die inventory cycles exceeding twenty weeks at specialized machine shops expose foundries to capacity gating when demand surges for EV battery tray envelopes. Qualified secondary aluminum streams cluster in Germany and China, with magnesium alloying additives subject to ECHA scrutiny forcing reformulation costs. Raw material dependencies center on scrap aluminum segregation, hardened steel die blanks, and rare earth magnesium modifiers. Single-source vulnerability concentrates in Japanese and European tooling specialists. Distribution runs through tier-1 automotive supplier corridors anchored around Stuttgart, Munich, and Shanghai-Ningbo manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-pressure die casting incumbents face substitution pressure from advanced polymer composites and additive manufacturing in non-structural automotive applications, requiring defensive positioning around safety-critical qualification moats.
For Market Incumbents: Shield platform relationships by acquiring captive scrap aluminum recycling capacity in Germany or China to secure qualified secondary alloy streams against feedstock disruption. Accelerate cold chamber retooling for larger battery tray envelopes before OEM consolidation locks out non-integrated foundries. Vacuum die casting certification for aerospace brake components offers margin defense against polymer substitution in non-structural segments.
For New Entrants and Emerging Players: Differentiate on thin-walled motor housing specialization for India's electric bus electrification, where organized foundry penetration remains limited and BIS standards alignment opens export pathways. Target GB standards compliance as a qualification wedge for European battery platform subcontracting. Cold chamber equipment partnerships with Yangtze River Delta machinery distributors reduce capital barriers versus European or Japanese sourcing.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because OEM single-source responsibility mandates for battery tray assemblies are compressing vendor lists and rewarding integrated foundry-machining operators. Acquisition targets should display captive metallurgy R&D and established relationships with German technical universities for process technician pipelines. Monitor EU Green Deal carbon border adjustment implementation timing as an inflection signal for scrap aluminum supply chain restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chamber Capacity Retooling | Captures EV battery tray contracts as OEMs consolidate sourcing under single-supplier responsibility mandates. |
| Scrap Aluminum Supply Integration | Secures qualified secondary alloy streams against REACH-driven reformulation costs and carbon border exposure. |
| Vacuum Die Casting Certification | Qualifies for aerospace brake and steering component margins unavailable to conventional gravity casting competitors. |
| Digital Twin Implementation | Enables real-time porosity prediction from in-mold sensor arrays, compressing prototyping cycles for structural programs. |
| GB Standards Alignment Investment | Opens export qualification pathways to European battery platform demand under SAMR automotive component integrity rules. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with tier-1 automotive procurement directors, foundry operations managers, vacuum die casting technicians, and OEM platform engineers; and secondary validation through customs trade data, SEC filings from listed automotive suppliers, IHS Markit vehicle production databases, and ECHA REACH substance registration records. Bottom-up capacity modeling across cold chamber, hot chamber, and vacuum equipment installations triangulated against top-down aluminum die casting consumption estimates from national foundry associations.
Across the analysis window, forecasts derived from segment-level CAGRs weighted by automotive electrification program timelines, aerospace safety-critical certification backlogs, and electronics enclosure replacement cycles. Modeled dimensions span product type, end user industry, geometric form complexity, and process technology tier. Industry-specific inputs incorporated OEM battery platform requalification timelines and EU Green Deal carbon border adjustment implementation trajectories.
Material uncertainties — scrap aluminum supply disruption, REACH additive restriction expansion, and tooling capacity bottlenecks — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding OEM platform consolidation velocity and foundry integration economics. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Freight Elevators Market
Material Handling Equipment
Cam and Groove Fittings Market
Material Handling Equipment
Global Bucket Loader Market
Material Handling Equipment
North America Forklift Market
Material Handling Equipment
Swivel Coupler Market
Material Handling Equipment
Slow Speed Shredding Machines Market
Material Handling Equipment
Australia Forklift Market
Material Handling Equipment
Rail Mounted Gantry Crane Market
Material Handling Equipment
Global Tension Control Market
Material Handling Equipment
Floor Scrubber Machine Market
Material Handling Equipment
Mobile Conveyor Market
Material Handling Equipment
Europe Conveyors Market
Material Handling Equipment
United States Conveyor Belt Market
Material Handling Equipment
Jaw Crushers Market
Material Handling Equipment
Vibratory Feeder Machine Market
Material Handling Equipment
Linear Slides Market