
 Vibratory Feeder Machine Market | 2026-2036
Vibratory Feeder Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Vibratory Feeder Machine Market Analytics
Aftermarket service contracts and predictive maintenance platforms is pivoting how vibratory feeder vendors monetize equipment lifecycles. Eriez leverages its global service network to lock in multi-year maintenance agreements across mining and food processing installations. Carrier Vibrating Equipment anchors its competitive stance through captive engineering services that extend machine uptime guarantees. General Kinematics differentiates by embedding vibration monitoring software into its mechanical feeder lines, creating recurring revenue streams beyond hardware shipment.
Vibratory feeder machines employ controlled oscillatory motion—typically electromagnetic or electromechanical drive systems operating at frequencies between 50 and 120 Hz—to convey, orient, and dispense bulk solids or discrete parts in continuous manufacturing flows. Bowl feeders achieve part orientation through helical track geometries with mechanical selection tooling, while linear feeders maintain consistent feed rates via tuned spring-mass resonant systems for downstream assembly or packaging integration. Electromagnetic technology commands the largest installed base due to precise amplitude control and rapid start-stop response, though piezoelectric actuation is gaining traction in cleanroom pharmaceutical applications where electromagnetic interference must be minimized. Manufacturing applications generate the deepest margin pools as automotive and electronics producers specify customized feeder configurations with integrated vision rejection and traceability systems.
OSHA noise exposure limits and EU Machinery Directive safety standards compel manufacturers to redesign drive housings and add acoustic damping, raising engineering costs but creating barriers for uncertified imports. FDA cGMP validation requirements and REACH material compliance further segment the supplier landscape between certified pharmaceutical-grade builders and general industrial vendors. Stakeholders must weigh captive service revenue against the capital intensity of region-specific certification portfolios as automation buyers consolidate supplier relationships.
Market Dynamics
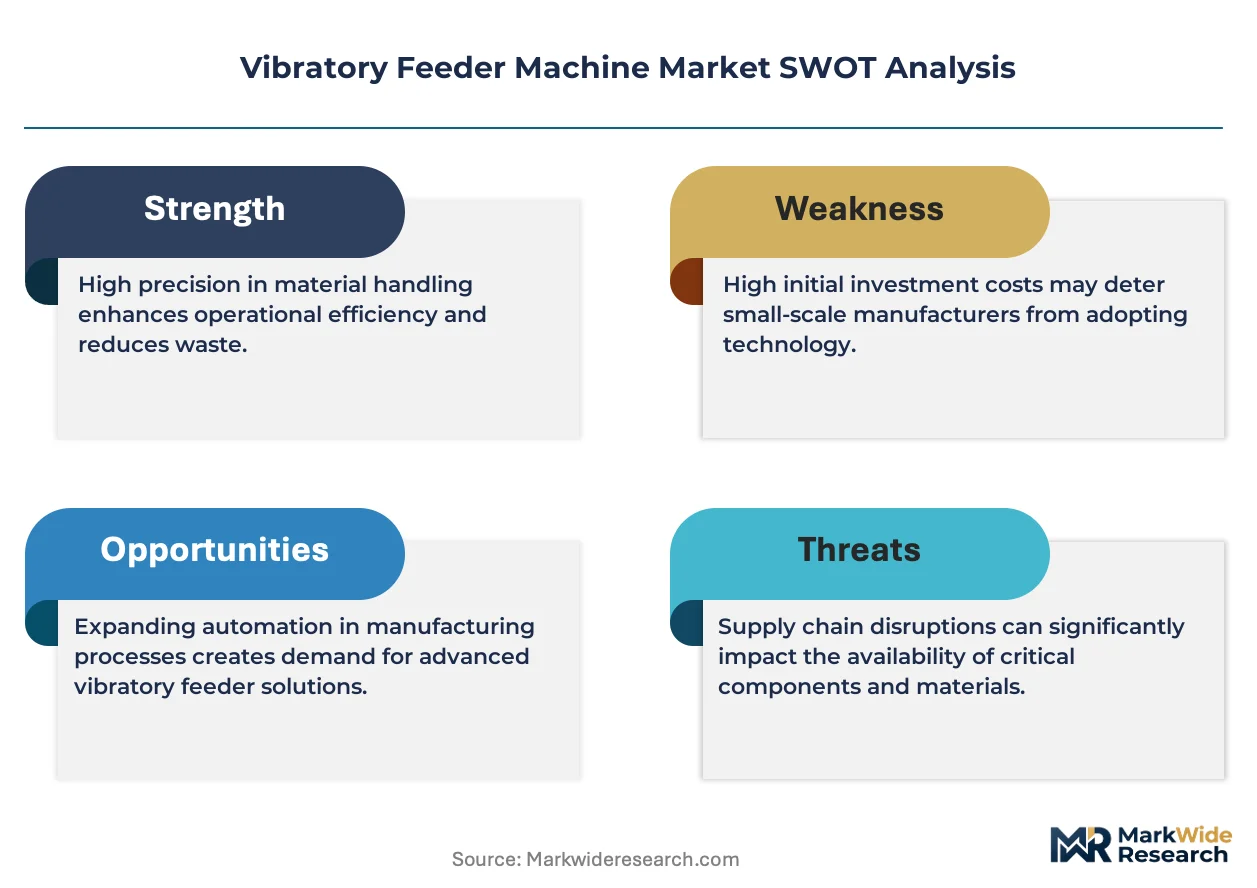
Electromagnetic interference restrictions in pharmaceutical cleanrooms are forcing feeder manufacturers to redesign drive architectures, while predictive maintenance platforms are converting hardware vendors into recurring-revenue service providers across mining and food processing installations.
Growth Catalysts
- Pharmaceutical automation mandates:FDA cGMP validation requirements for processing equipment are compelling drug manufacturers to replace manual handling with validated vibratory feeding systems in sterile filling lines.
- Precision manufacturing clustering:China's Guangdong and Jiangsu provinces are concentrating electronics assembly operations that demand high-throughput bowl feeders with integrated vision rejection capabilities.
- EU Machinery Directive enforcement:CE marking requirements for acoustic safety and emergency stop functionality are filtering out uncertified competitors across European industrial automation procurement.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and samarium-cobalt price swings in Chinese spot markets destabilize electromagnetic drive unit economics for mid-tier manufacturers.
- Electromechanical substitution threat:Servo-driven linear positioning systems with programmable motion profiles are capturing applications requiring variable feed rates beyond fixed-frequency vibration.
- REACH material compliance friction:ECHA restrictions on surface coatings and elastomer compounds force reformulation of track linings and isolation springs, extending qualification timelines.
Strategic Opportunities
- India PLI scheme alignment:Production-linked incentives for electronics manufacturing and medical devices are attracting feeder OEMs to establish local assembly operations near Chennai and Pune.
- Piezoelectric-ultrasonic convergence:Cleanroom pharmaceutical applications are creating demand for piezoelectric actuation that eliminates electromagnetic field generation near sensitive biologic formulations.
- Aftermarket platform monetization:Vibration monitoring software subscriptions and predictive maintenance contracts are opening recurring revenue streams beyond initial equipment sales in mining and aggregate processing.
Industry Challenges
- Mechatronics talent scarcity:Sourcing engineers with combined expertise in resonant mechanical systems and industrial IoT integration is constraining R&D velocity for smart feeder development.
- Multi-jurisdiction certification stacking:Simultaneous FDA, EU Machinery Directive, and GB standard compliance for pharmaceutical-grade equipment is extending time-to-market by 8-14 months.
- Legacy control architecture integration:Retrofitting vibration monitoring and remote diagnostics into installed electromechanical feeders without disrupting plant-wide SCADA protocols demands specialized field engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vibratory Feeder Machine Market |
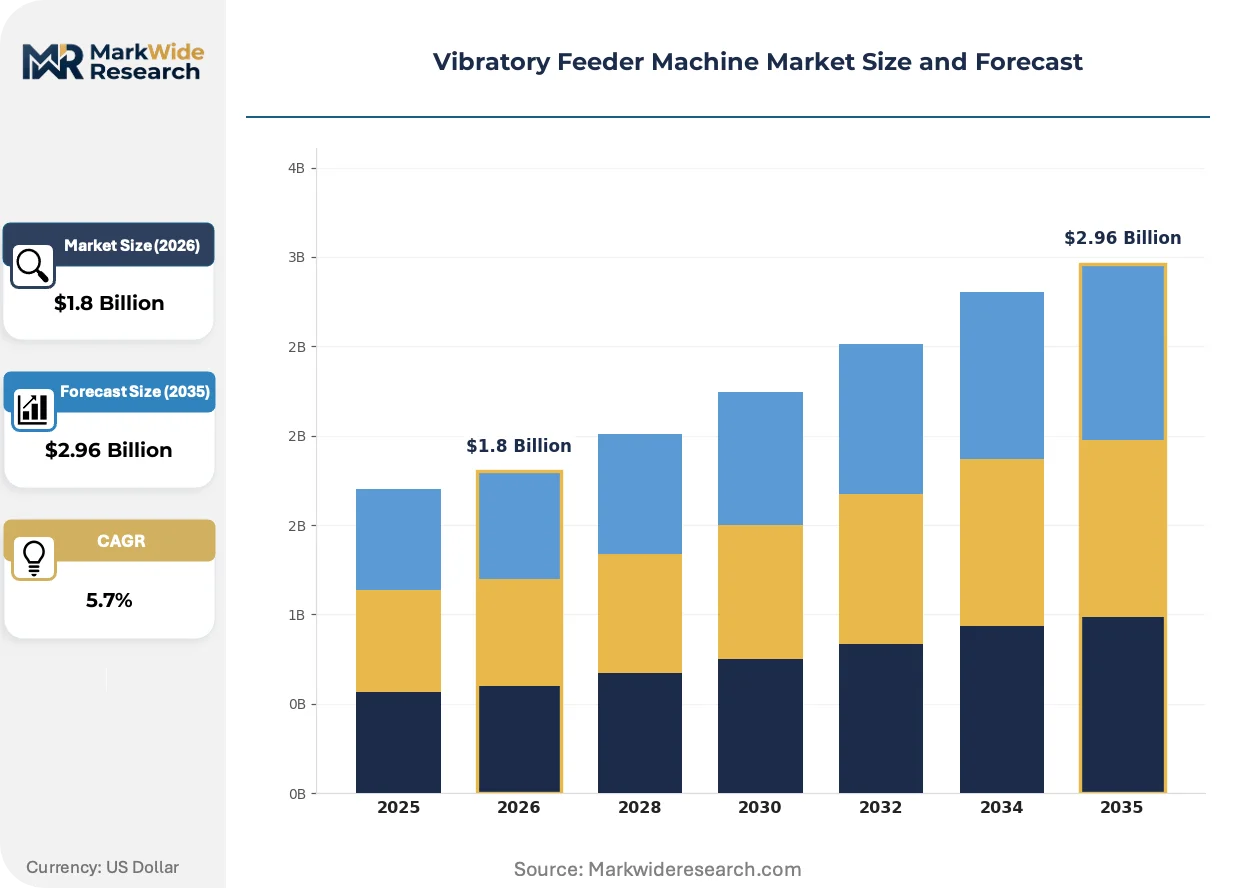
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Feeders, Bowl Feeders, Magnetic Feeders, Hopper Feeders Application: Mining, Pharmaceuticals, Food Processing, Manufacturing End User: Agriculture, Automotive, Electronics, Packaging Technology: Electromagnetic, Piezoelectric, Mechanical, Hydraulic |
| Companies Covered | Eriez, Carrier Vibrating Equipment, General Kinematics, Fortville Feeders, Syntron Material Handling, Hoosier Feeder Company, PPM Technologies Holdings, Vibra Screw, Cleveland Vibrator Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vibratory Feeder Machine Market Evolving Landscape
Feeder technology is pivoting from standalone mechanical components to intelligent, connected subsystems that integrate with plant-wide automation architectures and generate recurring service revenue through predictive analytics platforms.
Electromagnetic drive systems with amplitude feedback control are converging with machine vision-based part rejection and traceability logging. Pharmaceutical and automotive assemblers are specifying these integrated configurations to eliminate downstream quality escapes. The technology is compressing supplier margins on standalone hardware while expanding total contract value through software and service attachments.
REACH restrictions on perfluorinated compounds and heavy metal pigments are forcing track lining material substitutions across European pharmaceutical installations. Industrial consequence includes accelerated qualification cycles for FDA-validated equipment and preference shifts toward suppliers with captive polymer compounding capabilities. German and Swiss OEMs with in-house formulation labs are capturing specification authority from general industrial vendors.
Consolidated procurement frameworks among multinational food processors are unbundling equipment purchase from installation and aftermarket service. Tier-one buyers now contract directly with regional system integrators for deployment, while OEMs retain component supply and remote monitoring subscriptions. This pattern is most visible in North American dairy packaging and ready-to-eal meal assembly operations where plant engineering teams have absorbed feeder specification expertise internally.
Vibratory Feeder Machine Market Segmentation
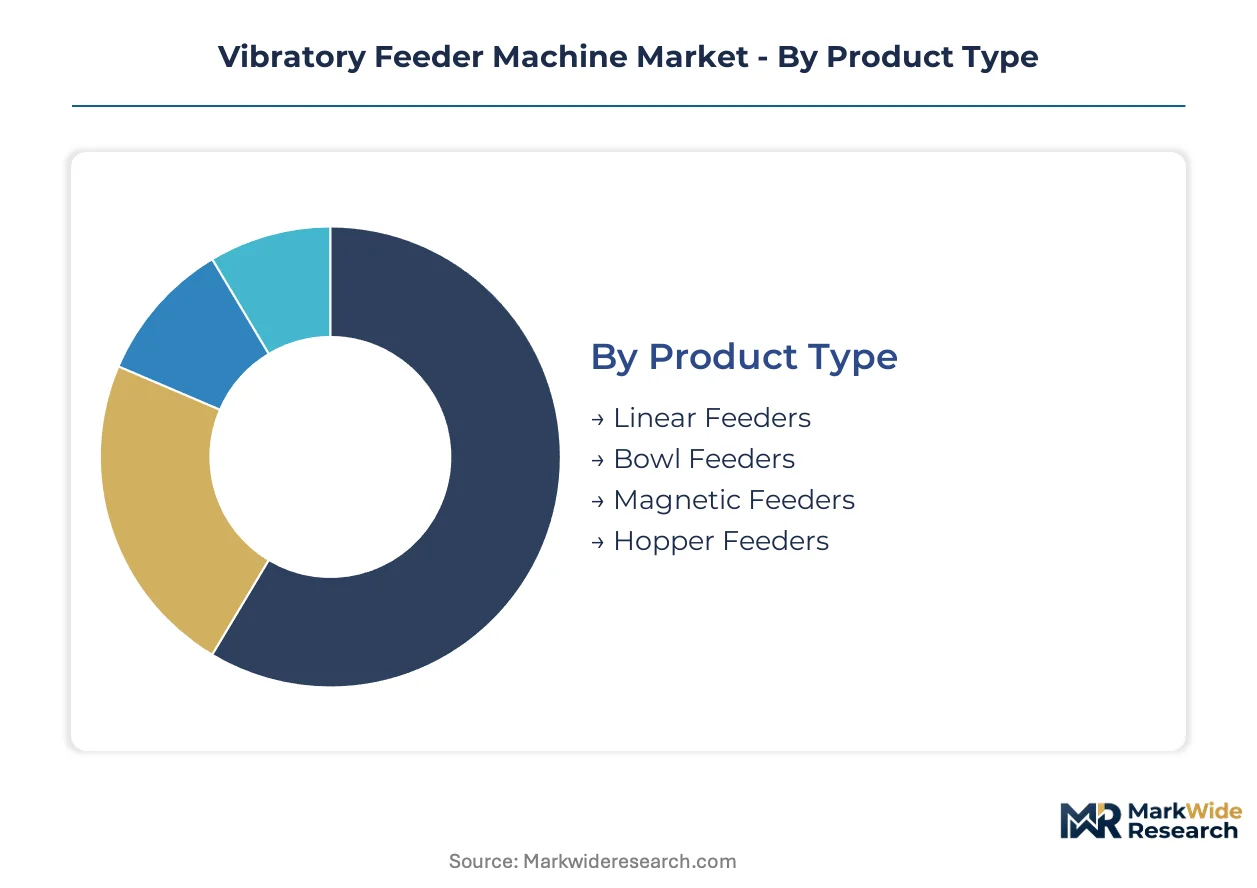
Vibratory feeder machine segmentation reveals how engineering specifications diverge across regulatory environments and automation maturity levels. Product architecture, drive technology, and end-use validation requirements create distinct commercial pockets with uneven margin profiles.
Product Type:
Supply concentration in electromagnetic and electromechanical drive systems shapes competitive positioning across feeder architectures, with European and Chinese OEMs dominating distinct mechanical formats.
- Linear Feeders:Tuned spring-mass resonant systems maintain consistent feed rates for downstream assembly integration. Pharmaceutical filling lines in Germany and electronics assembly clusters in China's Guangdong province specify these for traceable continuous flow.
- Bowl Feeders:Helical track geometries with mechanical selection tooling achieve part orientation through controlled oscillatory motion. Automotive and electronics producers in Japan and South Korea demand high-throughput configurations with integrated vision rejection.
- Magnetic Feeders:Rare earth electromagnetic drives suit mining bulk material handling where amplitude precision matters less than durability.
- Hopper Feeders:Bulk storage-to-metering transition units serve aggregate processing and food ingredient batching.
Linear feeders absorb the bulk of installed capacity; bowl feeders are expanding most quickly.
Application:
Regulatory stringency tiers separate margin pools, with validated pharmaceutical and food-grade equipment commanding engineering premiums over general industrial installations.
- Pharmaceuticals:FDA cGMP validation requirements and sterile filling line mandates drive specification of piezoelectric and electromagnetic feeders with traceability logging. German and Swiss OEMs with captive polymer compounding capture specification authority from general industrial vendors.
- Manufacturing:Automotive and electronics assembly operations in China's Jiangsu province and Japan's industrial corridors demand bowl feeders with vision-based part rejection and SCADA integration.
- Mining:Bulk solids handling prioritizes mechanical durability over precision control, with aftermarket service contracts monetizing equipment lifecycles.
- Food Processing:USDA and EFSA hygiene standards compel stainless steel construction and clean-in-place compatibility, with North American dairy packaging consolidating procurement frameworks.
Manufacturing absorbs the bulk of installed capacity; pharmaceuticals is climbing the fastest.
End User:
Automation maturity and part complexity requirements segment demand, with electronics and automotive driving specification intensity while packaging and agriculture prioritize cost efficiency.
- Electronics:Miniaturized component handling in South Korea's semiconductor packaging and India's PLI-subsidized assembly operations demands sub-millimeter precision bowl feeders with electromagnetic interference mitigation.
- Automotive:Powertrain and EV battery assembly lines in Germany and Japan specify heavy-duty linear feeders with predictive maintenance platform integration.
- Packaging:Ready-to-eat meal and beverage operations in North America unbundle equipment purchase from regional system integrator deployment.
- Agriculture:Seed and grain handling applications favor mechanical drive simplicity over sophisticated control architectures.
Automotive absorbs the bulk of installed capacity; electronics is gaining share fastest.
Technology:
Drive architecture selection trades precision control against electromagnetic compatibility, with pharmaceutical cleanroom restrictions forcing architectural pivots.
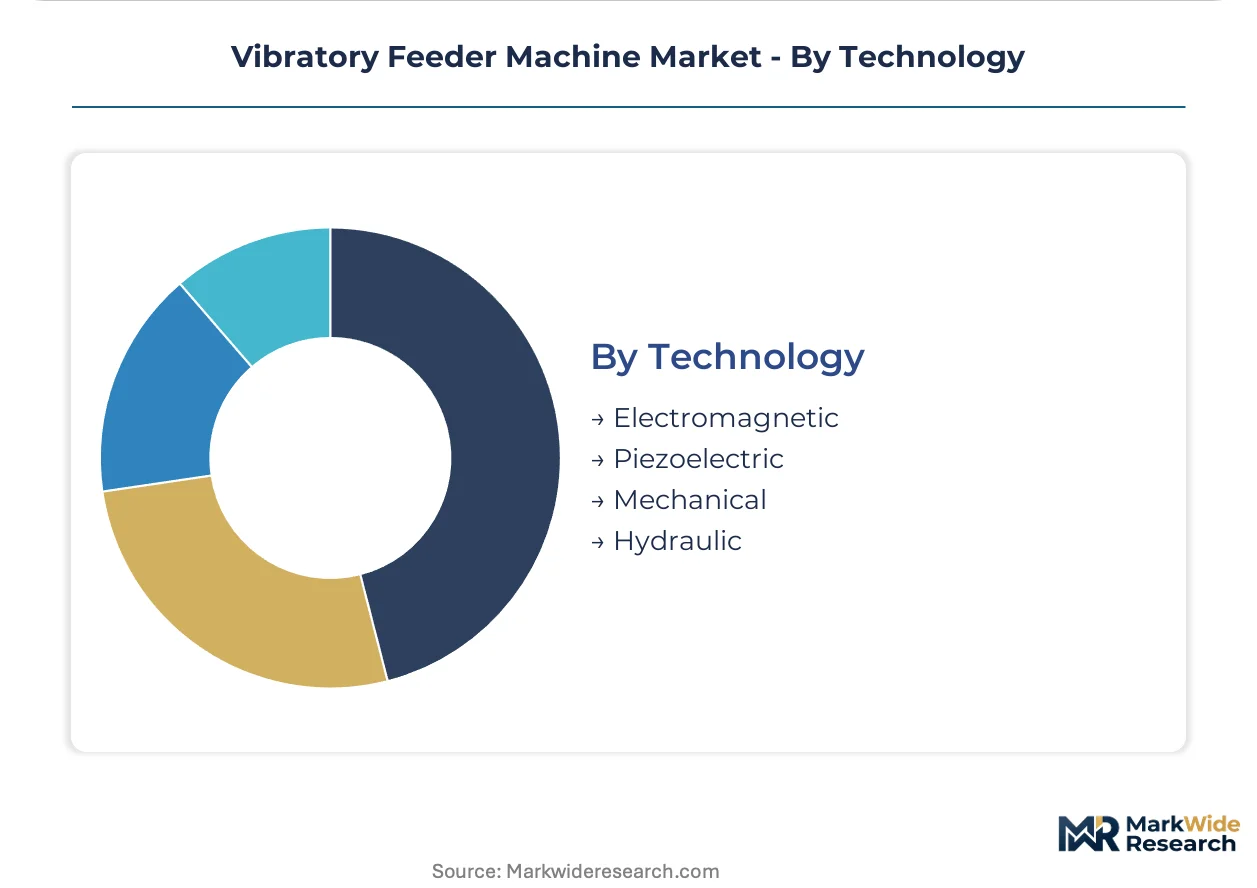
- Electromagnetic:Precise amplitude control and rapid start-stop response dominate general industrial installed base. Neodymium magnet cost volatility in Chinese spot markets destabilizes mid-tier manufacturer economics.
- Piezoelectric:Ultrasonic actuation eliminates electromagnetic field generation for sensitive biologic formulations in Swiss and German pharmaceutical manufacturing. Cleanroom pharmaceutical applications are accelerating qualification cycles.
- Mechanical:Electromechanical cam and eccentric drives serve heavy-duty mining and aggregate processing where fixed-frequency operation suffices.
- Hydraulic:High-force bulk material handling in mining operations where pneumatic or electric alternatives lack torque density.
Electromagnetic absorbs the bulk of installed capacity; piezoelectric shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of electromagnetic drive components while Germany and the United States absorb premium-tier pharmaceutical and automotive installations. Production clusters concentrate in Guangdong and Jiangsu provinces, with consumption gravity shifting toward validated sterile filling corridors in Bavaria and North Carolina.
United States
FDA cGMP mandates for sterile drug manufacturing propel demand for validated vibratory feeding systems in North Carolina's Research Triangle pharmaceutical corridor. OSHA noise exposure limits compel acoustic redesign of drive housings for domestic mining and food processing installations. Cleveland and Chicago anchor Midwestern automotive feeder procurement with integrated vision-rejection specifications.
Germany
EU Machinery Directive enforcement filters uncertified competitors from European industrial automation procurement. REACH restrictions on perfluorinated compounds force track lining reformulations for pharmaceutical-grade equipment. Bavaria's industrial automation corridor concentrates precision bowl feeder demand from automotive powertrain and EV battery assembly operations.
China
Guangdong and Jiangsu province electronics clusters specify high-throughput bowl feeders with electromagnetic interference mitigation for semiconductor packaging. MIIT dual carbon goals accelerate piezoelectric actuation adoption in cleanroom pharmaceutical applications. Shenzhen and Suzhou manufacturing hubs drive volume consumption of linear feeders for downstream assembly integration.
India
PLI scheme production-linked incentives for electronics manufacturing and medical devices attract feeder OEMs to establish local assembly near Chennai and Pune. BIS certification requirements extend qualification timelines for imported pharmaceutical-grade equipment. Karnataka and Maharashtra industrial corridors concentrate demand from automotive component and consumer electronics assembly operations.
Japan
METI industrial automation roadmaps prioritize predictive maintenance platform integration in automotive and electronics feeder specifications. JIS standards for vibration equipment safety create compliance barriers for non-domestic suppliers. Kansai and Chubu manufacturing belts anchor demand for sub-millimeter precision bowl feeders in semiconductor packaging applications.
Vibratory Feeder Machine Market Competitive Landscape
Top-tier vendors anchor premium-tier pharmaceutical and automotive specifications, while mid-tier fabricators compete on price in general industrial bulk handling. The vendor base stratifies across three tiers: integrated automation conglomerates with captive feeder divisions, specialized electromechanical OEMs with regional service networks, and component-focused suppliers serving system integrators. Two dominant competitive moves are reshaping positioning: predictive maintenance platform development to capture recurring service revenue, and captive polymer compounding capabilities to accelerate REACH-compliant track lining qualification.
Among North American electromechanical specialists, Eriez and Carrier Vibrating Equipment exemplify the service-revenue pivot through multi-year maintenance agreement structures. General Kinematics occupies a position within the condition-monitoring tier, embedding vibration analytics software to extend machine uptime guarantees. These three vendors represent contrasting archetypes for hardware-to-service monetization across mining, food processing, and aggregate material handling installations.
| Leading Market Players |
|---|
| Eriez |
| Carrier Vibrating Equipment |
| General Kinematics |
| Fortville Feeders |
| Syntron Material Handling |
| Hoosier Feeder Company |
| PPM Technologies Holdings |
| Vibra Screw |
| Cleveland Vibrator Company |
| Others |
Value Network & Pricing Analysis
Rare earth magnet cost volatility in Chinese spot markets cascades through electromagnetic drive unit economics, compressing margins for mid-tier manufacturers while certified pharmaceutical-grade builders in Germany and Switzerland capture pricing premiums through REACH-compliant track lining formulations.
Pricing Analysis
Margin tightening in standard industrial tiers reflects neodymium and samarium-cobalt price swings destabilizing electromagnetic drive economics. Three-tier pricing structure across premium FDA-validated, standard CE-marked, and economy unbranded levels separates specification authority by certification grade. Cost-down pressure on mid-tier fabricators accelerates because mining and aggregate buyers prioritize aftermarket service bundling over hardware margins. Electronics assemblers in Guangdong province exhibit highest price sensitivity, while sterile pharmaceutical filling lines in Bavaria and North Carolina absorb engineering premiums without volume negotiation.
Supply Chain Analysis
Mechatronics engineering talent scarcity in Guangdong and Jiangsu provinces constrains OEM capacity expansion for smart feeder development. Component manufacturing concentrates in China for electromagnetic coils, Germany for precision springs and isolation systems, and Japan for piezoelectric actuators. Rare earth magnet supply draws from Chinese mining operations with export quota exposure. Single-source vulnerability in neodymium processing creates procurement risk for drive unit assemblers. Distribution runs through regional system integrators in North American food processing and direct OEM channels in European automotive procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Machinery Directive acoustic safety and emergency stop mandates erect compliance barriers that filter uncertified competitors, creating sustainable margin pools for OEMs with captive certification resources.
For Market Incumbents: Hedge against servo-driven linear positioning substitution by embedding predictive maintenance platforms into installed electromechanical bases. Capture multi-year aftermarket service contracts across mining and aggregate processing to offset hardware margin compression. Deepen captive polymer compounding capabilities to accelerate REACH-compliant track lining qualification cycles ahead of reformulation deadlines. For New Entrants and Emerging Players: Regional system integrators in North American dairy packaging represent the most penetrable channel for unbundled equipment supply without installation liability. Target India's PLI-subsidized electronics assembly corridors near Chennai and Pune with locally assembled linear feeders priced below German import landed costs. Lead with vibration monitoring software subscriptions to establish recurring revenue relationships before hardware specification decisions. For Investors and Strategic Acquirers: FDA cGMP validation backlog extending time-to-market by 8-14 months is the leading indicator that certified pharmaceutical-grade builders command scarcity premiums. Mid-cap OEMs with in-house polymer formulation labs and multi-jurisdiction certification portfolios present acquisition targets with defendable moats. Watch piezoelectric actuation qualification velocity in Swiss and German cleanroom installations as inflection signal for electromagnetic displacement timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Captive neodymium sourcing insulates electromagnetic drive margins from Chinese spot market volatility. |
| Predictive Maintenance Platform Development | Vibration analytics subscriptions convert hardware vendors into recurring-revenue service providers across mining installations. |
| Captive Polymer Compounding Investment | In-house REACH-compliant track lining formulation accelerates qualification timelines for European pharmaceutical procurement. |
| Local Assembly Operations in India | Chennai and Pune facilities align with PLI scheme incentives while reducing BIS certification friction for electronics manufacturing. |
| Piezoelectric Actuation Qualification | Ultrasonic drive architectures capture cleanroom pharmaceutical specifications where electromagnetic interference is restricted. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and regulatory compliance officers across pharmaceutical, automotive, and mining verticals. FDA 483 observations, EU Machinery Directive notified body reports, and import-export harmonized system codes provided demand-side validation. Bottom-up equipment shipment analysis triangulated against top-down end-use industry capital expenditure patterns.
Segment-level modeling operated at product type, drive technology, end-use validation tier, and geographic regulatory cluster granularity across the projection horizon. CAGRs derived from equipment replacement cycles, automation penetration curves, and jurisdiction-specific compliance mandate timelines. Forecast inputs incorporated rare earth magnet price indices, PLI scheme disbursement schedules, and cleanroom pharmaceutical construction pipelines without year-specific anchoring.
Caveats apply where neodymium supply disruptions, REACH substance restriction expansions, or servo-driven substitution acceleration could materially shift the outlook. Forecasts embed assumptions regarding certification timeline stability and electromagnetic interference regulatory stringency evolution. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Forklift Work Platforms Market
Material Handling Equipment
Sorting Machines Market
Material Handling Equipment
Can Racks Market
Material Handling Equipment
Belt Scales Market
Material Handling Equipment
Europe Forklift Truck Market
Material Handling Equipment
Dynamic Compactor Market
Material Handling Equipment
Latin America Conveyors Market
Material Handling Equipment
Modular Self-Contained Aisle and Racking Systems Market
Material Handling Equipment
Vibrating Feed Conveyors Market
Material Handling Equipment
Rubber Tyre Gantry Crane Market
Material Handling Equipment
Conveying Equipment Market
Material Handling Equipment
Overhead Hoist Transport (OHT) Market
Material Handling Equipment
Material Handling Integration Market
Material Handling Equipment
Industrial Static Equipment Market
Material Handling Equipment
Arrestor Cables Market
Material Handling Equipment
Compaction Machines Market