
 Bulk Material Handling System Market | 2026-2036
Bulk Material Handling System Market Size, Share, and Industry Trends Forecast 2026-2036
Bulk Material Handling System Market Analysis
Skilled automation engineering talent is collapsing across North American mining districts, forcing equipment vendors to redesign systems for remote operability. Komatsu Ltd. leverages its autonomous haulage heritage to embed self-diagnosing controls into bulk transfer equipment. Caterpillar Inc. anchors its position through captive foundry capacity and dealer service density across Appalachian coal basins. thyssenkrupp AG differentiates via integrated crushing-to-conveying workflows that reduce intermediate handling stages.
Bulk material handling systems encompass the engineered equipment and integrated controls that transport, store, and discharge large volumes of raw commodities such as coal, iron ore, grains, and aggregates through continuous mechanical or pneumatic means, typically operating at throughput rates exceeding 1,000 tonnes per hour. These systems eliminate intermittent truck-and-shovel cycles, cutting unit logistics costs while reducing dust emissions and spillage at transfer points. Conveyors dominate capital deployment due to their energy efficiency over long distances, though automated systems represent the fastest-expanding technology category as mines and ports retrofit sensor arrays for condition monitoring. Integration services command premium margins because they tie disparate OEM subsystems into unified control architectures that optimize flow rates and minimize unplanned downtime.
OSHA mandates govern worker proximity to moving conveyor belts in US surface mining, while EPA particulate standards enforce dust suppression at transfer chutes and stockpile reclaim points. The EU Machinery Directive and CE marking requirements shape safety interlock specifications for European-sourced equipment, creating compliance cost tiers that influence procurement decisions. Stakeholders must weigh the capital intensity of full automation retrofits against the operational risk of prolonged reliance on semi-skilled labor pools in remote extraction zones.
Market Dynamics
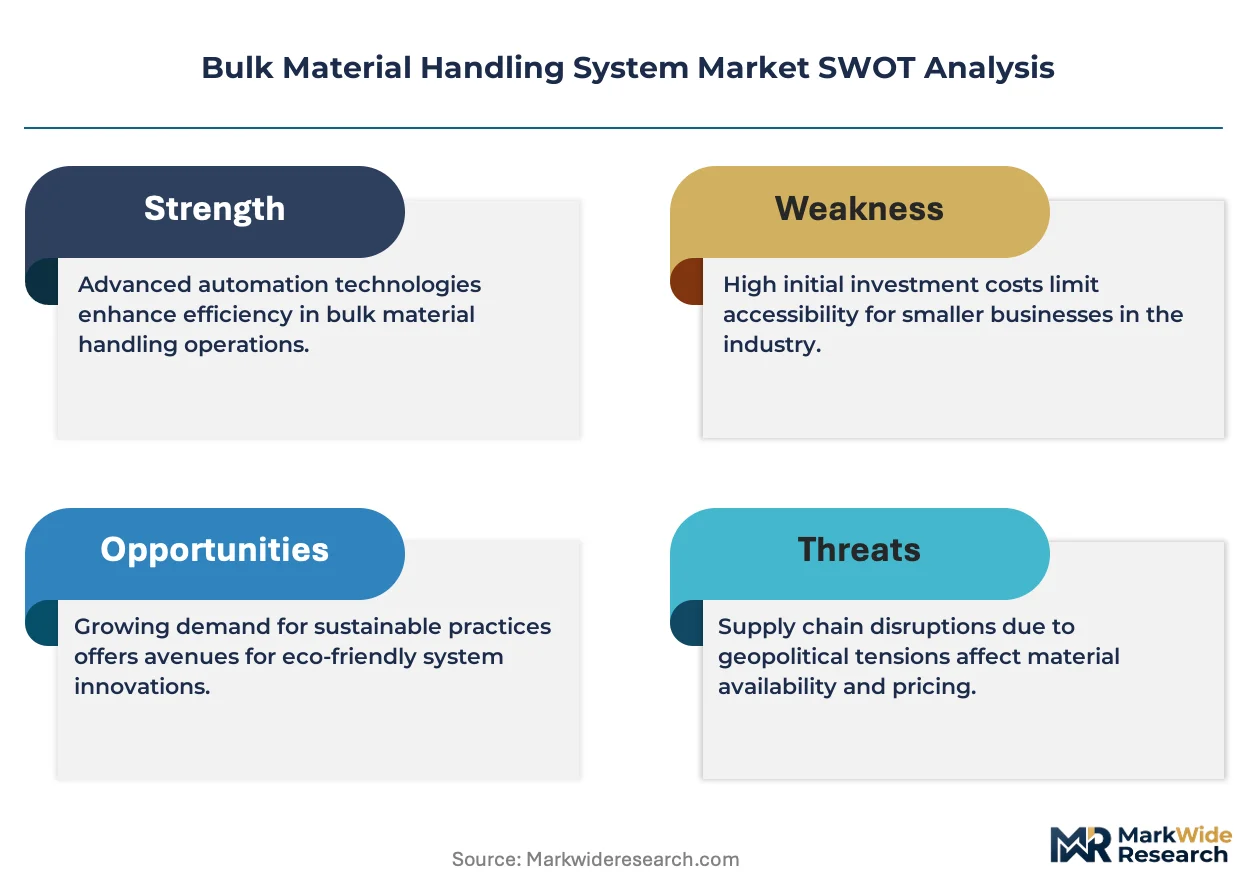
Automation integration through sensor networks and predictive maintenance software is compressing equipment replacement cycles while elevating technical specifications across procurement tenders.
Growth Catalysts
- EPA particulate mandates:Dust suppression requirements at transfer chutes and reclaim points are forcing port operators to upgrade enclosed conveyor systems with integrated suppression technology.
- Iron ore throughput expansion:Australian mining operations are deploying continuous pit-to-port conveyor corridors to displace truck-and-shovel logistics, cutting unit costs per tonne moved.
- Sensor fusion architectures:Vibration monitoring, thermal imaging, and acoustic analysis are converging into unified condition-monitoring platforms that enable predictive maintenance contracts.
Market Restraints
- Steel price volatility:Structural frames, idlers, and pulley assemblies constitute substantial steel tonnage per installed meter, exposing project margins to commodity swings.
- Foundry capacity concentration:Heavy-duty pulley and drive component casting relies on a narrow supplier base in industrial corridors with limited expansion headroom.
- EU Machinery Directive compliance tiers:CE marking requirements for safety interlocks create cost stratification that disadvantages mid-tier system integrators against full-service OEMs.
Strategic Opportunities
- China's northern industrial corridor:Coal and mineral processing clusters in Shanxi and Inner Mongolia require continuous throughput upgrades as aging batch systems reach end-of-life.
- Digital twin integration:Physics-based simulation of material flow, wear patterns, and energy consumption is enabling outcome-based service contracts with guaranteed availability clauses.
- Renewable energy site logistics:Bulk handling systems for biomass pellets, wood chips, and alternative fuels at European power generation facilities represent greenfield specification opportunities.
Industry Challenges
- Automation engineering talent scarcity:North American mining districts face collapsing availability of controls specialists capable of commissioning integrated PLC and SCADA architectures.
- Legacy system interoperability:Brownfield sites with decades-old relay logic and proprietary fieldbus protocols require expensive gateway layers to connect modern sensor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulk Material Handling System Market |
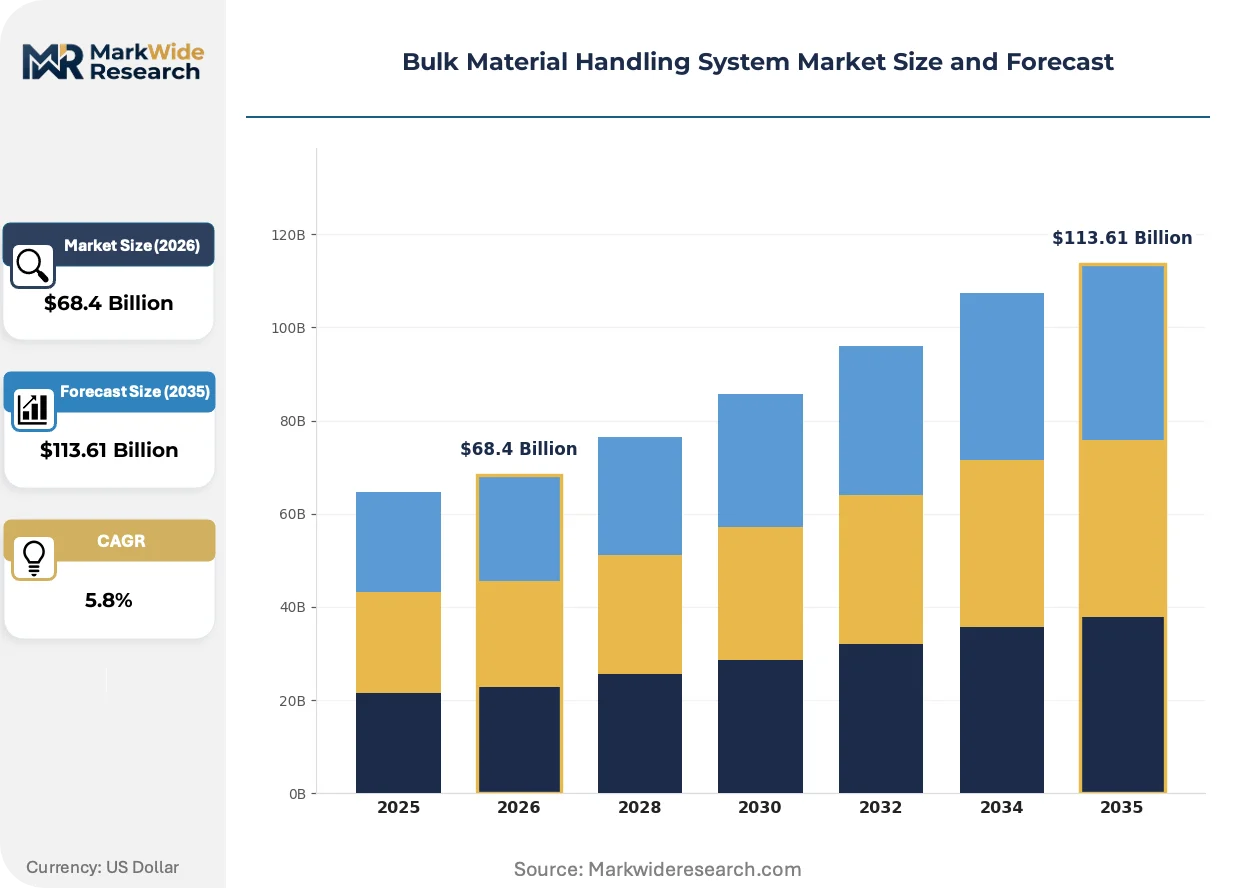
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conveyors, Cranes, Stackers, Loaders Technology: Automated Systems, Pneumatic Systems, Mechanical Systems, Hydraulic Systems End User: Mining, Agriculture, Construction, Manufacturing Solution: Integration Services, System Maintenance, Software Solutions, Equipment Leasing |
| Companies Covered | BEUMER Group GmbH & Co. KG, Komatsu Ltd., thyssenkrupp AG, Liebherr-International Deutschland GmbH, Hitachi Construction Machinery Co., Ltd., Metso Outotec Corporation, Caterpillar Inc., Tenova S.p.A, FLSmidth & Co. A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulk Material Handling System Market Emerging Trajectories
Edge computing architectures and modular drive systems are transforming how bulk handling equipment is specified, commissioned, and maintained across extraction and processing environments.
Intelligent edge nodes with onboard vibration analysis and motor current signature detection are miniaturizing condition monitoring hardware that previously required centralized PLC racks. Australian iron ore operators are deploying these units at transfer stations and drive heads to capture real-time bearing health data. The technology is miniaturizing the physical footprint of diagnostic infrastructure while collapsing installation costs for retrofit projects.
OSHA conveyor safety mandates in US surface mining are tightening proximity detection requirements for workers near moving belts. The regulation is compelling operators to install radar-based personnel detection and automatic emergency stop systems at loading zones. Appalachian coal basins are experiencing accelerated replacement cycles as older systems lack the control architecture to support these interlock upgrades.
Buyer organizations are unbundling aftermarket service contracts from initial equipment procurement, separating spare parts logistics, preventive maintenance, and emergency response into discrete competitive tenders. Mining houses with centralized procurement functions are driving this fragmentation to optimize working capital and supplier accountability. This pattern is most pronounced in Australian and South African operations with mature asset management frameworks.
Bulk Material Handling System Market Segmentation
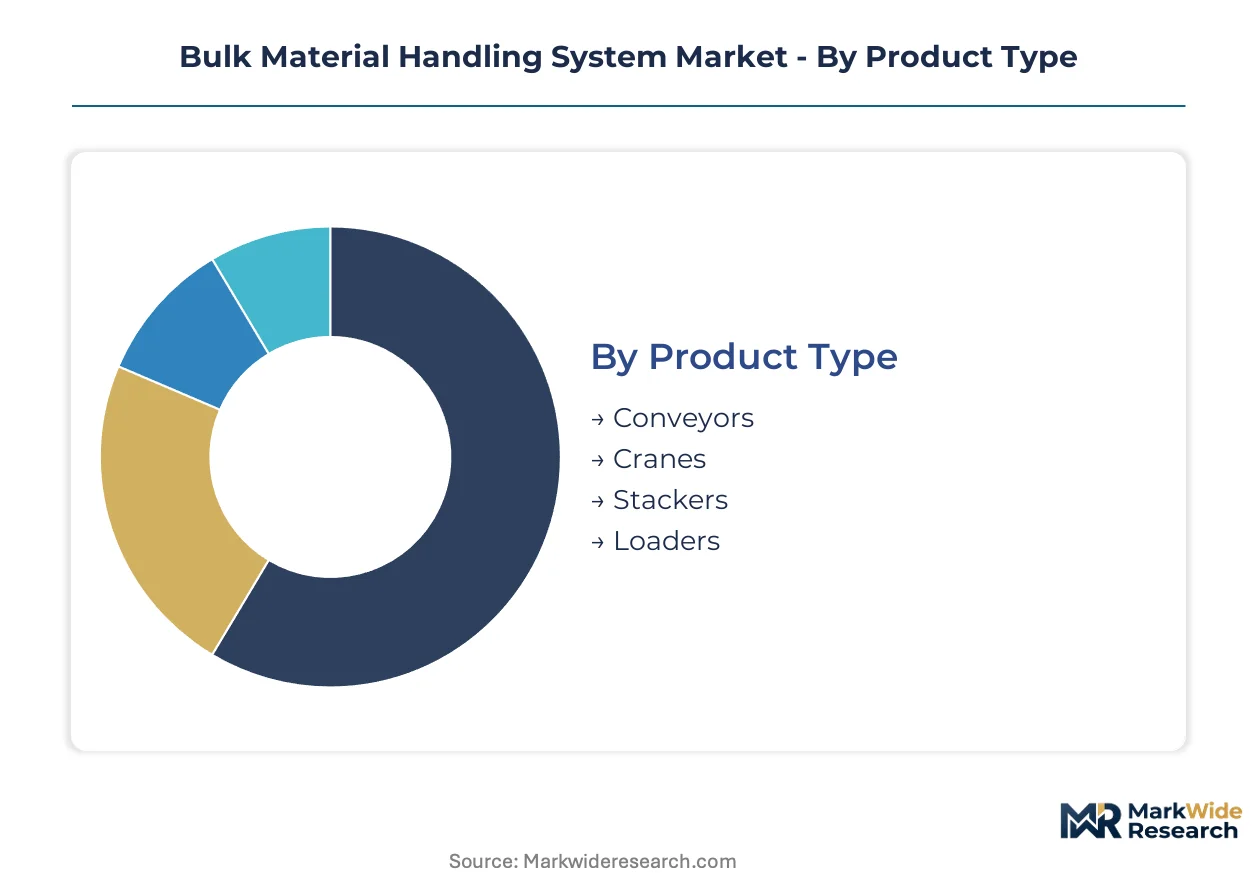
Equipment specification and procurement patterns diverge sharply across product architectures, control technologies, and service delivery models. Each segment carries distinct capital intensity profiles and regulatory compliance burdens that reshape vendor positioning and buyer decision frameworks.
Product Type:
OSHA conveyor safety mandates and EPA dust suppression standards create tiered compliance costs that stratify procurement across belt configurations and structural designs.
- Conveyors:Belt and roller assemblies engineered for continuous material transport at rates exceeding 1,000 tonnes per hour, with enclosed designs now mandatory under EPA particulate regulations at US port transfer points. Australian iron ore corridors from Pilbara pit operations to Port Hedland export terminals deploy these systems to displace truck-and-shovel logistics, cutting unit costs while satisfying dust containment requirements.
- Cranes:Overhead and gantry configurations for vertical lifting and cross-yard positioning of bulk containers and heavy process equipment. Demand concentrates in China's northern industrial corridor where coal processing clusters require yard cranes for stockpile management and vessel loading at Qinhuangdao and Caofeidian port complexes.
- Stackers:Boom-mounted equipment for radial stockpiling and layered blending of homogenized material streams.
- Loaders:Front-end and bucket wheel configurations for reclaim and direct feed applications at mine faces and processing plants.
Conveyors handle the majority of throughput; automated conveyor retrofits are gaining share fastest as sensor integration collapses lifecycle costs.
Technology:
Capital deployment patterns split between proven mechanical architectures and emerging control platforms that command premium pricing for guaranteed availability contracts.
- Automated Systems:Integrated PLC and SCADA architectures with sensor fusion for predictive maintenance, requiring scarce controls engineering talent for commissioning. Australian mining districts face collapsing availability of automation specialists, forcing vendors to embed self-diagnosing edge nodes that reduce field engineering dependencies.
- Mechanical Systems:Gear-driven belt drives, idler assemblies, and gravity discharge chutes forming the installed base across Appalachian coal basins. These systems face accelerated replacement cycles as OSHA proximity detection mandates require control architectures incompatible with decades-old relay logic.
- Pneumatic Systems:Vacuum and pressure conveying for fine powders and granular materials across food processing and chemical applications.
- Hydraulic Systems:High-torque drive solutions for heavy-start conditions and variable load profiles in mining and construction.
Mechanical systems retain the largest installed base; automated systems are expanding most quickly as digital twin integration enables outcome-based service contracts.
End User:
Site conditions and material characteristics dictate equipment durability specifications and maintenance interval economics across extraction and processing environments.
- Mining:Surface and underground operations handling iron ore, coal, and industrial minerals at throughput rates demanding 24/7 mechanical reliability. Australian operations from Western Australia's Pilbara to Queensland's Bowen Basin anchor demand for pit-to-port conveyor corridors that eliminate intermittent truck cycles.
- Agriculture:Grain handling, fertilizer distribution, and biomass logistics requiring seasonal surge capacity and corrosion-resistant finishes. European power generation facilities in Germany and Poland drive specification of bulk handling systems for wood chip and pellet fuel streams.
- Construction:Aggregate processing, cement manufacturing, and ready-mix distribution with high abrasion and moisture exposure.
- Manufacturing:In-plant material flow for steel, chemicals, and processed goods with integrated quality control checkpoints.
Mining commands the dominant share of capital deployment; agriculture is climbing the fastest as renewable energy feedstock logistics reshape equipment specifications.
Solution:
Buyer organizations are unbundling service components to optimize working capital and supplier accountability, fragmenting what were historically captive OEM revenue streams.
- Integration Services:Engineering and commissioning of unified control architectures that tie disparate OEM subsystems into optimized flow networks. These contracts command premium margins where brownfield sites in South Africa and Australia require gateway layers to connect legacy fieldbus protocols with modern sensor networks.
- System Maintenance:Preventive and predictive service programs including spare parts logistics and emergency response. Mining houses with centralized procurement functions are driving competitive tender separation of maintenance from initial equipment purchase.
- Software Solutions:Condition monitoring platforms, digital twin simulations, and fleet management systems delivered on subscription models.
- Equipment Leasing:Operating lease structures that transfer residual value risk and maintenance obligation to vendors.
Integration services capture the highest margin pool; software solutions are expanding most quickly as physics-based simulation enables guaranteed availability contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian mining operations deploy continuous pit-to-port conveyor corridors for iron ore logistics, while Chinese coal processors favor integrated crushing-to-conveying workflows that reduce intermediate handling stages. This consumption-mix differential reflects divergent material characteristics and regulatory enforcement intensity across extraction environments.
Australia
Western Australia's Pilbara region drives demand for enclosed conveyor systems that satisfy dust containment mandates while moving iron ore from mine faces to Port Hedland export terminals. EPA particulate standards enforce suppression technology at transfer chutes throughout Queensland's Bowen Basin coal operations. The country's national mining safety regulator mandates proximity detection systems at surface operations, accelerating replacement cycles for legacy belt infrastructure.
China
Shanxi and Inner Mongolia coal processing clusters require continuous throughput upgrades as aging batch systems reach end-of-life. GB standards and Ministry of Ecology and Environment directives enforce emission controls at material transfer points across northern industrial corridors. The Qinhuangdao and Caofeidian port complexes anchor specification demand for yard cranes and enclosed reclaim systems that satisfy dual carbon policy timelines.
United States
Appalachian coal basins experience accelerated equipment replacement as OSHA conveyor safety mandates tighten proximity detection requirements for workers near moving belts. EPA particulate regulations enforce dust suppression at transfer chutes and stockpile reclaim points throughout Powder River Basin surface operations. Pittsburgh and Charleston industrial corridors concentrate demand for integrated control architectures that connect legacy relay logic with modern sensor networks.
Germany
Ruhr industrial heritage and contemporary steel processing sustain demand for heavy-duty pulley assemblies and drive component systems. EU Machinery Directive and CE marking requirements shape safety interlock specifications that create compliance cost tiers influencing procurement decisions. The country's national industrial safety regulator enforces machinery standards that advantage full-service OEMs against mid-tier system integrators in brownfield retrofit tenders.
South Africa
Platinum and gold extraction operations in the Bushveld Complex and Witwatersrand Basin drive specification of unified control architectures for disparate OEM subsystems. The country's national mining regulator enforces trackless mobile machinery safety standards that extend to conveyor belt installations in underground environments. Johannesburg and Rustenburg industrial corridors concentrate maintenance service demand as mining houses unbundle aftermarket contracts from initial equipment procurement.
Bulk Material Handling System Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the bulk material handling system market. The upper tier commands premium positioning through captive foundry capacity, autonomous haulage heritage, and integrated crushing-to-conveying workflows. Specialist fabricators compete on modular drive configurations and regional service density. Dominant competitive moves include backward integration into heavy casting operations and geographic expansion through dealer network density.
Among Germany-based industrial conglomerates, thyssenkrupp AG and Liebherr-International Deutschland GmbH occupy positions that exemplify integrated equipment-to-controls positioning. Komatsu Ltd. anchors the autonomous systems tier through heritage in self-diagnosing control architectures. These three entities represent distinct competitive vectors: European engineering integration, Asian automation heritage, and captive manufacturing scale.
| Leading Market Players |
|---|
| BEUMER Group GmbH & Co. KG |
| Komatsu Ltd. |
| thyssenkrupp AG |
| Liebherr-International Deutschland GmbH |
| Hitachi Construction Machinery Co., Ltd. |
| Metso Outotec Corporation |
| Caterpillar Inc. |
| Tenova S.p.A |
| FLSmidth & Co. A/S |
| Others |
Supply Flow & Price Mechanics
Project-based equipment procurement with multi-year maintenance riders locks in supply access for Australian iron ore operators while anchoring price visibility against steel commodity swings. This contracting pattern concentrates volume commitments with foundry-integrated OEMs capable of delivering integrated crushing-to-conveying workflows across Pilbara pit-to-port corridors.
Pricing Analysis
Long-term offtake contracts with embedded spare parts riders dominate Australian and Chinese procurement, insulating buyers from spot steel volatility while tying vendors to availability guarantees. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked European systems with full safety interlock compliance from mid-tier Asian fabricators and basic mechanical configurations. Cost compression in standard-tier conveyor assemblies is intensifying because foundry capacity constraints in Germany and Japan limit supplier choice. State-owned mining houses in China's northern industrial corridor exhibit lowest price sensitivity, while mid-tier South African platinum operators negotiate hardest on upfront capital.
Supply Chain Analysis
Strait of Malacca transit underwrites component delivery timelines for Australian and Southeast Asian project sites, exposing schedules to maritime congestion during monsoon windows. Heavy-duty pulley casting concentrates in Germany, Japan, and select Chinese industrial corridors with limited expansion headroom. Structural steel, high-grade bearings, and specialized rubber belting feed from commodity markets with volatile input pricing. Single-source vulnerability runs through German foundries supplying critical drive assemblies for EU-compliant safety interlock systems. Distribution runs through OEM-direct project engineering teams with regional service depots anchoring aftermarket capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automation integration through sensor fusion and predictive maintenance platforms is compressing replacement cycles while elevating technical specifications, creating a high-growth disruption as OSHA and EPA mandates force accelerated capital deployment across North American mining districts.
For Market Incumbents: Fortify captive foundry capacity and dealer service density across Appalachian coal basins to defend against mid-tier Asian fabricators gaining share through modular drive configurations. Backward integration into heavy casting operations in industrial corridors with existing metallurgical infrastructure anchors margin protection against steel price volatility. CE marking compliance investment creates tiered cost barriers that disadvantage system integrators lacking full-service OEM scale. For New Entrants and Emerging Players: Differentiate on edge-computing condition monitoring architectures that reduce field engineering dependencies for brownfield retrofits in South Africa and Australia. Target renewable energy feedstock logistics in European power generation facilities, where biomass pellet handling specifications remain underpenetrated by incumbent mining-focused vendors. Partner with regional system integrators possessing legacy protocol gateway expertise to accelerate commissioning timelines. For Investors and Strategic Acquirers: Capital is best deployed toward automation-heritage equipment vendors with embedded self-diagnosing control platforms and proven predictive maintenance contract structures. Long-term viability hinges on software-enabled outcome-based revenue models with guaranteed availability clauses displacing transactional equipment sales. Watch for inflection signals in mining house procurement unbundling patterns, where competitive tender separation of maintenance from initial purchase accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Operations | Captive pulley casting capacity insulates margins against steel commodity volatility in German industrial corridors. |
| Digital Twin Platform Deployment | Physics-based simulation enables guaranteed availability contracting with Australian iron ore operators. |
| Edge Node Miniaturization | Onboard vibration analysis collapses installation costs for retrofit projects across aging Appalachian infrastructure. |
| Regional Service Depot Expansion | Proximity maintenance coverage captures unbundled aftermarket contracts from centralized mining procurement functions. |
| CE Marking Compliance Investment | Safety interlock certification creates procurement cost tiers favoring full-service OEMs over mid-tier integrators. |
Methodological Framework
A standing panel of maintenance directors at Australian iron ore operations, OEM procurement teams in Germany and Japan, aftermarket service heads across South African platinum extraction, and plant engineers at Chinese coal processing clusters provided ongoing calibration against secondary validation. Primary fieldwork combined structured interviews with trade data from customs records, SEC filings of listed equipment vendors, and industry association reports from mining federations. Bottom-up project pipeline tracking across Pilbara and Bowen Basin developments triangulated against top-down macroeconomic indicators for commodity throughput demand.
Consistency checks validated volume and value outputs against external benchmarks including installed base estimates from national mining safety regulators and capital expenditure disclosures from major mining houses. Segmentation modeling spanned equipment type, control technology architecture, end-use extraction environment, and solution delivery model across the projection horizon. CAGRs derived from weighted regression of historical replacement cycles against regulatory mandate acceleration timelines, with sensor fusion adoption curves and steel price elasticity as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained iron ore demand expansion or accelerated EPA enforcement timelines would require recalibration. Forecasts reflect documented assumptions regarding automation engineering talent availability and foundry capacity expansion headroom. Practitioners should keep alternative scenarios live as OSHA proximity detection mandate implementation schedules and EU Machinery Directive compliance cost trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Industrial Lift Ladder Market
Material Handling Equipment
Wear Plates Market
Material Handling Equipment
Pallet Circulation System Market
Material Handling Equipment
Heavy Duty Telehandler Market
Material Handling Equipment
Global Loading Dock Lifts Market
Material Handling Equipment
Industrial Carts Market
Material Handling Equipment
Pallet Truck Market
Material Handling Equipment
Japan Conveyor Belt Market
Material Handling Equipment
Belt Scales Market
Material Handling Equipment
High-Pressure Die Casting Market
Material Handling Equipment
North America Utility Locator Market
Material Handling Equipment
Cherry Picker Forklift Market
Material Handling Equipment
Asia-Pacific Conveyors Market
Material Handling Equipment
Linear Slide Units Market
Material Handling Equipment
Overhead Conveyor Systems Market
Material Handling Equipment
Global Automatic Palletizer and Depalletizer Market