
 Cable Conduit Systems Market | 2026-2036
Cable Conduit Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Conduit Systems Market Intelligence
UL-listed heavy-wall specifications is unwinding legacy procurement patterns across North American infrastructure projects. Atkore International leverages integrated steel and PVC manufacturing to control raw material cost exposure across multiple specification tiers. Schneider Electric anchors its position through specification-grade metallic tubing bundled with low-voltage distribution systems. Legrand competes on modular pre-fabricated conduit assemblies that reduce on-site labor hours for commercial contractors.
Cable conduit systems are protective raceways—typically steel, aluminum, or thermoplastic enclosures with defined wall thicknesses, bend radii, and corrosion-resistance ratings—engineered to route and shield electrical and fiber-optic cabling from mechanical damage, moisture, and electromagnetic interference. The primary industrial purpose centers on ensuring code-compliant cable management across commercial buildings, industrial facilities, and utility-scale infrastructure where unprotected conductors face environmental or operational hazards. Rigid conduit and liquid-tight conduit dominate specification sheets in heavy industrial and outdoor applications where crush resistance and sealed joints are non-negotiable. Flexible conduit captures expanding share in retrofit commercial environments and data center white spaces where routing agility offsets premium material costs. Polyvinyl Chloride and Steel materials split volume leadership, with PVC gaining in corrosive-environment commercial work while steel retains specification lock-in for high-temperature and high-impact industrial zones.
NFPA 70 National Electrical Code enforcement by US municipal inspectors drives minimum wall-thickness and grounding-bonding requirements that disqualify uncertified imports from specification lists. ECHA REACH restrictions on phthalate plasticizers and EU CPR fire-performance classifications are forcing European manufacturers to reformulate PVC compounds and re-test entire product lines for CE marking continuity. OSHA electrical safety directives and EPA site-remediation standards in the US add layered compliance costs for contractors sourcing conduit for industrial renovation work. Stakeholders must monitor evolving code cycles and material restriction timelines to avoid stranded inventory or specification lockout in bid-driven procurement channels.
Market Dynamics
NFPA 70 NEC enforcement and EU CPR compliance are compressing specification windows for uncertified imports while concentrating procurement authority among integrated domestic manufacturers with captive testing laboratories.
Growth Catalysts
- Data Center Buildouts:Hyperscale facility construction across the United States and Germany is accelerating specification of liquid-tight and rigid conduit systems for power distribution and fiber-optic backbone routing.
- REACH Reformulation Mandates:ECHA restrictions on phthalate plasticizers are forcing PVC compound reinvention, creating first-mover advantage for European manufacturers with certified alternative formulations already in production.
- Offshore Wind Installation:Nordic zone development in Danish and Norwegian waters is driving specification of corrosion-resistant metallic conduit for subsea cable protection and turbine nacelle wiring.
Market Restraints
- Steel Price Volatility:Hot-rolled coil input cost swings are compressing margin stability for manufacturers without backward integration into steel production or long-term scrap supply contracts.
- Import Certification Barriers:UL listing requirements and third-party testing costs are structurally excluding low-cost Asian producers from North American infrastructure bid channels regardless of price competitiveness.
- Thermoplastic Temperature Limits:PVC conduit loses structural integrity above 60°C continuous operating temperature, locking steel specifications into high-heat industrial zones and preventing material substitution in petrochemical corridors.
Strategic Opportunities
- Pre-Fabricated Modular Assemblies:Factory-built conduit runs with integrated junction boxes and termination hardware are compressing on-site labor hours for commercial contractors facing skilled electrician shortages.
- Gulf Coast Petrochemical Expansion:Louisiana and Texas corridor facility construction is concentrating demand for explosion-proof and liquid-tight specifications in a geographic cluster with limited qualified local supply.
- Smart Conduit Integration:Embedding fiber-optic sensing cables within conduit walls enables real-time temperature and fault monitoring, converging passive raceway function with predictive maintenance infrastructure.
Industry Challenges
- Certification Timeline Compression:NFPA 70 three-year code cycles and EU CPR fire-performance reclassification deadlines are forcing manufacturers to maintain parallel testing pipelines to avoid specification lockout during transition periods.
- Skilled Installation Labor Scarcity:Journeyman electrician shortages in commercial construction are extending project schedules and increasing warranty exposure for contractors unfamiliar with specialized bending and sealing techniques.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Conduit Systems Market |
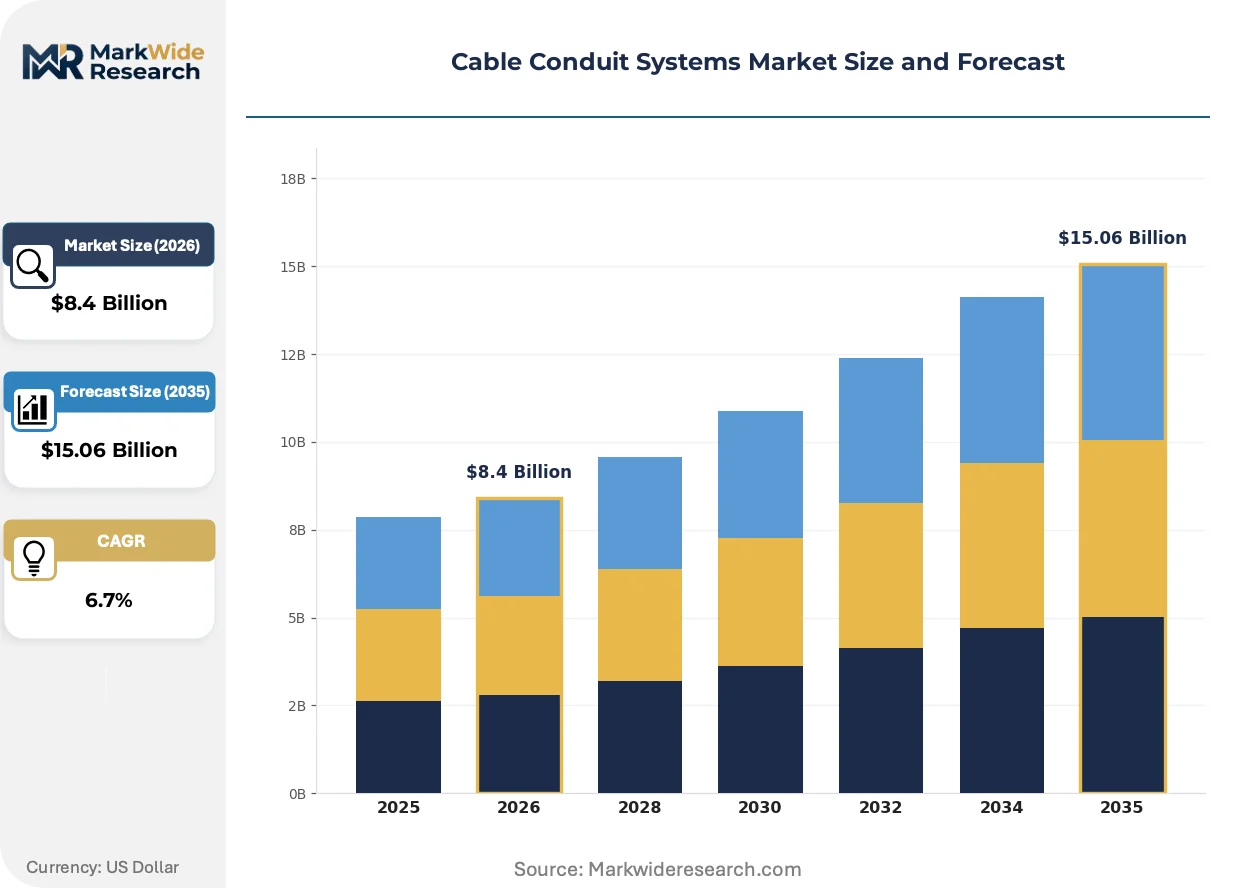
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Conduit, Rigid Conduit, Liquid-Tight Conduit, Electrical Metallic Tubing Material: Polyvinyl Chloride, Steel, Aluminum, Fiber-Reinforced Plastic Installation Method: Underground, Surface-Mounted, Pre-Fabricated, Exposed End User: Industrial, Commercial, Residential, Data Centers |
| Companies Covered | Atkore International, Schneider Electric, Legrand, Hubbell Incorporated, ABB, Eaton Corporation, Aliaxis Group, Dura-Line Holdings, Champion Fiberglass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Conduit Systems Market Strategic Shifts & Innovations
Material science advances and regulatory stringency are actively compressing the viable specification set while elevating performance premiums for certified systems. Three convergent developments are restructuring competitive positioning.
High-density polyethylene conduit formulations with enhanced UV stabilizers and crush resistance are displacing legacy PVC in outdoor commercial and utility-scale solar installations. Solar EPC contractors in the southwestern United States are specifying HDPE for direct-burial DC feeder runs where flexibility and trenching tolerance offset material cost premiums. The displacement is compressing PVC volume leadership in applications where temperature cycling and ground movement previously mandated metallic specifications.
ECHA REACH Annex XVII restrictions on cadmium and lead additives are forcing reformulation of PVC stabilizer packages across European manufacturing footprints. Compounders with pre-certified calcium-zinc alternative systems are capturing specification share while competitors face 18-24 month requalification timelines. German and French electrical distributors are prioritizing CE-marked inventory with documented substance compliance to avoid downstream liability exposure under CSRD supply chain disclosure requirements.
Specification-grade procurement is consolidating around integrated distributors with captive engineering support and just-in-time staging capabilities. Commercial contractors in Texas and California are bypassing traditional wholesale channels for direct manufacturer relationships that bundle material supply with digital takeoff tools and prefabrication services. The channel compression is most visible in data center and healthcare verticals where compressed construction schedules reward single-source accountability over price-driven multi-vendor sourcing.
Cable Conduit Systems Market Segmentation
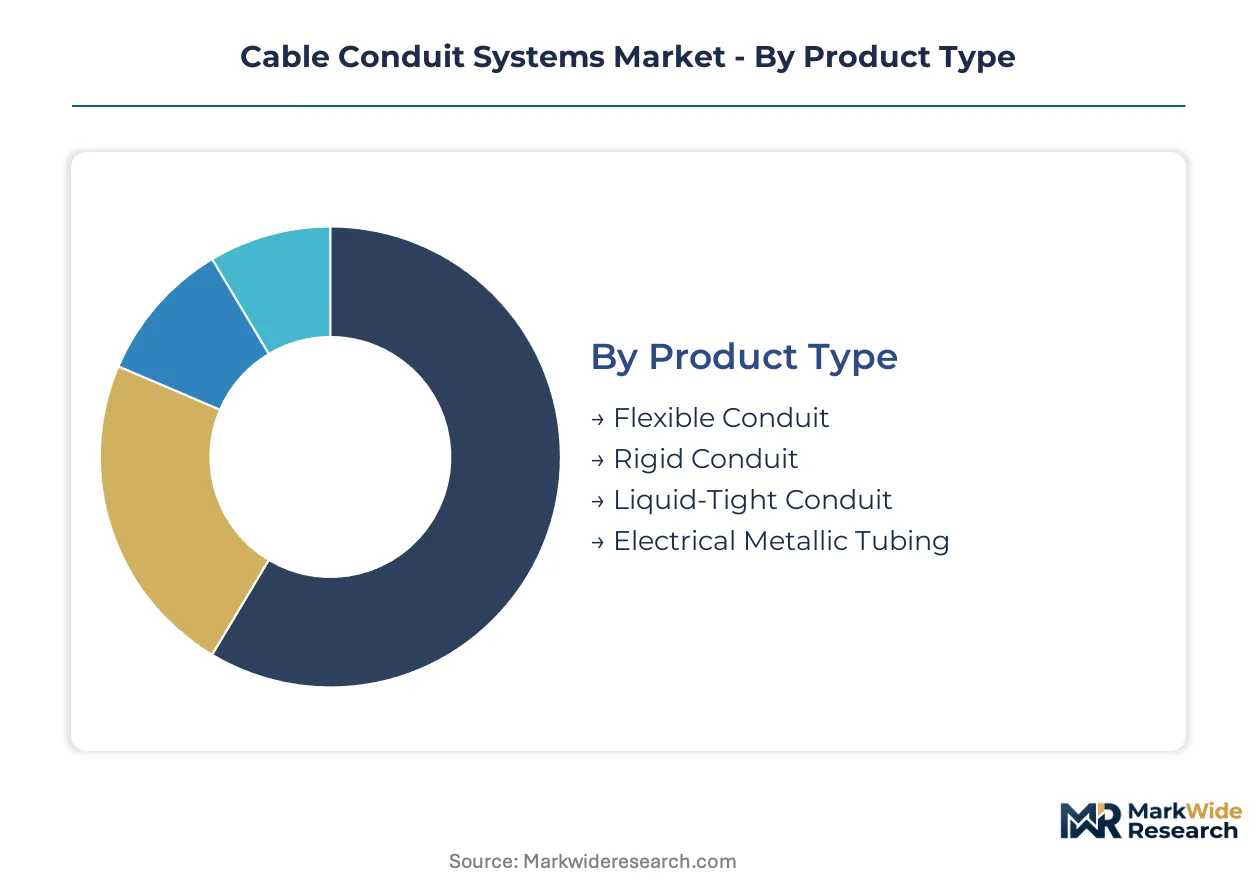
Specification-grade cable conduit procurement channels fragment sharply by product category, with industrial distributors, electrical wholesalers, and direct manufacturer relationships each dominating distinct material and installation segments. Understanding these channel-product pairings exposes margin concentration points and identifies where certification requirements create procurement friction.
Product Type:
Channel mix varies dramatically across conduit formats, with rigid and liquid-tight specifications flowing through industrial distributors serving petrochemical and utility contractors while flexible formats concentrate in commercial electrical wholesalers.
- Rigid Conduit:Thick-walled steel or aluminum enclosures with threaded joints engineered for high-impact protection and grounding continuity. Demand concentrates in Gulf Coast petrochemical corridors where NFPA 70 explosion-proof specifications disqualify alternative formats. Hot-rolled coil price volatility compresses margin stability for distributors without long-term mill contracts.
- Liquid-Tight Conduit:Sealed metallic or non-metallic systems with continuous flex capability and IP-rated joint integrity. Offshore wind installation in Danish and Norwegian waters drives specification for salt-spray-resistant formulations. ECHA REACH compliance on jacket compounds creates first-mover advantage for manufacturers with pre-certified alternatives.
- Flexible Conduit:Corrugated metallic or thermoplastic raceways prioritizing routing agility over crush resistance. Commercial retrofit contractors in Texas and California specify for data center white space reconfigurations.
- Electrical Metallic Tubing:Thin-wall steel tubing with compression or set-screw couplings for dry-location commercial work. Healthcare and education verticals in the United States specify through integrated distributor relationships bundling digital takeoff tools.
By volume, rigid conduit leads. By growth pace, liquid-tight formats are expanding most quickly.
Material:
Cost tier stratification separates commodity-grade PVC from premium metallic specifications, with aluminum occupying a mid-tier position increasingly threatened by fiber-reinforced plastic in corrosive environments.
- Steel:Hot-rolled or cold-formed carbon steel with zinc, PVC, or epoxy coatings for corrosion resistance. High-temperature industrial zones above 60°C continuous operation lock in steel specifications regardless of commodity price swings. Backward integration into scrap supply or captive rolling mills defends margin position for integrated manufacturers.
- Polyvinyl Chloride:Extruded thermoplastic formulations with calcium-zinc or legacy lead-based stabilizer packages. ECHA REACH Annex XVII reformulation mandates are forcing 18-24 month requalification timelines for compounders without pre-certified alternatives. German and French electrical distributors prioritize CE-marked inventory with documented substance compliance.
- Aluminum:Lightweight metallic conduit with anodized or coated finishes for weight-sensitive commercial installations. Weight advantages in high-rise construction offset material cost premiums versus steel in specific urban corridors.
- Fiber-Reinforced Plastic:Composite formulations combining thermoset resins with glass or carbon fiber for extreme corrosion resistance. Utility-scale solar EPC contractors in the southwestern United States specify for direct-burial DC feeder runs where ground movement tolerance outweighs material cost premiums.
By installed base, PVC dominates commercial volume. By specification momentum, fiber-reinforced plastic is gaining share fastest in outdoor utility applications.
Installation Method:
Customer type and project scale dictate installation approach, with data center and healthcare verticals driving pre-fabricated adoption while residential and light commercial remains captive to traditional field-installed methods.
- Pre-Fabricated:Factory-assembled conduit runs with integrated junction boxes, supports, and termination hardware delivered to site for drop-in installation. Skilled electrician shortages in Texas and California commercial construction compress on-site labor hours and reduce warranty exposure for contractors. Direct manufacturer relationships bypass traditional wholesale channels for bundled material-plus-digital-takeoff offerings.
- Underground:Direct-burial or concrete-encased installations requiring crush-resistant and moisture-barrier specifications. Utility infrastructure and petrochemical facility construction in Louisiana and Texas corridors concentrate demand.
- Surface-Mounted:Exposed wall or ceiling routing with clamp-supported systems for accessible maintenance. Commercial renovation work and industrial facility upgrades specify through electrical contractors facing compressed schedule windows.
- Exposed:Open architectural routing where aesthetic finish and bend precision are visible inspection points. Retail and hospitality verticals in urban United States markets specify premium metallic finishes.
By project count, surface-mounted leads. By labor cost compression, pre-fabricated is climbing the fastest.
End User:
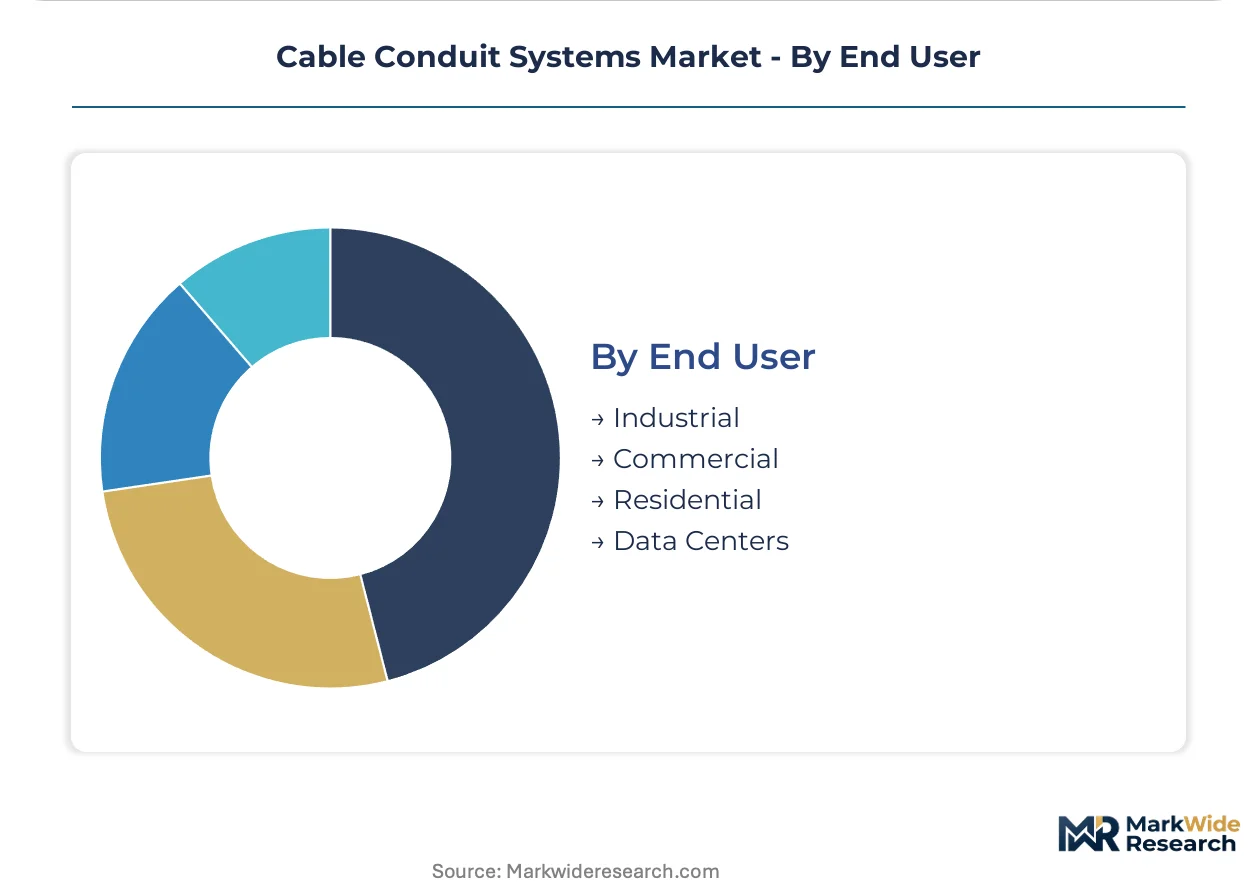
Application-specific code requirements create distinct procurement behaviors, with industrial and data center segments demanding specification-grade certification continuity while residential remains price-driven and fragmented.
- Data Centers:Hyperscale and colocation facilities requiring liquid-tight and rigid specifications for power distribution and fiber-optic backbone routing with 99.999% uptime liability. United States and Germany construction acceleration concentrates procurement authority with integrated manufacturers offering just-in-time staging.
- Industrial:Petrochemical, manufacturing, and utility facilities where NFPA 70 NEC enforcement and OSHA electrical safety directives mandate UL-listed heavy-wall specifications. Gulf Coast corridor expansion creates geographic demand clustering with limited qualified local supply.
- Commercial:Office, retail, healthcare, and education buildings where modular pre-fabricated assemblies reduce on-site labor exposure. Journeyman electrician shortages extend project schedules and increase contractor warranty risk.
- Residential:Single-family and multi-family construction where PVC dominates for cost-sensitive above-ground routing. Price-driven procurement through wholesale distributors with minimal specification engineering support.
By revenue concentration, data centers lead. By specification intensity, industrial maintains the steepest premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in cable conduit systems tilt toward import dependency in markets lacking integrated steel production, while export-oriented manufacturers in Germany and the United States capture premium specification share through captive testing laboratories and just-in-time staging capabilities.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth accelerates liquid-tight and rigid conduit procurement for power distribution backbone routing. NFPA 70 National Electrical Code enforcement by municipal inspectors locks out uncertified imports from infrastructure bid channels. Gulf Coast petrochemical corridor expansion in Louisiana and Texas concentrates demand for explosion-proof specifications where qualified local supply remains limited.
Germany
Offshore wind installation in Danish and Norwegian waters drives specification of corrosion-resistant metallic conduit for subsea cable protection and turbine nacelle wiring. ECHA REACH Annex XVII restrictions on phthalate plasticizers force PVC compound reformulation, creating first-mover advantage for manufacturers with pre-certified calcium-zinc alternatives. Industrial distributors in Frankfurt and Hamburg prioritize CE-marked inventory with documented substance compliance.
China
Utility-scale solar EPC deployment in western provinces accelerates direct-burial HDPE conduit adoption for DC feeder runs where trenching tolerance outweighs material cost premiums. GB standards enforcement by the national standardization administration tightens product certification requirements for domestic infrastructure projects. Manufacturing clusters in Jiangsu and Zhejiang provinces supply export markets while facing structural exclusion from North American UL-listed procurement channels.
India
Commercial construction acceleration in Maharashtra and Karnataka drives flexible conduit demand for retrofit electrical routing in data center and healthcare verticals. BIS certification requirements for electrical raceway products compress specification windows for uncertified imports in government-funded infrastructure. Mumbai and Bangalore electrical contractors face skilled installation labor scarcity extending project schedules.
Brazil
Industrial facility modernization in São Paulo and Rio de Janeiro states sustains rigid steel conduit demand for petrochemical and manufacturing zone upgrades. ANVISA-equivalent electrical safety enforcement through national standardization bodies elevates compliance costs for specification-grade procurement. Local distributors in the Southeast region struggle with steel price volatility transmitted from global hot-rolled coil markets.
Cable Conduit Systems Market Key Industry Players
Listed leaders compete with private specialists across certification continuity and specification engineering capabilities, producing a tiered structure where integrated manufacturers with captive testing laboratories capture premium infrastructure share while regional fabricators compete on price in residential and light commercial segments. Three archetypes dominate: steel-integrated producers controlling raw material cost exposure, electrical distribution bundlers anchoring specification-grade procurement, and modular pre-fabrication specialists compressing on-site labor hours. Competitive moves concentrate on backward integration into scrap supply or rolling mill capacity, and direct manufacturer relationships bypassing traditional wholesale channels for bundled digital takeoff and staging services.
Within the integrated manufacturing tier, Atkore International and Schneider Electric exemplify archetypes combining material production control with specification engineering support. Legrand occupies a position representing modular assembly specialists targeting labor-scarce commercial construction verticals. These three entities anchor distinct competitive vectors: captive steel supply, low-voltage distribution system bundling, and factory-built conduit runs with integrated termination hardware.
| Leading Market Players |
|---|
| Atkore International |
| Schneider Electric |
| Legrand |
| Hubbell Incorporated |
| ABB |
| Eaton Corporation |
| Aliaxis Group |
| Dura-Line Holdings |
| Champion Fiberglass |
| Others |
Cost & Logistics Intelligence
Ninety-day mill lead times for hot-rolled coil translate directly into distributor pricing power across Gulf Coast petrochemical corridors, where integrated manufacturers with captive rolling capacity command premium capture over import-dependent competitors facing volatile scrap arbitrage.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on UL certification tier and volume scale, with specification-grade rigid conduit carrying 40-60% premiums over uncertified alternatives. Pricing pressure stems from steel input cost compression in commodity-grade segments, while data center contractors show lowest price sensitivity due to uptime liability exposure and compressed construction schedules.
Supply Chain Analysis
China and the United States anchor global conduit fabrication, with German and Indian manufacturers serving regional specification-grade niches. Raw material flows draw from hot-rolled coil mills, PVC resin compounders, and aluminum smelters concentrated in Jiangsu province and the American Midwest. Supply chain risk centers on tariff exposure for Chinese finished goods entering North American infrastructure channels. Distribution runs through industrial distributors for petrochemical verticals and electrical wholesalers serving commercial construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cable conduit procurement is recovering from cyclical steel price troughs, with hyperscale data center construction serving as the primary demand accelerator across the United States and Germany.
For Market Incumbents: Consolidate specification-grade certification continuity by deepening captive testing laboratory capacity ahead of NFPA 70 code cycle transitions. Secure long-term scrap supply contracts or backward integration into rolling mill capacity to defend margin stability against hot-rolled coil volatility. Channel control through direct manufacturer relationships with digital takeoff bundling locks out price-driven wholesale competitors in Texas and California commercial verticals. For New Entrants and Emerging Players: Prefabricated modular assembly services represent the most penetrable white space, with journeyman electrician shortages in commercial construction creating acute labor-hour compression demand. Target data center and healthcare verticals in the American Southwest where compressed schedules reward single-source accountability over multi-vendor sourcing. Go-to-market positioning should emphasize factory-built conduit runs with integrated termination hardware and just-in-time staging capabilities. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pre-fabricated conduit assembly segments as factory automation and digital takeoff tooling requirements escalate. Long-term viability favors integrated manufacturers with captive steel production and specification engineering capabilities over pure-play distributors facing channel compression. Watch for inflection signals in municipal inspector enforcement patterns for NFPA 70 NEC compliance, which structurally exclude uncertified imports and concentrate procurement authority among domestic integrated players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Production | Captive hot-rolled coil supply insulates margin stability from commodity volatility in Gulf Coast petrochemical corridors. |
| Pre-Fabricated Modular Assembly Capacity | Factory-built conduit runs compress on-site labor hours for contractors facing electrician shortages in Texas and California. |
| Certification Laboratory Investment | UL-listed testing continuity locks out uncertified imports from North American infrastructure bid channels ahead of code cycles. |
| Direct Manufacturer Channel Bypass | Digital takeoff tools bundled with material supply disintermediate traditional wholesale relationships in data center verticals. |
| REACH-Compliant PVC Reformulation | Calcium-zinc stabilizer packages capture specification share while competitors face 18-24 month ECHA requalification timelines. |
Research Approach
Initial hypotheses were tested against primary input from electrical contractors, industrial procurement managers, specification engineers at EPC firms, and distributor inventory planners, then refined through secondary validation against customs trade data, SEC 10-K filings, NFPA code cycle documentation, and ECHA substance restriction databases. Bottom-up volume estimates triangulated with top-down spending pattern analysis across the analysis window.
Variance decomposition separated volume drivers by material type, installation method, end-use vertical, and geographic regulatory cluster to isolate specification-grade premium capture from commodity substitution effects. CAGRs were derived from installed base growth rates and replacement cycle timing, with steel price elasticity and data center construction permit flows serving as industry-specific forecast inputs throughout the projection horizon.
Underlying assumptions cover continued NFPA 70 NEC enforcement stringency and ECHA REACH Annex XVII compliance timelines, with deviation risk concentrated in steel tariff policy shifts and municipal inspector resource constraints. Recalibration cycles align with material shifts in hyperscale data center capex announcements and National Electrical Code adoption patterns across major metropolitan jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Pedestal Boom System Market
Material Handling Equipment
Global Rolling Mill Rolls Market
Material Handling Equipment
Global Screw Conveyors Market
Material Handling Equipment
Hoist Market
Material Handling Equipment
Global Bucket Loader Market
Material Handling Equipment
Wear Plates Market
Material Handling Equipment
Industrial Jacks Market
Material Handling Equipment
Cut-To-Length Line Systems Market
Material Handling Equipment
Low Clearance Loaders Market
Material Handling Equipment
Debris Loaders Market
Material Handling Equipment
Vibrating Feed Conveyors Market
Material Handling Equipment
Machined Springs Market
Material Handling Equipment
Europe Automated Material Handling (AMH) Market
Material Handling Equipment
US and Mexico Metal Stamping Market
Material Handling Equipment
Global Automatic Palletizer and Depalletizer Market
Material Handling Equipment
Asia Pacific Mobile Crane Market