
 Fluid Conveyance Systems Market | 2026-2036
Fluid Conveyance Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Fluid Conveyance Systems Market Analysis
Aftermarket service revenue is tilting toward predictive maintenance contracts as operators seek to minimize unplanned downtime in critical fluid networks. Parker Hannifin leverages its distributed service footprint to capture recurring revenue from industrial hose replacement programs. Eaton anchors its position through integrated hydraulic system diagnostics that extend equipment life cycles. Senior plc competes on aerospace-qualified conduit assemblies where certification barriers protect margin pools.
Fluid conveyance systems encompass the engineered network of pipes, hoses, fittings, and valves designed to transport liquids, gases, and slurries under controlled pressure, temperature, and flow parameters, typically manufactured through extrusion, braiding, forging, or injection molding processes depending on material and duty requirements. These systems serve as the circulatory infrastructure for industrial operations, ensuring safe and efficient media transfer across energy, chemical, water, and manufacturing installations. Hoses and composite material segments are capturing disproportionate growth as weight reduction and corrosion resistance become decisive specification factors in offshore and chemical processing environments. Steel pipes retain volume dominance in municipal water and oil field gathering systems where pressure ratings and decades-long service life remain non-negotiable procurement criteria.
EPA emission standards and OSHA process safety management requirements are tightening specifications for leak-resistant fittings and corrosion monitoring protocols in US fluid handling infrastructure. The EU F-Gas Regulation and REACH chemical restrictions are reshaping material eligibility for seals and liners in European fluid conveyance applications. Stakeholders must monitor evolving regulatory thresholds for fugitive emissions and material traceability as these specifications increasingly determine supplier qualification and contract eligibility.
Market Dynamics
EPA methane emission rules under the Clean Air Act are compelling pipeline operators to replace legacy steel infrastructure with advanced composite conveyance, compressing replacement cycles and reshaping supplier qualification criteria across North American energy infrastructure.
Growth Catalysts
- Shale field development:Permian Basin operators are pulling demand for high-pressure hose assemblies as hydraulic fracturing operations expand. Federal infrastructure spending accelerates municipal water system replacement cycles.
- REACH chemical restrictions:The EU F-Gas Regulation and REACH framework are reshaping material eligibility for seals and liners in European fluid conveyance applications, opening specification windows for compliant alternatives.
- Composite material adoption:Weight reduction and corrosion resistance specifications are becoming decisive factors in offshore and chemical processing environments, favoring engineered polymer systems over traditional metallics.
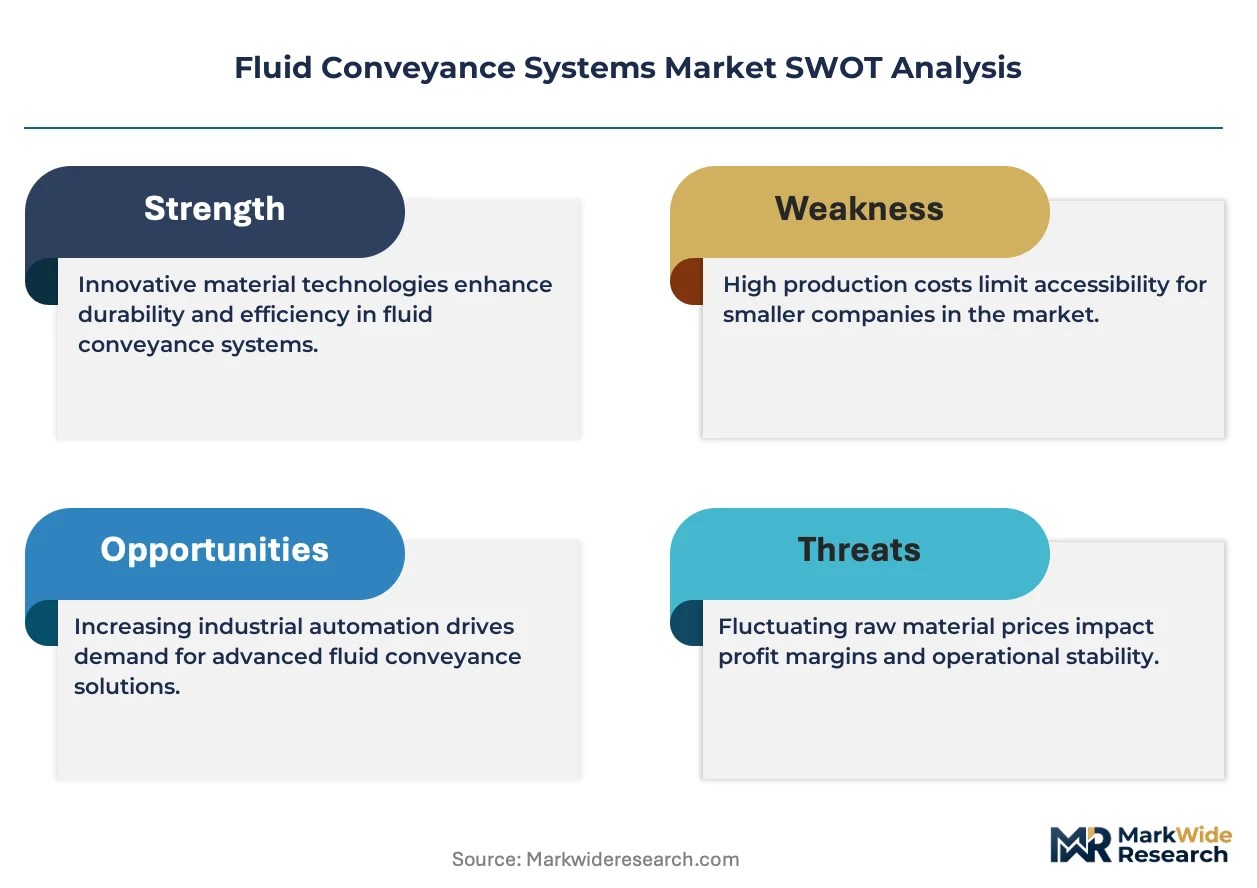
Market Restraints
- Steel price volatility:Carbon steel and stainless steel input costs fluctuate with global scrap metal and alloying element markets, compressing margin stability for pipe manufacturers serving municipal water and oil field gathering systems.
- Specialized resin supply concentration:High-performance fluoropolymer and thermoplastic elastomer feedstock production concentrates among a limited supplier base in Germany and Japan, creating vulnerability for composite hose producers.
- Legacy infrastructure lock-in:Decades-long service life ratings for installed steel piping systems delay replacement decisions even where advanced composites offer superior total cost of ownership.
Strategic Opportunities
- Predictive maintenance contracts:Aftermarket service revenue is tilting toward condition-monitoring agreements as operators seek to minimize unplanned downtime in critical fluid networks, creating recurring revenue streams.
- OSHA process safety management alignment:Tightening specifications for leak-resistant fittings and corrosion monitoring protocols create qualification advantages for suppliers with integrated diagnostics capabilities.
- Hydrogen conveyance infrastructure:Emerging hydrogen energy systems require specialized high-pressure hose and piping assemblies rated for embrittlement resistance and permeation control.
Industry Challenges
- Certification timeline compression:Aerospace-qualified conduit assemblies require extensive qualification protocols that extend sales cycles and strain engineering resources for tier-two suppliers.
- Integration complexity:Advanced composite systems must interface with legacy steel infrastructure using hybrid fitting technologies that add engineering cost and field installation risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluid Conveyance Systems Market |
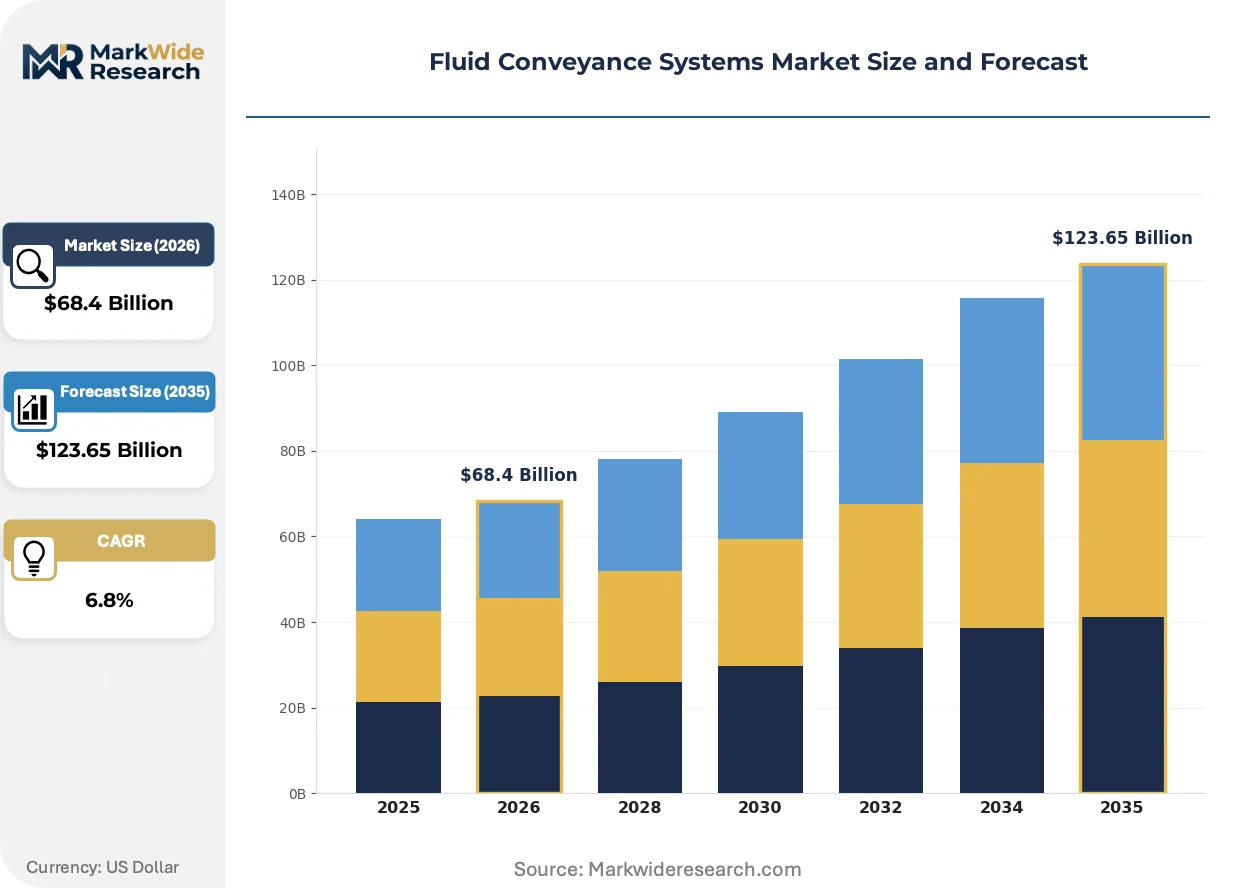
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pipes, Hoses, Fittings, Valves Material: Plastic, Steel, Rubber, Composite Application: Oil & Gas, Water Treatment, Chemical Processing, Agriculture End User: Manufacturing, Construction, Energy, Municipal |
| Companies Covered | Senior plc, PFW Aerospace, Parker Hannifin, Smiths Group, ITT Inc, Eaton, Unison, Titeflex, Flexfab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluid Conveyance Systems Market Emerging Trajectories
Material science advances and regulatory stringency are converging to reshape fluid conveyance specifications, with performance standards migrating toward corrosion resistance and emission containment rather than pressure rating alone.
Thermoplastic composite piping is migrating from niche chemical service applications into mainstream oil and gas gathering systems. Offshore platform operators in the Gulf of Mexico are specifying filament-wound reinforced thermoplastic pipe for subsea tiebacks and topside process piping. This technology is migrating from specialized corrosion-resistant niches into volume applications, compressing the addressable market for traditional carbon steel line pipe in moderate-pressure service.
The EPA's methane emission standards under the Clean Air Act are mandating leak detection and repair protocols that exceed legacy mechanical joint performance. Pipeline operators must now specify API-qualified compression fittings with enhanced seal geometries and material traceability documentation. Gathering system operators in Texas and New Mexico are responding by consolidating supplier bases toward vendors with integrated fugitive emissions testing capabilities.
Service unbundling is fragmenting traditional supply relationships in industrial hose replacement programs. End-users are separating hose procurement from installation and inspection services, creating openings for specialized field service contractors. This pattern is most visible in United States manufacturing facilities where maintenance outsourcing has compressed direct procurement authority among plant engineers.
Fluid Conveyance Systems Market Segmentation
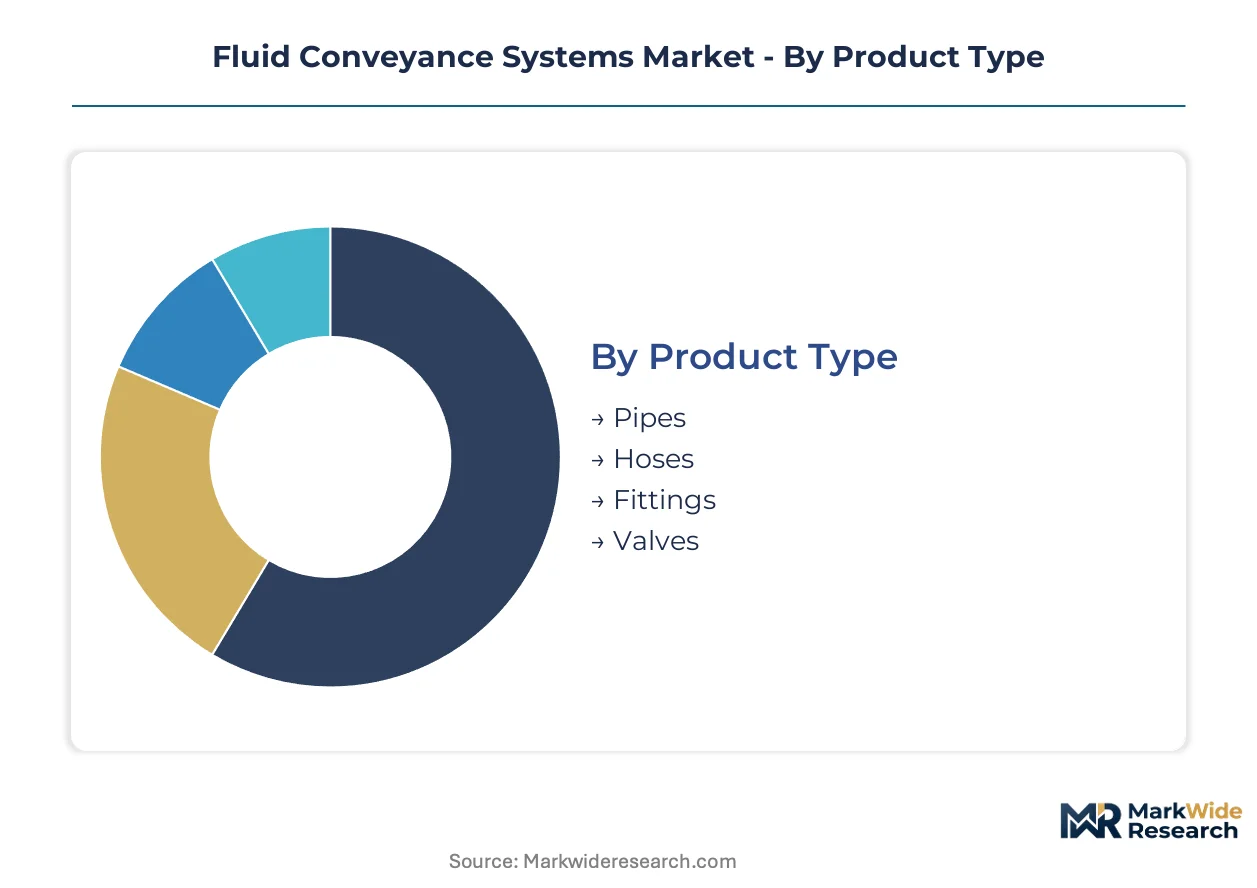
Fluid conveyance systems exhibit distinct replacement cycles and service intensity across product categories. Material selection determines corrosion resistance and pressure ratings. Application environments dictate regulatory compliance requirements.
Product Type:
After-sales-service intensity varies sharply across product types, with hose assemblies requiring frequent inspection and replacement compared to permanent piping infrastructure.
- Pipes:Manufactured through extrusion, forging, or seamless drawing processes to achieve specified pressure ratings and dimensional tolerances. Steel pipes dominate municipal water and oil field gathering systems in the United States where decades-long service life remains a non-negotiable procurement criterion under EPA infrastructure standards.
- Hoses:Constructed from elastomeric compounds reinforced with textile or metallic braiding to accommodate dynamic movement and vibration. High-pressure hose assemblies are pulling disproportionate demand from Permian Basin hydraulic fracturing operators who prioritize flexibility and rapid deployment over permanent installation.
- Fittings:Precision-engineered connection components including couplings, adapters, and flanges that ensure leak-free junctions between conveyance elements.
- Valves:Flow control devices regulating pressure, direction, and isolation within fluid networks through manual or automated actuation mechanisms.
By volume, Pipes leads. By growth pace, Hoses is ahead.
Material:
Cost tier stratification separates premium corrosion-resistant alloys from commodity carbon steel and engineered polymer alternatives.
- Steel:Carbon and stainless steel grades offering superior pressure containment and structural rigidity for high-stress applications. Steel price volatility tied to global scrap metal and alloying element markets compresses margin stability for manufacturers serving United States municipal water systems.
- Composite:Engineered polymer matrices reinforced with glass or carbon fibers delivering weight reduction and chemical resistance. Offshore platform operators in the Gulf of Mexico are specifying filament-wound reinforced thermoplastic pipe for subsea tiebacks where corrosion resistance outweighs initial cost premiums.
- Plastic:Thermoplastic resins including PVC, PE, and PP formulations for low-pressure water distribution and drainage applications.
- Rubber:Natural and synthetic elastomer compounds providing flexibility and abrasion resistance in mobile hydraulic and industrial transfer hoses.
By installed base, Steel dominates. By specification momentum, Composite is expanding most quickly.
Application:
Customer type differentiation separates capital-intensive energy infrastructure from maintenance-driven municipal operations with distinct procurement authority structures.
- Oil & Gas:Exploration, production, gathering, and transmission operations requiring high-pressure containment and sour gas compatibility. EPA methane emission rules under the Clean Air Act are compelling pipeline operators to replace legacy steel infrastructure with advanced composite conveyance, compressing replacement cycles.
- Water Treatment:Municipal and industrial purification, distribution, and wastewater management systems. Federal infrastructure spending is accelerating replacement cycles for aging United States municipal water systems where lead service line remediation drives specification urgency.
- Chemical Processing:Corrosive media handling in refineries, petrochemical plants, and specialty chemical manufacturing facilities.
- Agriculture:Irrigation, fertigation, and livestock watering systems operating at moderate pressures with seasonal usage patterns.
By capital deployment, Oil & Gas leads. By regulatory tailwinds, Water Treatment is gaining share fastest.
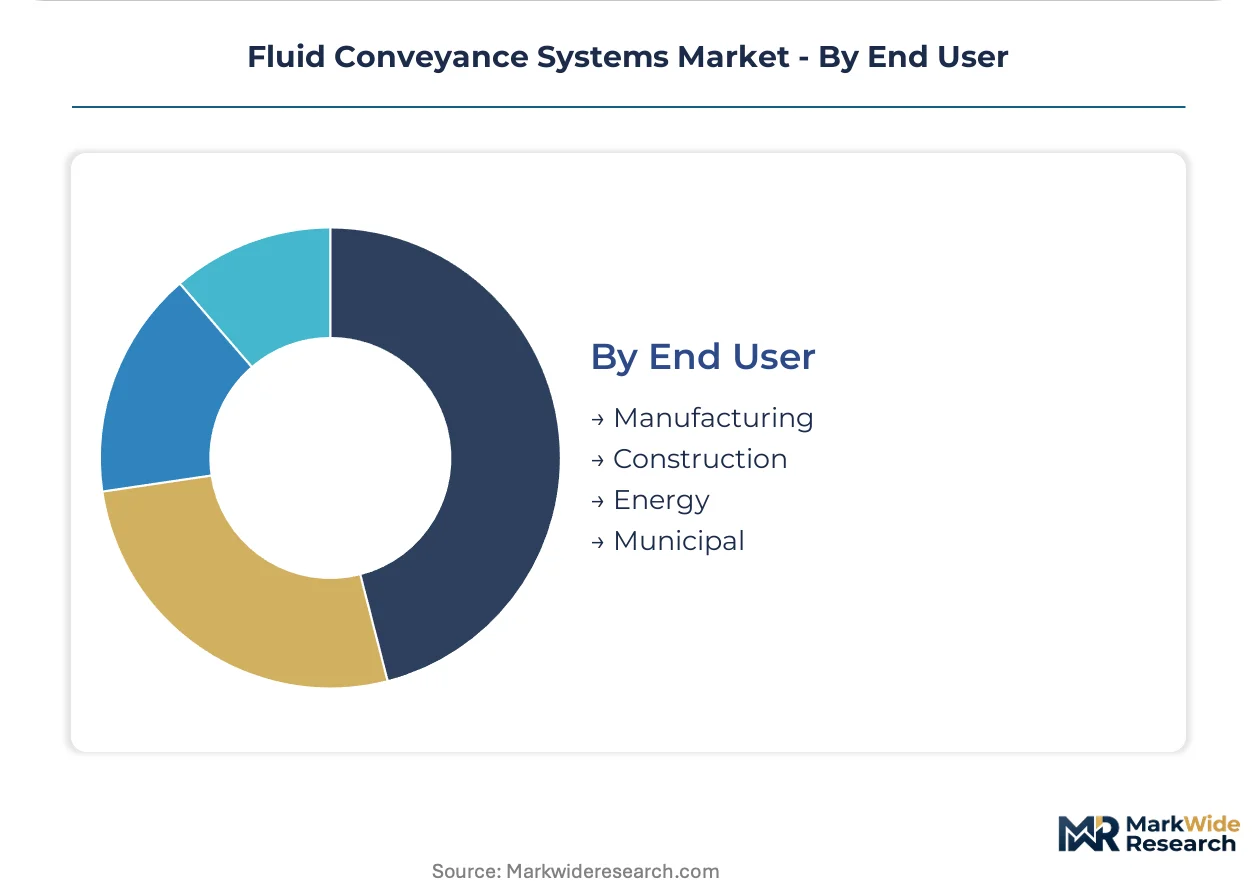
End User:
Geographic concentration within the United States shapes demand patterns, with shale field development in Texas and New Mexico diverting supply capacity from traditional manufacturing centers.
- Energy:Power generation, renewable hydrogen systems, and hydrocarbon extraction operations requiring specialized high-pressure assemblies. Emerging hydrogen energy infrastructure demands hose and piping assemblies rated for embrittlement resistance and permeation control under evolving safety protocols.
- Municipal:Government-owned water, wastewater, and stormwater infrastructure subject to federal procurement regulations and environmental compliance mandates.
- Manufacturing:Industrial production facilities utilizing hydraulic power transmission and process fluid handling systems.
- Construction:Temporary dewatering, concrete pumping, and equipment hydraulic systems with project-based demand cycles.
By contract value, Energy leads. By replacement frequency, Municipal is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for fluid conveyance systems concentrates among German precision fabricators, US shale-field suppliers, and Chinese industrial hose producers. This geographic distribution shapes regional specification standards and replacement cycle timing.
United States
Permian Basin hydraulic fracturing operations pull demand for high-pressure hose assemblies rated above 10,000 psi. EPA methane emission rules under the Clean Air Act compel pipeline operators to replace legacy steel infrastructure with advanced composite conveyance. Houston-area fabricators supply gathering systems across Texas and New Mexico where federal infrastructure spending accelerates municipal water replacement cycles.
Germany
EU F-Gas Regulation and REACH chemical restrictions reshape material eligibility for seals and liners in European fluid conveyance applications. The country's national chemical regulator enforces material traceability documentation that determines supplier qualification. Industrial clusters in North Rhine-Westphalia manufacture fluoropolymer-lined hoses for chemical processing plants across the Rhine-Ruhr region.
China
MIIT industrial standards govern pressure ratings and dimensional tolerances for steel pipe used in municipal water and oil field gathering systems. Dual carbon goals accelerate specification windows for lightweight composite alternatives in offshore platform applications. Yangtze River Delta fabricators export reinforced thermoplastic pipe to Southeast Asian chemical processing installations.
Japan
METI energy efficiency mandates drive demand for leak-resistant fittings in hydrogen conveyance infrastructure under development. JIS standards specify corrosion monitoring protocols that exceed legacy mechanical joint performance requirements. Chubu region manufacturers supply aerospace-qualified conduit assemblies where certification barriers protect margin pools.
India
BIS certification requirements tighten specifications for municipal water distribution piping as federal infrastructure programs expand. The country's national industrial regulator enforces pressure testing protocols for oil and gas gathering systems. Gujarat-based producers serve petrochemical plants in the Dahej and Hazira industrial corridors with corrosion-resistant alloy piping.
Fluid Conveyance Systems Market Vendor Landscape
Diversified industrial conglomerates and specialized aerospace fabricators split the market across distinct specification tiers. Tier-one suppliers anchor positions through integrated hydraulic system diagnostics and predictive maintenance contracts. Tier-two specialists compete on certification depth for aerospace and chemical processing applications. Consolidation pressure intensifies as end-users consolidate supplier bases toward vendors with integrated fugitive emissions testing capabilities.
Within the diversified industrial tier, Parker Hannifin and Eaton occupy positions defined by distributed service footprints and recurring revenue from replacement programs. Senior plc exemplifies the aerospace-specialist archetype where qualification protocols extend sales cycles but protect margin structures. These three companies represent the strategic positioning spectrum from scale-driven aftermarket capture to certification-protected niche dominance.
| Leading Market Players |
|---|
| Senior plc |
| PFW Aerospace |
| Parker Hannifin |
| Smiths Group |
| ITT Inc |
| Eaton |
| Unison |
| Titeflex |
| Flexfab |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese thermoplastic resin production is compressing feedstock pricing power while simultaneously eroding margin buffers for composite hose manufacturers in Germany and Japan who must absorb volatile specialty polymer costs.
Pricing Analysis
Aftermarket service contracts now drive lifetime value capture across fluid conveyance portfolios, with predictive maintenance agreements commanding premium positioning over transactional parts replacement. Pricing stratifies across aerospace-qualified, industrial-grade, and commodity tiers based on certification depth and traceability documentation requirements. Cost compression in standard steel pipe segments is intensifying as scrap metal volatility transmits directly through municipal procurement auctions. Municipal water authorities exhibit highest price sensitivity due to federal budget constraints, while Permian Basin operators prioritize rapid deployment over unit economics.
Supply Chain Analysis
Specialty fluoropolymer feedstock production concentrates in Germany and Japan, with high-performance thermoplastic elastomer supply anchored in the Rhine-Ruhr industrial corridor and Osaka-Kobe manufacturing belt. Composite hose fabrication draws from carbon fiber precursor supply chains in the United States and Taiwan, plus glass fiber rovings from China. Single-source vulnerability runs through German chemical regulators' REACH compliance certification chokepoints. Distribution runs through Houston-area fabricators serving Texas and New Mexico shale fields, plus regional distribution hubs in North Rhine-Westphalia for European chemical processing plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluid conveyance incumbents face sustained substitution pressure from thermoplastic composite piping displacing carbon steel in moderate-pressure oil and gas gathering systems.
For Market Incumbents: Insulate core revenue streams by deepening captive supply of aerospace certification capabilities and expanding predictive maintenance contract penetration across Permian Basin operator accounts. Vertical integration into fluoropolymer compounding mitigates German and Japanese feedstock concentration risk. Certification investment in EPA methane-compliant fitting geometries defends specification position against composite system encroachment. For New Entrants and Emerging Players: Build out hydrogen conveyance infrastructure capabilities ahead of METI-mandated deployment timelines in Japan, where embrittlement-resistant assembly standards remain underpenetrated by established suppliers. Target field service contractor relationships in United States manufacturing facilities where maintenance outsourcing has fragmented direct procurement authority. White-space exists in integrated fugitive emissions testing services for Texas and New Mexico pipeline consolidation trends. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across aerospace-qualified conduit assembly segments where qualification protocol timelines extend working capital cycles. Long-term viability favors targets with established EPA, REACH, and BIS certification portfolios spanning multiple regulatory jurisdictions. Acquisition archetype: mid-cap specialists with backward integration into polymer compounding and forward integration into predictive maintenance platforms. Signal to watch: Permian Basin operator consolidation patterns indicating supplier base rationalization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Compounding | Mitigates German and Japanese feedstock concentration risk for composite hose producers. |
| Predictive Maintenance Contract Expansion | Captures recurring revenue from Permian Basin operators seeking to minimize unplanned downtime. |
| Hydrogen Conveyance Certification Investment | Positions suppliers for METI-mandated embrittlement-resistant assembly standards in Japan. |
| Aerospace Qualification Protocol Acceleration | Compresses sales cycles for tier-two suppliers competing against Senior plc margin protection. |
| Integrated Fugitive Emissions Testing Capability | Qualifies vendors for EPA methane rule compliance in Texas and New Mexico pipeline consolidation. |
Methodological Framework
Initial hypotheses were tested against primary input from maintenance directors at Permian Basin operators, procurement leads at municipal water authorities, plant engineers in Gulf of Mexico offshore platforms, and aftermarket service heads at industrial hose distributors, then refined against secondary validation from EPA enforcement databases, FERC infrastructure filings, ACC chemical industry reports, and customs trade data for fluoropolymer imports. Bottom-up demand modeling triangulated against top-down supply capacity assessments across German, Japanese, and Chinese manufacturing clusters.
Demand-supply balance dynamics across product type, material grade, application environment, and end-user procurement structure shaped the analytical framework over the projection horizon. CAGRs were derived from replacement cycle timing analysis, regulatory compliance deadline clustering, and capital deployment patterns in shale field development and federal infrastructure programs. Industry-specific forecast inputs included hydraulic fracturing activity indices for the Permian Basin and lead service line remediation timelines under EPA infrastructure standards.
Stress conditions across steel scrap metal volatility, REACH chemical restriction enforcement intensity, and hydrogen infrastructure deployment pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and substitution elasticity between composite and metallic systems. Cross-checking against EIA drilling activity benchmarks and BIS certification issuance rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Dewatering Equipment Market
Material Handling Equipment
Global Large Conveyor Chain Market
Material Handling Equipment
Automated Material Handling (AMH) Market
Material Handling Equipment
Industrial Bag Dust Filter Market
Material Handling Equipment
Crate Handling Systems Market
Material Handling Equipment
Industrial Counterweights Market
Material Handling Equipment
Chute Liners Market
Material Handling Equipment
Die Casting Market
Material Handling Equipment
Robotic Palletizers Market
Material Handling Equipment
Australia and New Zealand Industrial Fasteners Market
Material Handling Equipment
Vertical Reciprocating Conveyor Market
Material Handling Equipment
Crane Mats Market
Material Handling Equipment
Telehandler Market
Material Handling Equipment
Eye and Eye Turnbuckle Market
Material Handling Equipment
Automatic Conveyor Market
Material Handling Equipment
Europe Conveyors Market