
 Asia Pacific Automated Material Handling and Storage Systems Market | 2026-2036
Asia Pacific Automated Material Handling and Storage Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Automated Material Handling and Storage Systems Market Outlook
High-bay AS/RS configurations with throughput exceeding 150 dual cycles per hour is redrawing competitive benchmarks for warehouse density and labor substitution. Daifuku leverages its captive production of stacker cranes to control delivery timelines across Japan and Southeast Asia. Geekplus specializes in swarm robotics for piece-picking, occupying a distinct tier below traditional pallet-handling systems. Murata Machinery anchors regional supply through its integrated conveyor and sorter manufacturing footprint in East Asia.
Automated material handling and storage systems encompass electromechanical equipment, control software, and sensor networks that transport, sort, and store goods with minimal human intervention, typically operating at throughputs of 50 to 400 cycles per hour depending on crane speed and rack configuration. Their primary purpose is to compress inventory dwell time and eliminate picking errors in high-SKU environments. Conveyor systems and AS/RS retain the largest installed base across the Asia Pacific, though automated guided vehicles represent the fastest expansion trajectory as lithium-ion traction batteries extend continuous runtime. Robotics and machine vision technologies command premium pricing due to integration complexity and commissioning requirements.
Japan's METI enforces industrial energy conservation standards that shape equipment procurement specifications, while China's SAMR oversees GB standards for automated machinery safety and electromagnetic compatibility. Australia's TGA and WorkSafe frameworks indirectly influence pharmaceutical warehouse validation requirements for automated storage. Stakeholders must weigh modular installation approaches against custom-built retrofits as facility lease structures shorten across the region.
Market Dynamics
Japan's METI energy-efficiency mandates are compressing procurement timelines for electrified equipment across warehouse operators, forcing rapid replacement of diesel-powered fleets with lithium-ion alternatives.
Growth Catalysts
- E-commerce fulfillment density:Southeast Asian logistics hubs are deploying robotic sortation systems to process same-day delivery volumes exceeding 500,000 parcels per facility.
- Dual carbon targets:China's MEE enforcement of carbon intensity benchmarks is accelerating AS/RS installations in Yangtze River Delta manufacturing corridors to reduce per-unit storage energy consumption.
- Machine vision integration:Smart factory investments are converging automated storage with real-time quality inspection, eliminating manual rework stations in high-SKU electronics assembly.
Market Restraints
- Lithium supply concentration:Battery cell manufacturing for AGV traction systems concentrates in Chinese and South Korean suppliers, exposing procurement to raw material price volatility.
- Stagnant conveyor margins:Standard belt and roller systems face commoditization pressure from regional fabricators in Vietnam and Indonesia, eroding pricing power for established vendors.
- GB standard fragmentation:China's SAMR maintains separate electromagnetic compatibility certifications for port equipment versus intralogistics machinery, duplicating compliance costs for multi-application vendors.
Strategic Opportunities
- Cold chain underpenetration:India's pharmaceutical distribution network retains 60% manual handling, creating white space for temperature-controlled AS/RS as CDSCO serialization mandates expand.
- Swarm robotics convergence:Piece-picking algorithms and AMR navigation stacks are merging, enabling heterogeneous robot fleets that share charging infrastructure and traffic management.
- Australian TGA validation:Therapeutic goods warehousing requirements for batch traceability are driving premium automation contracts in Sydney and Melbourne distribution corridors.
Industry Challenges
- Commissioning specialist scarcity:Systems integrators with combined mechanical, PLC, and machine vision expertise command 40% salary premiums, constraining deployment velocity.
- Legacy WMS integration:Brownfield facilities running 1990s-era warehouse management software require middleware development that extends project timelines by 4-8 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Automated Material Handling and Storage Systems Market |
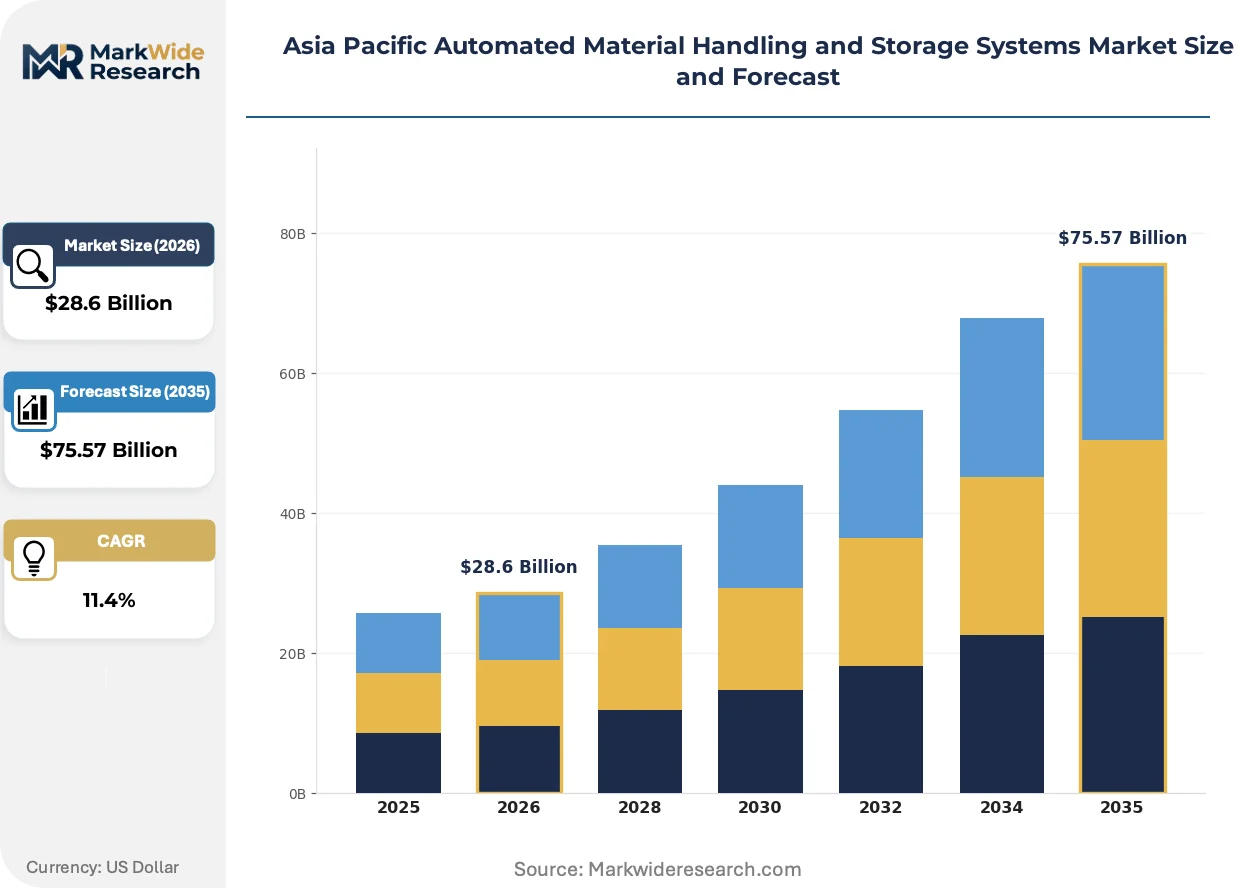
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conveyor Systems, AS/RS, Automated Guided Vehicles, Sortation Systems Technology: Robotics, IoT, Machine Vision, Artificial Intelligence End User: Manufacturing, E-commerce, Food & Beverage, Pharmaceuticals Installation: On-site, Modular, Custom-built, Retrofitted |
| Companies Covered | Daifuku, Swisslog, Geekplus, Vanderlande, Dematic, VisionNav Robotics, Murata Machinery, SSI Schaefer, GreyOrange, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Automated Material Handling and Storage Systems Market Strategic Shifts
Sensor fusion and edge computing architectures are compressing decision latency in automated handling equipment, enabling real-time path optimization without centralized server dependency.
Photoelectric and laser triangulation sensors for pallet dimensioning is miniaturizing from rack-mounted units to crane-integrated modules. Japanese automotive parts distributors are adopting these compact systems at 200% year-over-year rates. The technology is miniaturizing footprint requirements for high-bay facilities, allowing 18-meter clear heights in retrofitted structures previously limited to 12 meters.
METI's 2024 revision to industrial energy conservation standards tightens standby power limits for material handling equipment. Warehouse operators in Osaka and Nagoya corridors are pre-emptively specifying regenerative braking and smart sleep modes in procurement tenders. Electrified AGV categories face the steepest compliance deadlines, with full fleet conversion required by 2027.
Third-party logistics providers are unbundling automation-as-a-service from traditional equipment purchase models. Regional 3PLs in Thailand and Malaysia are leasing robotic sortation capacity by throughput tier rather than capital expenditure. This shift is most visible in Bangkok's e-commerce fulfillment cluster, where facility operators trade fixed asset ownership for per-scan pricing indexed to parcel volume volatility.
Asia Pacific Automated Material Handling and Storage Systems Market Segmentation
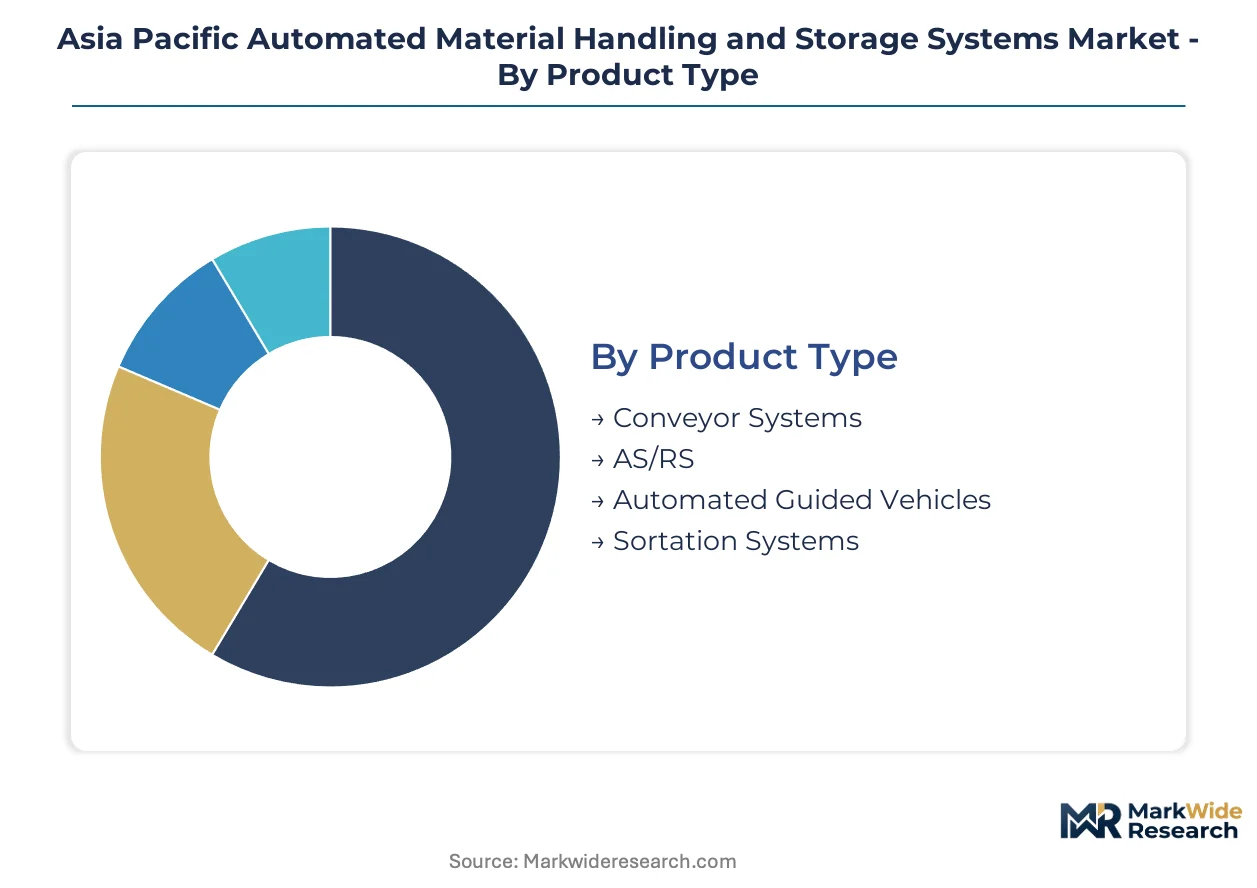
Segmentation in automated material handling reveals where capital deployment concentrates versus where emerging technologies are displacing legacy infrastructure. Procurement patterns across Asia Pacific diverge sharply between established manufacturing corridors and greenfield e-commerce fulfillment zones.
Product Type:
Conveyor systems face the most acute substitution pressure as robotic sortation and AGV fleets capture greenfield projects with higher labor substitution ratios.
- Conveyor Systems:Belt and roller configurations dominate brownfield installations across Vietnam and Indonesia. Standardized designs from regional fabricators are compressing margins for established vendors serving legacy automotive assembly plants.
- AS/RS:High-bay crane-based storage with throughput exceeding 150 dual cycles per hour is displacing conventional racking in China's Yangtze River Delta electronics manufacturing corridors. Smart factory investments integrate these systems with machine vision quality gates to eliminate manual rework stations.
- Automated Guided Vehicles:Lithium-ion traction batteries extend continuous runtime beyond 16 hours. Japan's METI energy-efficiency mandates are forcing Osaka and Nagoya warehouse operators toward full fleet electrification.
- Sortation Systems:Robotic parcel handling processes same-day delivery volumes exceeding 500,000 parcels per facility in Bangkok and Singapore e-commerce hubs.
Conveyor systems anchor the volume base while AS/RS gains share at the steepest rate.
Technology:
Cost tier differentiation separates premium-integrated technology stacks from standalone sensor modules in procurement specifications.
- Robotics:Swarm algorithms for piece-picking are converging with AMR navigation stacks to enable heterogeneous fleets sharing charging infrastructure. Geekplus and similar vendors occupy a distinct tier below traditional pallet-handling systems in Southeast Asian fulfillment centers.
- IoT:Sensor networks for predictive maintenance command premium pricing due to integration complexity with legacy warehouse management software. Brownfield facilities require middleware development extending project timelines.
- Machine Vision:Photoelectric and laser triangulation sensors miniaturize from rack-mounted units to crane-integrated modules. Japanese automotive parts distributors adopt these compact systems at accelerating rates.
- Artificial Intelligence:Edge computing architectures compress decision latency for real-time path optimization without centralized server dependency.
Machine vision commands the highest integration premiums while AI expands most quickly into greenfield specifications.
End User:
Application maturity varies dramatically across verticals, with pharmaceuticals and food & beverage presenting divergent compliance and throughput requirements.
- Manufacturing:Smart factory investments in China's Yangtze River Delta integrate AS/RS with real-time quality inspection. Dual carbon targets from China's MEE accelerate installations to reduce per-unit storage energy consumption.
- E-commerce:Southeast Asian logistics hubs deploy robotic sortation to process explosive parcel growth. Thailand and Malaysia 3PLs are unbundling automation-as-a-service from traditional equipment purchase models.
- Food & Beverage:Temperature-controlled automation remains underpenetrated relative to ambient storage across India and Southeast Asia.
- Pharmaceuticals:Australia's TGA validation requirements for batch traceability drive premium automation contracts in Sydney and Melbourne distribution corridors. India's CDSCO serialization mandates are expanding addressable market for cold chain AS/RS.
Manufacturing anchors the volume base while pharmaceuticals gains share at the steepest rate.
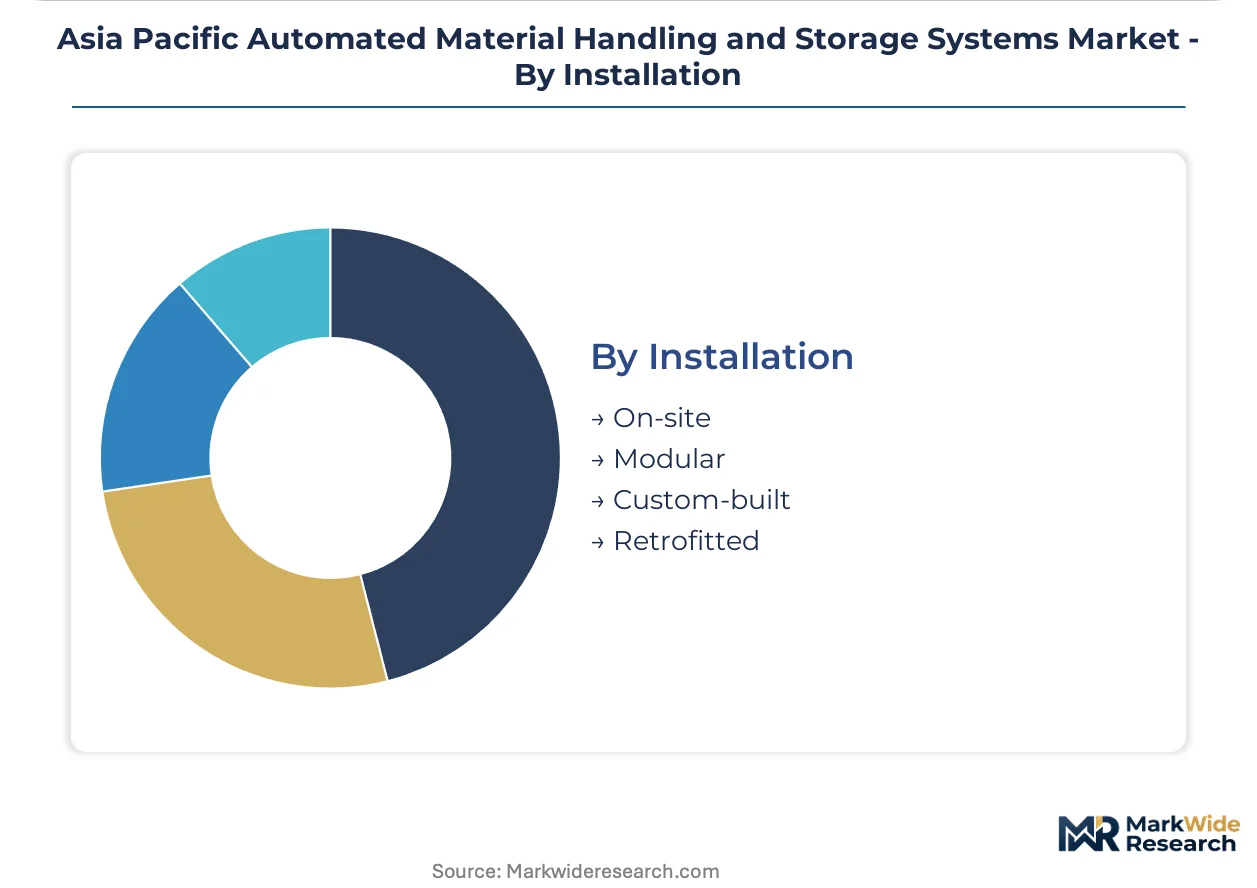
Installation:
Customer type and facility lease structures are shifting procurement toward modular approaches that preserve capital flexibility.
- On-site:Traditional fixed installations persist in owned facilities with 15-plus year depreciation horizons. Japanese automotive parts distributors favor this model for high-throughput assembly feed operations.
- Modular:Pre-engineered subsystems reduce commissioning time for 3PL operators facing parcel volume volatility. Bangkok's e-commerce cluster trades fixed asset ownership for per-scan pricing indexed to throughput tiers.
- Custom-built:Tailored retrofits for brownfield structures previously limited to 12-meter clear heights now achieve 18-meter specifications through compact crane-integrated sensor modules.
- Retrofitted:Legacy WMS integration challenges extend project timelines by 4-8 months for facilities running 1990s-era software.
On-site installations anchor the volume base while modular approaches gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for lithium-ion traction batteries shapes procurement timelines across warehouse operators, while export-oriented manufacturing corridors drive automation density in intra-Asia trade lanes. Equipment flows concentrate through Singapore and Hong Kong logistics hubs before distribution to national markets.
China
Smart factory investments in the Yangtze River Delta integrate AS/RS with machine vision quality gates. SAMR enforces GB standards for electromagnetic compatibility and automated machinery safety. Shanghai and Suzhou manufacturing clusters process electronics exports through high-bay configurations exceeding 150 dual cycles per hour.
Japan
Automotive parts distributors in Osaka and Nagoya corridors adopt compact crane-integrated sensor modules at accelerating rates. METI's 2024 revision to industrial energy conservation standards tightens standby power limits for material handling equipment. Kanto and Kansai warehouse operators face full fleet electrification deadlines by 2027.
India
Pharmaceutical distribution retains 60% manual handling, creating white space for temperature-controlled AS/RS deployment. CDSCO serialization mandates expand validation requirements for batch traceability. Mumbai and Ahmedabad distribution corridors attract premium automation contracts as cold chain infrastructure modernizes.
Australia
Therapeutic goods warehousing requirements under TGA frameworks drive premium automation specifications. Sydney and Melbourne distribution corridors prioritize modular installation approaches to preserve capital flexibility against lease structure volatility. Per-scan pricing models gain traction among 3PL operators managing parcel volume fluctuations.
Southeast Asia
E-commerce fulfillment centers in Bangkok and Singapore deploy robotic sortation systems processing same-day delivery volumes exceeding 500,000 parcels per facility. Thailand and Malaysia 3PLs unbundle automation-as-a-service from traditional equipment purchase models. Regional fabricators in Vietnam and Indonesia compress margins on standardized conveyor configurations.
Asia Pacific Automated Material Handling and Storage Systems Market Competitive Environment
Concentration sits with integrated stacker crane manufacturers and swarm robotics specialists serving distinct throughput tiers. Japanese and European incumbents control captive production of high-bay crane systems, while Chinese vendors occupy the piece-picking automation segment below traditional pallet-handling thresholds. Strategic moves center on modular service unbundling and energy-efficiency certification pre-emption ahead of regulatory deadlines.
Among Japanese integrated manufacturers, Daifuku and Murata Machinery exemplify the crane-captive archetype with regional production footprints anchoring supply security. Geekplus occupies the swarm robotics tier for piece-picking applications, representing the Chinese specialist model that converges AMR navigation with heterogeneous fleet management. These three anchors illustrate how competitive positioning splits between pallet-density maximization and labor substitution at the item level.
| Leading Market Players |
|---|
| Daifuku |
| Swisslog |
| Geekplus |
| Vanderlande |
| Dematic |
| VisionNav Robotics |
| Murata Machinery |
| SSI Schaefer |
| GreyOrange |
| Others |
Value Chain & Pricing Dynamics
Lithium-ion traction battery substitution for lead-acid and diesel powertrains is simultaneously redrawing procurement geography toward Chinese and South Korean cell manufacturers and compressing pricing power for traditional equipment vendors serving Japanese and Australian warehouse operators.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium certified systems, standard integrated configurations, and economy modular units. Price differentiation separates METI-compliant energy-efficient equipment from legacy diesel-powered alternatives, with certification tier and after-sales service bundling as primary drivers. Cost compression in standard conveyor configurations is intensifying because regional fabricators in Vietnam and Indonesia are eroding margin pools for established Japanese and European vendors. Price sensitivity concentrates among Thailand and Malaysia 3PL operators leasing automation-as-a-service, while Australian pharmaceutical distributors under TGA validation requirements exhibit minimal price elasticity.
Supply Chain Analysis
China and South Korea anchor lithium-ion cell manufacturing for AGV traction systems, with Japan retaining captive production of high-bay stacker crane components. Battery supply draws from nickel-cobalt-manganese cathode chemistries and rare-earth permanent magnet motors, creating raw material dependencies on Indonesian nickel and Australian lithium spodumene. Single-source vulnerability concentrates in Chinese electrolyte and separator production, exposing procurement timelines to export restriction risk. Distribution runs through Singapore and Hong Kong logistics hubs before national market allocation, with regional 3PLs in Bangkok and Kuala Lumpur adopting per-scan pricing models that shift inventory risk upstream.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
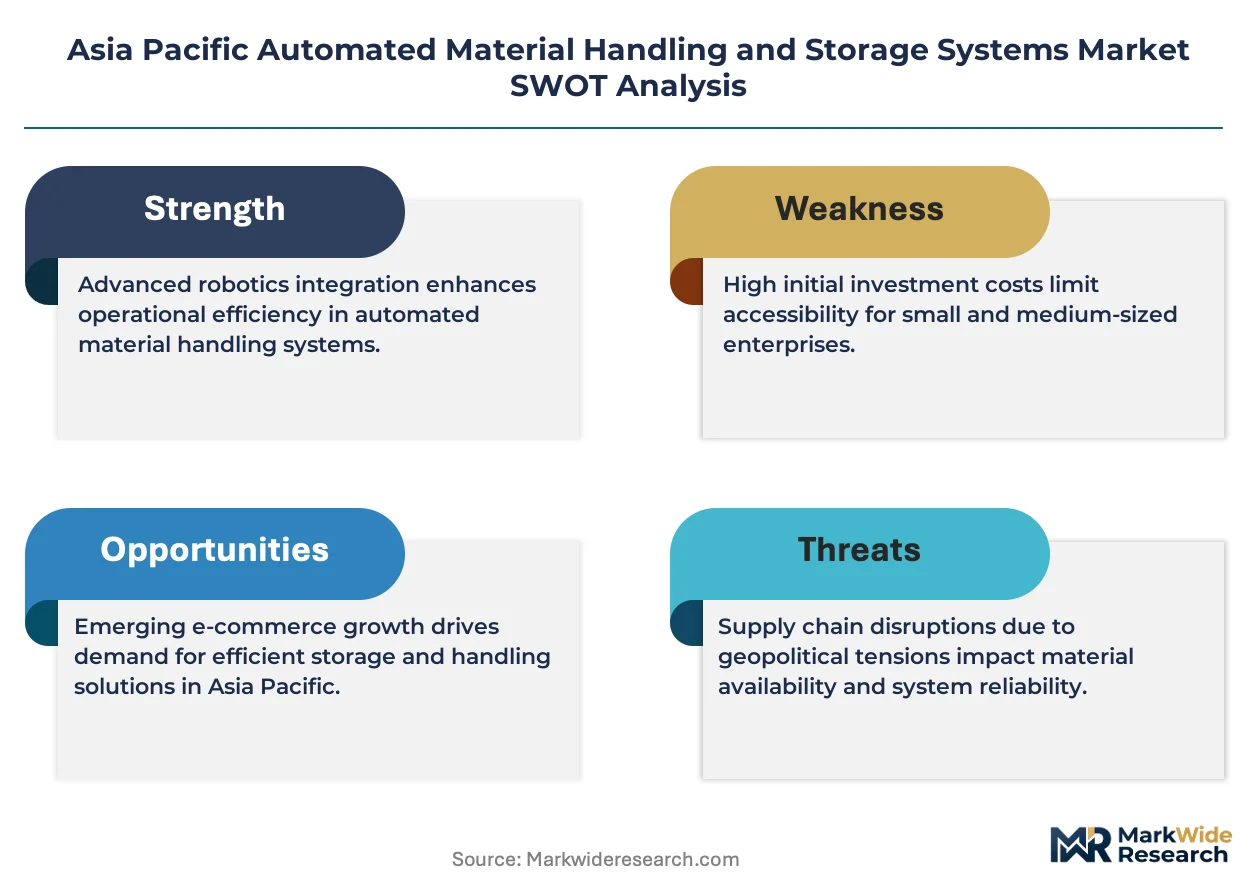
Incumbent crane manufacturers and conveyor specialists face substitution defense against swarm robotics vendors converging piece-picking algorithms with AMR navigation stacks, threatening traditional pallet-handling margin pools.
For Market Incumbents: Fortify captive production of stacker crane components against Chinese specialist encroachment by accelerating METI energy-efficiency certification pre-emption ahead of 2027 fleet conversion deadlines. Deepen backward integration into lithium-ion battery pack assembly to secure supply continuity against raw material volatility, while deploying modular service unbundling to match Thailand and Malaysia 3PL per-scan pricing expectations.
For New Entrants and Emerging Players: Lead with cold chain AS/RS deployment in India's pharmaceutical distribution corridors, where CDSCO serialization mandates are expanding addressable market for temperature-controlled automation previously excluded by 60% manual handling baselines. Target Australia's TGA-validated therapeutic goods warehousing segment with batch traceability software companions, using Sydney and Melbourne 3PL lease volatility as entry wedge for modular installation approaches.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European intralogistics specialists seeking Asia Pacific geographic expansion through regional crane manufacturers or swarm robotics platforms. Long-term viability across the analysis window favors vendors with integrated energy-efficiency certification pipelines and heterogeneous fleet management software stacks. Watch commissioning specialist salary premiums as inflection indicator for deployment velocity constraints affecting revenue recognition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Energy-Efficiency Certification Pre-emption | METI compliance deadlines force Osaka and Nagoya warehouse operators toward full fleet electrification by 2027. |
| Modular Automation-as-a-Service Launch | Thailand and Malaysia 3PLs trade fixed asset ownership for per-scan pricing indexed to parcel volume volatility. |
| Cold Chain AS/RS Geographic Expansion | India's CDSCO serialization mandates expand validation requirements for temperature-controlled pharmaceutical storage. |
| Swarm Robotics Fleet Convergence | Piece-picking algorithms merge with AMR navigation stacks enabling heterogeneous robot fleets sharing charging infrastructure. |
| Commissioning Specialist Capability Buildout | Systems integrators with combined mechanical, PLC, and machine vision expertise command 40% salary premiums constraining deployment velocity. |
Study Parameters
Initial hypotheses were tested against primary input from warehouse operations directors, OEM procurement teams, systems integration specialists, and aftermarket service heads and refined through secondary validation against customs and trade data, METI energy-efficiency filings, SAMR GB standard registrations, and SEC 10-K disclosures from listed equipment manufacturers. Bottom-up facility-level installation tracking and top-down regional automation spend estimates were triangulated to reconcile volume and value outputs.
Variance decomposition across the projection horizon isolates contributions from e-commerce fulfillment density, dual carbon target enforcement, and machine vision integration adoption. Segmentation dimensions modeled include equipment type, technology stack, end-use vertical, and installation approach, with CAGRs derived from logistic diffusion curves fitted to historical adoption patterns in comparable industrial automation categories. Forecast inputs incorporate lithium-ion battery cost trajectories and commissioning specialist labor supply elasticity.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce parcel growth, stable lithium raw material supply, or accelerated METI enforcement timelines would require recalibration. Recalibration cycles align with material shifts in energy-efficiency mandate revisions, CDSCO serialization rollout pace, and 3PL lease structure standardization across Southeast Asian logistics corridors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Portable Loading Ramps Market
Material Handling Equipment
Global Rolling Mill Rolls Market
Material Handling Equipment
Conveyor Scales Market
Material Handling Equipment
Hook Loader Market
Material Handling Equipment
Bridge Cable Sockets Market
Material Handling Equipment
High Pressure Grinding Rollers Market
Material Handling Equipment
Pipe Wipers Market
Material Handling Equipment
Hydraulics Components Market
Material Handling Equipment
Helical Gear Market
Material Handling Equipment
Heavy Duty Telehandler Market
Material Handling Equipment
Resistance Welding Products Market
Material Handling Equipment
Pipe Belt Conveyor Market
Material Handling Equipment
Carry Deck Crane Market
Material Handling Equipment
Lifting Machinery Market
Material Handling Equipment
Conveyor Sprocket Market
Material Handling Equipment
Truck Mounted Loader Cranes Market