
 Global Industrial Lifting Equipment Market | 2026-2036
Global Industrial Lifting Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Lifting Equipment Market Outlook
E-commerce fulfillment centers are redrawing procurement priorities for industrial lifting equipment away from traditional manufacturing buyers. Konecranes leverages its port automation expertise to capture terminal operator contracts. Toyota Industries Corporation anchors the forklift segment through manufacturing scale and channel density across Asian distribution networks.
Industrial lifting equipment encompasses cranes, hoists, forklifts, and pallet jacks engineered to move materials vertically and horizontally with rated load capacities spanning under 5 tons to over 20 tons; hydraulic and electric drive systems dominate heavy-lift applications where precision positioning and duty-cycle endurance determine operational uptime. The crane category leads capital expenditure in infrastructure and energy projects where over-20-ton capacity units command premium pricing. Electric technology is displacing pneumatic and manual alternatives in warehousing and logistics environments where emission restrictions and labor cost pressures reshape equipment specifications.
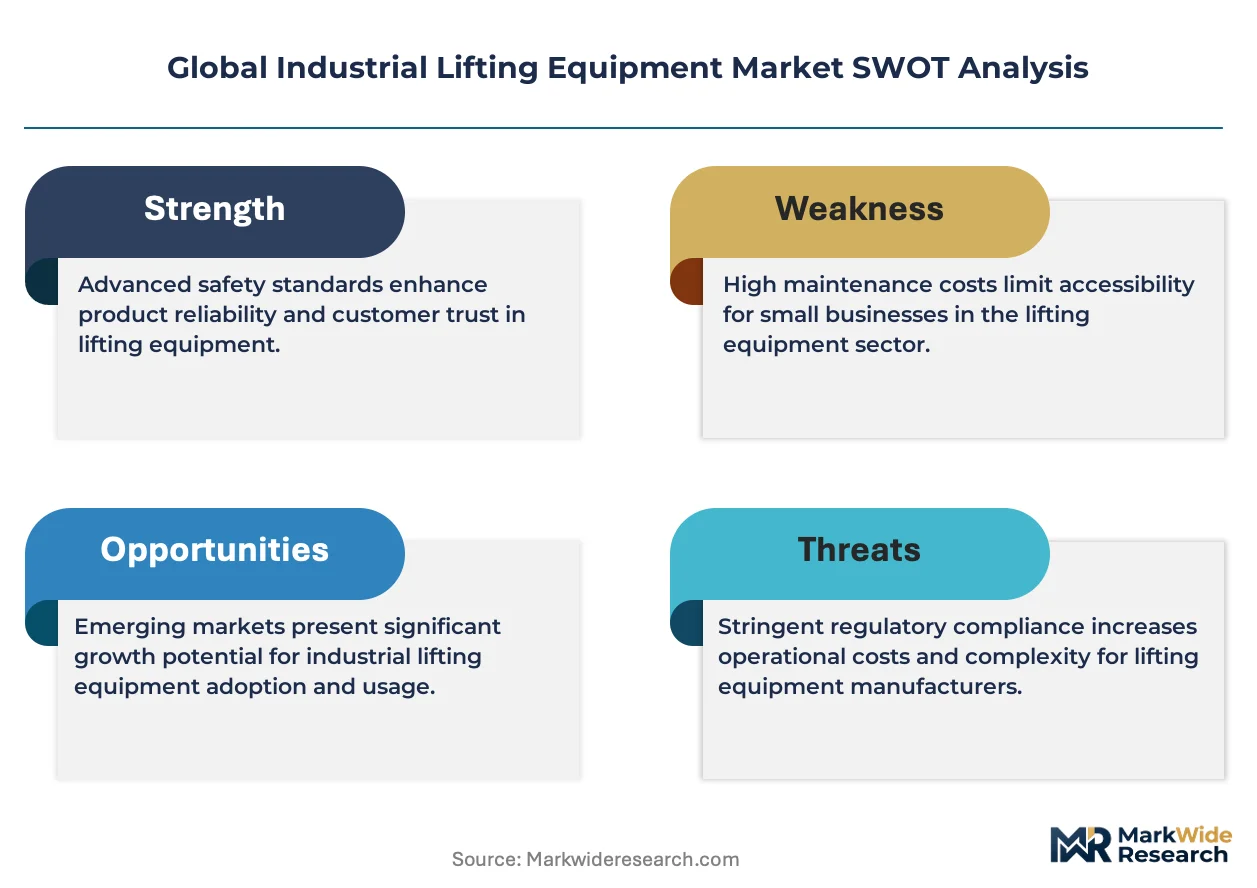
The EU Machinery Directive, OSHA standards in the United States, and ISO 4309 wire rope inspection protocols collectively mandate structural integrity testing and operator certification that elevate total cost of ownership and favor established suppliers with compliance infrastructure. China's GB standards and SAMR enforcement create additional conformity requirements for equipment imported into domestic steel and port automation projects. Stakeholders must monitor how carbon-border adjustments and local-content rules in multiple jurisdictions reshape supplier qualification criteria and aftermarket service obligations.
Market Dynamics
Port automation programs and warehouse robotics are compressing replacement cycles for industrial lifting equipment while elevating precision requirements beyond legacy mechanical specifications.
Growth Catalysts
- EU Machinery Directive compliance mandates:Terminal operators in Rotterdam and Hamburg are retrofitting gantry cranes with automated positioning systems to satisfy updated CE marking protocols for autonomous operation.
- Steel mill modernization in China:GB standard enforcement by SAMR is compelling heavy-capacity overhead crane upgrades at Baowu and Shagang facilities to support dual carbon emission targets.
- Lithium-ion electrification:Forklift fleets in e-commerce fulfillment centers are transitioning from lead-acid batteries to fast-charging lithium systems that eliminate battery swap labor.
Market Restraints
- High-grade steel input volatility:Specialized alloy plate for crane booms and hoist frames faces price pressure from scrap supply constraints and energy-intensive production curbs.
- Wire rope supply concentration:ISO 4309-certified rope manufacturers cluster in northern Italy and southern Germany, creating single-source vulnerability for inspection-compliant replacement cycles.
- Pneumatic system obsolescence:Compressed-air hoists and manipulators face displacement from electric servo alternatives, stranding maintenance expertise and spare parts networks.
Strategic Opportunities
- India port privatization wave:Adani Ports and JSW Infrastructure are tendering automated stacking crane contracts at Mundra and Hazira with 25-year service agreements attached.
- Carbon border adjustment mechanism:EU importers of Chinese-manufactured lifting equipment must document embedded emissions, creating aftermarket retrofit and certification service demand.
- Predictive maintenance convergence:Vibration sensors and digital twins are merging with crane control systems to enable condition-based replacement of wire ropes and brake assemblies.
Industry Challenges
- Certified inspector scarcity:OSHA-qualified crane inspectors and ISO 4309 rope examination technicians face demand saturation as inspection intervals tighten.
- Legacy PLC integration friction:Automated guided vehicles and stacker cranes must interface with 1990s-era warehouse management systems through costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Lifting Equipment Market |
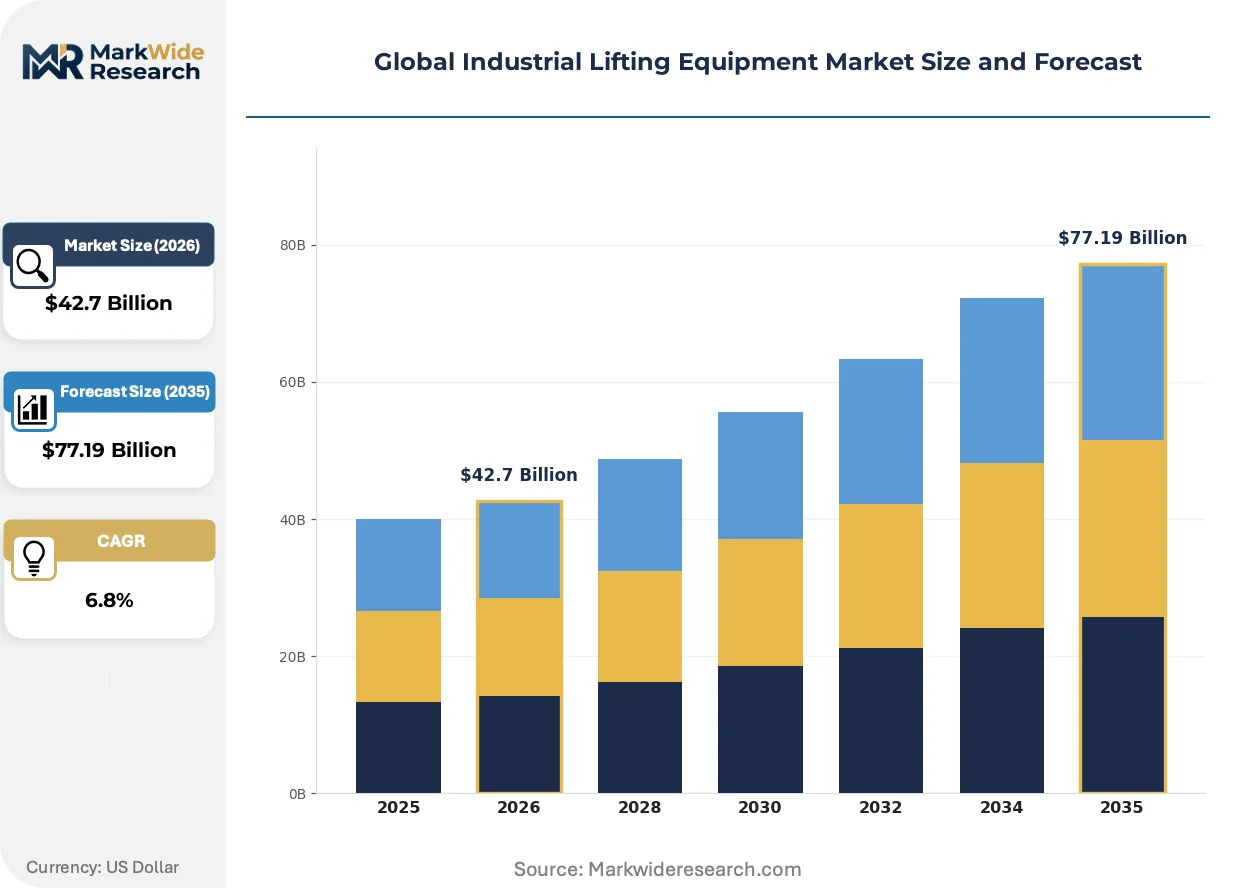
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $77.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crane, Hoist, Forklift, Pallet Jack Technology: Hydraulic, Electric, Pneumatic, Manual End User: Construction, Manufacturing, Warehousing, Logistics Capacity: Under 5 Ton, 5-10 Ton, 10-20 Ton, Over 20 Ton |
| Companies Covered | Daifuku Co., Ltd, Crown Equipment Corporation, Toyota Industries Corporation, Konecranes, Mitsubishi Forklift Trucks, KION Group, Liebherr-International GmbH, ABUS Crane Systems, Terex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Lifting Equipment Market Strategic Shifts
Electrification and digitalization are splitting equipment categories into precision-automated and rugged-mechanical tiers, with regulatory pressure accelerating the divide between premium and baseline specifications.
Servo-electric hoist technology is bifurcating the overhead crane market between high-precision positioning systems for semiconductor fabrication and cost-optimized units for general manufacturing. Cleanroom operators in South Korea and Taiwan specify sub-millimeter repeatability for wafer handling applications. Standard fabrication shops retain variable-frequency drive hydraulics for raw material handling, creating parallel supply chains with minimal component overlap.
OSHA's updated crane operator certification requirements and the EU Machinery Directive's autonomous equipment protocols are forcing control system architecture redesigns. Manufacturers must embed redundant safety PLCs and remote monitoring capabilities to satisfy both jurisdictions. Port operators in Long Beach and Antwerp are prioritizing suppliers with dual-compliant platform architectures to simplify fleet standardization.
Equipment-as-a-service contracting is displacing capital purchase models in third-party logistics and contract manufacturing verticals. Linde Material Handling and Jungheinrich are capturing multi-year forklift subscriptions with bundled maintenance and battery replacement. German automotive suppliers and Dutch cold-chain operators are the most advanced adopters, with contract structures now penetrating North American distribution networks.
Global Industrial Lifting Equipment Market Segmentation
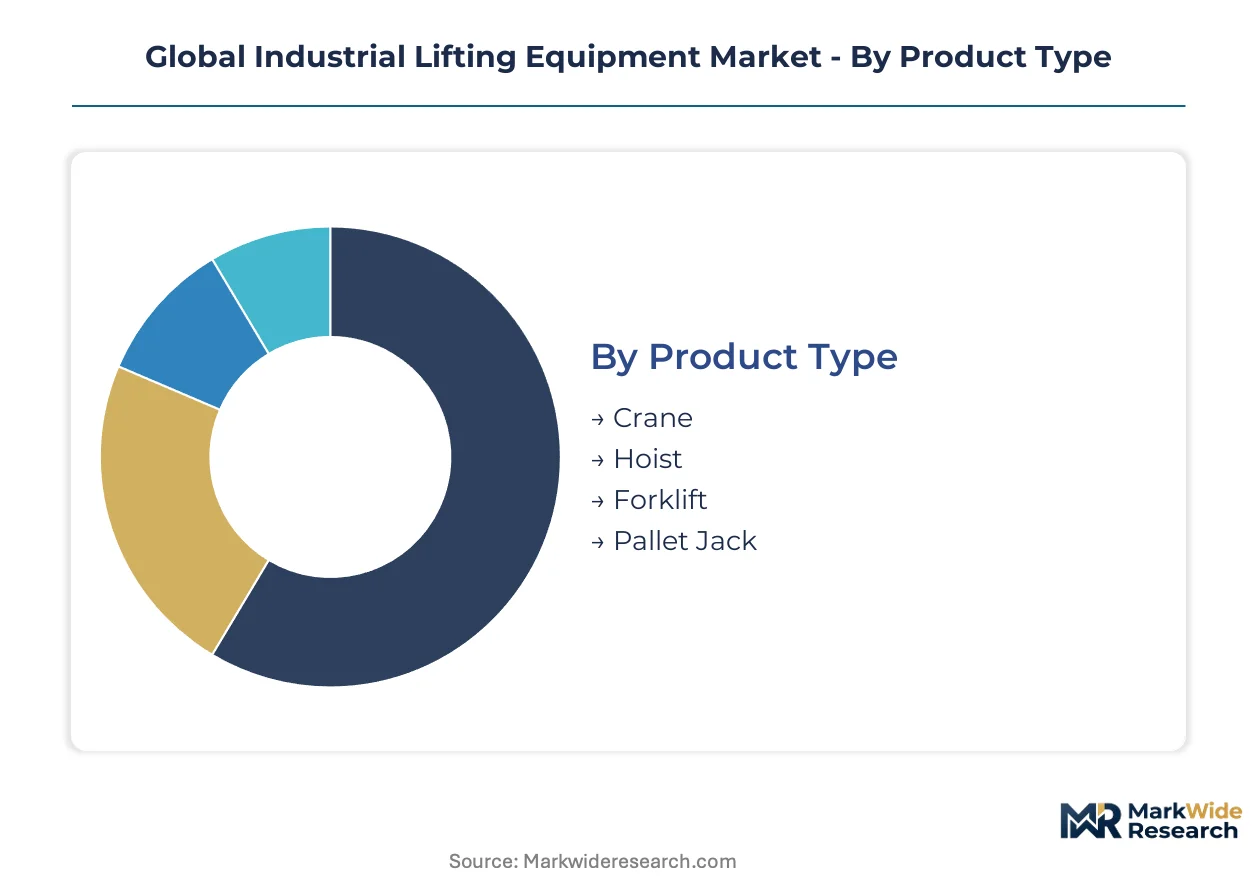
Equipment segmentation in industrial lifting reveals how capital allocation splits between heavy infrastructure and high-velocity logistics. Technology and capacity tiers now determine supplier profitability more than end-use verticals.
Product Type:
Margin pools concentrate in crane systems where over-20-ton capacity commands premium pricing and long-term service contracts, while forklifts compete on fleet scale and financing terms.
- Crane:Overhead, gantry, and jib configurations engineered for vertical lift and horizontal traverse across construction sites and manufacturing facilities. Port operators in Rotterdam and Hamburg are retrofitting gantry units with automated positioning to satisfy EU Machinery Directive protocols for autonomous operation.
- Forklift:Counterbalance and reach truck designs with mast assemblies for palletized load handling. E-commerce fulfillment centers in Germany and the Netherlands are transitioning fleets to lithium-ion electrification, eliminating battery swap labor and compressing replacement cycles.
- Hoist:Chain and wire rope mechanisms for repetitive vertical lifting in assembly and maintenance operations. Steel mills in China deploy heavy-capacity electric hoists under SAMR-enforced GB standards to support dual carbon emission targets.
- Pallet Jack:Manual and powered units for short-distance pallet transport within warehouse aisles. Third-party logistics providers favor electric walkie models for last-meter distribution tasks.
Crane holds installed capacity. Forklift is rotating up the share rankings.
Technology:
Cost tier stratification separates precision servo-electric systems from maintenance-intensive hydraulic and pneumatic alternatives, with electrification capturing logistics applications.
- Electric:Servo motor and battery-powered drive systems delivering precise positioning and regenerative braking. Semiconductor fabrication facilities in South Korea and Taiwan specify sub-millimeter repeatability for wafer handling cranes.
- Hydraulic:Fluid power actuation for heavy-lift applications requiring sustained force output. Variable-frequency drive hydraulics retain dominance in raw material handling for standard fabrication shops.
- Pneumatic:Compressed-air actuation for explosion-protected environments and lightweight manipulators. Maintenance expertise and spare parts networks face stranding as electric servo alternatives displace legacy installations.
- Manual:Human-powered chain blocks and lever tools for intermittent light-duty tasks. Small machine shops and maintenance departments retain these for zero-energy backup capability.
Hydraulic holds installed capacity. Electric is climbing the fastest.
End User:
Application intensity varies by duty cycle and precision requirements, with warehousing and logistics demanding higher equipment turnover than capital-heavy construction.
- Warehousing:High-velocity storage and retrieval operations requiring narrow-aisle maneuverability. Automated guided vehicles and stacker cranes compress replacement cycles while elevating precision beyond legacy mechanical specifications.
- Logistics:Cross-dock and distribution center material flow with rapid load turnover. Equipment-as-a-service contracting is displacing capital purchase models, with multi-year subscriptions bundling maintenance and battery replacement.
- Manufacturing:Production line feeding and work-in-process handling across automotive and industrial assembly. OSHA-qualified crane inspectors face demand saturation as inspection intervals tighten for overhead systems.
- Construction:Temporary lifting for structural erection and heavy component placement. Mobile and tower crane deployments concentrate in infrastructure and energy projects where premium pricing attaches to over-20-ton capacity.
Manufacturing holds installed capacity. Warehousing is gaining share fastest.
Capacity:
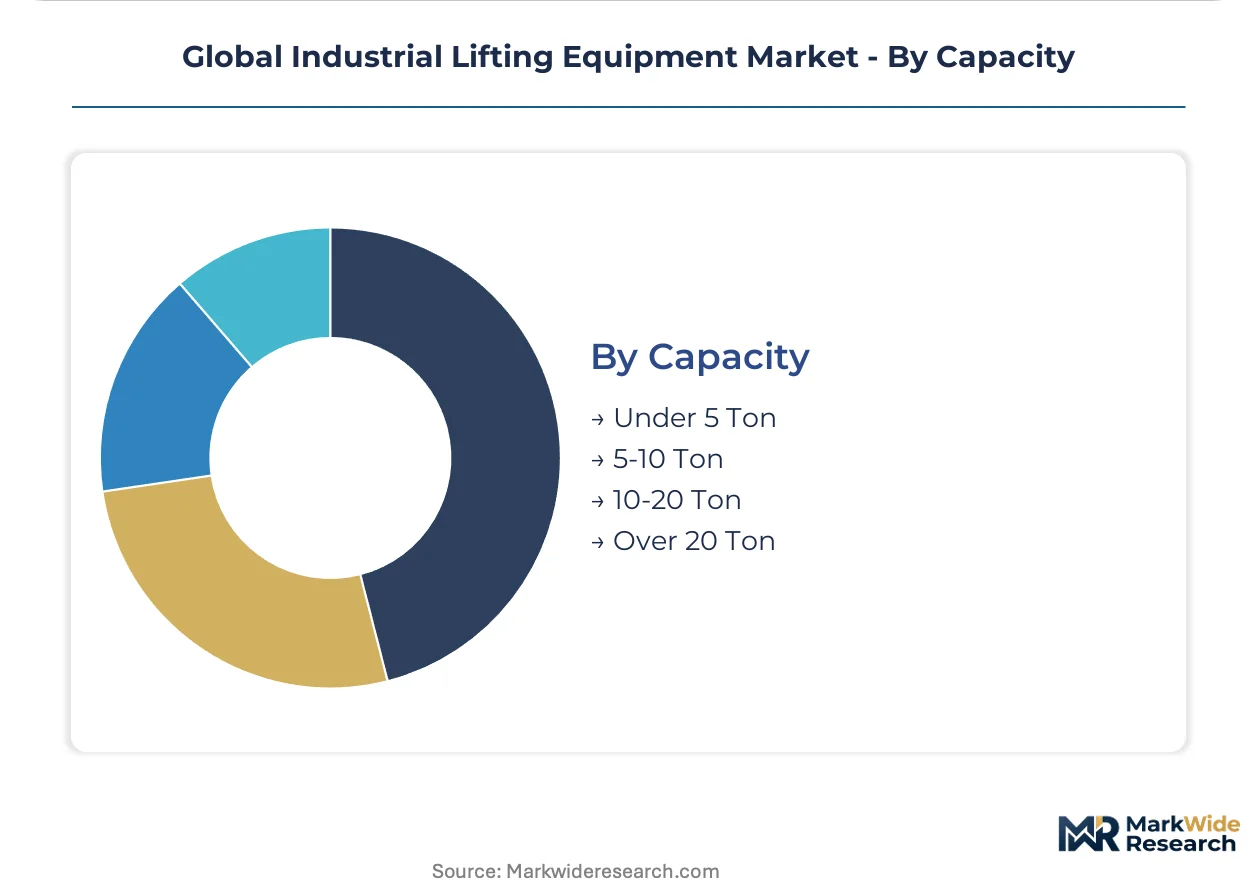
Volume concentration sits in mid-range tiers serving general industry, while heavy-capacity units generate disproportionate revenue per unit through specialized engineering and compliance certification.
- Over 20 Ton:Heavy-lift configurations for steel production, port cargo, and energy infrastructure. Baowu and Shagang facilities in China require SAMR-compliant overhead crane upgrades to support modernization programs.
- 10-20 Ton:Medium-heavy industrial applications in metal fabrication and heavy machinery assembly. This tier bridges general manufacturing and specialized heavy-lift requirements with standardized component platforms.
- 5-10 Ton:General-purpose manufacturing and warehouse operations with balanced mobility and payload. Forklift fleets in this range dominate Asian distribution networks through manufacturing scale advantages.
- Under 5 Ton:Light-duty warehousing, retail distribution, and maintenance tasks. Pallet jacks and compact forklifts serve high-velocity, low-payload environments where maneuverability outweighs lift capacity.
5-10 Ton holds installed capacity. Over 20 Ton is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized alloy supply and certified wire rope manufacturing cluster in northern Italy and southern Germany, while crane assembly and port automation integration concentrate in China, Germany, and the United States. Equipment procurement patterns diverge sharply between heavy-capacity infrastructure projects and high-velocity logistics fleets.
China
Port automation at Shanghai and Ningbo-Zhoushan drives gantry crane procurement, while steel mill modernization at Baowu and Shagang facilities compels SAMR-enforced GB standard upgrades for heavy-capacity overhead systems. The Yangtze River Delta anchors manufacturing clusters where domestic fabricators integrate automated positioning for terminal operators.
Germany
ISO 4309-certified wire rope suppliers in southern Germany face demand saturation from tightened inspection protocols, while Hamburg and Bremen port authorities retrofit gantry cranes for EU Machinery Directive autonomous operation compliance. Baden-Württemberg hosts precision servo-electric hoist development for semiconductor fabrication applications.
United States
OSHA-qualified crane inspectors face supply constraints as inspection intervals compress, while Long Beach and Los Angeles terminal operators prioritize dual-compliant control architectures for fleet standardization. The Gulf Coast energy corridor sustains mobile crane deployment for infrastructure and petrochemical construction.
Japan
Automotive suppliers in Toyota City and Nagoya adopt equipment-as-a-service forklift subscriptions with bundled maintenance, while METI efficiency standards accelerate lithium-ion fleet transitions. Kansai region fabrication shops retain variable-frequency drive hydraulics for raw material handling with minimal servo-electric penetration.
India
Adani Ports at Mundra and JSW Infrastructure at Hazira tender automated stacking crane contracts with 25-year service agreements attached, while port privatization waves reshape procurement toward long-term operator partnerships. DGFT import regulations and BIS certification requirements filter equipment qualification for domestic steel and logistics projects.
Global Industrial Lifting Equipment Market Competitive Environment
Concentration sits with diversified industrial conglomerates and specialized crane engineering houses. The vendor base splits between scale-driven forklift manufacturers with channel density advantages and precision-automation specialists capturing port and semiconductor verticals. Strategic archetypes include: integrated material handling conglomerates with captive battery and drive technology; crane-focused engineering houses with long-term service contract expertise; and regional fabricators competing on local-content compliance. Competitive moves center on multi-year equipment-as-a-service contracting and predictive maintenance platform integration.
Within the integrated conglomerate tier, Toyota Industries Corporation and KION Group anchor global forklift manufacturing with scale advantages in Asian and European distribution networks. Among crane engineering specialists, Konecranes and Liebherr-International GmbH occupy positions where port automation expertise and heavy-capacity engineering credentials determine terminal operator contract capture. Daifuku Co., Ltd exemplifies the automation-integrated archetype, representing convergence between material handling equipment and warehouse robotics control systems.
| Leading Market Players |
|---|
| Daifuku Co., Ltd |
| Crown Equipment Corporation |
| Toyota Industries Corporation |
| Konecranes |
| Mitsubishi Forklift Trucks |
| KION Group |
| Liebherr-International GmbH |
| ABUS Crane Systems |
| Terex Corporation |
| Others |
Value Chain & Pricing Dynamics
Equipment-as-a-service contracting locks in both supply access and price visibility for third-party logistics operators across German automotive supply chains and Dutch cold-chain networks. This subscription structure bundles lithium-ion battery replacement and predictive maintenance into fixed per-month fees that insulate fleet operators from spot-price volatility in high-grade steel inputs.
Pricing Analysis
EU Machinery Directive compliance dictates the pricing tier structure across European port automation projects. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked autonomous gantry systems from manually operated baseline units. ISO 4309 certification for wire rope inspection adds tier premiums for replacement cycles. Cost compression in standard fabrication shop hydraulics is intensifying because variable-frequency drive alternatives face margin pressure from servo-electric displacement. Warehousing and logistics buyers show highest price sensitivity due to fleet-scale procurement, while semiconductor fabrication facilities demonstrate lowest sensitivity for sub-millimeter precision systems.
Supply Chain Analysis
China, Germany, and northern Italy anchor specialized alloy plate production and ISO 4309-certified wire rope manufacturing for crane boom and hoist frame applications. The supply chain draws from high-grade steel scrap markets, lithium-ion cell production, and precision servo motor fabrication. Single-source vulnerability concentrates in wire rope replacement cycles where certified manufacturers cluster in southern Germany. Distribution runs through OEM direct sales for heavy-capacity infrastructure projects and dealer networks for forklift fleet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial lifting equipment sits in early-cycle expansion as port automation and warehouse robotics compress replacement cycles beyond legacy mechanical specifications. Lithium-ion electrification and predictive maintenance platform adoption create durable tailwinds for subscription-based revenue models.
For Market Incumbents: Shield service contract portfolios from electric servo displacement by embedding vibration sensors and digital twins into legacy crane control architectures. Backward integration into lithium-ion battery pack assembly secures supply continuity for forklift fleet subscriptions. Certification investment in dual-compliant control platforms for OSHA and EU Machinery Directive convergence protects terminal operator relationships at Long Beach and Antwerp.
For New Entrants and Emerging Players: Fast-track ISO 4309 rope examination technician certification captures inspector scarcity premiums as inspection intervals tighten across US manufacturing and European port facilities. White-space targets include predictive maintenance software for 1990s-era warehouse management system integration and aftermarket retrofit services for EU carbon border adjustment documentation. Channel partnerships with regional crane service depots offer the most penetrable go-to-market angle against established OEM direct sales.
For Investors and Strategic Acquirers: Capital is best deployed toward automation-integrated material handling specialists with warehouse robotics control system expertise. Long-term viability across the next decade rests on recurring revenue attachment rates from multi-year service agreements. Monitor tender announcements from Adani Ports and JSW Infrastructure in India as inflection indicators for automated stacking crane contract velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Integration | Vibration sensors and digital twins enable condition-based wire rope replacement at Baowu steel facilities. |
| Lithium-Ion Fleet Electrification | Fast-charging battery systems eliminate swap labor for e-commerce fulfillment centers in Germany and Netherlands. |
| Dual-Compliance Control Architecture | Redundant safety PLCs satisfy both OSHA certification and EU Machinery Directive autonomous operation protocols. |
| Equipment-as-a-Service Contracting | Multi-year subscriptions with bundled maintenance displace capital purchase models in third-party logistics verticals. |
| Backward Integration into Battery Assembly | In-house lithium-ion pack production secures supply continuity for forklift subscription fleet operators. |
Study Parameters
Initial hypotheses were tested against primary input from maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads and refined through secondary validation against customs trade data, SEC 10-K filings, and port authority procurement disclosures. Bottom-up equipment shipment analysis triangulated with top-down infrastructure spending forecasts across construction, energy, and logistics verticals.
Variance in volume and value outputs decomposes across technology type, capacity tier, end-use intensity, and regional regulatory cluster throughout the forecast period. CAGRs were derived from modeled replacement cycle compression and electrification penetration curves. Forecast inputs include steel mill modernization program announcements, port automation tender timelines, and e-commerce fulfillment center buildout pipelines.
Underlying assumptions cover sustained lithium-ion cost curves, GB standard enforcement continuity, and inspection interval tightening, with deviation risk concentrated in high-grade steel input volatility and certified technician supply constraints. Recalibration cycles align with material shifts in EU carbon border adjustment implementation and SAMR enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Air Hoist Market
Material Handling Equipment
Asia-Pacific Conveyors Market
Material Handling Equipment
Drum Handling Equipment Market
Material Handling Equipment
Industrial Racking Systems Market
Material Handling Equipment
Chute Liners Market
Material Handling Equipment
Silo Bin Activators Market
Material Handling Equipment
Europe Forklift Truck Market
Material Handling Equipment
Material Handling Automation Market
Material Handling Equipment
Pipe Jacking Machines Market
Material Handling Equipment
Log Stackers Market
Material Handling Equipment
Vibratory Feeder Machine Market
Material Handling Equipment
Conveying Equipment Market
Material Handling Equipment
Material Handling Equipment Telematics Market
Material Handling Equipment
Wood Chipper Market
Material Handling Equipment
Loaded Container Handler Market
Material Handling Equipment
Vertical Baling Press Market