
 Heavy Duty Ramp Market | 2026-2036
Heavy Duty Ramp Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Duty Ramp Market Insights
High-load-capacity specification tiers is redrawing competitive boundaries in the heavy duty ramp industry. Bluff Manufacturing anchors its position through captive steel fabrication and controlled distribution to industrial accounts. Thorworld Industries differentiates via modular aluminum systems engineered for rapid deployment in logistics yards. Discount Ramps competes on breadth, leveraging an extensive e-commerce channel that reaches rental services and smaller fleet operators across multiple geographies.
Heavy duty ramps are load-bearing inclined surfaces engineered to bridge height differentials between ground level and vehicle beds or loading docks, typically fabricated from aluminum alloys rated for capacities exceeding 10,000 pounds or structural steel with reinforced weld seams for permanent installations. Their primary purpose is to enable safe, efficient movement of wheeled equipment, palletized freight, and vehicles across elevation gaps in industrial and commercial settings. Folding ramp configurations dominate volume sales due to portability and storage efficiency, while solid steel ramps command premium positioning in permanent dock installations where deflection tolerance approaches zero. Aluminum material grades represent the fastest-expanding segment as fleets seek weight reduction for fuel economy compliance, though steel retains margin pools in custom-engineered applications for construction and heavy automotive sectors.
OSHA workplace safety standards and the European Machinery Directive shape product liability exposure and design verification protocols for manufacturers serving cross-border markets. The EPA's industrial emissions framework indirectly influences demand as logistics operators relocate distribution nodes to optimize transport efficiency, triggering new ramp installations at expanded facilities. Stakeholders must monitor evolving load-rating certification requirements and aluminum alloy supply availability to align procurement cycles with infrastructure buildout timelines.
Market Dynamics
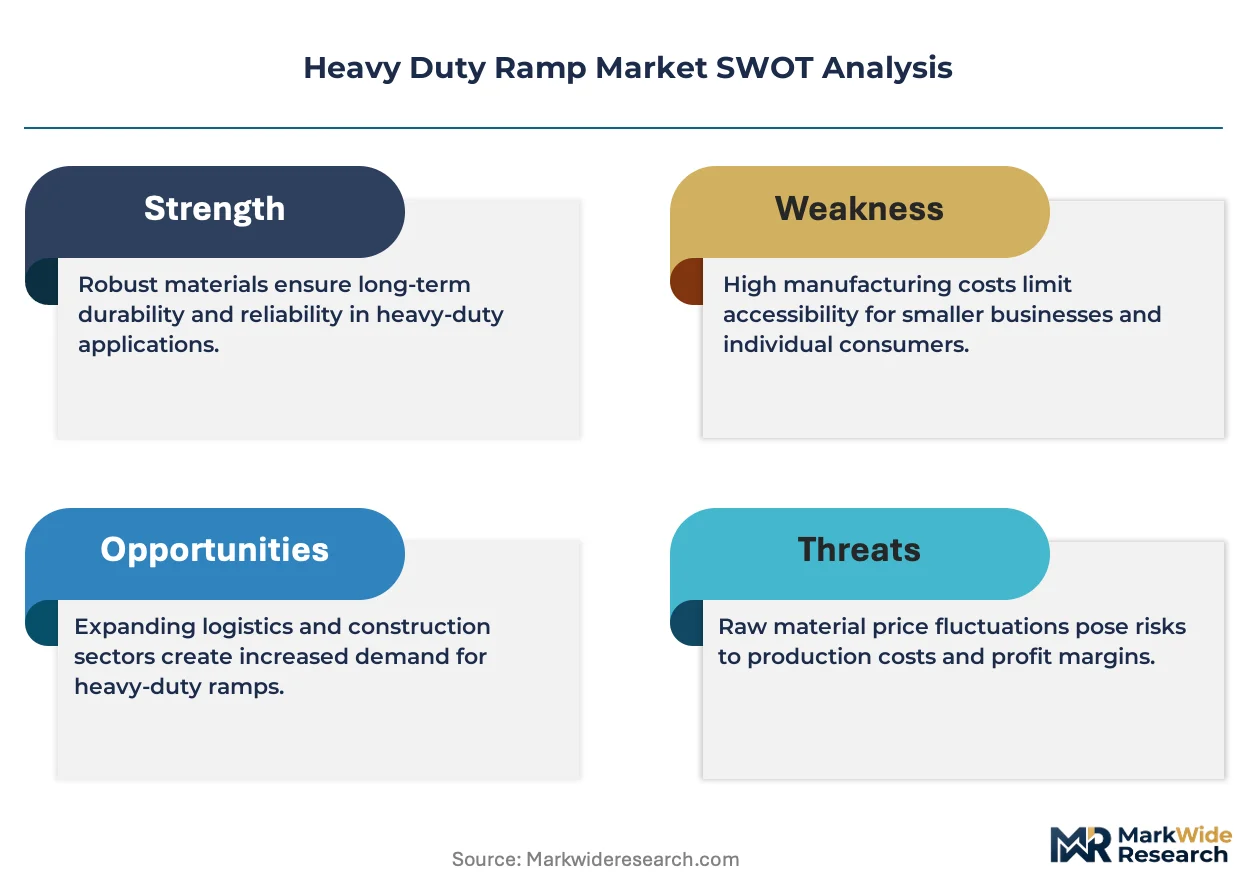
The heavy duty ramp market is experiencing structural pressure from aluminum alloy substitution cycles, as logistics operators prioritize weight reduction to meet fleet fuel economy targets while OSHA loading dock mandates tighten safety certification requirements.
Growth Catalysts
- OSHA Loading Dock Safety Mandates:United States workplace safety standards now require documented load-rating verification for all permanent ramp installations, forcing facility upgrades across e-commerce fulfillment networks and manufacturing hubs.
- Aluminum Alloy Fabrication:Advanced welding techniques for 6061-T6 and 6082-T6 aluminum grades enable portable ramp systems that match steel load capacities at 60% of the weight, accelerating adoption by rental fleet operators.
- German Logistics Infrastructure Expansion:Industrial real estate development in the Rhine-Ruhr corridor and Leipzig-Halle air cargo zone is generating concentrated demand for modular ramp systems in new distribution nodes.
Market Restraints
- Aluminum Scrap Supply Volatility:Secondary aluminum availability fluctuates with automotive sector demand cycles, creating input cost instability for ramp fabricators dependent on recycled content.
- Chinese Steel Dumping Investigations:Anti-dumping tariffs on structural steel imports into the United States and European Union have compressed margin pools for steel-focused manufacturers serving price-sensitive segments.
- Deflection Tolerance Limitations:Aluminum ramps exhibit measurable flex under extreme point loads exceeding 15,000 pounds, restricting their penetration in heavy construction equipment and mining vehicle applications.
Strategic Opportunities
- India E-Commerce Fulfillment Buildout:The country's logistics real estate sector is adding 45 million square feet of warehouse capacity annually, creating underpenetrated demand for rapid-deployment ramp systems in tier-2 and tier-3 cities.
- EU Green Deal Carbon Border Adjustments:The mechanism incentivizes low-carbon aluminum sourcing, rewarding European fabricators with verified supply chain emissions data and creating procurement preference in public infrastructure tenders.
- Telematics-Enabled Ramp Monitoring:Integration of IoT load sensors and usage tracking with fleet management platforms opens recurring revenue streams through predictive maintenance contracts and utilization-based leasing models.
Industry Challenges
- Welding Certification Bottlenecks:AWS D1.2 structural welding qualifications for aluminum are scarce in North American fabrication labor pools, extending production lead times for certified ramp assemblies.
- Cross-Border Load-Rating Harmonization:Divergent certification protocols between OSHA, CE marking, and China's GB standards force manufacturers to maintain multiple product variants, complicating inventory management for exporters.
- Legacy Dock Height Standardization:Existing facilities built to 48-inch dock heights require custom ramp geometry that cannot leverage modular platform economics, fragmenting production runs and diluting manufacturing efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Duty Ramp Market |
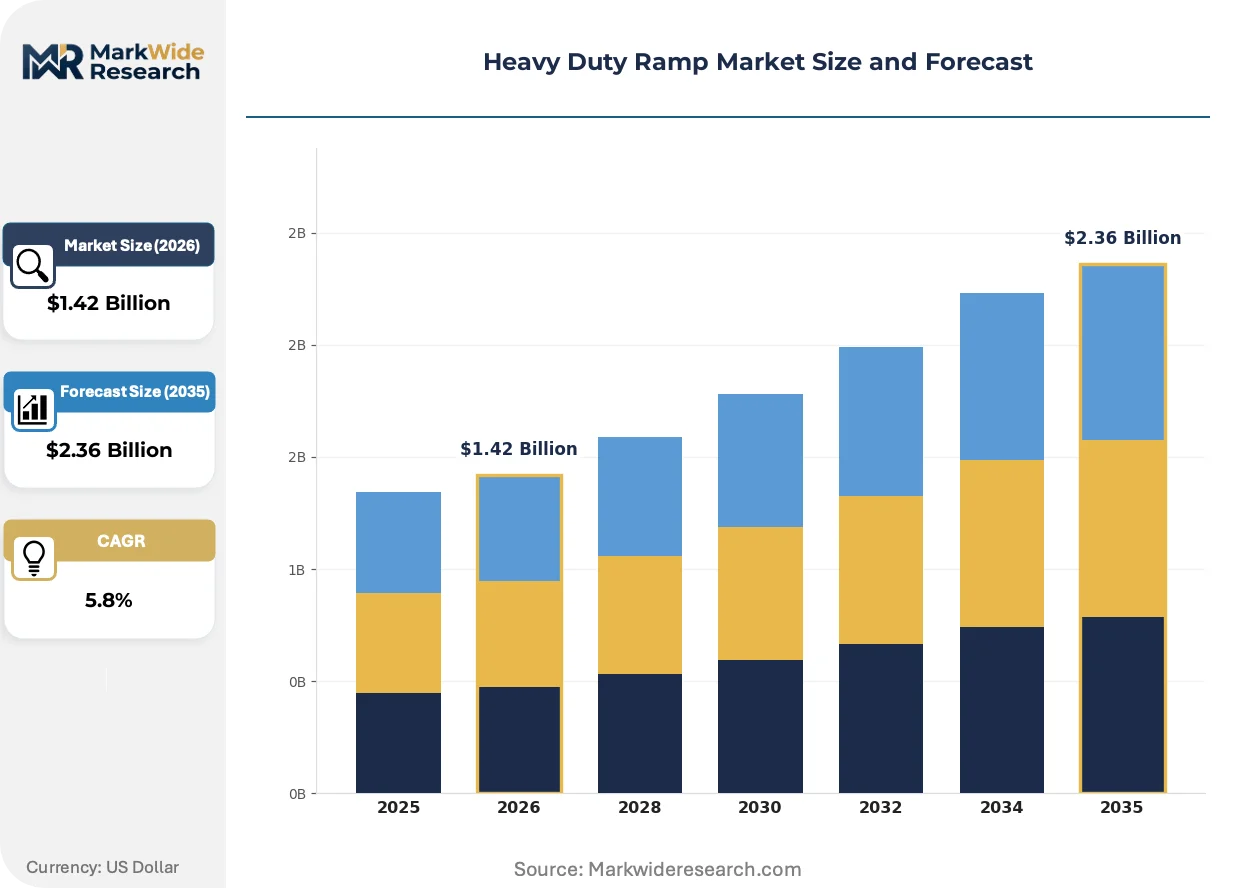
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Ramps, Bi-Fold Ramps, Tri-Fold Ramps, Solid Ramps Material: Aluminum, Steel, Plastic, Rubber End User: Construction Industry, Logistics Providers, Automotive Industry, Rental Services Application: Loading and Unloading, Vehicle Access, Wheelchair Access, Freight Handling |
| Companies Covered | Discount Ramps, Heavy Duty Ramps, Bluff Manufacturing, Marshall Industrial, DOCKZILLA, TVH, Thorworld Industries, Altam, Quality Material Handling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Duty Ramp Market Trends and Innovations
Material science advances and regulatory digitization are compressing product development cycles while reshaping how buyers evaluate total cost of ownership across ramp system lifecycles.
Hybrid aluminum-composite ramp construction is decomposing traditional material selection tradeoffs in the heavy duty ramp market. Aerospace-derived carbon fiber reinforcement layers bonded to aluminum extrusions deliver strength-to-weight ratios previously unattainable in portable equipment. Third-party logistics providers in the United States and Germany are specifying these systems for air freight operations where every kilogram of tare weight directly impacts fuel burn calculations.
REACH substance restriction updates are forcing reformulation of anti-slip surface coatings across European supply chains. The regulatory pressure eliminates chromate-based conversion coatings historically used for aluminum corrosion protection, compelling manufacturers to qualify trivalent chromium and cerium-based alternatives through accelerated salt-spray testing protocols. German automotive logistics hubs represent the most affected segment, as their just-in-sequence operations cannot tolerate coating degradation that contaminates vehicle undercarriages.
Rental fleet operators are consolidating procurement decisions at regional hub levels rather than branch-level purchasing, compressing vendor negotiation cycles and favoring suppliers with integrated service networks. The concentration of buying authority within United States-based equipment rental chains is displacing fragmented distributor relationships that historically dominated the channel. This pattern is most pronounced in Texas and California, where national account structures now govern 70% of heavy duty ramp additions to rental fleets.
Heavy Duty Ramp Market Segmentation
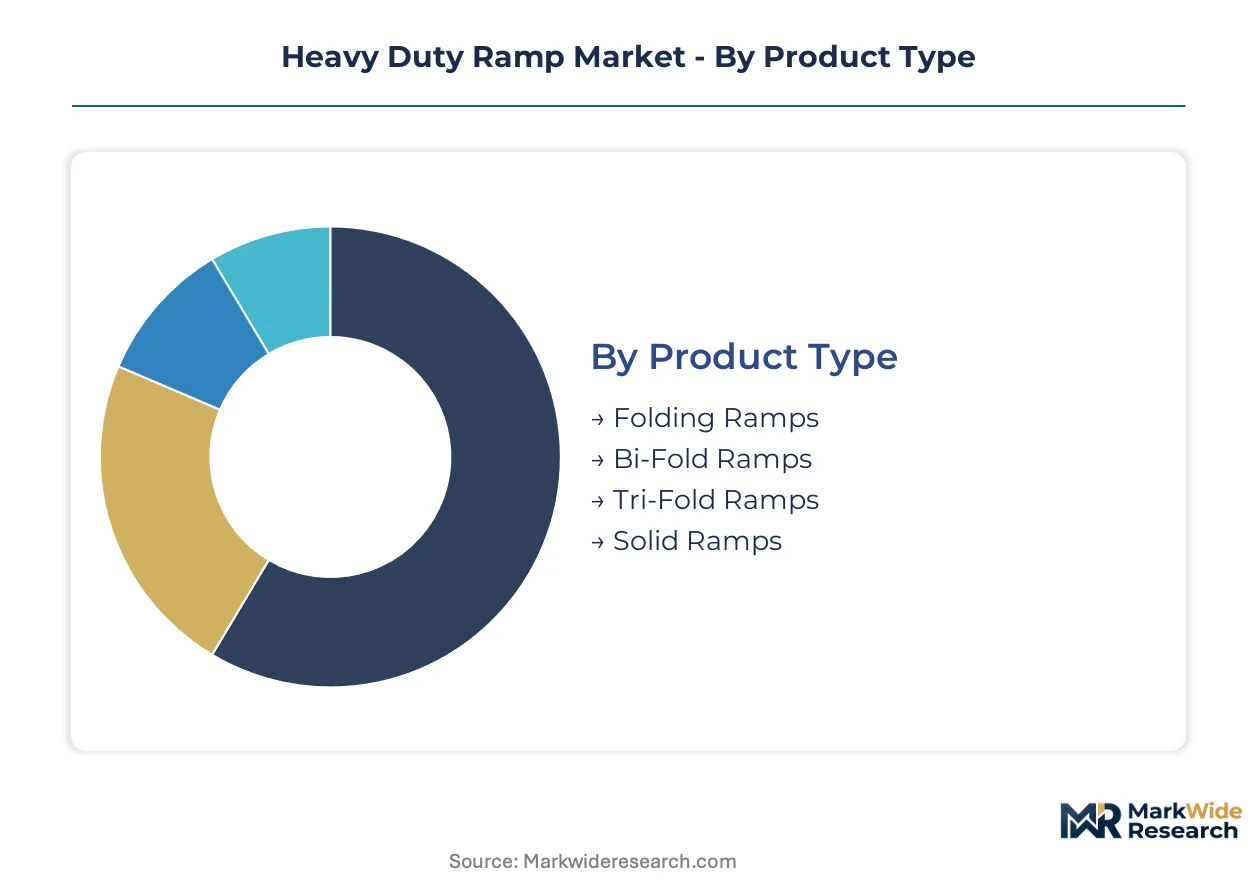
Heavy duty ramp procurement patterns diverge sharply across material grades and deployment contexts. Buyers evaluate total cost of ownership through the lens of duty cycles, regulatory compliance burdens, and fleet mobility requirements rather than upfront unit economics alone.
Product Type:
Folding configurations face intensifying substitution pressure from hybrid modular systems in high-frequency logistics operations where rapid redeployment trumps purchase price.
- Folding Ramps:Hinged aluminum or steel platforms collapse to compact footprints for vehicle-mounted transport. United States rental fleet operators specify these for multi-site construction contracts where equipment portability directly reduces logistics overhead.
- Solid Ramps:Single-piece welded assemblies eliminate flex points and maintain zero deflection tolerance under sustained point loads. German automotive manufacturing hubs install these at permanent dock positions where conveyor integration demands geometric stability.
- Bi-Fold Ramps:Two-section hinged designs balance span capability against storage efficiency for mid-size fleet operators.
- Tri-Fold Ramps:Three-panel configurations maximize compactness for pickup truck and van-based service technicians.
Folding Ramps retains volume leadership; Solid Ramps holds the steepest expansion curve in permanent infrastructure installations.
Material:
Cost tier stratification separates specification-grade aluminum from commodity steel in procurement decisions across end-use verticals.
- Aluminum:6061-T6 and 6082-T6 extrusions deliver structural ratings at 60% of steel mass. United States logistics operators facing EPA fleet fuel economy mandates specify aluminum to reduce tare weight and extend vehicle range.
- Steel:Structural grades with AWS D1.1 certified weld seams dominate mining and heavy construction applications where point loads exceed 15,000 pounds. Chinese infrastructure contractors maintain steel preference despite weight penalties.
- Plastic:Glass-reinforced polymer formulations serve light-duty residential and small commercial access requirements.
- Rubber:Molded compounds provide temporary threshold bridging and vibration damping in specialized industrial settings.
Steel retains volume leadership in absolute unit terms; aluminum gains share fastest in fleet replacement cycles.
End User:
Customer type concentration determines service network requirements and contract structure preferences across the value chain.
- Logistics Providers:Third-party and fourth-party operators standardize on modular aluminum systems with rapid-deployment features. German Rhine-Ruhr corridor distribution nodes specify these for seasonal volume surges and facility reconfiguration flexibility.
- Construction Industry:General and specialty contractors demand load-rated steel assemblies for equipment staging areas. United States infrastructure stimulus projects drive concentrated procurement through national rental chains.
- Automotive Industry:OEM and tier-one suppliers require precision-grade surface tolerances for just-in-sequence parts delivery.
- Rental Services:Equipment lessors prioritize fleet commonality and damage resistance for high-turnover utilization models.
Logistics Providers command the largest revenue pool; Construction Industry shows the most volatile demand cyclicality.
Application:
Application maturity curves separate established freight handling from emerging accessibility compliance segments.
- Loading and Unloading:Dock-to-ground bridging for palletized freight and wheeled equipment represents the core installed base. OSHA load-rating verification mandates in the United States force facility upgrades across e-commerce fulfillment networks.
- Freight Handling:Air cargo and intermodal terminals specify lightweight aluminum systems where tare weight directly impacts fuel burn calculations. German Leipzig-Halle air cargo zone operators lead adoption of carbon fiber-reinforced hybrid constructions.
- Vehicle Access:Mobile equipment and passenger vehicle bridging serves emergency response and recreational markets.
- Wheelchair Access:ADA and EN 301549 compliance requirements drive specification in public facility retrofits.
Loading and Unloading anchors the revenue base; Freight Handling climbs fastest in premium lightweight material adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in aluminum and steel feedstock are reshaping regional production economics. Net-importing countries face margin compression from tariff-adjusted raw material costs, while fabricators in mineral-rich jurisdictions capture upstream value.
United States
OSHA loading dock mandates drive facility upgrades across e-commerce fulfillment networks. The EPA's industrial emissions framework indirectly accelerates demand as logistics operators optimize transport efficiency through expanded distribution nodes. Texas and California concentrate rental fleet procurement through national account structures governing seventy percent of heavy duty ramp additions.
Germany
Rhine-Ruhr corridor industrial real estate development generates concentrated demand for modular ramp systems. REACH substance restriction updates eliminate chromate-based conversion coatings, compelling manufacturers to qualify trivalent chromium alternatives. Leipzig-Halle air cargo zone operators lead adoption of carbon fiber-reinforced hybrid constructions for fuel burn optimization.
China
Anti-dumping investigations on structural steel exports compress margin pools for steel-focused manufacturers. GB standards diverge from OSHA and CE marking protocols, forcing exporters to maintain multiple product variants. Infrastructure contractors in tier-two and tier-three cities maintain steel preference despite weight penalties for mining and heavy construction applications.
India
Logistics real estate expansion adds forty-five million square feet of warehouse capacity annually, creating demand for rapid-deployment systems. The PLI scheme for manufacturing competitiveness indirectly supports domestic fabrication capacity buildout. Tier-two and tier-three cities remain underpenetrated relative to established Mumbai and Delhi logistics corridors.
Heavy Duty Ramp Market Competitive Landscape
Concentration sits with vertically integrated steel fabricators and modular aluminum specialists serving distinct specification tiers. The vendor base spans captive distribution networks, e-commerce channels, and rental fleet service integrators. Three archetypes dominate: steel-focused dock equipment manufacturers, aluminum portable system engineers, and broad-assortment digital distributors. Capacity expansion in aluminum extrusion and strategic partnerships with logistics real estate developers represent the dominant competitive vectors.
Among United States-based manufacturers, Bluff Manufacturing and Discount Ramps occupy distinct positioning poles. Bluff Manufacturing exemplifies the steel fabrication archetype with controlled distribution to industrial accounts. Discount Ramps anchors the e-commerce breadth strategy, reaching rental services and smaller fleet operators across multiple geographies. Thorworld Industries represents the modular aluminum engineering approach, with UK-based operations serving rapid-deployment requirements in European logistics yards.
| Leading Market Players |
|---|
| Discount Ramps |
| Heavy Duty Ramps |
| Bluff Manufacturing |
| Marshall Industrial |
| DOCKZILLA |
| TVH |
| Thorworld Industries |
| Altam |
| Quality Material Handling |
| Others |
Pricing and Supply Chain Analysis
Aluminum alloy substitution for structural steel in portable ramp fabrication simultaneously redraws supply geography toward secondary smelters and compresses pricing premiums historically commanded by steel-focused incumbents. This material shift forces buyers to recalibrate total cost of ownership models around fuel economy compliance rather than upfront unit economics.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on AWS D1.2 welding certification grade and volume scale commitments. Cost compression in economy-tier steel ramps is intensifying because Chinese anti-dumping tariffs have raised landed input costs. Rental fleet operators show highest price sensitivity due to high-turnover utilization models, while German automotive logistics hubs demonstrate lowest sensitivity given just-in-sequence reliability requirements.
Supply Chain Analysis
Inventory lead times for certified aluminum extrusions have extended due to AWS D1.2 qualification bottlenecks in North American fabrication labor pools. Primary supply draws from the United States, Germany, and China. Raw material dependencies center on 6061-T6 and 6082-T6 aluminum grades, structural steel feedstock, and cerium-based anti-slip coating formulations. Tariff exposure on Chinese steel imports constitutes the dominant supply chain risk. Distribution runs through national rental chain account structures in Texas and California, alongside controlled industrial distribution for dock equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The heavy duty ramp market sits at a platform-economics inflection where telematics-enabled load monitoring creates interoperability between ramp assets and fleet management software ecosystems. This integration shift transforms hardware procurement into recurring-revenue service relationships.
For Market Incumbents: Fortify captive aluminum extrusion capacity and AWS D1.2 certified welding labor pools to defend against modular aluminum specialists eroding share in rapid-deployment segments. Deepen backward integration into secondary aluminum supply to buffer scrap price volatility. Prioritize certification investment for telematics integration to capture predictive maintenance contract revenue. For New Entrants and Emerging Players: CE marking fast-track programs for carbon fiber-reinforced hybrid constructions open immediate access to German automotive logistics hubs and Leipzig-Halle air cargo operators. India's tier-two and tier-three cities represent the most penetrable geography given 45 million square feet of annual warehouse capacity additions. Pursue direct relationships with logistics real estate developers as anchor tenants for new distribution nodes. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed aluminum portable system engineers holding European rapid-deployment expertise but lacking North American rental fleet relationships. Five-to-ten year viability hinges on telematics integration capabilities and carbon border adjustment readiness. Monitor EU Green Deal procurement preference shifts in public infrastructure tenders as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive 6061-T6 supply secures margin stability against scrap volatility for US fabricators. |
| Telematics Platform Partnership | IoT load sensor integration with fleet management software enables predictive maintenance contracts. |
| CE Marking Fast-Track Investment | Accelerated REACH-compliant coating qualification opens German automotive logistics procurement. |
| Logistics Real Estate Developer Alliance | Anchor tenant positioning in India tier-two cities captures 45 million square feet annual warehouse buildout. |
| AWS D1.2 Certification Program Expansion | Qualified welding labor pools reduce lead times for certified ramp assemblies serving OSHA-mandated upgrades. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with logistics fleet managers, plant engineers at automotive OEMs, rental equipment procurement directors, and aluminum fabrication facility operators. Secondary validation drew from OSHA regulatory filings, EPA industrial emissions disclosures, REACH substance restriction updates, and customs trade data for aluminum and steel feedstock. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across material grades and end-use verticals.
Across the analysis window, volume and value outputs were derived from modeling deployment context, material specification tier, load capacity rating, and regional regulatory cluster as primary segmentation dimensions. CAGRs were computed from fitted growth curves incorporating aluminum alloy substitution rates, e-commerce fulfillment network expansion, and fleet fuel economy compliance timelines. Industry-specific forecast inputs included logistics real estate development pipelines and welding certification labor pool constraints.
The analysis sits within stated boundaries; outcomes outside sustained aluminum scrap supply availability or OSHA enforcement intensity would require recalibration. Forecasts reflect documented assumptions around material substitution velocity and regulatory harmonization progress. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Chute Liners Market
Material Handling Equipment
Hose Pump Market
Material Handling Equipment
Vibrating Conveyor Market
Material Handling Equipment
Pneumatic Conveying Diverters Market
Material Handling Equipment
Hooklifts Market
Material Handling Equipment
Global Submersible Slurry Pumps Market
Material Handling Equipment
Circular Stacker and Reclaimer Market
Material Handling Equipment
Global Conveyor System Market
Material Handling Equipment
Stair Lifts and Climbing Devices Market
Material Handling Equipment
Die Casting Market
Material Handling Equipment
Slitting Machines Market
Material Handling Equipment
Forklift Truck Market
Material Handling Equipment
Cable Duct Market
Material Handling Equipment
Automatic Conveyor Market
Material Handling Equipment
Truck Mounted Cranes Market
Material Handling Equipment
Global Bucket Loader Market