
 Aluminum Die Casting Machinery Market | 2026-2036
Aluminum Die Casting Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Die Casting Machinery Market Analysis
Electric servo-motor integration into clamping and injection systems is rewriting the performance benchmarks for aluminum die casting machinery, replacing conventional hydraulic architectures with precision-controlled electromechanical alternatives. Buhler AG leverages its Swiss engineering heritage to dominate high-end cold chamber platforms for automotive structural castings. Toshiba Machine Co., Ltd. anchors its competitive position through deep R&D intensity in robotic casting automation. L.K. Technology Holdings Ltd. extends manufacturing scale across Asian supply chains to compete on cost-adjusted throughput.
Aluminum die casting machinery comprises industrial equipment designed to inject molten aluminum alloy into precision-machined steel dies under high pressure, typically operating at clamping forces from 250 to 4,000 tons and cycle times under 90 seconds for thin-walled automotive components. Cold chamber machines command the largest installed base due to their suitability for aluminum's high melting point, though automated die casting cells integrating robotic extraction and trimming represent the fastest-expanding margin pool as labor costs rise. Pressure casting technology leads volume throughput for engine block and transmission housing applications, while vacuum die casting commands premium positioning where porosity-sensitive structural EV components require aerospace-grade integrity.
The US EPA enforces foundry emissions standards under the National Emission Standards for Hazardous Air Pollutants, compelling machinery investments with integrated fume capture and thermal recovery systems. China's MIIT mandates GB energy-efficiency classifications that restrict market access for legacy hydraulic designs below specified performance thresholds. The EU Green Deal's carbon border adjustments are reshaping sourcing calculus for European automotive parts manufacturers evaluating machinery lifecycle emissions. Stakeholders must weigh servo-electric capital premiums against regulatory compliance timelines and evolving OEM supplier sustainability scorecards.
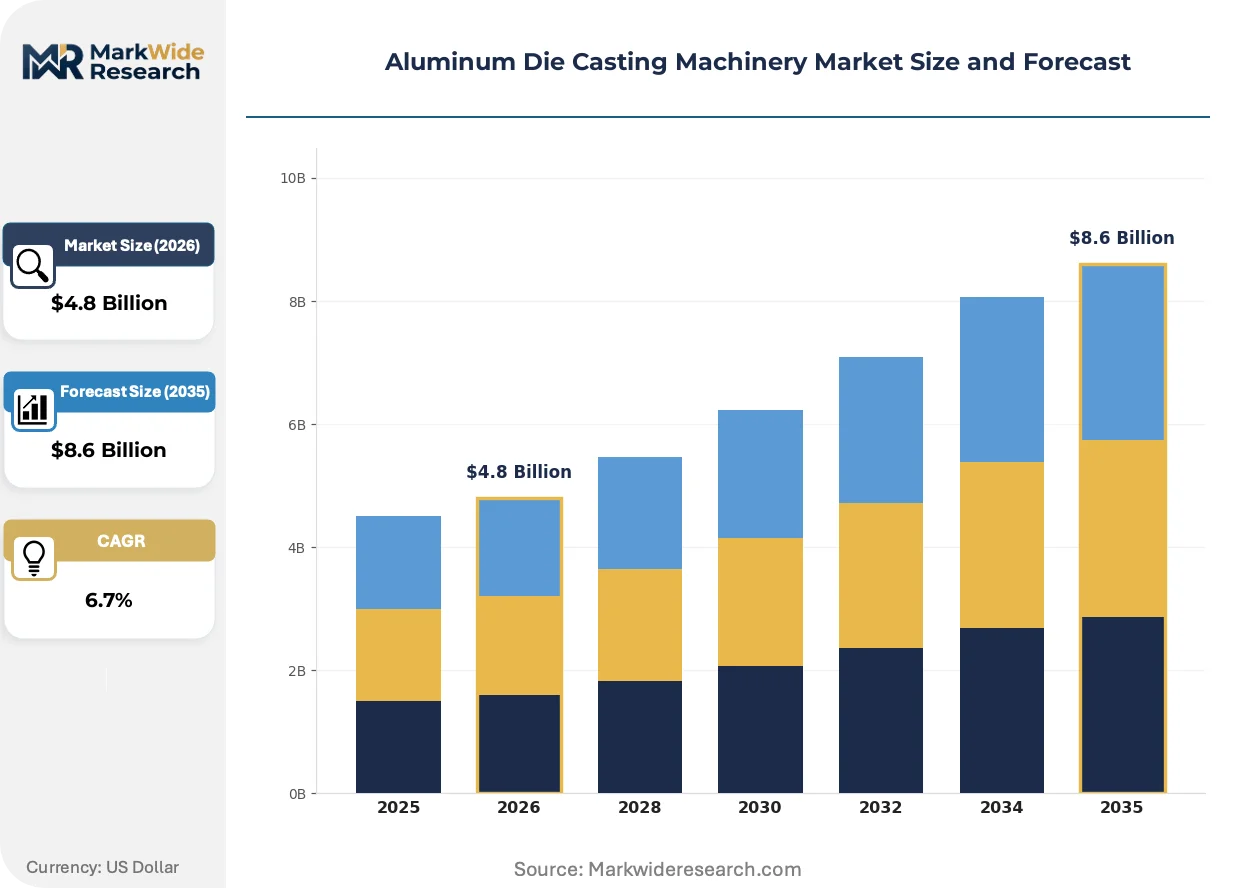
Market Dynamics
Servo-electric machine architectures are compressing hydraulic equipment margins as China's MIIT energy-efficiency mandates force foundry retooling decisions across multiple continents.
Growth Catalysts
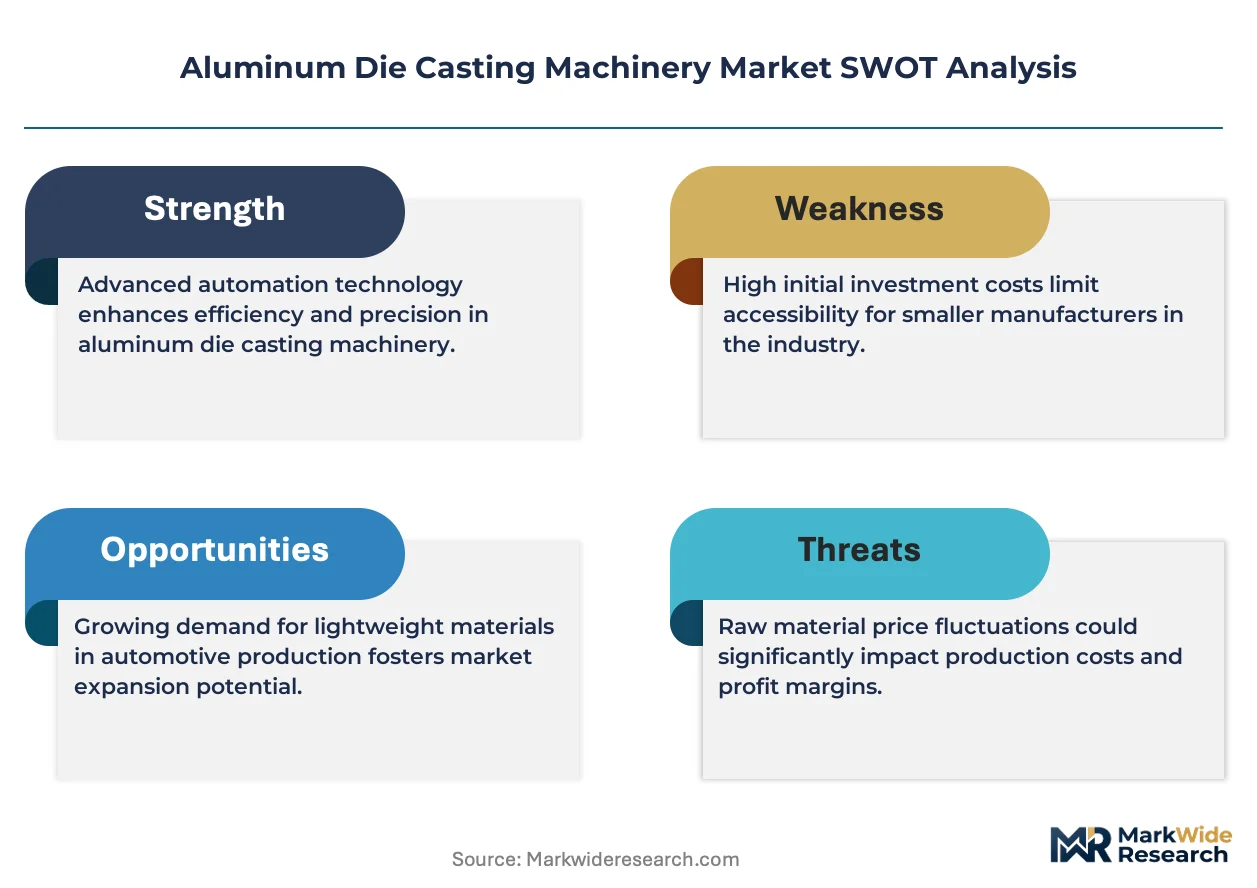
- EV Structural Component Demand:Automotive OEMs in Germany's Stuttgart-Munich corridor are commissioning high-pressure casting cells for lightweight battery housings and motor enclosures.
- MIIT GB Standards:China's tightened energy-efficiency classifications for foundry equipment are accelerating replacement cycles for legacy hydraulic machines.
- Robotic Automation Integration:Automated die casting cells with robotic extraction and trimming are capturing margin pools as labor costs escalate in precision manufacturing.
Market Restraints
- Servo-Electric Capital Premiums:Electromechanical clamping and injection systems carry higher upfront costs than conventional hydraulic alternatives, stretching payback periods for mid-tier foundries.
- Specialized Technician Scarcity:Servo-motor integration and precision control systems require skilled maintenance personnel that remain concentrated in Germany, Japan, and Switzerland.
- Aluminum Price Volatility:Primary aluminum input cost fluctuations compress machinery purchasing budgets during commodity upswings.
Strategic Opportunities
- Vacuum Die Casting Expansion:Porosity-sensitive structural EV components are creating premium positioning for vacuum-assisted technology in aerospace-grade integrity applications.
- EU Green Deal Carbon Border Adjustments:European automotive parts manufacturers are reevaluating machinery lifecycle emissions in supplier sustainability scorecards.
- India Manufacturing Scale-Up:Foundry equipment demand is accelerating as domestic automotive production expands and PLI scheme incentives attract component manufacturing investment.
Industry Challenges
- Retrofit Integration Complexity:Legacy hydraulic foundries face technical friction grafting servo-electric subsystems into existing plant configurations without full line replacement.
- EPA NESHAP Compliance Timelines:US foundries must coordinate machinery investments with integrated fume capture and thermal recovery systems to meet hazardous air pollutant standards.
- Cross-Border Certification Divergence:Machinery builders navigate incompatible safety and performance certifications between GB standards, CE marking, and OSHA requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Die Casting Machinery Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Chamber Machines, Hot Chamber Machines, Automated Die Casting Machines, Hybrid Die Casting Machines End User: Automotive Parts Manufacturers, Consumer Electronics, Aerospace Components, Industrial Equipment Technology: Robotic Casting, Pressure Casting, Gravity Casting, Vacuum Die Casting Application: Parts for Engines, Structural Components, Enclosures, Decorative Items |
| Companies Covered | Buhler AG, Toshiba Machine Co., Ltd., TOYO Machinery and Metal Co., Ltd., Ube Industries, Ltd., L.K. Technology Holdings Ltd., SHIBAURA MACHINE CO., LTD., Oskar Frech GmbH + Co. KG, Idra Group, Italpresse Gauss, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Die Casting Machinery Market Emerging Trajectories
Precision control technologies and emissions accountability are rewriting equipment specifications, compressing cycle times while expanding the boundary of what aluminum castings can structurally achieve.
Electromechanical servo drives are rendering obsolete hydraulic power units in clamping and injection systems. Tier 1 automotive suppliers in Germany and Japan are specifying all-electric architectures for new high-pressure casting cells. The shift is compressing maintenance intervals and energy consumption benchmarks while eliminating hydraulic fluid contamination risks in cleanroom-adjacent production environments.
The EU Green Deal's carbon border adjustment mechanism is recalibrating machinery procurement calculus for European automotive parts manufacturers. Lifecycle emissions documentation now factors into supplier scorecards alongside unit economics. Foundry equipment with integrated thermal recovery and fume capture systems is commanding preference in Germany, Italy, and France as OEMs harden Scope 3 reduction commitments.
Outcome-based service contracting is displacing traditional break-fix maintenance arrangements in high-volume foundry operations. Equipment builders in Japan and Switzerland are bundling performance guarantees with uptime commitments and predictive analytics subscriptions. The model is concentrating in Germany's automotive supplier belt where unplanned downtime costs exceed preventive service premiums by substantial margins.
Aluminum Die Casting Machinery Market Segmentation
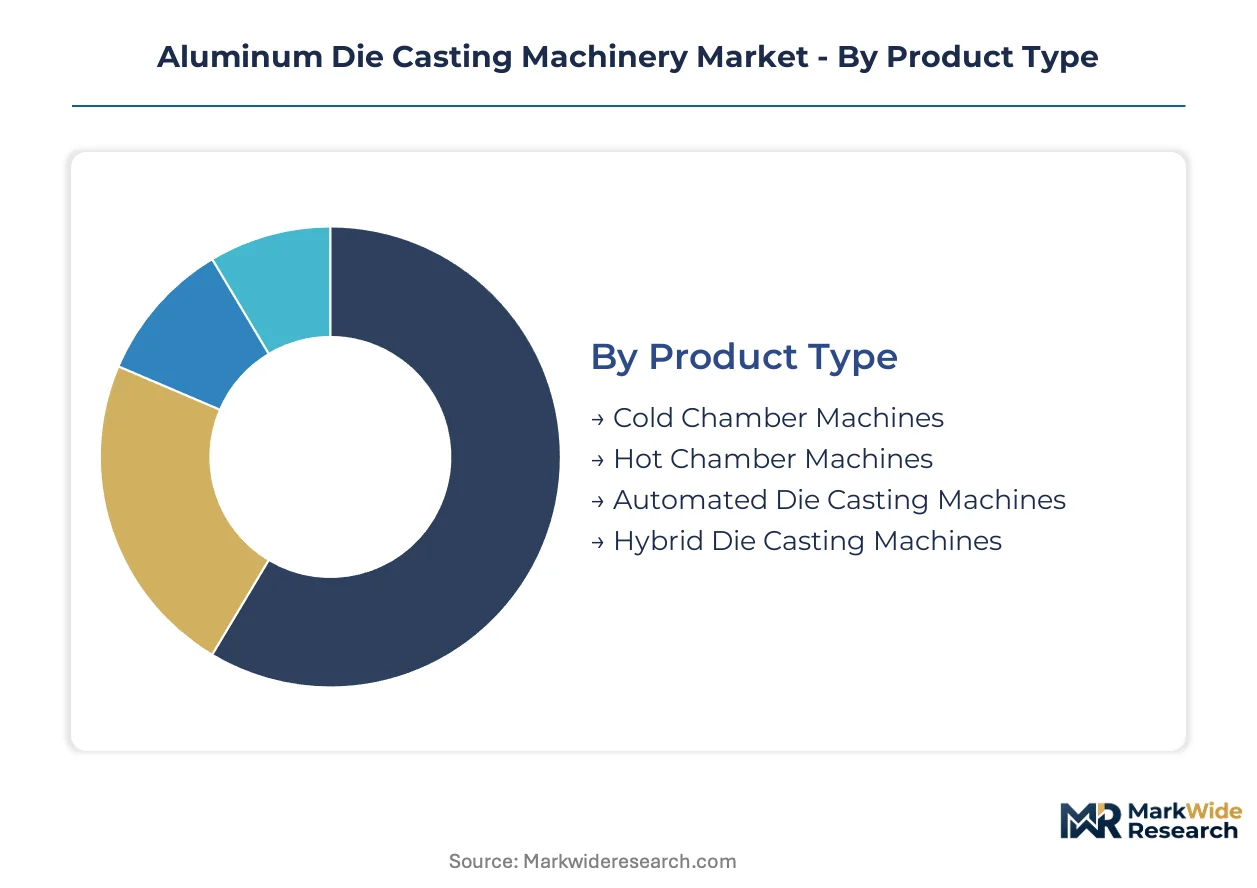
Equipment specification varies sharply across aluminum die casting machinery segments. Product architecture determines energy efficiency compliance, cycle speed, and capital intensity. End-use concentration in automotive powertrain and emerging EV structural applications is reshaping segment priorities.
Product Type:
Use-case spectrum spans legacy hydraulic installations through fully electric architectures, with each configuration carrying distinct regulatory and operational profiles.
- Cold Chamber Machines:Steel die casting systems engineered for aluminum's elevated melting point, utilizing separate furnaces and ladling mechanisms. Demand concentrates among German Tier 1 automotive suppliers retooling for EV motor housings and battery enclosures, driven by MIIT energy-efficiency mandates eliminating legacy hydraulic alternatives.
- Automated Die Casting Machines:Integrated cells combining robotic extraction, trimming, and quality inspection with precision injection control. Japanese and Swiss equipment builders are capturing margin expansion in Stuttgart's automotive supplier belt as labor costs escalate and unplanned downtime penalties stiffen.
- Hot Chamber Machines:Zinc and magnesium-focused systems with immersed gooseneck injection, limited aluminum applicability due to corrosion susceptibility.
- Hybrid Die Casting Machines:Servo-hydraulic architectures blending electric precision with hydraulic force multiplication, positioned for mid-tier foundries navigating capital constraints.
The dominant share belongs to Cold Chamber Machines, while Automated Die Casting Machines is closing the gap fastest.
End User:
Customer concentration reflects automotive OEM supplier consolidation and emerging electronics manufacturing scale.
- Automotive Parts Manufacturers:Tier 1 and Tier 2 suppliers producing powertrain housings, transmission cases, and structural EV components. Germany's Stuttgart-Munich corridor anchors equipment demand as domestic producers commission high-pressure casting cells for lightweight battery enclosures.
- Consumer Electronics:Laptop chassis, smartphone frames, and wearable device housings requiring thin-wall precision. Chinese contract manufacturers are expanding vacuum die casting adoption for porosity-sensitive enclosures.
- Aerospace Components:Structural brackets and housings demanding aerospace-grade integrity with vacuum-assisted porosity control.
- Industrial Equipment:Pump housings, valve bodies, and machinery frames serving general manufacturing and agricultural equipment.
Automotive Parts Manufacturers commands the largest equipment installed base, with Consumer Electronics expanding most quickly on electronics miniaturization trends.
Technology:
Process innovation is compressing cycle times while expanding structural applications for aluminum castings.
- Pressure Casting:High-velocity molten metal injection at forces exceeding 1,000 bar, optimized for thin-walled engine blocks and transmission housings. Volume throughput leadership persists in German and Japanese automotive supplier networks.
- Vacuum Die Casting:Chamber evacuation preceding injection eliminates gas porosity for structural EV components requiring weldability and heat treatability. Premium positioning strengthens as EU Green Deal carbon border adjustments harden supplier sustainability scorecards.
- Robotic Casting:Automated ladling, extraction, and finishing integrated with machine control systems.
- Gravity Casting:Low-pressure permanent mold filling for thick-section components with reduced porosity sensitivity.
Pressure Casting retains volume leadership, though Vacuum Die Casting gains share fastest on EV structural integrity requirements.
Application:
Component specification determines machine selection across thermal, structural, and aesthetic requirements.
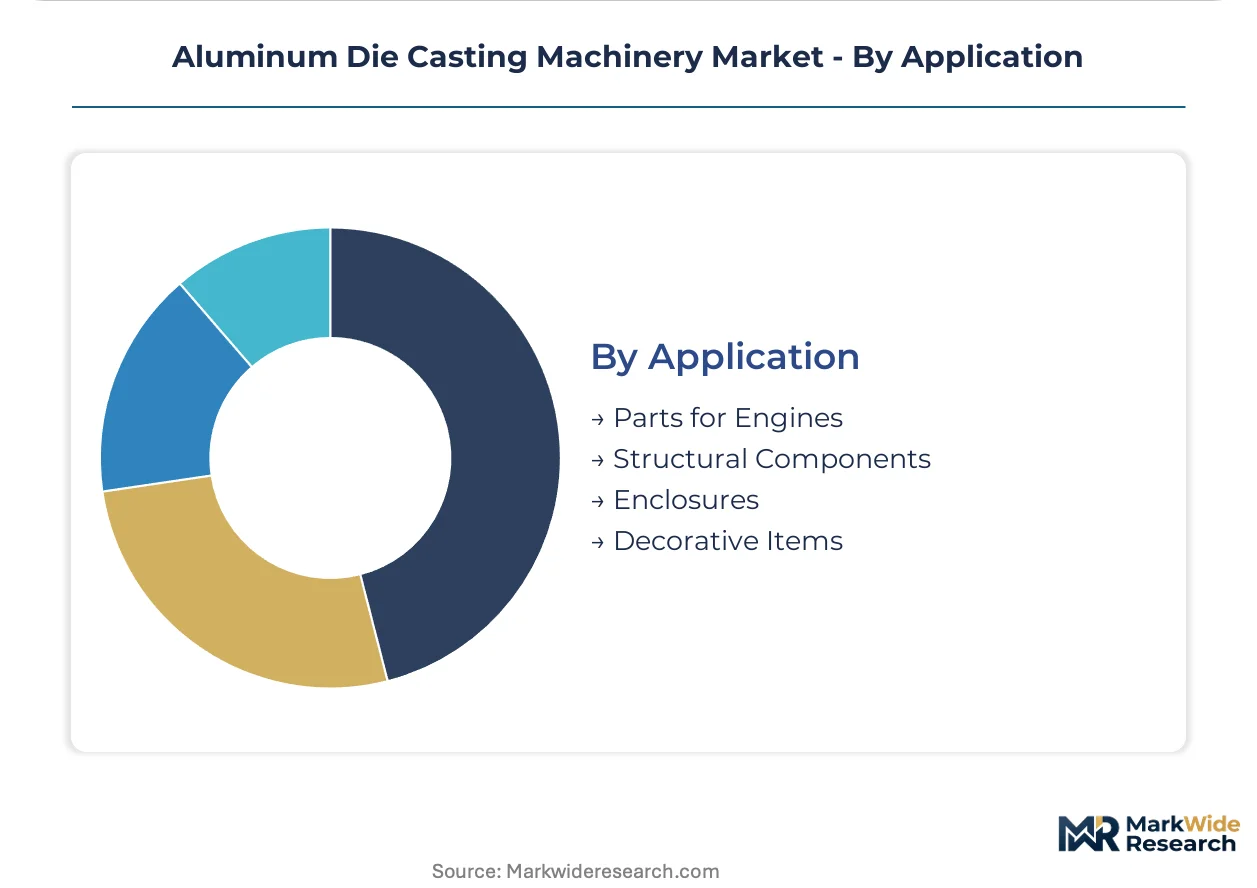
- Parts for Engines:Cylinder heads, blocks, and transmission cases requiring pressure-tight integrity under thermal cycling. German automotive suppliers dominate specification setting for high-volume powertrain castings.
- Structural Components:EV battery housings, motor enclosures, and chassis elements substituting steel stampings. China's MIIT efficiency standards are accelerating foundry retooling for these lightweight applications.
- Enclosures:Protective housings for electronics, motors, and industrial equipment.
- Decorative Items:Architectural hardware, lighting fixtures, and consumer goods prioritizing surface finish over mechanical properties.
Parts for Engines holds the largest historical installed base, while Structural Components climbs the fastest on EV platform proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment exports flow into automotive supplier networks across China, Japan, and the United States, establishing transcontinental technology transfer corridors for high-pressure casting architectures.
Germany
Stuttgart and Munich anchor Europe's densest concentration of Tier 1 automotive suppliers retooling for EV structural component production. The EU Green Deal's carbon border adjustment mechanism is hardening supplier sustainability scorecards and favoring machinery with integrated thermal recovery. Baden-Württemberg's automotive supplier belt is commissioning vacuum die casting cells for porosity-sensitive battery housings.
China
Domestic automotive production scale and electronics manufacturing expansion are driving foundry equipment demand across the Yangtze and Pearl River Deltas. MIIT's tightened GB energy-efficiency classifications are accelerating replacement cycles for legacy hydraulic machines below specified performance thresholds. Zhejiang and Guangdong provinces are absorbing servo-hydraulic and electric machine architectures as OEMs comply with dual carbon goals.
Japan
Precision manufacturing heritage and robotic automation integration are sustaining equipment demand from domestic automotive and electronics sectors. METI's industrial efficiency guidelines are nudging foundries toward electromechanical architectures with compressed maintenance intervals. The Nagoya-Toyota industrial corridor is specifying all-electric high-pressure casting cells for lightweight powertrain applications.
United States
Reshoring momentum in automotive component manufacturing and defense-related castings is stimulating machinery investment across the Midwest and Southeast. EPA enforcement of National Emission Standards for Hazardous Air Pollutants is compelling foundries to integrate fume capture and thermal recovery systems into new equipment purchases. Michigan and Ohio's automotive supplier networks are upgrading cold chamber installations for EV platform compatibility.
India
Domestic automotive production expansion and PLI scheme incentives for component manufacturing are accelerating foundry equipment demand in western and southern states. The country's national industrial efficiency regulator is tightening energy consumption benchmarks for heavy manufacturing equipment. Maharashtra and Tamil Nadu are absorbing automated die casting cells as labor costs escalate in precision manufacturing clusters.
Aluminum Die Casting Machinery Market Vendor Landscape
On the supply side, the industry is tiered between premium Swiss and Japanese engineering houses, scale-driven Chinese manufacturers, and specialized European mid-cap fabricators. Equipment builders concentrate in three strategic archetypes: precision-engineering specialists commanding technology premiums, high-volume manufacturers competing on cost-adjusted throughput, and integrated automation providers bundling robotic cells with performance guarantees. Dominant competitive moves include geographic expansion through localized assembly operations and strategic partnerships for servo-electric technology licensing.
Within the precision-engineering tier, Buhler AG and Toshiba Machine Co., Ltd. exemplify contrasting geographic anchors for technology leadership. Buhler AG occupies a position rooted in Swiss engineering heritage for high-end cold chamber platforms. Toshiba Machine Co., Ltd. represents Japanese R&D intensity in robotic casting automation. L.K. Technology Holdings Ltd. sits within the scale-driven archetype, extending manufacturing presence across Asian supply chains.
| Leading Market Players |
|---|
| Buhler AG |
| Toshiba Machine Co., Ltd. |
| TOYO Machinery and Metal Co., Ltd. |
| Ube Industries, Ltd. |
| L.K. Technology Holdings Ltd. |
| SHIBAURA MACHINE CO., LTD. |
| Oskar Frech GmbH + Co. KG |
| Idra Group |
| Italpresse Gauss |
| Others |
Supply Flow & Price Mechanics
The Rhine-Alpine freight corridor's container cost dynamics amplify supply concentration effects for German automotive suppliers while compressing price differentiation between servo-electric and hydraulic machine tiers. Machinery builders leverage Stuttgart-Munich logistics proximity to extract technology premiums, yet rising aluminum ingot transport costs from Rotterdam are forcing mid-tier foundries toward hybrid architectures that balance capital constraints with MIIT compliance deadlines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Swiss-engineered all-electric cells from Japanese servo-hybrid platforms and Chinese hydraulic legacy systems. Price differentiation centers on energy-efficiency certification tier and robotic automation bundling, with EU Green Deal carbon documentation commanding substantial premiums. Cost compression in standard-tier equipment is intensifying because Chinese OEMs are absorbing margin to secure MIIT-compliant market share. Mid-tier foundries in India and Southeast Asia exhibit highest price sensitivity, while German Tier 1 suppliers prioritize total cost of ownership over upfront capital.
Supply Chain Analysis
Primary aluminum feedstock draws from Chinese smelters, Russian ingot producers, and Australian bauxite refiners, with secondary scrap recycling expanding across European foundry networks. Critical component dependencies include high-grade steel dies from German toolmakers, servo motors from Japanese precision manufacturers, and robotic arms from Swiss automation specialists. Supply chain risk centers on single-source vulnerability for large-tonnage clamping cylinders sourced from Italian and German specialists. Distribution runs through OEM-direct channels for premium architectures and regional equipment distributors for mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against polymer composite and stamped steel alternatives that threaten aluminum's structural component dominance. Incumbents must harden technology moats while new entrants exploit geographic white space and investors target consolidation-arbitrage opportunities.
For Market Incumbents: Pre-empt servo-electric commoditization by locking in exclusive supply agreements for rare-earth servo motors and securing backward integration into precision die manufacturing. Defensive patent filings around vacuum-assisted casting controls will raise rival capital requirements, while capacity addition in Tamil Nadu and Maharashtra captures India's PLI-driven demand surge before Chinese competitors localize assembly. For New Entrants and Emerging Players: India's western and southern states present the most penetrable geography, with domestic automotive expansion outpacing local machinery supply and PLI incentives reducing effective customer procurement costs. Target vacuum die casting subsystems as the entry wedge, licensing core clamping technology from European mid-caps while developing indigenous robotic integration capabilities. A go-to-market angle emphasizing lifecycle emissions documentation aligns with EU automotive supplier scorecard requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized foundry equipment divisions, particularly those lacking servo-electric R&D depth or Asian manufacturing footprint. Long-term viability hinges on regulatory tailwinds for energy-efficient equipment persisting across multiple compliance cycles. The signal to watch is MIIT enforcement intensity against sub-GB-standard hydraulic imports, which would accelerate replacement demand and validate premium technology valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electric Technology Licensing | Japanese precision manufacturers monetize R&D depth through cross-border partnerships with Chinese OEMs. |
| Regional Assembly Localization | Swiss and German builders reduce landed cost exposure in India and Southeast Asia through captive facilities. |
| Vacuum Die Casting Subsystem Development | Specialist suppliers capture EV structural component premiums as porosity standards tighten. |
| Outcome-Based Service Contracting | Equipment builders lock in recurring revenue through uptime guarantees and predictive analytics subscriptions. |
| Backward Integration into Die Manufacturing | Machinery OEMs secure tool steel supply and accelerate customer lead times for complex castings. |
Methodological Framework
Desk research of customs trade databases, equipment registration filings, and MIIT energy-efficiency certification records preceded structured interviews with foundry plant managers, OEM procurement directors, aftermarket service heads, and robotics integration specialists. Primary fieldwork across Germany's Stuttgart-Munich corridor, China's Yangtze River Delta, and India's Maharashtra-Tamil Nadu manufacturing clusters was validated against secondary sources including SEC filings of listed machinery builders and automotive production databases. Bottom-up equipment shipment tallies were triangulated against top-down foundry capacity expansion announcements.
Assumptions held fixed include MIIT GB standard enforcement timelines, EU carbon border adjustment implementation scope, and primary aluminum price band stability, while variables tested included EV platform proliferation rates and robotic labor substitution elasticity. Segmentation modeling spanned machine architecture, automation level, end-use industry, and regional regulatory cluster dimensions. CAGRs were derived from logistic diffusion curves fitted to technology substitution patterns, with inputs including foundry energy cost trajectories and automotive lightweighting content-per-vehicle targets.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed equipment consortia or sudden aluminum price spikes would shift outcomes substantially. Cross-checking against customs import data for large-tonnage casting machinery is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Industrial Machinery Market
Construction Equipment and Machinery
Concrete Floor Grinding Machine Market
Construction Equipment and Machinery
Grouting Machine Market
Construction Equipment and Machinery
Hydraulic Shop Crane Market
Construction Equipment and Machinery
Milling Machine Market
Construction Equipment and Machinery
Grader Machinery Market
Construction Equipment and Machinery
India Lathe Machines Market
Construction Equipment and Machinery
Lattice Cranes Market
Construction Equipment and Machinery
Europe Metal Fabrication Equipment Market
Construction Equipment and Machinery
Hydraulic Chainsaw Market
Construction Equipment and Machinery
Global Woodworking Machinery Market
Construction Equipment and Machinery
Shaper & Shaping Machine Market
Construction Equipment and Machinery
Global Hydraulic Ironworker Machine Market
Construction Equipment and Machinery
Global Hydraulic Demolition Machine and Breaker Market
Construction Equipment and Machinery
Latin America Paper Making Machine Market
Construction Equipment and Machinery
Injection Molding Machine Market