
 Sway Bar Bushing Market | 2026-2036
Sway Bar Bushing Market Size, Share, and Industry Trends Forecast 2026-2036
Sway Bar Bushing Market Analytics
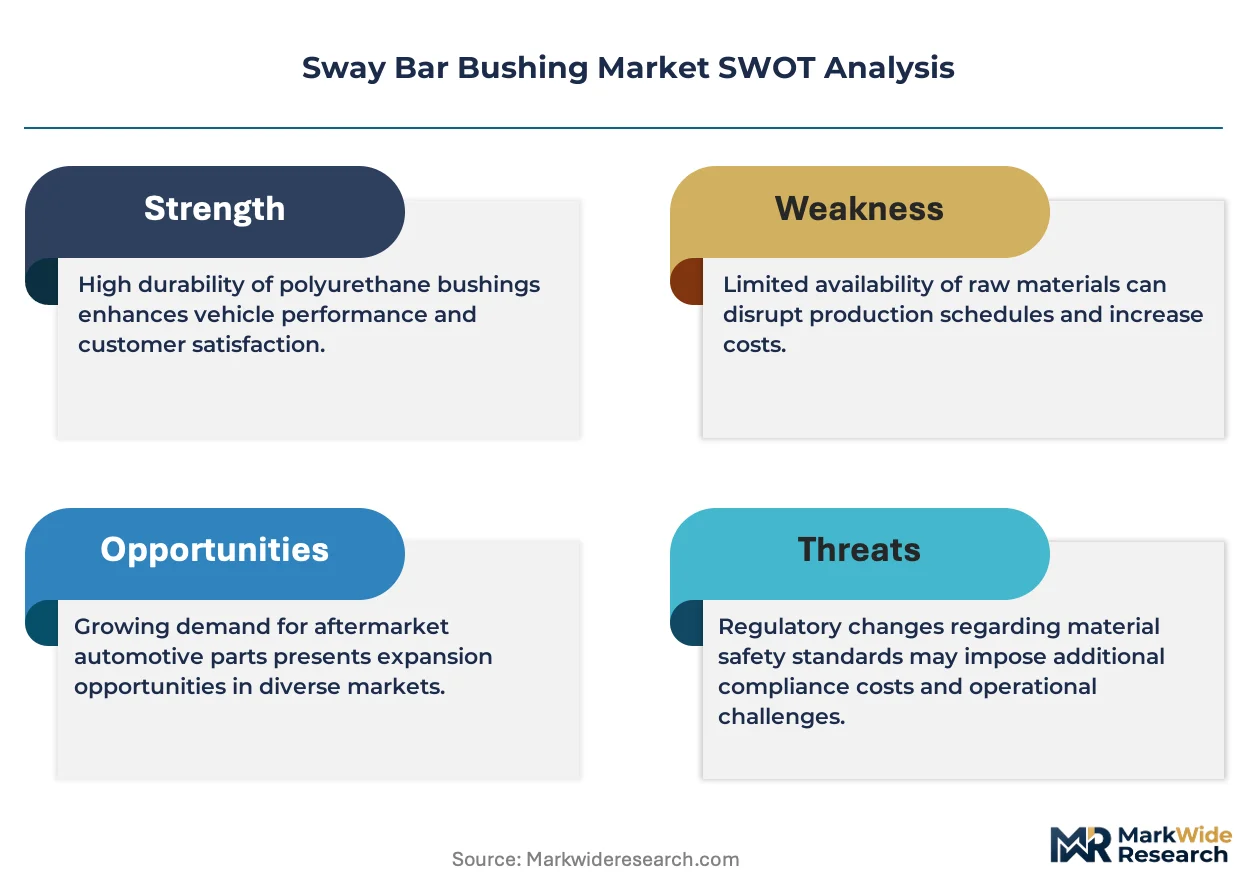
Thailand is rewriting regional supply patterns through expanded elastomer compounding and suspension component manufacturing. Tenneco leverages vertical integration across rubber formulation and stamped metal brackets to control cost positions in OEM channels. Energy Suspension specializes in castable polyurethane systems that outperform conventional rubber in desert and high-UV climates. Schaeffler Group anchors European demand through its chassis systems division, supplying precision-molded bushings to German premium automakers.
A sway bar bushing is an elastomeric or metallic cylindrical sleeve that isolates an anti-roll bar from the vehicle chassis while permitting controlled rotational movement, typically manufactured through compression molding of natural rubber compounds or injection molding of thermoplastic polyurethane with specified durometer ratings between 60A and 95A shore hardness. Its primary commercial purpose is to maintain suspension geometry alignment, reduce noise-vibration-harshness transmission, and preserve steering response predictability across duty cycles. Polyurethane bushings command premium positioning in racing cars and performance aftermarket channels where deflection tolerance below two millimeters justifies higher replacement frequency. Rubber formulations dominate passenger car OEM fitments where ride comfort and cost efficiency outweigh durability extremes. Metal-sleeved variants occupy heavy-duty vehicle segments where load ratings exceed fifteen thousand kilograms and bushing crush resistance prevents premature failure.
Federal Motor Vehicle Safety Standards administered by NHTSA govern lateral stability thresholds that indirectly mandate bushing integrity in US-market vehicles. EPA regulations on volatile organic compound emissions from rubber curing processes constrain compounding plant locations and capital deployment. REACH restrictions on aromatic oils and plasticizers within the European Union are accelerating reformulation investments among compounders serving EMA-regulated automotive suppliers. Stakeholders must monitor divergence between regional chemical compliance regimes and assess captive compounding capacity as a strategic hedge against supply interruption.
Market Dynamics
China's MIIT fuel economy mandates and NHTSA vehicle stability requirements are compressing design cycles for suspension component suppliers, forcing simultaneous compliance with divergent regional testing protocols while OEMs demand lighter, more durable elastomer formulations.
Growth Catalysts
- MIIT Fuel Economy Mandates:China's tightening corporate average fuel consumption standards are compelling automakers to reduce unsprung mass, driving specification of advanced polyurethane bushings with lower hysteresis losses in chassis applications.
- Light Truck Fleet Prioritization:Commercial fleet operators in the United States are extending vehicle replacement intervals, creating sustained aftermarket pull for high-durometer rubber variants rated beyond 85A shore hardness.
- Stuttgart-Wolfsburg Supplier Corridor:Germany's concentrated automotive engineering ecosystem accelerates co-development cycles between tier-one chassis integrators and compounders specializing in dynamic stiffness tuning.
Market Restraints
- Natural Rubber Price Volatility:Southeast Asian latex supply disruptions and currency fluctuations in Thailand and Indonesia are compressing gross margins for compounders lacking forward-contract hedging mechanisms.
- REACH Aromatic Oil Restrictions:ECHA's classification of high-aromatic process oils as substances of very high concern is forcing costly reformulation of conventional rubber compounds ahead of sunset date enforcement.
- Metal Sleeve Substitution:Heavy-duty vehicle manufacturers above fifteen thousand kilogram ratings are migrating toward fully metallic spherical bearings in high-load suspension nodes, eroding addressable volume in the upper weight class.
Strategic Opportunities
- Desert Climate Aftermarket:Australia's high-UV, abrasive-dust operating environments are creating premium positioning for castable polyurethane systems with enhanced ozone and thermal aging resistance.
- EPA VOC Compliance Arbitrage:Rubber curing plants with installed regenerative thermal oxidizers can capture displaced volume from competitors facing capital constraints under tightened volatile organic compound emission ceilings.
- 3D-Printed Fixture Convergence:Hybrid manufacturing workflows combining injection-molded bushings with topology-optimized metal brackets are reducing tooling lead times for low-volume performance vehicle programs.
Industry Challenges
- Durometer Specification Tolerance:OEM chassis engineers are narrowing acceptable shore hardness bands to plus-or-minus two points, requiring compounders to retool mixing sequences and extend quality verification cycles.
- Cross-Regional Certification Complexity:Suppliers must maintain parallel test matrices for NHTSA FMVSS lateral stability validation, ECE R14 anchorage requirements, and GB/T Chinese national standards without unified mutual recognition protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sway Bar Bushing Market |
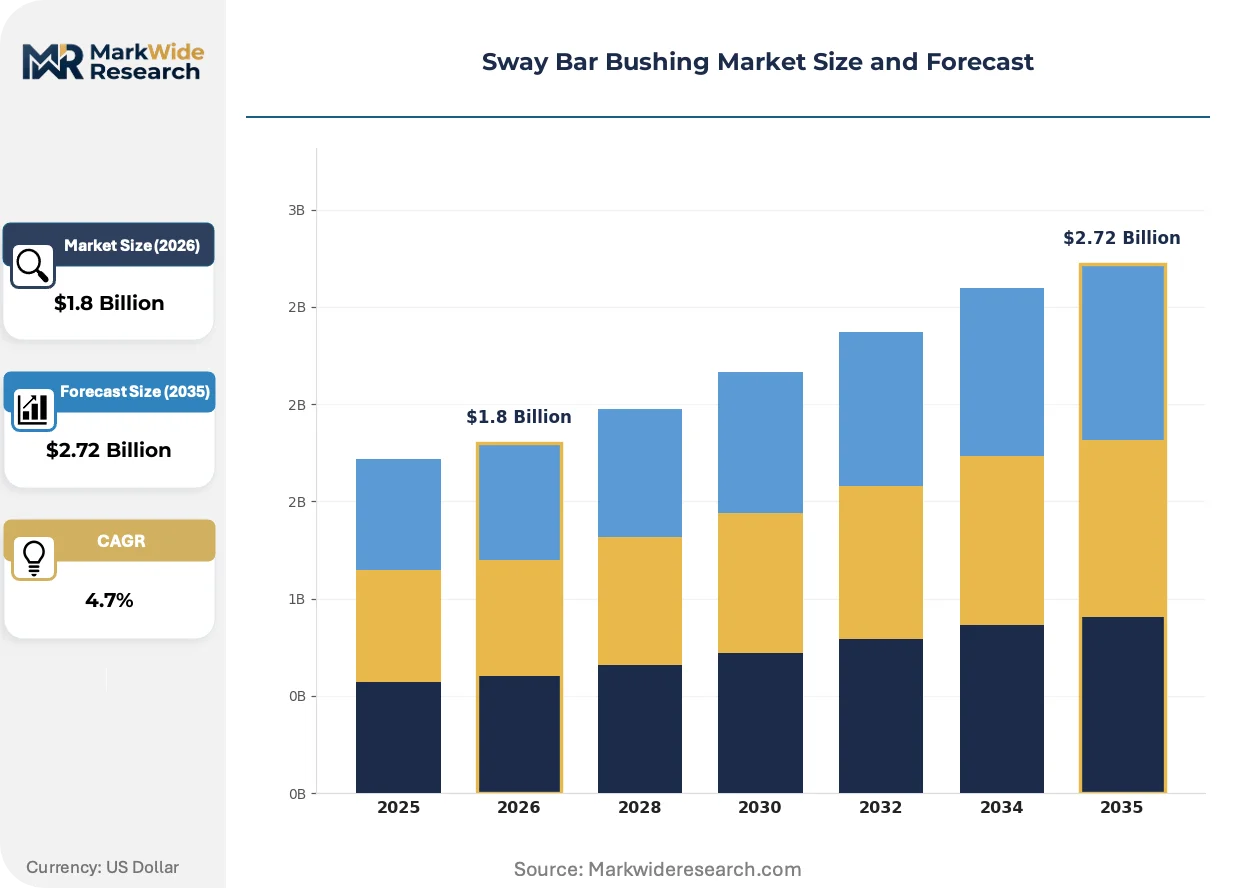
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber, Polyurethane, PTFE, Metal End User: OEMs, Aftermarket Providers, Dealerships, Automotive Enthusiasts Application: Passenger Cars, Light Trucks, Heavy-Duty Vehicles, Racing Cars Installation Type: Front Suspension, Rear Suspension, Independent Suspension, Solid Axle |
| Companies Covered | Benteler International AG, Delphi Technologies, Tenneco, Energy Suspension, SuperPro, ZF Friedrichshafen AG, Dorman Products, Febi Bilstein, Schaeffler Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sway Bar Bushing Market Evolving Landscape
Material science advances and regulatory fragmentation are converging to reshape how sway bar bushings are specified, manufactured, and distributed across passenger, commercial, and performance vehicle segments.
Thermoplastic polyurethane formulations with dynamic mechanical analysis-tuned loss factors are hybridizing traditional rubber-dominated OEM supply chains. Tier-one chassis suppliers in Germany and Japan are qualifying these materials for series production at accelerated pace. The technology is hybridizing procurement patterns by enabling single-source supply agreements that span both compression-molded rubber and injection-molded polyurethane within unified platform architectures.
REACH restrictions on aromatic oils and plasticizers are forcing compounders serving EMA-regulated automotive suppliers to eliminate extender oils above three percent polycyclic aromatic content. Industrial consequence includes accelerated migration toward bio-based process oils and hydrogenated nitrile rubber alternatives. Premium passenger car segments in France and Germany are responding fastest, with Schaeffler Group and Continental integrating reformulated compounds ahead of mandatory compliance deadlines.
Fleet maintenance departments are unbundling suspension component replacement from bundled dealer service contracts, creating direct procurement relationships with aftermarket specialists. Independent repair channels in the United States are displacing authorized service networks for light truck bushing replacement cycles. This behavioral shift concentrates most visibly in Texas and California commercial fleet hubs where total cost-per-mile metrics override brand-loyalty considerations in sourcing decisions.
Sway Bar Bushing Market Segmentation
After-sales service intensity varies dramatically across sway bar bushing segments, with polyurethane variants requiring replacement at one-third the interval of rubber equivalents while commanding triple the unit economics. Fleet operators and performance enthusiasts generate disproportionate lifetime value through repeat purchase cycles that OEM fitments rarely match.
Product Type:
Cost tier positioning determines margin architecture, with formulation chemistry and durometer precision separating premium compounds from commodity alternatives.
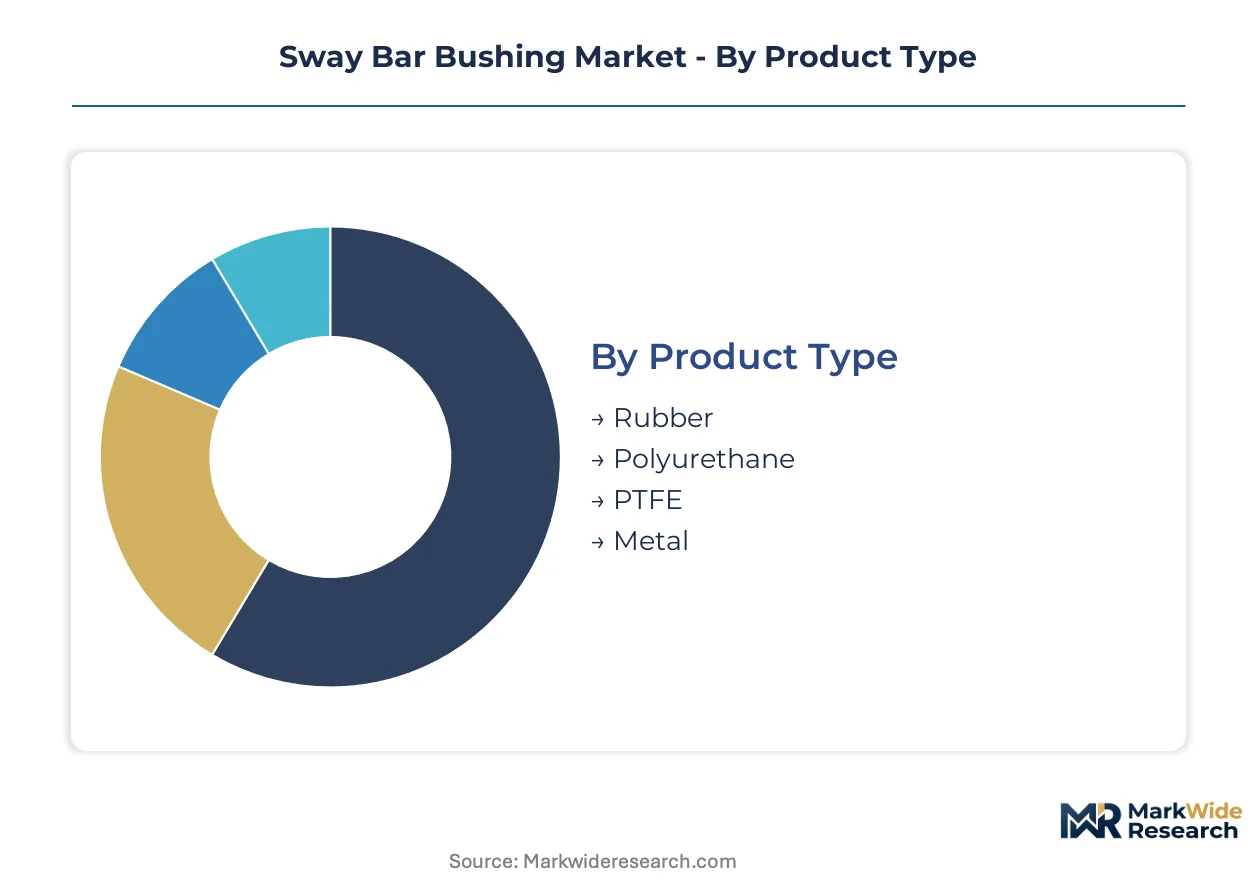
- Rubber:Natural and synthetic elastomer compounds processed through compression molding dominate passenger car OEM channels, where Stuttgart-based chassis integrators specify 70A-85A shore hardness for ride comfort optimization. German premium automakers and Japanese volume manufacturers anchor procurement volumes, though REACH aromatic oil restrictions are forcing compounders toward hydrogenated nitrile alternatives.
- Polyurethane:Injection-molded thermoplastic systems with 90A-95A durometer ratings deliver sub-two-millimeter deflection tolerance for racing and desert climate applications. Australia's high-UV operating environments and Texas fleet operators generate concentrated demand for castable formulations with enhanced thermal aging resistance.
- PTFE:Fluoropolymer-lined sleeves serve niche low-friction requirements in independent suspension architectures where maintenance-free operation justifies material cost premiums.
- Metal:Spherical bearings and sleeved assemblies occupy heavy-duty segments above fifteen thousand kilograms, with crush-resistant designs preventing premature failure in mining and construction vehicle suspensions.
By volume, rubber leads. By growth pace, polyurethane is climbing the fastest.
End User:
Customer type fragmentation creates divergent procurement patterns, with specification authority shifting between engineering departments and fleet maintenance managers.
- OEMs:Platform engineering teams at German and Japanese automakers integrate bushings during chassis development cycles, qualifying suppliers through dynamic stiffness tuning protocols and NVH validation matrices.
- Aftermarket Providers:Independent distributors in Texas and California commercial fleet hubs are displacing authorized service networks, with total cost-per-mile metrics overriding brand loyalty in sourcing decisions.
- Dealerships:Bundled service contracts still capture passenger car replacement cycles, though unbundling trends accelerate as vehicle owners seek direct component procurement.
- Automotive Enthusiasts:Performance-oriented consumers prioritize handling precision over ride comfort, driving specification of high-durometer polyurethane through specialized retail channels.
By installed base, OEMs dominate. By margin expansion, aftermarket providers are gaining share fastest.
Application:
Vehicle duty cycle intensity directly correlates with replacement frequency and material specification rigor.
- Passenger Cars:Comfort-optimized rubber formulations with 60A-75A shore hardness prioritize NVH isolation over dynamic response, with Chinese and European volume manufacturers specifying billions of units annually.
- Light Trucks:Commercial fleet operators in the United States extend replacement intervals through 85A+ durometer compounds, creating sustained pull for durability-rated variants.
- Heavy-Duty Vehicles:Load ratings exceeding fifteen thousand kilograms drive migration toward metal-sleeved or fully metallic spherical bearings in high-load suspension nodes.
- Racing Cars:Deflection tolerance below two millimeters justifies premium polyurethane positioning despite accelerated wear rates and higher replacement frequency.
By unit volume, passenger cars lead. By value per unit, racing cars command the steepest premium trajectory.
Installation Type:
Suspension architecture geometry dictates bushing load paths and rotational movement envelopes.
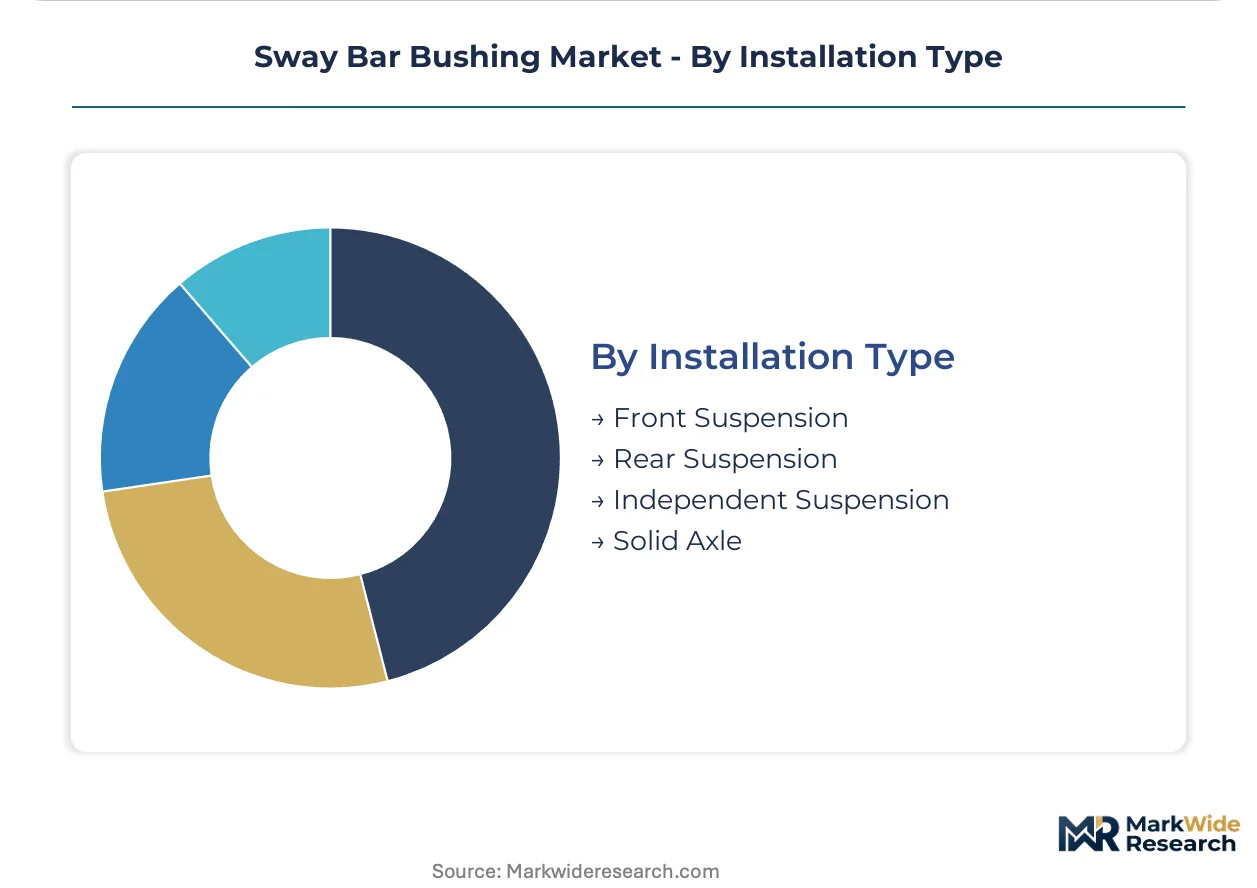
- Front Suspension:Steering response predictability requirements drive precision-molded specifications with tight tolerance bands, particularly in German premium vehicle platforms.
- Rear Suspension:Lateral stability mandates under NHTSA FMVSS protocols concentrate engineering attention on rear bar anchorage integrity.
- Independent Suspension:Multi-link architectures require compound bushings with differentiated stiffness characteristics across radial and axial load directions.
- Solid Axle:Heavy-duty commercial and off-road applications specify crush-resistant designs with reinforced metal sleeves for extreme load cycling.
By specification complexity, independent suspension leads. By standardization potential, solid axle offers the most streamlined procurement path.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European automotive component distribution, handling containerized elastomer compounds and precision-molded suspension parts for German OEM supply chains. This infrastructure underwrites the region's dominance in chassis system engineering and tier-one supplier concentration.
United States
Commercial fleet operators in Texas and California extend vehicle replacement cycles, driving specification of high-durometer rubber variants. NHTSA FMVSS lateral stability mandates tighten bushing integrity requirements for light truck applications. Detroit's automotive supplier corridor concentrates stamping and rubber-to-metal bonding operations for domestic OEM platforms.
Germany
Stuttgart-based chassis integrators co-develop dynamic stiffness-tuned bushings with premium automakers. REACH aromatic oil restrictions force compounders toward hydrogenated nitrile rubber alternatives ahead of ECHA sunset dates. Wolfsburg anchors volume production through Volkswagen Group's consolidated procurement of precision-molded suspension components.
China
MIIT corporate average fuel consumption standards compel automakers to reduce unsprung mass through advanced polyurethane formulations. GB/T national standards govern suspension component testing protocols distinct from ECE and FMVSS regimes. Yangtze River Delta manufacturing clusters around Shanghai integrate elastomer compounding with just-in-time chassis assembly for domestic EV platforms.
Thailand
Expanded natural rubber processing capacity serves regional OEM demand from Japanese transplant factories. The country's Board of Investment incentives attract suspension component manufacturers seeking ASEAN market access. Eastern Economic Corridor industrial zones concentrate tire and automotive rubber compounding operations with backward integration into latex supply chains.
Australia
High-UV desert operating environments generate concentrated demand for castable polyurethane systems with enhanced ozone resistance. TGA-equivalent automotive safety frameworks align with UN ECE regulations for aftermarket component certification. Melbourne and Sydney distribution hubs serve mining fleet operators prioritizing durability-rated suspension bushings for extreme duty cycles.
Sway Bar Bushing Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying elastomer formulations and precision-molded sleeves. The vendor base stratifies across three tiers: multinational chassis system houses with captive compounding, independent rubber compounders serving aftermarket channels, and polyurethane specialists targeting performance segments. Two dominant competitive moves define current positioning: backward integration into rubber formulation to secure raw material cost positions, and geographic expansion into Thailand and Mexico to capture regional OEM sourcing shifts.
Among European-headquartered system suppliers, Schaeffler Group and ZF Friedrichshafen AG exemplify the platform-integrator archetype with chassis systems divisions supplying precision-molded components. Tenneco represents the vertically integrated compounder-processor model with control spanning rubber formulation through stamped metal bracket assembly. Energy Suspension occupies the specialization tier as a polyurethane-focused supplier serving desert climate and performance aftermarket channels.
| Leading Market Players |
|---|
| Benteler International AG |
| Delphi Technologies |
| Tenneco |
| Energy Suspension |
| SuperPro |
| ZF Friedrichshafen AG |
| Dorman Products |
| Febi Bilstein |
| Schaeffler Group |
| Others |
Value Network & Pricing Analysis
Thailand's concentrated natural rubber processing capacity funnels latex derivatives into German and Japanese tier-one compounders, anchoring margin capture at the formulation stage while downstream stamping and bonding operations compete on scale efficiency. This upstream concentration leaves mid-tier aftermarket distributors exposed to feedstock volatility that OEMs hedge through captive supply agreements.
Pricing Analysis
REACH aromatic oil restrictions dictate the pricing tier structure across European automotive supply chains, forcing hydrogenated nitrile rubber alternatives to command 15-25% premiums over conventional compounds. Three-tier pricing structure across premium polyurethane, standard rubber, and economy metal-sleeved variants separates racing aftermarket channels from passenger car OEM fitments and heavy-duty commercial applications. Cost compression in rubber compounding is intensifying because ECHA sunset dates accelerate reformulation investments ahead of enforcement timelines. Fleet operators in Texas and California exhibit the highest price sensitivity, while German premium automakers prioritize dynamic stiffness precision over unit economics.
Supply Chain Analysis
Export-control restrictions on advanced polymer processing equipment limit technology transfer to Southeast Asian compounding facilities, constraining regional capability buildout despite raw material abundance. Manufacturing gravity centers on Germany, Thailand, and China, with Stuttgart-based chassis integrators, Eastern Economic Corridor rubber processors, and Yangtze River Delta EV assemblers anchoring distinct supply nodes. Formulation chemistry draws from Malaysian latex, Saudi petrochemical feedstocks, and German hydrogenated nitrile rubber imports. Single-source vulnerability concentrates in aromatic oil alternatives where ECHA restrictions have thinned qualified supplier pools. Distribution runs through Hamburg container terminals for European OEM channels and Port of Long Beach hubs for North American aftermarket fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT fuel economy mandates and NHTSA vehicle stability requirements are compressing design cycles, creating a high-growth disruption window for suppliers capable of simultaneous multi-regional compliance with lighter, more durable elastomer formulations.
For Market Incumbents: Harden backward integration into rubber formulation to secure cost positions against natural rubber price volatility emanating from Southeast Asian supply disruptions. Expand captive compounding capacity in Thailand's Eastern Economic Corridor as a strategic hedge against REACH-driven supply interruption in European channels. Prioritize dynamic stiffness tuning protocols that narrow shore hardness tolerance bands to plus-or-minus two points, locking in OEM platform engineering relationships. For New Entrants and Emerging Players: Pursue Australia's desert climate aftermarket as the most penetrable white-space target, where high-UV operating environments generate concentrated demand for castable polyurethane systems with enhanced ozone resistance. Target Texas and California commercial fleet hubs where total cost-per-mile metrics override brand loyalty and independent repair channels displace authorized service networks. Lead with direct procurement platforms that unbundle suspension component replacement from bundled dealer service contracts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with polyurethane-focused specialists serving performance aftermarket channels, where Energy Suspension-type business models command premium positioning in racing and desert climate applications. Five-to-ten year viability hinges on compounders' ability to navigate divergent regional chemical compliance regimes without stranded capacity. Watch for consolidation signals when REACH aromatic oil restrictions force sub-scale compounders toward distressed divestiture ahead of sunset date enforcement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber Formulation | Tenneco's captive compounding model controls cost positions across OEM procurement channels. |
| Geographic Expansion into Thailand | Eastern Economic Corridor incentives attract suspension manufacturers seeking ASEAN market access. |
| Multi-Regional Certification Investment | Suppliers maintaining parallel NHTSA FMVSS, ECE R14, and GB/T test matrices capture platform engineering slots. |
| Polyurethane Formulation R&D | Thermoplastic polyurethane systems with DMA-tuned loss factors hybridize traditional rubber-dominated supply chains. |
| Aftermarket Channel Direct Procurement | Fleet maintenance departments unbundling from dealer contracts create independent distributor relationships. |
Research Methodology
A spread of perspectives from OEM platform engineers, tier-one chassis integrators, aftermarket distributors, rubber compounders, and fleet maintenance managers converged on the working assumptions driving segmentation and growth estimates. Primary interviews with Stuttgart-based suspension specialists and Texas commercial fleet operators combined with secondary validation through vehicle production databases, customs and trade flow records, IHS Markit registration data, and regulatory filings from NHTSA, ECHA, and MIIT. Bottom-up unit economics triangulated against top-down market sizing across material type, end user, application, and installation type dimensions.
Demand-supply balance modeling anchored volume projections across the analysis window, with segmentation spanning rubber, polyurethane, PTFE, and metal product types; OEM, aftermarket, dealership, and enthusiast end users; passenger car, light truck, heavy-duty, and racing applications; and front, rear, independent, and solid axle installation configurations. CAGRs derived from regression analysis of historical replacement intervals, vehicle parc growth, and content-per-vehicle trends. Industry-specific inputs included MIIT corporate average fuel consumption trajectory, NHTSA lateral stability mandate implementation timing, and REACH aromatic oil restriction enforcement schedules.
Sensitivities concentrate around natural rubber price volatility, ECHA sunset date acceleration, and heavy-duty vehicle migration toward fully metallic spherical bearings. Forecasts reflect assumptions regarding sustained fleet operator replacement interval extension and polyurethane penetration rates in premium passenger car segments. Material shifts in regional chemical compliance regimes or abrupt latex supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Car Oil Filter Market
Powertrain
Italy Electro Hydraulic Power Steering Market
Powertrain
Automotive Half Shaft Market
Powertrain
South Korea Electro Hydraulic Power Steering Market
Powertrain
Racing Clutches Market
Powertrain
Automotive Chain Tensioners Market
Powertrain
Global Automotive Engine Belt and Hose Market
Powertrain
Power Liftgate for Automotive Market
Powertrain
Global Industrial Brakes and Clutches Market
Powertrain
Colombia Automotive Engine Oils Market
Powertrain
Automotive Turbocharger Market
Powertrain
Fuel Pumps Market
Powertrain
Engine Flush Market
Powertrain
Electric Two-Wheeler Powertrain and Range Validation Test Systems Market
Powertrain
South America Internal Combustion Engines Market
Powertrain
Automotive Vacuum Pump Market