
 Automotive Slipper Clutch Market | 2026-2036
Automotive Slipper Clutch Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Slipper Clutch Market Intelligence
Aftermarket providers serving performance enthusiasts is rotating share from traditional OEM supply chains as track-day culture penetrates mid-income rider segments across Asia and Southern Europe. EXEDY Corporation leverages its foundry-to-assembly vertical integration to control cost positions in mechanical slipper clutch production. Schaeffler Technologies AG & Co. KG anchors European premium supply through its torque-vectoring clutch architectures for sports car platforms. STM Italy SRL dominates racing-tier customization with billet-machined pressure plate designs that command specialist channel loyalty.
An automotive slipper clutch is a torque-limiting coupling that permits controlled rear-wheel slip during aggressive downshifting, typically incorporating a ramp-and-ball mechanism or multi-plate wet clutch pack with calibrated spring preload to prevent rear-wheel hop while preserving engine braking authority. The device serves primarily to enhance rider safety and reduce drivetrain stress in high-performance and racing applications where rapid deceleration events concentrate mechanical load. Mechanical technology continues to occupy the largest installed base due to its simplicity and rebuildability, though electronic actuation is gaining fastest in OEM sports car programs where clutch engagement maps integrate with stability control systems. Race application clutches carry the deepest margin pools because teams accept premium pricing for fractional weight savings and billet construction, while Standard product types face commoditization pressure from Asian volume manufacturers.
The US NHTSA and EPA jointly influence slipper clutch specification through motorcycle emissions and safety equipment mandates that affect how OEMs calibrate driveline behavior. Europe's ECHA REACH framework restricts friction material formulations, pushing suppliers toward ceramic-metallic composites that alter heat dissipation profiles and clutch plate wear rates. India's BIS certification requirements for replacement clutch assemblies create formal market access barriers that favor established suppliers with local testing partnerships. Stakeholders must monitor how powertrain electrification at the vehicle level reshapes clutch content per platform, since hybrid architectures may retain or eliminate mechanical decoupling devices depending on motor placement strategy.
Market Dynamics
Track-day culture penetration across mid-income rider segments in Asia and Southern Europe is restructuring demand flows, rotating share from OEM supply chains toward aftermarket channels as performance enthusiasts seek specialized mechanical and electronic clutch configurations.
Growth Catalysts
- Euro 5 torque-management mandates:European emission standards tighten integration between engine mapping and clutch behavior, forcing OEMs to source electronically actuated slipper clutches with calibrated engagement profiles.
- India commuter-to-performance upgrades:Rapid motorcycle displacement escalation in Indian metropolitan markets creates aftermarket demand for retrofit slipper clutch kits as riders transition from 100-150cc commuters to 300cc+ performance models.
- Ceramic-metallic friction materials:Heat-resistant composite formulations enable higher thermal capacity in compact multi-plate wet clutch packs, extending service intervals for track-day enthusiasts.
Market Restraints
- Palladium and steel input volatility:Friction plate substrates and pressure plate stampings face raw material price swings that compress margins for mechanical clutch assemblers without foundry captive supply.
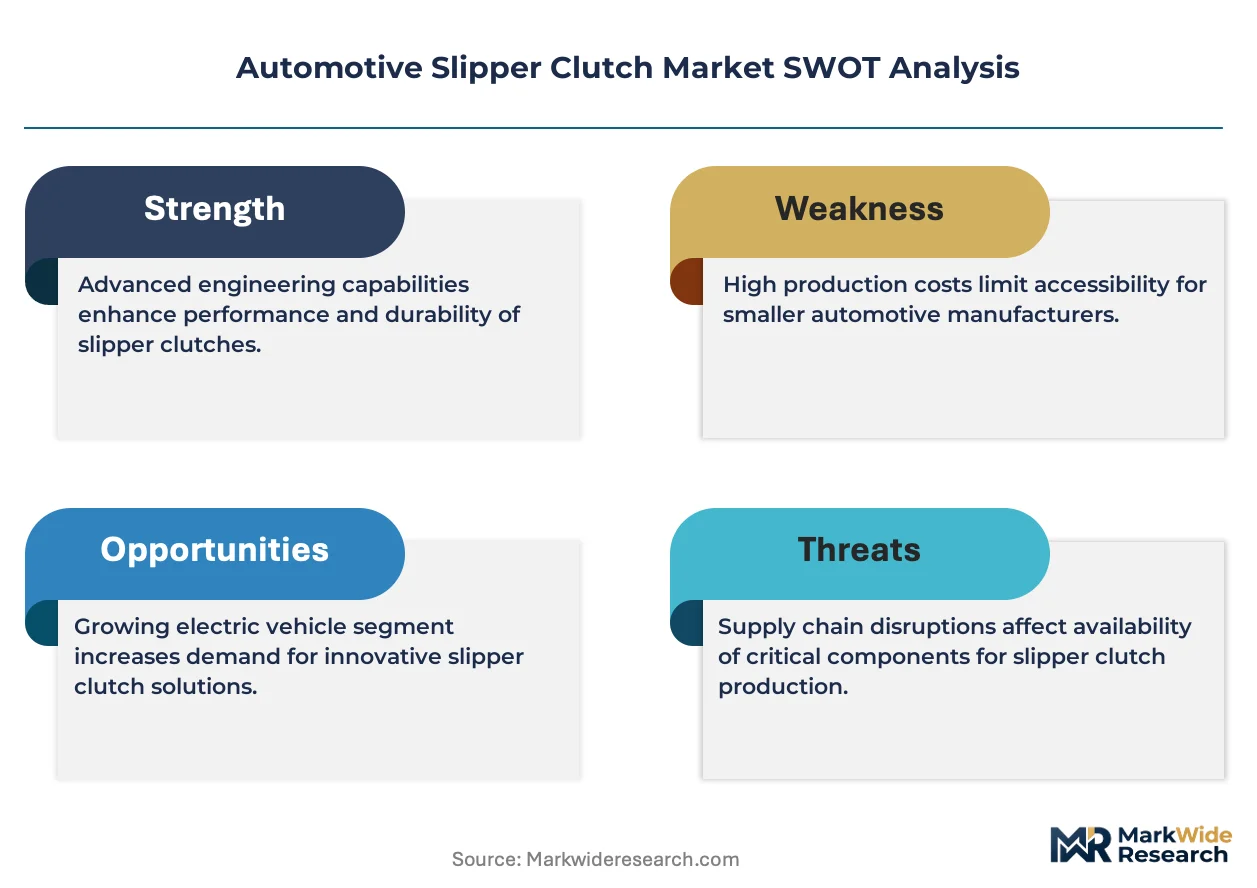
- European supply concentration:Premium torque-vectoring architectures for sports car platforms depend on a limited supplier base in Germany and Italy, creating single-source vulnerability for OEM sports car programs.
- Powertrain electrification substitution:Hybrid motor placement strategies in performance vehicles may eliminate mechanical decoupling devices entirely, threatening long-term clutch content per platform.
Strategic Opportunities
- India BIS certification partnerships:Local testing alliances with Bureau of Indian Standards accredited laboratories unlock formal aftermarket access for replacement clutch assemblies in the fastest-growing demand concentration point.
- Electronic-mechanical convergence:Integration of ramp-and-ball mechanisms with sensor-actuated preload adjustment creates adaptive slipper clutches that bridge racing performance and street usability.
- Direct-to-rider digital channels:Specialist e-commerce platforms bypass traditional distributor networks, capturing margin pools previously allocated to regional parts wholesalers in track-day enthusiast segments.
Industry Challenges
- Tribology and thermal modeling expertise:Shortage of engineers capable of simulating heat dissipation profiles across ceramic-metallic friction interfaces delays product development cycles for next-generation wet clutch packs.
- ECHA REACH compliance timelines:Reformulation of friction material chemistries to eliminate restricted substances extends certification periods, freezing product launches for 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Slipper Clutch Market |
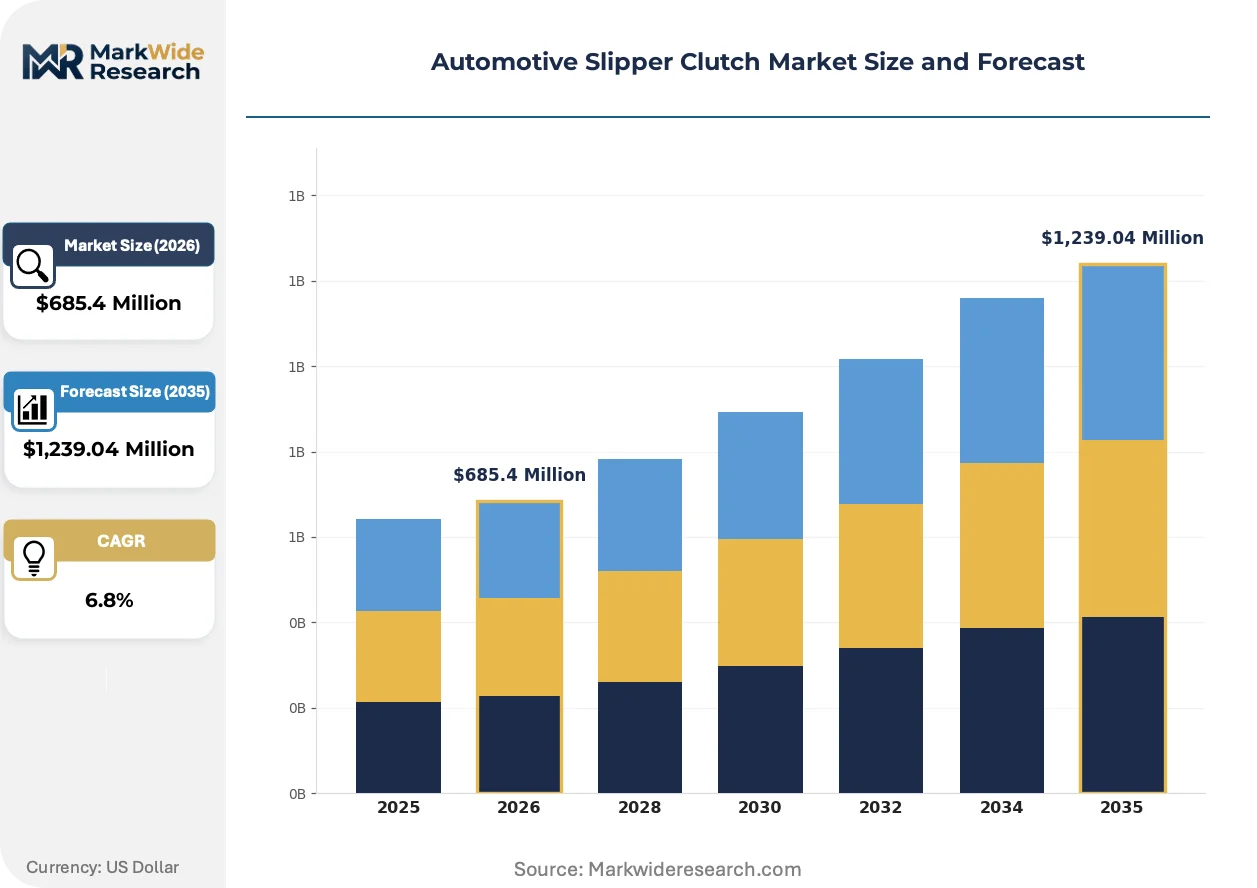
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Race, Off-Road, Custom Application: Motorcycles, Sports Cars, ATVs, Racing Vehicles End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Enthusiasts Technology: Hydraulic, Mechanical, Electronic, Pneumatic |
| Companies Covered | EXEDY Corporation, F.C.C. Co. Ltd, Hinson Racing, Hyper Racing Inc, Ricardo Plc, Schaeffler Technologies AG & Co. KG, Sigma Performance Limited, STM Italy SRL, SURFLEX SRL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Slipper Clutch Market Strategic Shifts & Innovations
Clutch technology development is splitting along performance-versus-integration axes as mechanical simplicity competes with electronic adaptability, reshaping how suppliers allocate R&D resources across racing and street applications.
Ramp-and-ball mechanical slipper clutches is bifurcating the installed base between rebuildable track-day units and sealed OEM modules. Racing teams and enthusiast riders favor billet-machined designs with serviceable internals, while volume manufacturers specify non-serviceable assemblies with integrated sensors. This split is compressing mid-tier mechanical suppliers unable to serve either extreme.
Europe's ECHA REACH framework restricts legacy friction material formulations containing copper and certain phenolic resins. Suppliers pivot toward ceramic-metallic composites that alter heat dissipation profiles and accelerate pressure plate wear rates. Racing-tier product categories absorb these material transitions fastest due to shorter replacement cycles and premium pricing tolerance.
Track-day participation widening across mid-income segments in Thailand, Malaysia, and Spain is fragmenting buyer profiles. Enthusiasts now self-install aftermarket slipper clutch kits using video tutorials, displacing traditional mechanic-channel dependence. This behavioral shift concentrates margin capture with specialized billet-machining houses and direct-shipping logistics providers rather than regional parts distributors.
Automotive Slipper Clutch Market Segmentation
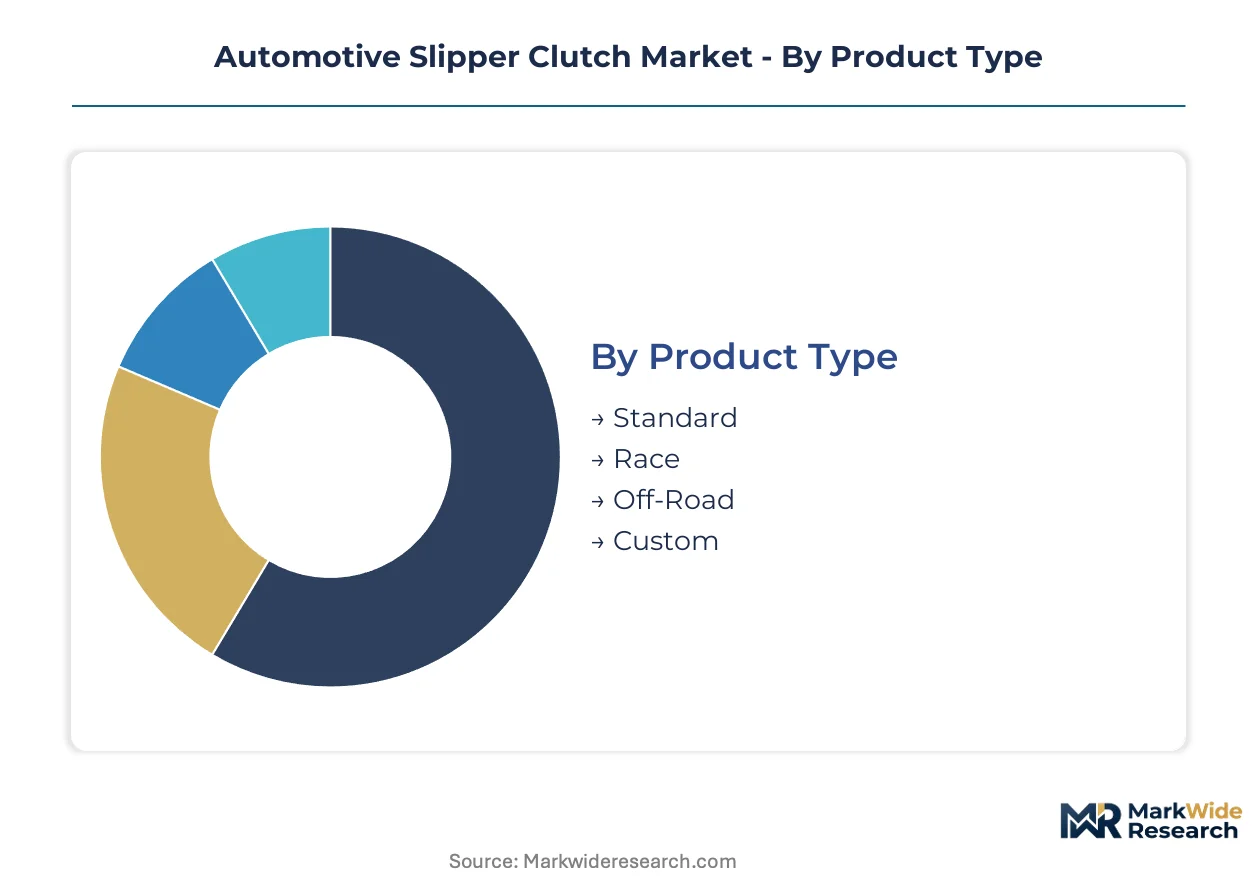
Slipper clutch segmentation reflects divergent pressure points from electrification, regulatory chemistry shifts, and rider behavior changes across performance tiers. Category boundaries are blurring as electronic actuation migrates downward from racing into street applications.
Product Type:
Race and Custom segments face acute substitution pressure from integrated electronic torque management in hybrid powertrains, while Standard and Off-Road categories retain mechanical resilience.
- Race:Billet-machined pressure plates with serviceable ramp-and-ball mechanisms deliver fractional weight savings and rapid rebuild cycles. Demand concentrates with track-day participants in Thailand and Spain where self-installation culture bypasses traditional service channels. Teams accept premium pricing for ceramic-metallic friction formulations that withstand sustained thermal loading.
- Standard:Non-serviceable multi-plate wet clutch packs with integrated preload springs dominate OEM fitment for commuter motorcycles. Volume manufacturers in India specify these units for 150-300cc platforms where cost discipline overrides serviceability requirements.
- Off-Road:Sealed mechanical assemblies resist contamination in dirt and enduro applications. Specialized friction materials accommodate intermittent water exposure without delamination.
- Custom:Specialist billet houses machine pressure plates to rider-specific preload profiles. Direct-to-consumer digital channels capture margins previously allocated to regional distributors.
Standard retains volume leadership; Race holds the steepest expansion curve.
Application:
Cost tier stratification separates premium sports car integration from mass motorcycle fitment, with ATV and racing vehicle categories occupying intermediate positions.
- Motorcycles:Dominant installed base spans 300cc+ performance models and emerging 150-200cc commuter upgrades in Indian metropolitan markets. Euro 5 torque-management mandates force tighter engine mapping integration for electronically actuated variants.
- Sports Cars:Torque-vectoring clutch architectures from German and Italian suppliers serve OEM programs where stability control integration demands sensor-actuated engagement profiles. Hybrid motor placement strategies threaten mechanical decoupling content per platform.
- ATVs:Recreational and utility applications specify robust mechanical assemblies with extended service intervals. Friction plate wear rates accelerate in high-torque agricultural deployments.
- Racing Vehicles:Purpose-built drag and circuit applications prioritize unsprung mass reduction over durability. Replacement cycles measured in hours rather than kilometers justify exotic material specifications.
Motorcycles command the largest unit base; Sports Cars are climbing the fastest as electronic integration spreads.
End User:
Volume concentration among OEM supply chains contrasts with margin capture migrating toward enthusiast-direct channels.
- OEMs:Volume procurement of non-serviceable assemblies with calibrated engagement maps for emissions compliance. Euro 5 integration requirements favor electronically actuated suppliers with foundry-to-assembly control.
- Aftermarket Providers:Fastest-expanding buyer segment as track-day culture penetrates mid-income rider segments across Asia and Southern Europe. Specialized distributors stock billet-machined kits for self-installation.
- Vehicle Assemblers:Contract manufacturing relationships for private-label clutch packs in emerging market motorcycle production.
- Enthusiasts:Direct procurement from specialist e-commerce platforms displaces traditional mechanic-channel dependence. Video tutorial availability enables self-installation of complex ramp-and-ball mechanisms.
OEMs retain volume leadership; Aftermarket Providers are gaining share fastest.
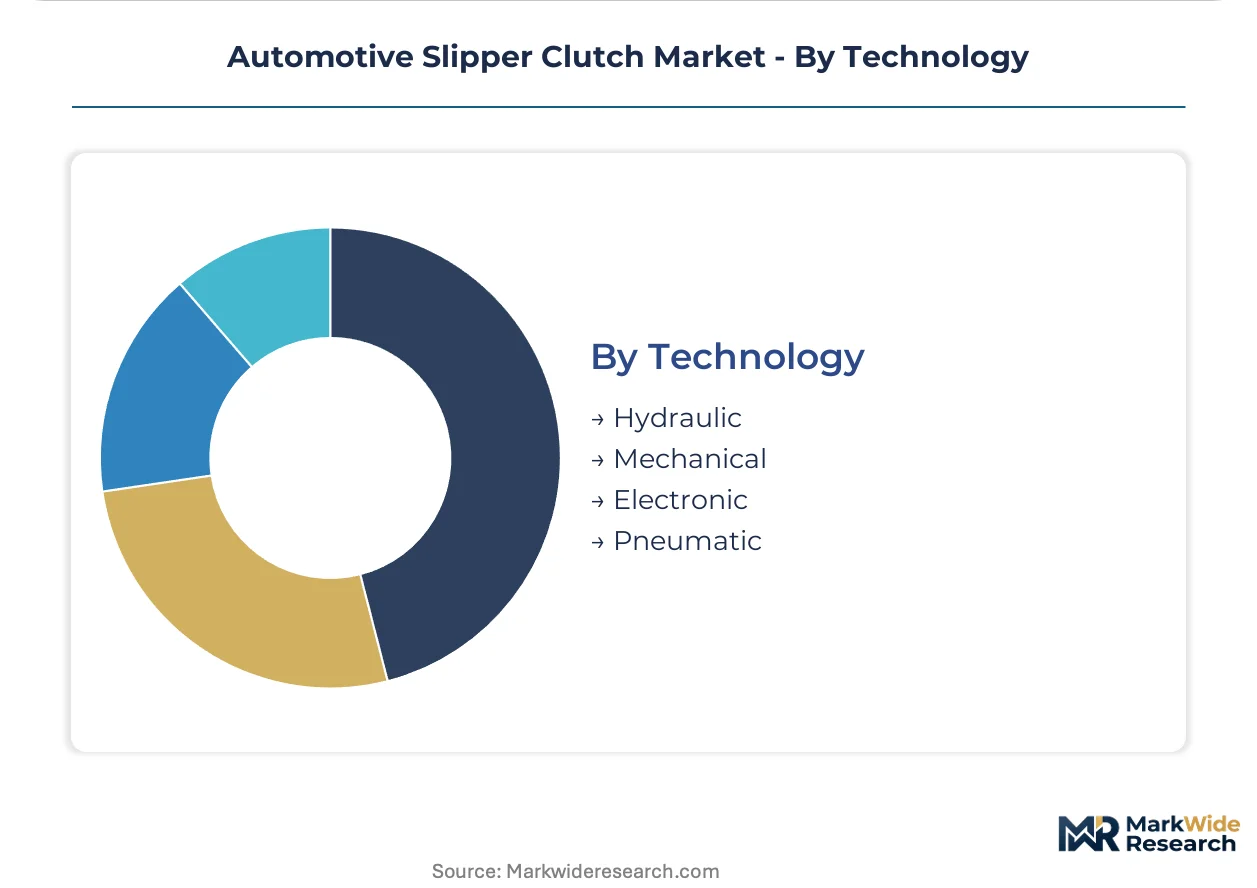
Technology:
Maturity gradients separate proven mechanical architectures from emerging electronic and pneumatic alternatives facing thermal and complexity barriers.
- Mechanical:Ramp-and-ball and multi-plate wet clutch packs occupy the largest installed base due to simplicity, rebuildability, and cost discipline. Foundry-captive suppliers control cost positions through in-house production of pressure plate stampings.
- Electronic:Sensor-actuated preload adjustment enables adaptive slip profiles that bridge racing performance and street usability. ECHA REACH compliance timelines for friction material reformulation extend product launch cycles.
- Hydraulic:Actuation systems for heavy-duty applications where cable routing proves impractical. Thermal management challenges limit adoption in compact motorcycle installations.
- Pneumatic:Compressed air engagement mechanisms for industrial and specialized racing applications. Complexity and maintenance overhead constrain mainstream penetration.
Mechanical retains volume leadership; Electronic shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian suppliers export billet-machined racing clutches to Thailand and Spain where track-day participation widens fastest, while German torque-vectoring architectures serve premium sports car programs across European OEM networks.
Germany
Schaeffler Technologies anchors European premium supply through torque-vectoring clutch architectures for sports car platforms. The KBA enforces stringent type-approval standards for electronic actuation systems that integrate with stability control. Stuttgart and Munich host development centers where OEMs calibrate clutch engagement maps for Euro 5 compliance.
Italy
STM Italy SRL dominates racing-tier customization with billet-machined pressure plate designs that command specialist channel loyalty. ECHA REACH restrictions on copper-based friction materials push suppliers toward ceramic-metallic composites. Bologna and Modena clusters concentrate precision machining capacity for track-day retrofit kits.
India
Commuter-to-performance motorcycle upgrades accelerate fastest in Indian metropolitan markets, creating aftermarket demand for retrofit slipper clutch kits. BIS certification requirements for replacement clutch assemblies favor established suppliers with local testing partnerships. Pune and Chennai manufacturing corridors supply domestic OEM fitment and export replacement markets.
Thailand
Mid-income rider segments penetrate track-day culture across Bangkok and Chiang Mai provinces, rotating demand toward aftermarket channels. The country's industrial standards regulator mandates quality benchmarks for imported friction materials. Eastern Economic Corridor clusters assemble Japanese and European brand motorcycles requiring localized clutch sourcing.
Spain
Southern European enthusiasts self-install aftermarket kits using video tutorials, displacing traditional mechanic-channel dependence. National environmental regulations align with EU-wide emission standards affecting engine mapping integration. Catalonia and Madrid metropolitan areas concentrate motorsport retail distribution for direct-to-rider digital channels.
Automotive Slipper Clutch Market Key Industry Players
Listed leaders compete with private specialists across technology tiers as foundry-captive assemblers battle sensor-integration specialists for OEM program wins. The market structure concentrates around three archetypes: vertically integrated mechanical producers, electronic actuation developers, and billet-machining customization houses. Dominant competitive moves include backward integration into foundry operations and strategic partnerships with BIS-accredited testing laboratories for Indian market access.
Among Japanese and German industrial conglomerates, EXEDY Corporation and Schaeffler Technologies AG & Co. KG exemplify scale-driven archetypes with in-house production capabilities spanning foundry-to-assembly control. STM Italy SRL occupies a specialist position within the racing-tier customization segment where billet-machined designs command premium positioning. These three entities represent contrasting strategic postures across mechanical simplicity, electronic integration, and bespoke performance engineering.
| Leading Market Players |
|---|
| EXEDY Corporation |
| F.C.C. Co. Ltd |
| Hinson Racing |
| Hyper Racing Inc |
| Ricardo Plc |
| Schaeffler Technologies AG & Co. KG |
| Sigma Performance Limited |
| STM Italy SRL |
| SURFLEX SRL |
| Others |
Cost & Logistics Intelligence
India's BIS certification requirements for replacement clutch assemblies gate both supply qualification and price differentiation simultaneously, forcing aftermarket entrants to absorb testing costs that established suppliers amortize across volume, while Euro 5 torque-management mandates in Europe create tiered pricing based on electronic integration depth.
Pricing Analysis
Current-generation electronic slipper clutches command substantial premiums over prior-generation mechanical ramp-and-ball units, while next-generation adaptive systems with sensor-actuated preload adjustment sit at the apex of pricing stratification across premium, standard, and economy tiers. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by certification grade and after-sales service bundling rather than hardware cost alone. Pricing pressure stems from palladium and steel input volatility compressing margins for mechanical clutch assemblers without captive foundry supply. OEM procurement teams exhibit lowest price sensitivity due to emissions compliance requirements, while Indian commuter-upgrade riders demonstrate highest sensitivity to kit pricing.
Supply Chain Analysis
Inventory cycles for ceramic-metallic friction materials extend lead times beyond mechanical clutch pack norms, compressing planning horizons for racing-tier suppliers. Manufacturing concentrates in Germany, Italy, and India, with precision machining clusters in Bologna and Stuttgart feeding racing applications while Pune and Chennai serve volume motorcycle production. Raw material dependencies center on palladium-bearing friction substrates, high-carbon steel stampings, and specialty aluminum alloys for billet housings. Single-source vulnerability threatens European sports car programs dependent on German torque-vectoring architectures. Distribution runs through specialist e-commerce platforms displacing traditional regional parts wholesalers in track-day enthusiast segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from rebuild kits and calibration services is expanding faster than hardware sales as track-day enthusiasts extend clutch lifecycles through preventive maintenance rather than replacement purchases.
For Market Incumbents: Consolidate backward integration into foundry operations to secure cost positions against palladium price volatility, while deepening BIS-accredited testing partnerships in India to defend aftermarket access against emerging local competitors. Electronic actuation specialists threaten mechanical incumbents through Euro 5 integration mandates that favor sensor-equipped suppliers. For New Entrants and Emerging Players: Lead with direct-to-rider digital channels targeting Thailand and Spain where self-installation culture bypasses established distributor networks, capturing margin pools previously allocated to regional parts wholesalers. White-space concentrates in billet-machined custom pressure plates for 300cc+ Indian commuter upgrades. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electronic-mechanical convergence architectures as sensor integration and thermal modeling expertise requirements escalate development costs. Long-term viability favors acquisition targets with tribology simulation capabilities and ECHA REACH-compliant friction material formulations. Watch for inflection when hybrid powertrain motor placement strategies stabilize clutch content per platform.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Operations | Captive supply of pressure plate stampings insulates margin from palladium and steel price swings. |
| BIS Certification Partnership | Local testing alliances with Bureau of Indian Standards unlock formal aftermarket access in fastest-growing demand concentration. |
| Electronic-Mechanical Convergence R&D | Adaptive slipper clutches with sensor-actuated preload bridge racing performance and street usability segments. |
| Direct-to-Rider E-Commerce Platform | Specialist digital channels bypass traditional distributors to capture margin pools in track-day enthusiast segments. |
| Ceramic-Metallic Friction Material Transition | ECHA REACH-compliant formulations extend service intervals while accelerating pressure plate replacement cycles. |
Research Approach
Initial hypotheses were tested against primary input from OEM platform engineers, aftermarket distributor procurement heads, racing team mechanics, and BIS-accredited laboratory directors and refined through secondary validation against vehicle production databases, IHS Markit registration data, customs/trade records, and SEC filings from listed clutch suppliers. Bottom-up unit economics triangulated against top-down market sizing across technology generations and application tiers.
Variance decomposition across product type, application, end user, and technology dimensions anchored the analytical framework over the projection horizon, with CAGRs derived from segment-level growth rate reconciliation against macro vehicle production forecasts. Modeled inputs included motorcycle displacement escalation curves in Indian metropolitan markets, Euro 5 compliance timelines affecting electronic actuation penetration, and track-day participation rates across Thailand and Spain.
Forecasts assume regulatory continuity in India's BIS certification regime and Europe's ECHA REACH framework; material policy shifts would require re-modeling friction material substitution curves and aftermarket access barriers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
South Africa Automotive Engine Oils Market
Powertrain
EV Powertrain-in-the-Loop (P-HIL) Test Benches Market
Powertrain
Global Automotive Clutch Market
Powertrain
Automotive Performance Tuning Market
Powertrain
Tachometer Market
Powertrain
Global Industrial Engine Market
Powertrain
Automotive Power Distribution Block Market
Powertrain
Automotive Driveline Market
Powertrain
Automotive Clutch Rotor Market
Powertrain
LNG Engine Market
Powertrain
Engine Support Bar Market
Powertrain
Brazil Automotive Engine Oils Market
Powertrain
North America Electrically Powered Hydraulic Steering Market
Powertrain
Europe Electrically Powered Hydraulic Steering Market
Powertrain
Synchronizer for Dual-Clutch Transmissions (DCT) Market
Powertrain
Turbocharger Market