
 Continuous Variable Transmission Market | 2026-2036
Continuous Variable Transmission Market Size, Share, and Industry Trends Forecast 2026-2036
Continuous Variable Transmission Market Outlook
ISO/TS 16949 automotive quality certification is bifurcating the supplier landscape into qualified tier-one integrators and excluded smaller vendors. ZF Friedrichshafen AG leverages its captive supply of torque converters and control modules to dominate European passenger vehicle programs. JATCO Ltd anchors volume production through dedicated CVT platforms for Japanese and Chinese original equipment manufacturers. Aisin Corporation differentiates through hybrid CVT architectures that bridge conventional and electrified powertrain demand.
A continuous variable transmission employs a continuously variable ratio mechanism, typically using a steel push-belt or chain running between variable-diameter pulleys, to maintain engine operation at optimal efficiency points across all vehicle speeds. The system eliminates fixed gear steps, reducing mechanical losses and enabling fuel consumption improvements of several percentage points over conventional automatic transmissions. Electronic CVT systems command the fastest expansion trajectory as torque converter lockup strategies and software-defined shift logic displace purely hydraulic architectures. Passenger vehicles retain the dominant value share, though agriculture equipment represents a concentrated margin pool where sealed-system durability under variable load cycles justifies premium pricing. Hybrid CVT configurations are gaining structural importance as automakers seek transmission solutions compatible with mild-hybrid and full-hybrid electrification without abandoning familiar mechanical layouts.
EPA corporate average fuel economy standards and NHTSA safety compliance requirements in the United States shape product development priorities, while EMA and REACH frameworks in Europe constrain material selection for belts and friction surfaces. China's MIIT enforces fuel consumption limits that directly incentivize CVT adoption in domestic vehicle segments. Stakeholders must monitor how dual carbon goals in Beijing and evolving EU Green Deal automotive standards recalibrate the competitive balance between mechanical efficiency gains and full electrification substitution risk.
Market Dynamics
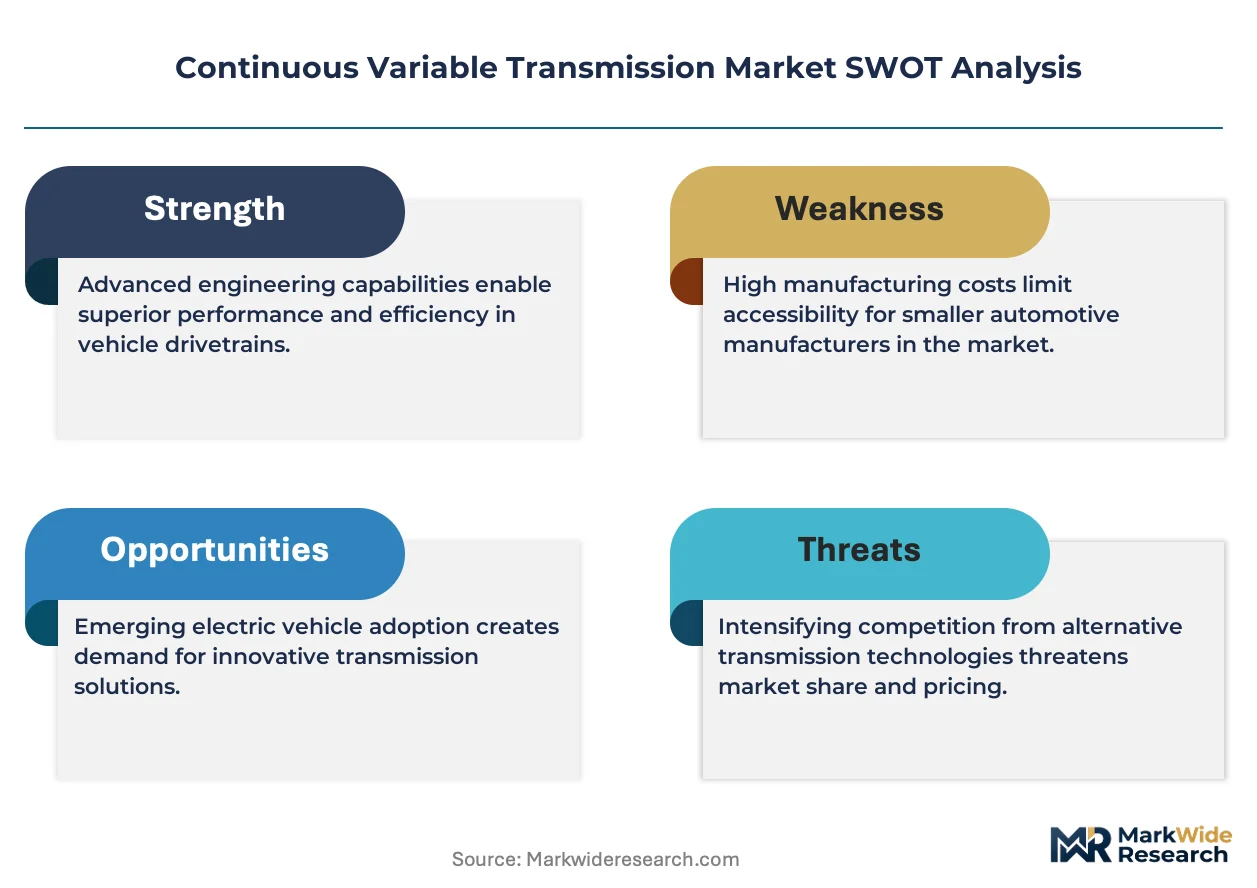
Hybrid CVT architectures are compressing the boundary between conventional automatic transmissions and electrified powertrains, forcing suppliers to engineer dual-capability platforms that satisfy both efficiency mandates and consumer familiarity preferences.
Growth Catalysts
- EPA and NHTSA fuel economy mandates:United States corporate average fuel economy standards tighten annually, compelling passenger vehicle manufacturers to specify CVT systems that maintain engine operation at optimal efficiency points across variable load cycles.
- Steel push-belt metallurgy advances:Improved fatigue resistance and reduced friction coefficients in belt materials extend service intervals and expand torque capacity ratings for compact car platforms.
- East Asian manufacturing cluster concentration:Dedicated CVT production lines in Japan and China achieve economies of scale that compress unit costs for original equipment manufacturers serving domestic and export markets.
Market Restraints
- Steel and rare earth input cost volatility:Fluctuations in nickel and neodymium prices destabilize belt and electric motor component costing for transmission assemblers.
- Full battery-electric substitution threat:Single-speed reduction gearboxes eliminate ratio variation entirely, rendering CVT mechanical complexity redundant in pure electric vehicle architectures.
- REACH material constraints:European restrictions on friction surface coatings and belt elastomers force reformulation of established CVT component specifications.
Strategic Opportunities
- Agriculture equipment sealed-system durability:Variable load cycles in tractors and harvesters justify premium pricing for CVT units engineered to operate without maintenance intervals in contaminated field environments.
- China MIIT dual carbon alignment:Domestic fuel consumption limits create procurement pull for hybrid CVT integration in vehicles manufactured for the Chinese market.
- Software-defined shift logic convergence:Electronic control module advancement enables torque converter lockup strategies that merge hydraulic reliability with algorithmic precision.
Industry Challenges
- ISO/TS 16949 certification timeline compression:Tier-one supplier qualification requirements exclude smaller vendors from bidding on volume passenger vehicle programs.
- Hybrid powertrain integration complexity:Engineering teams must synchronize CVT ratio management with electric motor torque fill and regenerative braking recuperation algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuous Variable Transmission Market |
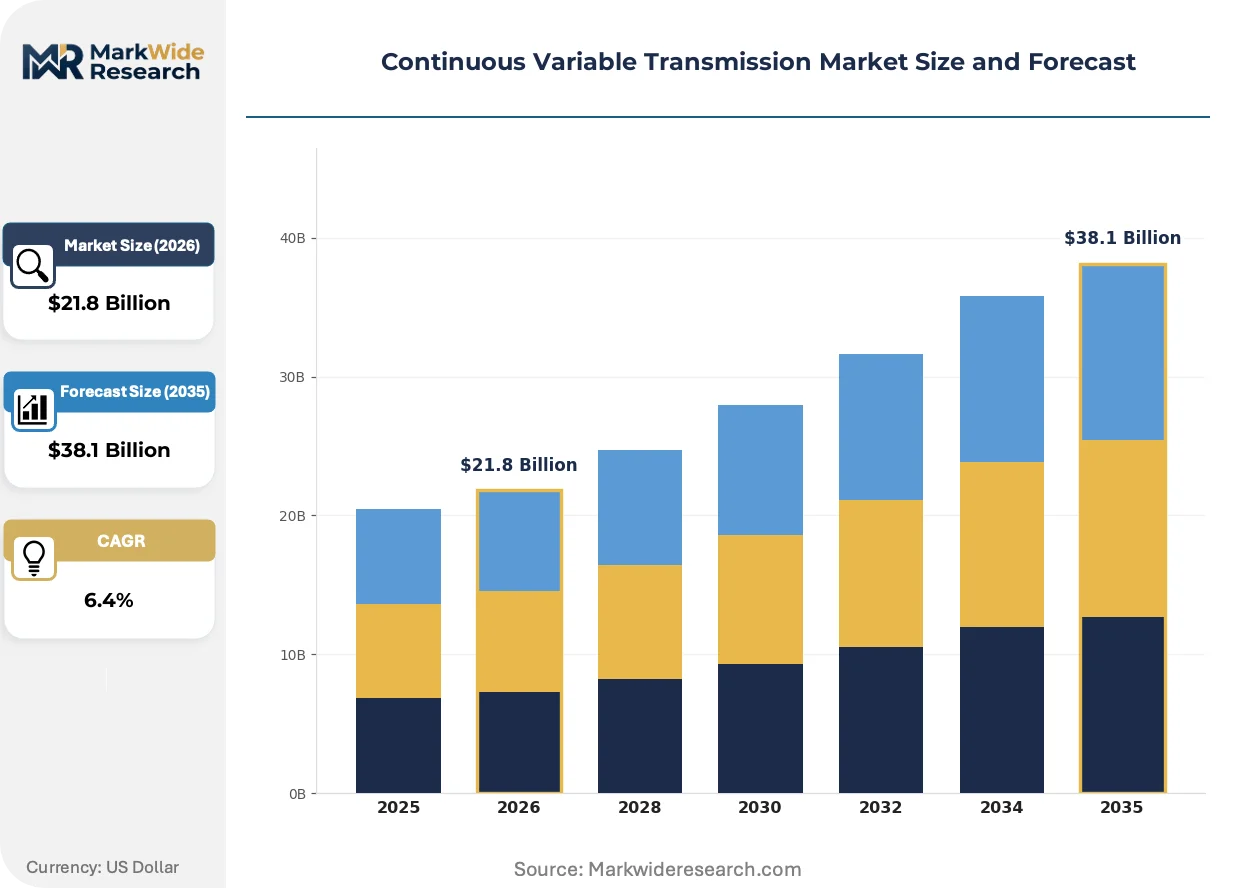
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $38.1 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Hydraulic, Electronic, Mechanical, Hybrid Application: Passenger Vehicles, Commercial Vehicles, Agriculture Equipment, Two-Wheelers Component: Drive Belt, Transmission Control Module, Torque Converter, Engine Deployment: On-road, Off-road, Light-duty, Heavy-duty |
| Companies Covered | ZF Friedrichshafen AG, JATCO Ltd, Aisin Corporation, Robert Bosch GmbH, BorgWarner Inc., Schaeffler AG, Magna International Inc., Endurance Technologies Limited, Punch Powertrain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuous Variable Transmission Market Strategic Shifts
Electronic control architectures are displacing purely hydraulic CVT systems across all torque classes, redefining supplier capability requirements and compressing development cycles for new vehicle programs.
Steel push-belt continuous variable transmission technology is fragmenting the supplier landscape between qualified integrators and excluded component vendors. Passenger vehicle manufacturers in China and Japan specify electronic CVT platforms for compact car production. The shift toward algorithmic ratio control is fragmenting legacy hydraulic expertise into software and hardware specialization tracks.
REACH and EU Green Deal automotive standards constrain material selection for CVT belts and friction surfaces in European markets. Manufacturers reformulate coating chemistries and elastomer compounds to maintain performance under tightened environmental thresholds. Hybrid CVT architectures face the most severe compliance burden as they integrate electrified components subject to both mechanical and chemical substance regulations.
Buyer concentration among East Asian original equipment manufacturers rotates procurement gravity toward dedicated CVT platforms engineered for regional fuel efficiency mandates. Japanese and Chinese automakers specify hybrid-compatible transmissions that bridge conventional and electrified powertrain demand. This geographic demand rotation forces European and North American suppliers to establish engineering presence in East Asian technical centers or risk exclusion from platform development cycles.
Continuous Variable Transmission Market Segmentation
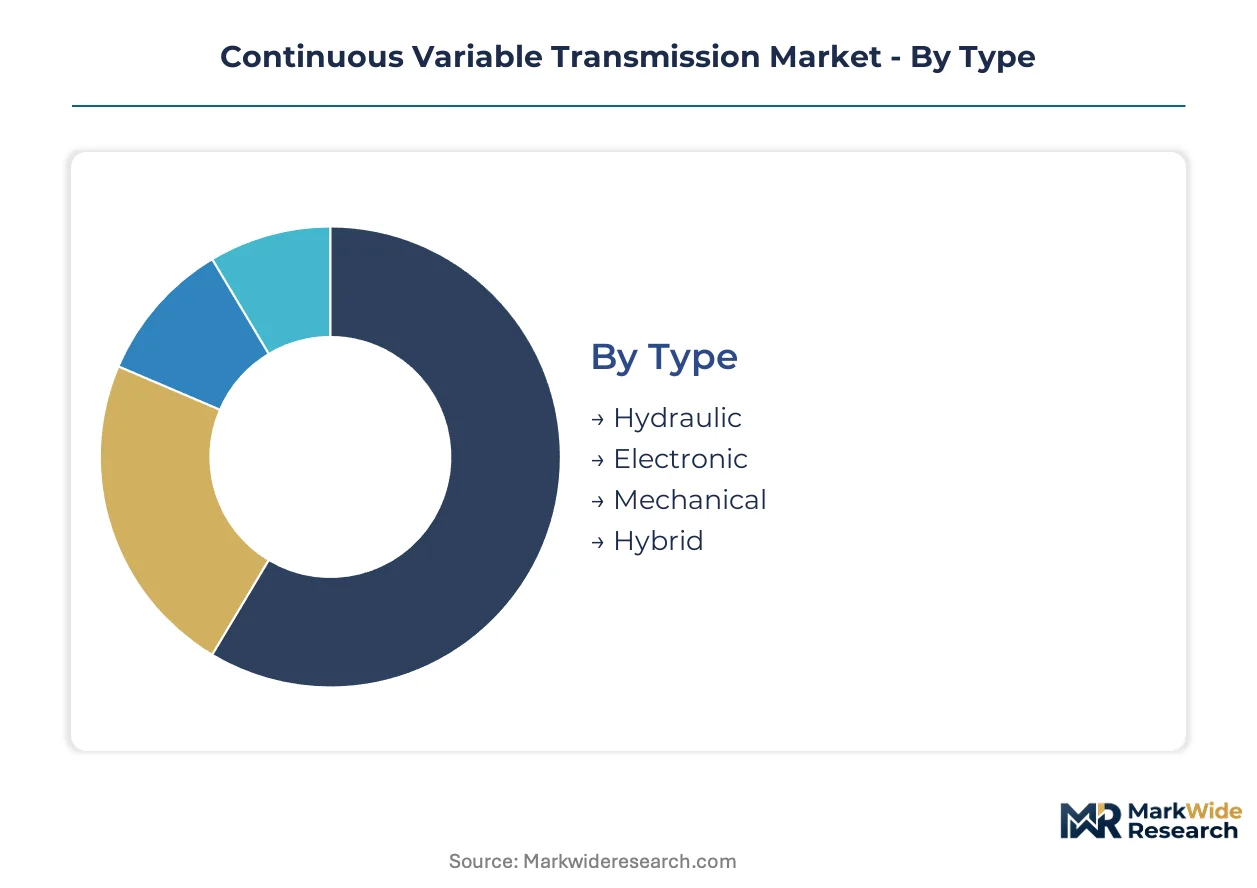
CVT architectures fragment across multiple technical and commercial dimensions, each carrying distinct margin profiles and supplier qualification requirements. Understanding where value concentrates within each segmentation axis enables procurement strategy and competitive positioning decisions.
Type:
Margin pools concentrate in electronic and hybrid architectures where software-defined control commands premium pricing over commodity hydraulic units.
- Electronic:Torque converter lockup strategies and algorithmic ratio management displace hydraulic architectures across compact car platforms. Demand concentrates in East Asian manufacturing clusters where Japanese and Chinese OEMs specify electronic CVT for fuel efficiency compliance under MIIT and EPA mandates.
- Hybrid:Dual-capability platforms bridge conventional automatic transmissions and electrified powertrains, commanding structural importance as automakers seek mild-hybrid and full-hybrid compatibility. Chinese and Japanese manufacturers specify hybrid CVT integration to satisfy dual carbon goals and tightening corporate average fuel economy standards without abandoning familiar mechanical layouts.
- Hydraulic:Purely hydraulic architectures retain volume in cost-sensitive vehicle segments and emerging market applications where electronic control module costs prove prohibitive.
- Mechanical:Basic variable-diameter pulley systems without electronic intervention serve niche applications in light-duty equipment and aftermarket replacement demand.
Electronic holds installed capacity. Hybrid is rotating up the share rankings.
Application:
Volume gravity centers on passenger vehicles, though agriculture equipment delivers concentrated margins through sealed-system durability requirements.
- Passenger Vehicles:Compact car platforms in China and Japan specify CVT systems to maintain engine operation at optimal efficiency points. EPA and NHTSA fuel economy mandates in the United States compel OEMs to adopt electronic CVT architectures that reduce mechanical losses versus conventional automatic transmissions.
- Agriculture Equipment:Tractors and harvesters operate under variable load cycles in contaminated field environments, justifying premium pricing for sealed CVT units engineered to eliminate maintenance intervals. REACH material constraints in Europe force reformulation of friction surfaces and belt elastomers for agricultural deployment.
- Commercial Vehicles:Light and medium-duty trucks adopt CVT for urban delivery cycles where stop-start efficiency gains offset higher transmission costs.
- Two-Wheelers:Scooter and motorcycle applications in Southeast Asian markets drive demand for compact, low-cost CVT architectures with simplified maintenance profiles.
Passenger vehicles anchor production scale. Agriculture equipment is expanding most quickly in margin contribution.
Component:
Supply-side capability scarcity sits with transmission control modules and advanced drive belt metallurgy, separating qualified tier-one integrators from excluded component vendors.
- Transmission Control Module:Electronic control architectures compress development cycles and redefine supplier capability requirements. Software-defined shift logic enables torque converter lockup strategies that merge hydraulic reliability with algorithmic precision.
- Drive Belt:Steel push-belt metallurgy advances improve fatigue resistance and reduce friction coefficients, extending service intervals and expanding torque capacity ratings for compact car platforms. Nickel price volatility destabilizes belt costing for transmission assemblers.
- Torque Converter:Captive supply of torque converters and control modules enables dominant European suppliers to lock in passenger vehicle program wins.
- Engine:CVT-engine integration complexity demands synchronized calibration between ratio management and powertrain control units.
Drive belt commands material cost exposure. Transmission control module is climbing the fastest in value-added share.
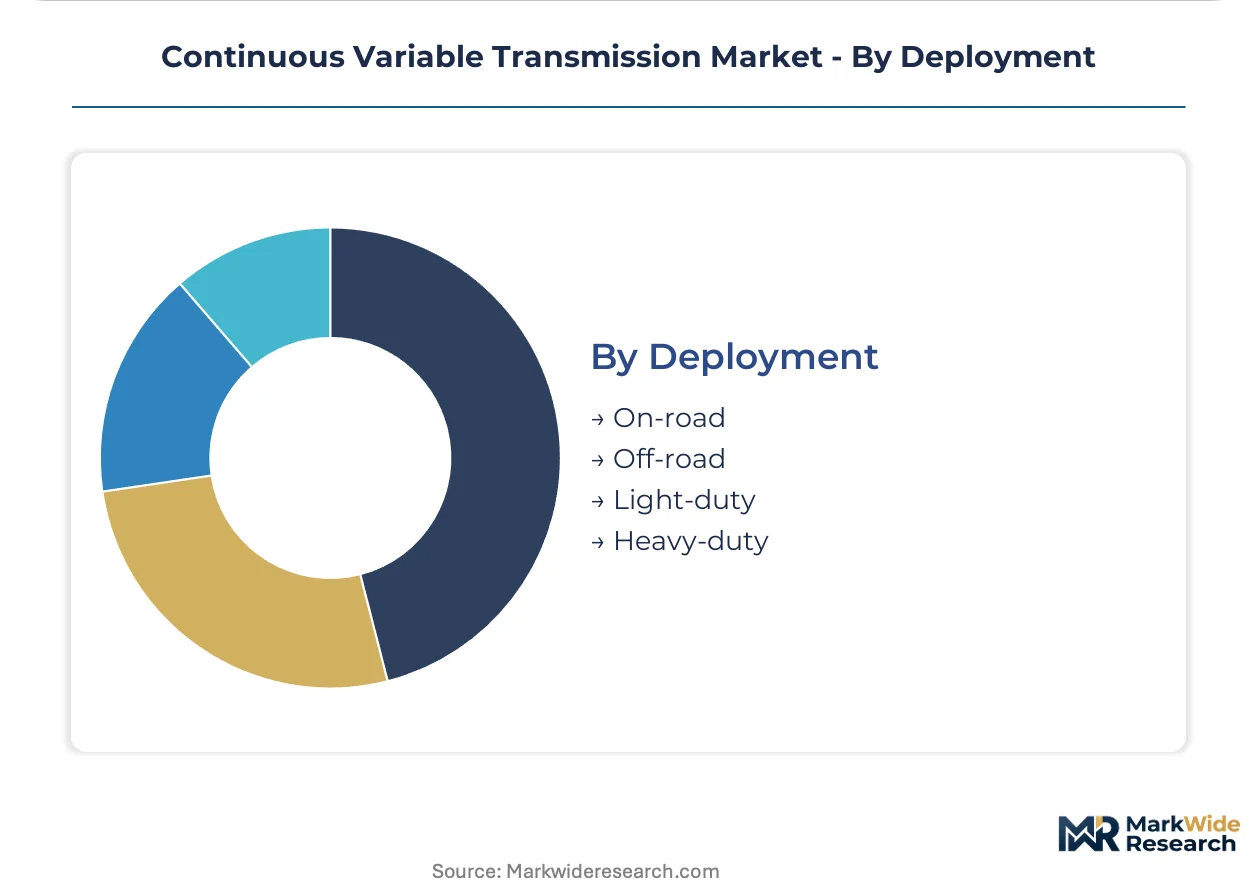
Deployment:
On-road applications concentrate procurement volume, while off-road durability specifications create pricing power for sealed-system engineering.
- On-road:Passenger and commercial vehicle deployment dominates unit demand, with electronic CVT architectures displacing hydraulic systems across EPA and MIIT regulated markets.
- Off-road:Construction and agricultural machinery require sealed-system CVT units capable of operating without maintenance intervals in contaminated environments.
- Light-duty:Compact car and light commercial vehicle segments drive economies of scale in East Asian manufacturing clusters.
- Heavy-duty:Torque capacity requirements and durability specifications limit CVT penetration in long-haul trucking and heavy construction applications.
On-road retains volume concentration. Off-road is gaining share fastest in margin-adjusted revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA and NHTSA fuel economy mandates in the United States, MIIT dual carbon goals in China, and REACH material constraints in Europe are recalibrating procurement gravity toward East Asian manufacturing clusters and selective Western regulatory compliance zones.
United States
Passenger vehicle manufacturers specify electronic CVT architectures to satisfy tightening corporate average fuel economy standards. NHTSA safety compliance requirements shape product development priorities for torque converter lockup strategies. Detroit and Southeast automotive corridors concentrate engineering resources for hybrid CVT integration with electrified powertrains.
China
Domestic fuel consumption limits enforced by MIIT directly incentivize CVT adoption in compact car platforms. Dual carbon goals in Beijing accelerate procurement of hybrid CVT systems for mild-hybrid and full-hybrid vehicles. Yangtze River Delta manufacturing clusters achieve economies of scale that compress unit costs for original equipment manufacturers.
Japan
Japanese automakers anchor volume production through dedicated CVT platforms engineered for regional and export markets. METI industrial policy supports transmission efficiency improvements through standardized JIS certification frameworks. Nagoya and Tokyo technical centers concentrate hybrid CVT development for bridge powertrain solutions.
Germany
European suppliers leverage captive supply of torque converters and control modules to dominate passenger vehicle programs. REACH restrictions on friction surface coatings force reformulation of belt elastomers and coating chemistries. Baden-Württemberg engineering clusters specialize in software-defined shift logic for algorithmic ratio management.
India
Two-wheeler and compact car segments drive demand for low-cost CVT architectures with simplified maintenance profiles. BIS automotive quality standards create qualification barriers for tier-one supplier status. Maharashtra and Tamil Nadu manufacturing hubs concentrate assembly capacity for domestic and export market supply.
Continuous Variable Transmission Market Competitive Environment
Player mix skews toward integrated tier-one suppliers with captive component supply and software-defined control expertise. The supplier landscape bifurcates sharply between ISO/TS 16949-qualified integrators and excluded smaller vendors. Dominant strategic archetypes include European torque converter specialists, Japanese volume platform engineers, and hybrid-architecture bridge developers. Competitive moves center on backward integration into control module production and geographic expansion into East Asian technical centers.
Among European integrated suppliers, ZF Friedrichshafen AG and Schaeffler AG occupy positions anchored by captive supply chains and regional passenger vehicle program dominance. JATCO Ltd exemplifies the Japanese volume-platform archetype, representing dedicated CVT engineering for East Asian original equipment manufacturers. Aisin Corporation sits within the hybrid-architecture specialist tier, bridging conventional and electrified powertrain demand through dual-capability transmission platforms.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| JATCO Ltd |
| Aisin Corporation |
| Robert Bosch GmbH |
| BorgWarner Inc. |
| Schaeffler AG |
| Magna International Inc. |
| Endurance Technologies Limited |
| Punch Powertrain |
| Others |
Value Chain & Pricing Dynamics
East Asian manufacturing cluster density at dedicated CVT production lines in Japan and China compresses unit costs while simultaneously elevating price floors for qualified tier-one integrators holding ISO/TS 16949 certification. Scale economies in Yangtze River Delta and Nagoya technical centers concentrate procurement gravity toward electronic and hybrid architectures, forcing smaller vendors toward commodity hydraulic segments or exclusion entirely.
Pricing Analysis
Certification level creates the primary spread between ISO/TS 16949-qualified tier-one integrators and excluded component vendors. Three-tier pricing structure separates electronic CVT platforms with software-defined shift logic from standard hydraulic units and economy mechanical systems. Cost compression in hydraulic tiers is intensifying because nickel price volatility destabilizes steel push-belt metallurgy inputs. Compact car manufacturers in China exhibit highest price sensitivity, while agriculture equipment buyers accept premium positioning for sealed-system durability specifications.
Supply Chain Analysis
Japan and China anchor CVT platform engineering and volume production for regional OEMs and export markets. Steel push-belt metallurgy draws from nickel and rare earth supply chains subject to commodity price volatility. Single-source vulnerability concentrates in torque converter and transmission control module captive supply held by dominant European and Japanese integrators. Distribution runs through tier-one supplier direct-to-OEM contracts with limited aftermarket channel penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO/TS 16949 certification barriers and electronic control module expertise gaps bifurcate competitive access, concentrating margin capture among integrators with backward integration into torque converters and software-defined shift logic. The capability-scarcity dynamic favors incumbents with established East Asian engineering presence while constraining new entrant pathways to niche or aftermarket segments.
For Market Incumbents: Consolidate control module production and torque converter captive supply to defend against full battery-electric substitution threat eliminating ratio variation entirely. Deepen engineering presence in Yangtze River Delta technical centers to maintain platform development cycle access. Prioritize hybrid CVT architecture R&D to bridge conventional and electrified powertrain demand without abandoning familiar mechanical layouts.
For New Entrants and Emerging Players: Differentiate on agriculture equipment sealed-system durability where variable load cycles justify premium pricing outside passenger vehicle procurement concentration. Target two-wheeler CVT architectures in Southeast Asian markets with simplified maintenance profiles and lower certification barriers. Pursue aftermarket replacement demand for mechanical pulley systems in light-duty equipment segments underserved by tier-one integrators.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid-architecture bridge developers with dual-capability platforms compatible with mild-hybrid and full-hybrid electrification. Long-term viability hinges on software-defined control expertise rather than legacy hydraulic engineering. Acquisition target archetype: tier-one suppliers with captive transmission control module production and established MIIT compliance pathways. Signal to watch: EPA and NHTSA fuel economy mandate acceleration compressing development cycles for electronic CVT platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Control Modules | Software-defined shift logic expertise separates qualified integrators from excluded component vendors. |
| Hybrid CVT Platform Standardization | Dual-capability architectures bridge conventional automatic and electrified powertrain demand under MIIT dual carbon goals. |
| East Asian Technical Center Expansion | Engineering presence in Yangtze River Delta clusters secures platform development cycle access for Chinese OEM programs. |
| Agriculture Equipment Sealed-System Development | Premium pricing power in tractors and harvesters offsets passenger vehicle margin compression from steel input volatility. |
| REACH-Compliant Material Reformulation | Reformulated belt elastomers and friction coatings maintain European market access under tightened environmental thresholds. |
Study Parameters
Operator-level perspectives from OEM platform engineers, tier-one supplier procurement leads, transmission control module developers, and aftermarket distributors anchored the qualitative base for this study. Primary interview findings triangulated against vehicle production databases, IHS Markit registration data, EPA and NHTSA regulatory filings, and MIIT fuel consumption compliance records. Bottom-up unit demand modeling and top-down value chain analysis converged through iterative stakeholder validation.
Sensitivity analysis across steel push-belt metallurgy cost scenarios, battery-electric substitution penetration rates, and REACH material constraint timelines shaped the analytical framework. Segmentation dimensions modeled include transmission architecture type, vehicle propulsion system, torque capacity class, regional production cluster, and OEM tier positioning. CAGRs derived from regression analysis of historical adoption curves against regulatory mandate acceleration patterns, with hybrid CVT integration rates and electronic control displacement timelines as primary forecast inputs.
Material uncertainties — nickel and neodymium price volatility, full battery-electric substitution acceleration, and EPA/NHTSA mandate tightening schedules — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding MIIT dual carbon goal implementation pacing and REACH reformulation timeline compliance. Recalibration cycles align with material shifts in regulatory mandate schedules and electrification substitution rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
North America Precision Gearbox Market
Powertrain
Modular Belt Drive Market
Powertrain
Crate Engines Market
Powertrain
EV Powertrain Market
Powertrain
Gear Oil Market
Powertrain
Automotive Half Shaft Market
Powertrain
Industrial Diesel Turbocharger Market
Powertrain
Global Automotive Transmission Engineering Services Outsourcing Market
Powertrain
Timing Belt Market
Powertrain
Global Automotive Clutch Pedals Market
Powertrain
Automatic Transmission Torque Converter Market
Powertrain
Fuel Injection Systems Market
Powertrain
Automotive Engine Cylinder Block Market
Powertrain
Automotive Engine Market
Powertrain
Automotive Park Brake Lever (Handbrake) Market
Powertrain
Russia Electro Hydraulic Power Steering Market