
 CNG Powertrain Market | 2026-2036
CNG Powertrain Market Size, Share, and Industry Trends Forecast 2026-2036
CNG Powertrain Market Intelligence
Specialized CNG engine calibration expertise is bifurcating the competitive landscape into tier-1 integrators and component specialists. Cummins Inc. leverages its heavy-duty engine platform to anchor fleet contracts in North American freight corridors. Maruti Suzuki India Limited dominates entry-level passenger CNG configurations through factory-fitted dual-fuel systems. Volkswagen AG sustains European market presence via dedicated CNG variants aligned with EU Green Deal emission benchmarks.
A CNG powertrain comprises a spark-ignition or compression-ignition engine modified to combust compressed natural gas at pressures of 20–25 MPa, incorporating hardened valves, specialized fuel injectors, and high-pressure cylinder assemblies to deliver torque curves comparable to conventional gasoline or diesel equivalents. The technology serves commercial fleets seeking lower particulate emissions and reduced fuel volatility exposure. Heavy-duty trucks represent the most entrenched vehicle type segment due to established depot-fueling economics and predictable route profiles. Bi-fuel configurations are gaining traction among light-duty operators requiring gasoline fallback capability in regions with sparse station coverage. Public transport applications concentrate margin pools through long-term municipal procurement contracts with standardized service intervals.
EPA emission certifications under Tier 3 standards constrain aftermarket conversion eligibility in the United States, while EU F-Gas Regulation and CE marking requirements govern cylinder integrity protocols across European member states. India's BIS and Automotive Research Association of India enforce type-approval testing that limits import of uncertified CNG kits. Stakeholders must monitor pipeline infrastructure buildout schedules and cylinder material transitions from Type I steel to Type IV carbon-fiber composites when allocating R&D budgets across regional portfolios.
Market Dynamics
Pipeline infrastructure density is bifurcating the CNG powertrain landscape into conversion-viable corridors and supply-starved peripheries, forcing fleet operators to cluster procurement around compressor station networks rather than distribute geographically.
Growth Catalysts
- EU Green Deal emission benchmarks:Dedicated CNG variants qualify for preferential fleet procurement scoring in municipal tender processes across German and Italian urban transit authorities.
- Type IV carbon-fiber composite cylinders:Lightweight storage assemblies extend vehicle range without payload penalty, accelerating adoption in long-haul freight configurations where weight sensitivity dominates total cost calculations.
- Municipal bus fleet procurement:Latin American cities including São Paulo and Buenos Aires are mandating CNG transition timelines in public transport concession renewals.
Market Restraints
- Steel input cost volatility:Type I cylinder production remains exposed to global scrap metal and alloying element price swings that compress margin predictability for budget fleet conversions.
- EPA Tier 3 certification friction:Aftermarket conversion eligibility constraints in the United States limit kit import pathways and extend type-approval timelines for non-OEM suppliers.
- Battery-electric substitution threat:Depot-charged electric buses and trucks are capturing overlapping fleet procurement budgets in European and Chinese urban logistics corridors with established grid infrastructure.
Strategic Opportunities
- India's western and northern states:Pipeline density in Gujarat, Maharashtra, Punjab and Delhi-NCR creates contiguous conversion zones where bi-fuel light commercial vehicles can operate with minimal range anxiety.
- Biogas-CNG convergence:Upgraded anaerobic digester output injected into transport fuel grids enables carbon-negative fleet positioning for sustainability-mandated logistics contracts.
- Direct OEM factory-fit channels:Passenger vehicle manufacturers are embedding CNG variants into standard production lines, bypassing aftermarket installation bottlenecks and capturing warranty-integrated service revenue.
Industry Challenges
- High-pressure fuel system calibration expertise:The specialized skill set for spark-timing optimization and injector mapping remains concentrated among a limited supplier base, constraining conversion throughput capacity.
- BIS type-approval timeline compression:India's tightening cylinder safety certification protocols require extended testing cycles that delay product launch schedules for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CNG Powertrain Market |
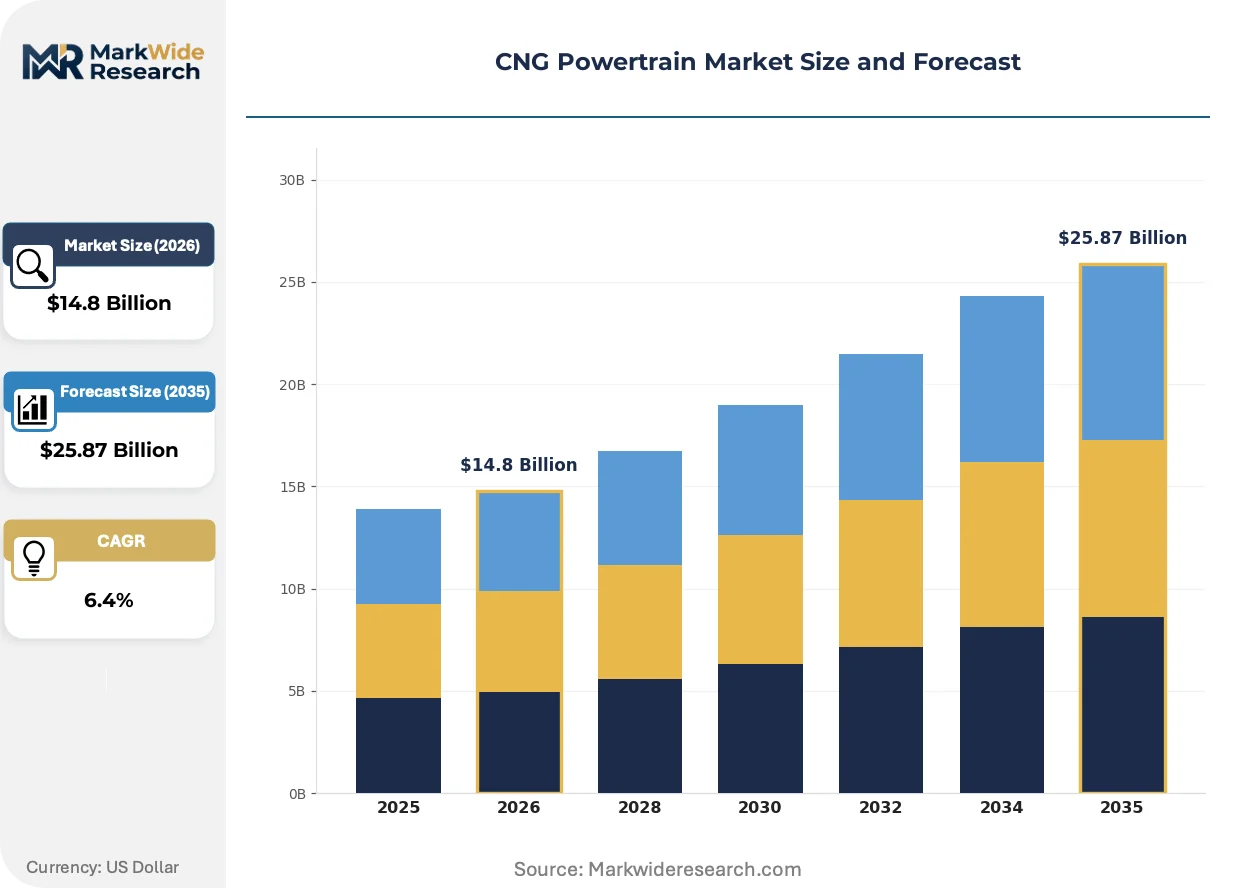
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Compressed Natural Gas, Bi-Fuel, Dedicated, Dual-Fuel Vehicle Type: Light-Duty Vehicles, Heavy-Duty Trucks, Buses, Vans Application: Public Transport, Freight Transportation, City Logistics, Waste Management Fuel Supply: Pipeline Supply, Cylinder Tanks, Gas Stations, Mobile Filling Units |
| Companies Covered | Hyundai Motor Company, Cummins Inc., Volkswagen AG, Maruti Suzuki India Limited, Tata Motors Limited, Ford Motor Company, Robert Bosch GmbH, The Volvo Group, Honda Motor Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CNG Powertrain Market Strategic Shifts & Innovations
Material science advances in pressure vessel construction are compressing the cost-performance gap between steel and composite storage, while regulatory emission ceilings are hardening the business case for gaseous fuel alternatives in heavy-duty applications.
Type IV carbon-fiber composite cylinder assemblies are displacing conventional Type I steel tanks in medium and heavy-duty fleet specifications. Freight operators in India's compressed natural gas corridors are specifying these lightweight alternatives to recover payload capacity lost to fuel storage mass. The technology is displacing incumbent steel-cylinder suppliers from premium fleet contracts where total cost of ownership calculations now favor composite lifecycle economics despite higher upfront capital requirements.
India's BIS certification mandates for CNG cylinder safety are tightening product integrity protocols through enhanced burst-testing and fatigue-cycle requirements. Domestic cylinder manufacturers must retool inspection infrastructure to meet revised type-approval standards that now align with UN ECE R110 global harmonization frameworks. The regulatory pressure is compressing import pathways for uncertified kits and consolidating procurement around BIS-approved domestic fabricators with established testing laboratory relationships.
Fleet procurement is consolidating around long-term municipal service contracts with standardized maintenance intervals and depot-fueling exclusivity clauses. Public transport authorities in São Paulo, Buenos Aires and Delhi are displacing spot-market fuel purchasing with integrated concession agreements that bundle vehicle supply, CNG compression infrastructure and scheduled overhaul services. The contract structure is visible most prominently in Latin American and South Asian metropolitan regions where municipal budget cycles favor predictable operational expenditure over volatile fuel price exposure.
CNG Powertrain Market Segmentation
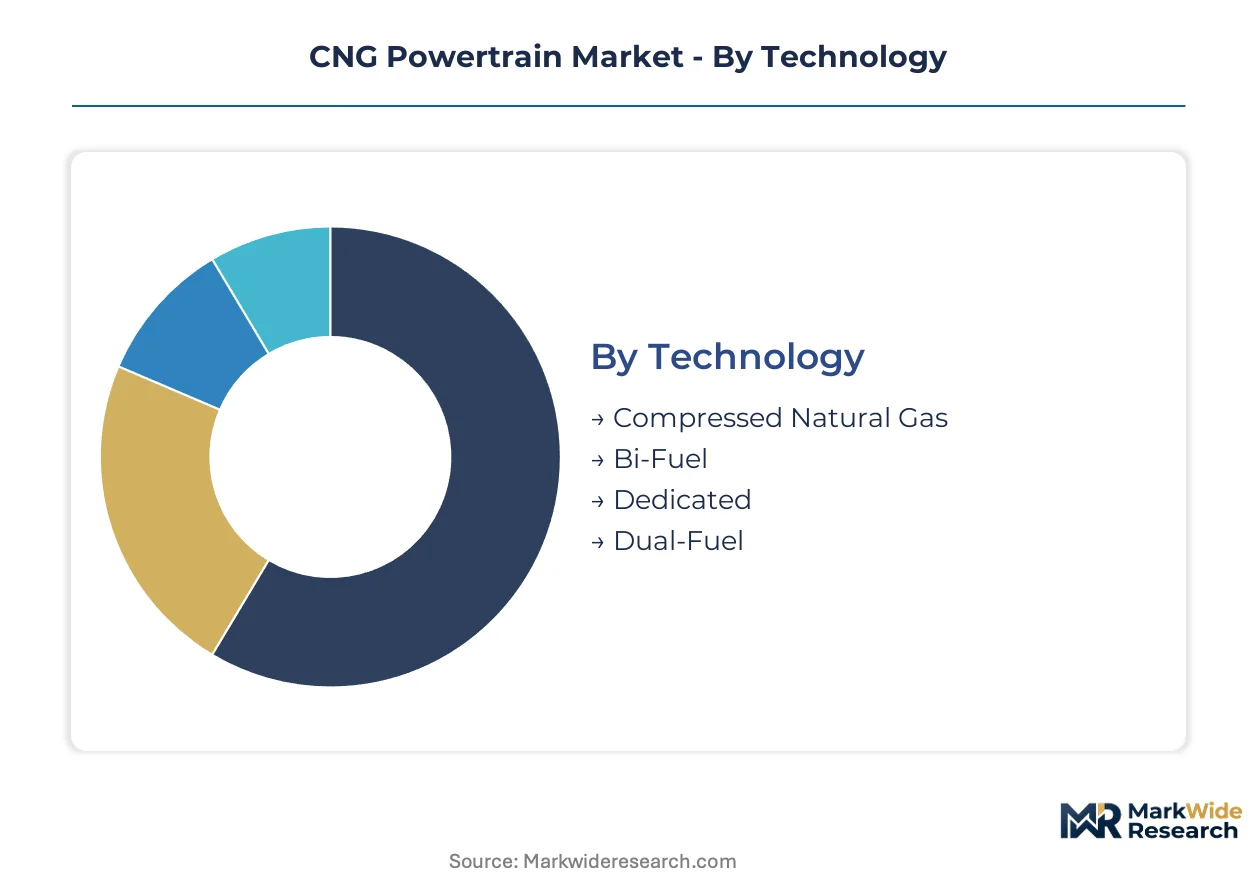
CNG powertrain procurement patterns diverge sharply across technology configurations and fleet operational profiles. Understanding segment-level margin distribution enables suppliers to prioritize R&D allocation and distribution partnerships.
Technology:
Margin pools concentrate in configurations that balance conversion flexibility with regulatory compliance burden.
- Dedicated:Purpose-built CNG engines optimize combustion efficiency through hardened valve seats and specialized piston crowns. Municipal bus operators in São Paulo and Delhi specify these systems for depot-fueled routes where gasoline fallback capability holds zero value, capturing lifecycle cost advantages.
- Bi-Fuel:Parallel fuel systems enable gasoline ignition when CNG pressure drops below operational thresholds. Light-duty fleet operators across India's western corridor deploy these configurations to bridge pipeline coverage gaps between Gujarat and Maharashtra, mitigating range anxiety without dual vehicle investments.
- Dual-Fuel:Simultaneous diesel-CNG combustion reduces particulate emissions in heavy-duty freight corridors.
- Compressed Natural Gas:Baseline mono-fuel systems dominate budget conversion segments.
The dominant share belongs to Dedicated configurations, while Bi-Fuel is closing the gap fastest.
Vehicle Type:
Volume concentration tracks depot-fueling economics and route predictability rather than absolute vehicle population.
- Heavy-Duty Trucks:Long-haul freight operators specify CNG powertrains for fixed corridor operations between compression stations. The segment leverages predictable mileage profiles to amortize cylinder capital costs across high-utilization cycles, with Indian logistics clusters in Punjab and Haryana driving procurement.
- Buses:Urban transit authorities bundle vehicle procurement with exclusive CNG supply concessions. Buenos Aires and São Paulo municipal tender processes mandate factory-fitted systems with standardized 10-year service intervals, locking in aftermarket revenue streams.
- Vans:Last-mile delivery fleets in European city centers adopt bi-fuel variants.
- Light-Duty Vehicles:Passenger car conversions concentrate in price-sensitive segments.
Heavy-Duty Trucks command the largest installed base, though Buses are expanding most quickly through municipal procurement mandates.
Application:
Contract structure durability separates stable revenue pools from spot-market volatility.
- Public Transport:Concession-based procurement with depot-fueling exclusivity clauses generates predictable operational expenditure profiles. Latin American metropolitan authorities favor 15-year service contracts bundling vehicle supply, compression infrastructure, and scheduled overhauls.
- Freight Transportation:Long-haul operators calculate total cost of ownership around fuel price differentials and payload recovery through Type IV composite cylinders.
- City Logistics:Urban delivery constraints are accelerating bi-fuel van specifications.
- Waste Management:Municipal sanitation fleets with fixed depot operations convert to dedicated CNG systems.
Public Transport holds the dominant share, while Freight Transportation is gaining share fastest through corridor-specific fleet renewals.
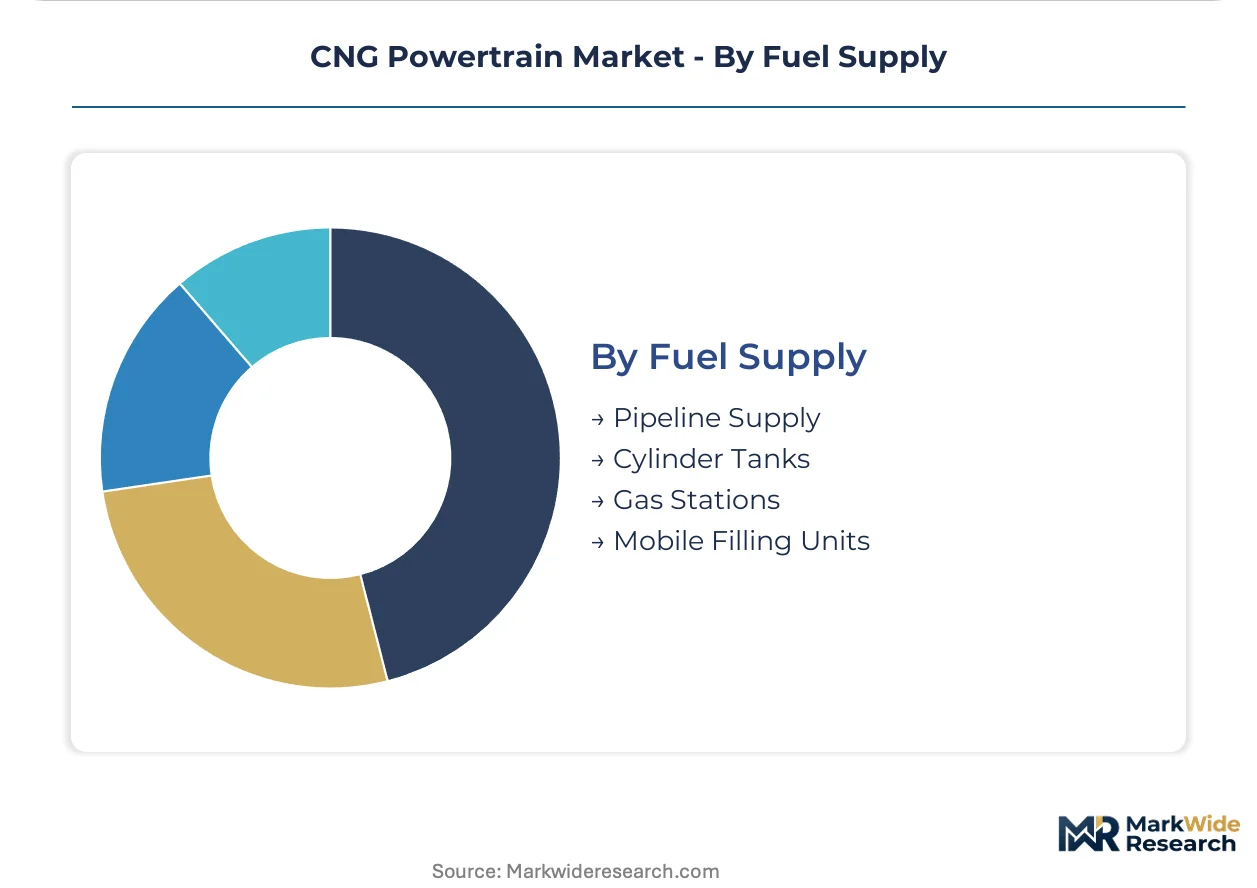
Fuel Supply:
Infrastructure ownership models determine margin capture between energy suppliers and vehicle operators.
- Pipeline Supply:Direct utility connections eliminate cylinder logistics costs for depot-based fleets. Indian state gas distributors in Gujarat and Maharashtra offer preferential commercial rates to high-volume transport consumers with guaranteed offtake commitments.
- Gas Stations:Retail compression infrastructure enables route flexibility for irregular operators. Network density in Delhi-NCR and Buenos Aires supports bi-fuel light commercial vehicle adoption where depot investment is uneconomical.
- Cylinder Tanks:Bulk storage systems serve remote fleet operations beyond pipeline reach.
- Mobile Filling Units:Compressor-mounted trailers extend CNG access to temporary worksites.
Pipeline Supply dominates where infrastructure exists, while Gas Stations are climbing the fastest in emerging conversion corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BIS certification mandates anchor procurement patterns in India, where pipeline density in Gujarat and Maharashtra compresses conversion economics for commercial fleets. Regulatory frameworks across multiple geographies are hardening cylinder integrity protocols while municipal tender processes in Latin America and Europe embed emission benchmarks into long-term service contracts.
India
Western and northern states concentrate CNG fleet conversions around pipeline corridors linking Gujarat, Maharashtra, Punjab and Delhi-NCR. BIS type-approval testing limits import pathways for uncertified conversion kits while compressing launch schedules for new market entrants. The Automotive Research Association of India enforces cylinder safety protocols that align with UN ECE R110 harmonization frameworks.
Brazil
São Paulo municipal authorities mandate CNG transition timelines in public transport concession renewals spanning 15-year service contracts. ANVISA-equivalent transport regulators enforce cylinder integrity standards through periodic recertification requirements. The São Paulo metropolitan region anchors Latin American bus fleet procurement with bundled vehicle supply and compression infrastructure agreements.
Germany
EU Green Deal emission benchmarks qualify dedicated CNG variants for preferential scoring in urban transit tender processes. The KBA enforces CE marking and F-Gas Regulation compliance for cylinder integrity protocols across member state borders. Industrial clusters in Bavaria and Baden-Württemberg host OEM engineering centers developing factory-fitted CNG configurations for European freight corridors.
United States
EPA Tier 3 certification constraints limit aftermarket conversion eligibility and extend type-approval timelines for non-OEM suppliers. Heavy-duty freight operators cluster procurement around compressor station networks in Texas and California corridor economics. NHTSA safety protocols govern high-pressure fuel system installations across interstate fleet operations.
Argentina
Buenos Aires metropolitan authorities displace spot-market fuel purchasing with integrated concession agreements bundling vehicle supply and depot-fueling exclusivity. The national transport secretariat enforces cylinder recertification cycles that compress import pathways for uncertified assemblies. The Buenos Aires-Rosario-Córdoba triangle concentrates bi-fuel light commercial vehicle adoption where pipeline coverage gaps persist.
CNG Powertrain Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with factory-fit OEM channels capturing warranty-integrated service revenue while aftermarket conversion specialists concentrate around regional certification expertise. The structure bifurcates between heavy-duty engine platform anchors and entry-level passenger configurations. Three archetypes dominate: integrated automotive OEMs with dual-fuel production lines, heavy-duty engine specialists with depot-fueling fleet contracts, and component fabricators with cylinder manufacturing relationships. Competitive moves concentrate on direct OEM factory-fit channel expansion and backward integration into composite cylinder production.
Within the integrated OEM tier, Maruti Suzuki India Limited and Volkswagen AG occupy positions anchoring divergent regional strategies. Cummins Inc. exemplifies the heavy-duty engine specialist archetype with freight corridor concentration. Hyundai Motor Company sits within the factory-fit channel expansion vector alongside Tata Motors Limited, which represents Indian commercial vehicle integration. These five entities span the geographic and segment coverage defining competitive positioning.
| Leading Market Players |
|---|
| Hyundai Motor Company |
| Cummins Inc. |
| Volkswagen AG |
| Maruti Suzuki India Limited |
| Tata Motors Limited |
| Ford Motor Company |
| Robert Bosch GmbH |
| The Volvo Group |
| Honda Motor Company |
| Others |
Cost & Logistics Intelligence
Type IV carbon-fiber composite cylinder assemblies displacing Type I steel tanks simultaneously redraws procurement geography toward India and China while compressing margin structures for incumbent metal fabricators unable to retool. The material transition rewards suppliers with backward integration into carbon-fiber weaving and resin systems, while steel-dependent converters face pricing power erosion in municipal fleet tenders where lifecycle cost calculations now favor lightweight alternatives despite higher upfront capital requirements.
Pricing Analysis
Long-term offtake agreements with depot-fueled municipal bus operators anchor pricing stability, while spot-market conversions for light-duty bi-fuel configurations exhibit greater volatility. Three-tier pricing structure across premium composite-cylinder systems, standard steel-tank configurations, and economy retrofit kits differentiates procurement tiers. Pricing pressure stems from battery-electric substitution in European and Chinese urban logistics corridors where overlapping fleet budgets compress CNG conversion premiums. Municipal transit authorities demonstrate lowest price sensitivity due to emission-mandated procurement timelines, whereas independent owner-operators in India's fragmented light-commercial segment negotiate aggressively on kit costs.
Supply Chain Analysis
Inbound logistics costs for carbon-fiber precursor materials from Japan and South Korea concentrate supply risk on Asia-Pacific trade lanes subject to container availability fluctuations. Cylinder manufacturing draws from specialized resin systems, high-tensile carbon fiber, and precision valve assemblies sourced predominantly from China, India, and Germany. Single-source vulnerability persists in Type IV composite pressure vessel certification testing where UN ECE R110-aligned laboratories concentrate in Europe and India. Distribution runs through OEM factory-fit channels capturing warranty-integrated service revenue, alongside aftermarket conversion specialists dependent on regional BIS and EPA certification expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CNG powertrain penetration sits at early-cycle expansion with municipal emission mandates in São Paulo, Delhi, and Buenos Aires accelerating fleet procurement timelines ahead of battery-electric infrastructure maturity. Factory-fit OEM channels are capturing warranty-integrated service revenue streams that aftermarket converters cannot replicate.
For Market Incumbents: Fortify backward integration into carbon-fiber composite cylinder production to defend margin position against steel-tank commoditization. Lock in exclusive depot-fueling concession agreements with Latin American and South Asian municipal authorities before battery-electric alternatives achieve charging infrastructure parity. Prioritize BIS and UN ECE R110 certification investment to compress launch timelines for new product variants. For New Entrants and Emerging Players: Lead with biogas-CNG convergence positioning to capture sustainability-mandated logistics contracts in European and North American corridors where carbon-negative fleet branding commands procurement preference. Target India's western state pipeline corridors for light-commercial bi-fuel configurations bridging coverage gaps between Gujarat and Maharashtra. Pursue direct OEM supply partnerships rather than aftermarket kit distribution to bypass certification timeline bottlenecks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cylinder fabricators in India and China possessing established BIS and UN ECE R110 testing laboratory relationships. Five-to-ten year viability hinges on composite material cost curves achieving parity with steel alternatives at scale. Monitor biogas injection capacity buildout into transport fuel grids as the signal indicating sustained CNG demand against battery-electric substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Composite Cylinder Production | In-house carbon-fiber weaving capacity insulates margin structures from precursor material cost volatility. |
| Exclusive Depot-Fueling Concession Agreements | Buenos Aires and São Paulo municipal tenders bundle vehicle supply with compression infrastructure exclusivity. |
| Biogas-CNG Convergence Certification | Anaerobic digester output injection enables carbon-negative positioning for sustainability-mandated logistics contracts. |
| Direct OEM Factory-Fit Channel Expansion | Maruti Suzuki and Volkswagen warranty-integrated configurations bypass aftermarket installation bottlenecks. |
| BIS Type-Approval Testing Infrastructure Investment | Domestic Indian laboratories with UN ECE R110 alignment compress launch schedules for new market entrants. |
Research Approach
Operator-level perspectives from fleet procurement managers at municipal transit authorities, cylinder manufacturing plant engineers, OEM platform integration specialists, and aftermarket conversion kit distributors anchored the qualitative base. Secondary validation drew from EPA Tier 3 certification filings, BIS type-approval registries, EU F-Gas Regulation compliance databases, and Automotive Research Association of India test reports. Bottom-up fleet procurement volume estimates triangulated against top-down pipeline infrastructure buildout schedules across India, Brazil, and Argentina.
Sensitivity analysis around carbon-fiber composite cost curves, steel input price volatility, and battery-electric substitution rates informed projection boundaries across the analysis window. Segmentation dimensions modeled included technology configuration, vehicle type, application contract structure, and fuel supply infrastructure ownership. CAGRs derived from correlated regression against historical fleet conversion velocities, municipal tender award patterns, and cylinder material transition adoption curves. Industry-specific inputs incorporated compressor station network density metrics and biogas injection capacity expansion timelines.
Forecasts assume regulatory continuity in EPA Tier 3, EU F-Gas Regulation, and India's BIS certification regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Power Assisted Steering Market
Powertrain
Electric Vehicle Powertrain Market
Powertrain
Automotive Park Brake Lever (Handbrake) Market
Powertrain
Automotive Engine Cylinder Block Market
Powertrain
Axle Shaft Market
Powertrain
Italy Electro Hydraulic Power Steering Market
Powertrain
Fuel Cell Powertrain Market
Powertrain
Canada Automotive Engine Oils Market
Powertrain
Clutch Friction Plate Market
Powertrain
Automotive Performance Tuning Market
Powertrain
Brazil Automotive Engine Oils Market
Powertrain
Global Automotive GD Injector Market
Powertrain
Asia Pacific Electrically Powered Hydraulic Steering Market
Powertrain
Automotive Crankshaft Market
Powertrain
Middle East and Africa Internal Combustion Engines Market
Powertrain
Drive Mode-Linked Powertrain Actuator Systems Market