
 Singapore Electric Vehicle Market | 2026-2036
Singapore Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Electric Vehicle Market Analytics
Powertrain electrification is fragmenting traditional automotive value chains as battery-electric architectures displace internal combustion engineering. Tesla Inc. dominates direct-to-consumer distribution with integrated software-hardware stacks that sustain recurring revenue from over-the-air updates. BYD Co. Ltd anchors fleet procurement through blade battery safety credentials and aggressive leasing structures. Hyundai Motor Company competes via dedicated EV platforms that reduce component count and assembly complexity.
Singapore electric vehicles are road-registered automobiles propelled by electric motors drawing energy from rechargeable battery packs, typically lithium-ion cells with energy densities exceeding 250 Wh/kg, designed for zero-tailpipe-emission urban mobility. Passenger cars occupy the dominant volume position, though commercial vehicles and buses represent accelerating replacement cycles as logistics operators face tightening diesel restrictions. Lithium-ion battery technology leads installed capacity while solid-state chemistries attract R&D investment for their potential to eliminate thermal runaway risks in tropical climates. Public charging stations command strategic priority given Singapore's high-rise residential density and limited private parking availability.
Singapore's Land Transport Authority enforces vehicle emission schemes that impose escalating surcharges on carbon-intensive models while granting rebates for battery-electric registrations. The Energy Market Authority coordinates grid interconnection standards for high-capacity charging depots, ensuring distribution network stability as commercial fleet electrification scales. Stakeholders must monitor Certificate of Entitlement quota reductions and carbon border adjustment developments to time fleet conversion investments and infrastructure commitments.
Market Dynamics
Certificate of Entitlement quota compression and carbon-based vehicle taxation are forcing commercial fleet operators toward battery-electric platforms faster than consumer adoption curves, restructuring procurement patterns across Singapore's automotive sector.
Growth Catalysts
- Vehicle Emission Schemes:Singapore's Land Transport Authority imposes escalating surcharges on carbon-intensive models while granting substantial rebates for battery-electric registrations, directly altering total cost of ownership calculations for fleet managers.
- Logistics Electrification:Ride-hailing and last-mile delivery operators face tightening diesel restrictions in industrial corridors, redirecting capital expenditure toward centralized fast-charging depot infrastructure.
- Lithium-Ion Energy Density:Cell chemistries exceeding 250 Wh/kg now enable commercial vehicle range adequacy without payload compromise, satisfying tropical climate thermal management requirements.
Market Restraints
- Land Scarcity:Singapore's high-rise residential density limits private parking availability, constraining distributed residential charging deployment and forcing dependence on public infrastructure.
- Grid Capacity Constraints:The Energy Market Authority must coordinate distribution network stability as commercial fleet electrification scales, creating interconnection approval bottlenecks for high-capacity charging depots.
- Certificate of Entitlement Auctions:Quota reductions inflate upfront vehicle acquisition costs across all powertrain types, compressing margin structures for fleet operators managing large vehicle pools.
Strategic Opportunities
- Jurong Innovation District:Industrial zone clustering creates concentrated demand for megawatt-scale charging hubs serving heavy commercial vehicle electrification.
- Solid-State Battery R&D:Tropical climate thermal runaway risks are driving investment in next-generation chemistries that eliminate cooling system complexity and extend operational lifespan.
- Integrated Mobility Platforms:Software-hardware stacks enabling over-the-air updates and recurring revenue streams are attracting technology capital toward vehicle-as-a-service business models.
Industry Challenges
- High-Voltage Technician Shortage:Battery-electric powertrains require specialized safety certification for maintenance personnel that Singapore's vocational training pipeline has not yet scaled to meet.
- Depot Electrification Capex:Fleet operators must fund grid connection upgrades, transformer installations, and charging hardware simultaneously with vehicle procurement, straining capital allocation.
- Interoperability Standards:Multiple connector protocols and payment systems across public charging networks create friction for drivers operating across Singapore's island-wide infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Electric Vehicle Market |
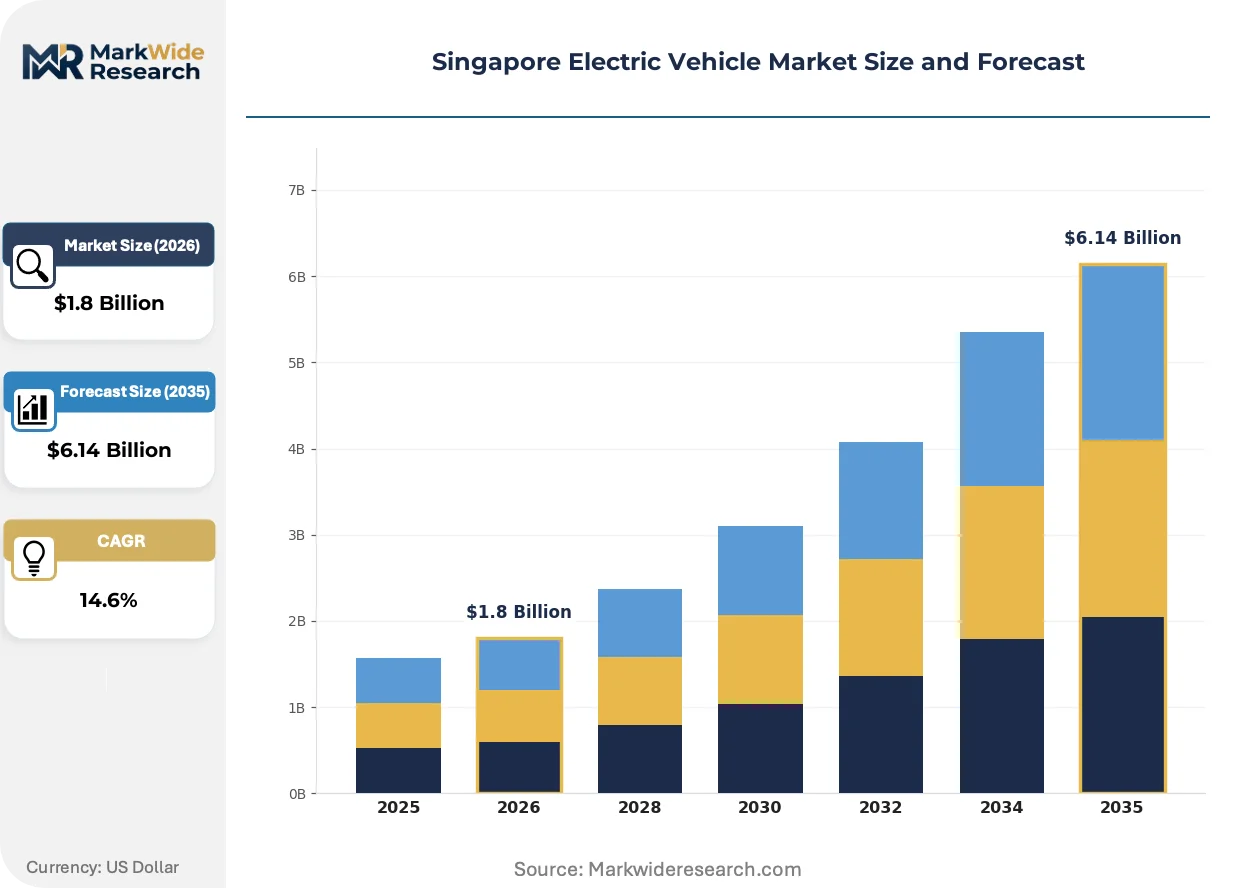
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Cars, Buses, Motorcycles, Commercial Vehicles Battery Technology: Lithium-ion, Solid State, Lead Acid, Nickel Metal Hydride Charging Infrastructure: Home Charging, Public Charging Stations, Fast Chargers, Wireless Charging Ownership Model: Leasing, Direct Purchase, Subscription, Car Sharing |
| Companies Covered | BYD Co. Ltd, Tesla Inc., Hyundai Motor Company, BMW AG, Mercedes-Benz Group AG, Nissan Motor Co., Toyota Motor Corporation, Kia Corporation, SAIC Motor - MG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Electric Vehicle Market Evolving Landscape
Battery chemistry evolution, regulatory incentive restructuring, and fleet procurement centralization are converging to reshape Singapore's electric vehicle competitive landscape and infrastructure investment patterns.
Lithium-iron-phosphate cells are migrating from entry-level passenger applications into commercial vehicle platforms where thermal stability and cycle life outweigh energy density priorities. Logistics operators with fixed depot routes are adopting these chemistries for their reduced fire risk in Singapore's humid tropical climate. This chemistry shift is compressing nickel-cobalt-manganese cell dominance in the heavy-duty segment.
Singapore's Energy Market Authority coordinates grid interconnection standards that mandate smart charging protocols and demand response capability for high-capacity depots. These requirements are accelerating vehicle-to-grid integration investments among fleet operators seeking ancillary revenue streams. Commercial charging infrastructure developers face compliance timelines that favor established energy sector participants over automotive entrants.
Fleet procurement is consolidating through leasing structures that bundle vehicles, charging infrastructure, and energy management into single contracts. Ride-hailing operators and logistics platforms are displacing traditional ownership models, transferring residual value risk to financial institutions and infrastructure providers. This bundling is most advanced among last-mile delivery operators serving Singapore's dense urban core.
Singapore Electric Vehicle Market Segmentation
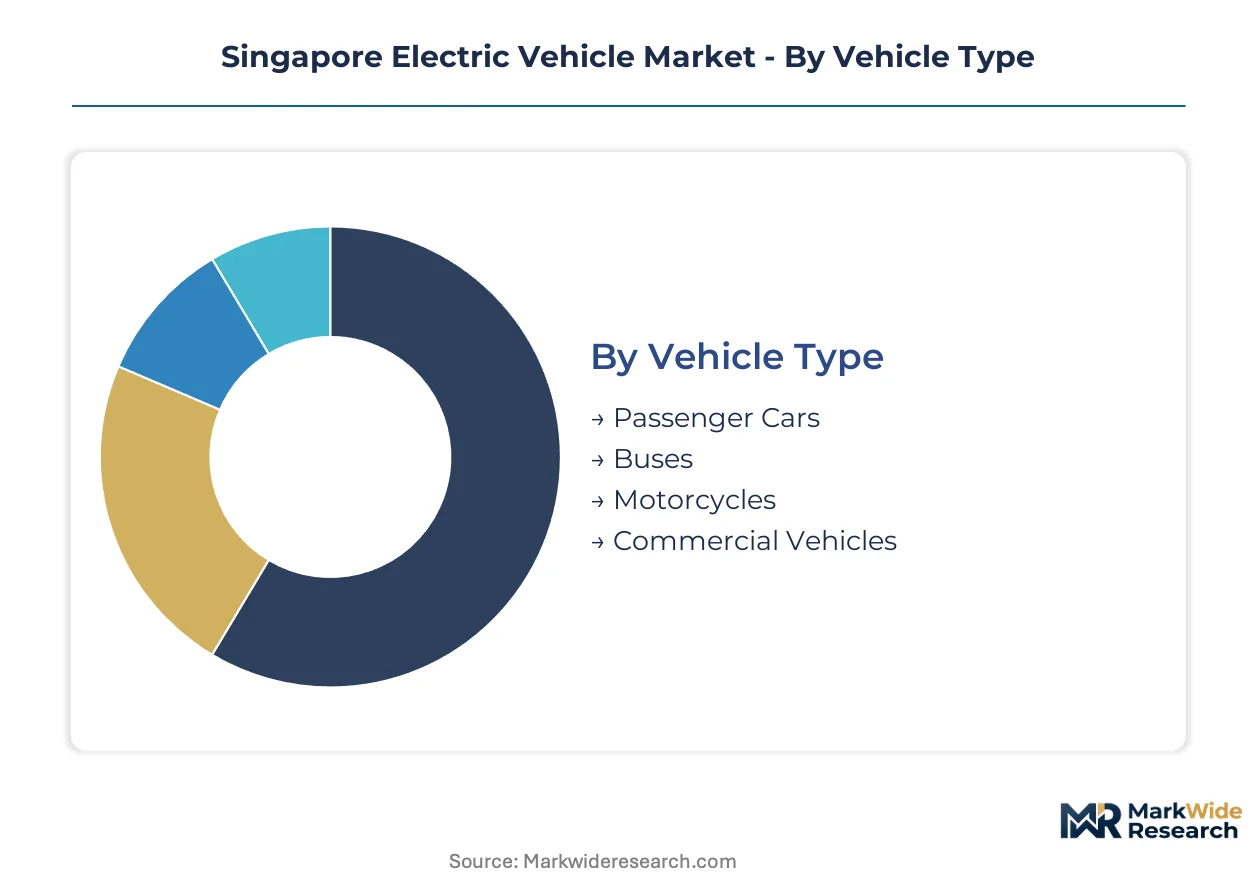
Singapore's electric vehicle segmentation reflects the city-state's unique constraints: land scarcity, high-rise residential density, and aggressive fleet electrification mandates. Each dimension reveals distinct procurement patterns and infrastructure requirements that diverge from conventional automotive markets.
Vehicle Type:
Replacement cycles vary dramatically across vehicle categories, with commercial fleets turning over every 3-5 years while passenger cars average 7-10 years.
- Passenger Cars:Private automobiles with lithium-ion battery packs typically ranging 50-75 kWh, optimized for urban commuting distances under 50 km daily. Demand concentrates in premium segments where Certificate of Entitlement costs are absorbed more easily, driven by Land Transport Authority rebates that alter total cost of ownership calculations.
- Commercial Vehicles:Light and heavy-duty trucks, vans, and delivery vehicles with larger battery capacities enabling 200+ km ranges under tropical thermal loads. Logistics operators in Jurong and Tuas industrial corridors are replacing diesel fleets fastest due to tightening emission zone restrictions and depot-based charging economies.
- Buses:Public transit and private charter vehicles with high-capacity battery systems requiring dedicated depot infrastructure. Land Transport Authority procurement mandates are accelerating replacement timelines for public bus fleets.
- Motorcycles:Two-wheeled electric vehicles with smaller battery footprints suited for last-mile delivery and individual commuting. Food delivery platforms are piloting electric motorcycle fleets in Singapore's dense urban core.
Passenger cars anchor the volume base while commercial vehicles gain share at the steepest rate.
Battery Technology:
Cost tiers separate established chemistries from emerging alternatives, with price premiums of 30-50% separating commercial-grade from entry-level cell technologies.
- Lithium-ion:Dominant cell chemistry using nickel-cobalt-manganese or lithium-iron-phosphate cathodes with energy densities exceeding 250 Wh/kg. Singapore's tropical climate favors lithium-iron-phosphate variants for their thermal stability in commercial vehicle applications.
- Solid State:Next-generation cells replacing liquid electrolytes with ceramic or polymer conductors, eliminating thermal runaway risks. R&D investment is accelerating for tropical climate applications where cooling system simplification offers operational advantages.
- Lead Acid:Mature technology with lower energy density and cycle life, limited to auxiliary power and low-speed vehicle applications. Cost sensitivity drives residual demand in specific industrial vehicle niches.
- Nickel Metal Hydride:Intermediate chemistry with moderate energy density and established recycling infrastructure. Hybrid vehicle applications retain limited demand as full electrification advances.
Lithium-ion configurations dominate current installations while solid-state alternatives attract the most capital deployment for future production.
Charging Infrastructure:
Application context determines infrastructure priority, with fleet depot solutions scaling faster than consumer-facing networks due to concentrated demand and simpler utilization economics.
- Public Charging Stations:Grid-connected points in shopping malls, office complexes, and public carparks serving dispersed vehicle owners. HDB estate carparks represent the critical deployment challenge given Singapore's high-rise residential density and limited parking availability per unit.
- Fast Chargers:High-power DC systems delivering 150-350 kW for rapid turnaround in commercial and highway-adjacent locations. Fleet operators along the Pan Island Expressway corridor are prioritizing these for logistics vehicle mid-route replenishment.
- Home Charging:Residential AC charging points dependent on private parking access. Landed property owners in districts like Bukit Timah and Sentosa represent the addressable market, constraining mass-market penetration.
- Wireless Charging:Inductive pad systems enabling automated charging without physical connector engagement. Bus depot trials are underway for scheduled overnight charging of public transit fleets.
Public charging stations provide the broadest geographic coverage while fast chargers deliver the highest utilization rates per installed point.
Ownership Model:
Customer type bifurcates between capital-rich individual purchasers and operating-expense-focused fleet managers with divergent risk appetites and financing constraints.
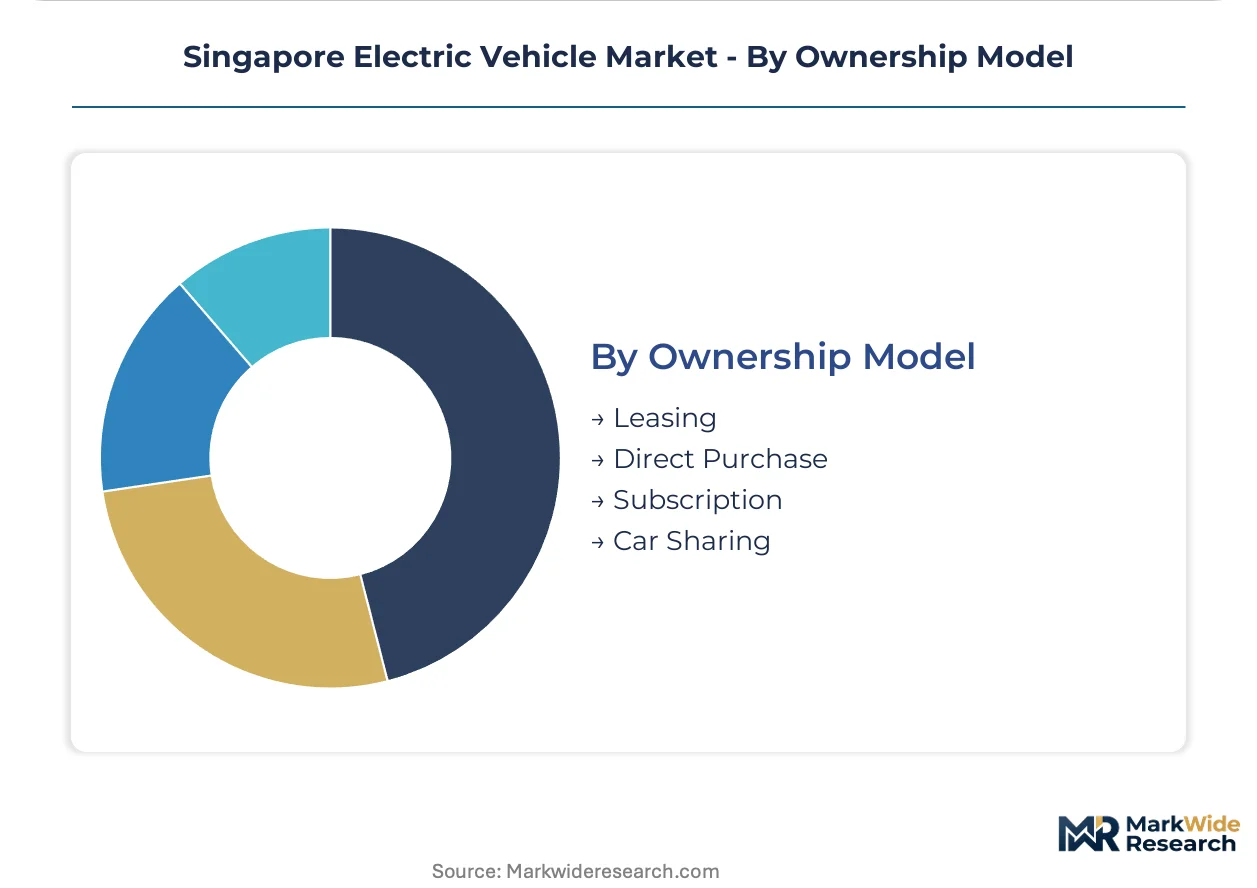
- Leasing:Multi-year contracts bundling vehicles, maintenance, and charging infrastructure access into predictable monthly payments. Ride-hailing operators prefer this structure to preserve capital for platform technology investments.
- Direct Purchase:Outright acquisition with full residual value exposure and depreciation risk. Private buyers with Certificate of Entitlement tenure certainty favor this for long-term cost minimization.
- Subscription:Flexible short-term access with all-inclusive fees covering insurance, maintenance, and energy. Young professionals in Singapore's central business district are adopting this for lifestyle flexibility without parking obligations.
- Car Sharing:Hourly or per-kilometer access to pooled vehicle fleets via mobile applications. Corporate campus deployments in one-north and Changi Business Park are reducing parking demand and fleet redundancy.
Direct purchase retains the largest transaction volume while leasing expands most quickly among commercial fleet operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators in ride-hailing and logistics concentrate procurement decisions across Singapore's sub-regional markets, with Certificate of Entitlement auctions and carbon-based taxation redirecting commercial investment toward battery-electric platforms in distinct geographic corridors.
Central Business District
Corporate fleet managers and ride-hailing operators dominate vehicle procurement in Singapore's dense commercial core, where parking scarcity and congestion pricing amplify total cost of ownership sensitivity. Land Transport Authority vehicle emission schemes impose surcharges on carbon-intensive models entering the CBD while granting substantial rebates for battery-electric registrations. Charging infrastructure developers are deploying fast-charging hubs in Marina Bay and Raffles Place to serve commercial fleet overnight parking and daytime turnaround requirements.
Jurong Innovation District
Heavy commercial vehicle electrification accelerates in Singapore's western industrial corridor as logistics operators face tightening diesel restrictions in freight zones. The Energy Market Authority coordinates grid interconnection standards for megawatt-scale charging depots serving heavy-duty truck and delivery van fleets. Industrial zone clustering creates concentrated demand for centralized fast-charging infrastructure that reduces land-use intensity compared to distributed residential solutions.
Tuas Industrial Estate
Port-connected logistics operators are replacing diesel fleets fastest in Singapore's southwestern manufacturing and shipping corridor due to emission zone enforcement and depot-based charging economies. Land Transport Authority procurement mandates for public bus electrification intersect with private freight operator conversion timelines in this sub-region. Battery-electric commercial vehicles with lithium-iron-phosphate chemistries are penetrating this humid tropical environment for their thermal stability advantages.
Tampines and Eastern Town Centres
Residential charging deployment faces structural constraints in Singapore's high-rise eastern new towns, forcing dependence on public infrastructure in shopping mall and HDB estate carparks. Subscription and car-sharing ownership models are expanding most quickly among young professionals in this sub-region who seek lifestyle flexibility without parking obligations. Wireless charging trials for public transit depots are underway to automate overnight bus fleet replenishment.
Northern Woodlands Corridor
Cross-border logistics operators serving Malaysia-connected supply chains are evaluating battery-electric platforms for route segments within Singapore's emission-controlled zones. The Pan Island Expressway corridor through this sub-region is prioritizing fast-charger deployment for mid-route commercial vehicle replenishment. Fleet leasing structures bundling vehicles, charging infrastructure, and energy management are consolidating procurement decisions among operators with fixed depot routes.
Singapore Electric Vehicle Market Competitive Landscape
Channel-controlling players compete with product-specialist players for positioning across Singapore's electric vehicle procurement channels, with direct-to-consumer distribution models clashing against fleet-focused leasing structures. The market exhibits tiered concentration where integrated software-hardware stacks sustain recurring revenue streams alongside hardware-centric manufacturers competing on battery safety credentials and platform efficiency. Strategic archetypes include direct-sales technology integrators, fleet-leasing specialists, and dedicated EV platform engineers. Dominant competitive moves encompass strategic partnerships bundling vehicles with charging infrastructure and geographic expansion through centralized depot electrification.
Within the technology-integrator tier, Tesla Inc. and BYD Co. Ltd anchor contrasting approaches to Singapore's bifurcated demand structure. Tesla Inc. exemplifies the direct-to-consumer archetype with integrated software-hardware stacks, while BYD Co. Ltd occupies a position within the fleet-specialist tier through blade battery safety positioning. Hyundai Motor Company sits within the dedicated-platform engineering archetype, reducing component count and assembly complexity for commercial vehicle applications. These three companies represent the strategic positioning spectrum visible across Singapore's procurement channels.
| Leading Market Players |
|---|
| BYD Co. Ltd |
| Tesla Inc. |
| Hyundai Motor Company |
| BMW AG |
| Mercedes-Benz Group AG |
| Nissan Motor Co. |
| Toyota Motor Corporation |
| Kia Corporation |
| SAIC Motor - MG |
| Others |
Value Network & Pricing Analysis
The Pan Island Expressway corridor concentrates freight cost dynamics where battery-electric fleet procurement intersects with Certificate of Entitlement auction volatility and carbon-based vehicle taxation, creating downstream price differentiation between depot-based commercial operators and dispersed residential buyers.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate commercial vehicle procurement, separating premium fleet-leasing bundles from standard direct-purchase arrangements. Price differentiation hinges on battery chemistry grade and charging infrastructure bundling intensity. Pricing pressure stems from Certificate of Entitlement quota compression inflating upfront acquisition costs. Fleet operators exhibit highest price sensitivity due to margin compression from simultaneous vehicle and depot electrification capex.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Chinese and South Korean cell manufacturers anchor working capital structures for Singapore-based fleet operators. Geographic concentration centers on China, South Korea, and Japan for lithium-ion cell production. Raw material dependencies span lithium hydroxide, nickel sulfate, and cobalt cathode precursors. Single-source vulnerability from concentrated cathode processing creates structural exposure. Distribution runs through regional hub ports with last-mile assembly in ASEAN manufacturing zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's electric vehicle market is entering a cyclical recovery phase as Certificate of Entitlement quota reductions and carbon taxation force fleet replacement cycles, compressing traditional diesel asset lifespans.
For Market Incumbents: Entrench position through backward integration into charging infrastructure development and captive battery supply agreements with Chinese cell manufacturers. BYD Co. Ltd and Tesla Inc. threaten margin structures through bundled leasing offers. Prioritize Jurong Innovation District depot electrification to lock in logistics operator relationships.
For New Entrants and Emerging Players: Pursue white-space opportunities in wireless charging systems for public bus depots and subscription-based urban mobility platforms targeting young professionals in Tampines and eastern town centres. The most penetrable segment is electric motorcycle fleets for food delivery platforms. Deploy car-sharing partnerships with corporate campuses as the primary go-to-market angle.
For Investors and Strategic Acquirers: Charging infrastructure specialists with Energy Market Authority grid interconnection approvals represent the priority acquisition archetype. Long-term viability rests on depot electrification scaling through the projection horizon. Monitor Land Transport Authority procurement mandate acceleration as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cell offtake with Chinese manufacturers secures thermal-stable lithium-iron-phosphate capacity for tropical fleet applications. |
| Depot Electrification Partnership | Joint development of megawatt-scale charging hubs in Jurong Innovation District reduces land-use intensity for logistics operators. |
| Software-Defined Vehicle Investment | Over-the-air update capabilities enable recurring revenue streams from fleet management platforms serving ride-hailing operators. |
| Charging Infrastructure Expansion | Fast-charger deployment along Pan Island Expressway corridor addresses commercial vehicle mid-route replenishment requirements. |
| Platform Standardization | Dedicated EV architectures reduce component count and assembly complexity for commercial vehicle manufacturing scale. |
Research Methodology
Initial hypotheses were tested against primary input from fleet procurement managers, charging infrastructure developers, Land Transport Authority policy officers, and Energy Market Authority grid planners and refined through secondary validation against vehicle registration databases, Certificate of Entitlement auction records, and Land Transport Authority emission scheme documentation. Bottom-up fleet operator surveys triangulated with top-down regulatory impact modeling.
Demand-supply balance framing anchored the analytical approach across the projection horizon, modeling vehicle class, battery chemistry, charging infrastructure type, ownership model, and sub-regional corridor dimensions. CAGRs derived from segment-level replacement cycle analysis and fleet electrification mandate compliance timelines. Forecast inputs incorporated Certificate of Entitlement quota trajectory assumptions and carbon tax escalation schedules.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments and construction cost inflation would shift the trajectory of depot electrification investment. Forecasts reflect documented assumptions about regulatory enforcement intensity and cell chemistry cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Compact E-Scooter Market
Electric Vehicles
NGO Steel in Electric Vehicle Market
Electric Vehicles
Construction Electric Vehicle Market
Electric Vehicles
Electric Vehicle Sound Generators Market
Electric Vehicles
Global Electric Classic Car Market
Electric Vehicles
France Automotive High Performance Electric Vehicles Market
Electric Vehicles
RV SLI Battery Market
Electric Vehicles
UK Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
South America Electric Bus Battery Pack Market
Electric Vehicles
Vietnam E-Bike Market
Electric Vehicles
Asia-Pacific Electric Vehicle Thermal Management System Market
Electric Vehicles
Norway E-Bike Market
Electric Vehicles
E-SUV Market
Electric Vehicles
Electric Vehicle Insulation Market
Electric Vehicles
Electric Vehicle Relay Market
Electric Vehicles
Lithium Battery Electric Scooters Market