
 United States Electro Hydraulic Power Steering Market | 2026-2036
United States Electro Hydraulic Power Steering Market Size, Share, and Industry Trends Forecast 2026-2036
United States Electro Hydraulic Power Steering Market Analytics
Aluminum is replacing cast iron in EHPS pump housings and is realigning component weight and thermal management economics across supplier tiers. ZF Friedrichshafen AG leverages in-house aluminum die-casting capabilities to control pump assembly costs. Nexteer Automotive Group Ltd anchors its North American production footprint with dedicated EHPS lines in Michigan and Mexico. JTEKT Corporation competes through precision bearing integration that reduces hydraulic friction losses in steering assist modules.
Electro hydraulic power steering combines an electric motor-driven hydraulic pump with electronic control units to provide variable steering assist, typically operating at system pressures between 80 and 120 bar while drawing power only on demand rather than continuously from the engine belt. Its primary purpose is to reduce parasitic fuel loss relative to conventional hydraulic systems while preserving the road feel and load capacity required by heavier vehicles. Integrated product configurations lead the OEM channel due to their compact packaging and reduced assembly complexity at vehicle plants. Aftermarket Providers represent a growing segment as aging EHPS-equipped fleets require pump and sensor replacements outside warranty periods. Electronic Control technology commands attention from Tier-1 Suppliers seeking to embed adaptive steering algorithms directly into hydraulic actuation hardware.
NHTSA enforces fuel economy and safety standards that directly incentivize steering system electrification, while EPA tailpipe emissions rules amplify pressure on parasitic load reduction. The Department of Transportation's vehicle safety recall protocols shape liability exposure for steering component durability, pushing suppliers toward predictive maintenance telemetry. Stakeholders must monitor how NHTSA's evolving autonomous vehicle guidance treats steering redundancy requirements, as this will determine whether EHPS architectures retain relevance alongside steer-by-wire alternatives or evolve into hybrid backup systems.
Market Dynamics
NHTSA's Corporate Average Fuel Economy standards are compressing steering system efficiency thresholds, forcing suppliers to reengineer hydraulic architectures around on-demand electric pump activation rather than continuous belt-driven operation.
Growth Catalysts
- CAFE Standards:NHTSA mandates tighten parasitic load reduction requirements, compelling light-duty truck and SUV manufacturers to specify EHPS systems over conventional hydraulic steering.
- Aluminum Die-Casting:Pump housing material substitution reduces component mass and improves thermal dissipation, enabling compact packaging in engine bays with severe space constraints.
- Michigan-Tennessee Corridor:Concentrated OEM assembly capacity across the Midwest and Southeast generates localized demand pull, reducing logistics costs for Tier-1 suppliers with regional production footprints.
Market Restraints
- Aluminum Price Volatility:Raw material cost swings for die-cast pump housings compress margin stability for suppliers without backward integration into primary metal sourcing.
- Steer-by-Wire Substitution:Fully electric steering architectures eliminate hydraulic components entirely, threatening EHPS relevance as autonomous vehicle redundancy requirements evolve.
- EPA Certification Burden:Tailpipe emissions testing protocols add validation layers to steering system integration, extending development timelines for new vehicle programs.
Strategic Opportunities
- Aftermarket Telemetry:Predictive maintenance sensor integration creates recurring revenue streams as aging EHPS-equipped fleets exit warranty coverage and require pump replacement.
- Hybrid Backup Architectures:NHTSA autonomous vehicle guidance may designate EHPS as fail-safe redundancy for steer-by-wire systems, preserving hydraulic component demand.
- Electronic Control Convergence:Tier-1 suppliers embedding adaptive steering algorithms directly into hydraulic actuation hardware capture value from software-defined vehicle trends.
Industry Challenges
- Mechatronics Talent Scarcity:Cross-disciplinary engineering expertise combining hydraulic system design with embedded software development commands premium compensation and constrains supplier scaling.
- Legacy Fleet Integration:Service technicians face diagnostic complexity when EHPS electronic control units interface with aging vehicle electrical architectures lacking standardized communication protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Electro Hydraulic Power Steering Market |
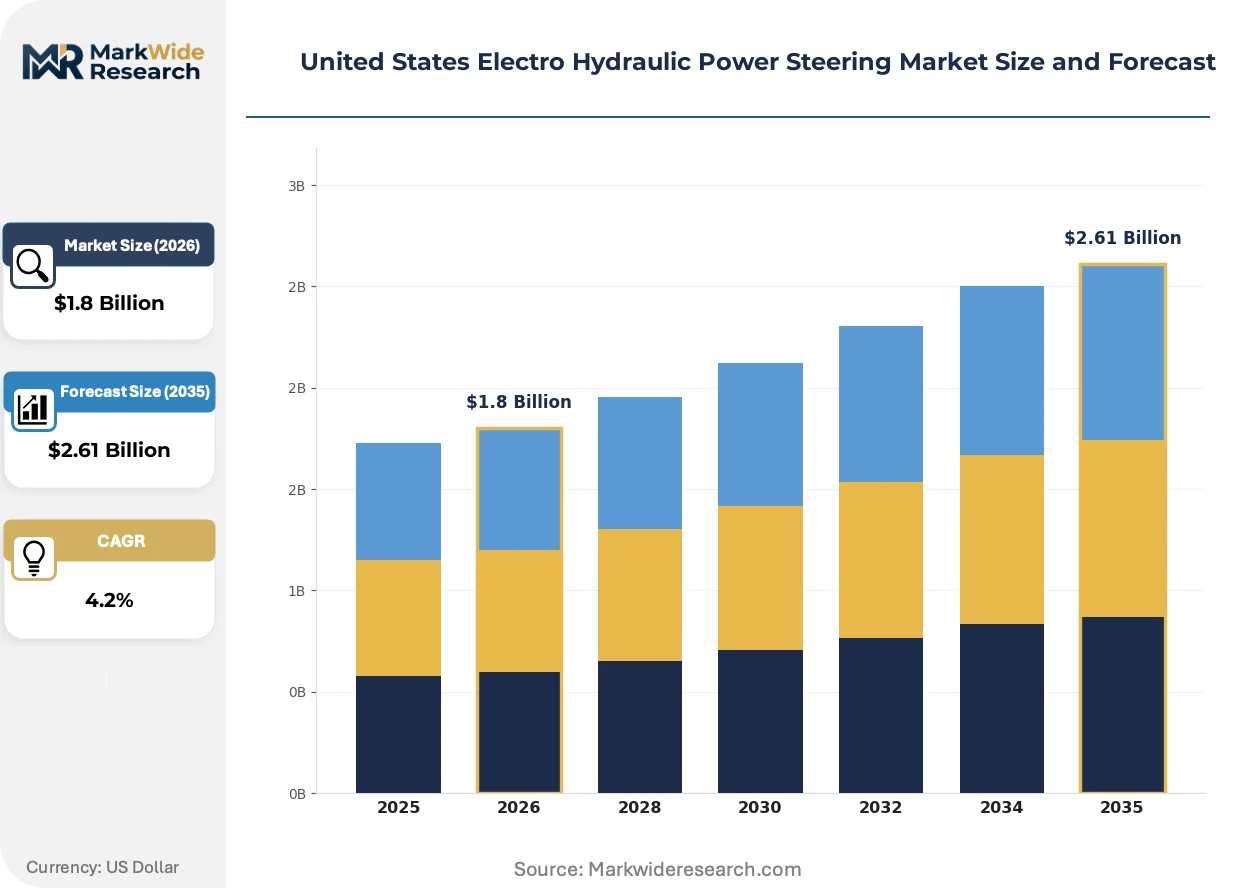
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact, Integrated, Modular, Standalone End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Distributed Control, Centralized Control, Electronic Control, Hydraulic Actuation Installation: Factory Installed, Retrofit, Onboard, Offboard |
| Companies Covered | JTEKT Corporation, Nexteer Automotive Group Ltd, ZF Friedrichshafen AG, NSK Ltd, Robert Bosch GmbH, Hyundai Mobis, Mitsubishi Electric, Delphi Technologies, GKN Automotive, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Electro Hydraulic Power Steering Market Evolving Landscape
Active material substitution and embedded intelligence are redefining component boundaries in steering systems, collapsing traditional separations between mechanical actuation and electronic decision-making.
Variable-displacement vane pumps with integrated motor control are expanding into integrated product configurations that package hydraulic generation, pressure modulation, and electronic supervision within single casting assemblies. Light-duty truck OEMs in the Southeast assembly belt are specifying these compact modules to reduce line-side assembly steps. The technology is expanding into adjacent commercial vehicle categories previously served by conventional constant-flow pumps.
NHTSA's evolving autonomous vehicle guidance is creating regulatory uncertainty around steering redundancy requirements, forcing suppliers to engineer dual-path architectures that satisfy both current safety standards and anticipated rulemakings. This compliance burden falls heaviest on integrated Tier-1 suppliers with direct OEM relationships. Michigan-based engineering centers are responding by pre-certifying EHPS variants against draft redundancy protocols.
Fleet operators are unbundling steering system maintenance from comprehensive vehicle service contracts, creating direct procurement relationships with aftermarket component distributors. Independent repair facilities in the Midwest automotive corridor are capturing this disintermediated demand through specialized hydraulic diagnostic equipment. The pattern concentrates where aging light-duty truck populations exceed regional dealership service capacity.
United States Electro Hydraulic Power Steering Market Segmentation
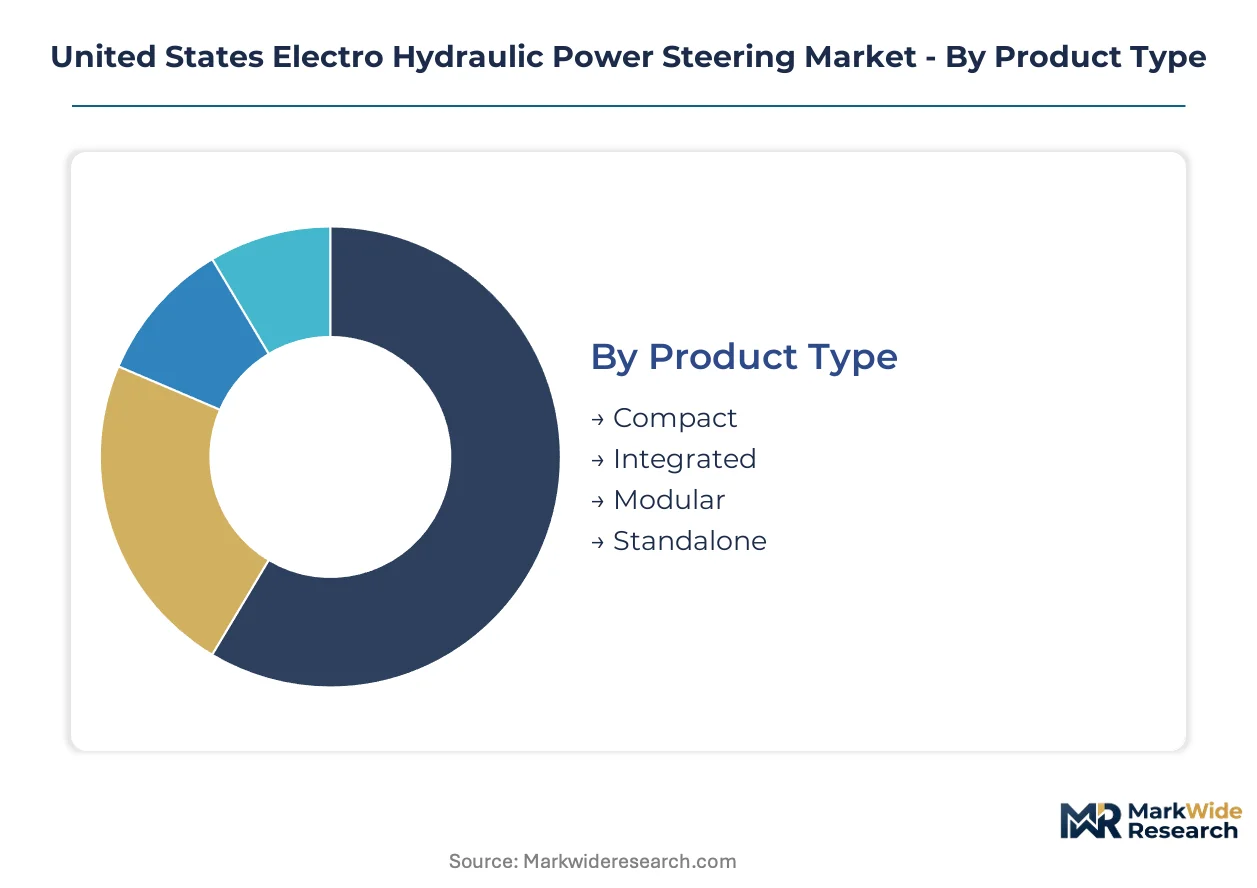
Segmentation reveals how EHPS suppliers align product architectures with distinct procurement channels and technical requirements. Upgrade cycles differ sharply between new vehicle programs and aging fleet maintenance, creating divergent margin structures across categories.
Product Type:
Replacement cycles vary from single-model-year refreshes to decade-long platform commitments, with packaging constraints dicting which configurations suit specific vehicle classes.
- Integrated:Combines pump, motor, and electronic control within a single aluminum die-cast housing optimized for engine bay thermal management. Light-duty truck OEMs across Michigan's manufacturing corridor specify these units to reduce assembly line complexity and meet NHTSA fuel economy mandates through weight reduction.
- Compact:Reduced-form-factor assemblies targeting space-constrained crossover SUVs with transverse engine layouts. Demand clusters in Tennessee and South Carolina assembly plants where platform flexibility requires modular steering integration without structural redesign.
- Modular:Separates hydraulic generation from electronic supervision to enable field-service component replacement. Independent repair facilities in the Midwest automotive corridor favor this architecture for aging fleet maintenance outside dealership networks.
- Standalone:Conventional pump-and-reservoir configurations for legacy vehicle platforms with minimal electronic integration. Sustained demand from commercial vehicle upfitters serving utility and vocational truck segments.
Volume placements concentrate in Integrated; the faster expansion belongs to Compact.
End User:
Procurement authority differs markedly between entities controlling new vehicle specifications and those managing post-warranty component flows.
- OEMs:Direct vehicle manufacturers with platform-level steering system specification authority. NHTSA CAFE compliance deadlines drive their EHPS sourcing decisions for light-duty truck and SUV lineups.
- Tier-1 Suppliers:Integrated system houses delivering complete steering modules to vehicle assembly plants. These entities capture value through embedded software development and predictive maintenance algorithm integration.
- Aftermarket Providers:Distributors and remanufacturers serving vehicles exiting warranty coverage. Fleet operators in the Southeast assembly belt are unbundling steering maintenance from comprehensive service contracts, expanding this channel.
- Vehicle Assemblers:Contract manufacturers and specialty vehicle builders with limited in-house steering engineering. Their procurement emphasizes plug-compatible modules with minimal calibration requirements.
Revenue concentration sits with OEMs; aftermarket channels are climbing the fastest as EHPS-equipped fleets age.
Technology:
Control architecture selection determines how steering systems interface with broader vehicle electrical networks and autonomous driving platforms.
- Electronic Control:Embeds adaptive algorithms and torque mapping directly into hydraulic actuation hardware. Tier-1 suppliers leverage this capability to meet NHTSA's evolving autonomous vehicle redundancy guidance through software-defined steering behavior.
- Centralized Control:Routes all steering sensor data through a dedicated domain controller, simplifying diagnostics but requiring robust vehicle network bandwidth. Preferred by OEMs with standardized electrical architectures across multiple platforms.
- Distributed Control:Locates processing at the pump assembly to reduce wiring complexity and improve fault isolation. Southeast assembly plants favor this approach for its resilience against single-point electrical failures.
- Hydraulic Actuation:Conventional pressure-based assist without electronic modulation, retained for heavy-load commercial applications where mechanical simplicity outweighs efficiency gains.
Design wins cluster around Electronic Control; steepest expansion trajectory belongs to Distributed Control as network architecture diversity increases.
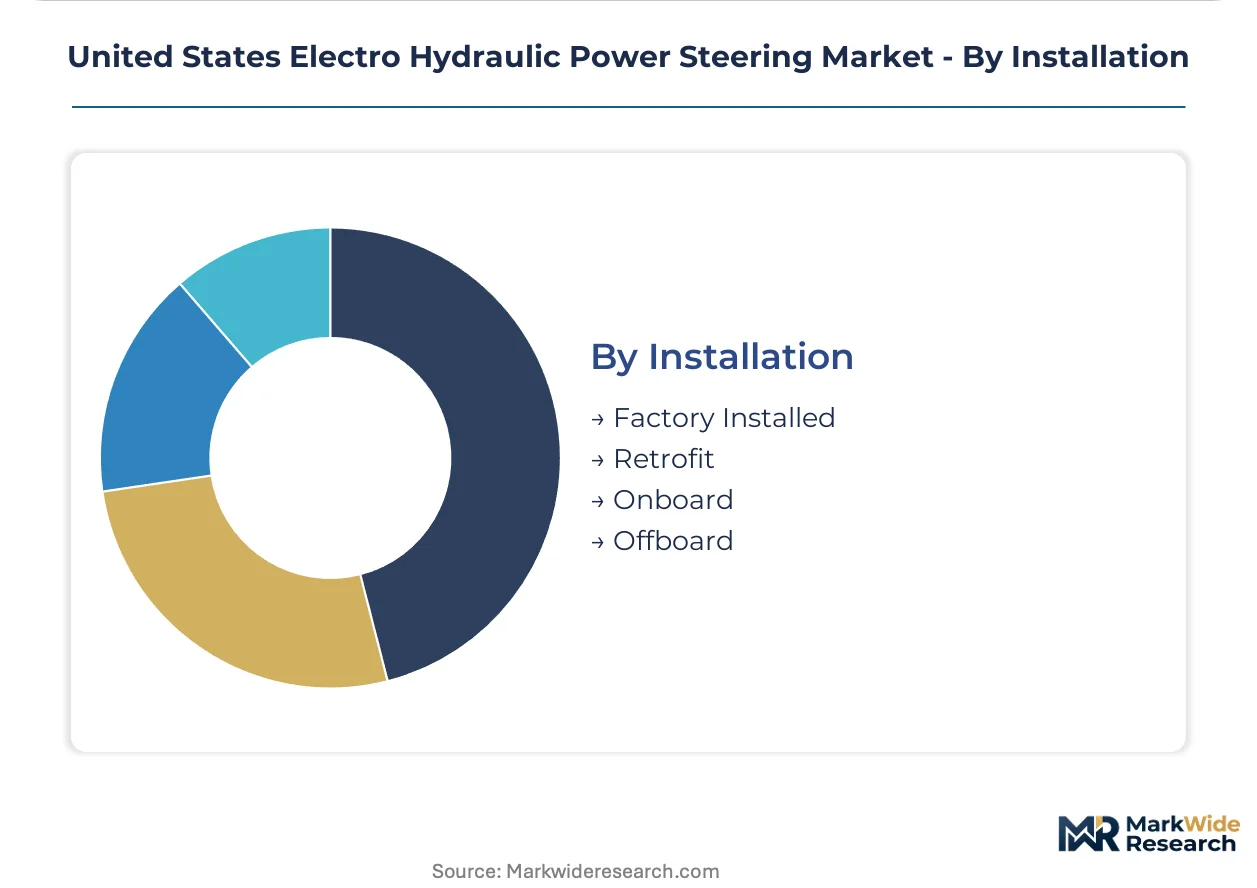
Installation:
Point of integration determines warranty liability, calibration complexity, and service channel economics throughout a product's lifecycle.
- Factory Installed:Line-fit assembly at vehicle manufacturing plants with full OEM warranty coverage. Michigan and Tennessee corridors dominate this channel through concentrated light-duty truck production capacity.
- Retrofit:Post-production installation for fleet modifications and accessibility conversions. Vocational truck upfitters in the Midwest leverage this channel to customize steering assist characteristics for specific duty cycles.
- Onboard:Systems integrated during vehicle assembly but designed for field serviceability without structural disassembly. Supports the predictive maintenance telemetry strategies emerging in commercial fleet management.
- Offboard:Bench-test and remanufacturing configurations for component-level refurbishment. Independent repair facilities use these protocols to extend EHPS service life beyond original equipment specifications.
Factory Installed commands absolute volume dominance; Retrofit applications are gaining share fastest as fleet operators seek to extend vehicle service life.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for electro hydraulic power steering concentrates in manufacturing corridors where light-duty truck and SUV assembly clusters intersect with NHTSA compliance deadlines. State-level fuel economy enforcement and localized supplier footprints shape procurement patterns across distinct sub-regional markets.
Michigan
OEM headquarters concentration and Tier-1 engineering centers drive specification authority for EHPS architectures. NHTSA CAFE standards enforcement through the Department of Transportation presses manufacturers toward on-demand electric pump systems. Detroit-Warren-Dearborn MSA anchors production with dedicated EHPS lines serving Ford, General Motors, and Stellantis light-duty truck platforms.
Tennessee
Nissan and Volkswagen assembly operations generate pull for compact EHPS configurations suited to crossover SUV transverse engine layouts. State economic development incentives for automotive suppliers reduce landed costs for pump housing manufacturers. Chattanooga-Nashville corridor facilities specialize in modular steering integration for platform-flexible vehicle programs.
South Carolina
BMW Manufacturing and Volvo Car USA operations concentrate demand for precision steering modules with embedded electronic control. EPA tailpipe emissions testing protocols for Southeast vehicle exports extend validation requirements for hydraulic system integration. Spartanburg-Greenville area suppliers coordinate just-in-time delivery to minimize inventory carrying costs.
Alabama
Mercedes-Benz and Hyundai Motor Manufacturing assembly plants specify integrated EHPS housings optimized for engine bay thermal management. State workforce development programs targeting mechatronics skills address cross-disciplinary engineering scarcity. Tuscaloosa-Montgomery supplier parks reduce logistics friction through proximity to final assembly lines.
Ohio
Honda of America Manufacturing and Lordstown Motors operations sustain demand for standalone and retrofit EHPS configurations. Ohio EPA coordination with federal NHTSA standards creates dual-layer compliance environments for steering system durability. Toledo-Cleveland corridor independent repair facilities capture aftermarket telemetry revenue from aging fleet populations.
United States Electro Hydraulic Power Steering Market Competitive Landscape
Backward integration into aluminum die-casting capabilities dominates the current landscape as suppliers seek margin protection against raw material volatility. The vendor base concentrates around integrated system houses with direct OEM relationships, creating tiered competition between full-module providers and component specialists. Two strategic archetypes prevail: diversified automotive suppliers leveraging cross-platform scale, and steering-focused specialists embedding software-defined functionality. Capacity expansion in the Michigan-Tennessee corridor and technology licensing for electronic control algorithms represent the dominant competitive moves reshaping supplier positioning.
Within the integrated Tier-1 tier, ZF Friedrichshafen AG and Nexteer Automotive Group Ltd occupy positions defined by regional production footprints and captive manufacturing capabilities. JTEKT Corporation exemplifies the precision-component archetype, anchoring competitive positioning through bearing integration expertise rather than full-system assembly. These three entities collectively represent the spectrum from diversified conglomerate structures to focused steering technology specialists, with each archetype responding differently to NHTSA's evolving autonomous vehicle redundancy requirements.
| Leading Market Players |
|---|
| JTEKT Corporation |
| Nexteer Automotive Group Ltd |
| ZF Friedrichshafen AG |
| NSK Ltd |
| Robert Bosch GmbH |
| Hyundai Mobis |
| Mitsubishi Electric |
| Delphi Technologies |
| GKN Automotive |
| Others |
Value Network & Pricing Analysis
Mechatronics engineering scarcity across Michigan's automotive corridor widens pricing-tier spreads between premium integrated modules and economy standalone configurations, as labor-cost differentials compound raw material volatility in aluminum die-cast pump housings.
Pricing Analysis
Volume placements concentrate in factory-installed integrated configurations, while aftermarket modular replacements generate fatter unit margins despite lower absolute throughput. Three-tier pricing structure across premium, standard, and economy levels separates OEM-specified electronic control modules from retrofit standalone pumps and commercial upfitter configurations. Cost compression in economy tiers is intensifying because aluminum price volatility squeezes suppliers without backward integration into primary metal sourcing. Fleet operators managing aging light-duty truck populations exhibit highest price sensitivity, whereas BMW Manufacturing and Volvo Car USA operations in South Carolina absorb premium positioning for embedded telemetry capabilities.
Supply Chain Analysis
Dual-sourcing requirements from NHTSA safety recall protocols push Tier-1 suppliers to qualify multiple aluminum die-casting partners across Michigan, Tennessee, and Mexico. The supply chain draws from bauxite refining concentrations in Australia and Guinea, secondary smelting capacity in Canada, and precision machining clusters in Germany and Japan. Single-source vulnerability concentrates in specialized bearing integration where JTEKT Corporation and NSK Ltd control precision friction-reduction technologies. Distribution runs through just-in-time supplier parks adjacent to Detroit-Warren-Dearborn and Chattanooga-Nashville assembly corridors, with aftermarket channels disintermediating through independent repair facilities in the Midwest automotive corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum die-casting capacity constraints across the Michigan-Tennessee corridor prop pricing power for suppliers with captive foundry operations, as mechatronics talent scarcity limits rapid competitor scale-up.
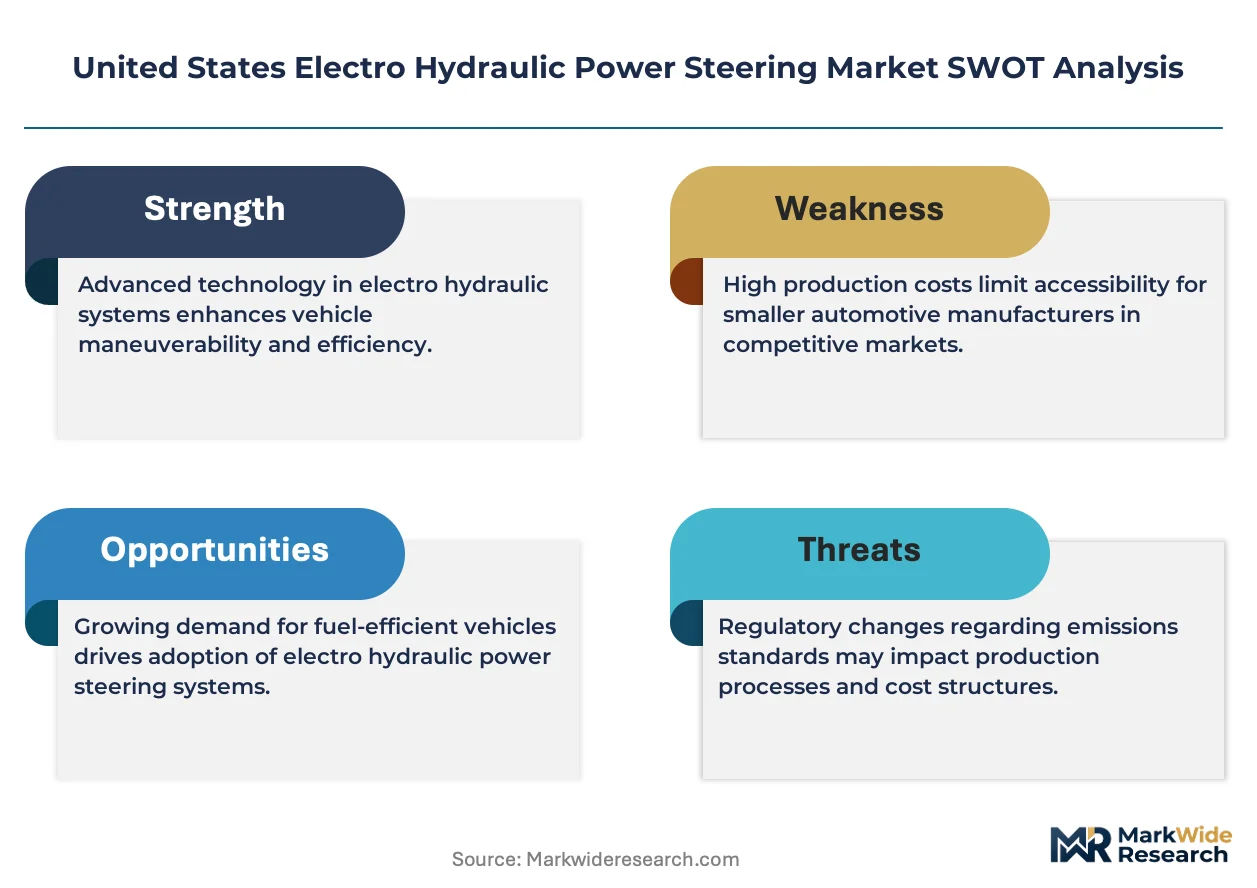
For Market Incumbents: Hedge against steer-by-wire substitution by pre-certifying EHPS variants as fail-safe redundancy for autonomous vehicle platforms under NHTSA's evolving guidance. Deepen backward integration into aluminum primary metal sourcing to insulate margin stability from commodity swings. Prioritize embedded software development capacity to capture value from adaptive steering algorithm convergence.
For New Entrants and Emerging Players: Predictive maintenance telemetry integration offers a technology-first wedge into aftermarket channels where aging fleets exit warranty coverage and dealerships lack diagnostic capacity. Target independent repair facilities in Ohio and Indiana where EHPS-equipped commercial vehicle populations exceed service infrastructure. Pursue direct procurement relationships with fleet operators unbundling steering maintenance from comprehensive vehicle contracts.
For Investors and Strategic Acquirers: Re-rating potential sits with Tier-1 suppliers possessing captive aluminum die-casting and embedded electronic control capabilities given NHTSA's tightening CAFE enforcement and autonomous vehicle redundancy requirements. Long-term viability favors integrated system houses over component specialists as software-defined vehicle trends collapse traditional mechanical-electronic boundaries. Watch NHTSA autonomous vehicle guidance finalization as the inflection signal determining whether EHPS architectures evolve into hybrid backup systems or face displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum Die-Casting Backward Integration | Captive foundry operations insulate ZF Friedrichshafen and Nexteer from raw material volatility compressing competitor margins. |
| Embedded Electronic Control Convergence | Tier-1 suppliers embedding adaptive algorithms directly into hydraulic hardware capture software-defined vehicle value pools. |
| Aftermarket Telemetry Integration | Predictive maintenance sensor deployment creates recurring revenue streams as EHPS-equipped fleets age beyond warranty coverage. |
| Dual-Path Redundancy Certification | Pre-certification against draft NHTSA autonomous vehicle protocols positions EHPS as steer-by-wire fail-safe backup. |
| Regional Production Footprint Expansion | Michigan and Mexico manufacturing lines anchor Nexteer's North American supply security for Stellantis and Ford platforms. |
Research Methodology
Document review covered SEC automotive supplier filings, NHTSA CAFE compliance databases, and aluminum trade flow records, complemented by interviews with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributor operations heads, and independent repair facility owners across the Midwest and Southeast. Secondary validation drew from vehicle production databases, EPA tailpipe emissions testing protocols, and state-level economic development incentive disclosures. Bottom-up unit economics triangulated against top-down market sizing across product type, end user, technology, and installation segmentation dimensions.
Segment-level outputs across the projection horizon reflect vehicle class stratification, propulsion architecture differentiation, content-per-vehicle assumptions, and regional production cluster concentration. CAGRs were derived from regression analysis of historical EHPS adoption rates against NHTSA regulatory phase-in schedules and OEM platform refresh cycles. Industry-specific inputs included light-duty truck and SUV production forecasts, aluminum price trajectory modeling, and mechatronics engineering labor market tightness indices.
Several conditions sit outside the modeled scope, including potential NHTSA rulemaking acceleration on autonomous vehicle redundancy, breakthroughs in fully electric steer-by-wire cost parity, and structural shifts in aluminum sourcing from geopolitical trade policy. Forecasts reflect assumptions regarding sustained CAFE standard enforcement and gradual autonomous vehicle deployment timelines. Deviation in NHTSA's final autonomous vehicle guidance treatment of hydraulic backup requirements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
North America Torque Vectoring Market
Powertrain
Power Liftgate for Automotive Market
Powertrain
Automotive Drivetrain Market
Powertrain
Asia-Pacific Torque Vectoring Market
Powertrain
Brazil Automotive Market
Powertrain
Turbocharger Market
Powertrain
Diesel Engine Catalyst Market
Powertrain
New Energy Vehicle Scroll Compressor Market
Powertrain
South America Automotive Market
Powertrain
Asia Pacific Gasoline Injection Technologies Market
Powertrain
Automotive Driveline Market
Powertrain
Transmission Sales Market
Powertrain
Tuning Box Market
Powertrain
Engine Starter Market
Powertrain
Transmission Repair Market
Powertrain
EGR and Emissions Control Actuator Systems Market