
 Marine Strip Market | 2026-2036
Marine Strip Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Strip Market Analytics
East Asian steel mills and specialty metal processors is pivoting toward marine-grade output as Korean and Chinese shipyards expand newbuild schedules. HD Hyundai Heavy Industries leverages captive forging capacity to secure internal strip supply chains for hull construction. China State Shipbuilding Corporation anchors domestic demand through state-backed naval and commercial vessel programs. Fincantieri differentiates via precision-formed decorative strip for luxury yacht interiors.
Marine strip denotes narrow, elongated metal or polymer profiles engineered to exacting width and thickness tolerances for hull reinforcement, interior finishing, and watertight sealing applications in saltwater environments. Stainless steel variants typically conform to ASTM A240 or equivalent marine grades with molybdenum-enhanced pitting resistance, while aluminum strip achieves weight reduction through 5083-H116 temper specifications. Flat strip dominates volume in structural hull applications where straight-edge reinforcement is critical, while decorative strip commands premium positioning in superyacht fit-outs. Custom strip segments are expanding fastest as naval architects specify non-standard geometries for stealth and hydrodynamic optimization.
IMO conventions on anti-fouling systems and coating safety, alongside national shipbuilding standards administered by classification societies such as Lloyd's Register and DNV, mandate material traceability and corrosion performance for all hull-contact components. The EU's REACH framework and evolving EPA stormwater regulations for shipyard runoff further constrain permissible alloy compositions and surface treatment chemistries. Stakeholders must monitor classification society rule changes and regional green procurement mandates to anticipate specification shifts before contract tendering cycles.
Market Dynamics
Shipyards in South Korea and China are consolidating procurement around certified marine-grade strip suppliers capable of delivering full material traceability under tightening IMO environmental standards. This concentration pressure is reshaping supplier qualification protocols and accelerating backward integration among major builders.
Growth Catalysts
- IMO Anti-Fouling Convention:The International Maritime Organization's restrictions on biocidal coating systems are redirecting hull protection strategies toward corrosion-resistant metal strip solutions with documented environmental compliance.
- Naval vessel programs:State-backed shipbuilding initiatives in China and South Korea are generating sustained demand for custom-width structural strip with stealth-optimized geometries and signature-reduction specifications.
- Superyacht interior fit-out specialization:European luxury yacht builders are specifying precision-formed decorative strip in bronze and titanium alloys for bespoke cabin finishes, creating premium pricing tiers.
Market Restraints
- Nickel price volatility:Molybdenum-enhanced stainless steel grades depend on nickel alloy inputs subject to London Metal Exchange price swings that compress mill margins and destabilize contract pricing.
- East Asian supply concentration:Over 70 percent of marine-grade flat strip capacity sits in Chinese, Japanese, and South Korean steel mills, creating geographic risk exposure for European and North American shipyards.
- Welding compatibility constraints:Dissimilar metal galvanic corrosion between aluminum strip hull reinforcement and traditional steel framing limits hybrid construction adoption in commercial vessels.
Strategic Opportunities
- Brazilian offshore support vessel renewal:Petrobras platform supply vessel replacement programs are opening procurement channels for corrosion-resistant strip in 5083-H116 aluminum grades.
- EU Green Deal procurement mandates:European public vessel tenders are incorporating recycled content thresholds that favor domestic strip processors with verified scrap-to-product supply chains.
- Digital twin integration:Shipyard engineering platforms are converging with metallurgical databases to enable real-time strip specification optimization based on predicted stress loading and saltwater exposure profiles.
Industry Challenges
- Welding technician certification bottlenecks:Lloyd's Register and DNV qualification requirements for marine-grade aluminum and stainless steel joining are extending yard workforce training timelines.
- Multi-classification compliance complexity:Vessels requiring simultaneous ABS, Bureau Veritas, and Korean Register certification face conflicting strip surface finish and hardness specifications that fragment production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Strip Market |
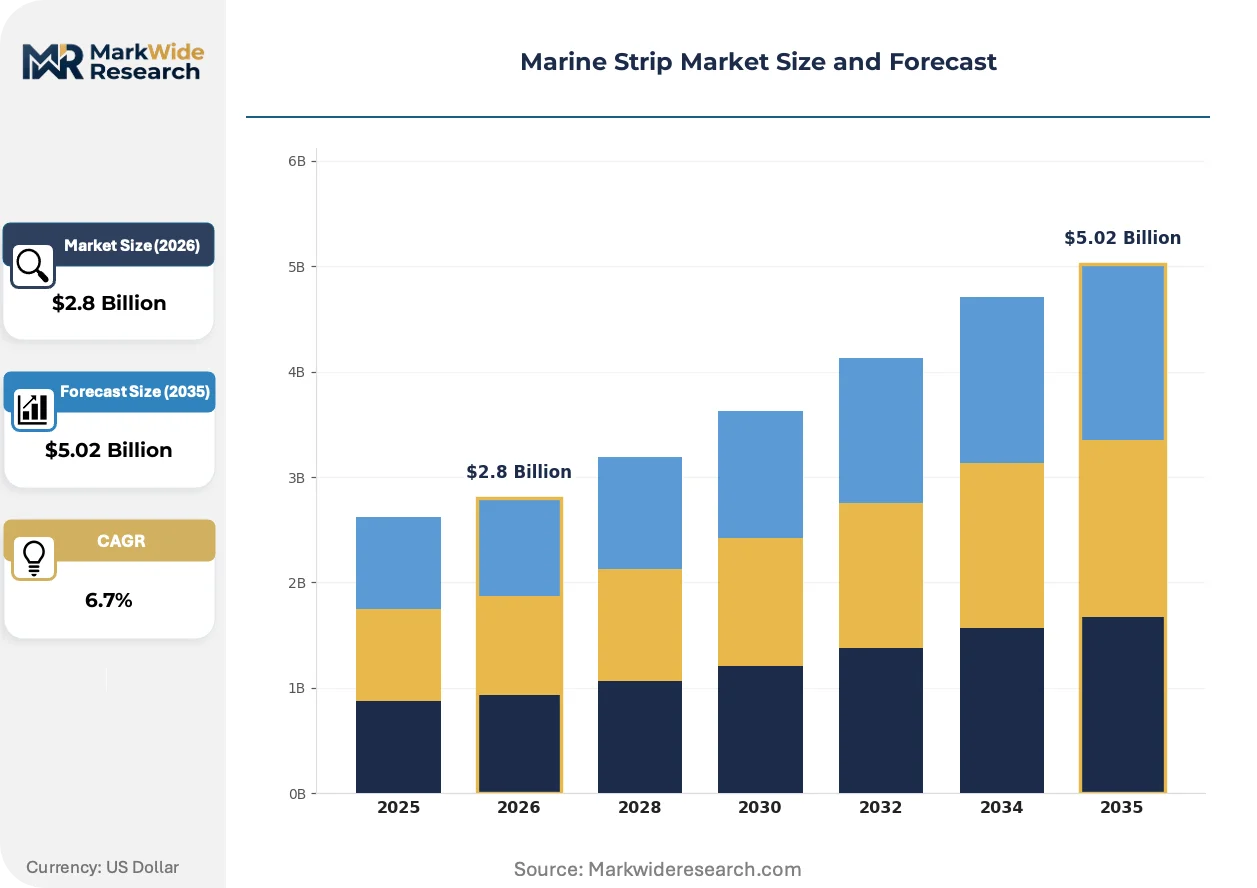
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Strip, Round Strip, Decorative Strip, Custom Strip Material: Stainless Steel, Aluminum, Bronze, Plastic Application: Boat Manufacturing, Shipbuilding, Marine Maintenance, Repair Services End User: Recreational Boaters, Commercial Vessels, Naval Forces, Marine Technicians |
| Companies Covered | HD Hyundai Heavy Industries, China State Shipbuilding Corporation, Fincantieri, Huntington Ingalls Industries, Mitsubishi Heavy Industries, Damen Shipyards Group, General Dynamics NASSCO, BAE Systems, Austal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Strip Market Evolving Landscape
Digital specification tools and advanced alloy formulations are compressing design-to-delivery cycles while enabling non-standard geometries that were previously uneconomical at production scale.
Laser-profiled custom strip with variable thickness along the coil length is overtaking traditional flat-rolled products in naval hull applications. Norwegian and French naval architects are specifying these profiles for hydrodynamic optimization at bow and stern sections. The technology is overtaking conventional fixed-width rolling by eliminating secondary machining steps and reducing material scrap rates.
REACH framework restrictions on hexavalent chromium surface treatments are forcing mills to migrate toward trivalent chrome and chrome-free passivation chemistries for stainless strip. The regulation is compressing supplier qualification timelines as yards demand pre-certified alternative finishes. European superyacht builders are most affected, with Fincantieri and German yards accelerating supplier audits.
Direct mill-to-yard contracting is displacing traditional distributor intermediaries for high-volume structural strip categories. Korean mega-yards including HD Hyundai Heavy Industries are establishing multi-year offtake agreements with POSCO and Hyundai Steel that bundle metallurgical testing and just-in-sequence delivery. This pattern is most visible in Ulsan and Geoje shipbuilding clusters where inventory carrying costs are being pushed upstream to steel producers.
Marine Strip Market Segmentation
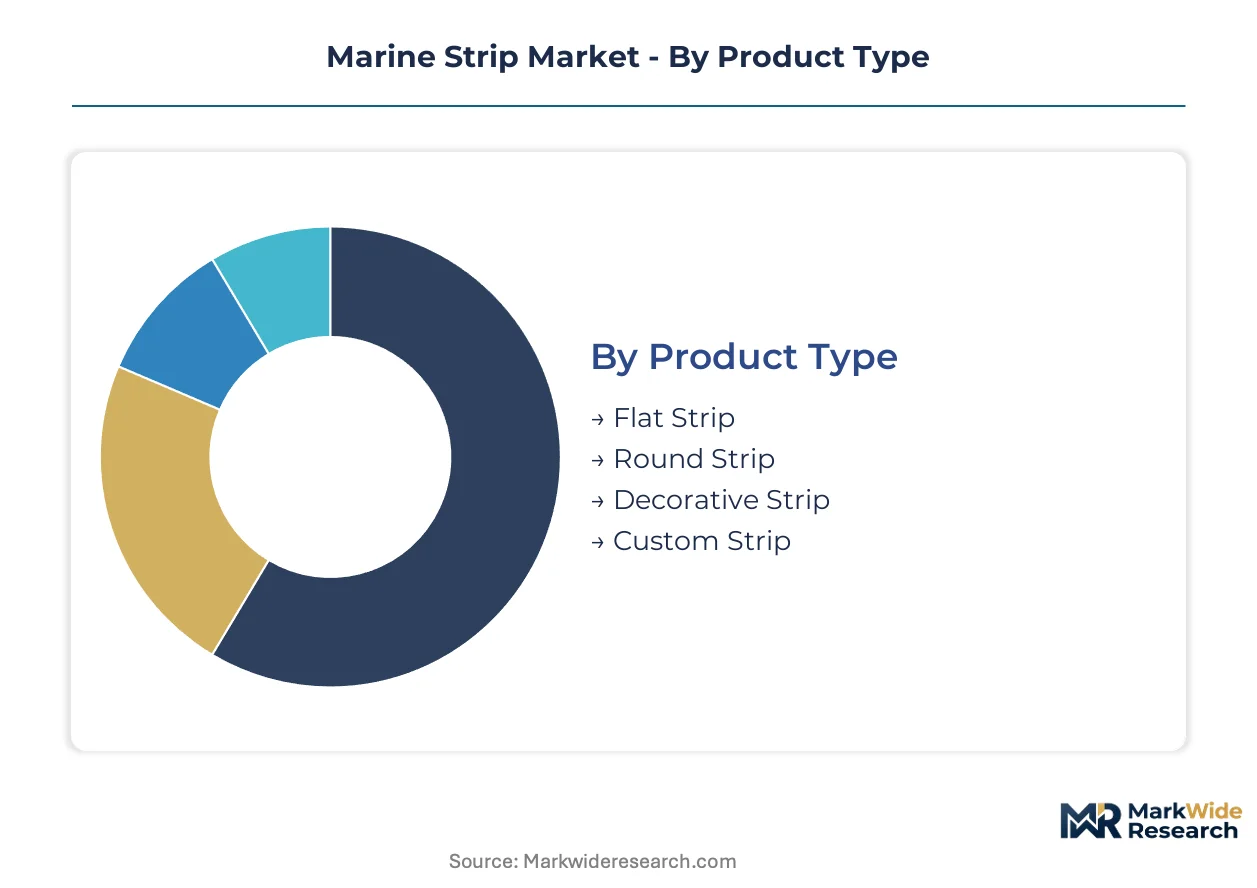
Marine strip procurement splits sharply between high-volume structural applications demanding certified metallurgical traceability and specialized decorative segments commanding alloy premiums. Shipyards and naval architects specify across four intersecting dimensions where material grade, geometric precision, and regulatory compliance determine supplier qualification.
Product Type:
Buyers differentiate primarily by manufacturing complexity tolerance and secondary processing requirements.
- Flat Strip:Rolled to uniform width and thickness tolerances for longitudinal hull reinforcement and watertight bulkhead sealing. Korean shipyards at Ulsan and Geoje consume the majority for commercial tanker and container vessel construction, with procurement bundled into multi-year metallurgical testing agreements.
- Custom Strip:Laser-profiled with variable thickness along coil length for hydrodynamic optimization at bow and stern sections. Norwegian and French naval architects specify these profiles for stealth-optimized geometries, eliminating secondary machining steps while reducing material scrap rates.
- Round Strip:Extruded or drawn circular profiles for handrail stanchions and curved framing applications in passenger vessel interiors.
- Decorative Strip:Precision-formed bronze and titanium alloys for bespoke superyacht cabin finishes, with Fincantieri and German yards driving premium specification tiers.
Volume sits with flat strip for structural hull applications; growth tilts toward custom strip as naval programs specify non-standard geometries for signature reduction.
Material:
Alloy selection hinges on weight reduction targets versus corrosion performance in saltwater exposure profiles.
- Stainless Steel:Molybdenum-enhanced grades conforming to ASTM A240 specifications deliver pitting resistance for hull-contact components. South Korean mills supply HD Hyundai Heavy Industries through captive forging arrangements, though nickel price volatility compresses contract margins.
- Aluminum:5083-H116 temper specifications achieve weight reduction for high-speed vessel hulls and offshore support platforms. Brazilian Petrobras platform supply vessel programs are opening procurement channels for corrosion-resistant aluminum grades in Atlantic basin operations.
- Bronze:Naval brass and silicon bronze variants specified for decorative marine hardware and traditional vessel restoration projects.
- Plastic:Glass-reinforced polymer strips for non-structural interior finishing and temporary protective edging during yard construction phases.
Stainless steel dominates commercial shipbuilding tonnage; aluminum is climbing fastest on offshore vessel renewal and naval weight-reduction mandates.
Application:
Contract value and certification intensity separate newbuild programs from aftermarket service workflows.
- Shipbuilding:Newbuild construction demands full material traceability under IMO environmental standards and classification society rules. China State Shipbuilding Corporation anchors domestic demand through state-backed naval and commercial vessel programs.
- Marine Maintenance:Scheduled dry-dock replacement of corroded strip edging and seal interfaces, with procurement urgency tied to vessel certification renewal timelines.
- Boat Manufacturing:Recreational craft production at smaller scale, with less stringent classification requirements than commercial tonnage.
- Repair Services:Emergency unscheduled replacement of damaged hull reinforcement, typically sourced through distributor networks rather than mill-direct channels.
Shipbuilding commands the highest contract values; marine maintenance offers recurring revenue stability through fleet aging.
End User:
Budget authority and specification complexity range from individual recreational owners to classified naval procurement offices.
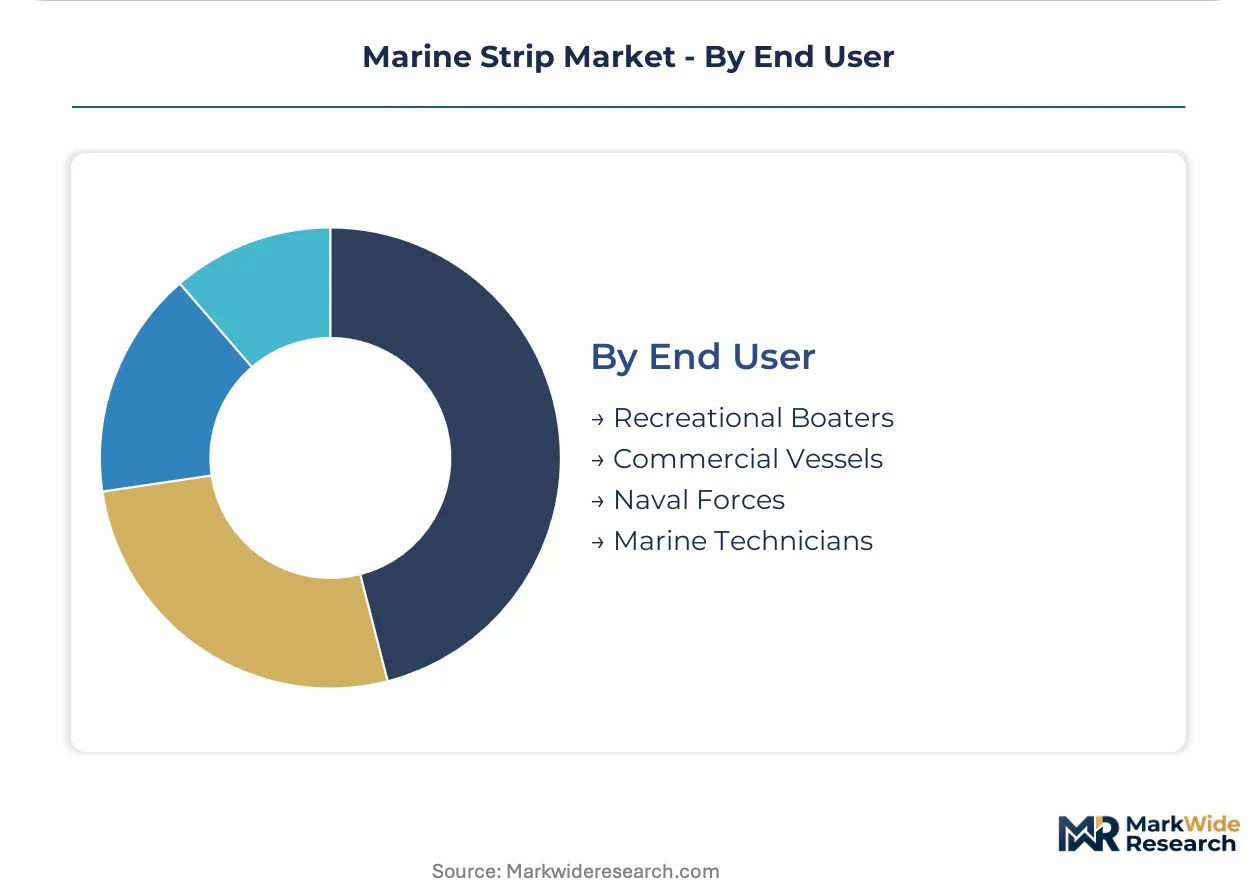
- Commercial Vessels:Container lines and tanker operators prioritize lifecycle cost optimization, driving standardization around mill-direct procurement of certified flat strip.
- Naval Forces:State-backed programs in China and South Korea generate demand for custom-width structural strip with stealth-optimized geometries and signature-reduction specifications.
- Recreational Boaters:Individual yacht owners and small charter operators sourcing through marine chandlers and distributor networks.
- Marine Technicians:Independent repair contractors performing emergency hull reinforcement with limited alloy specification authority.
Commercial vessels generate baseline volume; naval programs are expanding most quickly on state-backed fleet modernization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty steel capacity concentrates in East Asian mill complexes that feed Korean and Chinese shipbuilding clusters. Nickel-molybdenum alloy supply chains anchor procurement patterns for corrosion-resistant hull reinforcement materials.
South Korea
Ulsan and Geoje shipbuilding complexes drive demand for ASTM A240 certified stainless strip through multi-year offtake agreements with POSCO and Hyundai Steel. Korean Register classification rules mandate full material traceability for hull-contact components. HD Hyundai Heavy Industries leverages captive forging capacity to secure internal strip supply chains for commercial tanker construction.
China
State-backed naval and commercial vessel programs through China State Shipbuilding Corporation anchor domestic demand for custom-width structural strip. GB standards and MEE environmental regulations constrain permissible alloy compositions for shipyard applications. Yangtze River Delta and Pearl River Delta clusters concentrate newbuild output for both military and export commercial tonnage.
Japan
METI industrial policy supports precision rolling capacity for high-tolerance marine-grade output serving domestic and export shipbuilders. JIS standards govern material specifications for hull reinforcement applications. Nagoya and Osaka industrial corridors host specialty metal processors supplying Mitsubishi Heavy Industries and regional naval programs.
Italy
Fincantieri superyacht construction in Monfalcone and Trieste drives premium demand for decorative bronze and titanium strip alloys. EU Green Deal procurement mandates incorporate recycled content thresholds favoring domestic processors with verified scrap-to-product supply chains. ECHA REACH framework restrictions on hexavalent chromium surface treatments force mills toward trivalent chrome passivation chemistries.
Brazil
Petrobras platform supply vessel replacement programs open procurement channels for 5083-H116 aluminum strip in Atlantic basin offshore operations. ANVISA and environmental agency regulations govern surface treatment chemistries for hull-contact materials. Rio de Janeiro and Espírito Santo shipyard clusters concentrate offshore support vessel construction and maintenance activity.
Marine Strip Market Competitive Landscape
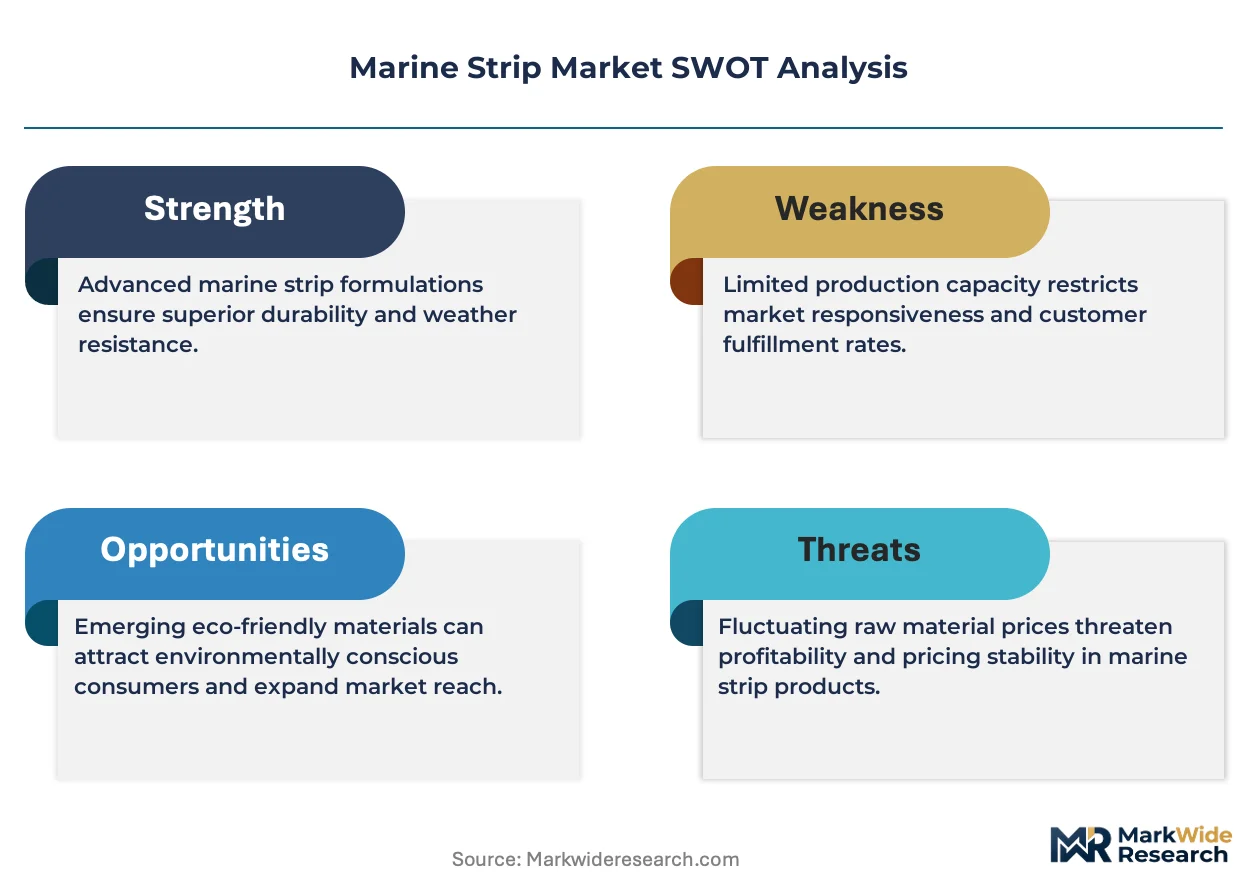
Global majors compete with regional champions across certification depth and metallurgical testing capabilities. The vendor base stratifies into integrated steel mills with captive marine divisions, specialized alloy processors, and precision fabricators serving superyacht fit-out segments. Three archetypes dominate: East Asian mill-shipyard conglomerates with backward integration into strip production; European precision specialists commanding alloy premiums for luxury applications; and state-linked builders securing domestic supply chains through national procurement programs. Capacity expansion and strategic partnerships represent the dominant competitive moves as yards consolidate supplier qualification protocols.
Within the integrated conglomerate tier, HD Hyundai Heavy Industries and China State Shipbuilding Corporation exemplify the captive supply model where mill capacity anchors construction cost control. Among European precision specialists, Fincantieri occupies a position representing premium-tier decorative strip demand. These named entities sit within broader patterns where geographic concentration of steel capacity directly shapes competitive positioning across certification-intensive procurement channels.
| Leading Market Players |
|---|
| HD Hyundai Heavy Industries |
| China State Shipbuilding Corporation |
| Fincantieri |
| Huntington Ingalls Industries |
| Mitsubishi Heavy Industries |
| Damen Shipyards Group |
| General Dynamics NASSCO |
| BAE Systems |
| Austal |
| Others |
Value Network & Pricing Analysis
London Metal Exchange nickel price volatility cascades through marine strip supply chains into contract pricing tiers, compressing mill margins on molybdenum-enhanced stainless grades while amplifying buyer leverage in aluminum 5083-H116 procurement for offshore vessel programs.
Pricing Analysis
Multi-year metallurgical testing and certification bundling separates premium contract tiers from spot-market transactional purchasing. Korean mega-yards negotiate captive supply arrangements with POSCO and Hyundai Steel that embed just-in-sequence delivery and full traceability documentation, while European superyacht builders absorb alloy premiums for decorative bronze and titanium strip. Pricing pressure stems from nickel input cost compression on stainless margins, with commercial vessel operators exhibiting highest price sensitivity through standardized flat strip specifications, whereas naval programs tolerate premium positioning for signature-reduction custom geometries.
Supply Chain Analysis
Seaborne freight costs from East Asian mill complexes to Atlantic basin shipyards constrain procurement flexibility for European and Brazilian builders lacking regional marine-grade capacity. Production concentrates in South Korea, China, and Japan, where specialty steel processors feed Ulsan, Geoje, and Yangtze River Delta construction clusters. Nickel-molybdenum alloy supply and 5083-H116 aluminum billet feedstock anchor raw material dependencies. Single-source vulnerability around Korean Register and DNV certification-qualified mills creates qualification bottlenecks. Distribution runs through direct mill-to-yard contracting for structural categories, with distributor networks handling emergency repair procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine strip supply constraints tighten around Korean and Chinese mill capacity qualified under IMO environmental standards and classification society rules, with certification bottlenecks propping pricing power for accredited suppliers.
For Market Incumbents: To counter nickel price volatility compressing stainless steel margins, deepen backward integration into captive forging capacity following HD Hyundai Heavy Industries' model, and secure multi-year offtake agreements bundling metallurgical testing to lock in yard procurement relationships before contract tendering cycles. For New Entrants and Emerging Players: Enter via Brazilian offshore support vessel renewal programs, where Petrobras platform supply vessel demand for 5083-H116 aluminum strip outpaces qualified local supply. Target EU Green Deal procurement mandates favoring verified scrap-to-product supply chains as the penetrable entry point, with certification investment as the primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor European precision specialists with trivalent chrome passivation capabilities in Italy and Germany, where REACH framework restrictions on hexavalent chromium surface treatments force supplier consolidation. Long-term viability hinges on digital twin integration positioning, with shipyard engineering platform convergence as the signal to watch for metallurgical database differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Forging | HD Hyundai Heavy Industries secures internal strip supply chains for hull construction cost control. |
| Multi-year Offtake Agreement | Korean mega-yards bundle metallurgical testing and just-in-sequence delivery with POSCO and Hyundai Steel. |
| Certification Investment | European mills migrate toward trivalent chrome passivation to meet ECHA REACH framework restrictions. |
| Digital Twin Integration | Shipyard engineering platforms converge with metallurgical databases for real-time specification optimization. |
| Scrap-to-product Supply Chain Verification | EU Green Deal procurement mandates favor domestic processors with verified recycled content thresholds. |
Research Methodology
Document review covered Lloyd's Register and DNV classification society rule filings, IMO convention documentation, and customs trade data, complemented by interviews with shipyard procurement directors, specialty steel mill technical sales leads, and naval architect specification engineers. Secondary validation drew from China State Shipbuilding Corporation program disclosures, Fincantieri superyacht output reports, and Petrobras vessel procurement announcements. Bottom-up segment sizing triangulated against top-down steel industry capacity assessments.
Segment-level outputs across product type, material grade, application, and end user combined with regional production cluster analysis to inform projections across the analysis window. CAGRs derived from weighted average of historical shipbuilding output trajectories, naval modernization program announcements, and offshore vessel replacement cycles. Forecast inputs incorporated nickel price correlation models and classification society rule change probability assessments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt IMO environmental standard revisions or nickel supply disruption scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Spreader Lights Market
Marine
Marine Transport Refrigeration Unit Market
Marine
Marine Lighting Market
Marine
India Boat Davits Market
Marine
Marine Fin Stabilizer Market
Marine
Ship Heat Exchanger Market
Marine
Marine Engines Market
Marine
Singapore Container Transshipment Market
Marine
Buoys and Beacon Market
Marine
Swamp Boat Market
Marine
Sailboat Propellers Market
Marine
Marine VFD Market
Marine
Marine Salvage Services Market
Marine
Marine Big Data Market
Marine
Steel Ship Plate Market
Marine
Fishing Vessel Market