
 Europe Automatic Transmission for Passenger Car Market | 2026-2036
Europe Automatic Transmission for Passenger Car Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automatic Transmission for Passenger Car Market Analysis
The EU Green Deal is restructuring demand patterns across the Europe Automatic Transmission for Passenger Car Market as OEMs face binding CO2 reduction mandates. ZF Friedrichshafen leverages its integrated mechatronics portfolio to dominate electrified transmission architectures. Schaeffler anchors its position through precision clutch module manufacturing serving multiple European assembly plants. Continental competes via software-defined transmission control systems that optimize shift strategies for hybrid powertrains.
Europe Automatic Transmission for Passenger Car denotes torque-transfer systems utilizing planetary gearsets, hydraulic actuators, and electronic control units to automate gear selection without driver clutch engagement, typically operating at input torques between 250-600 Nm for C-segment and D-segment vehicles. Dual-clutch configurations lead volume in performance and luxury tiers due to their efficiency advantages over torque converter units, while continuously variable transmissions retain structural importance in economy hatchbacks where cost minimization governs procurement decisions. The SUV segment generates disproportionate margin contribution as higher gross vehicle weights demand reinforced clutch packs and expanded ratio spreads.
EMA, REACH, and the EU F-Gas Regulation collectively shape product compliance requirements for transmission fluids, friction materials, and thermal management components across European assembly networks. EMA's evolving emissions protocols force recalibration of shift maps to minimize NOx and particulate spikes during transient load conditions. Stakeholders must monitor how delegated acts under the EU AI Act classify autonomous gear-selection algorithms and their liability implications for automated manual systems deployed in rental and fleet channels.
Market Dynamics
The EU Green Deal's binding CO2 fleet targets are forcing OEMs to re-engineer powertrain architectures, with automated transmission procurement patterns shifting decisively toward electrified variants that optimize thermal efficiency across transient drive cycles.
Growth Catalysts
- EMA emissions protocols:Recalibrated shift maps reduce NOx spikes during load transients, compelling fleet operators toward automated systems that maintain compliance margins.
- Dual-clutch technology:Efficiency advantages over torque converter architectures drive premium sedan adoption in Southern European manufacturing corridors.
- SUV gross vehicle weights:Reinforced clutch pack demand from heavier platforms expands ratio spread requirements across C-segment and D-segment portfolios.
Market Restraints
- Specialized friction material supply:Concentrated sourcing of high-performance clutch facings from limited European compounders creates input cost volatility.
- REACH chemical restrictions:Transmission fluid formulation constraints limit thermal durability options for hybrid powertrain integration.
- Electrified powertrain substitution:Battery-electric platforms eliminate multi-speed transmission architectures entirely from dedicated EV architectures.
Strategic Opportunities
- Polish and Czech assembly corridors:Underpenetrated transmission module sourcing creates white space for localized clutch pack manufacturing serving German OEM networks.
- EU AI Act delegated acts:Emerging liability frameworks for autonomous gear-selection algorithms open compliance advisory services for rental fleet channels.
- Software-defined control convergence:Integration of mechatronics with predictive shift algorithms enables subscription-based calibration updates.
Industry Challenges
- Mechatronics systems integration:Hydraulic actuator precision tolerances demand specialized calibration expertise scarce across European technician training pipelines.
- EMA protocol certification timelines:Extended validation cycles for revised shift maps delay platform launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automatic Transmission for Passenger Car Market |
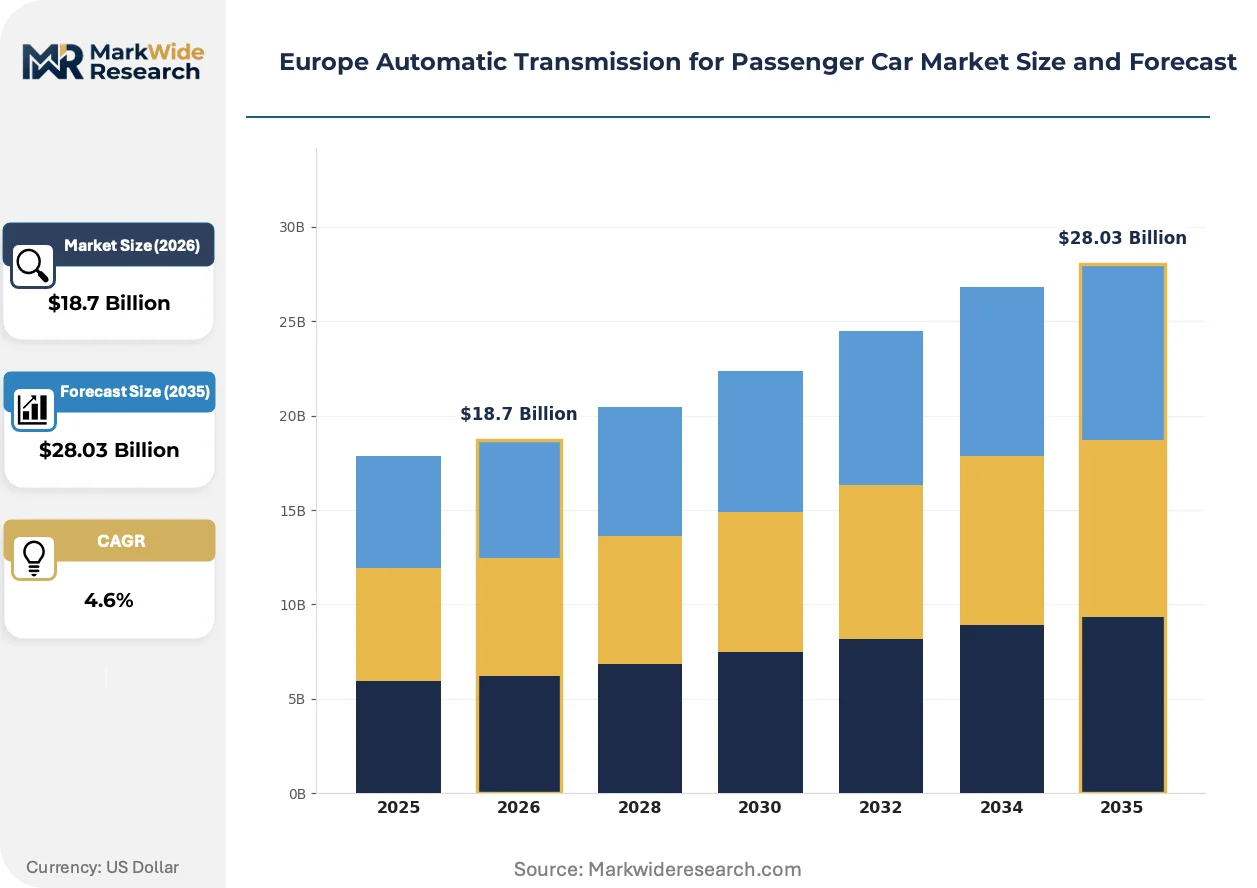
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transmission Type: Dual-Clutch, Continuously Variable, Torque Converter, Automated Manual Vehicle Type: SUV, Sedan, Hatchback, Coupe Market Share: Luxury, Economy, Mid-Range, Performance End User: Individual Consumers, Fleet Operators, Rental Services, Dealerships |
| Companies Covered | Allison Transmission, Schaeffler, ZF Friedrichshafen, Magna Powertrain, Continental, Aisin Seiki, BorgWarner, GKN Automotive, Voith, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automatic Transmission for Passenger Car Market Emerging Trajectories
Electrification is compressing the traditional transmission architecture stack, with software-defined control systems and integrated thermal management emerging as the primary vectors of competitive differentiation across European assembly networks.
Integrated thermal-fluid modules are unifying transmission cooling circuits with battery and inverter thermal loops in hybrid architectures. Tier-1 suppliers serving German premium OEMs are adopting these systems at accelerated procurement cadences. This convergence is unifying previously separate component supply chains into consolidated mechatronics portfolios.
REACH Annex XVII restrictions on perfluorinated compounds are forcing reformulation of high-performance transmission fluids. Compounders serving French and Italian assembly plants face reformulation costs that compress margin structures. The premium SUV segment absorbs these costs through specification upgrades while economy hatchback procurement delays adoption.
Fleet procurement contracts are consolidating transmission maintenance into powertrain-as-a-service agreements. Rental operators across Spain and Portugal are unbundling after-sales service from hardware acquisition, shifting supplier relationships toward outcome-based performance guarantees. This restructuring concentrates buying power among multi-brand fleet managers.
Europe Automatic Transmission for Passenger Car Market Segmentation
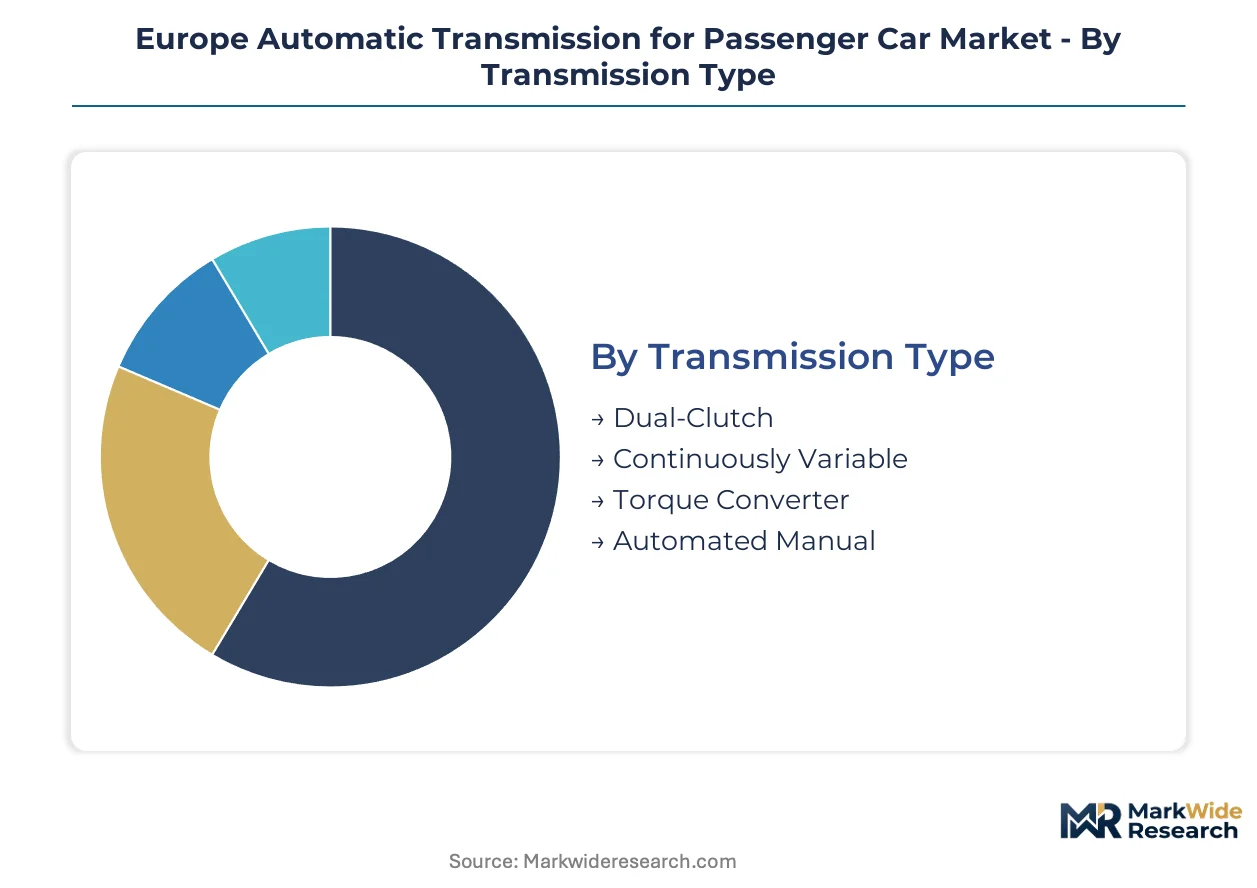
Transmission architecture selection across European passenger car platforms hinges on torque requirements, electrification readiness, and fleet CO2 compliance margins. Each segment carries distinct certification burdens under EMA protocols and REACH chemical frameworks that shape procurement specifications and supplier qualification pathways.
Transmission Type:
EMA emissions certification and EU F-Gas thermal management compliance impose divergent validation timelines across architectures, with electrified variants facing extended shift-map recalibration cycles.
- Dual-Clutch:Twin-shaft layouts with separate odd-even gear trains enable sub-200 millisecond shifts without torque interruption. Southern European premium sedan assembly corridors concentrate procurement as German OEMs optimize CO2 fleet averages through efficiency gains over torque converter alternatives.
- Continuously Variable:Pulley-and-belt systems maintain engine operation at optimal thermal efficiency points across transient drive cycles. Economy hatchback demand from French and Italian manufacturing clusters sustains volume despite torque limitations below 400 Nm restricting SUV applicability.
- Torque Converter:Hydrodynamic coupling architectures dominate North American-derived platforms assembled in European transplants. REACH transmission fluid formulation constraints complicate thermal durability certification for hybrid integration programs.
- Automated Manual:Synchronized manual gearboxes with electro-hydraulic actuation minimize parasitic losses for cost-sensitive segments. Rental fleet channels across Spain and Portugal specify these units for fuel economy compliance in urban duty cycles.
Leading the category by volume: Dual-Clutch. Growing fastest: Automated Manual in fleet electrification transitions.
Vehicle Type:
Gross vehicle weight ratings determine clutch pack specification tiers and ratio spread requirements, with heavier platforms demanding reinforced friction materials and expanded gear ranges.
- SUV:Elevated curb weights above 1,800 kg necessitate multi-plate clutch configurations and widened ratio spreads for launch performance. Polish and Czech assembly corridors serving German OEM networks drive disproportionate margin contribution through premium specification uptake.
- Sedan:Aerodynamic profiles and lower frontal areas enable optimized shift maps for highway fuel economy. Dual-clutch penetration concentrates in D-segment executive models manufactured across Southern European corridors.
- Hatchback:Compact packaging constraints favor transverse-mounted continuously variable units. Economy procurement from French and Italian brands prioritizes cost minimization over shift quality refinement.
- Coupe:Low-volume performance variants specify rapid-shift dual-clutch architectures with launch control integration. Tier-1 suppliers allocate limited production slots to German premium OEM programs.
SUV commands premium pricing power. Hatchback maintains structural volume anchor.
Market Share:
Price tier stratification aligns with thermal management complexity and software-defined control feature depth, with premium segments absorbing REACH fluid reformulation costs.
- Luxury:Integrated mechatronics with predictive shift algorithms and thermal-fluid module convergence. German premium OEM procurement specifications mandate EU AI Act compliance documentation for autonomous gear-selection liability frameworks.
- Economy:Minimized electronic content and fixed shift maps without adaptive learning capability. Margin compression from REACH Annex XVII perfluorinated compound restrictions delays technology refresh cycles.
- Mid-Range:Selectable drive modes with partial mechatronics integration bridging cost and performance requirements. Fleet operator procurement across Germany and France concentrates in this tier for CO2 target compliance.
- Performance:Track-calibrated shift strategies with reinforced clutch packs rated above 600 Nm. Limited volume production concentrates at specialized Southern European manufacturing facilities.
Mid-Range captures fleet transition volume. Performance tier expands most quickly in electrified hybrid configurations.
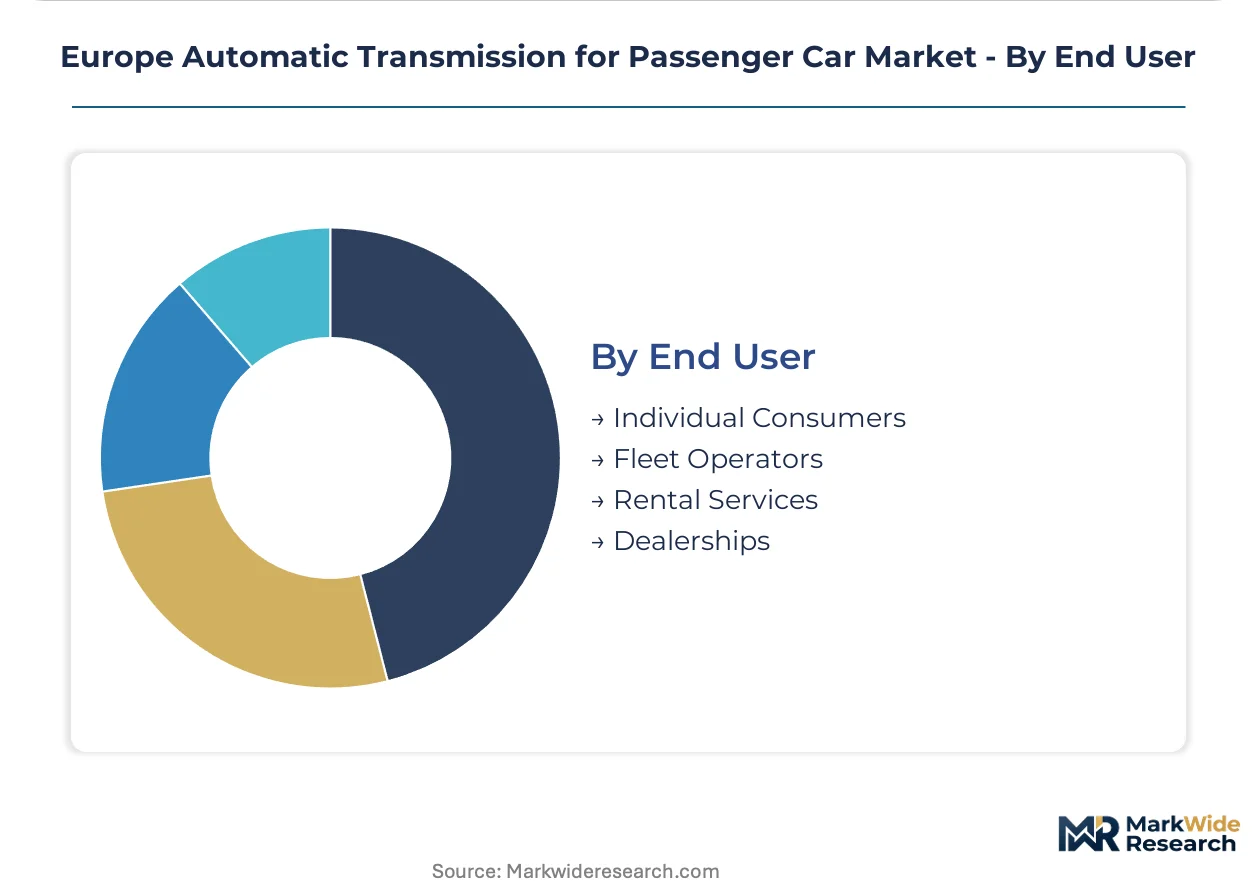
End User:
Procurement contracting structures diverge sharply between retail channels and fleet-managed volume, with rental operators unbundling maintenance into outcome-based service agreements.
- Individual Consumers:Retail purchases prioritize shift quality refinement and brand heritage associations. Southern European markets exhibit stronger preference for dual-clutch engagement characteristics.
- Fleet Operators:Multi-vehicle procurement contracts specify standardized transmission architectures for maintenance simplification. German and French corporate fleets face binding EU Green Deal CO2 reduction mandates accelerating automated transmission adoption.
- Rental Services:Powertrain-as-a-service agreements shift supplier relationships toward performance guarantees. Spanish and Portuguese operators consolidate buying power through multi-brand fleet managers.
- Dealerships:Inventory financing structures influence specification mix toward faster-turning mid-range configurations. Network distribution concentration varies across national aftermarket service capabilities.
Fleet operators drive standardization pressure. Rental services are gaining share fastest through servitization restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European automatic transmission engineering, with the Neckar Valley corridor housing ZF Friedrichshafen headquarters and multiple Tier-1 mechatronics facilities serving German OEM networks.
Germany
Baden-Württemberg and Bavaria concentrate dual-clutch manufacturing for premium sedan exports. KBA type-approval protocols enforce extended validation cycles for electrified transmission variants. The Stuttgart-Munich industrial axis drives procurement standardization across Volkswagen, BMW, and Mercedes-Benz powertrain programs.
France
Paris-based fleet operators accelerate automated manual adoption under EU Green Deal CO2 reduction mandates. ANSM chemical oversight intersects with REACH Annex XVII friction material compliance for transmission fluid formulations. The Hauts-de-France manufacturing belt sustains continuously variable transmission assembly for economy hatchback platforms.
Italy
Turin and Modena engineering centers specialize in high-torque dual-clutch architectures for performance applications. ECHA restrictions on perfluorinated compounds force clutch facing reformulation at Emilia-Romagna compounders. The Bologna-Modena corridor supplies reinforced clutch packs to Southern European SUV assembly plants.
Spain
Barcelona rental fleet operators consolidate powertrain-as-a-service agreements for automated transmission maintenance. CNIL data governance frameworks extend to telematics-enabled predictive shift systems in commercial vehicle channels. The Martorell manufacturing complex integrates mechatronics modules for export-oriented compact SUV production.
Poland
Underpenetrated transmission module sourcing creates white space for localized clutch pack manufacturing serving German OEM networks. EU F-Gas Regulation thermal management compliance shapes hybrid powertrain integration timelines at emerging assembly corridors. The Silesian and Greater Poland voivodeships attract Tier-2 supplier relocation from higher-cost Western European jurisdictions.
Europe Automatic Transmission for Passenger Car Market Vendor Landscape
Premium-margin players sit above commodity-margin players across mechatronics integration depth and software-defined control capability. The supplier base concentrates around integrated system architects, precision component specialists, and regional assembly service providers. Three archetypes dominate: full-system integrators owning planetary gearset-to-software stacks; modular clutch pack fabricators supplying multiple OEM programs; and emerging software-centric entrants licensing predictive shift algorithms. Consolidation pressure intensifies through strategic partnerships bridging electrification competency gaps and capacity expansion into Central European manufacturing corridors.
Within the full-system integrator tier, ZF Friedrichshafen and Continental exemplify divergent strategic positioning. ZF anchors integrated mechatronics portfolios spanning torque converter through dual-clutch architectures. Continental occupies a software-defined transmission control position emphasizing hybrid powertrain optimization. Schaeffler represents the precision component archetype through clutch module manufacturing serving dispersed European assembly networks.
| Leading Market Players |
|---|
| Allison Transmission |
| Schaeffler |
| ZF Friedrichshafen |
| Magna Powertrain |
| Continental |
| Aisin Seiki |
| BorgWarner |
| GKN Automotive |
| Voith |
| Others |
Supply Flow & Price Mechanics
German premium OEM procurement concentration anchors value-based pricing models that tie transmission module costs to CO2 compliance outcomes and fleet efficiency guarantees. Fleet operators across France and Spain negotiate powertrain-as-a-service agreements that unbundle hardware acquisition from performance-based maintenance pricing.
Pricing Analysis
Value-based pricing anchored to CO2 fleet compliance outcomes dominates procurement contracts for electrified transmission architectures. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by thermal management complexity and software-defined control depth. Cost compression in economy hatchback segments is intensifying because REACH Annex XVII fluid reformulation expenses cannot be passed through to price-sensitive buyers. Fleet operators exhibit lowest price sensitivity due to binding EU Green Deal mandates, while individual retail consumers in Southern European markets prioritize shift quality over cost minimization.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Volkswagen, BMW, and Mercedes-Benz powertrain programs across German assembly networks. Supply concentration in Germany, Italy, and Poland feeds from specialized friction material compounders and precision mechatronics fabricators. High-performance clutch facings and electro-hydraulic actuator modules constitute critical input dependencies. Single-source vulnerability in REACH-compliant transmission fluid formulations creates exposure to regulatory-driven supply interruptions. Distribution runs through consolidated Tier-1 integrators serving multiple OEM platforms from centralized Baden-Württemberg and Bavaria hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized friction material capacity constraints prop pricing power for compounders serving hybrid powertrain integration programs. Limited European sourcing of REACH-compliant clutch facings sustains margin premiums across transmission architecture tiers.
For Market Incumbents: Deploy backward integration into precision actuator manufacturing to capture calibration expertise scarce across European technician training pipelines. Consolidate clutch pack fabrication capacity in Polish and Czech corridors to deflect margin pressure from Western European labor costs. Battery-electric platform substitution threatens multi-speed transmission volumes, necessitating accelerated electrified hybrid architecture development. For New Entrants and Emerging Players: Cloud-based predictive shift algorithm licensing offers low-capital entry into software-defined transmission control segments. Polish assembly corridors present underpenetrated white space for localized clutch module manufacturing serving German OEM networks. Fleet electrification transitions in France and Spain create procurement entry points through powertrain-as-a-service contracting models. For Investors and Strategic Acquirers: The window for entry favors precision mechatronics specialists with EU AI Act compliance documentation capabilities. Long-term viability hinges on electrified powertrain integration competency rather than legacy torque converter architectures. Monitor EMA protocol certification timeline extensions as inflection indicators for platform launch delays affecting supplier revenue recognition.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces clutch pack SKU complexity for ZF Friedrichshafen and Continental across German OEM networks. |
| Battery Supply Agreement | Secures thermal-fluid module integration capacity for hybrid powertrain programs at Stuttgart engineering centers. |
| Software-Defined Vehicle Investment | Enables predictive shift algorithm deployment under EU AI Act liability frameworks for rental fleet channels. |
| Geographic Manufacturing Footprint | Relocates clutch fabrication to Silesian voivodeships serving Czech and Polish assembly corridors. |
| Charging Infrastructure Partnership | Aligns transmission electrification roadmaps with battery-electric platform substitution timelines. |
Methodological Framework
Independent corroboration across OEM platform engineering directors, Tier-1 supplier procurement leads, and fleet operator maintenance managers underwrites the qualitative findings. Secondary validation draws from KBA type-approval databases, ECHA REACH registration dossiers, and EU F-Gas Regulation compliance filings. Bottom-up volume modeling triangulates against top-down OEM production schedule aggregation.
Comparable-period anchoring to historical EMA protocol certification cycles establishes baseline assumptions across the analysis window. Segmentation dimensions span transmission architecture type, vehicle class, electrification readiness tier, and regional manufacturing cluster. CAGRs derive from unit shipment trajectories weighted by content-per-vehicle value differentials. Shift-map recalibration timelines and thermal management module penetration curves constitute industry-specific forecast inputs.
The model holds under stable REACH chemical restriction enforcement; deviation in EU AI Act delegated act timing would shift liability framework adoption curves. Forecasts reflect assumptions regarding EMA protocol stringency and fleet CO2 target compliance pathways. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Asia Pacific Automotive Engine Market
Powertrain
Engine Support Bar Market
Powertrain
Modular Belt Drive Market
Powertrain
Automotive Timing Chain and Belt Market
Powertrain
Turbocharger Actuators Market
Powertrain
North America Precision Gearbox Market
Powertrain
Transmission Oil Filters Market
Powertrain
Clutch Hub Puller Market
Powertrain
Powertrain Domain Control Unit Platforms Market
Powertrain
Global Hydrogen Combustion Engine Market
Powertrain
Automotive Dual Mass Flywheel Market
Powertrain
Small Gas Engine Market
Powertrain
Transmission Sales Market
Powertrain
Drive Shaft Market
Powertrain
Automotive Fuel Feed Pumps Market
Powertrain
Automotive Fan Clutch Market