
 High Speed Rolling Bearings Market | 2026-2036
High Speed Rolling Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
High Speed Rolling Bearings Market Insights
The capital-intensity divergence between integrated steel-forging operations and outsourced ceramic-hybrid specialists is unwinding competitive stability across the bearing supply base. SKF leverages captive metallurgy and testing infrastructure to sustain premium positioning in aerospace-qualified product lines. Schaeffler anchors European machine tool demand through its application engineering centers in Germany. NSK dominates Asian electric motor supply with localized production and JIS-certified quality systems.
High speed rolling bearings are precision-engineered antifriction devices designed to sustain rotational velocities exceeding standard catalog ratings, typically incorporating optimized cage geometries, controlled clearance tolerances, and advanced lubrication regimes to manage centrifugal loading and thermal expansion. These components enable power density improvements in spindles, turbomachinery, and traction systems where operating speeds surpass conventional bearing thresholds. Ball bearings occupy the largest volume share across machine tool spindles and electric motor shafts, while ceramic hybrid technology captures expanding margin pools in aerospace equipment where weight reduction and thermal stability command specification premiums. Cylindrical roller bearings retain mature positioning in heavy-duty textile machinery where load capacity outweighs speed requirements.
ISO 492 and ABMA standards govern dimensional precision and running accuracy for high speed bearing classifications, while EASA and FAA certification protocols shape product qualification pathways for aerospace tier-one suppliers. REACH and RoHS frameworks restrict substance compositions in bearing steels, coatings, and lubricant formulations, compelling reformulation investments across European manufacturing footprints. Stakeholders must monitor evolving EU AI Act requirements for predictive maintenance algorithms integrated into smart bearing systems, as regulatory scope expands from hardware to embedded diagnostic software.
Market Dynamics
The divergence between captive steel-forging operations and outsourced ceramic-hybrid specialists is fragmenting competitive stability across bearing supply chains, as aerospace OEMs demand thermal stability while machine tool builders prioritize cost control.
Growth Catalysts
- EU Green Deal compliance:Tightening F-Gas Regulation on bearing lubricants and seal technologies is forcing reformulation investments that favor advanced ceramic materials with lower thermal expansion coefficients.
- Electric motor shaft applications:Power density improvements in traction systems are pulling demand for optimized cage geometries that manage centrifugal loading at elevated rotational velocities.
- German precision engineering clusters:Stuttgart and Munich anchor OEM supply chains for machine tool spindles, creating localized demand concentration that sustains application engineering investments.
Market Restraints
- Specialized alloy input costs:Vacuum-degassed bearing steel and silicon nitride powder prices fluctuate with energy-intensive production cycles, compressing margins for mid-tier suppliers lacking long-term supply agreements.
- Japanese ceramic powder concentration:High-purity silicon nitride feedstock production clusters in specific Japanese industrial zones, creating geographic single-point-of-failure exposure for hybrid bearing manufacturers.
- REACH substance restrictions:ECHA framework limitations on chromium-based coatings and certain lubricant additives force costly material substitutions without immediate performance equivalents.
Strategic Opportunities
- Indian electric vehicle traction motors:Underpenetrated demand for high-speed bearings in domestic EV manufacturing offers first-mover positioning before localized supply chains mature.
- EU AI Act diagnostic integration:Regulatory scope expansion into embedded predictive maintenance algorithms creates compliance-mandated upgrade cycles for smart bearing systems in aerospace and rail applications.
- Direct OEM technical partnerships:Bypassing traditional distribution channels through application-specific engineering collaborations captures margin pools previously allocated to intermediaries.
Industry Challenges
- Tribology and thermal management expertise:Shortage of engineers capable of optimizing lubrication regimes for ceramic-steel interface dynamics limits product development velocity.
- EASA airworthiness certification timelines:Extended qualification protocols for aerospace-qualified product lines delay revenue recognition and tie up testing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Speed Rolling Bearings Market |
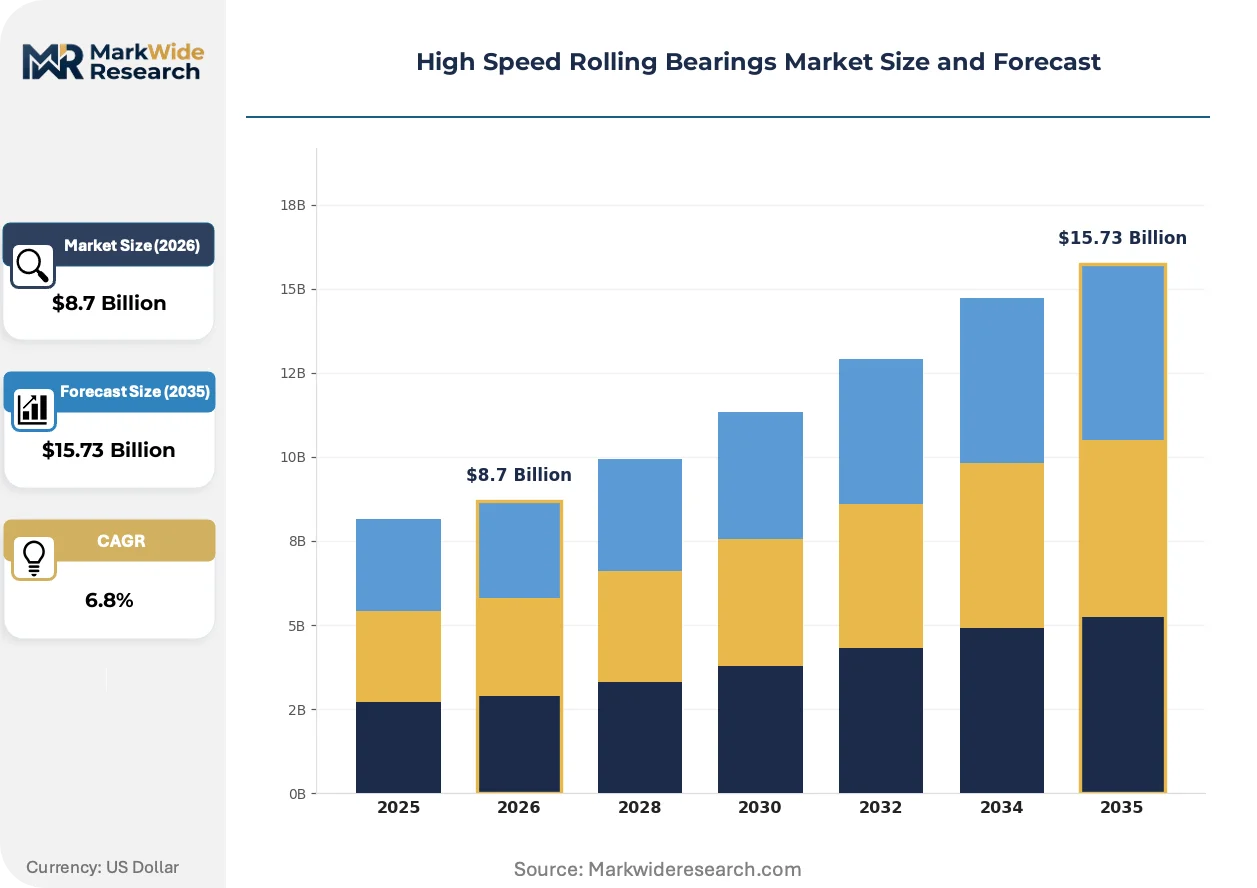
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Bearings, Cylindrical Roller Bearings, Thrust Bearings, Needle Roller Bearings Technology: Ceramic Hybrid, Steel, Magnetic, Polymer Application: Machine Tools, Aerospace Equipment, Electric Motors, Textile Machinery End User: OEMs, Aftermarket Suppliers, Distributors, Maintenance Services |
| Companies Covered | SKF, Schaeffler, NSK, NTN, Timken, JTEKT, NACHI-Fujikoshi, C&U Group, RBC Bearings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Speed Rolling Bearings Market Trends and Innovations
Ceramic hybrid architectures are compressing traditional metal-on-metal bearing configurations across multiple end-use verticals, while regulatory frameworks expand from hardware compliance into embedded software governance.
Silicon nitride rolling elements are replacing conventional steel balls in aerospace turbine applications where weight reduction and thermal stability command specification premiums. Turbomachinery OEMs are specifying hybrid configurations for new engine platforms, accelerating procurement velocity for qualified suppliers. This material transition is miniaturizing the performance gap between standard catalog bearings and custom-engineered solutions, eroding premium pricing power for legacy metallurgy specialists.
EU F-Gas Regulation phase-down schedules are eliminating hydrofluorocarbon-based lubricants from bearing systems in European manufacturing footprints. Industrial consequence includes forced reformulation of greases and oils used in high-speed spindles and electric motor shafts. Machine tool builders in Germany are responding by qualifying synthetic ester and polyalkylene glycol alternatives, extending validation cycles but securing long-term market access.
After-sales service unbundling is disrupting traditional bundled maintenance contracts in the machine tool vertical. End-users are separating bearing replacement from spindle rebuild services, sourcing components directly from manufacturers rather than through OEM service departments. This pattern is most visible in German and Japanese precision engineering clusters, where technical buyer sophistication supports direct specification.
High Speed Rolling Bearings Market Segmentation
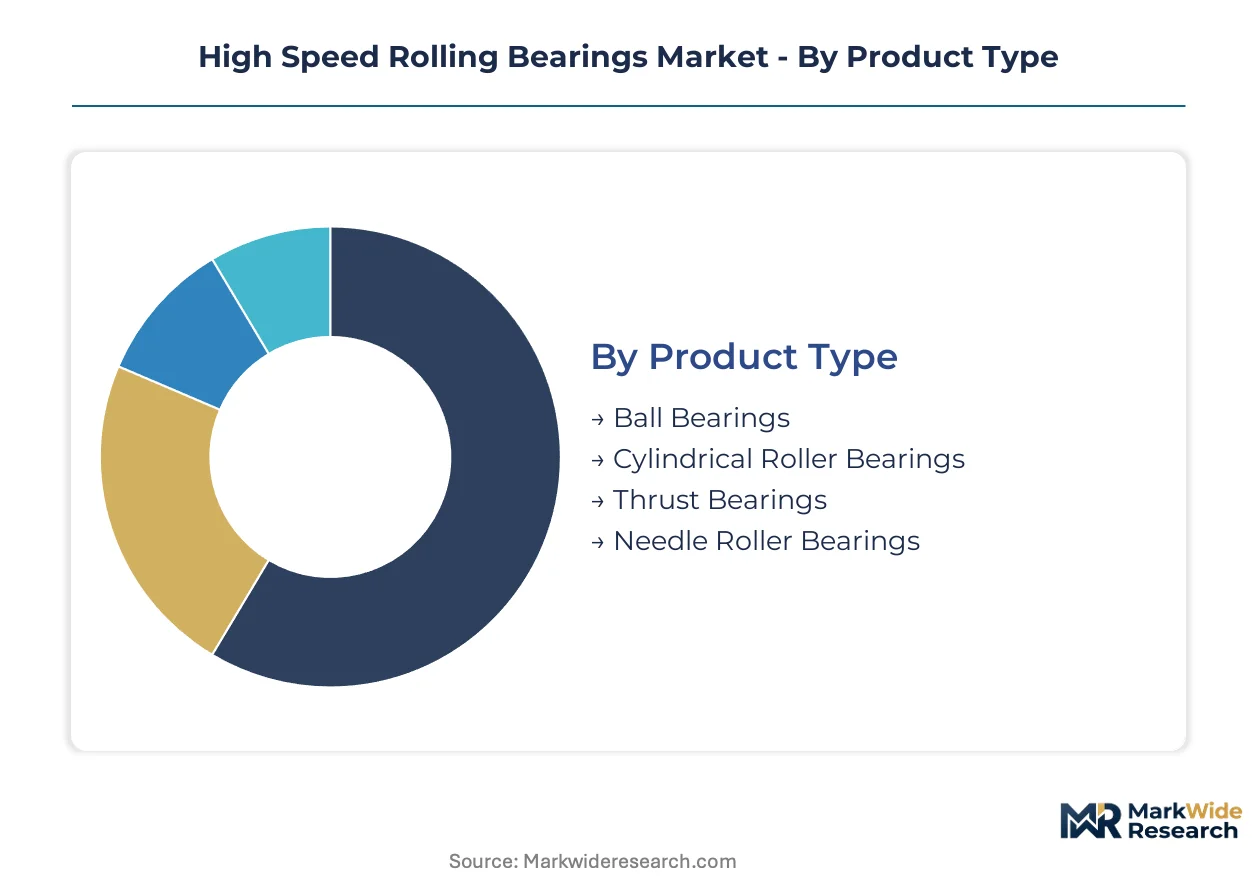
High speed rolling bearings serve divergent performance requirements across industrial verticals, with specification standards varying sharply between aerospace qualification protocols and machine tool cost optimization. Channel dynamics differ materially by segment, with OEM direct procurement dominating certified aerospace lines while distributor networks handle standard catalog products for maintenance services.
Product Type:
Ball bearings and cylindrical roller variants flow primarily through OEM direct channels for original equipment fitment, while thrust and needle configurations see heavier aftermarket distribution for maintenance replacement cycles.
- Ball Bearings:Precision-engineered antifriction devices with optimized cage geometries sustain rotational velocities exceeding standard catalog ratings in electric motor shafts and machine tool spindles. Demand concentrates in German precision engineering clusters around Stuttgart and Munich, where power density improvements in traction systems pull specification upgrades.
- Cylindrical Roller Bearings:Heavy-duty configurations retain mature positioning in textile machinery where load capacity outweighs absolute speed requirements, utilizing controlled clearance tolerances for thermal expansion management. Japanese industrial zones anchor production for high-purity silicon nitride integration into hybrid variants.
- Thrust Bearings:Axial load specialists serve turbomachinery applications with specialized alloy requirements subject to REACH substance restrictions on chromium-based coatings.
- Needle Roller Bearings:Compact radial designs fit space-constrained aerospace actuator systems where EASA airworthiness certification timelines govern supplier qualification.
By volume, ball bearings lead across electric motor and machine tool applications. By growth pace, cylindrical roller hybrids with ceramic elements are climbing the fastest on aerospace procurement expansion.
Technology:
Cost tiers separate these segments sharply, with ceramic hybrid commanding specification premiums against steel commoditization while magnetic and polymer alternatives occupy emerging technology niches.
- Ceramic Hybrid:Silicon nitride rolling elements replace conventional steel balls in aerospace turbine applications where weight reduction and thermal stability command specification premiums. Turbomachinery OEMs specify hybrid configurations for new engine platforms, accelerating procurement velocity for qualified suppliers.
- Steel:Vacuum-degassed bearing steel remains the volume backbone for machine tool spindles and standard electric motor shafts, though margin compression from energy-intensive production cycles challenges mid-tier suppliers lacking long-term supply agreements.
- Magnetic:Contactless rotation systems eliminate lubrication regimes entirely, positioning for EU F-Gas Regulation compliance as hydrofluorocarbon-based lubricants face phase-down schedules.
- Polymer:Lightweight alternatives target specific textile machinery applications where corrosion resistance outweighs load-bearing requirements.
Steel retains the largest volume share across catalog products. Ceramic hybrid captures the steepest expansion trajectory on aerospace OEM thermal stability requirements.
Application:
Customer sophistication varies by vertical, with aerospace and machine tool buyers demanding application engineering collaboration while electric motor and textile purchasers prioritize catalog availability.
- Machine Tools:High-speed spindles require optimized cage geometries managing centrifugal loading, with German builders qualifying synthetic ester lubricant alternatives under EU F-Gas Regulation reformulation pressures.
- Aerospace Equipment:Turbine applications demand EASA and FAA certification protocols, extending qualification timelines that delay revenue recognition for suppliers.
- Electric Motors:Traction system power density improvements pull demand for bearings sustaining elevated rotational velocities, with Indian EV manufacturing offering underpenetrated positioning.
- Textile Machinery:Load-capacity-priority applications retain mature cylindrical roller configurations with less technology disruption than speed-critical verticals.
Machine tools generate the highest absolute volume. Aerospace equipment shows the fastest specification upgrade cycle on ceramic hybrid adoption.
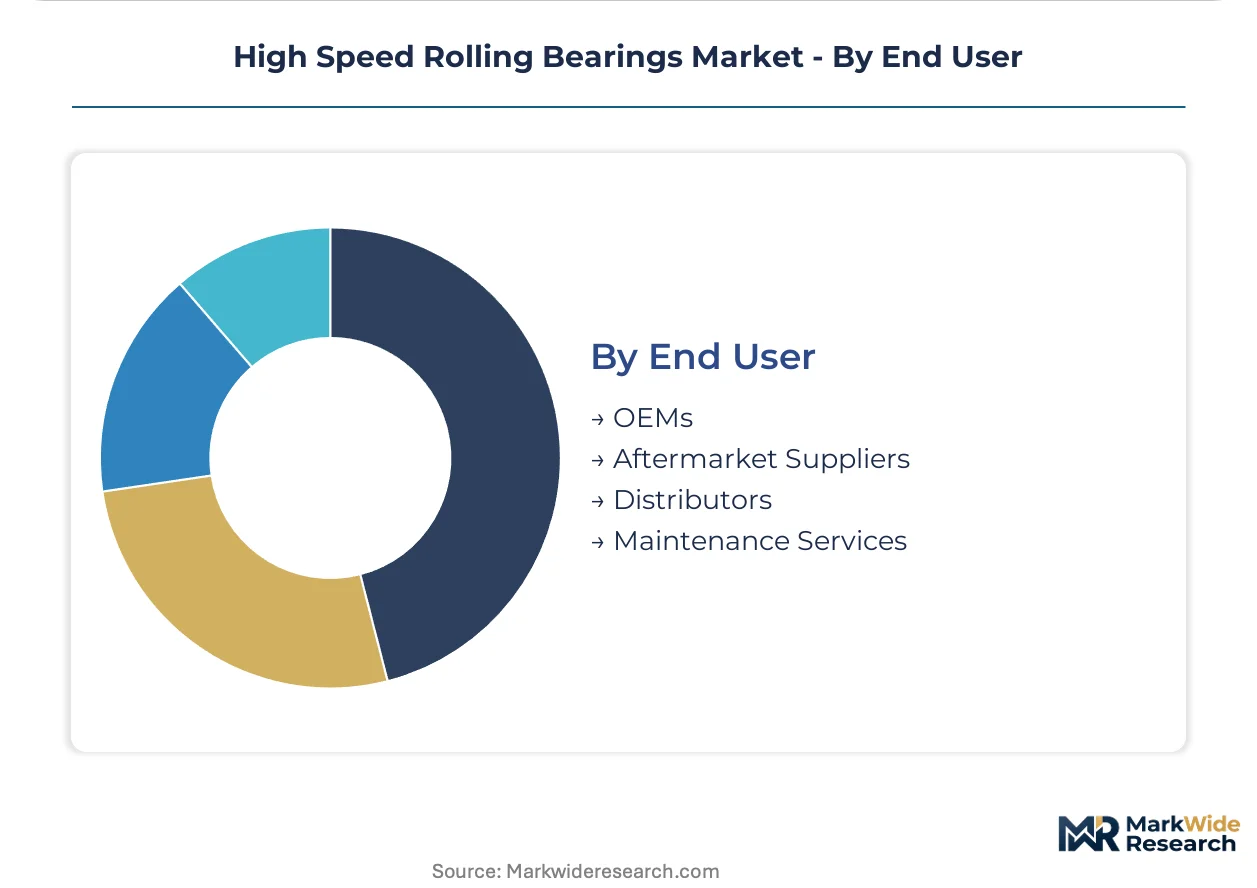
End User:
Margin structures diverge by channel, with OEM direct relationships capturing engineering collaboration premiums while aftermarket and distributor channels compete on availability and technical support.
- OEMs:Original equipment manufacturers specify bearings during platform design, locking in multi-year supply agreements with qualified suppliers meeting ISO 492 and ABMA standards.
- Aftermarket Suppliers:Replacement component specialists benefit from after-sales service unbundling trends, with end-users separating bearing replacement from spindle rebuild services.
- Distributors:Inventory-heavy intermediaries face margin pressure as technical buyers in German and Japanese clusters source directly from manufacturers.
- Maintenance Services:Bundled service providers compete against unbundled component sourcing, requiring predictive maintenance algorithm integration under EU AI Act diagnostic requirements.
OEMs dominate value capture through design-in relationships. Aftermarket suppliers are gaining share fastest on maintenance unbundling trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes ceramic hybrid bearings for aerospace turbine applications at specification premiums, while India sources steel configurations for cost-sensitive electric motor traction systems. This consumption-mix differential separates thermal-stability-driven procurement from power-density-optimization priorities.
Germany
Machine tool builders in Stuttgart and Munich anchor OEM supply chains for high-speed spindles requiring optimized cage geometries. EU F-Gas Regulation phase-down schedules force reformulation of hydrofluorocarbon-based lubricants toward synthetic ester alternatives. Precision engineering clusters sustain application engineering investments through direct technical partnerships with bearing manufacturers.
United States
Aerospace equipment manufacturers expand procurement of ceramic hybrid bearings for turbine applications under FAA certification protocols. EPA and OSHA frameworks govern substance compositions in bearing steels and coatings for industrial machinery. Manufacturing concentration in the Midwest and Southeast supports localized production for electric motor shaft applications.
Japan
High-purity silicon nitride powder production clusters create geographic feedstock concentration for hybrid bearing manufacturers serving electric motor and textile machinery segments. METI industrial standards and JIS certification systems shape quality requirements for export-oriented production. Industrial zones around Nagoya and Osaka anchor ceramic material processing capabilities.
China
Domestic electric vehicle traction motor manufacturing pulls demand for bearings sustaining elevated rotational velocities. MIIT and GB standards govern dimensional precision for high-speed classifications in industrial equipment. Yangtze River Delta manufacturing bases concentrate production for machine tool and textile machinery aftermarket replacement.
India
Underpenetrated demand for high-speed bearings in domestic EV manufacturing offers first-mover positioning before localized supply chains mature. BIS standards and PLI scheme incentives support component localization for electric motor applications. Manufacturing clusters in Maharashtra and Gujarat develop assembly capabilities for traction system suppliers.
High Speed Rolling Bearings Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive metallurgy operations separating premium-positioned suppliers from outsourced ceramic-hybrid competitors. The structure concentrates qualified aerospace supply among vertically integrated players while fragmenting standard catalog production across regional specialists. Three archetypes dominate: integrated steel-forging operators with captive testing infrastructure, ceramic-hybrid specialists dependent on Japanese powder feedstock, and scale-driven catalog manufacturers serving distributor channels. Competitive moves center on direct OEM technical partnerships bypassing traditional distribution, and application engineering center investments in demand-concentrated industrial clusters.
Among integrated European operators, SKF and Schaeffler occupy positions representing the metallurgy-captive archetype with aerospace qualification capabilities. NSK anchors the Asian specialist tier with JIS-certified quality systems for electric motor supply. These three exemplify how geographic proximity to precision engineering clusters in Germany and industrial manufacturing bases in Japan translates into specification influence during platform design phases.
| Leading Market Players |
|---|
| SKF |
| Schaeffler |
| NSK |
| NTN |
| Timken |
| JTEKT |
| NACHI-Fujikoshi |
| C&U Group |
| RBC Bearings |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at vacuum-degassed steel mills in Germany and Japan anchors price floors for standard catalog bearings, while ceramic-hybrid specialists with outsourced silicon nitride feedstock face steeper margin compression during energy-intensive production cycles. Scale economies in captive metallurgy operations enable SKF and Schaeffler to sustain premium positioning against mid-tier competitors lacking long-term alloy supply agreements.
Pricing Analysis
After-sales service revenue from spindle rebuild contracts and predictive maintenance subscriptions now exceeds hardware margins for qualified aerospace suppliers. Three-tier pricing structure across aerospace-certified, machine tool precision, and economy catalog levels separates EASA-qualified products from standard ISO 492 configurations. Pricing pressure stems from after-sales service unbundling in German precision engineering clusters, where end-users source bearings directly from manufacturers. Electric motor OEMs in India exhibit highest price sensitivity, while aerospace turbine manufacturers prioritize thermal stability over unit cost.
Supply Chain Analysis
Inventory lead times for high-purity silicon nitride powder stretch across Japanese industrial zones in Nagoya and Osaka, creating geographic concentration risk for hybrid bearing manufacturers. Supply draws from Germany for vacuum-degassed bearing steel, Japan for ceramic feedstock, and China for machined bearing cages. Single-source vulnerability in Japanese silicon nitride production threatens procurement continuity for aerospace-qualified hybrid configurations. Distribution runs through OEM direct channels for certified aerospace lines and distributor networks for standard catalog maintenance products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high speed rolling bearings market functions as a service-attach opportunity where predictive maintenance algorithm subscriptions and spindle rebuild contracts expand faster than hardware unit sales. Recurring revenue from embedded diagnostic software under EU AI Act compliance mandates now outpaces traditional component replacement cycles.
For Market Incumbents: Shield aerospace qualification capabilities through captive metallurgy investments and EASA-certified testing infrastructure. Consolidate application engineering centers in Stuttgart and Munich to deepen OEM technical partnerships. Counter magnetic bearing substitution threats by accelerating ceramic hybrid thermal stability roadmaps. Prioritize backward integration into vacuum-degassed steel supply to defend margin position against energy-intensive production cost volatility.
For New Entrants and Emerging Players: Lead with Indian electric vehicle traction motor applications as the most penetrable white-space target before localized supply chains mature. Exploit after-sales service unbundling trends to capture direct procurement relationships with machine tool maintenance departments. Establish technical partnerships with Maharashtra and Gujarat manufacturing clusters for assembly capabilities. Target distributor channel disruption through direct specification support for sophisticated buyers in German precision engineering clusters.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors ceramic-hybrid specialists with qualified aerospace supply relationships over commoditized steel catalog manufacturers. Long-term viability hinges on regulatory compliance capabilities spanning REACH substance restrictions and EU AI Act diagnostic requirements. Acquisition targets should demonstrate captive testing infrastructure or Japanese powder feedstock security. Monitor EASA airworthiness certification timeline compression as inflection indicator for revenue recognition acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Application Engineering Center Expansion | Stuttgart and Munich clusters anchor OEM design-in relationships for machine tool spindles. |
| Ceramic Hybrid Qualification Investment | EASA and FAA certification protocols govern aerospace turbine procurement specifications. |
| Predictive Maintenance Algorithm Development | EU AI Act compliance mandates embedded diagnostic software in smart bearing systems. |
| Direct OEM Technical Partnership | Bypassing distributor channels captures margin pools from after-sales service unbundling. |
| Silicon Nitride Feedstock Security | Japanese industrial zone concentration creates geographic single-point-of-failure exposure. |
Research Methodology
A spread of perspectives from maintenance directors at German machine tool OEMs, procurement leads at aerospace tier-one suppliers, ceramic materials specialists in Japanese industrial zones, and aftermarket service heads at distributor channels converged on the working assumptions. Primary fieldwork combined with secondary validation from EASA certification databases, REACH substance restriction filings, MIIT production statistics, and SEC disclosures from listed bearing manufacturers. Bottom-up unit economics triangulated against top-down industrial production indices.
Segmentation dimensions modeled include product type across ball, cylindrical roller, thrust, and needle configurations; technology tier separating ceramic hybrid, steel, magnetic, and polymer alternatives; application vertical spanning machine tools, aerospace equipment, electric motors, and textile machinery; and end-user channel structure across OEM direct, aftermarket, distributor, and maintenance service providers. CAGRs derived from regression analysis against industrial capital expenditure cycles and electric vehicle production trajectories. Forecast inputs incorporated F-Gas Regulation phase-down schedules and EU AI Act implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained aerospace procurement expansion or accelerated Indian EV localization would require recalibration. Forecasts reflect documented assumptions regarding ceramic hybrid adoption curves and regulatory compliance investment cycles. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
North America Automotive AHSS Market
Automotive Parts
Steel Cords for Radial Tyres Market
Automotive Parts
Automotive Oil and Valve Stem Seals Market
Automotive Parts
Automotive Oil Seals Market
Automotive Parts
Europe Automotive Lubricants Market
Automotive Parts
Die Cast Parts for Electric Vehicle Market
Automotive Parts
Global Automotive Plastics Market
Automotive Parts
Automotive Roller Bearing Market
Automotive Parts
Global Automotive Closure Market
Automotive Parts
Electromagnetic Clutch System Market
Automotive Parts
Spain Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Oil and Air Filters Market
Automotive Parts
Turkey Passenger Vehicles Lubricants Market
Automotive Parts
Morocco Automotive Engine Oils Market
Automotive Parts
Automotive Canister Purge Valve Market
Automotive Parts
Global Automotive Auxiliary Brake Market