
 Global Automotive Clutch Pedals Market | 2026-2036
Global Automotive Clutch Pedals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Clutch Pedals Market Analysis
Fleet procurement consolidation among European commercial vehicle assemblers is expanding contract volumes for integrated pedal modules. Continental AG leverages its braking and chassis integration expertise to anchor long-term supply agreements with major OEM platforms. ZF Friedrichshafen AG competes through mechatronic pedal systems that bridge conventional hydraulic feel with electronic signal architecture. Valeo sustains aftermarket channel dominance across Latin America and Southeast Asia through localized distribution partnerships.
Automotive clutch pedals translate driver foot force into clutch plate engagement through mechanical linkage, hydraulic fluid pressure, or electronic sensor output, typically fabricated from stamped steel, aluminum forgings, or polymer-composite hybrids with specified fatigue resistance exceeding one million operational cycles. Electronic pedal variants capture the fastest growth trajectory as torque-sensor integration enables clutch-by-wire architectures in hybrid powertrains. Conventional mechanical pedals retain margin concentration in emerging-market passenger car segments where cost thresholds override electromechanical sophistication. OEM direct supply relationships dominate value capture, while aftermarket providers serve replacement demand concentrated in high-mileage commercial vehicle populations across Africa and Central Asia.
Federal Motor Vehicle Safety Standards administered by NHTSA govern pedal displacement and retention requirements in the United States, while ECE R13-H harmonization across EU member states mandates specific force-displacement characteristics for type-approved clutch controls. China's GB standards and MIIT certification protocols enforce electromagnetic compatibility thresholds for electronic pedal assemblies sold into domestic production. Stakeholders must monitor divergence between UN-ECE regulatory harmonization and national deviations in Brazil and India as these jurisdictions develop independent homologation pathways for electronic actuation systems.
Market Dynamics
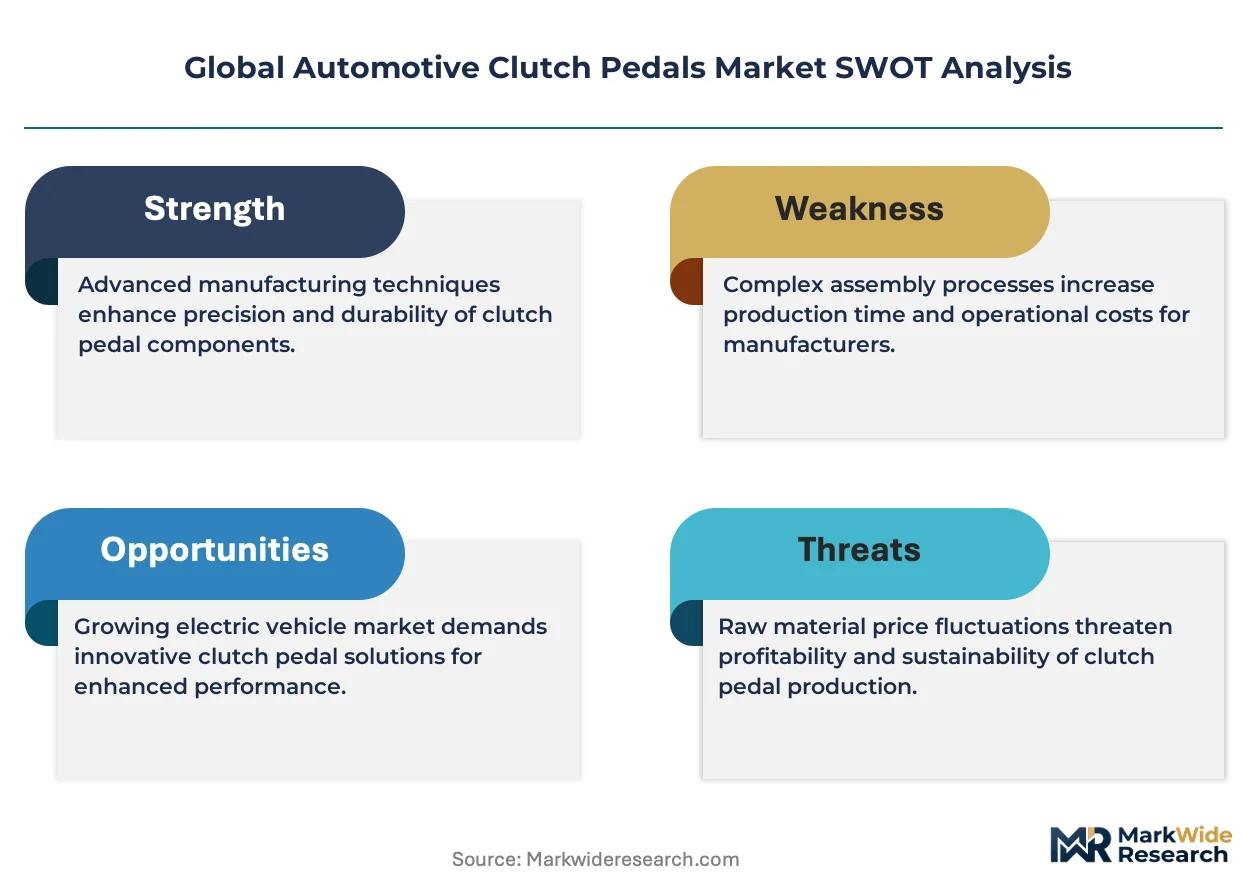
The transition from mechanical linkage to electronic signal architecture is compressing supplier margins while elevating torque-sensor integration requirements across hybrid powertrain platforms. This technological displacement is redrawing competitive boundaries between traditional stamped-metal fabricators and mechatronic system specialists.
Growth Catalysts
- China's Dual Carbon Goals:MIIT efficiency mandates are accelerating aluminum-forging and polymer-composite adoption in pedal assemblies to reduce vehicle mass. Domestic OEMs source lightweight modules from certified tier-1 suppliers.
- Brazilian Fleet Modernization:Light commercial vehicle operators in São Paulo and Minas Gerais are retrofitting electronic clutch pedals to extend transmission life in high-cycle urban delivery applications.
- India's Entry-Level Passenger Car Segment:Cost-optimized mechanical pedals retain production dominance as Maruti Suzuki and Hyundai Motor India prioritize price-point engineering over electromechanical sophistication.
Market Restraints
- Aluminum Input Volatility:LME price fluctuations for 6061-T6 forging-grade aluminum compress margin predictability for stamped-pedal manufacturers in Tier-2 supplier networks.
- Electronic Actuation Certification Fragmentation:Divergence between UN-ECE R13-H harmonization and Brazil's INMETRO homologation pathways forces dual-validation investments for clutch-by-wire architectures.
- Dual-Clutch Transmission Substitution:Automated manual systems in European premium passenger cars eliminate pedal-actuated clutch engagement, eroding addressable volume in Germany and Italy.
Strategic Opportunities
- Aftermarket Channel Digitization:E-commerce platforms in Indonesia and Vietnam are displacing traditional distributor networks for replacement mechanical pedals in high-mileage Toyota and Mitsubishi commercial fleets.
- REACH-Compliant Polymer Hybrids:ECHA substance restrictions on phthalate plasticizers are opening specification windows for bio-based composite pedal substrates in EU-bound production.
- Clutch-by-Wire Convergence:Integration of hall-effect torque sensors with brake-pedal position modules creates bundled sourcing opportunities for hybrid powertrain assemblers in Japan and South Korea.
Industry Challenges
- Mechatronics Talent Scarcity:Shortages of firmware engineers with automotive-grade signal-processing expertise delay electronic pedal development cycles at mid-cap suppliers.
- Legacy Platform Integration Friction:Retrofitting torque-sensor outputs into hydraulic clutch systems requires custom calibration protocols that extend OEM validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Clutch Pedals Market |
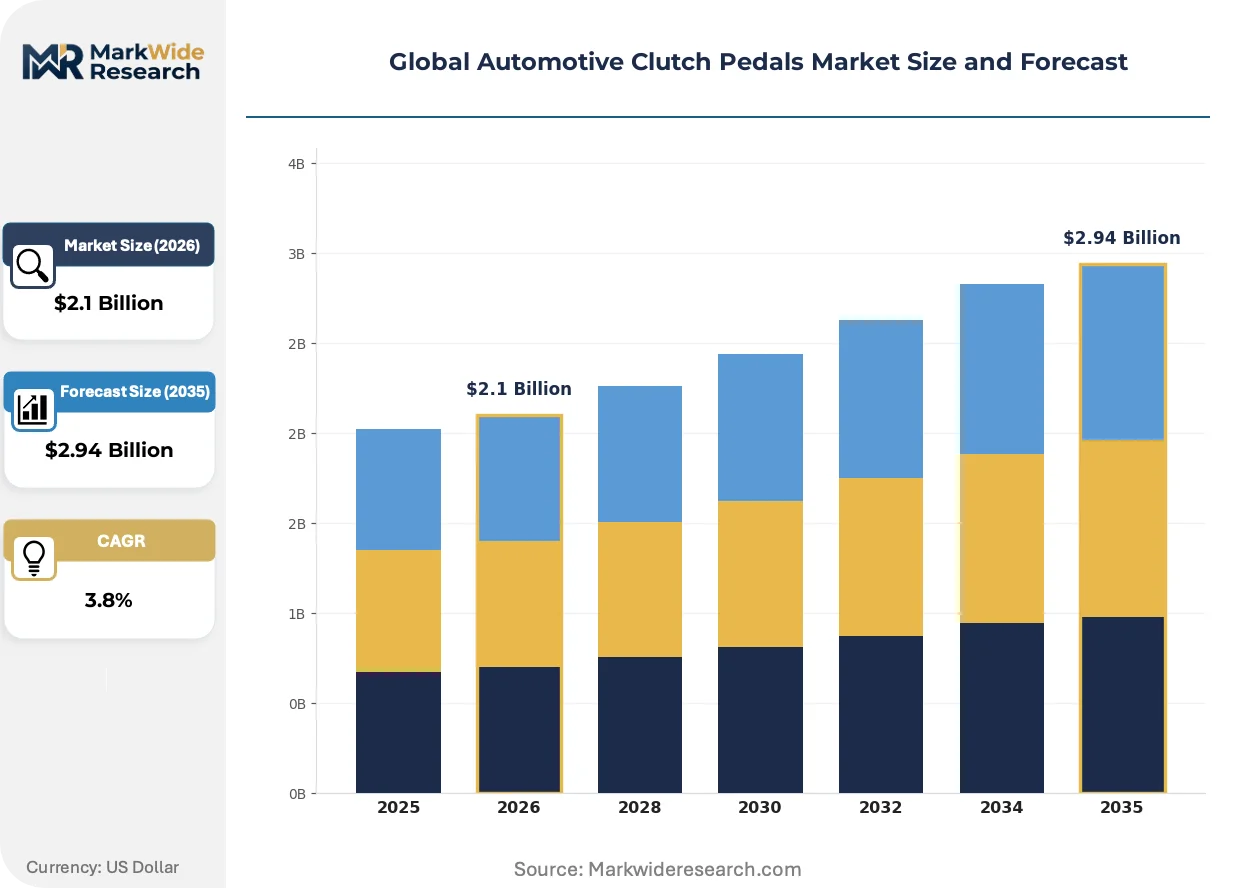
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Electronic, Hydraulic, Pneumatic End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Installation: Manual, Automatic, Semi-Automatic, Integrated Vehicle Type: Passenger Cars, Commercial Vehicles, Light Trucks, Others |
| Companies Covered | Continental AG, DENSO Corporation, F.TECH Inc., KSR International Inc., CTS Corporation, Toyoda Iron Works, ZF Friedrichshafen AG, Valeo, BorgWarner, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Clutch Pedals Market Emerging Trajectories
Material substitution and signal-architecture migration are compressing traditional supply relationships while opening specification windows for hybrid-structure assemblies. These shifts are redrawing competitive boundaries between metal-forming specialists and electronic-system integrators.
Polymer-composite pedal substrates reinforced with glass-fiber or carbon-fiber fillers are consolidating specification share in premium passenger car platforms. BMW and Mercedes-Benz source hybrid-structure assemblies from tier-1 suppliers to meet fleet-average weight reduction targets. This consolidation is marginalizing pure stamped-steel fabricators in German and Austrian supply chains.
REACH substance restrictions administered by ECHA are banning specific phthalate plasticizers in pedal-bushing compounds by 2025. Compounders in Belgium and the Netherlands are reformulating bio-based alternatives to retain automotive qualification status. Electronic pedal variants face additional electromagnetic compatibility testing under ECE R10 that mechanical assemblies bypass.
Fleet procurement teams at European commercial vehicle assemblers are unbundling pedal-module contracts from full chassis sourcing agreements. DAF Trucks and Iveco Group now issue separate RFQs for integrated brake-clutch pedal modules to compress unit costs. This disintermediation is visible most acutely in the Netherlands and Poland where logistics-fleet density concentrates contract volumes.
Global Automotive Clutch Pedals Market Segmentation
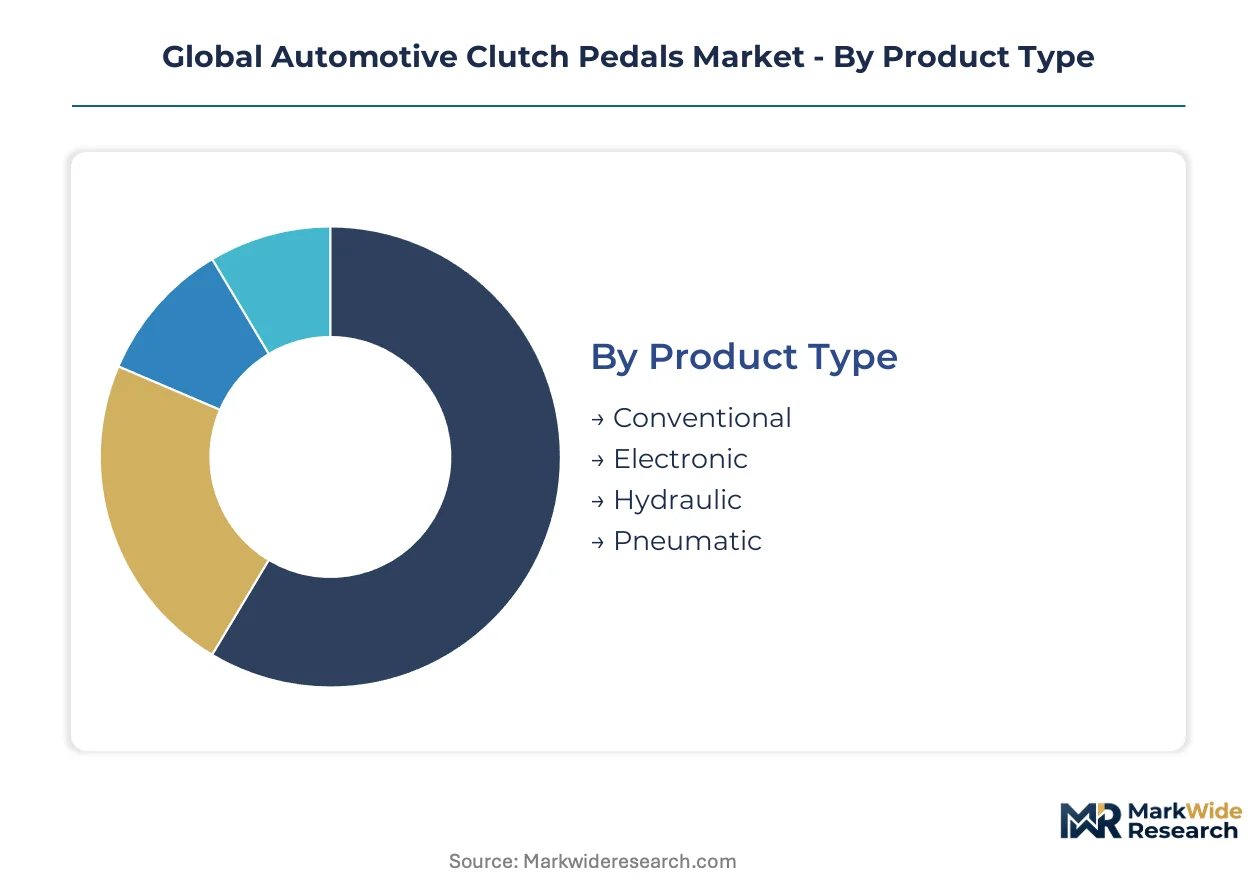
Clutch pedal segmentation reveals divergent capital requirements across mechanical and electronic architectures, with suppliers facing distinct tooling investments for stamped-metal fabrication versus torque-sensor integration. Understanding these structural divides illuminates where margin pools concentrate and which technology pathways demand strategic repositioning.
Product Type:
Electronic variants demand the heaviest upfront capital outlays for sensor calibration equipment and electromagnetic compatibility testing infrastructure, while conventional mechanical pedals rely on mature stamping and forging assets with lower replacement cycles.
- Conventional:Stamped-steel or aluminum-forged assemblies with mechanical linkage to clutch release bearings. Maruti Suzuki and Hyundai Motor India specify these for entry-level passenger cars where cost thresholds override electromechanical sophistication.
- Electronic:Torque-sensor-integrated architectures outputting digital signals to clutch-by-wire actuators. Hybrid powertrain assemblers in Japan and South Korea are consolidating procurement for these modules to enable seamless engine-stop functionality.
- Hydraulic:Fluid-pressure amplification systems reducing pedal effort in heavy commercial applications.
- Pneumatic:Compressed-air actuation reserved for specialty off-highway and agricultural equipment.
Conventional pedals absorb the bulk of installed capacity; electronic variants are expanding most quickly.
End User:
Cost tier stratification separates direct OEM relationships commanding specification authority from aftermarket channels serving replacement demand on price-sensitive terms.
- OEMs:Original equipment manufacturers defining pedal geometry, force-displacement curves, and material specifications for platform-specific integration. BMW and Mercedes-Benz source hybrid-structure assemblies to meet fleet-average weight reduction targets.
- Aftermarket Providers:Independent distributors and e-commerce platforms serving high-mileage vehicle populations. Indonesian and Vietnamese online marketplaces are displacing traditional distributor networks for replacement mechanical pedals in Toyota and Mitsubishi commercial fleets.
- Vehicle Assemblers:Final-stage manufacturers integrating pedal modules with powertrain and chassis systems.
- Tier-1 Suppliers:System integrators managing sub-tier fabrication and delivering completed modules to OEM assembly lines.
OEM direct supply relationships concentrate value capture; aftermarket channels are climbing the fastest as fleet digitization accelerates.
Installation:
Application complexity escalates from discrete pedal replacement to integrated module architectures requiring synchronized brake-clutch positioning.
- Manual:Standalone pedal assemblies with discrete mechanical or electronic actuation. Brazilian light commercial fleet operators in São Paulo retrofit these to extend transmission life in high-cycle urban delivery applications.
- Automatic:Pedal-less configurations in dual-clutch and continuously variable transmissions eliminating driver-actuated clutch engagement.
- Semi-Automatic:Automated manual transmissions retaining pedal presence with electronic shift assistance.
- Integrated:Combined brake-clutch pedal modules with shared mounting structures and unified electronic control units. DAF Trucks and Iveco Group now issue separate RFQs for these to compress unit costs.
Manual installations retain the largest installed base; integrated modules are gaining share fastest as fleet procurement consolidates.
Vehicle Type:
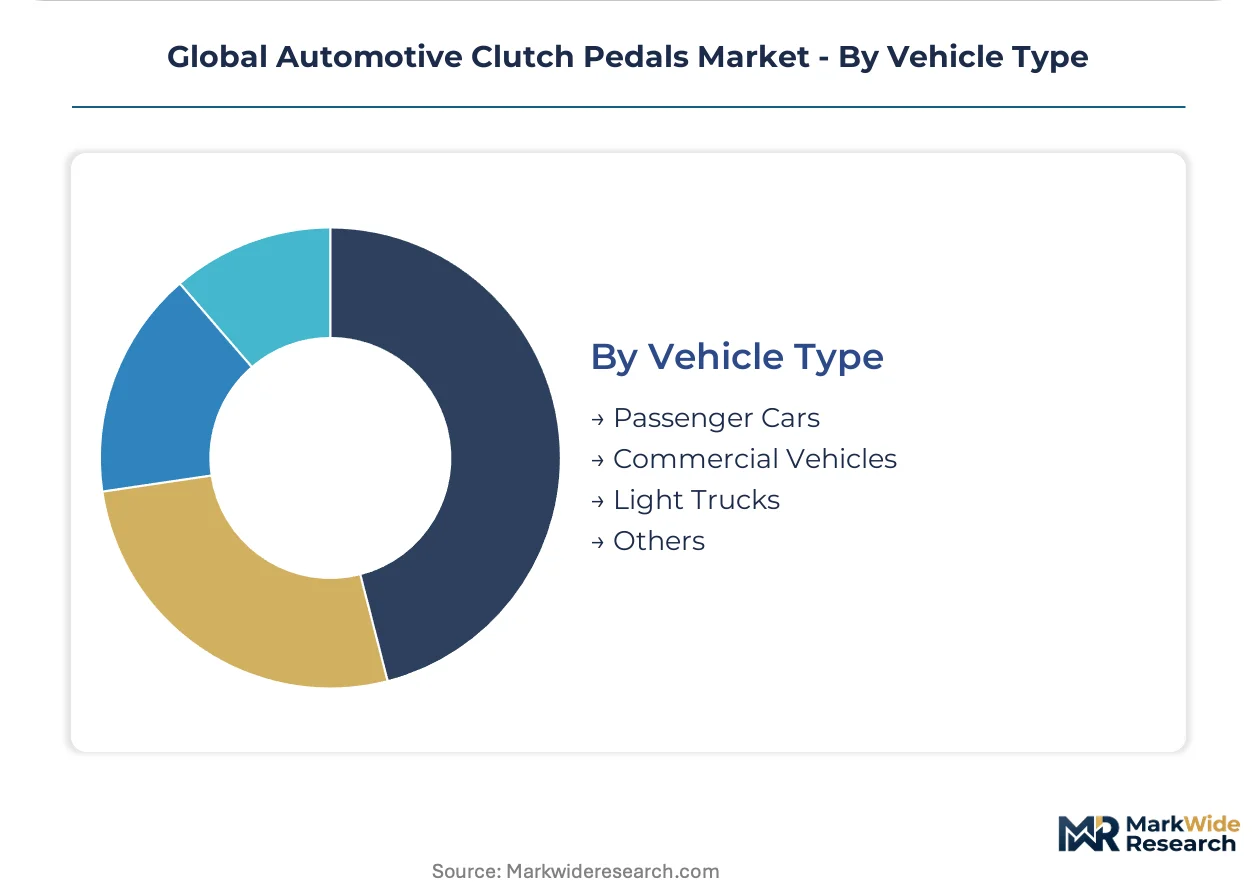
Volume concentration versus margin structure separates high-unit passenger car production from specialized commercial vehicle requirements.
- Passenger Cars:Individual-owner vehicles spanning economy through premium segments. China's domestic OEMs source lightweight aluminum-forging and polymer-composite pedals from certified tier-1 suppliers to satisfy MIIT efficiency mandates.
- Commercial Vehicles:Fleet-operated trucks and buses with durability specifications exceeding one million operational cycles. High-mileage populations across Africa and Central Asia drive replacement demand concentration.
- Light Trucks:Mixed-use vehicles bridging passenger comfort expectations with commercial duty cycles.
- Others:Specialty and off-highway equipment with customized actuation requirements.
Passenger cars dominate unit volume; commercial vehicles command the steepest expansion trajectory as fleet modernization accelerates in emerging economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the heaviest procurement volumes for lightweight pedal assemblies as domestic OEMs pursue MIIT efficiency mandates. Germany and Japan anchor electronic architecture development for hybrid powertrain integration. Brazil and India sustain mechanical pedal dominance through cost-optimized entry-level vehicle production.
China
Domestic OEMs source aluminum-forging and polymer-composite pedal modules from certified tier-1 suppliers to satisfy MIIT vehicle efficiency mandates. GB standards and electromagnetic compatibility protocols enforced by the ministry govern electronic pedal assemblies sold into domestic production. The Yangtze River Delta manufacturing cluster around Shanghai concentrates lightweighting R&D and supplier qualification activity.
Germany
BMW and Mercedes-Benz specify hybrid-structure pedal assemblies to meet fleet-average weight reduction targets under EU Green Deal implementation. ECE R13-H harmonization mandates specific force-displacement characteristics for type-approved clutch controls across EU member states. The Baden-Württemberg automotive corridor anchors integrated brake-clutch module development for commercial vehicle platforms.
Japan
Hybrid powertrain assemblers consolidate procurement for torque-sensor-integrated pedals enabling seamless engine-stop functionality. METI efficiency regulations and JIS standards govern material specifications and signal-architecture reliability thresholds. The Nagoya-Toyota industrial zone concentrates clutch-by-wire convergence with brake-pedal position module bundling.
Brazil
Light commercial vehicle operators in São Paulo and Minas Gerais retrofit electronic clutch pedals to extend transmission life in high-cycle urban delivery applications. INMETRO homologation pathways for electronic actuation systems diverge from UN-ECE R13-H harmonization, forcing dual-validation investments. The São Paulo metropolitan area anchors fleet procurement consolidation among logistics operators.
India
Maruti Suzuki and Hyundai Motor India prioritize cost-optimized mechanical pedals for entry-level passenger cars where price-point engineering overrides electromechanical sophistication. BIS certification and DGFT import regulations shape supplier qualification for domestic assembly. The Tamil Nadu automotive corridor around Chennai concentrates stamped-steel pedal fabrication for compact vehicle platforms.
Global Automotive Clutch Pedals Market Vendor Landscape
German producers anchor the integrated systems tier; Japanese specialists hold torque-sensor integration expertise. The supplier base stratifies across three tiers: multinational tier-1 system integrators, regional metal-forming fabricators, and emerging mechatronic specialists. Two strategic archetypes dominate: braking-and-chassis integration generalists competing through bundled module supply, and signal-processing specialists capturing electronic architecture transitions. Competitive moves concentrate on long-term OEM platform anchoring and backward integration into sensor calibration capabilities.
Among German-based diversified suppliers, Continental AG and ZF Friedrichshafen AG occupy positions spanning braking, chassis, and pedal module integration. Valeo represents the aftermarket channel archetype with established distribution networks across emerging economies. These three companies exemplify how competitive positioning diverges between OEM direct-supply consolidation and aftermarket geographic coverage strategies.
| Leading Market Players |
|---|
| Continental AG |
| DENSO Corporation |
| F.TECH Inc. |
| KSR International Inc. |
| CTS Corporation |
| Toyoda Iron Works |
| ZF Friedrichshafen AG |
| Valeo |
| BorgWarner |
| Others |
Supply Flow & Price Mechanics
LME 6061-T6 forging-grade aluminum price volatility cascades through Tier-2 supplier networks, compressing margin predictability for stamped-pedal fabricators and forcing cost absorption or pass-through trade-offs to OEM procurement teams.
Pricing Analysis
High-volume conventional mechanical pedals trade on razor-thin unit economics while electronic variants with torque-sensor integration capture wider spreads. Price differentiation rests on certification tier—ECE R13-H homologation commands premiums over non-type-approved alternatives—and volume scale with fleet procurement consolidation. Cost compression in entry-level passenger car segments intensifies as Maruti Suzuki and Hyundai Motor India squeeze mechanical pedal suppliers. Aftermarket channels serving high-mileage commercial fleets exhibit the steepest price sensitivity; hybrid powertrain OEMs demonstrate the least.
Supply Chain Analysis
Workforce availability for firmware engineers with automotive-grade signal-processing expertise constrains electronic pedal development cycles in Germany and Japan, even as stamping and forging talent remains abundant in India and Brazil. Supply concentrates in China for aluminum-forging and polymer-composite modules, Germany for integrated brake-clutch architectures, and Japan for torque-sensor integration. Raw material dependencies draw from LME-grade aluminum, glass-fiber and carbon-fiber fillers, and hall-effect sensor components. Single-source vulnerability in torque-sensor calibration equipment creates chokepoint exposure. Distribution runs through OEM direct-supply relationships for value capture and e-commerce platforms for aftermarket replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as electronic architecture migration and certification fragmentation force capital-constrained stamped-metal fabricators toward exit or acquisition, concentrating share among mechatronic system specialists with sensor calibration capabilities.
For Market Incumbents: Lock in long-term platform anchoring with BMW, Mercedes-Benz, and Toyota through bundled brake-clutch module supply agreements that exploit braking-and-chassis integration expertise. Deepen backward integration into hall-effect torque sensor calibration to capture clutch-by-wire specification windows and defend against emerging mechatronic specialists. Prioritize REACH-compliant polymer hybrid R&D to retain EU qualification status as ECHA phthalate restrictions tighten.
For New Entrants and Emerging Players: Aftermarket e-commerce platforms in Indonesia and Vietnam offer the most penetrable entry vector, displacing traditional distributor networks for replacement mechanical pedals in high-mileage Toyota and Mitsubishi commercial fleets. Target Brazil's INMETRO homologation divergence as a regulatory arbitrage opportunity—dual-validation capabilities for electronic actuation systems command premium positioning. Pursue white-label supply relationships with regional metal-forming fabricators lacking electronic architecture expertise.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap stamped-metal fabricators in India's Tamil Nadu corridor and Brazil's São Paulo metropolitan area, where aluminum input volatility and OEM pricing pressure create acquisition windows below replacement cost. Long-term viability favors targets with latent torque-sensor integration capabilities or established tier-1 supplier relationships with Maruti Suzuki and Hyundai Motor India. Watch for INMETRO-UN-ECE regulatory convergence as the inflection signal—harmonization would eliminate dual-validation moats and revalue electronic pedal specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | BMW and Mercedes-Benz consolidate hybrid-structure pedal sourcing to meet EU Green Deal fleet weight targets. |
| Backward Integration into Sensor Calibration | Torque-sensor calibration captive supply secures clutch-by-wire specification wins with Toyota and Hyundai. |
| Geographic Manufacturing Footprint | Yangtze River Delta and Tamil Nadu corridor positioning captures MIIT and BIS compliance proximity advantages. |
| Long-term Supply Agreement | DAF Trucks and Iveco Group unbundle integrated brake-clutch modules from chassis contracts to compress unit costs. |
| Sustainability Repositioning | REACH-compliant bio-based polymer hybrids replace phthalate plasticizers to retain ECHA automotive qualification status. |
Methodological Framework
Trade flow databases, vehicle production registries, and regulatory filing repositories formed the secondary backbone, cross-referenced with primary interviews encompassing Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors in Indonesia and Vietnam, and firmware development leads at mechatronic specialists. Bottom-up and top-down triangulation reconciled unit shipment estimates with aluminum-forging and polymer-composite consumption patterns across certified supplier networks.
Bottom-up modeling aggregated platform-specific content-per-vehicle assumptions across passenger car, commercial vehicle, and light truck segments, while top-down verification anchored aggregate market value to MIIT efficiency mandate compliance spending and fleet procurement contract disclosures. Segmentation dimensions spanned product architecture, end-user channel, installation type, and vehicle class. CAGRs derived from regression analysis of historical material substitution rates and electronic adoption curves in hybrid powertrain platforms.
Caveats apply where LME aluminum volatility, INMETRO-ECE regulatory divergence resolution, or dual-clutch transmission penetration could materially shift the outlook. Forecasts embed assumptions regarding manual transmission retention rates in emerging economies and electronic pedal certification timeline harmonization. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Asia Pacific Electrically Powered Hydraulic Steering Market
Powertrain
Automotive Engine Air Filter Market
Powertrain
Europe Internal Combustion Engines Market
Powertrain
Power Assisted Steering Market
Powertrain
Brazil Automotive Market
Powertrain
Yaw Damper Market
Powertrain
Automotive Turbocharger Market
Powertrain
Automotive Carburetor Market
Powertrain
Engine Rocker Arm Market
Powertrain
Emission Control Catalyst for Small Engines Market
Powertrain
Automotive Vacuum Pump Market
Powertrain
South Korea Electro Hydraulic Power Steering Market
Powertrain
Electrically Powered Hydraulic Steering Market
Powertrain
Power Transmission Gearbox Market
Powertrain
South America Internal Combustion Engines Market
Powertrain
Automotive Clutch Slave Cylinder Market