
 Dental Suction Mirror Market | 2026-2036
Dental Suction Mirror Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Suction Mirror Market Outlook
The gap between premium LED-integrated suction mirrors and commodity disposable alternatives is repositioning procurement strategies across dental practices. Dentsply Sirona leverages its end-to-end platform control to bundle suction mirrors with chairside imaging systems. Henry Schein, Inc. anchors North American distribution through its direct-to-clinic logistics network. Zirc Dental Products specializes in color-coded infection control protocols that differentiate its mirror lines in group purchasing organization contracts.
A dental suction mirror combines an intraoral reflective surface with integrated aspiration channels, typically fabricated from autoclavable stainless steel or high-grade polycarbonate with suction ports ranging from 2.5 mm to 4.0 mm diameter to evacuate fluids and maintain visibility during procedures. Its primary function is to eliminate the need for separate handpiece suction, freeing the clinician's non-dominant hand and reducing procedure time in operative and surgical settings. LED Mirrors command premium placement in cosmetic procedure suites where illumination consistency affects shade matching accuracy, while Disposable Mirrors gain traction in mobile and emergency dental units prioritizing cross-contamination elimination over per-unit cost. Stainless Steel dominates hospital-based oral surgery due to autoclave durability requirements, though Polycarbonate advances in pediatric practices seeking reduced weight and thermal conductivity.
The FDA regulates dental suction mirrors as Class I medical devices under 21 CFR 872.6850, requiring adherence to biocompatibility and sterility validation protocols that elevate barrier-to-entry for new suppliers. The EU Medical Device Regulation mandates unique device identification and post-market surveillance, compelling manufacturers like Hager Worldwide GmbH and Carl Martin GmbH to maintain notified body certifications for CE marking access. Dental clinics must track how reimbursement shifts toward value-based preventive care bundles influence capital equipment refresh cycles versus disposable mirror replenishment rates.
Market Dynamics
The EU Medical Device Regulation's sterility tracking mandates are compressing supplier margins while forcing dental clinics toward LED-integrated systems that reduce handpiece changeover time during operative procedures.
Growth Catalysts
- Outpatient Surgery Volumes:Ambulatory dental surgery centers in the United States are expanding procedural throughput, creating sustained demand for suction mirrors that eliminate auxiliary handpiece requirements.
- REACH Compliance:European chemical safety standards are phasing out legacy mirror coatings, accelerating replacement cycles for autoclavable stainless steel alternatives.
- Polycarbonate Formulation Advances:High-grade thermoplastic variants with reduced thermal conductivity are penetrating pediatric practices seeking lighter instrument weight.
Market Restraints
- Stainless Steel Input Volatility:Surgical-grade 316L stainless price swings directly compress margin structures for reusable mirror manufacturers.
- Notified Body Bottlenecks:EU MDR certification queues extend CE marking timelines for new market entrants beyond eighteen months.
- Disposable Mirror Substitution:Single-use polycarbonate alternatives threaten reusable instrument refresh rates in mobile and emergency dental units.
Strategic Opportunities
- Color-Coded Infection Control:Group purchasing organization contracts favor mirror lines with protocol-differentiated visual identification systems.
- LED-Thermal Integration:Convergence of illumination arrays with suction channel thermal management opens cosmetic procedure suite placement.
- India Dental Infrastructure:Central government health scheme expansions into tier-two cities create first-time equipment procurement windows.
Industry Challenges
- Biocompatibility Validation:ISO 10993 testing timelines for new mirror materials delay product commercialization by nine to fourteen months.
- Legacy Chairside Integration:Proprietary suction coupling standards from established dental unit manufacturers fragment aftermarket compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Suction Mirror Market |
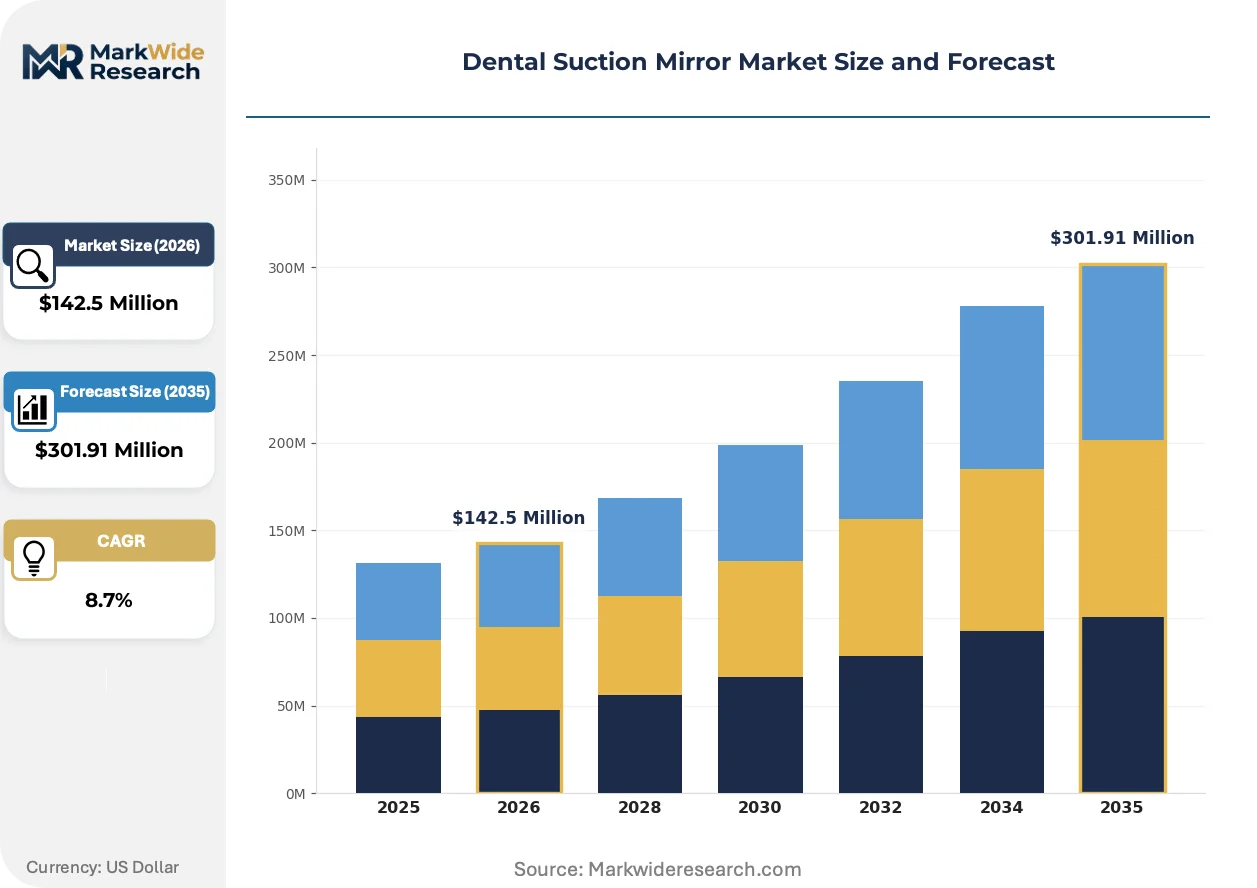
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $301.91 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Mirrors, LED Mirrors, Disposable Mirrors, Custom Mirrors Material: Plastic, Glass, Polycarbonate, Stainless Steel Application: General Dentistry, Oral Surgery, Preventive Care, Cosmetic Procedures End User: Dental Clinics, Hospitals, Laboratories, Research Facilities |
| Companies Covered | Nu-Bird Inc, Zirc Dental Products, Hager Worldwide GmbH, Henry Schein, Inc., Acteon Group, Dentsply Sirona, Carl Martin GmbH, DenMat Holdings, Richmond Dental & Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Suction Mirror Market Strategic Shifts
Mirror instrumentation is converging around three vectors: optical-electrical integration, regulatory traceability mandates, and procurement consolidation through group purchasing organizations.
LED-integrated suction mirrors are unifying illumination and aspiration into single-handpiece workflows. Cosmetic procedure suites are adopting these systems fastest, driven by shade-matching accuracy requirements. The technology is compressing procedure times by eliminating instrument swaps between mirror, suction, and curing light functions.
EU MDR unique device identification requirements are mandating serialized production tracking for all CE-marked dental instruments. Manufacturers must maintain post-market surveillance databases accessible to notified bodies. German dental clinics are upgrading to LED-integrated systems preemptively to streamline compliance documentation.
Group purchasing organization contracts are consolidating procurement decisions for multi-clinic dental service organizations. Direct-to-clinic logistics networks are displacing traditional dental distributor relationships in North America. This concentration is most visible in United States metropolitan markets where dental service organization penetration exceeds forty percent of practice volume.
Dental Suction Mirror Market Segmentation
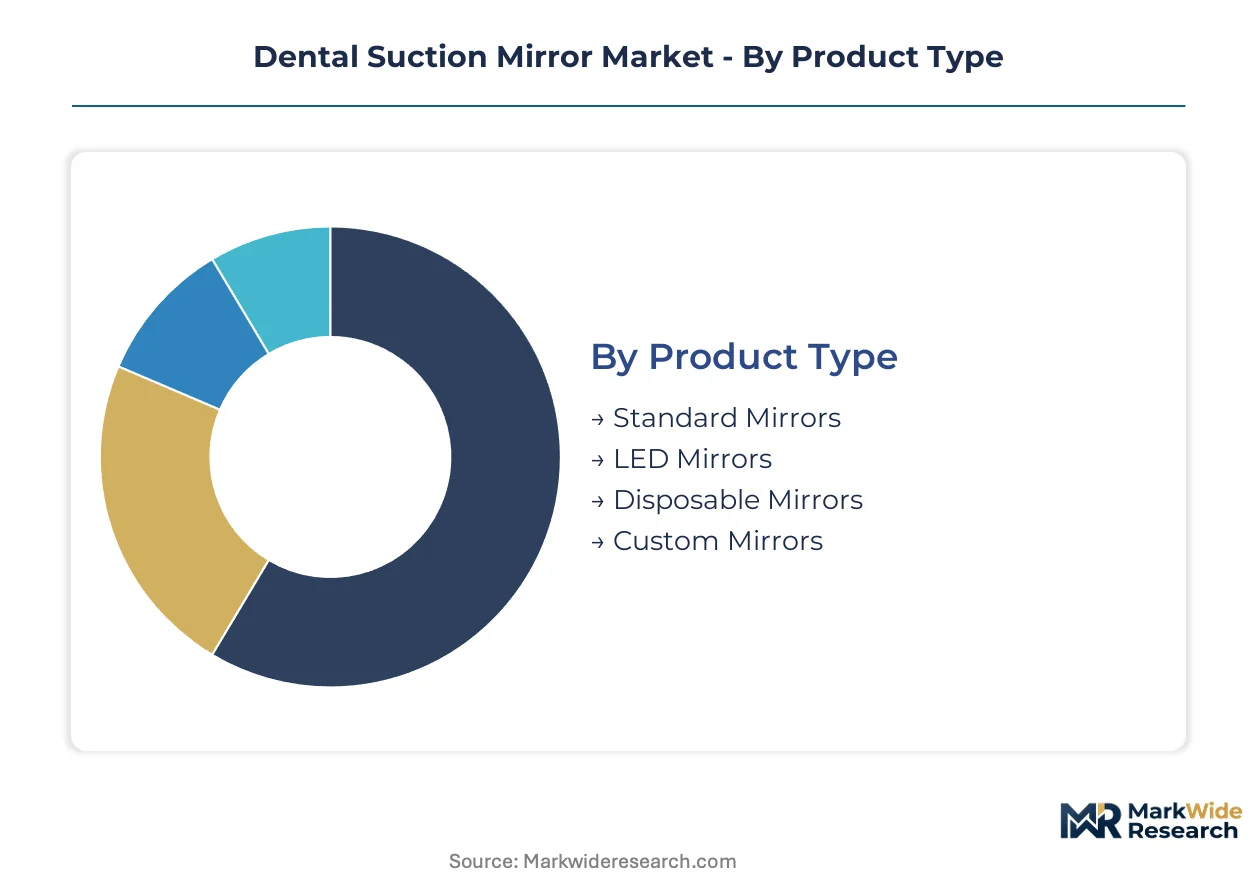
Dental suction mirrors segment across four critical dimensions that determine procurement priorities, sterility protocols, and reimbursement pathways. Product type and material selection drive capital expenditure versus operational expenditure trade-offs, while application and end-user categories dictate regulatory compliance burdens and volume concentration.
Product Type:
Procurement strategies diverge sharply between capital-intensive reusable systems and consumable disposables, with LED integration commanding premium placement in high-margin procedure suites.
- LED Mirrors:These instruments embed illumination arrays directly into mirror housings, typically delivering 25,000-50,000 lux output through fiber-optic or LED chip configurations. Demand concentrates in cosmetic procedure suites across Germany and the United States, where shade-matching accuracy requirements justify per-unit premiums and EU MDR sterility tracking mandates favor integrated systems with serialized production histories.
- Disposable Mirrors:Single-use polycarbonate instruments eliminate cross-contamination risks and autoclave maintenance costs. Mobile dental units and emergency response teams in the United States prioritize these for field deployment, though landfill disposal regulations in California and New York are compressing adoption rates.
- Standard Mirrors:Conventional stainless steel or glass mirrors without suction integration serve basic diagnostic functions in cost-constrained practices.
- Custom Mirrors:Bespoke configurations address specialized oral surgery requirements including angled aspiration channels and extended reach specifications.
Standard mirrors lead volumes today; LED mirrors are gaining share fastest.
Material:
Autoclave compatibility and thermal conductivity properties separate hospital-grade procurement from pediatric and mobile applications.
- Stainless Steel:Surgical-grade 316L formulations dominate hospital-based oral surgery in Germany and Japan, where autoclave durability requirements exceed 500 sterilization cycles and FDA biocompatibility validation under ISO 10993-5 cytotoxicity protocols is mandatory.
- Polycarbonate:High-grade thermoplastic variants with reduced thermal conductivity and 60% weight reduction versus steel penetrate pediatric practices in the United States and France, where instrument fatigue and patient comfort drive procurement decisions.
- Plastic:Commodity polymers serve single-use disposable lines where per-unit cost minimization outweighs durability requirements.
- Glass:Traditional reflective substrates persist in diagnostic-only applications lacking integrated suction channels.
Stainless steel dominates revenue today; polycarbonate shows the steepest expansion trajectory.
Application:
Reimbursement rate differentials and procedure complexity determine whether practices invest in premium LED-integrated systems or maintain commodity instrument inventories.
- Cosmetic Procedures:Veneer placement, whitening, and aesthetic restorations demand illumination consistency for shade matching. LED-integrated mirrors command placement in boutique suites across Beverly Hills, London's Harley Street district, and Dubai's healthcare free zones where patient self-pay rates exceed insurance reimbursement by 300-400%.
- Oral Surgery:Extraction, implant placement, and periodontal procedures require continuous aspiration to maintain visibility. Hospital outpatient departments in the United States prioritize stainless steel systems with 4.0 mm suction ports for blood and irrigant evacuation.
- General Dentistry:Routine examinations and basic restorations utilize standard mirrors with or without suction integration depending on practice volume.
- Preventive Care:Prophylaxis and hygiene services favor lightweight disposable options to minimize cross-contamination protocols.
General dentistry leads procedure volumes today; cosmetic applications are climbing the fastest.
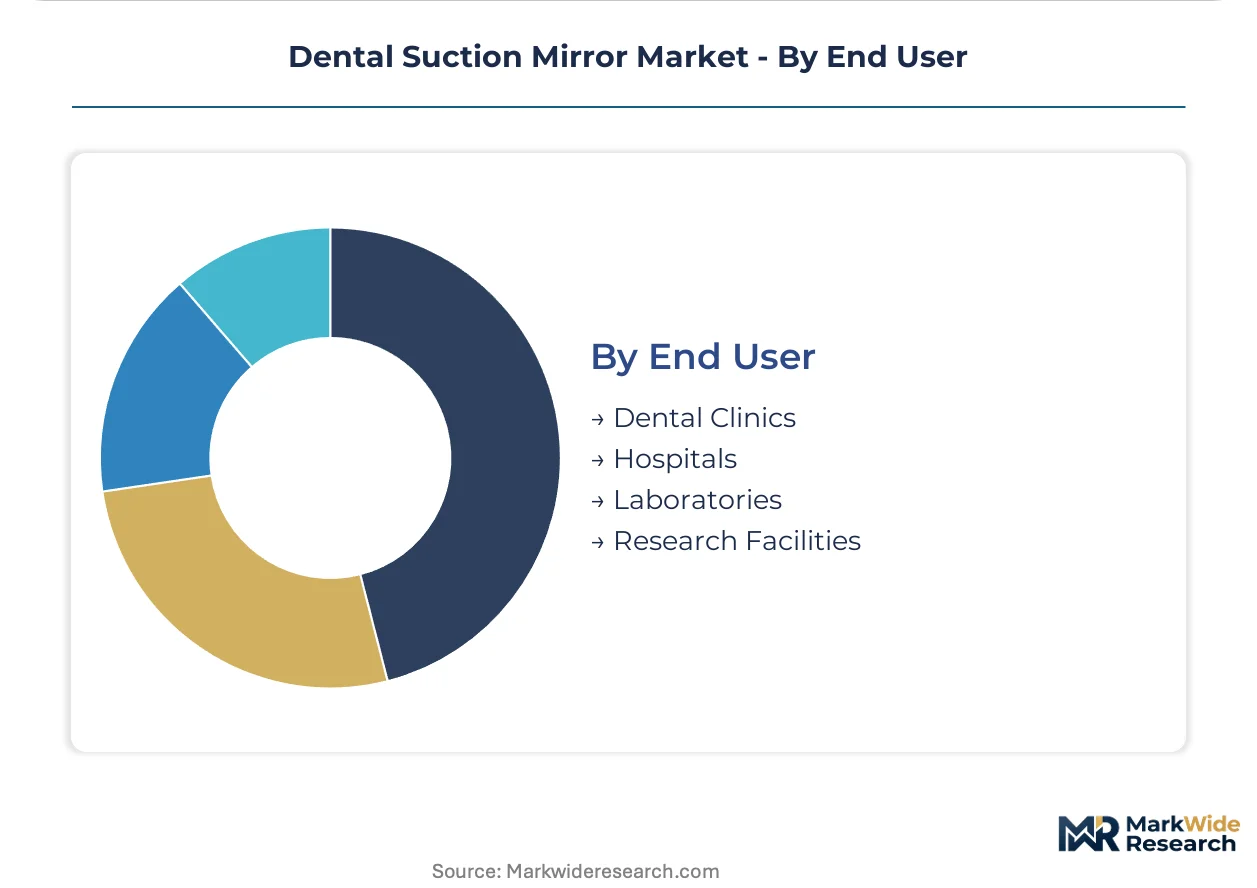
End User:
Capital equipment refresh cycles and group purchasing organization contract structures create divergent procurement patterns across practice settings.
- Dental Clinics:Independent and dental service organization-affiliated practices drive volume concentration, with United States metropolitan markets exceeding 40% DSO penetration and centralized procurement favoring color-coded infection control protocols from specialized suppliers.
- Hospitals:Academic medical centers and community hospital outpatient departments require FDA-validated Class I device documentation and maintain capital equipment depreciation schedules spanning 7-10 years.
- Laboratories:Dental prosthesis fabrication facilities utilize suction mirrors for shade verification and quality control in crown and bridge production.
- Research Facilities:University dental schools and clinical trial sites instrument studies with standardized mirror configurations to eliminate procedural variability.
Dental clinics anchor demand today; hospital outpatient departments are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's dental clinics are upgrading to LED-integrated suction mirrors faster than United States practices, reflecting tighter EU Medical Device Regulation timelines versus fragmented FDA enforcement priorities.
United States
Ambulatory dental surgery centers in Texas and Florida are expanding procedural throughput, driving suction mirror demand that eliminates auxiliary handpiece requirements. The FDA regulates these devices as Class I medical devices under 21 CFR 872.6850, mandating biocompatibility validation that elevates supplier barriers. Henry Schein, Inc. anchors distribution through direct-to-clinic logistics networks concentrated in metropolitan markets where dental service organization penetration exceeds forty percent.
Germany
Hospital-based oral surgery departments in Bavaria and North Rhine-Westphalia prioritize surgical-grade 316L stainless steel systems for autoclave durability exceeding 500 cycles. The EU Medical Device Regulation mandates unique device identification and post-market surveillance, compelling manufacturers to maintain notified body certifications for CE marking access. Hager Worldwide GmbH and Carl Martin GmbH maintain production clusters in the Stuttgart and Frankfurt regions to streamline regulatory documentation.
Japan
Academic medical centers in Tokyo and Osaka require FDA-validated Class I device documentation for capital equipment depreciation schedules spanning 7-10 years. METI industrial standards guide procurement specifications for autoclavable instruments in hospital outpatient departments. The Kanto region concentrates demand for premium LED-integrated systems in cosmetic procedure suites where shade-matching accuracy commands patient self-pay premiums.
India
Central government health scheme expansions into tier-two cities such as Pune and Jaipur create first-time equipment procurement windows for dental clinics. The CDSCO regulates medical device imports while BIS standards govern domestic manufacturing quality. Maharashtra and Gujarat host emerging distribution networks serving independent practices transitioning from basic diagnostic mirrors to suction-integrated systems.
France
Pediatric practices in Paris and Lyon prioritize polycarbonate variants with reduced thermal conductivity and sixty percent weight reduction versus steel for instrument fatigue reduction. ANSM oversees post-market surveillance alongside EU MDR compliance timelines. The Île-de-France region concentrates group purchasing organization contract activity favoring color-coded infection control protocols.
Dental Suction Mirror Market Competitive Environment
Top-tier vendors anchor platform-level bundling strategies, while mid-tier specialists differentiate through infection control protocols and regional certification expertise. The vendor base stratifies across three tiers: integrated dental equipment platforms, specialized instrument manufacturers, and disposable-focused suppliers. Strategic archetypes include end-to-end platform controllers, infection control specialists, and regional certification navigators. Dominant competitive moves encompass backward integration into illumination component supply and geographic expansion through direct-to-clinic logistics networks.
Among German-based fabricators, Hager Worldwide GmbH and Carl Martin GmbH exemplify the regional certification navigator archetype, occupying positions shaped by EU MDR notified body relationships. Dentsply Sirona represents the integrated platform controller archetype, sitting within a tier where end-to-end system bundling displaces standalone instrument procurement. Zirc Dental Products anchors the infection control specialist vector, with color-coded protocol differentiation resonating in group purchasing organization contract structures.
| Leading Market Players |
|---|
| Nu-Bird Inc |
| Zirc Dental Products |
| Hager Worldwide GmbH |
| Henry Schein, Inc. |
| Acteon Group |
| Dentsply Sirona |
| Carl Martin GmbH |
| DenMat Holdings |
| Richmond Dental & Medical |
| Others |
Value Chain & Pricing Dynamics
Surgical-grade 316L stainless steel price indices cascade through dental suction mirror manufacturing into three distinct procurement tiers: premium LED-integrated systems for cosmetic suites, standard autoclavable instruments for general practice, and commodity disposables for mobile units. Input volatility from European REACH compliance costs and Asian polycarbonate feedstock markets compresses margin structures differently across each tier, forcing manufacturers to optimize certification investments against volume scale.
Pricing Analysis
Capacity additions in China's polycarbonate compounding sector are reshaping price floors for disposable mirror alternatives, intensifying cost competition against German and Japanese stainless steel fabricators. Three-tier pricing structure across premium LED-integrated, standard autoclavable, and economy disposable levels differentiates on FDA Class I validation depth and EU MDR notified body certification tier. Pricing pressure stems from single-use substitution in emergency dental units, with mobile operators exhibiting highest price sensitivity and hospital outpatient departments least sensitive due to capital depreciation schedules.
Supply Chain Analysis
Notified body certification gating concentrates finished instrument supply in Germany, Japan, and the United States, where FDA biocompatibility validation and EU MDR post-market surveillance infrastructure anchor production. Raw material flows draw from Swedish surgical steel mills, Saudi petrochemical feedstocks for polycarbonate resin, and Taiwanese LED chip foundries for illumination arrays. Single-source vulnerability runs through German notified body queues extending CE marking timelines. Distribution runs through Henry Schein's direct-to-clinic logistics network and dental service organization group purchasing contracts in North American metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dental suction mirror economics favor margin expansion through polycarbonate formulation advances that reduce per-unit material costs while LED integration commands premium placement in cosmetic procedure suites.
For Market Incumbents: Acquire illumination component supply chains to capture LED chip margin and eliminate fiber-optic coupling dependency. Secure backward integration into polycarbonate compounding to offset 316L stainless volatility. Defend against disposable mirror substitution by embedding serialized EU MDR tracking into reusable system refresh cycles, leveraging regulatory compliance as a switching cost. For New Entrants and Emerging Players: Tier-two Indian dental clinics represent the most penetrable buyer archetype, with central government health scheme expansions creating first-time equipment procurement windows. Target pediatric practices in France and the United States with lightweight polycarbonate variants differentiated by thermal conductivity specifications. Pursue group purchasing organization contract entry through color-coded infection control protocol specialization rather than head-to-head LED feature competition. For Investors and Strategic Acquirers: Asymmetric upside sits with regional certification navigators possessing EU MDR notified body relationships and established CE marking pathways. Long-term viability centers on manufacturers bridging stainless steel autoclave durability with polycarbonate weight reduction through hybrid material platforms. Watch FDA enforcement intensity around Class I biocompatibility validation as the signal indicating whether premium LED-integrated systems or commodity disposables capture share in United States outpatient surgery centers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR notified body relationships compress eighteen-month certification queues for German manufacturers. |
| Hospital System Partnership | Academic medical center contracts in Tokyo and Osaka anchor seven-to-ten-year capital depreciation schedules. |
| Backward Integration | In-house LED chip sourcing eliminates fiber-optic coupling dependency and captures illumination margin. |
| Software Companion Development | Serialized production tracking databases streamline EU MDR post-market surveillance documentation burdens. |
| Reimbursement Strategy | Value-based preventive care bundle alignment influences capital equipment refresh versus disposable replenishment rates. |
Study Parameters
Multiple input streams — primary interviews with dental equipment procurement managers, GPO contracts specialists, and biomedical engineers; secondary validation through FDA 510(k) filings, EU MDR notified body registries, and hospital capital expenditure databases; plus customs trade data for surgical steel and polycarbonate resin flows — were reconciled through bottom-up and top-down triangulation. Stakeholder perspectives from German dental clinic operators, United States ambulatory surgery center administrators, and Indian tier-two city practitioners informed demand-side assumptions.
Historical shipment data cross-referenced against expert panel input established baseline volumes across the projection horizon. Segmentation dimensions modeled include product type tier, material grade, application procedure complexity, and end-user capital cycle position. CAGRs were derived from procedure volume trajectories, reimbursement pathway shifts, and regulatory compliance cost curves. Forecast inputs incorporated REACH chemical safety phase-out timelines and CDSCO import regulation evolution for Indian market penetration assumptions.
Underlying measurement precision varies by segment; LED-integrated and stainless steel categories carry tighter precision than emerging polycarbonate variants due to established production reporting. Forecasts reflect assumptions about outpatient surgery volume continuity and notified body certification throughput. A model refresh is warranted upon material change in EU MDR enforcement intensity or FDA Class I biocompativity validation scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Chair Market
Dental Devices
Titanium Dental Implants Market
Dental Devices
Middle East and Africa Dental Lab Market
Dental Devices
Dental Sealants Market
Dental Devices
Digital Facebow Market
Dental Devices
Dental Implants and Abutment Systems Market
Dental Devices
Guided Biofilm Therapy Market
Dental Devices
Dental Aligners Market
Dental Devices
Dental Carpule Market
Dental Devices
Spain Dental Devices Market
Dental Devices
Dental Diagnostic and Surgical Market
Dental Devices
GCC Dental Implants Market
Dental Devices
Global Dentures Market
Dental Devices
Endodontics and Orthodontics Market
Dental Devices
Dental Healing Caps Market
Dental Devices
Dental Devices and Consumables Market