
 Dimpleplasty Market | 2026-2036
Dimpleplasty Market Size, Share, and Industry Trends Forecast 2026-2036
Dimpleplasty Market Intelligence
Social media influencer marketing is restructuring how aesthetic centers attract dimpleplasty patients, shifting budgets from traditional dermatology referrals to Instagram and TikTok campaigns. Apollo Cosmetic Clinics leverages celebrity endorsements to sustain brand visibility across Southeast Asian markets. Beverly Hills Plastic Surgery Group anchors premium pricing through concierge service models. ID Hospital dominates Seoul's Gangnam medical tourism corridor with multilingual patient coordination.
Dimpleplasty creates artificial dimples through precise incision and suturing of the buccinator muscle, typically using absorbable sutures or submucosal tacking at 3-5 millimeter depths to achieve permanent facial dimpling. The procedure serves primarily cosmetic enhancement purposes, with surgical variants offering irreversible results versus minimally invasive techniques using dermal fillers for temporary outcomes. Single-point surgical techniques occupy the mature volume segment due to established reimbursement pathways in hospital settings, while laser-assisted methods represent the fastest-growing category as precision tools reduce post-operative bruising duration. Hybrid techniques that combine suture anchoring with filler overlay are capturing margin pools in high-end aesthetic centers where patients seek customizable depth control.
FDA oversight of silicone implants and dermal fillers shapes material selection for US-based providers, while CE marking under the EU MDR governs device approval for European clinics. South Korea's Ministry of Food and Drug Safety enforces strict advertising standards that limit before-and-after imagery in promotional materials. Stakeholders must monitor evolving telemedicine consultation regulations that determine whether pre-operative assessments can occur across state or national borders without in-person examination.
Market Dynamics
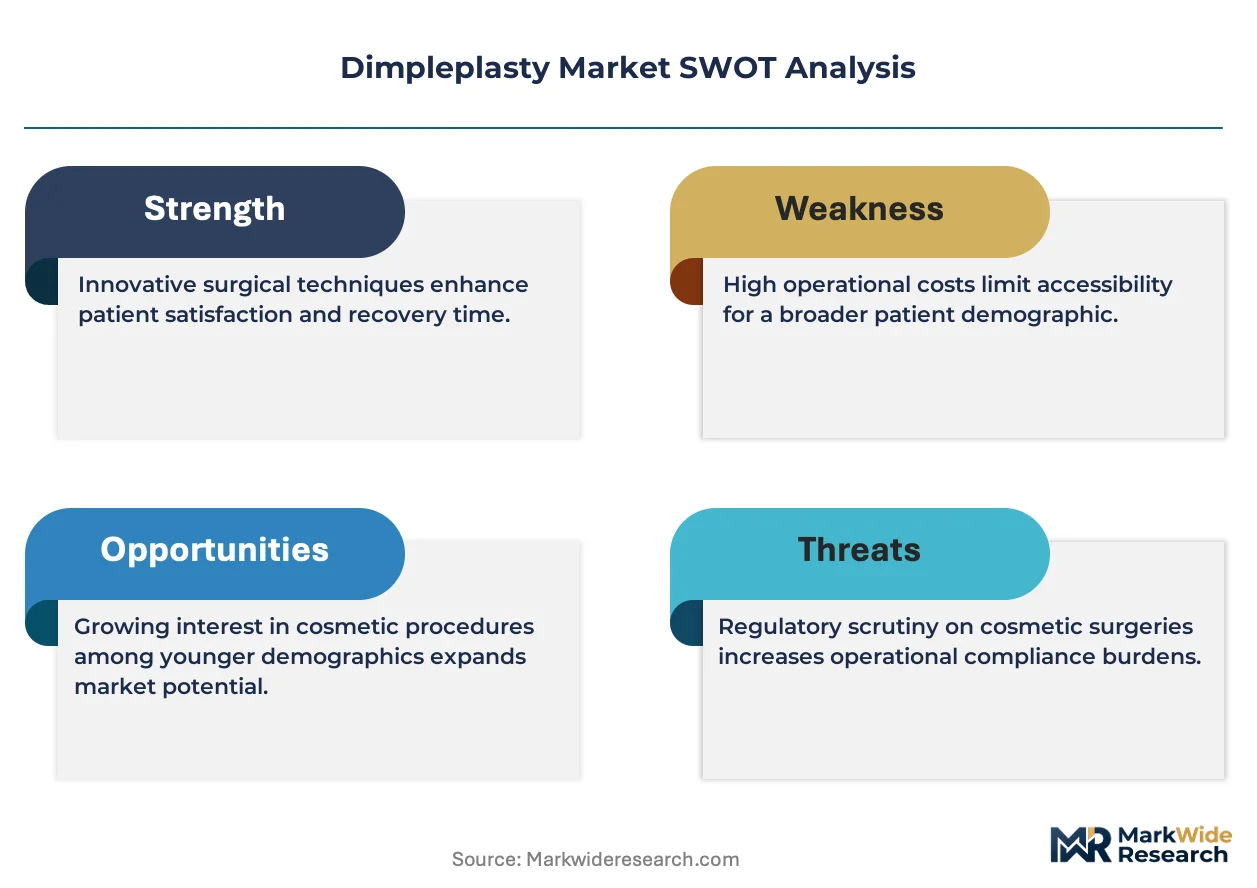
Social media-driven aesthetic demand is restructuring patient acquisition economics, forcing clinics to redirect marketing spend from physician networks toward influencer partnerships and platform-native content strategies.
Growth Catalysts
- MFDS Advertising Standards:South Korea's strict promotional guidelines paradoxically elevate clinic credibility through controlled before-and-after documentation, attracting medical tourists seeking regulated transparency.
- Absorbable Suture Materials:Advanced polymer formulations reduce revision surgery rates by enabling predictable tissue integration without permanent foreign body presence.
- Seoul-Los Angeles Corridor:Bidirectional patient flow between these aesthetic surgery clusters creates standardized technique diffusion and premium pricing benchmarks.
Market Restraints
- CE Marking Under EU MDR:Reclassification of facial implant materials as Class III devices extends approval timelines and concentrates sourcing among pre-certified European suppliers.
- Buccinator Muscle Anatomy Variability:Non-standardized facial muscle architecture limits procedure reproducibility and elevates malpractice exposure for permanent nerve injury.
- Hyaluronic Acid Price Volatility:Dermal filler input costs fluctuate with pharmaceutical-grade HA fermentation capacity, compressing margins on temporary dimple techniques.
Strategic Opportunities
- Telemedicine Pre-Assessment:Cross-border video consultation frameworks enable clinics to capture international patients before travel commitment, with Dubai and Bangkok piloting regulated remote screening protocols.
- Laser-Assisted Suturing:Integration of CO2 laser precision with traditional anchoring techniques reduces post-operative edema duration, opening same-day procedure markets.
- Package Bundling:Multiprocedure tourism products combining dimpleplasty with rhinoplasty or jaw contouring extract higher per-visit revenue from Asian medical travelers.
Industry Challenges
- Microsurgical Skill Scarcity:Precise buccinator dissection requires specialized training that outpaces current fellowship program output in Western markets.
- FDA 510(k) Pathway Complexity:Novel suture anchoring devices face prolonged predicate device matching requirements, delaying commercialization for modified materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dimpleplasty Market |
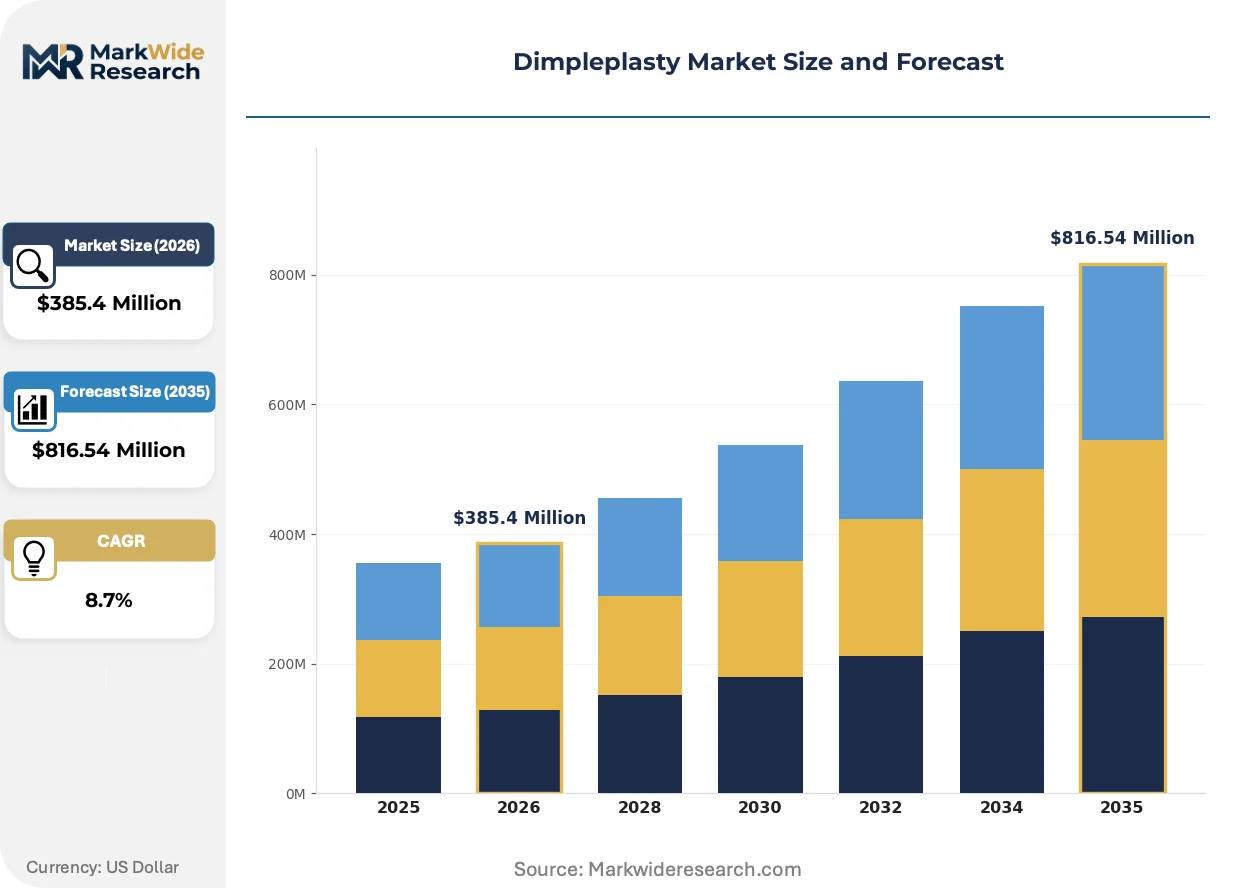
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Non-Surgical, Surgical, Minimally Invasive, Cosmetic End User: Clinics, Hospitals, Aesthetic Centers, Dermatology Practices Technique: Single-Point, Double-Point, Hybrid, Laser-Assisted Material: Silicone, Dermal Filler, Autologous Tissue, Others |
| Companies Covered | AbbVie, Apollo Cosmetic Clinics, Beverly Hills Plastic Surgery Group, Harley Street Aesthetics, Zenith Cosmetic Clinics, ID Hospital, Aesthetica Clinics, The Aivee Clinic, The Private Clinic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dimpleplasty Market Strategic Shifts & Innovations
Digital-native patient journeys are compressing decision timelines from consultation to surgery, while precision instrumentation and evolving regulatory frameworks reshape technical and commercial operating models across aesthetic surgery centers.
Fractional CO2 laser technology is converging with traditional suture-based dimple creation to enable bloodless dissection through the buccal mucosa. High-end Gangnam clinics are adopting these hybrid workstations to differentiate on recovery speed. The convergence is compressing procedure duration from forty-five to under twenty minutes while reducing hematoma incidence rates.
EU MDR implementation is reclassifying facial implantable materials under stricter clinical evidence requirements. European manufacturers must now submit post-market surveillance data for suture materials previously grandfathered under prior directives. Aesthetic centers in Germany and France are responding by consolidating supplier relationships toward established CE-marked vendors with robust technical documentation.
Platform-native content discovery is displacing traditional referral networks as the primary patient source. Instagram and TikTok algorithmic distribution enables direct surgeon-to-patient relationship formation without intermediary dermatology gatekeepers. This behavioral shift concentrates demand among younger demographic cohorts in Southeast Asian urban centers where mobile-first content consumption dominates healthcare research patterns.
Dimpleplasty Market Segmentation
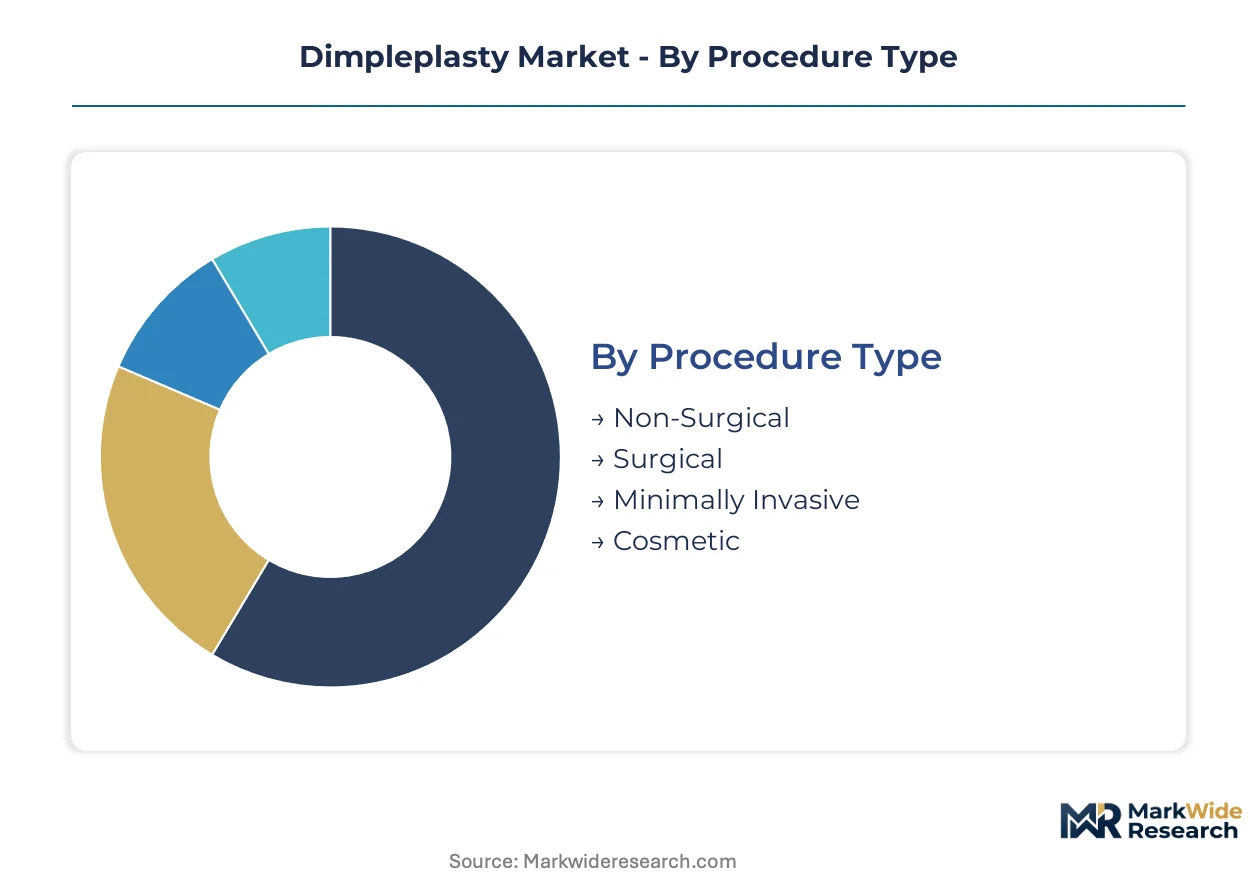
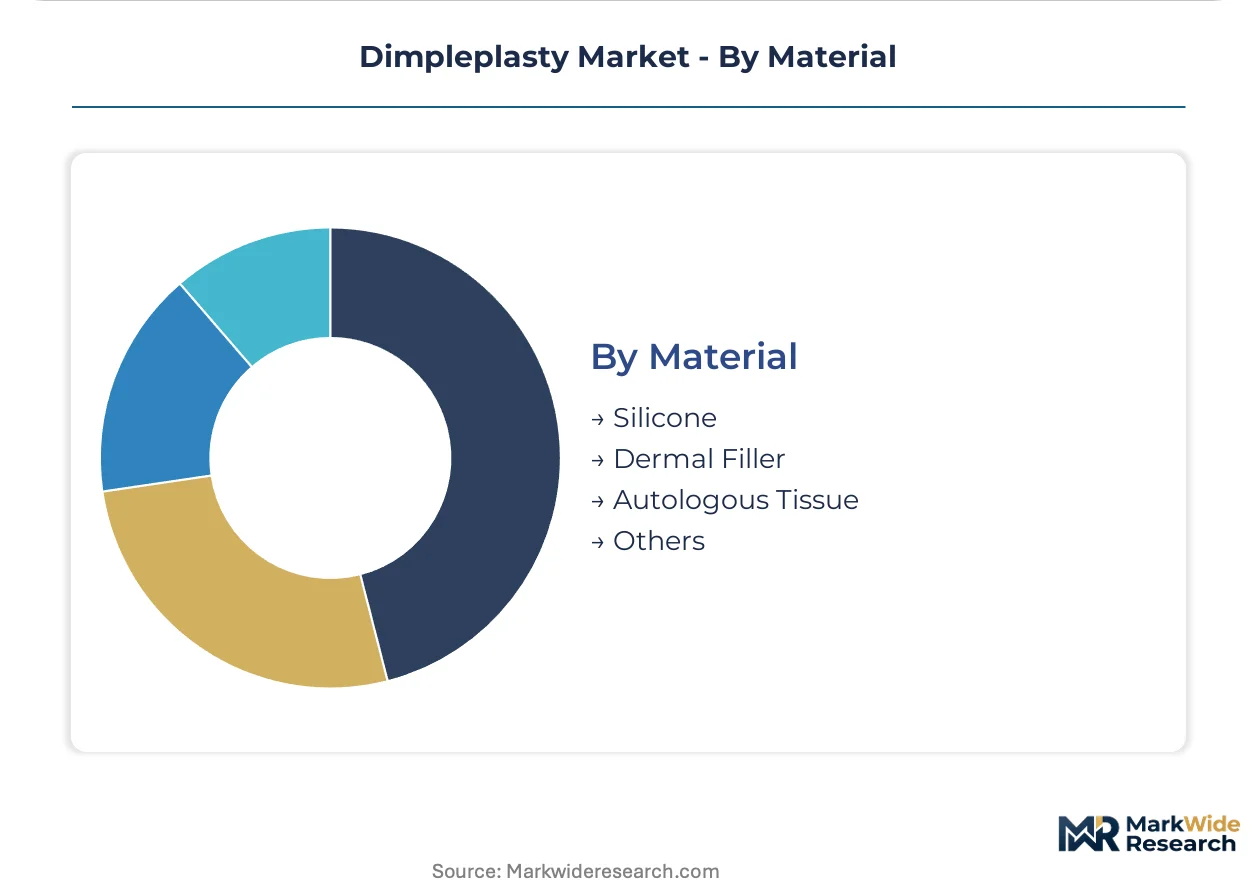
Procedure differentiation in dimpleplasty determines reimbursement pathways, recovery protocols, and patient acquisition economics. Material selection shapes regulatory compliance requirements across FDA, CE marking, and MFDS jurisdictions. Technique innovation is compressing operating room time while expanding addressable patient pools beyond traditional surgical candidates.
Procedure Type:
Upgrade cycles in aesthetic medicine accelerate as temporary techniques convert patients toward permanent solutions, creating recurring revenue streams across the patient journey.
- Surgical:Permanent buccinator muscle suturing through intraoral incision creates irreversible dimple formation. Demand concentrates in Seoul's Gangnam corridor and Los Angeles, where medical tourism packages bundle surgical dimpleplasty with rhinoplasty and jaw contouring procedures.
- Non-Surgical:Dermal filler injection into predetermined facial points creates temporary dimpling lasting 6-12 months. Beverly Hills clinics and Bangkok aesthetic centers capture younger demographics seeking reversible outcomes with minimal downtime.
- Minimally Invasive:Thread-based anchoring through micro-incision offers semi-permanent results with reduced tissue disruption.
- Cosmetic:Makeup simulation and prosthetic accessories provide non-invasive appearance modification for trial purposes.
Surgical sits at the top of the volume ranking, with Non-Surgical climbing the fastest.
End User:
Patient acquisition costs vary dramatically by facility type, with Instagram-driven discovery favoring standalone aesthetic centers over hospital-based departments.
- Aesthetic Centers:Dedicated cosmetic surgery facilities in Seoul, Los Angeles, and Dubai deploy influencer marketing and concierge service models. ID Hospital and Apollo Cosmetic Clinics anchor premium positioning through multilingual coordination and celebrity endorsement networks.
- Clinics:Outpatient surgical clinics in Southeast Asian urban centers optimize for procedure volume through standardized technique protocols and compressed consultation-to-surgery timelines.
- Hospitals:Academic medical centers in Germany and France navigate EU MDR compliance for implantable materials through established procurement relationships with CE-marked suppliers.
- Dermatology Practices:Skin-focused practices in US metropolitan areas leverage existing patient relationships for cross-selling minimally invasive techniques.
Aesthetic Centers command the highest revenue per procedure, with Clinics expanding most quickly across Southeast Asia.
Technique:
Precision instrumentation investments separate high-margin providers from commodity competitors, with laser integration requiring capital deployment that smaller operators cannot match.
- Laser-Assisted:CO2 laser dissection through buccal mucosa enables bloodless tissue separation with reduced post-operative edema. Gangnam clinics differentiate on recovery speed, compressing procedure duration from forty-five to under twenty minutes while lowering hematoma incidence.
- Single-Point:Established one-suture anchoring technique dominates hospital reimbursement pathways in the United States and European Union, where insurance coding recognizes standardized procedural protocols.
- Double-Point:Dual-anchor suturing creates deeper, more pronounced dimpling for patients with thicker buccal fat pads.
- Hybrid:Combined suture anchoring with filler overlay enables customizable depth control in high-end aesthetic centers targeting customization-seeking patients.
Single-Point retains volume leadership through reimbursement advantages, with Laser-Assisted gaining share fastest among premium providers.
Material:
Regulatory reclassification of implantable substances is consolidating supplier relationships toward vendors with robust technical documentation and post-market surveillance capabilities.
- Dermal Filler:Hyaluronic acid formulations enable reversible, temporary outcomes with immediate visual confirmation. Price volatility in pharmaceutical-grade HA fermentation capacity compresses margins for temporary technique providers in competitive metropolitan markets.
- Silicone:Permanent implant materials face heightened FDA 510(k) scrutiny and EU MDR Class III reclassification, extending approval timelines and concentrating sourcing among pre-certified European and Korean suppliers.
- Autologous Tissue:Patient-derived fat grafting eliminates foreign body rejection risk while requiring specialized liposuction infrastructure.
- Others:Experimental collagen matrices and synthetic absorbable polymers remain in limited clinical deployment pending long-term integration studies.
Dermal Filler leads procedure volume through lower barrier to trial, with Autologous Tissue expanding most quickly among revision-averse patient segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gangnam's aesthetic surgery corridor anchors international demand for dimpleplasty, with Seoul and Los Angeles forming a bidirectional patient flow that standardizes technique diffusion and premium pricing benchmarks across the analysis window.
United States
FDA oversight of silicone implants and dermal fillers shapes material selection for US-based providers. The 510(k) pathway complexity for novel suture anchoring devices delays commercialization timelines. Beverly Hills Plastic Surgery Group anchors premium positioning through concierge service models in the Los Angeles metropolitan cluster.
South Korea
MFDS advertising standards paradoxically elevate clinic credibility through controlled before-and-after documentation. Strict promotional guidelines limit imagery in marketing materials while attracting medical tourists seeking regulated transparency. ID Hospital dominates Seoul's Gangnam district with multilingual patient coordination and bundled procedure packages.
United Kingdom
CE marking under EU MDR reclassification extends approval timelines for facial implant materials. Harley Street Aesthetics and The Private Clinic navigate Class III device requirements through established procurement with pre-certified European suppliers. London's medical district concentrates demand among revision-averse patient segments.
Thailand
Bangkok aesthetic centers pilot regulated remote screening protocols for cross-border video consultation frameworks. Apollo Cosmetic Clinics leverages celebrity endorsements to sustain brand visibility across Southeast Asian markets. The city's outpatient surgical clinics optimize for procedure volume through compressed consultation-to-surgery timelines.
Philippines
The Aivee Clinic exemplifies platform-native patient acquisition through Instagram and TikTok algorithmic distribution. Mobile-first content consumption dominates healthcare research patterns among younger demographic cohorts in Manila. Dermatology practices cross-sell minimally invasive techniques to existing patient relationships.
Dimpleplasty Market Key Industry Players
Capacity expansion dominates the current landscape as aesthetic centers deploy laser-assisted workstations and multilingual coordination infrastructure. The vendor base stratifies across three tiers: hospital-affiliated academic centers with established reimbursement pathways, standalone premium clinics with influencer-driven acquisition, and high-volume outpatient operators optimizing for throughput. Two strategic archetypes predominate: technology-differentiated providers investing in CO2 laser precision tools, and service-integrated operators bundling dimpleplasty with rhinoplasty and jaw contouring. Geographic expansion into medical tourism corridors and portfolio diversification into hybrid suture-filler techniques represent the dominant competitive moves.
Within the premium-tier aesthetic center segment, ID Hospital and Beverly Hills Plastic Surgery Group exemplify divergent geographic anchoring strategies, with the former concentrating on Seoul's Gangnam medical tourism corridor and the latter on Los Angeles celebrity-adjacent positioning. Apollo Cosmetic Clinics occupies a position bridging Southeast Asian volume markets with endorsement-driven brand visibility. Harley Street Aesthetics and The Private Clinic represent European compliance-focused archetypes navigating EU MDR requirements through consolidated supplier relationships. AbbVie's pharmaceutical-scale infrastructure contrasts with the clinic-dominant competitive set, reflecting material supply chain concentration rather than direct procedural competition.
| Leading Market Players |
|---|
| AbbVie |
| Apollo Cosmetic Clinics |
| Beverly Hills Plastic Surgery Group |
| Harley Street Aesthetics |
| Zenith Cosmetic Clinics |
| ID Hospital |
| Aesthetica Clinics |
| The Aivee Clinic |
| The Private Clinic |
| Others |
Cost & Logistics Intelligence
Instagram-driven patient acquisition in Seoul and Los Angeles is compressing consultation-to-surgery timelines and forcing aesthetic centers to absorb premium suture material costs without full pass-through, squeezing margins on standard techniques while laser-assisted procedures sustain pricing power through differentiated recovery protocols.
Pricing Analysis
Hyaluronic acid fermentation capacity constraints and absorbable polymer R&D costs pass through unevenly across procedure tiers. Three-tier pricing structure across premium, standard, and economy levels separates Gangnam laser-assisted suites from Bangkok volume clinics and Southeast Asian outpatient operators. Pricing pressure stems from dermal filler input volatility, compressing margins on temporary techniques in competitive metropolitan markets. Younger demographics seeking reversible outcomes in Bangkok and Manila exhibit highest price sensitivity, while bundled medical tourism packages in Seoul sustain premium positioning.
Supply Chain Analysis
Single-source vulnerability sits with Korean and German suppliers of CE-marked absorbable sutures under EU MDR Class III requirements. Manufacturing concentrates in South Korea, Germany, and the United States for FDA-cleared implantable materials. Raw material dependencies include pharmaceutical-grade hyaluronic acid, medical-grade silicone, and advanced polymer formulations for tissue integration. Tariff exposure on Korean-manufactured sutures shipped to European clinics elevates procurement risk. Distribution runs through hospital procurement committees in academic medical centers and direct-to-clinic relationships for standalone aesthetic operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as patient demand shifts toward permanent surgical outcomes with predictable tissue integration, elevating specifications for absorbable suture materials and laser-assisted precision tools.
For Market Incumbents: Cement supplier relationships with MFDS-certified Korean manufacturers and CE-marked European vendors ahead of EU MDR post-market surveillance requirements. Expand laser-assisted workstation capacity in Gangnam and Los Angeles corridors to defend against thread-based minimally invasive substitutes. Prioritize multilingual patient coordination infrastructure to capture medical tourism flow. For New Entrants and Emerging Players: The price-point gap between Beverly Hills concierge-tier bundling and Bangkok volume clinics creates white-space opportunity for mid-market hybrid suture-filler techniques. Target Southeast Asian urban centers with compressed consultation protocols and platform-native TikTok acquisition. Enter through telemedicine pre-assessment frameworks piloted in Dubai and Bangkok. For Investors and Strategic Acquirers: Asymmetric upside sits with aesthetic center chains possessing both laser capital equipment and established medical tourism coordination. Long-term viability hinges on regulatory compliance infrastructure across FDA, CE marking, and MFDS jurisdictions. Watch for MFDS advertising standard relaxations as inflection signal for marketing spend reallocation toward before-and-after documentation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class III reclassification extends timelines for suture material suppliers in Germany. |
| Laser Workstation Deployment | CO2 precision tools differentiate Gangnam clinics on recovery speed and hematoma reduction. |
| Medical Tourism Packaging | Bundled rhinoplasty-dimpleplasty-jaw contouring extracts higher per-visit revenue in Seoul. |
| Telemedicine Pre-Assessment | Regulated remote screening frameworks in Dubai and Bangkok capture patients before travel commitment. |
| Multilingual Coordination Infrastructure | ID Hospital's patient acquisition model depends on seamless cross-border consultation and scheduling. |
Research Approach
Multiple input streams — surgeon interviews at Gangnam and Los Angeles aesthetic centers, procurement manager discussions at German hospital systems, and regulatory affairs consultations with MFDS compliance officers — were reconciled against FDA 510(k) filings, CE marking databases under EU MDR, and South Korean medical tourism statistics. Secondary validation drew from customs records for absorbable suture imports, hospital procurement database extracts, and platform-native content analytics from Instagram and TikTok healthcare discovery patterns. Bottom-up procedure volume estimates and top-down market sizing were triangulated to anchor projections.
Data-stream reconciliation across surgical technique adoption curves, material regulatory approval timelines, and patient acquisition cost structures shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include procedure type, end-user facility category, technique precision tier, and implantable material class. CAGRs were derived from technique diffusion rates and medical tourism corridor expansion patterns. Forecast inputs incorporated MFDS advertising enforcement intensity and EU MDR post-market surveillance data submission requirements.
Caveats apply where MFDS promotional guideline shifts, EU MDR clinical evidence requirement changes, or hyaluronic acid fermentation capacity constraints could materially shift the outlook. Forecasts reflect assumptions about telemedicine regulatory acceptance for pre-operative assessment and sustained Instagram-TikTok algorithmic distribution favoring direct surgeon-to-patient relationship formation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
Japan Cosmetic Surgery Market
Cosmetic Surgery
India Cosmetic Surgery Market
Cosmetic Surgery
Italy Cosmetic Surgery Market
Cosmetic Surgery
China Cosmetic Surgery Market
Cosmetic Surgery
Brazil Cosmetic Surgery Market
Cosmetic Surgery
Saudi Arabia Cosmetic Surgery Market
Cosmetic Surgery
Mexico Cosmetic Surgery Market
Cosmetic Surgery
US Gender Reassignment Surgery Market
Cosmetic Surgery
Gynecomastia Procedures Market
Cosmetic Surgery
Cosmetic Surgery Products Market
Cosmetic Surgery
Cosmetic Surgery and Services Market
Cosmetic Surgery
Cosmetic Surgery and Procedure Market
Cosmetic Surgery
Rhytidectomy Market
Cosmetic Surgery
Reconstructive Surgery Market
Cosmetic Surgery
Rhinoplasty Market
Cosmetic Surgery
Global Plastic Surgery and Integumentary System Procedures Market