
 Coronary Heart Disease Diagnostic Imaging Devices Market | 2026-2036
Coronary Heart Disease Diagnostic Imaging Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Coronary Heart Disease Diagnostic Imaging Devices Market Intelligence
Hospital procurement of coronary imaging systems is collapsing toward integrated cardiovascular service lines that bundle diagnostic throughput with interventional capacity. Siemens Healthineers leverages its dual-source CT platform to anchor high-end hospital contracts across North American academic centers. GE Healthcare competes through its Edison AI ecosystem, embedding algorithmic stenosis scoring directly into angiography workflows. Canon Medical Systems Corporation specializes in detector technology that sustains image quality at reduced radiation exposure, a priority for repeat-scan protocols.
Coronary heart disease diagnostic imaging devices encompass non-invasive and minimally invasive instruments that generate structural, functional, or perfusion data from myocardial tissue and coronary vasculature, typically operating at spatial resolutions below one millimeter and temporal resolutions under 100 milliseconds to capture dynamic cardiac cycles. These systems serve the clinical purpose of detecting flow-limiting stenosis, characterizing plaque composition, and guiding revascularization decisions before catheterization or surgery. CT scan modalities lead volume deployment due to widespread availability and lower per-procedure cost, while optical coherence tomography captures the fastest-growing segment as intracoronary imaging demand rises for stent optimization. Magnetic resonance applications concentrate margin pools in pre-operative planning for complex congenital cases where radiation avoidance commands premium pricing.
FDA 510(k) clearance pathways, EU MDR technical documentation requirements, and Japan PMDA shonin approvals collectively shape product development timelines and software lock-in protocols for AI-enabled coronary analysis. The EU AI Act introduces additional conformity obligations for machine-learning diagnostic outputs that will reroute vendor compliance spending toward algorithmic transparency documentation. Stakeholders must monitor how reimbursement authority decisions on AI add-on codes in the United States and Germany determine whether software-enhanced reads achieve separate payment recognition from hardware-based imaging fees.
Market Dynamics
Hospital procurement of coronary imaging systems is collapsing toward integrated cardiovascular service lines that bundle diagnostic throughput with interventional capacity, compressing standalone device margins while elevating ecosystem vendors.
Growth Catalysts
- EU MDR technical documentation:CE marking under the EU MDR is tightening software validation requirements for AI-enhanced coronary analysis tools, accelerating vendor consolidation toward compliant platforms.
- Aging demographics:Demand is concentrating in the United States, Germany, and Japan where reimbursement stability supports capital equipment replacement cycles.
- Intracoronary imaging:Optical coherence tomography captures the fastest-growing segment as stent optimization protocols expand in tertiary cardiac centers.
Market Restraints
- Software lock-in protocols:FDA 510(k) clearance pathways and Japan PMDA shonin approvals shape product development timelines that freeze out smaller developers lacking regulatory capital.
- Radiation exposure liability:Repeat-scan protocols face institutional review board scrutiny, limiting CT deployment in pediatric and young-adult populations.
- Contrast agent supply:Iodinated contrast shortages disrupt angiography scheduling, forcing hospitals to maintain dual-source inventory or defer elective procedures.
Strategic Opportunities
- EU AI Act conformity:Algorithmic transparency documentation obligations will reroute vendor compliance spending toward explainable machine-learning outputs, creating first-mover advantage for documented systems.
- Magnetic resonance premium:Pre-operative planning for complex congenital cases commands premium pricing where radiation avoidance justifies higher per-scan reimbursement.
- AI add-on codes:Reimbursement authority decisions in Germany and the United States on software-enhanced reads will determine whether algorithmic analysis achieves separate payment recognition from hardware-based imaging fees.
Industry Challenges
- Interoperability with legacy PACS:AI-enhanced coronary analysis tools face integration friction with hospital picture archiving systems that lack API standardization.
- Specialized imaging physicists:Dual-source CT and spectral detector protocols require scarce personnel trained in iterative reconstruction algorithms, constraining deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coronary Heart Disease Diagnostic Imaging Devices Market |
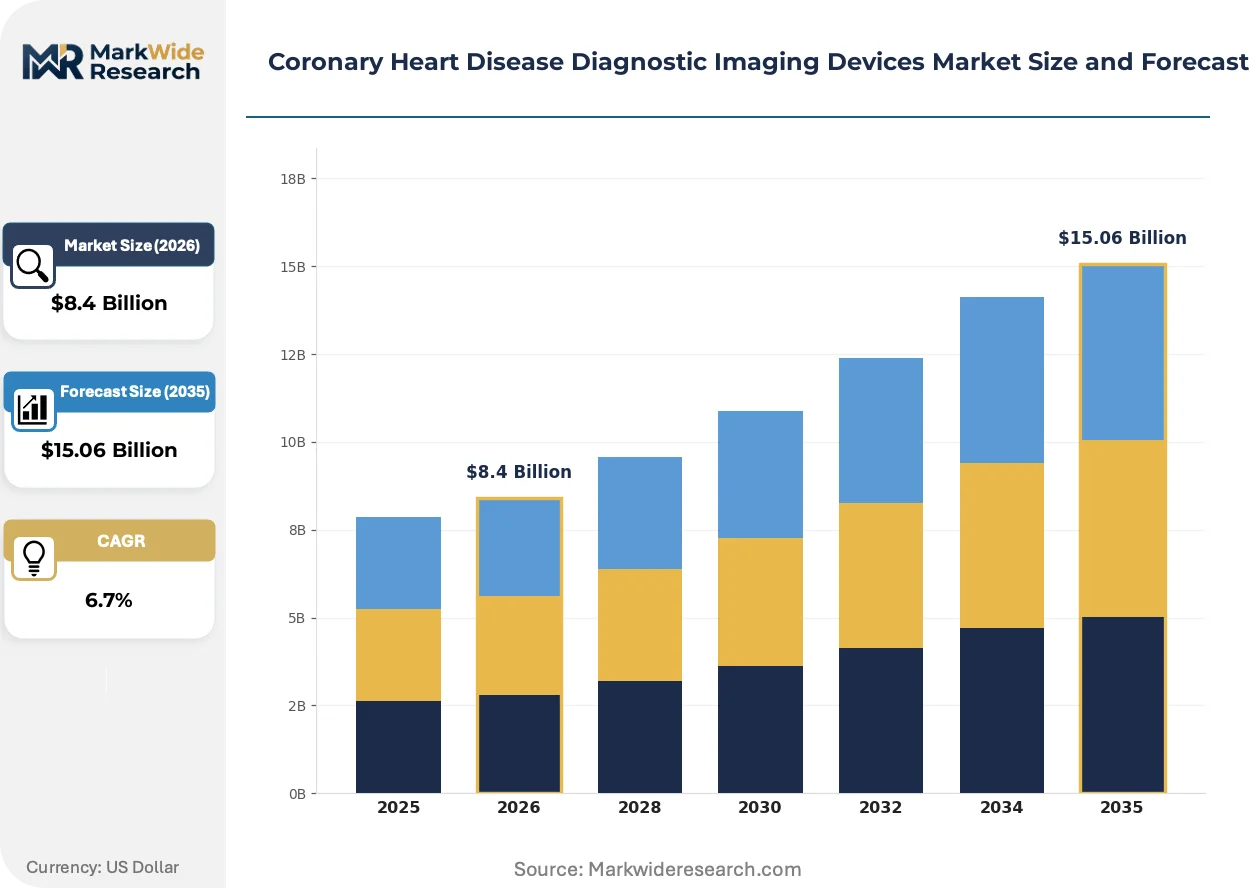
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MRI, CT Scan, Ultrasound, PET Scan Technology: Digital Angiography, Computed Tomography, Magnetic Resonance, Optical Coherence Tomography End User: Hospitals, Imaging Centers, Cardiology Clinics, Research Institutions Application: Diagnostic Testing, Risk Assessment, Treatment Monitoring, Pre-operative Planning |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips, Canon Medical Systems Corporation, Fujifilm, Shimadzu Corporation, Toshiba, Hitachi, Shenzhen Mindray Bio-Medical Electronics Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coronary Heart Disease Diagnostic Imaging Devices Market Strategic Shifts & Innovations
Coronary imaging is undergoing platform convergence where hardware manufacturers embed algorithmic analysis directly into acquisition workflows, collapsing the traditional separation between device vendors and diagnostic software providers.
Intravascular ultrasound catheters are miniaturizing below 2.9 French profiles to enable distal coronary access in tortuous anatomy. Interventional cardiologists in Japanese and German academic centers are adopting these platforms for complex left-main and bifurcation lesions. This miniaturization is compressing the addressable market for standalone angiography guidance, forcing vendors to bundle physiological assessment with anatomical imaging.
The EU AI Act introduces additional conformity obligations for machine-learning diagnostic outputs that mandate algorithmic transparency documentation. Industrial consequence includes extended technical file preparation timelines and third-party notified body involvement for software-as-medical-device classifications. Cardiac CT vendors targeting European hospital networks are responding by establishing dedicated regulatory affairs functions for post-market surveillance of AI model drift.
Hospital networks are consolidating imaging procurement under cardiovascular service line administrators rather than radiology departments, centralizing capital allocation decisions. Equipment financing through managed service contracts is displacing traditional capital purchase models in United States integrated delivery networks. This shift is most visible in Florida and Texas health systems where private equity-backed cardiology platforms prioritize predictable per-procedure costs over ownership.
Coronary Heart Disease Diagnostic Imaging Devices Market Segmentation
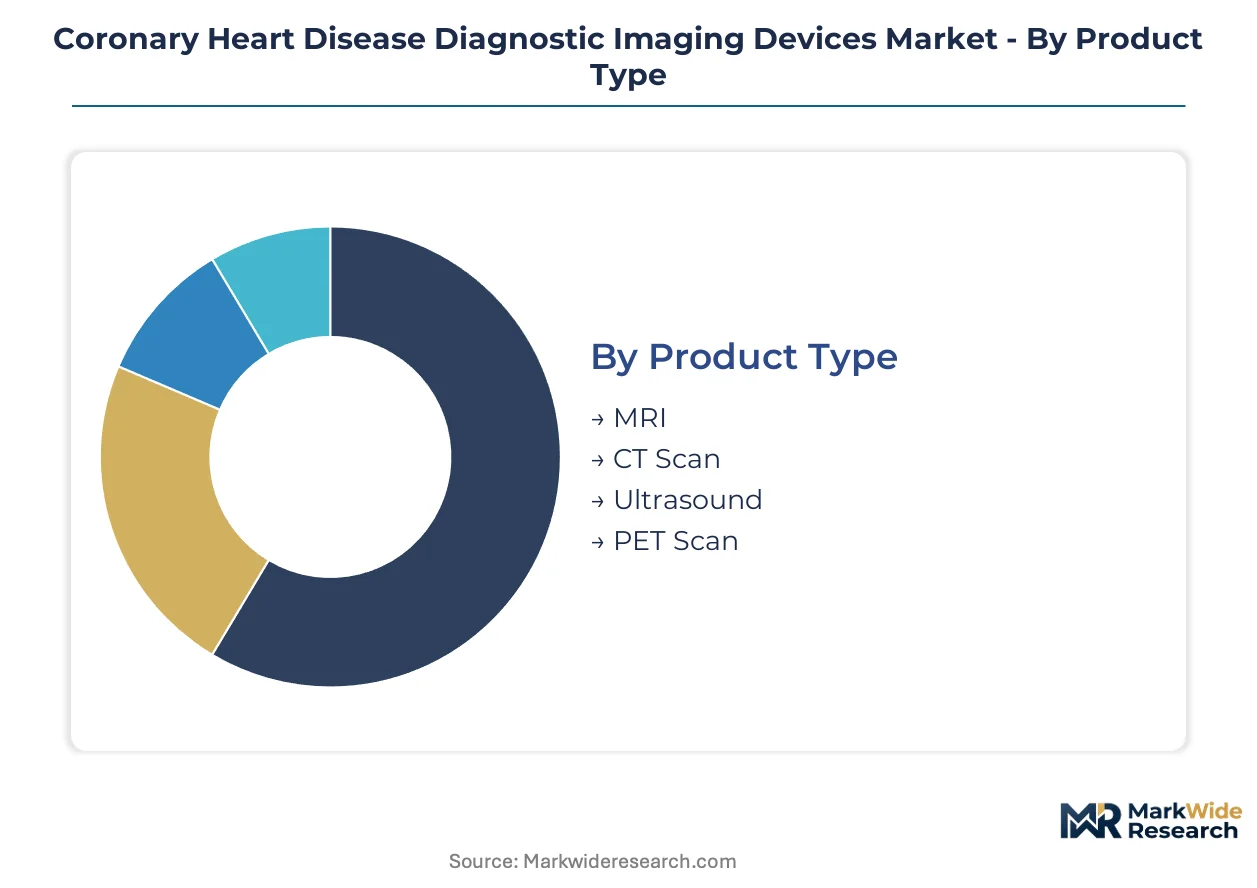
Segmentation in coronary imaging reveals how capital flows concentrate around radiation-avoidant modalities and interventional workflows. Procurement patterns diverge sharply between high-throughput hospital networks seeking bundled cardiovascular service lines and specialized centers prioritizing precision over volume.
Product Type:
Margin pools concentrate in modalities that command premium reimbursement through radiation avoidance or functional tissue characterization.
- CT Scan:Dual-source and spectral detector platforms dominate installed base economics through lower per-procedure operational costs. United States hospital networks deploy these systems for high-throughput chest pain protocols in emergency departments, though iodinated contrast supply volatility constrains scheduling predictability.
- MRI:Cardiovascular magnetic resonance captures premium pricing in pre-operative planning for complex congenital cases where iterative reconstruction algorithms justify extended scan times. German and Japanese academic centers maintain dedicated cardiac MRI suites for viability assessment and scar characterization.
- Ultrasound:Transthoracic and transesophageal echocardiography serve point-of-care screening functions with portable system penetration expanding in ambulatory settings.
- PET Scan:Myocardial perfusion imaging with rubidium-82 or ammonia-13 tracers occupies niche applications where absolute quantification of coronary flow reserve guides revascularization decisions.
CT Scan holds installed capacity. MRI is rotating up the share rankings.
Technology:
Technology segmentation tracks how hardware vendors embed algorithmic analysis directly into acquisition workflows, collapsing traditional separations between device and software providers.
- Optical Coherence Tomography:Intracoronary imaging platforms below 2.9 French profiles enable distal access in tortuous anatomy. Japanese interventional cardiologists deploy these systems for left-main and bifurcation lesion optimization, compressing addressable space for standalone angiography guidance.
- Computed Tomography:Coronary CT angiography with AI-enhanced stenosis scoring anchors hospital procurement decisions through integration with cardiovascular service line administrators rather than radiology departments.
- Digital Angiography:Conventional X-ray fluoroscopy with flat-panel detectors persists in catheterization laboratories for real-time procedural guidance despite radiation exposure liability concerns.
- Magnetic Resonance:Late gadolinium enhancement and T1/T2 mapping sequences concentrate in tertiary referral patterns for myocarditis and infiltrative disease characterization.
Computed Tomography anchors procurement volume. Optical Coherence Tomography is climbing the fastest among interventional modalities.
End User:
Customer type segmentation reflects capital allocation authority shifting from radiology departments toward cardiovascular service line administrators.
- Hospitals:Integrated delivery networks in Florida and Texas health systems favor managed service contracts with predictable per-procedure costs over traditional capital purchase models.
- Imaging Centers:Independent diagnostic facilities compete on throughput metrics and payer contract breadth, constraining margin capture relative to hospital-based sites of care.
- Cardiology Clinics:Private equity-backed cardiology platforms prioritize point-of-care ultrasound and limited CT access to capture diagnostic revenue upstream of hospital referral.
- Research Institutions:Academic medical centers in the United States and Germany maintain spectral CT and 7 Tesla MRI platforms for plaque characterization protocols that lack routine reimbursement codes.
Hospitals concentrate capital deployment authority. Cardiology Clinics are gaining share fastest through vertical integration of diagnostic and interventional services.
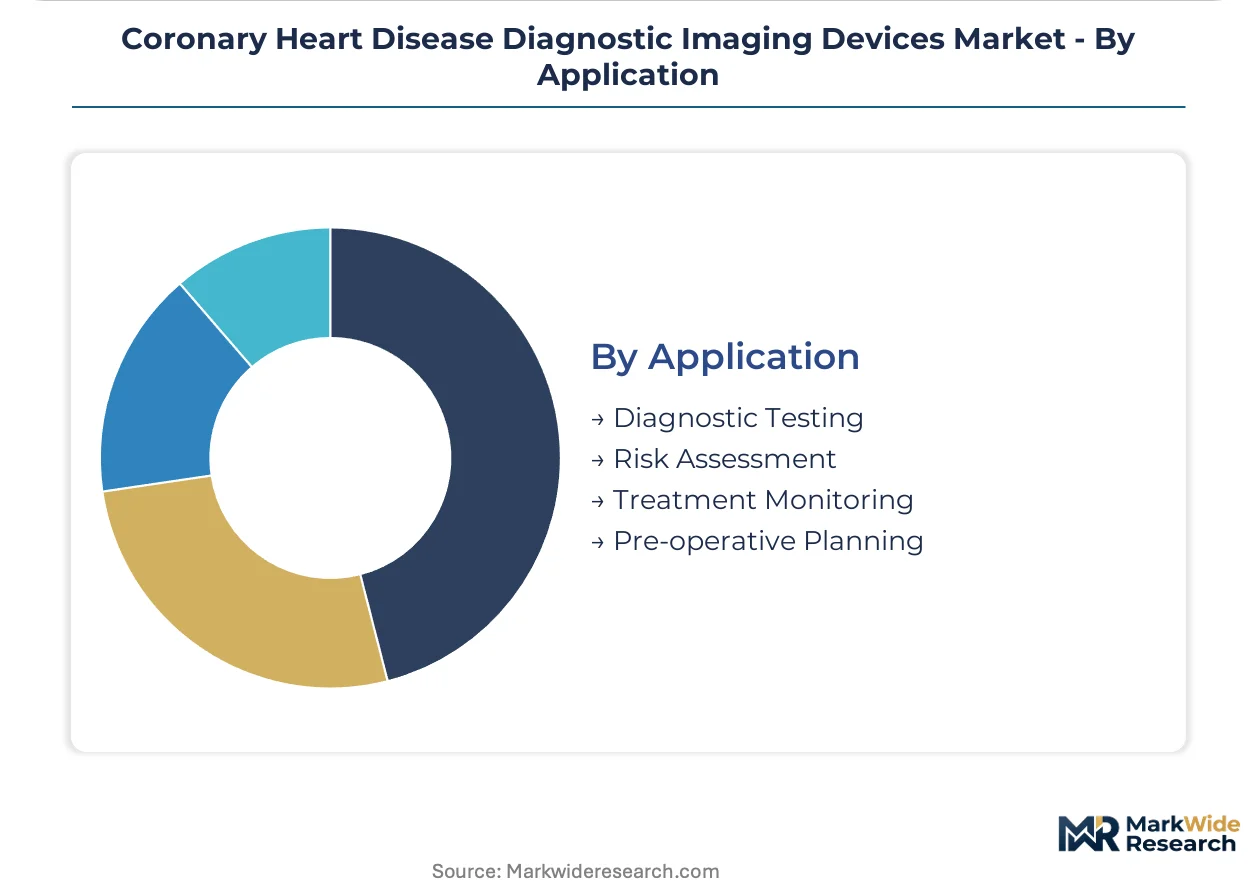
Application:
Application segmentation tracks reimbursement code differentiation between screening, diagnostic, and procedural guidance functions.
- Diagnostic Testing:Symptomatic patient evaluation with coronary CT angiography commands distinct CPT codes from screening applications, with United States Medicare coverage determinations shaping hospital investment decisions.
- Pre-operative Planning:Complex congenital and reoperative cases justify premium MRI reimbursement where radiation avoidance commands explicit value-based payment recognition.
- Risk Assessment:Asymptomatic screening with coronary artery calcium scoring faces variable payer coverage, limiting deployment to direct-pay and employer-sponsored wellness programs.
- Treatment Monitoring:Post-revascularization surveillance with intracoronary imaging guides stent optimization protocols in Japanese and German tertiary centers.
Diagnostic Testing holds procedure volume concentration. Pre-operative Planning is rotating up the share rankings through value-based payment pilots.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement authority concentrates in integrated cardiovascular service lines across mature healthcare economies, with capital deployment decisions shifting from radiology departments toward enterprise administrators managing bundled diagnostic-interventional workflows.
United States
Private equity-backed cardiology platforms in Florida and Texas drive managed service contract adoption, prioritizing predictable per-procedure costs over equipment ownership. FDA 510(k) clearance pathways for AI-enhanced coronary analysis compress development timelines for compliant vendors. The Cleveland Clinic and Mayo Clinic anchor academic procurement clusters where spectral CT platforms support high-throughput chest pain protocols.
Germany
Academic medical centers in Berlin and Munich maintain dedicated cardiac MRI suites for viability assessment where radiation avoidance commands premium reimbursement. EU MDR technical documentation requirements under CE marking tighten software validation protocols for algorithmic stenosis scoring. The Rhine-Ruhr industrial corridor concentrates vendor regulatory affairs functions for post-market surveillance of AI model drift.
Japan
Interventional cardiologists at tertiary centers in Tokyo and Osaka deploy miniaturized intracoronary imaging platforms for left-main and bifurcation lesion optimization. PMDA shonin approvals shape product development timelines that favor established vendors with regulatory capital reserves. The Kansai region anchors stent optimization protocol adoption as optical coherence tomography gains procedural share.
United Kingdom
NHS England coverage determinations for coronary CT angiography influence hospital investment decisions across integrated care systems. MHRA conformity assessment procedures align with EU MDR documentation standards for software-as-medical-device classifications. The Oxford-Cambridge-London arc concentrates research-intensive cardiac imaging deployment for complex congenital pre-operative planning.
China
Provincial hospital networks in Shanghai and Guangzhou expand dual-source CT capacity to manage rising ischemic patient volumes in aging urban populations. NMPA medical device registration pathways prioritize local clinical evidence generation for AI-enhanced diagnostic outputs. The Yangtze River Delta anchors domestic vendor assembly operations for detector technology components.
Coronary Heart Disease Diagnostic Imaging Devices Market Key Industry Players
Player mix skews toward diversified medical technology conglomerates with imaging hardware heritage, compressing standalone device margins while elevating ecosystem vendors with embedded algorithmic capabilities. Siemens Healthineers and GE Healthcare anchor the premium tier through integrated cardiovascular service line contracts. Three archetypes dominate: full-platform vendors bundling hardware with AI workflows, component specialists in detector technology, and regional challengers competing on capital cost. Competitive moves concentrate on strategic partnerships for software integration and managed service contract expansion.
Among diversified imaging conglomerates, Siemens Healthineers, GE Healthcare, and Canon Medical Systems Corporation occupy positions that exemplify platform-centric competition. Siemens Healthineers represents the dual-source CT anchor model in North American academic centers. GE Healthcare exemplifies ecosystem architecture through embedded algorithmic scoring. Canon Medical Systems Corporation anchors detector specialization with radiation reduction prioritization. Koninklijke Philips and Fujifilm sit within the tier competing on workflow integration and portable system penetration.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips |
| Canon Medical Systems Corporation |
| Fujifilm |
| Shimadzu Corporation |
| Toshiba |
| Hitachi |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd |
| Others |
Cost & Logistics Intelligence
Managed service contracts with per-procedure pricing lock United States hospital networks into predictable cost structures while securing vendor access to spectral CT and AI-enhanced analysis platforms. These arrangements bundle hardware depreciation, software licensing, and maintenance into unified payment streams that compress capital expenditure volatility for integrated delivery networks in Florida and Texas.
Pricing Analysis
Cost-plus contracts with iodinated contrast indexation anchor procurement negotiations between United States hospital networks and imaging vendors. Three-tier pricing structure across premium dual-source CT, standard single-source systems, and economy refurbished platforms differentiates capital access tiers. Pricing pressure stems from private equity-backed cardiology platforms prioritizing per-scan cost predictability over equipment ownership. Independent imaging centers exhibit highest price sensitivity due to constrained payer contract breadth, while academic medical centers in Germany and Japan absorb premium positioning for radiation-avoidant MRI protocols.
Supply Chain Analysis
Japan and Germany anchor precision detector manufacturing for dual-source CT platforms, while China concentrates assembly operations for flat-panel components. Supply chains draw from rare earth deposits for scintillator crystals, specialized semiconductor foundries for ASIC readout electronics, and iodine extraction facilities for contrast agent production. Single-source vulnerability pervades AI training data licensing for coronary stenosis algorithms. Distribution runs through authorized dealer networks serving hospital procurement committees and cardiovascular service line administrators rather than radiology departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates around AI-enhanced diagnostic workflows where incumbent hardware vendors under-serve algorithmic transparency documentation. Hospital procurement authority shifting toward cardiovascular service line administrators creates niche entry points for software-native challengers.
For Market Incumbents: Consolidate regulatory affairs functions in the Rhine-Ruhr corridor and Tokyo to manage EU AI Act conformity and PMDA shonin pathways for machine-learning outputs. Backward integration into detector technology mitigates supply disruption from rare earth processing concentration. Priority lever rests on embedding stenosis scoring algorithms directly into acquisition workflows before standalone software vendors achieve hospital system penetration. For New Entrants and Emerging Players: Post-market surveillance compliance for AI model drift represents an underserved service layer where established CT vendors lack dedicated regulatory infrastructure. Target German academic medical centers with algorithmic transparency documentation tools that satisfy notified body requirements under EU MDR software-as-medical-device classifications. Go-to-market angle emphasizes managed service contract participation as third-party algorithmic validation partners. For Investors and Strategic Acquirers: Component specialists with captive detector technology and iterative reconstruction algorithm IP command acquisition premiums in consolidation scenarios. Long-term viability frames around reimbursement authority decisions on AI add-on codes in the United States and Germany determining whether software-enhanced reads achieve separate payment recognition. Signal to watch is CMS coverage determination timelines for coronary CT angiography with embedded algorithmic analysis.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR CE Marking Pathway | Software validation documentation accelerates vendor consolidation toward compliant AI-enhanced platforms. |
| Hospital System Partnership | Managed service contracts with Florida and Texas IDNs displace traditional capital purchase models. |
| Software Companion Development | Algorithmic stenosis scoring embedded in Siemens and GE workflows collapses standalone diagnostic software margins. |
| FDA 510(k) Submission | Clearance pathways for optical coherence tomography platforms shape stent optimization protocol adoption. |
| Reimbursement Strategy | AI add-on code recognition in Germany determines separate payment for algorithmic analysis. |
Research Approach
The analysis maps coronary CT angiography, intracoronary imaging, and cardiovascular magnetic resonance modalities, each validated through interventional cardiologists, hospital purchasing committees, biomedical engineers, and GPO contracts managers. Primary interview data triangulates against FDA 510(k) filings, EU MDR technical documentation, PMDA shonin records, and hospital procurement databases. Bottom-up equipment installation tracking and top-down reimbursement code analysis cross-validate market sizing across the projection horizon.
Consistency checks against external benchmarks validated volume and value outputs across product type, technology, end user, and application segmentation dimensions. CAGRs derive from procedure volume trajectories in United States Medicare claims, German statutory health insurance data, and Japanese diagnostic imaging utilization surveys. Modeling incorporates iodinated contrast supply volatility, EU AI Act implementation timelines, and private equity cardiology platform expansion as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FDA premarket notification pathways, EU MDR CE marking procedures, and Japan PMDA approval frameworks; material policy shifts would require re-modeling. Recalibration cycles align with material shifts in reimbursement authority coverage determinations and AI add-on code recognition decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Procalcitonin Antibody Market
Diagnostic Devices
ENT Diagnostic Devices Market
Diagnostic Devices
Global Dermatology Diagnostic Devices Market
Diagnostic Devices
Breast Biopsy Market
Diagnostic Devices
Blood Testing Devices Market
Diagnostic Devices
Portable Diagnostic Devices Market
Diagnostic Devices
Digital Diagnostic Audiometer Market
Diagnostic Devices
AI Portable Chest X-ray Triage Device Market
Diagnostic Devices
Pulmonary Function Testing Devices Market
Diagnostic Devices
Bronchial Biopsy Devices Market
Diagnostic Devices
North America Saliva Test Devices Market
Diagnostic Devices
Diagnostic Stopper Market
Diagnostic Devices
Pelvic Floor Diagnostics Market
Diagnostic Devices
Sleep Apnea Diagnostic Systems Market
Diagnostic Devices
Global Dental Caries Detectors Market
Diagnostic Devices
Global Breath Analyzer Market